
 Outdoor Lithium Battery Power Supplies Market | 2026-2036
Outdoor Lithium Battery Power Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Lithium Battery Power Supplies Market Insights
Remote construction crews and disaster relief agencies are bifurcating demand away from casual recreational buyers. ECOFLOW anchors its position through proprietary inverter technology and direct-to-consumer channel control. Jackery leverages aggressive Amazon marketplace positioning and influencer-driven brand recognition. Bluetti differentiates via higher AC output capacities and LiFePO4 chemistry specialization that appeals to off-grid homesteaders.
Outdoor lithium battery power supplies are rechargeable electrochemical energy storage systems built around lithium-ion or lithium iron phosphate cells, typically housed in weather-resistant enclosures with integrated inverters, MPPT charge controllers, and multiple output ports for AC and DC devices. These units store between 100Wh and several kWh, enabling silent, emission-free electricity generation for locations beyond grid reach. Solar generators now capture the fastest-growing margin pool as panel bundling lifts average selling prices and extends replacement cycles. Power stations above 600Wh dominate revenue contribution from van-life enthusiasts and mobile tradespeople. Portable chargers under 300Wh face commoditization pressure as Shenzhen Poweroak Technology and PISEN compete on cell cost alone.
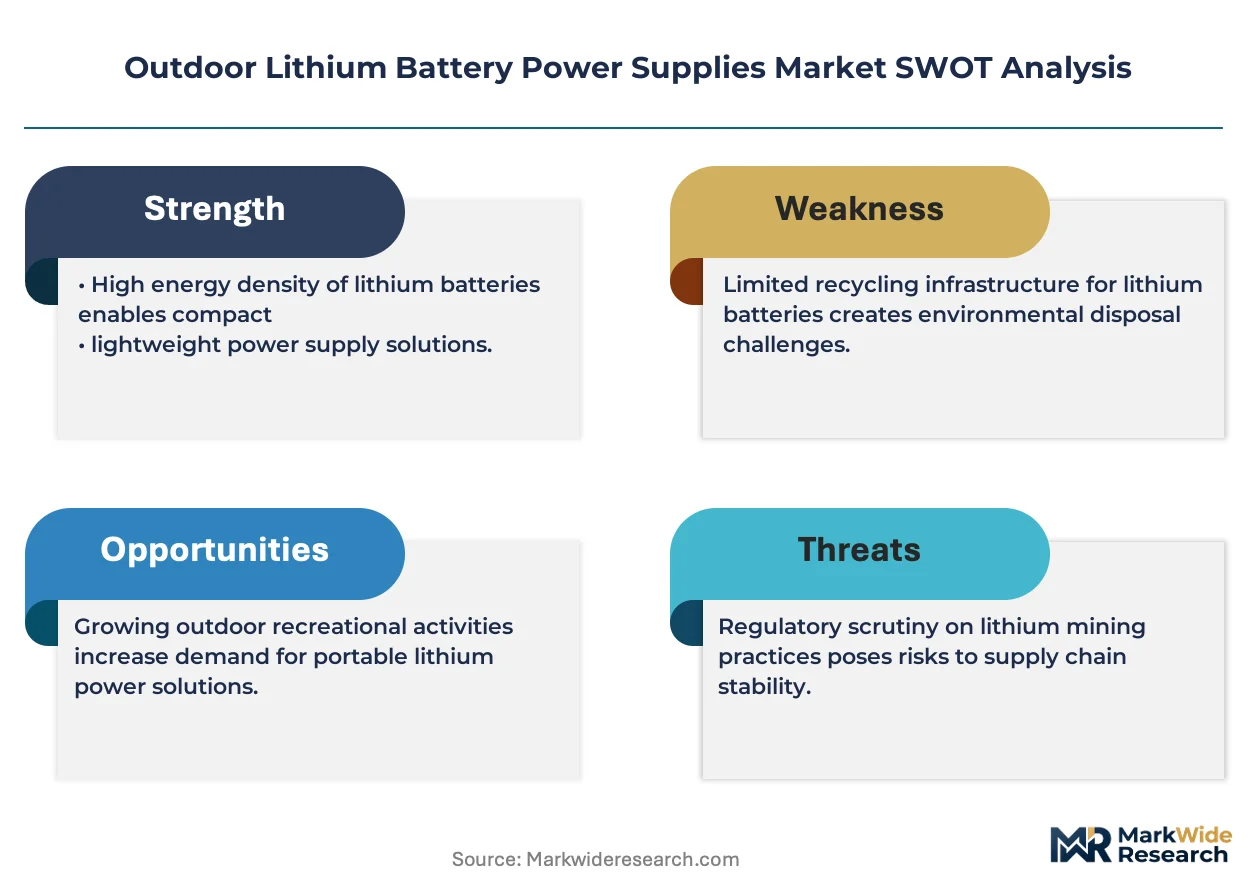
The US EPA and FCC enforce battery transport and electromagnetic emission standards that constrain product design and cross-border shipment logistics. China's MIIT and GB standards govern cell manufacturing quality, directly affecting supply availability and cost structures for brands sourcing from Shenzhen and Dongguan clusters. Stakeholders must monitor how evolving carbon border adjustments and right-to-repair mandates reshape sourcing economics and product-service bundling strategies.
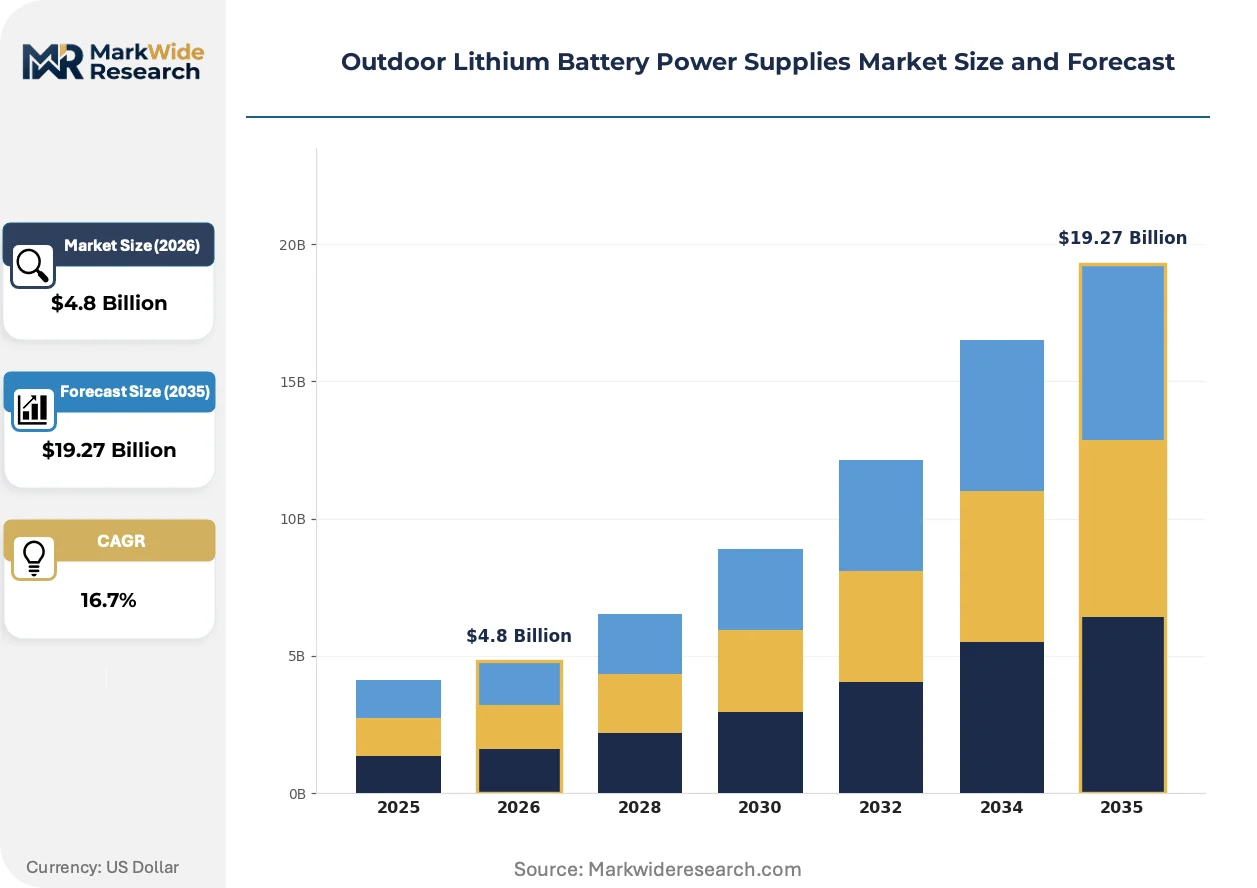
Market Dynamics
Cell chemistry bifurcation between NMC and LiFePO4 architectures now dictates procurement economics, with van-life enthusiasts and remote construction crews pulling capacity requirements in opposite directions. This tension compresses product development cycles while expanding SKU proliferation.
Growth Catalysts
- US IRA clean energy tax credits:Federal incentives for domestic battery assembly accelerate OEM reshoring decisions and expand consumer rebate eligibility for solar generator bundles.
- Remote construction electrification:Diesel generator bans on federally managed lands in the United States and Germany push contractors toward silent lithium alternatives for equipment charging.
- Solar panel bundling:MPPT charge controller integration with rigid and flexible photovoltaic arrays extends replacement cycles and lifts average selling prices across the 600Wh-2kWh segment.
Market Restraints
- Lithium carbonate price volatility:Qinghai and Salar de Atacama supply concentration exposes cell manufacturers to 40-60% input cost swings that compress gross margins.
- US EPA battery transport regulations:UN38.3 testing mandates and hazmat shipping classifications add 12-18% to landed costs for cross-border direct-to-consumer fulfillment.
- Lead-acid residual demand:Price-sensitive RV owners and emergency preppers in rural Australia continue selecting flooded batteries for sub-500Wh applications.
Strategic Opportunities
- India PLI scheme for advanced chemistry cells:Production-linked incentives for 50GWh annual capacity create localized supply alternatives to Shenzhen and Dongguan clusters.
- Vehicle-to-load bidirectional charging:Electric pickup trucks from Ford and Rivian enable power export protocols that displace standalone power stations at job sites.
- Right-to-repair mandates in the European Union:CSRD-adjacent product longevity requirements favor modular battery architectures with swappable cell packs and open diagnostic interfaces.
Industry Challenges
- Battery management system firmware certification:FCC Part 15B electromagnetic emissions testing and UL 2743 safety validation extend new product introduction timelines by 8-14 months.
- Thermal runaway containment engineering:Cell-to-pack integration expertise scarcity constrains in-house development capabilities for brands lacking automotive-tier battery engineering benches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Lithium Battery Power Supplies Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Chargers, Solar Generators, Power Stations, Battery Packs Use Case: Camping, Emergency Backup, Off-Grid Living, Recreational Activities Capacity: 100Wh, 300Wh, 600Wh, 1200Wh Integration Level: Standalone, Modular, Grid-Tied, Smart Integrated |
| Companies Covered | ECOFLOW, Jackery, Goal Zero, Anker, Bluetti, Allpowers, Shenzhen Poweroak Technology, PISEN, Westinghouse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Lithium Battery Power Supplies Market Trends and Innovations
Silent, emission-free power delivery now competes with fuel-cell and hydrogen alternatives across off-grid applications. Technology trajectories concentrate on chemistry optimization, regulatory pre-compliance, and channel restructuring.
LiFePO4 chemistry is fragmenting the mid-capacity segment as cylindrical cell formats displace prismatic alternatives in 500Wh-2kWh power stations. Off-grid homesteaders and full-time van dwellers prioritize cycle life over energy density, accepting 30% weight penalties for 4,000+ cycle ratings. This preference compression forces NMC specialists to retreat toward sub-300Wh portable chargers or pivot to automotive-grade cylindrical supply.
REACH substance restrictions and EU Battery Regulation due diligence obligations are tightening supply chain documentation requirements for cobalt and nickel sourcing. Manufacturers must now provide carbon footprint declarations and recycled content quotas to maintain CE marking eligibility. German distributors and French retail chains are demanding batch-level traceability certificates before listing new products.
Direct-to-consumer channel expansion is bypassing traditional outdoor retail networks that previously controlled category visibility. Amazon marketplace optimization and TikTok-native influencer content now drive 60-70% of first-time buyer discovery for sub-1kWh units. This disintermediation concentrates in the United States and Australia, where REI and BCF store footprints are contracting while warehouse-direct fulfillment scales.
Outdoor Lithium Battery Power Supplies Market Segmentation
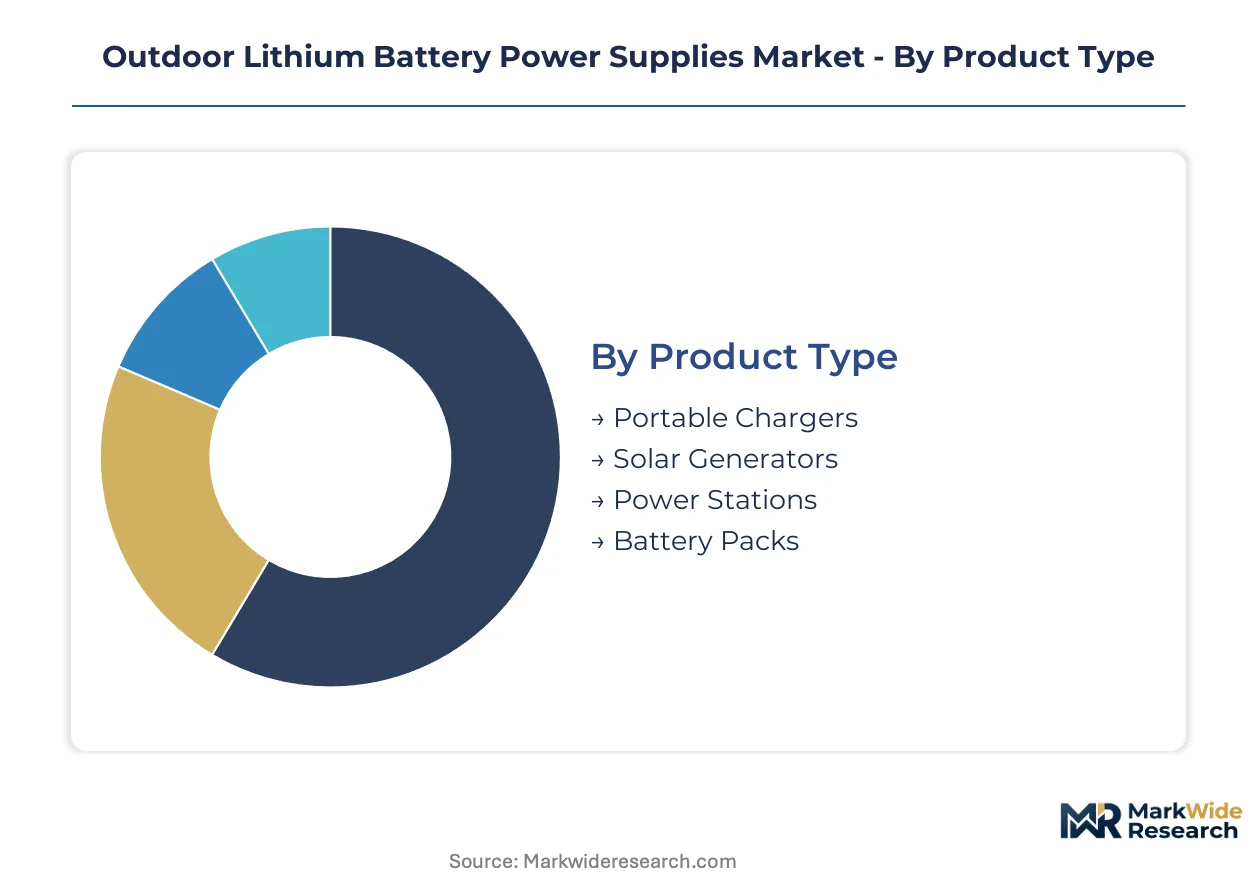
Segmentation in outdoor lithium battery power supplies reveals how cell chemistry, capacity thresholds, and integration architectures dictate procurement economics. Buyers now sort across four distinct category systems that separate recreational convenience from professional-grade resilience.
Product Type:
Margin pools concentrate in bundled solar generator configurations where MPPT charge controller integration lifts average selling prices and extends replacement cycles.
- Solar Generators:Integrated photovoltaic-ready systems combine lithium cells with MPPT controllers and rigid or flexible panel compatibility. Van-life enthusiasts and remote construction crews in the United States and Germany drive procurement volumes as diesel generator bans on federally managed lands accelerate electrification mandates.
- Power Stations:High-capacity AC-output units ranging from 600Wh to several kWh with pure sine wave inverters and multiple output ports. Mobile tradespeople and off-grid homesteaders prioritize these for tool charging and appliance runtime, accepting weight penalties for LiFePO4 chemistry durability.
- Portable Chargers:Sub-300Wh pocket-sized units for smartphone and laptop charging.
- Battery Packs:Modular cell assemblies without integrated inverters, requiring external power management.
The dominant share belongs to Power Stations, while Solar Generators are gaining share fastest through panel bundling and tax credit eligibility.
Use Case:
Application-based demand splits between recreational convenience buyers and resilience-oriented professionals with divergent replacement cycles and price sensitivity.
- Emergency Backup:Grid-tie-ready systems with automatic transfer switching and UPS functionality for medical devices and refrigeration. Disaster relief agencies and emergency preparedness planners in hurricane-prone United States coastal counties and Australian bushfire regions concentrate procurement volumes ahead of seasonal risk windows.
- Off-Grid Living:Permanent installation systems with expansion battery compatibility and solar array scaling for homesteaders and rural property owners prioritizing cycle life over energy density.
- Camping:Lightweight sub-600Wh units for weekend recreational users.
- Recreational Activities:Tailgating, fishing, and outdoor event power for occasional use patterns.
Emergency Backup commands the largest revenue pool, though Off-Grid Living shows the steepest expansion trajectory as full-time van dwellers multiply.
Capacity:
Volume-weighted economics favor mid-capacity segments where manufacturing scale and cell standardization intersect with professional buyer willingness to pay for runtime certainty.
- 600Wh:The threshold where pure sine wave inverters, multiple AC outlets, and solar input compatibility become standard. Mobile tradespeople and weekend van-life enthusiasts in Australia and Germany select this tier for tool charging and overnight appliance operation without weight penalties that constrain air travel.
- 1200Wh:Professional-grade systems with 2000W+ surge capacity for power tool startups and small appliance clusters. Remote construction crews on federally managed United States lands and German infrastructure projects specify these for diesel displacement compliance.
- 100Wh:Pocket-scale units for personal electronics charging.
- 300Wh:Entry-level camping power for LED lighting and small device charging.
600Wh systems hold the dominant position, while 1200Wh configurations climb the fastest as contractor electrification mandates expand.
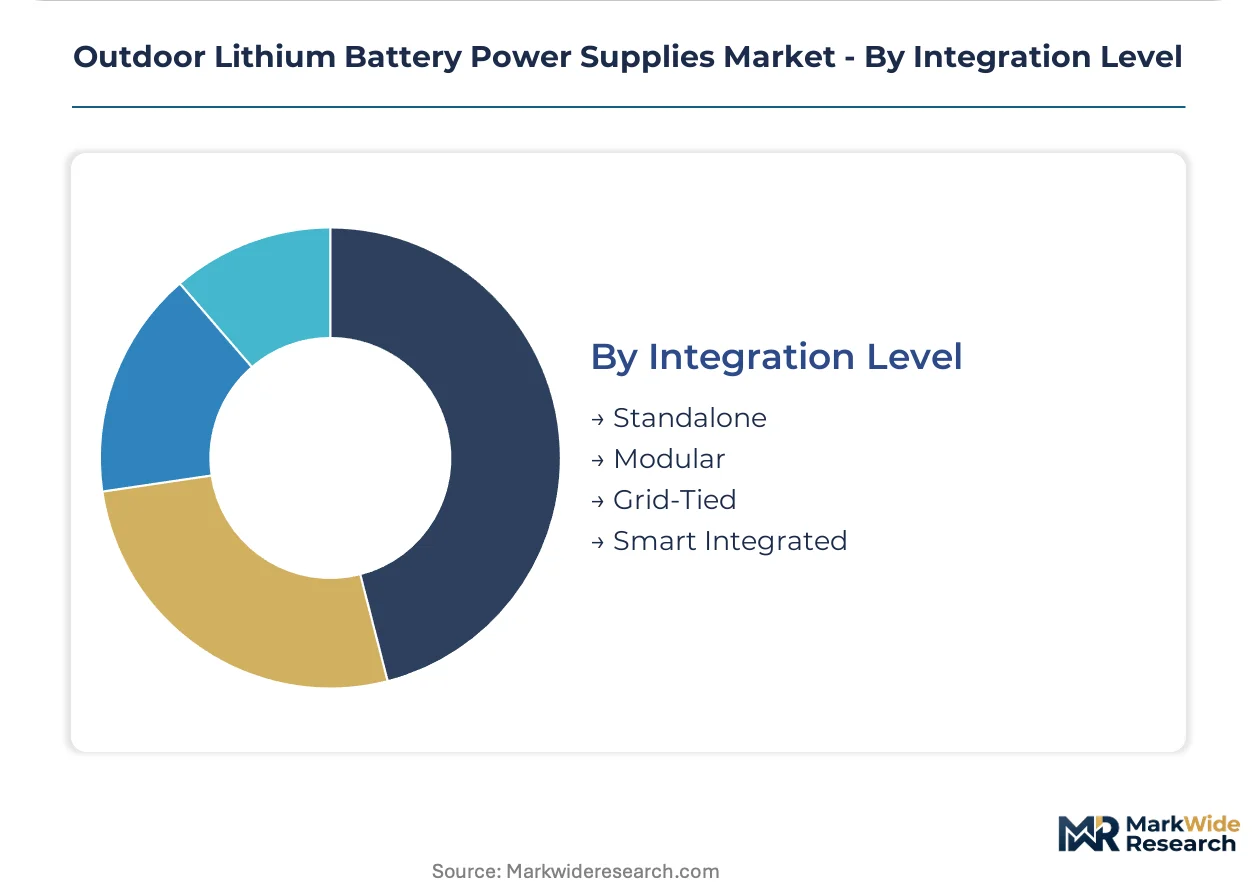
Integration Level:
Architecture choices determine whether buyers capture operational flexibility through modularity or simplicity through sealed all-in-one designs.
- Smart Integrated:App-connected units with Bluetooth monitoring, firmware-updatable battery management systems, and IoT-enabled load scheduling. Tech-forward buyers in United States metropolitan markets and Australian urban centers prioritize remote diagnostics and over-the-air feature expansion.
- Modular:Expansion-battery-compatible systems allowing capacity scaling through daisy-chained cell packs. Off-grid homesteaders and full-time van dwellers favor swappable architectures that extend system lifespan beyond single-pack degradation.
- Standalone:Sealed integrated units without expansion capability or connectivity features.
- Grid-Tied:Systems with utility interconnection hardware for net metering and backup power export.
Standalone systems retain the largest installed base, yet Smart Integrated configurations are expanding most quickly through app ecosystem lock-in and feature differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cell manufacturers in Shenzhen and Dongguan export lithium battery packs to United States distributors and Australian retailers, with German importers serving as the primary European gateway for assembled power stations.
United States
Remote construction crews on federally managed lands drive procurement volumes as diesel generator bans accelerate electrification mandates. The IRA clean energy tax credits expand consumer rebate eligibility for solar generator bundles. Austin and Denver serve as distribution hubs where van-life enthusiasts and mobile tradespeople concentrate demand.
Germany
Infrastructure contractors specify high-capacity AC-output units for silent equipment charging on noise-restricted job sites. The EU Battery Regulation due diligence obligations tighten supply chain documentation for cobalt and nickel sourcing. Bavarian distributors demand batch-level traceability certificates before listing new products.
Australia
Bushfire-prone regions and remote mining camps concentrate emergency preparedness procurement ahead of seasonal risk windows. The TGA and state-level electrical safety standards govern product certification for grid-interconnection hardware. Sydney and Melbourne warehouse-direct fulfillment scales as traditional outdoor retail footprints contract.
China
Shenzhen and Dongguan clusters manufacture cylindrical and prismatic cells for export assembly, with MIIT and GB standards governing manufacturing quality. The dual carbon goals accelerate domestic lithium cell sourcing shifts toward cleaner production methods. Zhejiang and Jiangsu provinces house expanding inverter and BMS component suppliers.
India
Production-linked incentives for advanced chemistry cells create localized supply alternatives to Chinese manufacturing clusters. The BIS certification requirements and state-level solar rooftop programs expand addressable market for solar-ready power stations. Gujarat and Tamil Nadu industrial corridors attract cell assembly investments.
Outdoor Lithium Battery Power Supplies Market Competitive Landscape
Listed leaders compete with private specialists across channel strategy and chemistry specialization. The vendor base separates into direct-to-consumer platform optimizers, automotive-tier engineering descendants, and contract manufacturing aggregators. Three archetypes dominate: proprietary inverter developers, marketplace-native brands, and cell chemistry specialists. Capacity expansion and strategic channel partnerships constitute the dominant competitive moves as firms defend margin position against Shenzhen-based cost competitors.
Within the premium engineering tier, ECOFLOW and Bluetti occupy positions defined by proprietary technology control and LiFePO4 specialization respectively. Jackery exemplifies the marketplace-native archetype through aggressive Amazon positioning. These three entities anchor the competitive structure while Shenzhen Poweroak Technology and PISEN represent the contract manufacturing aggregation model competing on cell cost alone.
| Leading Market Players |
|---|
| ECOFLOW |
| Jackery |
| Goal Zero |
| Anker |
| Bluetti |
| Allpowers |
| Shenzhen Poweroak Technology |
| PISEN |
| Westinghouse |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between cell manufacturers and lithium carbonate processors lock in both supply access and price visibility for brands assembling power stations above 600Wh, insulating procurement teams from Qinghai supply volatility while compressing margin flexibility for spot-market buyers.
Pricing Analysis
Current-generation LiFePO4 cylindrical cells command 15-20% premiums over prior-generation prismatic NMC alternatives, with next-generation silicon-anode architectures poised to reset cost baselines. Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade cell sourcing from consumer-tier alternatives. Cost compression in sub-300Wh portable chargers intensifies because Shenzhen contract manufacturers compete on cell cost alone. Emergency preparedness planners exhibit lowest price sensitivity, accepting surge premiums for UPS functionality, while weekend campers drive commoditization at entry tiers.
Supply Chain Analysis
Strategic stockpiling of lithium carbonate and electrolyte salts dominates procurement strategy as buyers buffer against 40-60% input cost swings from Salar de Atacama and Qinghai concentration. Manufacturing gravity centers on China, South Korea, and Japan for cylindrical cell formats, with BMS firmware and inverter components drawing from Taiwanese semiconductor foundries. Single-source vulnerability in automotive-grade cylindrical supply constrains capacity expansion timelines for LiFePO4 specialists. Distribution runs through Amazon marketplace fulfillment centers and direct-to-consumer warehouse networks, bypassing contracting outdoor retail footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Demand bifurcation between recreational convenience and professional resilience creates fragmentation opportunity as van-life enthusiasts and remote construction crews pull procurement specifications in opposite directions.
For Market Incumbents: Secure proprietary inverter technology control and direct-to-consumer channel dominance before vehicle-to-load bidirectional charging from Ford and Rivian displaces standalone power stations at job sites. Expand LiFePO4 cylindrical cell sourcing through backward integration into Zhejiang BMS component suppliers. Certification investment in UL 2743 and FCC Part 15B pre-compliance compresses new product introduction timelines against emerging challengers. For New Entrants and Emerging Players: Lead with modular battery architectures targeting EU right-to-repair mandates and CSRD-adjacent product longevity requirements, where swappable cell packs and open diagnostic interfaces command premium positioning. India's PLI scheme for advanced chemistry cells offers the most penetrable geography for localized assembly alternatives to Shenzhen clusters. Go-to-market execution should emphasize TikTok-native influencer content for first-time buyer discovery in Australian warehouse-direct channels. For Investors and Strategic Acquirers: Capital is best deployed toward automotive-tier engineering descendants with in-house thermal runaway containment capabilities and cell-to-pack integration expertise, as capability scarcity constrains development benches for brands lacking battery engineering depth. Long-term viability over the next decade hinges on chemistry optimization trajectories and regulatory pre-compliance positioning. The signal to watch is carbon border adjustment implementation timelines reshaping sourcing economics for European market access.| Strategic Initiative | Industry Significance |
|---|---|
| LiFePO4 Chemistry Specialization | Cycle life ratings above 4,000 attract off-grid homesteaders accepting weight penalties. |
| MPPT Controller Integration | Solar generator bundling lifts average selling prices and extends replacement cycles. |
| Direct-to-Consumer Channel Expansion | Amazon marketplace optimization captures 60-70% of first-time buyer discovery. |
| Modular Battery Architecture Development | Swappable cell packs align with EU right-to-repair mandates and CSRD requirements. |
| Automotive-Tier BMS Certification | UL 2743 and FCC Part 15B validation compresses new product introduction timelines. |
Research Methodology
The analysis maps solar generator configurations, power station capacities, portable charger tiers, and battery pack modularity levels, each validated through procurement directors at disaster relief agencies, remote construction fleet managers, van-life community organizers, and off-grid homesteading cooperatives. Primary interview intelligence triangulates against customs records from Shenzhen and Dongguan export clusters, EPA and FCC regulatory filing databases, IRA tax credit eligibility documentation, and EU Battery Regulation due diligence guidance. Bottom-up unit economics from cell cost structures reconcile with top-down category revenue estimates across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs, with modeled segmentation spanning product type, use case, capacity threshold, and integration architecture. CAGRs derive from installed base growth rates, replacement cycle extensions from solar panel bundling, and penetration assumptions across emergency preparedness, off-grid living, and recreational activity applications. Forecast inputs incorporate lithium carbonate price volatility scenarios, diesel generator ban implementation timelines, and vehicle-to-load protocol adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained IRA credit extension, stable lithium carbonate supply from Qinghai and Salar de Atacama, and continued diesel displacement mandates on federally managed lands would require recalibration. Forecasts reflect documented assumptions regarding cell chemistry transition timelines and channel migration velocities. Revision becomes warranted when carbon border adjustment mechanisms or right-to-repair enforcement intensity crosses regulatory implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
Lithium-Ion Battery Metal Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
United Kingdom Electric Vehicle Battery Anode Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
United Kingdom Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
EV SOLID State Battery Market