
 Lithium-Ion (Li-Ion) Batteries Market | 2026-2036
Lithium-Ion (Li-Ion) Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion (Li-Ion) Batteries Market Insights
Project finance tied to gigafactory buildouts is reconfiguring which manufacturers can secure offtake agreements and scale cathode-active material capacity. CATL leverages its integrated mining-to-cell footprint to lock in long-term raw material streams. LG Energy Solution anchors its competitiveness through multi-billion-dollar project finance structures in North America and Europe. Samsung SDI differentiates via premium NCM chemistry specialization for automotive OEMs demanding higher energy density thresholds.
Lithium-ion batteries store electrochemical energy through reversible intercalation of lithium ions between a graphite anode and a metal-oxide cathode, typically operating at nominal voltages of 3.2 to 3.7 volts depending on cathode chemistry. Their primary industrial purpose centers on delivering high gravimetric energy density for mobility and grid-scale stationary storage applications. Pouch formats now dominate automotive pack architectures due to space efficiency and thermal management flexibility, while cylindrical cells sustain cost advantages in consumer electronics and certain electric vehicle platforms. LFP technology leads volume growth in commercial vehicle and energy storage deployments where cycle life and safety margins outweigh raw energy density requirements.
The EPA tailpipe emission standards and the EU Battery Regulation's recycled-content mandates are forcing cell producers to document carbon intensity and material provenance across supply chains. China's MIIT battery industry规范 and SAMR product safety standards shape which cell designs gain domestic production licenses and export eligibility. Stakeholders must monitor how divergent recycling obligations across jurisdictions reshape cost structures and sourcing geography decisions.
Market Dynamics
Cell producers face a structural squeeze between cathode metal price volatility and OEMs demanding cost-down roadmaps, forcing manufacturers to renegotiate offtake terms and accelerate in-house precursor production.
Growth Catalysts
- EPA tailpipe emission standards:US automotive OEMs must electrify light-duty fleets by 2032, mandating battery procurement at scale and reshaping supplier qualification timelines.
- Grid-scale stationary storage:Utility procurement of lithium-ion systems for renewable integration and peak shaving is accelerating deployment volumes across independent power producers.
- China's dual carbon goals:Domestic cell producers must decarbonize manufacturing processes to maintain export eligibility and state-backed project finance access.
Market Restraints
- Lithium carbonate price volatility:Spot market swings in South American and Australian spodumene concentrates compress cathode producer margins and destabilize contract pricing.
- Supply concentration risk:Over 70% of refined cobalt originates from the DRC, creating geopolitical exposure and forced labor scrutiny across due diligence frameworks.
- Technical limitation:Silicon anode expansion during cycling degrades cell longevity, limiting energy density gains in high-performance automotive applications.
Strategic Opportunities
- India's PLI scheme:Cell and module manufacturing incentives are attracting gigafactory investments to serve domestic two-wheeler and three-wheeler electrification.
- EU Battery Regulation recycled-content mandates:Producers establishing European hydrometallurgical recycling capacity gain preferential market access and compliance cost advantages.
- Solid-state electrolyte convergence:Sulfide and oxide ceramic technologies promise fire-safety improvements and simplified thermal management for aviation battery systems.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and manufacturing process engineers command premium compensation, constraining R&D expansion at mid-tier producers.
- Gigafactory capex intensity:Dry electrode coating and formation equipment require multi-year capital commitment before revenue recognition, straining balance sheets.
- EU Battery Regulation compliance timeline:Carbon footprint declaration and due diligence documentation obligations demand IT system overhauls with 2027 enforcement deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion (Li-Ion) Batteries Market |
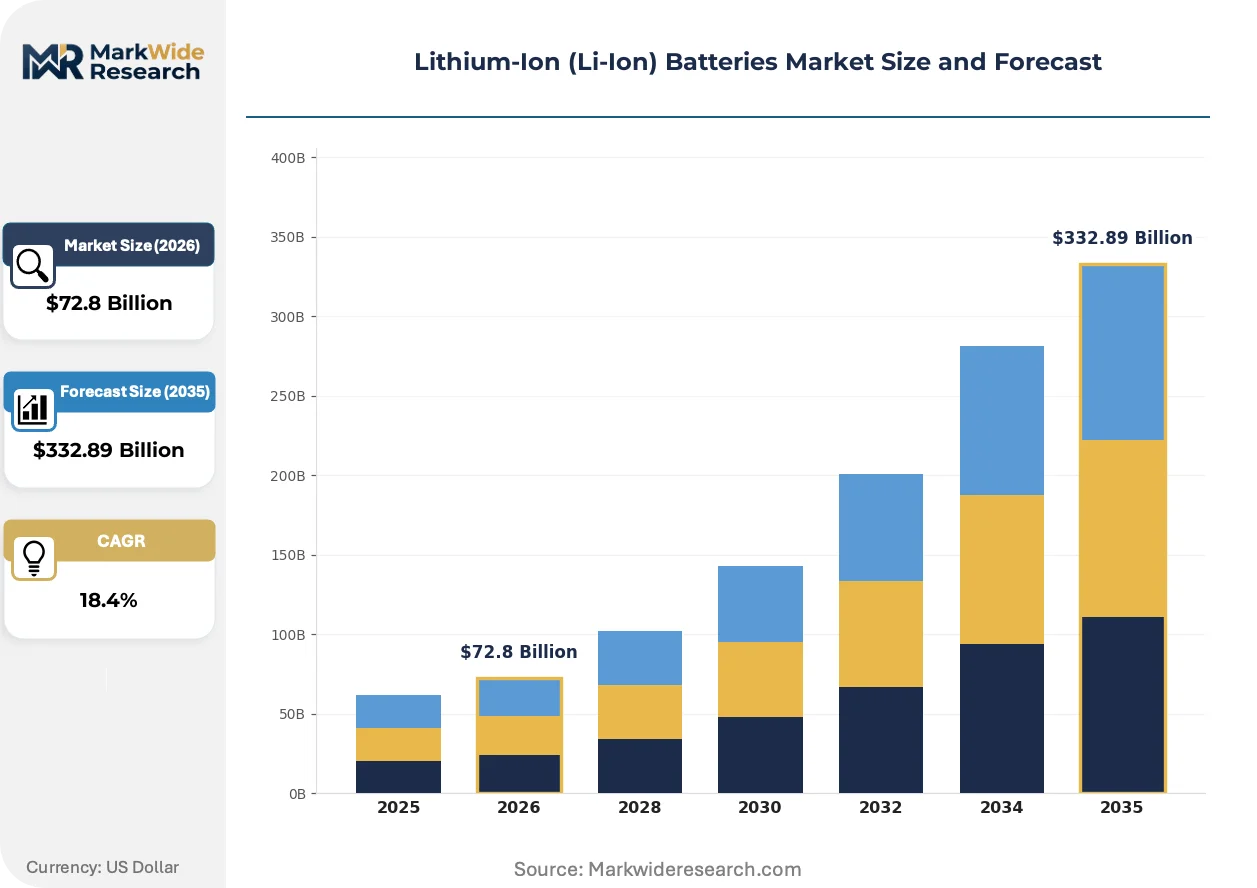
| Market Size in 2026 | $72.8 Billion |
| Market Size in 2035 | $332.89 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical, Prism, Pouch, Coin Application: Consumer Electronics, Electric Vehicles, Industrial Equipment, Renewable Energy Storage Technology: LFP, NMC, NCA, LTO End User: Automotive OEMs, Electronics Manufacturers, Energy Providers, Aerospace |
| Companies Covered | SK On, EVE Energy, CATL, SVOLT, Samsung SDI, BYD, Panasonic, Gotion High-Tech, LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion (Li-Ion) Batteries Market Trends and Innovations
Electrode manufacturing and pack architecture are undergoing simultaneous transformation as producers chase cost parity with internal combustion and regulatory compliance with material traceability mandates.
Lithium iron phosphate (LFP) cathode chemistry is collapsing the cost structure of commercial vehicle and energy storage battery packs. Fleet operators and utility procurement teams are specifying LFP-dominant configurations for their superior cycle life and thermal stability. This chemistry shift is compressing nickel cobalt manganese (NCM) market share in volume segments while redirecting cobalt and nickel demand toward premium automotive applications.
The EU Battery Regulation's due diligence and carbon footprint rules are forcing cell producers to restructure supplier relationships. Manufacturers must document material provenance from mining through refining or face market exclusion. Automotive OEMs with European assembly operations are now requiring tier-one battery suppliers to achieve EU-conformity assessment before contract award.
Long-term offtake contracting is displacing spot market purchasing among electric vehicle manufacturers. Cell producers and cathode material suppliers are negotiating five-to-ten-year volume commitments with price escalation clauses tied to lithium and cobalt indices. This procurement consolidation is most visible in Germany's industrial corridor, where OEMs anchor supplier investment decisions through guaranteed purchase minimums.
Lithium-Ion (Li-Ion) Batteries Market Segmentation
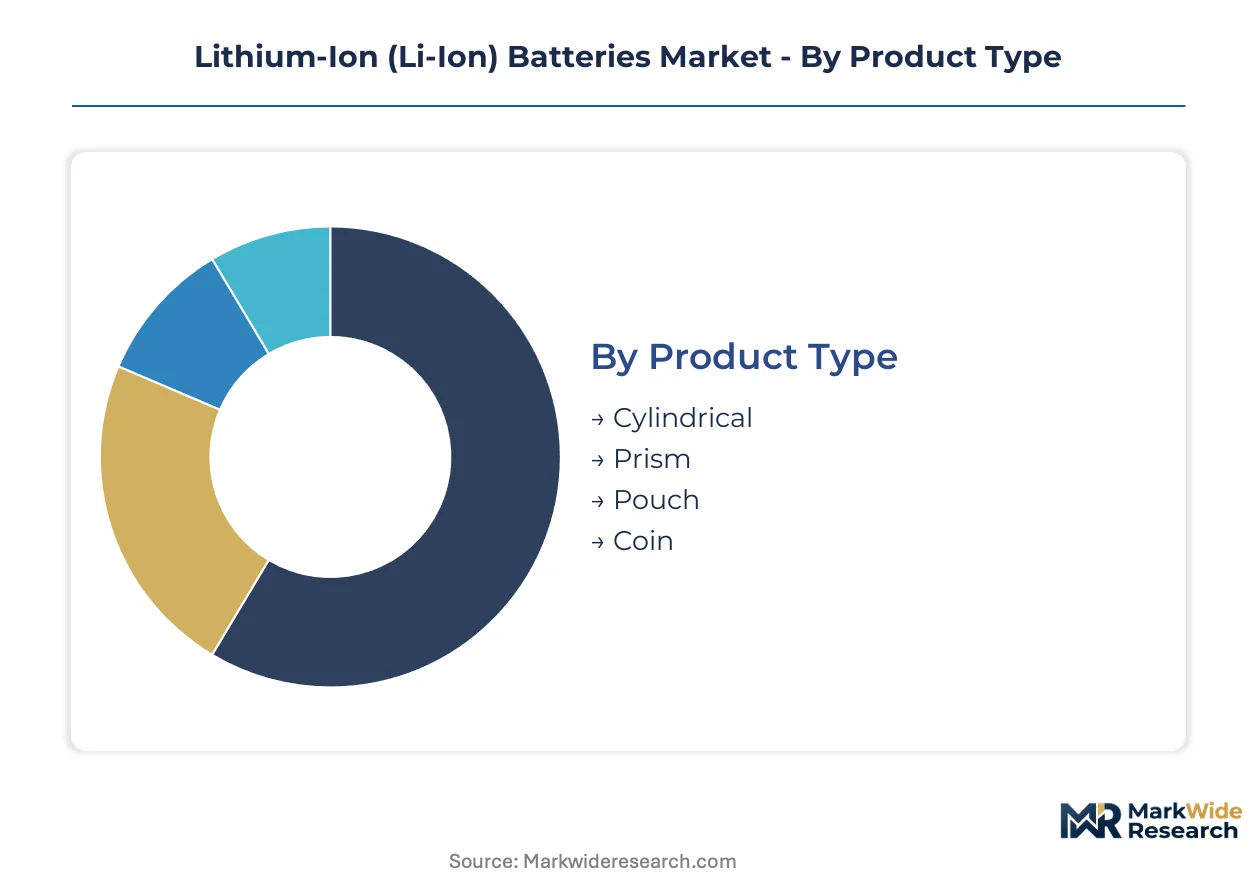
Cell format and chemistry decisions determine thermal management architecture, pack energy density, and manufacturing capital intensity. Procurement teams segment supplier qualifications around these technical boundaries rather than commodity pricing alone.
Product Type:
Format selection tracks directly to thermal runaway tolerance and automated assembly compatibility across end-use applications.
- Cylindrical:Steel-cased cells with jellyroll electrode winding deliver superior structural integrity for high-vibration environments. Tesla's 4680 format and power tool manufacturers anchor demand in Texas and Guangdong production corridors, with cell-to-pack designs eliminating module-level overhead.
- Pouch:Aluminum-laminated flexible enclosures maximize volumetric energy density through rectangular packing efficiency. Korean and Chinese automotive OEMs specify pouch architectures for European EV platforms where space constraints dominate design tradeoffs.
- Prism:Rigid aluminum-housed cells with stacked electrode layers balance thermal conductivity with form factor flexibility. Industrial forklift and marine propulsion systems in Germany's port cities specify prism formats for their repairability and cycle life predictability.
- Coin:Compact single-cell units with limited discharge rates serve medical implantables and IoT sensor networks. Swiss and Japanese precision electronics manufacturers maintain specialized procurement channels for these low-volume, high-reliability applications.
Established volume favors cylindrical formats for cost-scaled automotive programs; emerging adoption favors pouch architectures in premium European EV platforms.
Application:
End-use requirements diverge sharply on cycle life, discharge rate, and safety certification thresholds.
- Electric Vehicles:Automotive-grade cells must satisfy UN 38.3 transport testing and OEM-specific abuse tolerance protocols. German and Chinese OEM qualification timelines now span 24-36 months, with pack-level thermal propagation resistance as the gating technical requirement.
- Renewable Energy Storage:Grid-tied systems prioritize 6,000+ cycle life and passive thermal stability over gravimetric density. Texan and Australian utility-scale deployments specify LFP-dominant configurations for their degradation predictability under daily cycling regimens.
- Consumer Electronics:Smartphones and laptops demand maximum energy density within constrained form factors. Korean and Japanese electronics brands negotiate annual cost-down roadmaps that compress cathode supplier margins.
- Industrial Equipment:Forklifts, mining vehicles, and port automation systems require IP-rated enclosures and opportunity-charging compatibility. Warehouse automation deployments in the Netherlands and California specify standardized pack interfaces for fleet interoperability.
Procurement concentration clusters on electric vehicle platforms; steepest expansion trajectory appears in utility-scale storage as renewable penetration climbs.
Technology:
Cathode chemistry selection determines voltage profile, cobalt exposure, and recycling pathway economics.
- LFP:Iron-phosphate cathodes eliminate cobalt and nickel dependency while delivering 3.2V nominal voltage. Chinese cell producers dominate LFP capacity expansion, with BYD and CATL supplying European commercial vehicle OEMs seeking supply chain decoupling from DRC cobalt.
- NMC:Nickel-manganese-cobalt layered oxides optimize energy density through nickel content escalation from 523 to 811 stoichiometries. Korean producers anchor NMC competitiveness through precursor refining integration and Korean automotive OEM offtake commitments.
- NCA:Nickel-cobalt-aluminum formulations deliver highest gravimetric energy density for luxury automotive segments. Panasonic and Tesla's Nevada partnership sustains NCA specialization despite cobalt cost volatility.
- LTO:Lithium-titanate anode systems enable 10,000+ cycle life and sub-zero operation at the cost of energy density. Japanese rail and grid stabilization projects specify LTO for their degradation immunity under extreme temperature cycling.
Cost-sensitive volume applications favor LFP; performance-premium positioning favors high-nickel NMC and NCA variants.
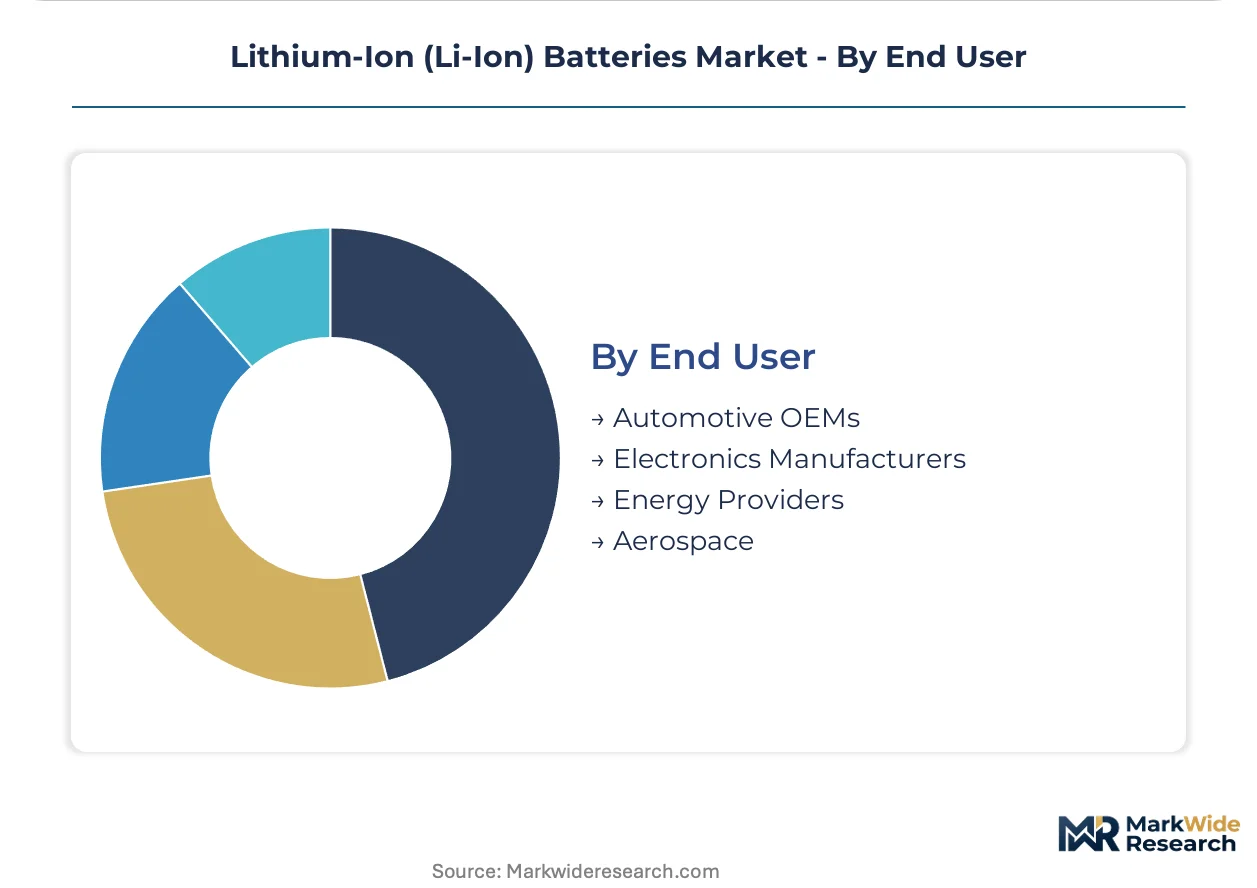
End User:
Customer procurement power and technical specification authority reshape supplier competitive dynamics.
- Automotive OEMs:Vehicle manufacturers impose cell-level traceability, carbon footprint documentation, and 15-year warranty terms. German OEMs now require EU Battery Regulation conformity assessment as a contract precondition, filtering supplier qualification pools.
- Energy Providers:Utility and independent power producer procurement emphasizes bankability, degradation warranties, and fire safety certification. Texan ERCOT-connected storage projects require NERC reliability compliance that European battery suppliers must newly navigate.
- Electronics Manufacturers:Consumer device brands prioritize supply assurance and annual cost reduction over technical differentiation. Korean and Chinese smartphone assemblers consolidate cell purchasing through long-term framework agreements with reduced spot market exposure.
- Aerospace:Aviation battery systems must satisfy FAA and EASA thermal runaway containment standards with 10^-9 failure probability. Emerging electric vertical takeoff programs in California and Toulouse specify solid-state development timelines that exceed current lithium-ion capabilities.
Contract concentration favors automotive OEMs for volume scale; margin premium favors aerospace qualification pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redrawing cell production geography as tariff exposure and carbon border adjustments penalize long supply chains. Countries with integrated cathode refining and gigafactory capacity are capturing trade flows that previously favored component importers.
China
Domestic EV sales and energy storage procurement absorb the majority of cell output from Yangtze River Delta producers. MIIT battery industry规范 and SAMR safety standards filter which designs gain production licenses and export eligibility. CATL and BYD anchor megascale facilities in Fujian and Shenzhen that supply European commercial vehicle OEMs seeking LFP chemistry.
Germany
Automotive OEM electrification timelines and utility-scale storage auctions drive demand concentration in the North Rhine-Westphalia industrial corridor. EU Battery Regulation recycled-content mandates and carbon footprint declarations reshape supplier qualification requirements. LG Energy Solution and CATL have committed gigafactory investments near Erfurt and Thuringia to localize supply for German vehicle assembly.
United States
IRA production tax credits and EPA tailpipe emission standards are accelerating domestic cell manufacturing commitments. ERCOT-connected storage projects in Texas and California ISO grid interconnections specify bankable degradation warranties that favor established cell producers. Panasonic's Nevada operations and SK On's Georgia facility exemplify the manufacturing migration toward end-market proximity.
South Korea
Premium NCM chemistry specialization and precursor refining integration sustain Korean competitiveness for high-energy-density automotive applications. MFDS industrial safety frameworks and METI-aligned export standards shape cell design protocols. Samsung SDI and LG Energy Solution anchor R&D and pilot production in Gyeonggi-do and Daejeon-Sejong corridors serving domestic Hyundai-Kia and export OEM contracts.
India
Two-wheeler and three-wheeler electrification under the PLI scheme is attracting cell and module assembly investments to Tamil Nadu and Gujarat. CEA grid connectivity standards and BIS product certification create compliance thresholds for storage system suppliers. Ola Electric and Ather Energy procurement commitments are pulling Korean and Chinese cell producers into joint venture discussions for local manufacturing.
Lithium-Ion (Li-Ion) Batteries Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cathode active material and precursor refining. The structure concentrates around five-to-eight cell producers with gigascale capacity, while mid-tier manufacturers compete on regional offtake relationships and chemistry specialization. Three archetypes dominate: integrated mining-to-cell conglomerates, chemistry-agnostic scale players, and premium-segment specialists. Capacity expansion and backward integration into precursor production represent the dominant competitive moves as metal price volatility compresses margins.
Among Korean producers, LG Energy Solution and Samsung SDI exemplify the chemistry-specialist archetype, with the former anchoring multi-regional project finance structures and the latter occupying premium NCM positioning for automotive OEMs. Chinese producers CATL and BYD represent integrated scale players with captive material streams and domestic market dominance. SK On sits within the expansion-focused tier, leveraging North American facility commitments to capture IRA-aligned procurement. These named entities illustrate how geographic production placement and chemistry portfolio decisions separate competitive positions without guaranteeing offtake security.
| Leading Market Players |
|---|
| SK On |
| EVE Energy |
| CATL |
| SVOLT |
| Samsung SDI |
| BYD |
| Panasonic |
| Gotion High-Tech |
| LG Energy Solution |
| Others |
Pricing and Supply Chain Analysis
Fujian province's cathode-active material refineries feed directly into CATL's megascale cell plants, concentrating upstream pricing power among integrated producers while downstream automotive OEMs demand multi-year cost-down roadmaps. This geographic clustering of precursor-to-cell capacity creates asymmetric bargaining dynamics between miners, refiners, and pack integrators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate procurement above spot-market purchasing. Pricing stratifies across automotive-grade certification tiers, UL-listed energy storage systems, and uncertified industrial forklift packs. Cost compression in commercial vehicle segments is intensifying because LFP chemistry expansion collapses cathode metal exposure. Fleet operators exhibit highest price sensitivity; aerospace qualification pathways command least sensitivity due to fire-safety certification premiums.
Supply Chain Analysis
Extended payment terms from Korean automotive OEMs and supply-chain finance facilities from Chinese state-backed institutions reshape working capital requirements across the value chain. Cathode precursor production concentrates in China, South Korea, and Japan; lithium carbonate refining draws from Australian spodumene and South American brine operations. Single-source vulnerability in DRC cobalt concentrates feeds tariff exposure into European carbon border adjustment calculations. Distribution runs through tier-one battery suppliers to automotive OEM assembly plants and utility-scale EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around German and Chinese automotive OEMs with multi-gigawatt-hour annual procurement commitments, squeezing supplier margins and reshaping qualification timelines. This concentration forces cell producers into captive capacity investments and long-term price escalation clauses.
For Market Incumbents: Entrench backward integration into precursor refining to offset lithium carbonate volatility and lock in cathode-active material streams. Accelerate EU Battery Regulation conformity assessment investments to preempt German OEM contract preconditions. Solid-state electrolyte R&D represents the priority capability defense against sulfide-ceramic disruptors. For New Entrants and Emerging Players: Establish a beachhead in India's two-wheeler and three-wheeler electrification segment where PLI scheme incentives reduce capital barriers and Korean-Chinese joint venture gaps create procurement openings. Target utility-scale storage in Texas ERCOT and California ISO territories where bankability requirements filter incumbent-dominated supplier pools. Lead with LFP chemistry specialization and degradation warranty guarantees. For Investors and Strategic Acquirers: Long-term, this sits as a materials-chemistry play because cathode precursor refining and hydrometallurgical recycling capacity will capture margin expansion as EU recycled-content mandates tighten. Acquisition targets should screen for European hydrometallurgical recycling assets with EU Battery Regulation-aligned carbon footprint documentation systems. The signal to watch is German automotive OEM qualification timeline compression as solid-state development timelines extend.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | CATL and LG Energy Solution anchor competitiveness through captive cathode-active material streams. |
| EU Battery Regulation Conformity Assessment | Cell producers achieving carbon footprint documentation gain preferential German OEM contract access. |
| LFP Chemistry Capacity Expansion | BYD and CATL supply European commercial vehicle OEMs seeking DRC cobalt supply chain decoupling. |
| Hydrometallurgical Recycling Investment | Producers establishing European recycling capacity secure compliance cost advantages under recycled-content mandates. |
| Solid-State Electrolyte R&D Partnership | Sulfide and oxide ceramic development targets aviation battery systems exceeding current lithium-ion thermal runaway standards. |
Research Methodology
Operator-level perspectives from cell manufacturing plant managers, automotive OEM procurement leads, utility-scale storage project developers, and cathode material R&D directors anchored the qualitative base. Primary interview findings triangulated against secondary sources including MIIT battery industry规范 filings, EPA tailpipe emission standard regulatory dockets, EU Battery Regulation implementation guidance, and customs trade data on lithium carbonate and cobalt concentrate flows. Bottom-up cell capacity buildout tracking and top-down automotive electrification mandate analysis converged on segment-level sizing.
Scenario-bracketing around lithium carbonate price volatility bands and EU carbon border adjustment implementation timelines framed the projection horizon. Segmentation modeling incorporated cell format, cathode chemistry, end-use application, and regional regulatory cluster dimensions. CAGRs derived from installed capacity ramp rates, OEM electrification procurement commitments, and utility-scale storage auction pipelines across the analysis window. Forecast inputs included German gigafactory investment announcements and Indian PLI scheme disbursement trajectories.
Sensitivities concentrate around South American lithium brine supply disruptions, DRC cobalt export restrictions, and solid-state electrolyte technology breakthrough timelines. Forecasts reflect documented assumptions on cathode chemistry substitution rates and automotive OEM platform electrification cadence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
Advanced Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium Solid-State Battery Market
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
Lithium-Ion Manganese Oxide Battery Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Salt Lake Battery Grade Lithium Carbonate Market