
 Automotive Lithium Based Battery Market | 2026-2036
Automotive Lithium Based Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Lithium Based Battery Market Analysis
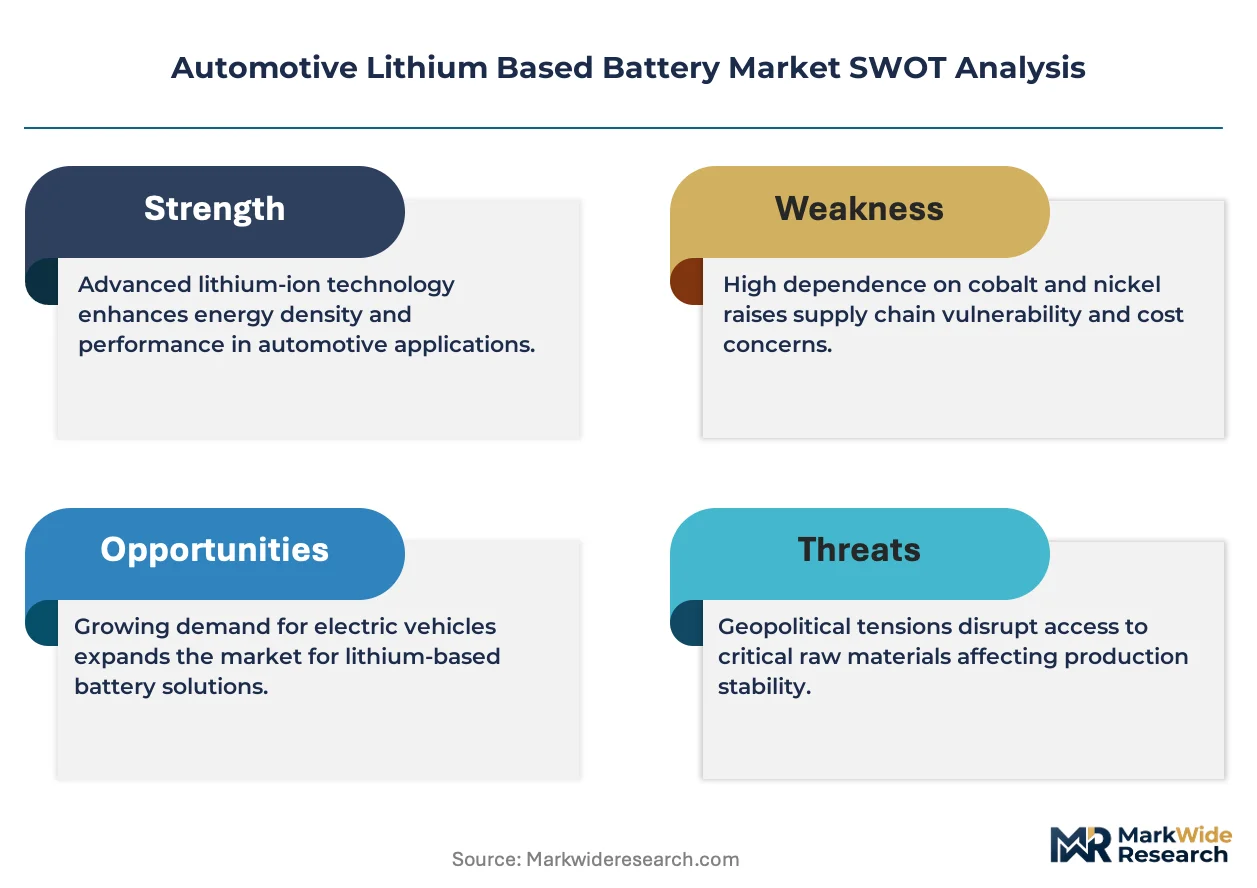
China's gigafactory expansion is reshaping supply geography across the automotive lithium based battery value chain. Contemporary Amperex Technology Co. Limited leverages integrated cathode material production to secure feedstock access at scale. LG Energy Solution anchors its position through joint ventures with multiple US and European automakers. Samsung SDI competes on premium cylindrical cell architectures for performance electric vehicles.
Automotive lithium based batteries store electrochemical energy through lithium-ion intercalation between layered oxide cathodes and graphite anodes, with nominal voltages ranging from 3.2V for lithium iron phosphate to 3.7V for nickel manganese cobalt chemistries, serving as the primary traction energy source for electrified powertrains. LFP chemistry dominates entry-level electric vehicle segments where cost per kilowatt-hour and thermal stability outweigh energy density requirements. Solid-state technology represents the fastest-growing research frontier as developers target ceramic or sulfide electrolytes to eliminate flammable liquid components. OEM procurement from battery manufacturers concentrates volume in long-term offtake agreements that lock in capacity years ahead of vehicle platform launches.
The EU Battery Regulation and China's MIIT GB standards together establish divergent compliance pathways for carbon accounting and cell performance testing. EPA tailpipe rules and NHTSA fuel economy standards in the United States indirectly accelerate lithium cell demand by mandating fleet electrification timelines. Stakeholders must monitor regulatory fragmentation across these three jurisdictions as divergent recycling mandates and safety certification requirements multiply compliance costs for multinational suppliers.
Market Dynamics
Automotive lithium based battery procurement is consolidating around long-term offtake agreements as OEMs lock in cell capacity three to five years ahead of vehicle platform launches, compressing supplier negotiation leverage and reshaping capital allocation across the value chain.
Growth Catalysts
- EU Battery Regulation:Mandates for carbon footprint declarations and recycled content thresholds create compliance-driven replacement demand for European-sourced cells.
- Electric vehicle OEM procurement:Original equipment manufacturers electrifying model lineups are signing multi-gigawatt-hour contracts that guarantee offtake for new manufacturing capacity.
- Lithium iron phosphate chemistry:Entry-level electric vehicle segments favor LFP cells where cost per kilowatt-hour and thermal stability outweigh energy density requirements.
Market Restraints
- Upstream concentration:Cathode active material production concentrates in China, exposing non-Chinese cell manufacturers to feedstock access risk during trade friction.
- Technical limitation:Liquid electrolyte architectures face inherent flammability constraints that cap fast-charging rates in high-nickel chemistries.
- Regulatory friction:Divergent carbon accounting methodologies between EU Battery Regulation and China's MIIT GB standards multiply compliance costs for multinational suppliers.
Strategic Opportunities
- Solid-state electrolyte convergence:Ceramic and sulfide electrolyte research targets elimination of flammable liquid components while enabling lithium metal anodes.
- US domestic manufacturing:IRA production tax credits incentivize cell and module assembly localization for qualifying electric vehicle supply chains.
- Second-life stationary storage:Retired automotive packs find application in grid-scale energy storage, extending value capture beyond initial vehicle service.
Industry Challenges
- Electrolyte formulation expertise:Solid-state development requires scarce materials science talent familiar with ceramic processing and interfacial engineering.
- Cell-to-pack integration complexity:Structural battery architectures demand redesigned thermal management systems and crashworthiness validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Lithium Based Battery Market |
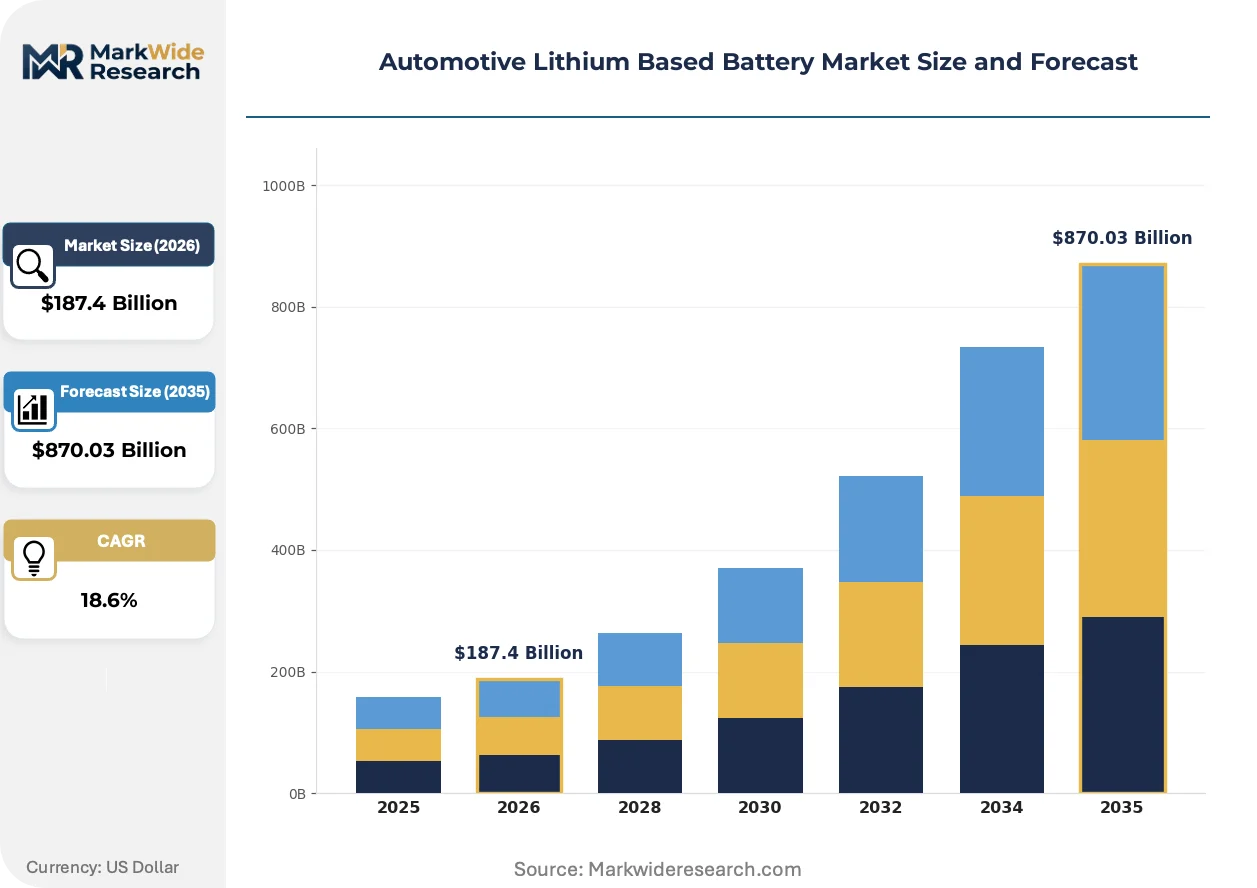
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $870.03 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Li-Ion, NMC, LFP, NCA Application: Electric Vehicles, Hybrid Vehicles, E-Bikes, Energy Storage Systems Technology: Battery Management Systems, Fast Charging, Solid-State Technology, Wireless Charging End User: OEMs, Aftermarket Providers, Fleet Operators, Battery Manufacturers |
| Companies Covered | Contemporary Amperex Technology Co. Limited, LG Energy Solution, Panasonic Holdings Corporation, BYD Company Ltd., Samsung SDI, SK Innovation, AESC, GS Yuasa Corporation, Northvolt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Lithium Based Battery Market Emerging Trajectories
Cell manufacturing is digitizing quality control and production scheduling, while regulatory pressure on carbon intensity and end-of-life accountability accelerates process innovation across cathode material synthesis and recycling infrastructure.
Silicon anode blends are digitizing energy density trajectories in premium cylindrical cells by replacing graphite with silicon-oxide composites that store more lithium ions per unit mass. High-performance electric vehicle platforms from luxury OEMs are adopting these architectures first. This chemistry shift is digitizing the competitive boundary between nickel manganese cobalt and lithium iron phosphate cost positions.
China's MIIT GB standards establish mandatory cell performance testing and traceability requirements that diverge from EU Battery Regulation carbon accounting methodologies. Domestic manufacturers must maintain dual compliance documentation for export markets. European suppliers face the steepest adaptation burden as they reconfigure quality management systems for divergent certification pathways.
Fleet operators and leasing companies are consolidating procurement through battery-as-a-service contracts that unbundle cell ownership from vehicle acquisition. This financing structure transfers residual value risk to cell manufacturers and specialized asset managers. Germany and the Netherlands show the fastest contract penetration where commercial electric vehicle adoption concentrates in regulated urban access zones.
Automotive Lithium Based Battery Market Segmentation
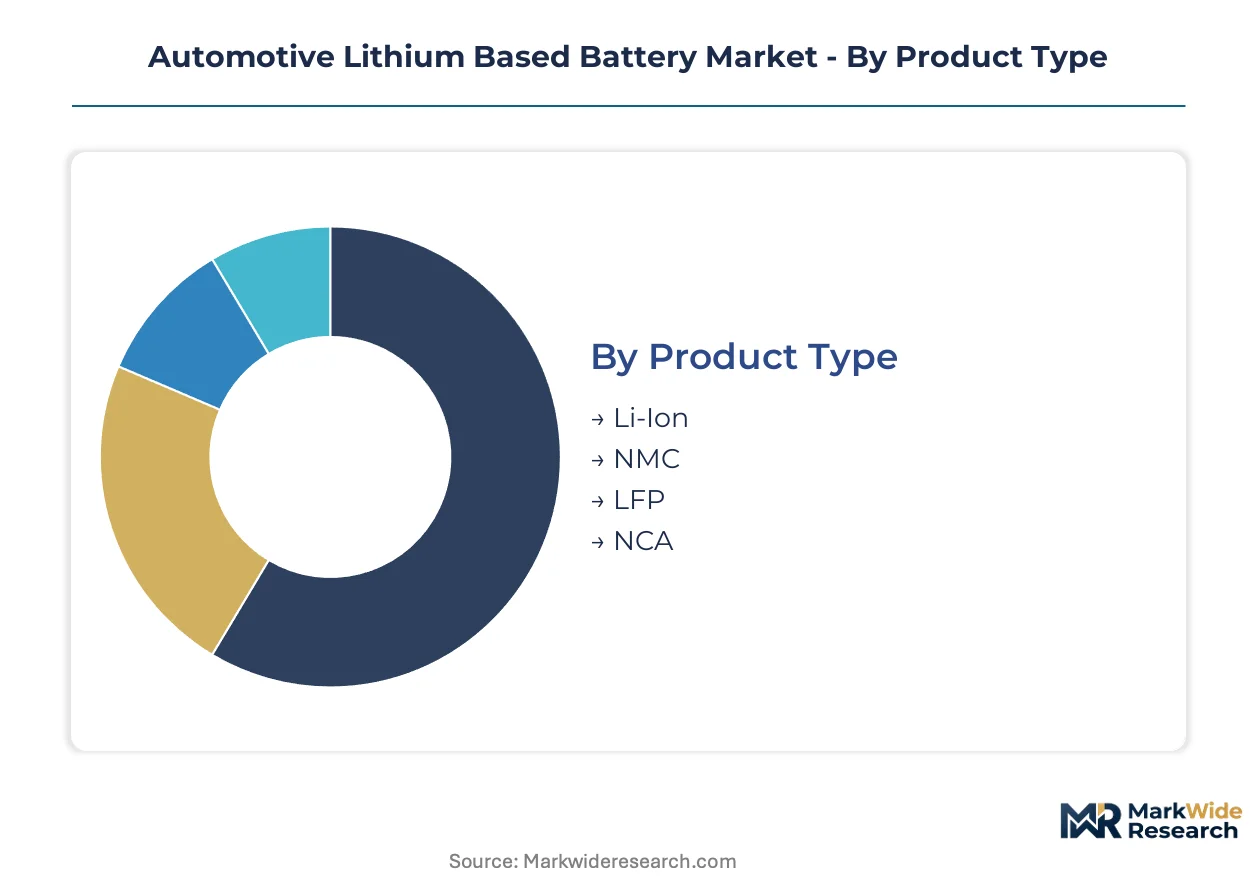
Automotive lithium based battery segmentation reveals how chemistry selection, application requirements, and procurement models fragment demand across divergent performance and cost specifications. Understanding these divides clarifies where cell manufacturers must configure production lines and which technology investments align with volume concentration.
Product Type:
Cell chemistry selection spans energy density, thermal stability, and cost trade-offs that map directly onto vehicle segment positioning and regional regulatory temperature.
- NMC:Nickel manganese cobalt layered oxide cathodes deliver 250-300 Wh/kg energy density, enabling 500+ kilometer range in premium electric vehicles. European OEM procurement concentrates here as EEA fleet CO₂ mandates drive long-range battery electric vehicle deployment.
- LFP:Lithium iron phosphate chemistry sacrifices 15-20% energy density for intrinsic thermal stability and 30% lower cell cost. Chinese domestic manufacturers dominate LFP production capacity, feeding entry-level electric vehicle platforms where range-per-dollar dominates consumer purchase decisions.
- Li-Ion:Generic lithium-ion architectures encompass blended cathode formulations and legacy graphite anode designs serving hybrid vehicle applications with moderate cycle depth requirements.
- NCA:Nickel cobalt aluminum oxide cells achieve the highest volumetric energy density in cylindrical formats, anchoring performance electric vehicle platforms from Tesla and Lucid Motors where pack mass directly impacts acceleration and handling metrics.
The dominant share belongs to NMC, while LFP is closing the gap fastest.
Application:
End-use segmentation tracks how duty cycles, scale economics, and ownership models reshape cell specification requirements.
- Electric Vehicles:Passenger car platforms demand 50-100 kWh packs with 8-year/160,000 km warranty coverage, driving cell selection toward high-nickel chemistries and precision thermal management. OEM direct procurement locks in multi-gigawatt-hour annual volumes through dedicated supply agreements.
- Energy Storage Systems:Stationary applications prioritize cycle life over energy density, with LFP chemistry capturing utility-scale deployments due to 6,000+ cycle durability and reduced fire suppression infrastructure costs.
- Hybrid Vehicles:Smaller 1-2 kWh packs operate at partial state-of-charge windows, favoring power-optimized cells with high discharge rate tolerance for engine-assist functionality.
- E-Bikes:Light electric vehicle segments source cylindrical 18650 or 21700 cells in 500-1,000 Wh configurations, with aftermarket replacement demand creating fragmented procurement channels.
Electric Vehicles commands the majority of cell volume, though Energy Storage Systems is expanding most quickly as grid decarbonization accelerates.
Technology:
Technology segmentation isolates where value-added components and charging infrastructure create differentiation beyond commodity cell production.
- Battery Management Systems:Cell balancing algorithms, state-of-charge estimation, and thermal runaway detection firmware protect pack integrity across 10+ year service life. OEMs increasingly specify ASIL-D functional safety requirements that favor tier-1 electronics suppliers.
- Solid-State Technology:Ceramic and sulfide electrolyte research targets elimination of flammable liquid components while enabling lithium metal anodes. Toyota and QuantumScape lead development timelines with pilot production targeting mid-decade commercialization.
- Fast Charging:800V architectures and enhanced cooling loops enable 10-80% state-of-charge in under 20 minutes, demanding cells with reduced lithium plating susceptibility at high C-rates.
- Wireless Charging:Inductive pad systems at 11-22 kW power levels require receiver coil integration into pack enclosures, with standardization gaps across SAE J2954 and IEC 61980 complicating multi-market deployment.
Battery Management Systems anchors current revenue, yet Solid-State Technology holds the steepest expansion trajectory as safety and energy density converge.
End User:
Procurement channel segmentation distinguishes between captive supply relationships and open market transactions.
- OEMs:Volkswagen, BYD, and Ford negotiate multi-year offtake agreements that guarantee capacity allocation and pricing corridors, transferring volume risk to cell manufacturers in exchange for platform integration collaboration.
- Fleet Operators:Battery-as-a-service contracts from Arrival, Volta Trucks, and municipal transit authorities unbundle cell ownership from vehicle acquisition, transferring residual value risk to specialized asset managers.
- Battery Manufacturers:Tier-2 cell producers source electrode materials and separator films for module assembly, creating intermediate demand for active materials and precision coating equipment.
- Aftermarket Providers:Independent service networks and collision repair facilities source replacement modules and diagnostic tools, with right-to-repair legislation in Massachusetts and proposed EU rules expanding channel access.
OEMs retain the dominant procurement volume, while Fleet Operators are gaining share fastest as commercial electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: China deploys automotive lithium based batteries predominantly in mass-market electric vehicle platforms, while European and North American procurement emphasizes premium long-range configurations with stricter carbon accountability requirements.
China
Domestic electric vehicle sales absorb over half of global cell output, with MIIT GB standards mandating traceability and performance testing for all domestic production. The Yangtze River Delta cluster houses cathode material synthesis facilities that feed integrated gigafactory operations.
Germany
Premium OEM platform launches drive demand for high-nickel chemistries with extended cycle warranties, with EU Battery Regulation carbon footprint declarations required from 2027. North Rhine-Westphalia hosts pilot solid-state research facilities alongside established module assembly plants.
United States
IRA production tax credits reshape cell procurement toward qualifying domestic assembly, with EPA tailpipe rules accelerating fleet electrification timelines. The Southeast region attracts module manufacturing investments serving Detroit and Southern California vehicle assembly.
South Korea
Cylindrical cell exports anchor the trade balance, with METI-aligned safety standards enabling premium electric vehicle supply to Japanese and European OEMs. The Busan-Ulsan corridor concentrates electrode coating capacity and maritime logistics infrastructure.
Japan
Hybrid vehicle demand sustains moderate cell volumes, with Toyota's solid-state pilot line targeting sulfide electrolyte commercialization by mid-decade. The Nagoya industrial zone maintains precision separator film and electrolyte salt production capabilities.
Automotive Lithium Based Battery Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three to five dominant cell manufacturers controlling over seventy percent of installed capacity, with tier-two specialists occupying regional niches or chemistry-specific segments. Strategic archetypes separate integrated cathode producers from pure-play cell assemblers and technology licensors. Competitive moves concentrate on multi-year offtake negotiations and backward integration into active material production.
Within the integrated manufacturing tier, Contemporary Amperex Technology Co. Limited exemplifies captive cathode supply advantages, while LG Energy Solution occupies a position bridging Korean cylindrical expertise with Western joint venture structures. BYD Company Ltd. represents the automotive-captive archetype where cell production serves in-house vehicle platforms exclusively.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| BYD Company Ltd. |
| Samsung SDI |
| SK Innovation |
| AESC |
| GS Yuasa Corporation |
| Northvolt |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta cluster anchors cathode active material production capacity exceeding half of global installed base, translating concentrated feedstock access into asymmetric pricing power for integrated Chinese cell manufacturers serving European and North American OEM procurement.
Pricing Analysis
Geographic price spreads between Chinese domestic contract rates and European delivered-cell pricing exceed 15-20% after carbon accounting compliance costs and logistics. Three-tier pricing structure across premium cylindrical NCA, standard prismatic NMC, and economy prismatic LFP levels dominates OEM procurement. Cost compression in entry-level LFP segments is intensifying because domestic Chinese manufacturers expand integrated cathode capacity. Fleet operators and commercial vehicle buyers exhibit highest price sensitivity, while luxury OEMs prioritize energy density and fast-charging tolerance over per-kilowatt-hour cost.
Supply Chain Analysis
Export control regimes including US Department of Commerce Entity List restrictions and EU critical raw materials screening limit cathode precursor technology transfers to non-allied manufacturing jurisdictions. Supply concentrates in China for cathode active materials, South Korea for cylindrical cell assembly, and Japan for separator films and electrolyte salts. Cell production draws from lithium carbonate from Chile and Australia, nickel from Indonesia, and cobalt from the Democratic Republic of Congo. Single-source vulnerability concentrates in Chinese-controlled graphite anode processing. Distribution runs through long-term offtake agreements that lock in capacity three to five years ahead of vehicle platform launches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where cell-to-pack structural architectures and 800V charging ecosystems are consolidating around interoperability standards that will determine which manufacturers capture modular reuse value across vehicle generations.
For Market Incumbents: Harden cathode material supply positions through backward integration into lithium conversion or binding offtake with Australian and Chilean spodumene producers. Secure ASIL-D functional safety certification for battery management systems firmware to defend against tier-1 electronics suppliers encroaching on pack integration revenue. Prioritize solid-state electrolyte pilot lines to maintain technology optionality against sulfide-ceramic breakthroughs from Japanese competitors. For New Entrants and Emerging Players: Second-life stationary storage aggregation for grid-scale frequency regulation represents the most penetrable entry point, requiring minimal cell manufacturing capital versus automotive qualification. Target North American commercial fleet operators seeking battery-as-a-service contracts under IRA production tax credit eligibility. Pursue joint development agreements with European energy utilities for retired automotive pack repurposing rather than competing head-to-head in cell manufacturing scale. For Investors and Strategic Acquirers: Long-term, this sits as a materials-chemistry consolidation play because active material synthesis expertise and solid-state intellectual property will concentrate value capture as liquid-electrolyte commoditization accelerates. Acquire specialists in silicon-anode blending or ceramic electrolyte processing rather than pure-play cell assemblers. Monitor NHTSA and EPA rulemaking velocity as the inflection signal for North American demand acceleration versus European regulatory saturation.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Cell Supply Agreement | Locks in capacity allocation for OEM platform launches under EPA fleet electrification mandates. |
| Backward Integration into Cathode Materials | Secures lithium carbonate and nickel sulfate feedstock access against MIIT export license restrictions. |
| Solid-State Electrolyte Pilot Production | Positions for sulfide-ceramic commercialization ahead of Toyota's mid-decade timeline. |
| Battery-as-a-Service Platform Launch | Captures residual value from retired packs in German and Dutch commercial fleet markets. |
| Second-Life Storage System Deployment | Extends value capture from automotive cells into grid-scale frequency regulation contracts. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement directors, cathode material plant managers, and utility-scale storage developers anchored the qualitative base. Primary interviews triangulated against secondary sources including MIIT GB standard filings, EU Battery Regulation delegated act drafts, EPA tailpipe rule dockets, IHS Markit vehicle production databases, and customs trade data for lithium carbonate and nickel sulfate flows. Bottom-up cell demand modeling by vehicle segment converged with top-down cathode material capacity assessments.
Scenario-bracketing framed low, baseline, and high electrification penetration assumptions across the projection horizon. Segmentation dimensions modeled include cell chemistry tier, vehicle propulsion architecture, OEM procurement channel, and regional regulatory cluster. CAGRs derived from installed capacity buildout schedules and vehicle platform launch timelines. Industry-specific inputs encompassed IRA tax credit eligibility criteria and EU Battery Regulation carbon intensity thresholds.
Macroeconomic conditions sit as an overlay; deviation in lithium spot prices, nickel exchange volatility, or trade policy friction would shift the trajectory. Forecasts reflect documented assumptions on cathode chemistry mix evolution and solid-state commercialization timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Global Lithium Ion Cell and Battery Pack Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Anode Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Asia-Pacific Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Lithium Cobalt Oxide Battery (LCO) Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market