
 India Electric Vehicle Battery Materials Market | 2026-2036
India Electric Vehicle Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Vehicle Battery Materials Market Insights
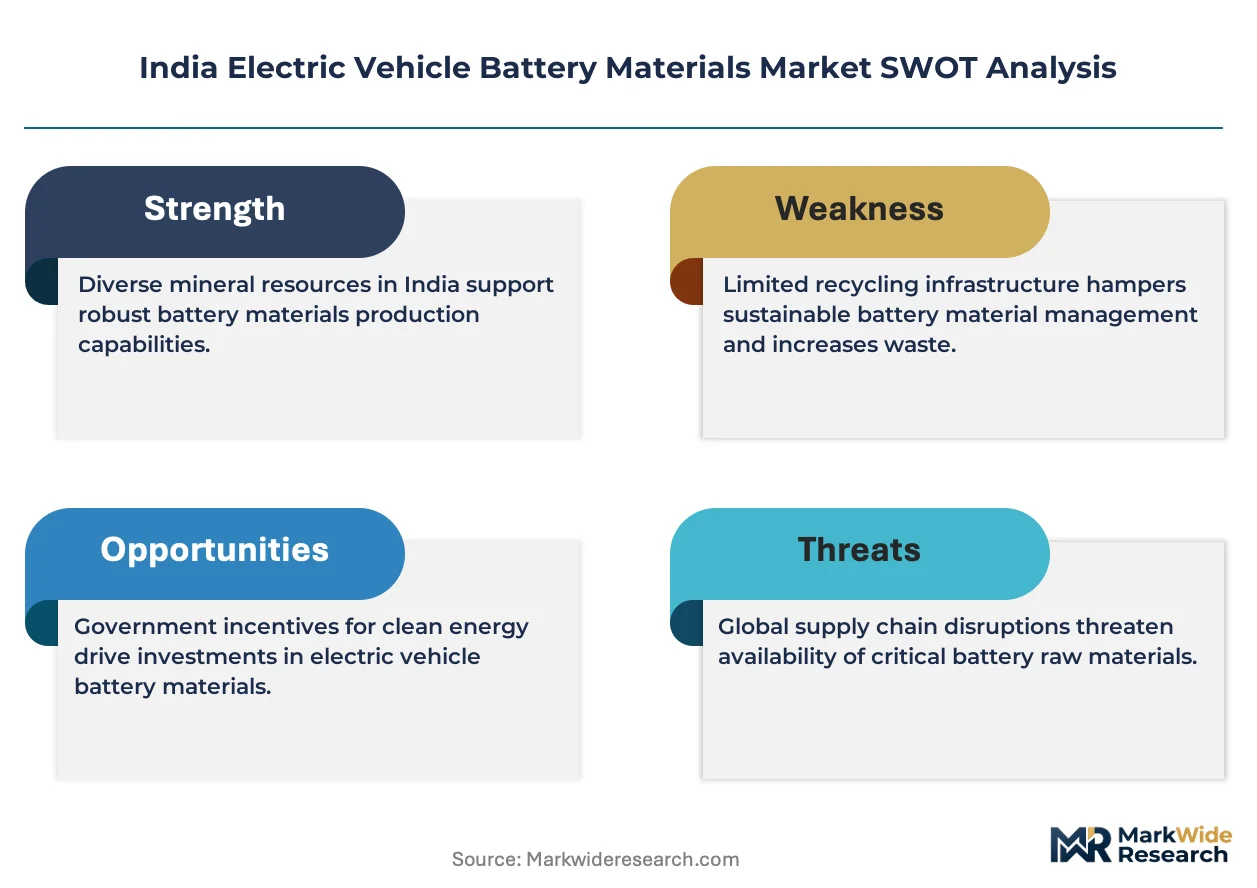
A capital-intensity divergence between integrated cathode producers and import-dependent midstream converters is redrawing competitive boundaries in India's battery materials sector. Tata Chemicals leverages its Soda Ash-derived lithium carbonate feedstock to anchor domestic precursor production. Himadri Speciality Chemicals specializes in coal-tar pitch for anode binders, occupying a narrow but defensible niche. Exide Industries competes through its established lead-acid infrastructure while navigating lithium-ion transition costs.
India Electric Vehicle Battery Materials encompass active and passive substances—cathode powders, anode graphite, electrolyte salts, and separator membranes—that enable electrochemical energy storage with specific energy densities exceeding 250 Wh/kg for NMC formulations. These materials constitute the core cost stack in lithium-ion cells, directly determining cycle life, thermal stability, and charge rates for automotive applications. Lithium-ion and Nickel Cobalt Manganese chemistries dominate current procurement volumes, though Lithium Iron Phosphate is gaining structural share in commercial vehicle segments where safety margins outweigh energy density requirements. Among battery types, Fast Charging Batteries command premium positioning due to silicon-doped anode and high-voltage electrolyte formulations, while Solid State Batteries remain pre-commercial with margin pools concentrated in patent licensing rather than manufacturing.
BIS certification mandates for cell safety and performance, combined with the Ministry of Heavy Industries' PLI scheme disbursement rules, are tightening domestic content thresholds and redirecting procurement toward local electrode and electrolyte suppliers. The CEA's technical standards for battery energy storage systems extend these requirements to grid-coupled applications, broadening the addressable material base. Stakeholders must weigh backward integration into precursor chemicals against offtake agreements with refining partners as capacity buildout decisions crystallize.
Market Dynamics
India's PLI scheme for advanced chemistry cell manufacturing is concentrating capital flows toward domestic precursor production, forcing midstream converters to choose between backward integration into lithium carbonate refining or surrendering margin to integrated cathode producers.
Growth Catalysts
- PLI scheme disbursement rules:The Ministry of Heavy Industries ties fiscal incentives to domestic content thresholds, redirecting procurement toward local electrode and electrolyte suppliers.
- Two-wheeler electrification:Tier-2 and tier-3 cities are accelerating uptake as battery-swapping infrastructure spreads through Gujarat and Tamil Nadu manufacturing clusters.
- Lithium Iron Phosphate chemistry:Commercial vehicle segments favor this formulation where safety margins outweigh energy density requirements, expanding addressable material volumes.
Market Restraints
- Spodumene concentrate dependence:Domestic converters lack captive lithium feedstock, exposing margin structures to Australian and Chilean mining output volatility.
- BIS certification timelines:Cell safety and performance mandates create extended validation cycles that delay commercial offtake for new electrode formulations.
- Graphite anode supply concentration:Synthetic and natural graphite processing capacity clusters in China, constraining India's anode supply security.
Strategic Opportunities
- Karnataka cell manufacturing clusters:Underdeveloped electrolyte salt and separator membrane capacity creates white space for specialty chemical entrants.
- CEA technical standards for grid storage:Battery energy storage system mandates extend domestic content requirements beyond automotive into stationary applications.
- Solid-state patent licensing:Pre-commercial margin pools concentrate in intellectual property rather than manufacturing, favoring R&D-intensive material developers.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and thermal management expertise remains concentrated among a small pool of specialists with lithium-ion platform experience.
- Precursor chemical capex intensity:Nickel sulfate and cobalt hydroxide refining requires billion-rupee furnace investments with long depreciation horizons.
- Legacy lead-acid infrastructure:Exide Industries and Amara Raja must navigate stranded asset risk while funding parallel lithium-ion transition programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Vehicle Battery Materials Market |
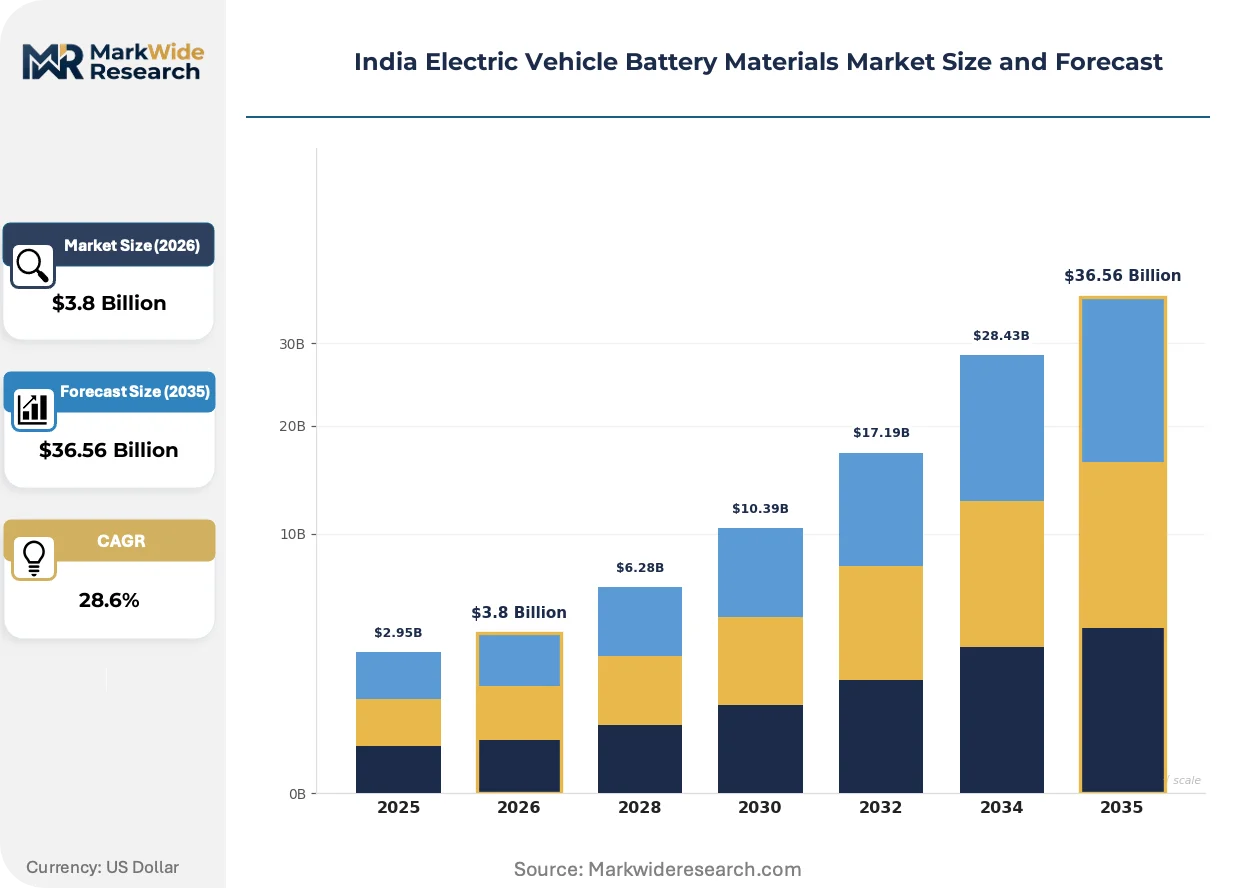
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium-ion, Nickel Cobalt Manganese, Lithium Iron Phosphate, Lead Acid End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions Battery Type: Standard Batteries, Fast Charging Batteries, Solid State Batteries, Swappable Batteries Component: Electrodes, Electrolytes, Separators, Conductors |
| Companies Covered | BASF SE, Mitsubishi Chemical Group Corporation, Umicore, Sumitomo Chemical Co. Ltd., UBE Corporation, Exide Industries, Tata Chemicals, Himadri Speciality Chemicals, Aether Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Vehicle Battery Materials Market Trends and Innovations
Active material formulations and manufacturing process architectures are undergoing simultaneous transformation, with silicon-doped anodes and high-nickel cathodes compressing legacy technology margins while policy mandates accelerate domestic supply chain buildout.
Silicon-doped graphite anodes are supplanting conventional carbon-only formulations in fast-charging battery architectures. Premium two-wheeler and three-wheeler OEMs in Gujarat and Tamil Nadu specify these materials to achieve sub-30-minute charge cycles. The technology is compressing procurement volumes for traditional spherical graphite while expanding demand for nano-silicon precursor suppliers.
The Ministry of Heavy Industries' PLI scheme disbursement rules now require 25% domestic value addition for cell manufacturers to qualify for fiscal incentives. This industrial consequence redirects electrode and electrolyte procurement toward local suppliers with BIS certification. Commercial vehicle battery pack assemblers are responding by signing multi-year offtake agreements with Himadri Speciality Chemicals and Tata Chemicals to lock in qualifying supply.
Fleet operators and battery-swapping network providers are consolidating procurement decisions at the state level rather than through fragmented dealer networks. Tamil Nadu and Karnataka energy service companies now negotiate directly with cathode active material producers for volume discounts tied to charging infrastructure deployment commitments. This channel consolidation is most visible in last-mile logistics electrification, where aggregated demand from e-commerce delivery fleets exceeds individual OEM procurement volumes.
India Electric Vehicle Battery Materials Market Segmentation
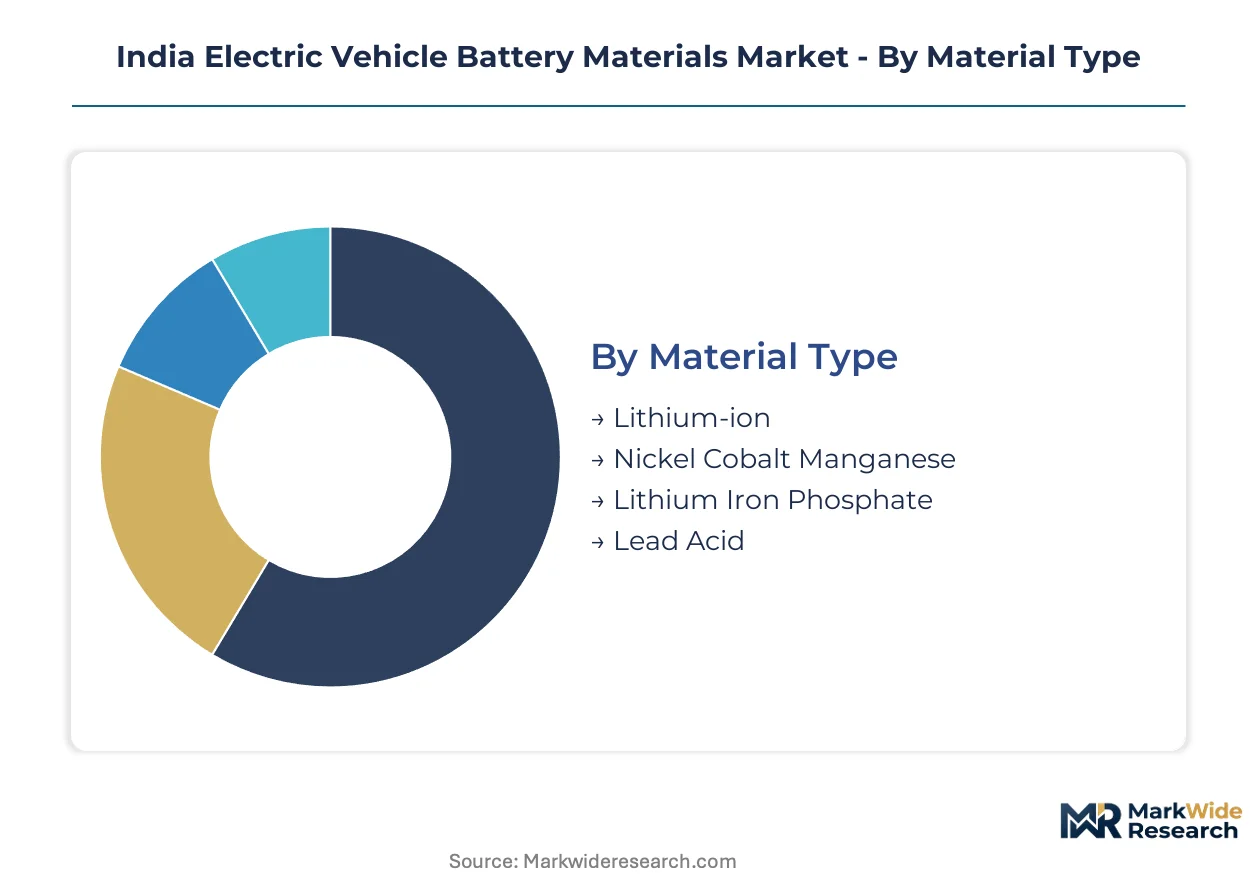
Segmentation in India's battery materials market reveals how chemistry choices, procurement channels, and cell architectures create divergent margin pools. Each dimension exposes distinct competitive pressures: material substitution threats, customer consolidation patterns, and component-level supply security gaps.
Material Type:
Nickel Cobalt Manganese faces the most acute substitution pressure from Lithium Iron Phosphate in commercial vehicle applications where thermal stability overrides energy density requirements.
- Lithium-ion:Encompasses liquid electrolyte cells with layered oxide cathodes and graphite anodes, forming the baseline chemistry for two-wheeler electrification in Gujarat and Tamil Nadu manufacturing corridors. OEM procurement concentrates here due to established BIS certification pathways and cell supplier familiarity.
- Nickel Cobalt Manganese:Delivers energy densities exceeding 250 Wh/kg through high-nickel cathode formulations, commanding premium positioning in three-wheeler fast-charging architectures. Domestic precursor production remains constrained by nickel sulfate refining capacity gaps, forcing reliance on imported cathode active materials.
- Lithium Iron Phosphate:Phosphate-based cathode chemistry with intrinsic thermal stability advantages, expanding share in state transport corporation bus electrification tenders across Karnataka and Maharashtra.
- Lead Acid:Mature flooded and VRLA technologies dominating starter-lighting-ignition applications and low-speed electric vehicles, facing displacement pressure from lithium-ion cost convergence in the two-wheeler replacement market.
Lithium-ion retains volume leadership; Lithium Iron Phosphate holds the steepest expansion curve.
End User:
Customer consolidation patterns favor direct procurement relationships over fragmented dealer networks, with fleet operators aggregating demand volumes that exceed individual OEM material consumption.
- OEMs:Integrated vehicle manufacturers specifying cell chemistry and active material grades for original fitment, concentrated among two-wheeler producers in Tamil Nadu and three-wheeler assemblers in Gujarat. PLI scheme domestic content thresholds redirect their procurement toward BIS-certified local electrode suppliers.
- Aftermarket Providers:Independent battery distributors and service networks addressing replacement demand in tier-2 and tier-3 cities, constrained by technical capability gaps in lithium-ion diagnostics and cell balancing.
- Fleet Operators:Aggregated logistics and mobility service companies negotiating volume cathode material contracts tied to charging infrastructure deployment, particularly visible in last-mile delivery electrification across Bengaluru and Chennai urban corridors.
- Research Institutions:IIT Madras, IISc Bengaluru, and CSIR laboratories piloting solid-state electrolyte and silicon-anode formulations, transferring patent positions to commercial partners rather than manufacturing directly.
Fleet operators are consolidating procurement fastest; aftermarket providers face margin compression from technical complexity barriers.
Battery Type:
Architecture differentiation separates commodity cell markets from premium segments where silicon-doped anodes and high-voltage electrolytes command material cost premiums.
- Standard Batteries:Conventional graphite anode and carbonate electrolyte configurations serving cost-sensitive two-wheeler applications, dominating unit volumes in Gujarat's manufacturing clusters.
- Fast Charging Batteries:Silicon-doped anode and high-voltage electrolyte formulations enabling sub-30-minute charge cycles, specified by premium three-wheeler OEMs and battery-swapping network operators in Tamil Nadu.
- Solid State Batteries:Ceramic or sulfide electrolyte architectures replacing liquid components, remaining pre-commercial with margin pools concentrated in patent licensing rather than manufacturing scale.
- Swappable Batteries:Standardized pack formats designed for automated exchange infrastructure, requiring durable connector materials and robust battery management systems deployed across Bengaluru and Delhi NCR mobility networks.
Standard Batteries retain volume leadership; Fast Charging Batteries hold the steepest expansion curve.
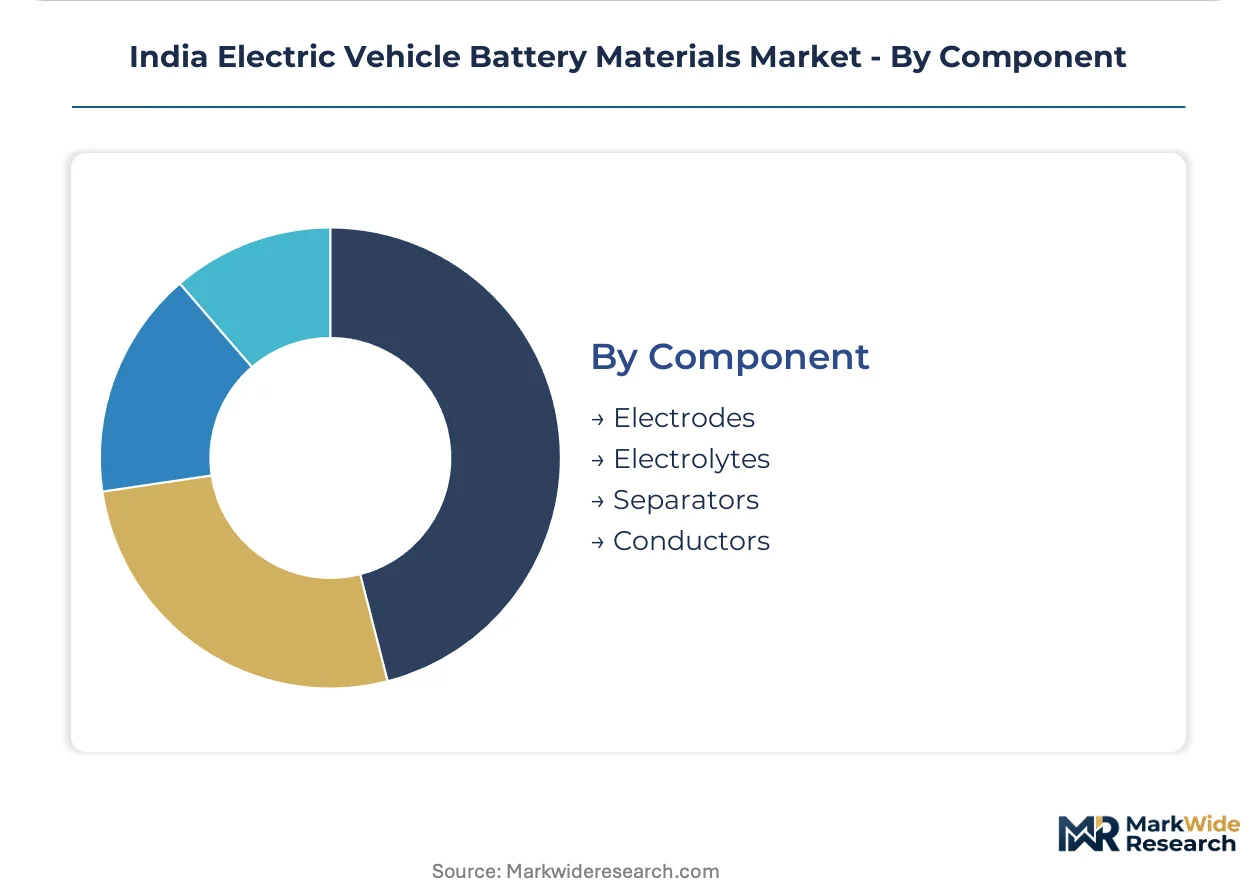
Component:
Supply concentration risks vary sharply across the cell stack, with separator and electrolyte salt capacity most exposed to import dependence.
- Electrodes:Cathode active materials and anode substrates constituting the electrochemical reaction interface, representing the largest cost share and the focus of PLI scheme domestic content requirements.
- Electrolytes:Lithium hexafluorophosphate salts and solvent formulations enabling ion transport, with domestic production limited to blending operations rather than salt synthesis.
- Separators:Polyethylene and polypropylene microporous membranes preventing internal short circuits, with wet-process manufacturing capacity concentrated outside India.
- Conductors:Copper foil current collectors and aluminum tab materials, benefiting from existing domestic metal processing infrastructure in Jharkhand and Odisha.
Electrodes retain volume leadership; Electrolytes face the steepest supply security challenges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Indian states diverge sharply between automotive manufacturing corridors and emerging battery-swapping networks, with Gujarat and Tamil Nadu driving cathode material demand while Karnataka and Maharashtra concentrate grid-storage procurement.
Gujarat
Two-wheeler and three-wheeler OEMs dominate cathode active material consumption through Sanand and Halol manufacturing belts. The state's EV policy offers capital subsidies for cell component manufacturing, accelerating precursor chemical investments. Domestic electrode suppliers cluster around Mundra port to leverage import logistics for nickel sulfate refining.
Tamil Nadu
Three-wheeler electrification and battery-swapping infrastructure drive electrolyte salt demand across Chennai and Coimbatore industrial zones. The Tamil Nadu Electric Vehicles Policy mandates 100% green energy for cell manufacturing facilities. Fleet operators in Hosur and Sriperumbudur negotiate direct cathode material contracts bypassing traditional distribution channels.
Karnataka
Grid-coupled battery energy storage systems expand addressable material volumes beyond automotive applications through Bengaluru and Mysuru corridors. The Karnataka Electric Vehicle and Energy Storage Policy prioritizes local separator membrane manufacturing capacity. Research institutions in Bengaluru transfer solid-state electrolyte patents to commercial partners rather than manufacturing directly.
Maharashtra
State transport corporation bus electrification tenders favor Lithium Iron Phosphate chemistry for thermal stability across Mumbai and Pune urban networks. The Maharashtra Electric Vehicle Policy extends fiscal incentives to cell component suppliers establishing operations in Chakan and Talegaon industrial areas. Fleet aggregation platforms in Mumbai negotiate volume discounts tied to charging infrastructure deployment commitments.
Telangana
Emerging cell manufacturing investments in Hyderabad and Medak districts create demand for anode graphite and electrolyte formulations. The Telangana Electric Vehicle and Energy Storage Policy offers land allotment priority for battery materials processing facilities. Specialty chemical entrants target underdeveloped electrolyte salt capacity in the state's pharmaceutical manufacturing corridor.
India Electric Vehicle Battery Materials Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in India's battery materials sector, with capital-intensity thresholds separating backward-integrated precursor producers from import-dependent converters. The upper tier commands cathode active material supply through captive lithium carbonate refining, while midstream players concentrate on anode binders and electrolyte blending. Three archetypes dominate: diversified chemical conglomerates leveraging soda ash and coal-tar derivatives, legacy battery manufacturers navigating lithium-ion transition costs, and international specialty material suppliers licensing high-performance formulations. Competitive moves center on multi-year offtake agreements with cell manufacturers and BIS certification acquisition to qualify for PLI scheme procurement.
Among domestic chemical specialists, Tata Chemicals and Himadri Speciality Chemicals exemplify divergent integration strategies, with the former anchoring lithium carbonate-derived precursor production and the latter occupying the anode binder niche through coal-tar pitch specialization. Exide Industries represents the legacy battery manufacturer archetype, competing through established lead-acid infrastructure while funding parallel lithium-ion transition programs. International players including Umicore and Mitsubishi Chemical Group Corporation occupy positions in high-nickel cathode formulations and electrolyte technologies, licensing advanced material architectures rather than manufacturing at scale domestically.
| Leading Market Players |
|---|
| BASF SE |
| Mitsubishi Chemical Group Corporation |
| Umicore |
| Sumitomo Chemical Co. Ltd. |
| UBE Corporation |
| Exide Industries |
| Tata Chemicals |
| Himadri Speciality Chemicals |
| Aether Industries |
| Others |
Pricing and Supply Chain Analysis
BIS certification mandates for cell safety and performance gate both supplier qualification and price differentiation in India's battery materials sector, compressing margins for uncertified imports while enabling domestic electrode producers to command premiums tied to PLI scheme compliance.
Pricing Analysis
Long-term offtake agreements dominate cathode active material procurement as cell manufacturers lock in nickel sulfate and lithium carbonate supply to satisfy PLI domestic content thresholds. Price differentiation rests on BIS certification grade and volume scale, with certified local suppliers capturing premium positioning over import-dependent converters. Cost compression in standard graphite anode tiers is intensifying because Chinese synthetic graphite oversupply is eroding margins. Fleet operators demonstrate highest price sensitivity due to aggregated volume bargaining power, while research institutions show lowest sensitivity given grant-funded procurement.
Supply Chain Analysis
Mundra port congestion on the Australia-India spodumene concentrate trade lane elevates inbound logistics costs for lithium carbonate refiners in Gujarat. Raw material supply draws from Australia, Chile, and China for spodumene, cobalt hydroxide, and synthetic graphite respectively. Single-source vulnerability concentrates in electrolyte salt synthesis where domestic capacity remains absent. Distribution runs through direct procurement relationships between cell manufacturers and electrode suppliers, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Electric Vehicle Battery Materials Market represents high-growth disruption as the PLI scheme's domestic content mandates restructure procurement incentives toward local precursor production.
For Market Incumbents: Shield cathode active material margins by securing captive lithium carbonate refining capacity in Gujarat before Australian spodumene contract renewals. Accelerate BIS certification acquisition for emerging silicon-doped anode formulations to preempt specialty chemical entrants. The priority lever is locking in multi-year offtake agreements with Tamil Nadu three-wheeler OEMs before fleet operator consolidation redirects procurement decisions. For New Entrants and Emerging Players: Battery-swapping network electrolyte blending services present an under-served service layer where incumbent chemical conglomerates lack dedicated formulation expertise. Karnataka separator membrane manufacturing capacity offers the most penetrable white space given absent domestic wet-process production. Target direct technical partnerships with Bengaluru research institutions transferring solid-state electrolyte patents rather than competing on commodity electrode supply. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical parents with latent battery materials assets requiring dedicated capital allocation and management focus. Long-term viability centers on precursor chemical producers with demonstrated BIS certification pathways and established relationships with PLI-qualified cell manufacturers. The signal to watch is Ministry of Heavy Industries disbursement rule modifications tightening domestic value addition thresholds beyond current 25% requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Carbonate Refining | Captive spodumene processing in Gujarat secures PLI compliance and insulates margin from Australian mining volatility. |
| Silicon-Doped Anode Capacity Buildout | Tamil Nadu fast-charging battery demand creates first-mover advantage for nano-silicon precursor suppliers. |
| Separator Membrane Manufacturing Joint Venture | Karnataka policy incentives and absent domestic wet-process capacity attract Korean or Japanese technology partners. |
| Electrolyte Salt Synthesis Licensing Agreement | Technology transfer from Japanese or South Korean partners addresses India's critical supply security gap in lithium hexafluorophosphate. |
| Battery-Swapping Infrastructure Partnership | Direct fleet operator relationships in Bengaluru and Chennai bypass fragmented OEM procurement channels. |
Research Methodology
Desk research of BIS certification databases, PLI scheme disbursement records, and CEA technical standards preceded structured interviews with cathode active material plant managers, cell manufacturer procurement leads, and fleet operator energy service companies. Primary fieldwork with Tamil Nadu three-wheeler OEMs and Gujarat precursor chemical producers was cross-validated against Ministry of Heavy Industries policy filings and customs trade data for lithium carbonate and nickel sulfate imports. Bottom-up electrode and electrolyte demand estimates were triangulated against top-down cell manufacturing capacity buildout projections.
Variance decomposition across material type, battery architecture, and end-user segments shaped the analytical framework over the projection horizon. Modeled dimensions encompassed cathode chemistry grade, cell format specification, and state-level manufacturing cluster adoption patterns. CAGRs were derived from segment-level volume buildups calibrated to PLI incentive disbursement timelines and OEM production announcements. Forecast inputs incorporated BIS certification pipeline visibility and electrolyte salt import dependency ratios.
Forecasts assume regulatory continuity in BIS safety mandates and PLI scheme domestic content rules; material policy shifts would require re-modeling. Battery chemistry substitution rates and spodumene concentrate price volatility represent primary forecast revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Sulfur Dioxide Battery Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Asia-Pacific Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
United Kingdom Electric Vehicle Battery Anode Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Thin Film Lithium-Ion Battery Market
Lithium-ion Battery
Cylindrical Lithium-Ion Battery Market
Lithium-ion Battery
Silicon Anode Battery Market