
 Global Aortic Repair Devices Market | 2026-2036
Global Aortic Repair Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aortic Repair Devices Market Foresight
CE marking under the EU Medical Device Regulation is unwinding the competitive landscape for smaller graft manufacturers. Medtronic leverages its vertically integrated manufacturing footprint across multiple continents to sustain cost advantages in stent graft production. W. L. Gore & Associates differentiates through proprietary expanded polytetrafluoroethylene material science that anchors its position in complex anatomical cases. Cook Medical competes by maintaining direct hospital contracting relationships that control distribution channels in key markets.
Aortic repair devices encompass implantable and interventional systems designed to reinforce, exclude, or replace diseased aortic segments, typically constructed from nitinol or cobalt-chromium alloy frameworks covered with woven polyester or expanded polytetrafluoroethylene membranes and delivered via catheter-based or open surgical approaches. These systems restore aortic wall integrity while maintaining luminal blood flow, serving as definitive therapy for life-threatening aneurysmal dilation and dissection. Stent grafts occupy the dominant value position within the product portfolio as endovascular aneurysm repair becomes the first-line intervention for infrarenal disease. Endovascular surgery leads technology adoption due to reduced perioperative mortality and shorter intensive care stays compared with open repair. Hospitals capture the largest end-user share, though ambulatory surgical centers are gaining traction for select elective procedures.
FDA premarket approval requirements and EU MDR technical documentation standards shape clinical evidence thresholds and market access timelines for new graft platforms. Japan's PMDA and China's NMPA impose additional localization testing that extends registration cycles for multinational manufacturers. Stakeholders must monitor evolving regulatory convergence between major jurisdictions to anticipate where clinical trial investments will yield simultaneous market entry advantages.
Market Dynamics
EU MDR technical documentation standards are compressing market access timelines for stent graft manufacturers, favoring incumbents with established quality management systems and clinical data repositories while smaller competitors face escalating compliance costs.
Growth Catalysts
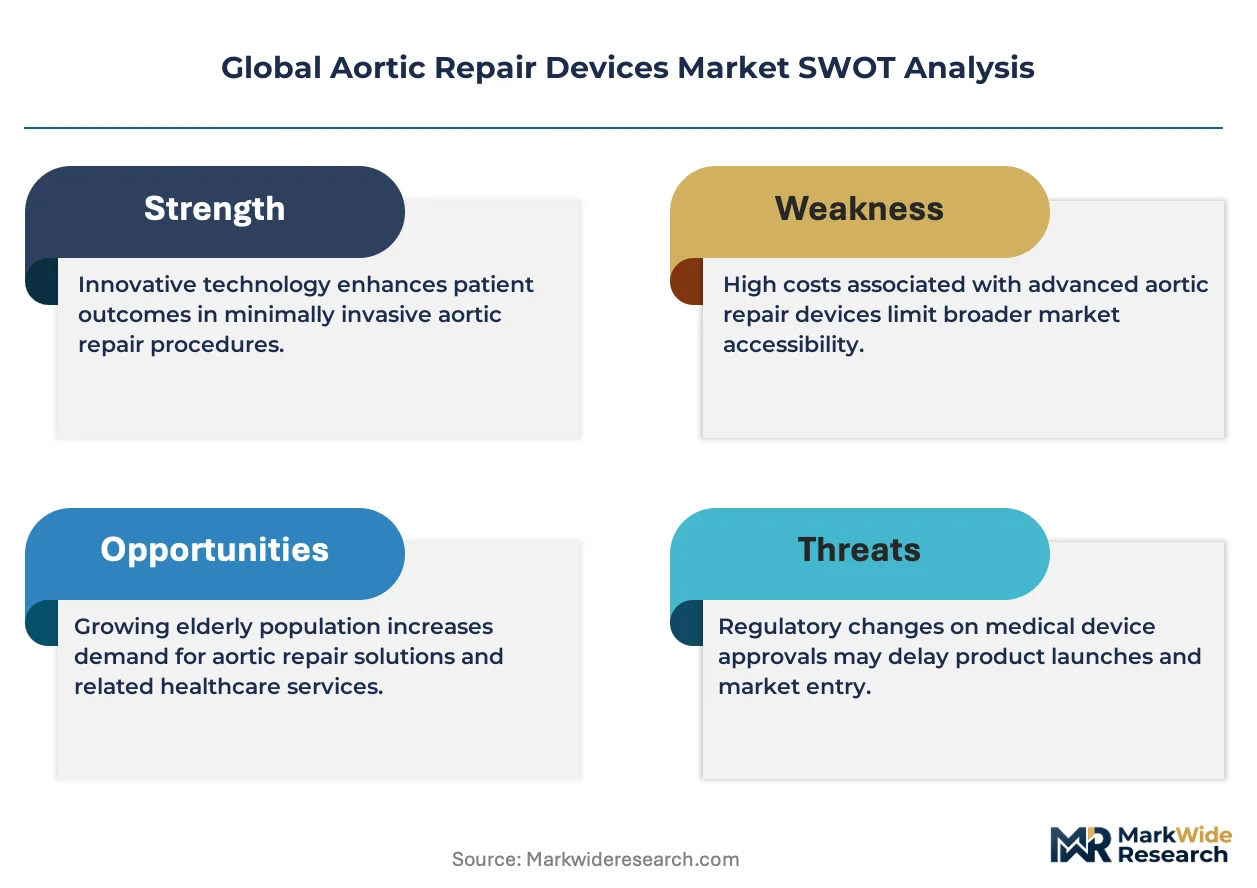
- FDA premarket approval pathway:Tightened clinical evidence thresholds for thoracic endovascular aortic repair devices accelerate consolidation toward manufacturers with dedicated trial infrastructure.
- Ambulatory surgical centers:Elective infrarenal aneurysm procedures are migrating to outpatient settings in the United States, expanding addressable procedure volume beyond traditional hospital systems.
- Nitinol alloy processing:Advances in shape-memory metal fabrication enable thinner-strut stent graft designs that improve deliverability through tortuous iliac anatomy.
Market Restraints
- Nickel-titanium supply concentration:Specialty alloy production clusters in Germany and the United States create input vulnerability for nitinol-dependent manufacturers.
- CE marking technical documentation:EU MDR requirements for biological evaluation and clinical evaluation reports extend registration cycles by 18-24 months for new graft platforms.
- Open surgical repair:Persistent viability of conventional graft replacement for complex juxtarenal anatomy limits endovascular penetration in younger, low-risk patient cohorts.
Strategic Opportunities
- Japan's PMDA localization pathway:Streamlined priority review for innovative medical devices creates first-mover advantage for manufacturers establishing domestic clinical evidence.
- Fenestrated and branched stent graft systems:Patient-specific manufacturing for juxtarenal and thoracoabdominal disease segments opens high-margin complex case categories.
- Digital surgery integration:Convergence of preoperative three-dimensional planning software with intraoperative navigation systems enables precision deployment in challenging anatomies.
Industry Challenges
- Vascular surgeon training pipelines:Prolonged fellowship requirements for endovascular certification create workforce bottlenecks that constrain procedure volume expansion.
- Quality management system recertification:Transition from ISO 13485:2016 to MDR-aligned notified body audits demands substantial documentation overhaul for established manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aortic Repair Devices Market |
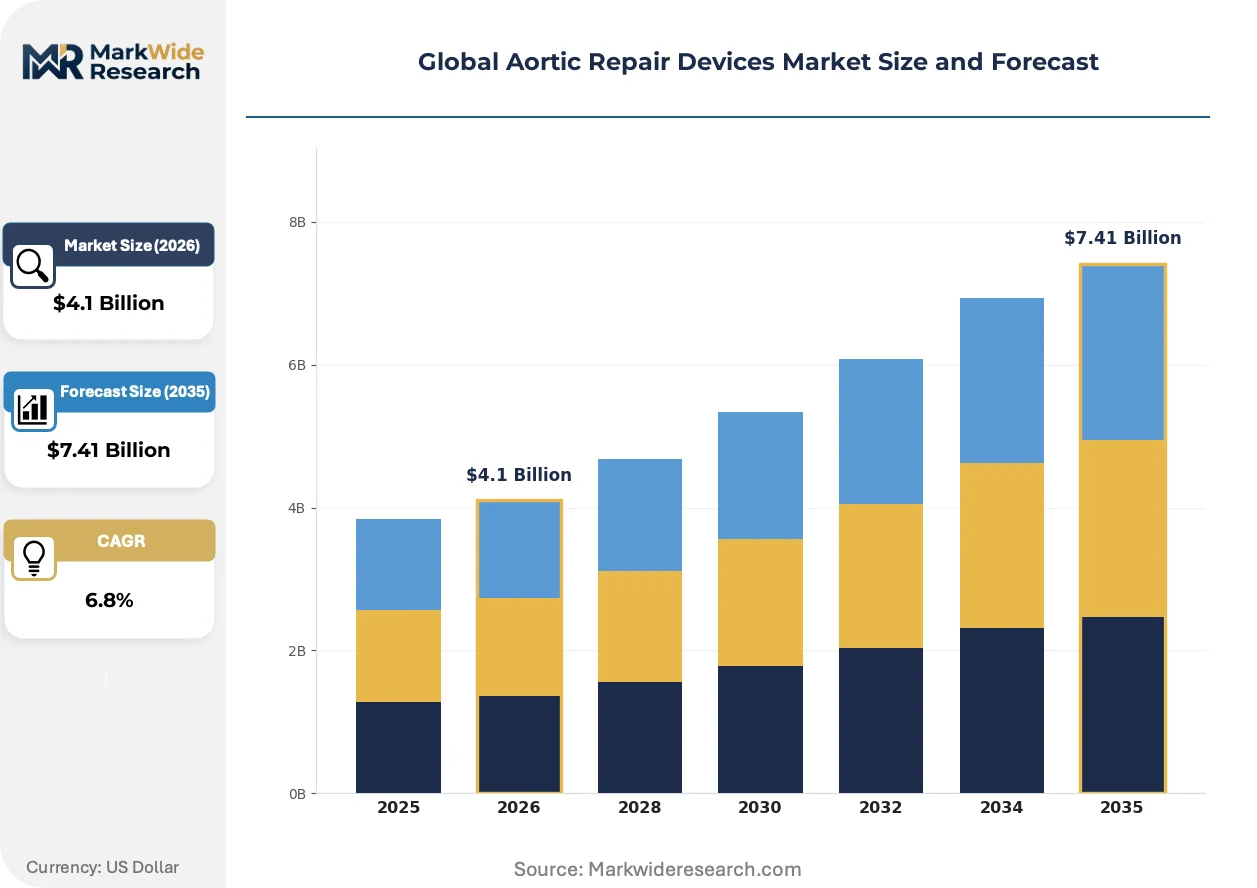
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stent Grafts, Surgical Grafts, Catheters, Occluders End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialty Centers Technology: Open Surgery, Endovascular Surgery, Hybrid Techniques, Robotic Assistance Application: Aortic Aneurysm, Aortic Dissection, Trauma, Vascular Malformations |
| Companies Covered | Terumo Aortic, Cook Medical, Medtronic, Endologix, Cardiatis, JOTEC GmbH, W. L. Gore & Associates, MicroPort Scientific Corporation, Bolton Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aortic Repair Devices Market Shifts & Advancements
Computational modeling and advanced materials science are compressing product development cycles while regulatory convergence across FDA, EMA, and PMDA is reshaping evidence generation strategies for multinational manufacturers.
Polymer-based sealing rings and low-permeability fabrics are bifurcating the stent graft market between conventional woven polyester platforms and next-generation expanded polytetrafluoroethylene constructs. Academic medical centers in Germany and Japan are adopting these materials for complex anatomical cases where endoleak prevention is critical. This material transition is bifurcating competitive positioning between incumbent polyester specialists and fluoropolymer innovators.
EU MDR Article 61 clinical evaluation requirements are mandating systematic literature reviews and post-market clinical follow-up protocols that exceed prior MEDDEV guidance. Manufacturers must now demonstrate equivalence through biological, technical, and clinical criteria rather than predicate device reliance alone. Thoracic stent graft platforms face the steepest compliance burden, with several notified bodies withdrawing certificates for legacy products.
Hospital procurement committees are consolidating vendor relationships through multi-year enterprise agreements that bundle stent grafts with procedural support and training services. Independent ambulatory surgical centers in the United States are resisting this consolidation, instead favoring distributor-mediated spot purchasing for elective cases. This channel tension is most acute in Texas and Florida, where freestanding endovascular centers compete directly with hospital outpatient departments.
Global Aortic Repair Devices Market Segmentation
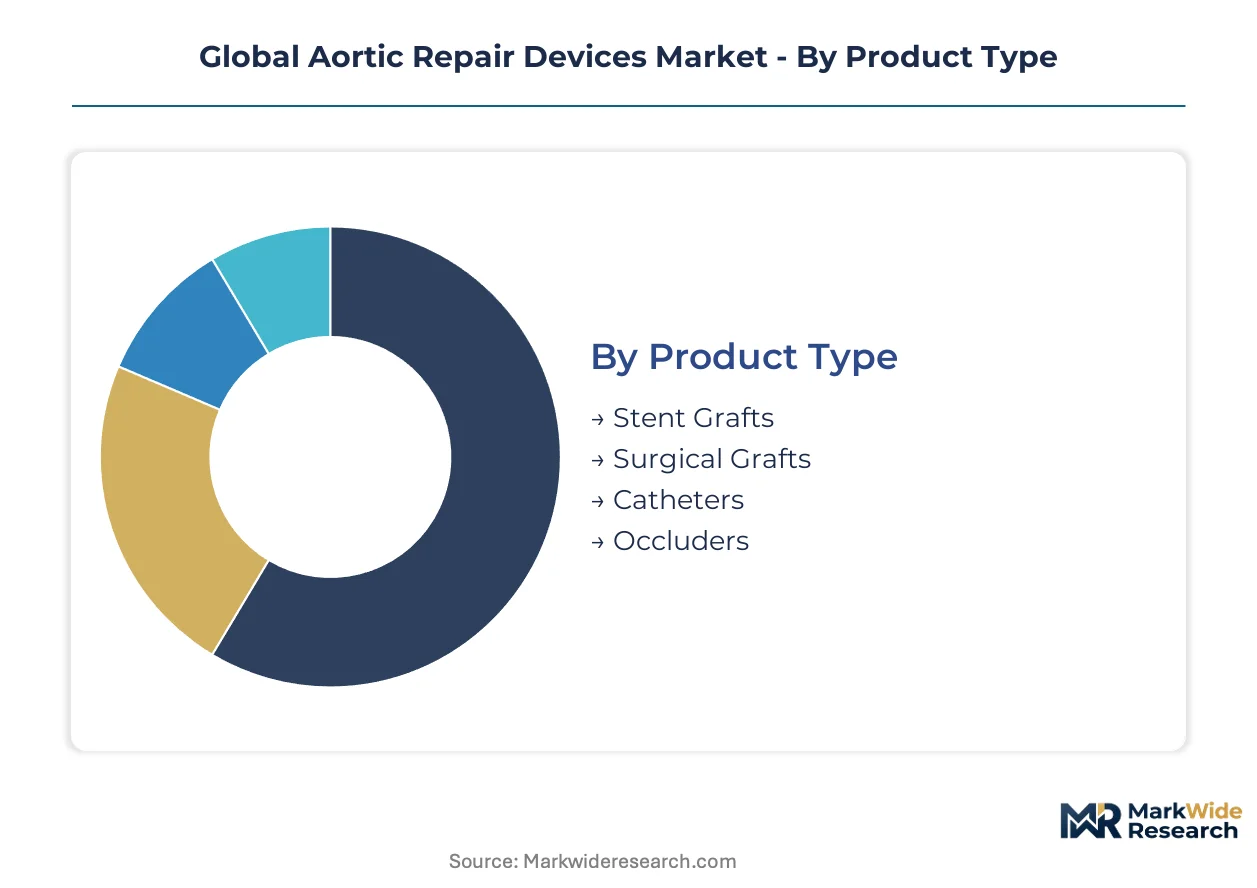
Segmentation in aortic repair devices reveals how clinical workflow requirements and reimbursement pathways fragment purchasing authority across hospital systems, outpatient facilities, and specialized vascular centers. Understanding these divides illuminates where manufacturers must build distinct commercial capabilities to capture procedure volume.
Product Type:
Margin pools concentrate in implantable systems where material science differentiation and regulatory exclusivity protect pricing power against commoditization pressures.
- Stent Grafts:Nitinol or cobalt-chromium frameworks sheathed in woven polyester or expanded polytetrafluoroethylene membranes, delivered via transfemoral catheter systems. Demand clusters in the United States and Germany where endovascular aneurysm repair reimbursement clarity supports first-line intervention for infrarenal disease, though nickel-titanium supply concentration in German and US specialty alloy producers creates input vulnerability.
- Surgical Grafts:Woven or knitted polyester tubes and bifurcated configurations for open aortic replacement, often incorporating collagen or gelatin sealing coatings. United States academic medical centers and Japan's high-volume cardiovascular institutes sustain demand for complex juxtarenal and thoracoabdominal cases where endovascular anatomical constraints persist.
- Catheters:Delivery sheaths, guidewires, and angiographic access devices supporting graft deployment procedures.
- Occluders:Plug devices for branch vessel embolization during fenestrated or branched endovascular repairs.
Stent grafts hold installed capacity. Surgical grafts are rotating up the share rankings as complex anatomical cases resist endovascular conversion.
End User:
Volume distribution tracks reimbursement site-of-service differentials and capital equipment requirements for intraoperative imaging.
- Hospitals:Inpatient and outpatient departments with hybrid operating suites combining fixed angiography systems and open surgical capability. United States hospital systems in Texas and Florida capture the largest procedure volumes through consolidated endovascular surgery programs, though procurement committees are bundling vendor relationships into multi-year enterprise agreements that squeeze distributor margins.
- Ambulatory Surgical Centers:Freestanding facilities equipped for elective infrarenal aneurysm repair with same-day discharge protocols. United States centers in competitive markets favor distributor-mediated spot purchasing over hospital-style bundled contracts, expanding addressable procedure volume beyond traditional health system capture.
- Clinics:Diagnostic and follow-up settings without interventional capability.
- Specialty Centers:Dedicated cardiovascular institutes with concentrated surgeon volume and research affiliations.
Hospitals dominate current throughput. Ambulatory surgical centers are climbing the fastest as site-of-service migration accelerates.
Technology:
Adoption curves diverge based on training pipeline capacity and device regulatory clearance breadth.
- Endovascular Surgery:Catheter-based graft deployment with fluoroscopic guidance, now standard for infrarenal and descending thoracic pathology. Germany and Japan lead procedural volume as vascular surgery fellowship programs emphasize endovascular certification, though workforce bottlenecks constrain expansion in smaller metropolitan markets.
- Open Surgery:Conventional graft replacement via median sternotomy or thoracoabdominal incision. Persistent viability for complex juxtarenal anatomy and younger low-risk cohorts limits endovascular penetration, with United States academic centers preserving open surgery volume for training and research purposes.
- Hybrid Techniques:Combined open debranching with endovascular exclusion for arch and thoracoabdominal disease.
- Robotic Assistance:Telemanipulation platforms for precision suturing in minimally invasive aortic procedures.
Endovascular surgery commands the steepest expansion trajectory. Hybrid techniques are rotating up the share rankings as fenestrated platforms enable more complex anatomical treatment.
Application:
Clinical indication severity determines urgency, reimbursement tier, and device specification requirements.
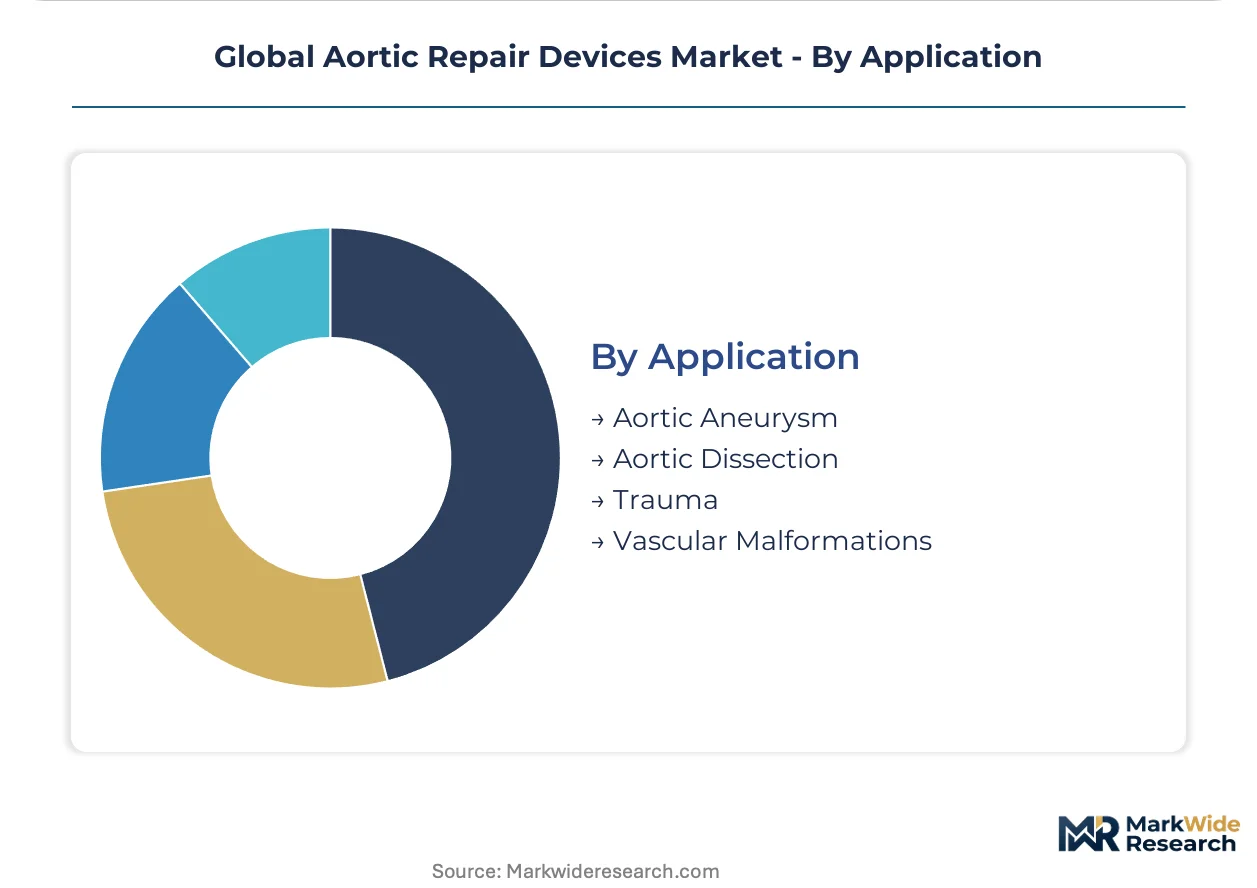
- Aortic Aneurysm:Focal aortic dilation exceeding 50% of normal diameter, addressed through diameter-based intervention thresholds. Screening programs in the United States and Japan identify ascending and abdominal disease, with elective repair volume concentrated in aging demographic cohorts where minimally invasive approaches reduce perioperative mortality.
- Aortic Dissection:Intimal tear with false lumen propagation requiring urgent or emergent intervention. Acute type B dissection drives thoracic endovascular aortic repair demand in United States trauma centers and Japanese emergency cardiovascular networks, where compressed treatment windows favor established graft platforms with rapid deployment characteristics.
- Trauma:Blunt or penetrating aortic injury requiring damage-control repair strategies.
- Vascular Malformations:Congenital or acquired structural anomalies including coarctation and pseudoaneurysm.
Aortic aneurysm holds installed capacity. Aortic dissection is gaining share fastest as acute intervention protocols standardize across emergency networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and vascular surgery programs concentrate purchasing authority across specific metropolitan clusters in aging economies with established endovascular reimbursement pathways.
United States
Texas and Florida hospital systems drive procedure volume through consolidated endovascular surgery programs capturing elective infrarenal aneurysm repairs. FDA premarket approval requirements for thoracic endovascular aortic repair devices favor manufacturers with dedicated trial infrastructure and established quality management systems. Greater Houston and Dallas-Fort Worth anchor the largest metropolitan concentrations of hybrid operating suites combining fixed angiography with open surgical capability.
Germany
Academic medical centers in Bavaria and Baden-Württemberg sustain demand for complex juxtarenal and thoracoabdominal cases where endovascular anatomical constraints persist. EU MDR technical documentation standards and CE marking pathways compress market access timelines while favoring incumbents with clinical data repositories. The Munich-Stuttgart corridor concentrates specialty nitinol alloy processing facilities that supply upstream stent graft manufacturers.
Japan
PMDA localization pathways and streamlined priority review for innovative medical devices create first-mover advantages for manufacturers establishing domestic clinical evidence. Aging demographics in the Kanto and Kansai regions expand screening-identified ascending and abdominal disease volumes. Tokyo and Osaka cardiovascular institutes emphasize endovascular certification in fellowship programs that shape workforce pipeline capacity.
China
NMPA registration cycles impose additional localization testing that extends market entry timelines for multinational manufacturers while domestic producers capture share in tier-two cities. The Yangtze River Delta and Pearl River Delta clusters concentrate hospital construction of hybrid operating suites. Shanghai and Guangzhou academic centers drive adoption of fenestrated and branched stent graft systems for complex anatomical cases.
United Kingdom
National Health Service procurement frameworks and specialized vascular networks concentrate purchasing authority across London, Birmingham, and Manchester tertiary centers. EU MDR convergence with post-Brexit regulatory alignment creates transitional compliance complexity for graft manufacturers. The Oxford-Cambridge-London arc anchors research affiliations driving digital surgery integration with preoperative three-dimensional planning software.
Global Aortic Repair Devices Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with vertically integrated manufacturing footprints and specialized vascular graft fabricators with proprietary material science positions. The competitive terrain stratifies across three tiers: multinational platform holders with global distribution infrastructure, mid-scale specialists with regional regulatory depth, and emerging Asia-Pacific challengers leveraging cost-advantaged production. Consolidation pressures intensify as notified body capacity constraints under EU MDR and FDA premarket approval pathway tightening accelerate competitive sorting. Dominant moves include backward integration into nitinol alloy processing and strategic partnerships for patient-specific manufacturing capabilities.
Among diversified platform holders, Medtronic, W. L. Gore & Associates, and Cook Medical exemplify distinct archetypes. Medtronic represents scale-driven manufacturing integration across multiple continents. W. L. Gore & Associates occupies a position anchored in proprietary expanded polytetrafluoroethylene material science for complex anatomical applications. Cook Medical sits within the direct hospital contracting tier, controlling distribution channels through established relationships rather than distributor intermediation. Terumo Aortic and JOTEC GmbH represent European-origin specialists with concentrated regulatory expertise in fenestrated and branched system platforms. MicroPort Scientific Corporation anchors the Asia-Pacific challenger archetype with cost-structured production positioning.
| Leading Market Players |
|---|
| Terumo Aortic |
| Cook Medical |
| Medtronic |
| Endologix |
| Cardiatis |
| JOTEC GmbH |
| W. L. Gore & Associates |
| MicroPort Scientific Corporation |
| Bolton Medical |
| Others |
Supply & Pricing Matrix
CE marking under EU MDR gates both supplier qualification and price differentiation simultaneously, compressing margins for manufacturers lacking established quality management systems while rewarding incumbents with clinical data repositories that command premium positioning in hospital procurement committees.
Pricing Analysis
Cost-plus contracts with nitinol alloy indexation dominate hospital system agreements, particularly in United States and German procurement frameworks. Three-tier pricing structure across premium, standard, and economy levels separates fenestrated platforms from conventional infrarenal devices and distributor-mediated spot purchases. Cost compression in economy tiers is intensifying because ambulatory surgical centers resist bundled enterprise contracts. Academic medical centers show least price sensitivity, prioritizing material science differentiation and training support over unit economics.
Supply Chain Analysis
Inventory lead times for specialty nitinol alloys stretch procurement cycles, forcing manufacturers to maintain strategic reserves against German and United States supply concentration. Production draws from German specialty metal processors, United States shape-memory fabricators, and Japanese precision wire manufacturers. Single-source vulnerability in nickel-titanium supply creates input risk for stent graft producers dependent on Munich-Stuttgart corridor facilities. Distribution runs through direct hospital contracting for complex platforms and distributor intermediation for elective outpatient procedures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aortic repair devices market sits in early-cycle expansion as fenestrated and branched platforms penetrate anatomical segments previously reserved for open surgery, with acute type B dissection protocols standardizing across emergency cardiovascular networks.
For Market Incumbents: Fortify positions through backward integration into nitinol alloy processing and captive supply of shape-memory wire to offset German supply concentration. Deepen hospital system partnerships with bundled training and procedural support services to defend against distributor-mediated spot purchasing erosion in ambulatory settings. For New Entrants and Emerging Players: Post-market clinical follow-up services represent a service-layer gap where incumbents under-serve, creating entry opportunity for manufacturers offering comprehensive surveillance programs. Target Japan's PMDA priority review pathway for innovative devices, leveraging streamlined domestic clinical evidence requirements against EU MDR registration delays. Pursue fenestrated platform development for thoracoabdominal disease as the most penetrable complex segment. For Investors and Strategic Acquirers: EU MDR Article 61 clinical evaluation requirements reshape the acquisition landscape toward manufacturers with established notified body relationships and systematic literature review capabilities. Five-to-ten-year viability favors mid-scale specialists with regional regulatory depth over undifferentiated commodity producers. Monitor notified body certificate withdrawals for legacy thoracic platforms as inflection signal for consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements compress market access timelines for prepared manufacturers. |
| Hospital System Partnership | Enterprise agreements bundling grafts with training services lock out distributor competitors in key metropolitan clusters. |
| Backward Integration into Nitinol | Captive alloy processing insulates margins from German supply concentration and spot price volatility. |
| Fenestrated Platform Development | Patient-specific manufacturing for juxtarenal anatomy opens high-margin complex case categories. |
| Reimbursement Strategy | Site-of-service economics favor outpatient migration for elective infrarenal procedures in competitive markets. |
Research Methodology
The analysis maps stent graft platforms, surgical graft configurations, and catheter delivery systems, each validated through vascular surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against FDA PMA filings, EMA CE marking databases, PMDA approval records, and hospital procurement contract repositories. Bottom-up procedure volume estimates triangulated with top-down manufacturer revenue analysis across the projection horizon.
Consistency checks validated volume and value outputs against external benchmarks including CMS Medicare procedure data, Japanese cardiovascular society registries, and German hospital discharge statistics. Segmentation modeling incorporated product type, end user facility class, technology adoption tier, and clinical indication severity throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with inputs including vascular surgeon fellowship pipeline capacity and hybrid operating suite installation rates.
Underlying assumptions cover reimbursement stability, regulatory pathway duration, and alloy supply continuity, with deviation risk concentrated in EU MDR notified body capacity constraints and nickel-titanium supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
Cardiac Ablation Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
LAMEA Cardiac Surgical Devices Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market
Cardiovascular Devices
Centrifugal Blood Pumps Market