
 Ambulatory Cardiac Monitoring Devices Market | 2026-2036
Ambulatory Cardiac Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ambulatory Cardiac Monitoring Devices Market Analysis
EU MDR is realigning the cost-of-entry calculus for ambulatory cardiac monitoring devices by mandating stricter clinical evidence and post-market surveillance obligations. Medtronic leverages its integrated manufacturing footprint to absorb compliance costs across multiple device categories. iRhythm Technologies specializes in AI-enhanced arrhythmia detection workflows that streamline diagnostic yield per monitored hour. Abbott Laboratories anchors its position through catheterization lab relationships that funnel patients into long-term ambulatory monitoring protocols.
Ambulatory cardiac monitoring devices are portable electrophysiological recording systems that capture heart rhythm data over extended periods ranging from 24 hours to 30 days or more, typically employing electrodes, amplifiers, and digital storage with wireless transmission capability for remote clinician review. These systems serve the primary commercial purpose of detecting intermittent arrhythmias, ischemic events, and post-interventional complications outside traditional hospital telemetry settings. Mobile Cardiac Telemetry represents the fastest-expanding device type segment as real-time streaming replaces store-and-forward diagnostic models. Hospitals remain the dominant end user channel, though Home Healthcare is capturing disproportionate growth as reimbursement codes mature for remote cardiac monitoring services.
FDA premarket notification pathways and EU MDR conformity assessment procedures shape product development timelines and commercial launch sequencing across the United States and European markets. Japan's PMDA enforces distinct electrical safety and software validation standards that create separate certification burdens for manufacturers seeking access. China's NMPA has tightened clinical trial requirements for imported Class III cardiac devices, extending registration timelines. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market performance data requirements under EU MDR as these frameworks increasingly determine competitive viability rather than purely technical differentiation.
Market Dynamics
The transition from episodic Holter monitoring to continuous real-time cardiac telemetry is compressing diagnostic timelines and forcing reimbursement recalibration across ambulatory care networks.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS and commercial payers in the United States have established dedicated billing codes for external cardiac telemetry, converting previously uncompensated home monitoring into revenue-generating clinical services.
- EU MDR Streamlined Pathways:The European Medical Device Regulation now offers priority review tracks for software-as-medical-device ECG algorithms, accelerating market access for AI-enabled diagnostic platforms.
- Catheter Ablation Expansion:Electrophysiology procedure volumes in Germany and Japan are generating post-procedural monitoring demand that ambulatory devices capture more cost-effectively than repeat hospital admissions.
Market Restraints
- Semiconductor Supply Concentration:Discrete analog-to-digital converters and low-noise amplifiers for biopotential sensing concentrate among Taiwanese and South Korean foundries, exposing device manufacturers to foundry allocation volatility.
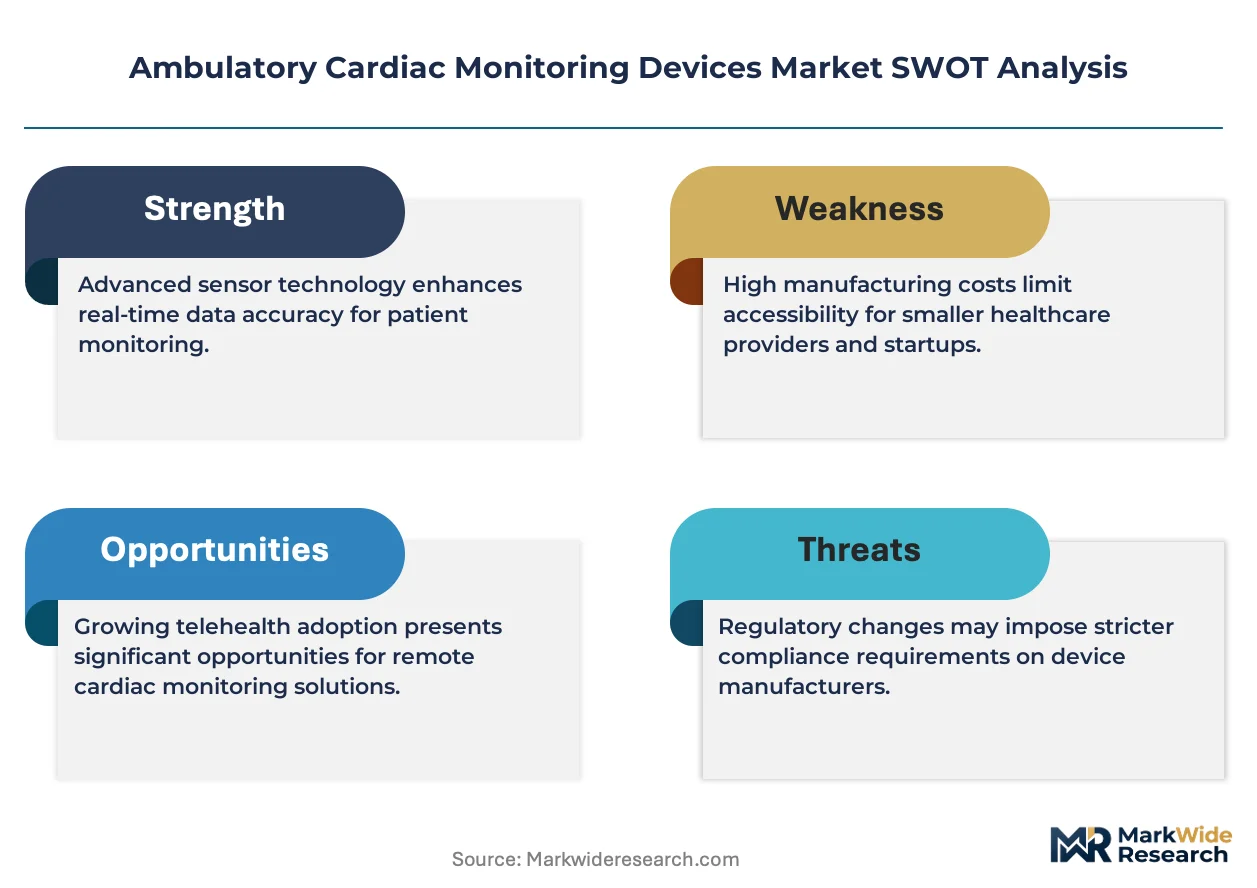
- EU MDR Clinical Evidence Burden:The expanded requirement for post-market clinical follow-up data under MDR Article 74 is extending certification timelines and inflating regulatory compliance costs for smaller manufacturers.
- Substitute Modalities:Insertable cardiac monitors from established electrophysiology device makers are capturing extended monitoring cases beyond 30 days, narrowing the addressable window for external patch-based systems.
Strategic Opportunities
- Home Healthcare Channel Maturation:Durable medical equipment suppliers in the United States are building direct-to-patient logistics capabilities that bypass traditional hospital procurement, opening ambulatory monitoring to chronic heart failure populations.
- AI-ECG Convergence:Deep learning architectures trained on multi-lead ECG databases are enabling single-lead wearable devices to achieve diagnostic sensitivity comparable to 12-lead systems, collapsing hardware complexity.
- Japan's Super-Aging Society:PMDA fast-track designations for geriatric cardiac devices are creating regulatory runway for extended-wear monitors targeting the country's 65-plus demographic, now exceeding 29 percent of population.
Industry Challenges
- Biomedical Signal Processing Talent Scarcity:The intersection of electrophysiology domain expertise and embedded systems engineering is narrowing the qualified hiring pool for algorithm development teams.
- Legacy EHR Integration Complexity:Hospital IT departments face protracted HL7 FHIR mapping projects to incorporate streaming telemetry data from third-party ambulatory devices into existing cardiac rhythm management workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambulatory Cardiac Monitoring Devices Market |
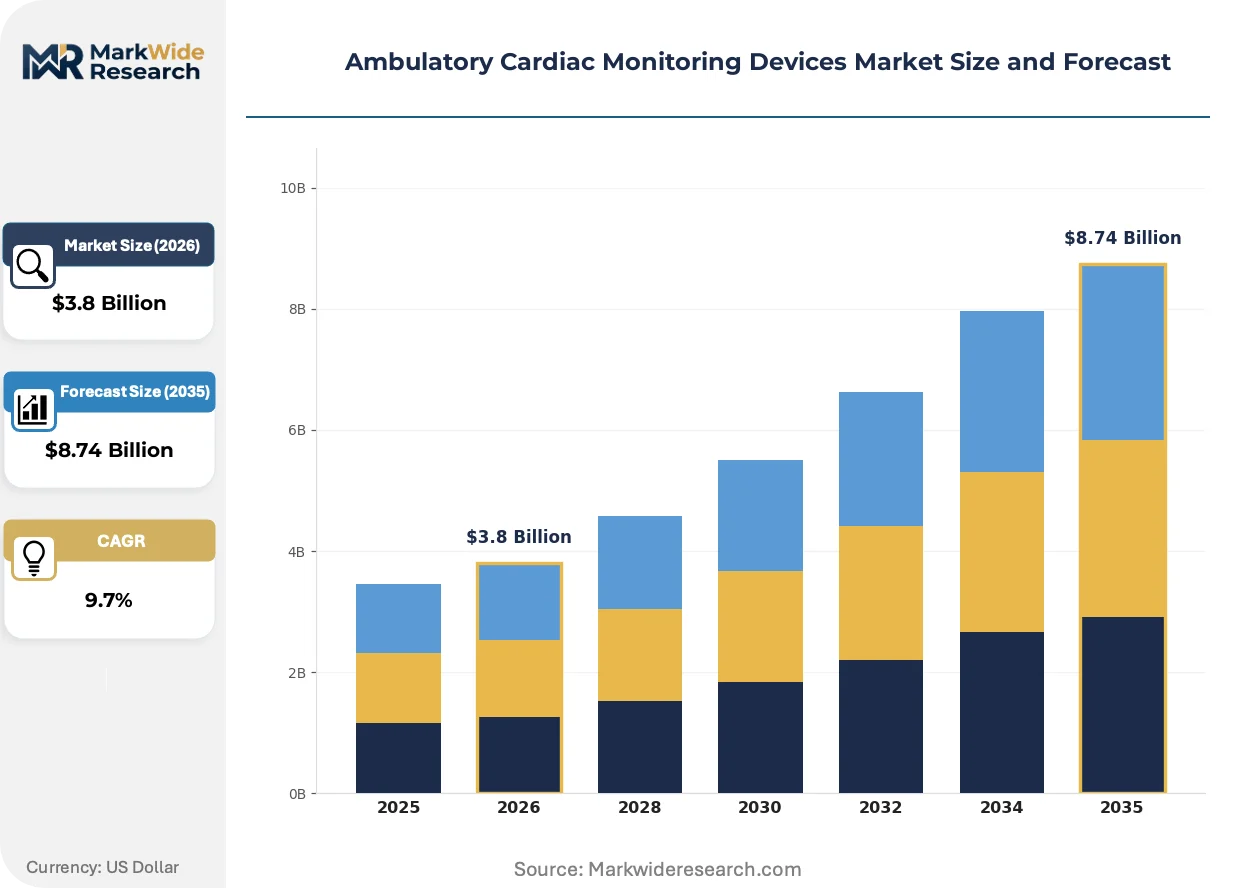
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Holter Monitors, Event Monitors, Implantable Monitors, Mobile Cardiac Telemetry End User: Cardiology Clinics, Hospitals, Home Healthcare, Ambulatory Surgery Centers Connectivity: Bluetooth, Wi-Fi, Cellular, Wired Application: Arrhythmia Detection, Post-Surgical Monitoring, Congestive Heart Failure, Cardiac Risk Assessment |
| Companies Covered | Koninklijke Philips, iRhythm Technologies, Medtronic, Nihon Kohden, BIOTRONIK, Abbott Laboratories, Boston Scientific Corporation, Shenzhen Mindray Bio-Medical Electronics, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambulatory Cardiac Monitoring Devices Market Emerging Trajectories
Algorithmic interpretation of electrophysiological signals is displacing human over-reading as the primary diagnostic bottleneck, while hardware miniaturization and wireless power transfer are collapsing form-factor constraints on patient compliance.
Photoplethysmography-enhanced ECG sensors are rewriting the standard for arrhythmia detection confidence in single-lead devices. Cardiology group practices in the United States are adopting these hybrid optical-electrical systems for atrial fibrillation screening protocols. The technology is compressing false-negative rates for paroxysmal events that electrical detection alone misses, forcing competitors to integrate multi-modal sensing or concede diagnostic yield.
FDA's evolving guidance on predetermined change control plans for machine learning-enabled devices is reshaping software update economics for ambulatory monitor manufacturers. The framework permits algorithmic modifications within validated bounds without fresh 510(k) submissions, reducing regulatory friction for iterative model improvement. Device makers with established quality management systems are restructuring development pipelines to exploit this pathway, while newcomers face compliance infrastructure build-out costs.
Cardiology service lines are unbundling device provision from professional interpretation, creating separate procurement decisions for hardware, software, and clinical reading services. Integrated delivery networks in Germany are contracting directly with telemetry platforms while retaining independent electrophysiologists for over-read, fragmenting traditional vendor-capture models. This bifurcation is most pronounced in metropolitan hospital systems where purchasing autonomy has devolved to service-line administrators rather than centralized materials management.
Ambulatory Cardiac Monitoring Devices Market Segmentation
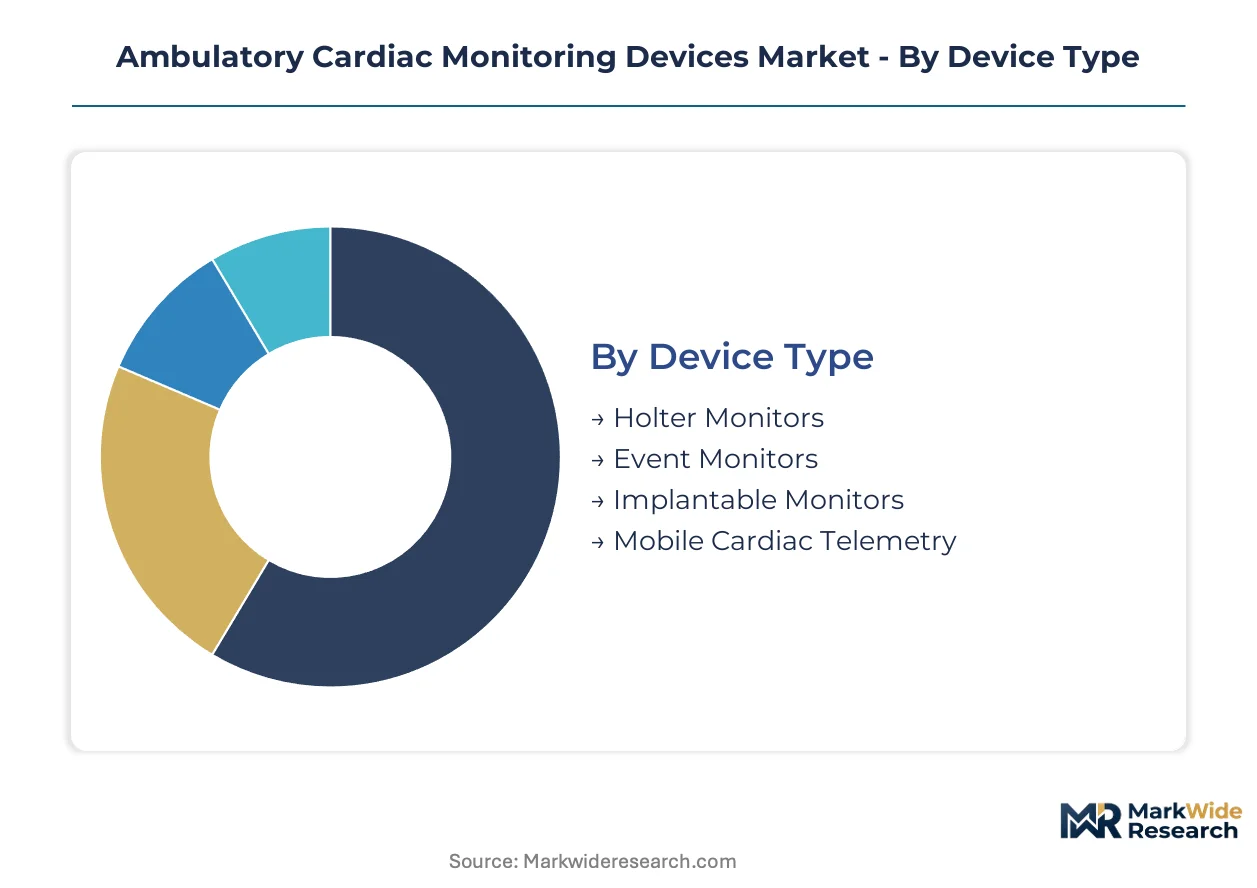
Segmentation in ambulatory cardiac monitoring reveals how hardware form factors, care delivery sites, and clinical applications allocate capital across divergent technology stacks. Procurement patterns split between hospital systems seeking enterprise telemetry platforms and home healthcare channels demanding consumer-grade wearables with medical validation.
Device Type:
Supply concentration for ambulatory cardiac monitors clusters among electrophysiology specialists with vertically integrated sensor manufacturing and FDA-cleared algorithm pipelines.
- Mobile Cardiac Telemetry:Real-time streaming systems combine cellular modems with cloud-based arrhythmia detection engines. Demand concentrates in United States cardiology group practices where CMS reimbursement codes for external telemetry have created sustainable revenue streams independent of hospital capital budgets.
- Holter Monitors:Continuous 24-48 hour tape-based or digital recorders remain the default diagnostic gateway for palpitation workups. German statutory health insurers maintain preferential reimbursement for Holter-based protocols, preserving volume despite technological obsolescence pressures.
- Event Monitors:Patient-activated or auto-triggered loop recorders capture symptomatic episodes. Japanese PMDA fast-track pathways are accelerating approval timelines for extended-wear event monitors targeting geriatric populations.
- Implantable Monitors:Subcutaneous devices capture cardiac electrical signals for multi-year monitoring windows. Insertable cardiac monitors from established electrophysiology device makers are capturing extended monitoring cases beyond thirty days.
Today's leader: Mobile Cardiac Telemetry. Tomorrow's challenger: Implantable Monitors.
End User:
Procurement authority is fragmenting across ambulatory cardiac monitoring as service-line administrators gain purchasing autonomy independent of centralized hospital materials management.
- Hospitals:Integrated delivery networks deploy enterprise telemetry platforms across emergency departments, observation units, and step-down floors. United States health systems are consolidating vendor contracts to capture volume discounts on multi-year remote monitoring agreements.
- Home Healthcare:Durable medical equipment suppliers build direct-to-patient logistics capabilities that bypass traditional hospital procurement entirely. Medicare Advantage plans in Florida and Arizona are piloting remote cardiac monitoring for congestive heart failure populations with thirty-day readmission risk.
- Cardiology Clinics:Independent electrophysiology practices purchase telemetry hardware paired with software-as-a-service interpretation platforms. German metropolitan clinic networks are unbundling device provision from professional over-read services.
- Ambulatory Surgery Centers:Freestanding surgical facilities require post-procedural monitoring for catheter ablation and electrophysiology cases. ASCs in Japan's urban corridors are adopting patch-based monitors to avoid transfer to acute care settings.
Channel concentration favors Hospitals. Disproportionate expansion sits with Home Healthcare.
Connectivity:
Radio frequency engineering capabilities determine competitive positioning as device makers balance power consumption against transmission reliability in ambulatory cardiac monitors.
- Cellular:Embedded LTE-M or NB-IoT modems enable real-time streaming without patient smartphone dependency. United States rural health networks prioritize cellular-enabled monitors where broadband infrastructure remains unreliable.
- Bluetooth:Low-energy protocols connect wearable sensors to patient smartphones for store-and-forward or real-time relay. Bluetooth 5.3 implementations are reducing power draw for multi-day patch monitors.
- Wi-Fi:Higher bandwidth connections support multi-lead ECG transmission in residential or clinical settings. Home healthcare deployments in German apartment complexes leverage existing Wi-Fi infrastructure.
- Wired:Tethered connections persist in research protocols and calibration scenarios requiring artifact-free signal acquisition. Academic medical centers in Japan maintain wired Holter systems for algorithm validation studies.
Cellular dominates new deployments. Bluetooth retains cost-sensitive segments.
Application:
Clinical indication drives sensor configuration and monitoring duration requirements across ambulatory cardiac device portfolios.
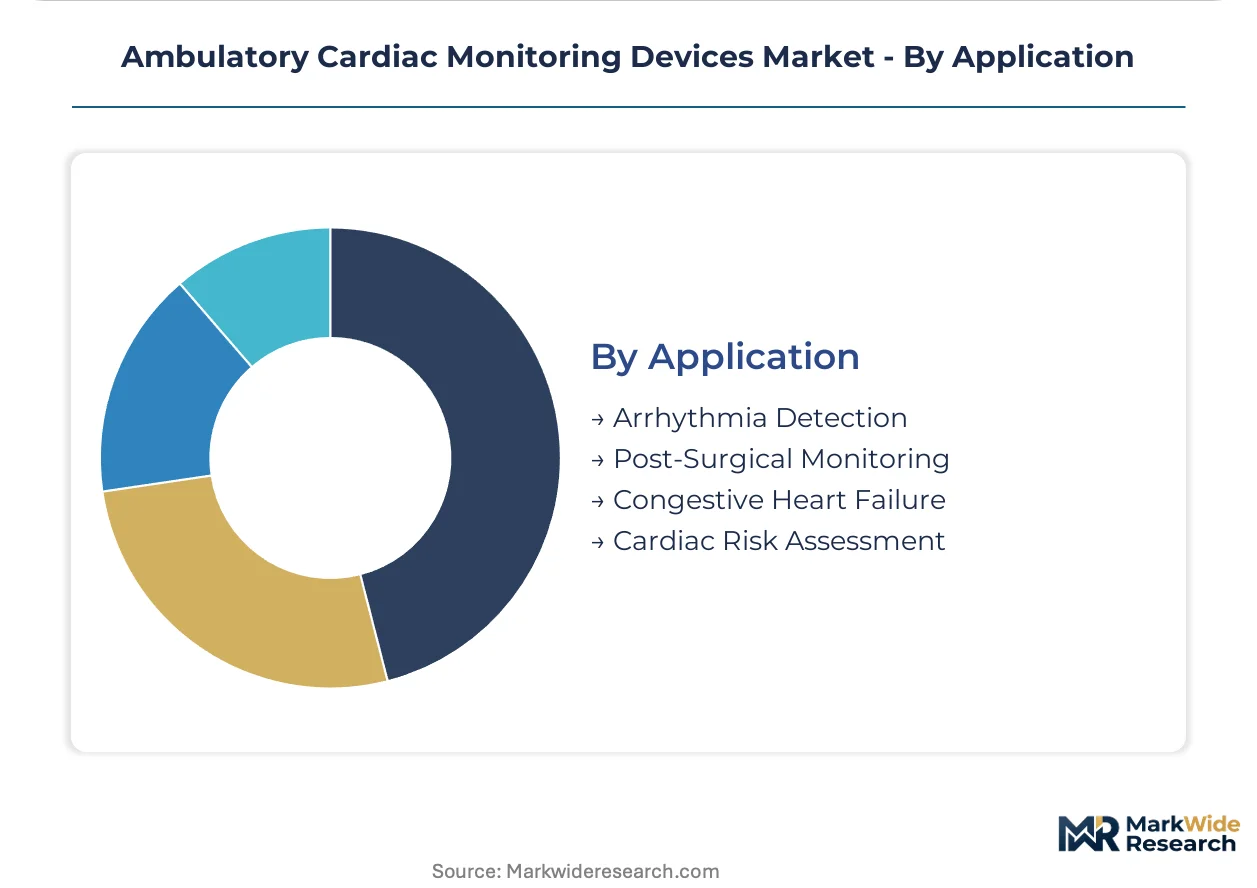
- Arrhythmia Detection:Atrial fibrillation screening and paroxysmal event capture represent the core commercial application. United States accountable care organizations are embedding ambulatory monitors into population health workflows for Medicare beneficiaries.
- Post-Surgical Monitoring:Electrophysiology procedure volumes in Germany and Japan generate post-procedural monitoring demand. Catheter ablation expansion is forcing reimbursement recalibration for external telemetry versus repeat hospital admission.
- Congestive Heart Failure:Impedance-derived fluid status monitoring combines with ECG for decompensation early warning. Home healthcare channels are capturing disproportionate growth as reimbursement codes mature for remote cardiac monitoring services.
- Cardiac Risk Assessment:Pre-operative clearance and occupational health screening drive episodic monitoring demand. Japanese corporate wellness programs are adopting single-lead wearables for executive cardiovascular screening protocols.
Arrhythmia Detection commands current volume. Congestive Heart Failure is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophysiology specialists and biomedical engineers concentrate in regional medical technology clusters where hospital procurement power and regulatory sophistication shape competitive entry. Workforce density in cardiac rhythm management determines market development velocity.
United States
Medicare Advantage expansion and CMS reimbursement codes for remote cardiac monitoring drive ambulatory device procurement. FDA's predetermined change control plans for machine learning-enabled devices accelerate algorithmic update cycles. The Minneapolis medical device corridor anchors electrophysiology manufacturing and clinical trial infrastructure.
Germany
Statutory health insurer preference for Holter-based diagnostic protocols preserves traditional device volumes alongside real-time telemetry adoption. EU MDR Article 74 post-market clinical follow-up requirements extend certification timelines for imported systems. The Rhine-Ruhr metropolitan region concentrates cardiac catheterization lab networks that generate post-procedural monitoring demand.
Japan
PMDA fast-track designations for geriatric cardiac devices address super-aging demographics where patients over 65 exceed 29 percent of population. Distinct electrical safety and software validation standards create separate certification burdens for market access. The Kansai corridor around Osaka hosts electrophysiology service lines adopting patch-based monitors for ablation follow-up.
China
NMPA tightened clinical trial requirements for imported Class III cardiac devices extend registration timelines for foreign manufacturers. Domestic device makers leverage local manufacturing scale for cost-sensitive hospital procurement. The Yangtze River Delta medical technology cluster concentrates biopotential sensor assembly and algorithm development capabilities.
Ambulatory Cardiac Monitoring Devices Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the ambulatory cardiac monitoring landscape. The market structure exhibits tiered concentration where integrated health technology holding companies command hospital enterprise contracts while electrophysiology specialists capture cardiology clinic channels. Three archetypes dominate: diversified medical device conglomerates with catheterization lab relationships, AI-native diagnostic platform developers, and regional manufacturers with cost-optimized hardware portfolios. Competitive moves center on regulatory pathway optimization for algorithm updates and unbundling of device provision from interpretation services.
Within the diversified conglomerate tier, Koninklijke Philips and Medtronic occupy positions anchored by integrated manufacturing footprints and multi-category compliance infrastructure. iRhythm Technologies exemplifies the pure-play specialist archetype focused on AI-enhanced arrhythmia detection workflows. Shenzhen Mindray Bio-Medical Electronics represents regional-scale manufacturers serving cost-sensitive procurement channels in Asia-Pacific markets.
| Leading Market Players |
|---|
| Koninklijke Philips |
| iRhythm Technologies |
| Medtronic |
| Nihon Kohden |
| BIOTRONIK |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Shenzhen Mindray Bio-Medical Electronics |
| GE Healthcare |
| Others |
Supply Flow & Price Mechanics
Biomedical signal processing engineers concentrated in the Minneapolis and Boston corridors command wage premiums that compress margins at the premium tier while enabling aggressive pricing at the economy tier through algorithmic automation. Labor-cost differentials between AI-native software stacks and hardware-integrated legacy systems drive a 3x spread in per-patient monitoring costs across market tiers.
Pricing Analysis
The bundled-versus-unbundled service split between device provision and clinical interpretation is fragmenting procurement decisions across United States integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance tier and algorithm sensitivity specifications. Cost compression in the standard tier is intensifying because cardiology group practices are negotiating direct SaaS contracts for AI over-read services. Home healthcare channels exhibit highest price sensitivity due to Medicare Advantage reimbursement caps, while hospital systems demonstrate lowest sensitivity where remote monitoring reduces 30-day readmission penalties.
Supply Chain Analysis
Freight cost volatility for temperature-sensitive biopotential sensors and lithium-polymer batteries is forcing regional assembly strategies that bypass trans-Pacific container routes. Manufacturing concentrates in China, Taiwan, and South Korea for discrete analog-to-digital converters, low-noise amplifiers, and cellular modem chipsets. Raw material dependencies include medical-grade silver-silver chloride electrodes, biocompatible adhesives, and rare-earth magnets for wireless charging coils. Single-source vulnerability in Taiwanese foundry capacity for precision ADCs exposes device makers to allocation disruptions. Distribution runs through durable medical equipment suppliers and GPO-contracted hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU MDR Article 74 post-market surveillance obligations and FDA predetermined change control plans simultaneously raise compliance barriers and accelerate algorithmic differentiation.
For Market Incumbents: To counter unbundling of device provision from interpretation services by German metropolitan clinic networks, Medtronic and Abbott Laboratories should deepen catheterization lab relationships that funnel patients into long-term monitoring protocols. Backward integration into biopotential sensor manufacturing at the Minneapolis corridor insulates against Taiwanese foundry allocation volatility. Certification investment in EU MDR streamlined pathways for AI-enabled ECG algorithms preserves European market access against emerging software-native competitors. For New Entrants and Emerging Players: AI-ECG convergence architectures represent the most penetrable technology wedge for single-lead wearable devices achieving 12-lead diagnostic equivalence. White-space targets include Japan's super-aging society where PMDA fast-track designations for geriatric cardiac devices reduce regulatory runway, and United States congestive heart failure populations in Medicare Advantage plans piloting remote monitoring. Go-to-market through direct-to-patient logistics partnerships with durable medical equipment suppliers bypasses hospital procurement gatekeepers. For Investors and Strategic Acquirers: Electrophysiology device conglomerates are the most active acquirer in this space, seeking AI-native diagnostic platforms to complement hardware portfolios. Long-term viability hinges on regulatory pathway optimization for iterative algorithm updates rather than hardware refresh cycles. Acquisition target archetypes include pure-play SaaS interpretation platforms with FDA-cleared machine learning pipelines. Signal to watch: CMS reimbursement code expansion for multi-condition remote monitoring beyond arrhythmia detection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Predetermined Change Control Plan | Accelerates algorithmic update cycles without fresh 510(k) submissions for ML-enabled arrhythmia detection. |
| CE Marking Pathway under EU MDR | Priority review tracks for software-as-medical-device ECG algorithms compress European market entry timelines. |
| Hospital System Partnership | Enterprise telemetry platform contracts with United States integrated delivery networks lock in multi-year recurring revenue. |
| Software Companion Development | HL7 FHIR integration modules reduce IT deployment friction and accelerate EHR workflow adoption. |
| Reimbursement Strategy | CMS billing code capture for external cardiac telemetry converts uncompensated home monitoring into revenue-generating services. |
Methodological Framework
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body certificates, and hospital procurement records. Triangulation across these sources calibrated device shipment estimates against clinical utilization patterns.
Historical trendline analysis of Holter monitor, event monitor, and mobile cardiac telemetry adoption curves informed projection elasticity assumptions across the analysis window. Segmentation dimensions modeled include device type, end-user channel, connectivity protocol, and clinical application indication. CAGRs derived from regression analysis of procedure volume growth, reimbursement code expansion, and technology substitution rates. Industry-specific forecast inputs incorporated catheter ablation procedure volumes in Germany and Japan, and Medicare Advantage penetration in United States sunbelt states.
The model holds under stable reimbursement alignment and regulatory pathway continuity; deviation in FDA cybersecurity guidance stringency or EU MDR post-market surveillance enforcement would shift competitive viability toward integrated conglomerates with compliance infrastructure. Forecasts reflect documented assumptions about algorithmic diagnostic sensitivity improvements and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Radiofrequency Balloon Catheter Market
Cardiovascular Devices
Smart Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Prosthetic Devices Market
Cardiovascular Devices
Absorbable Heart Stent Market