
 Japan Continuous Glucose Monitoring Devices Market | 2026-2036
Japan Continuous Glucose Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Continuous Glucose Monitoring Devices Market Foresight
PMDA's streamlined approval pathway for software-as-medical-device updates is expanding the cost-of-entry calculus for new entrants. Dexcom leverages its transmitter miniaturization expertise to sustain premium positioning in hospital procurement channels. Abbott anchors its competitive stance through integrated flash glucose monitoring systems that bypass calibration requirements. Terumo Corporation navigates domestic reimbursement complexity by partnering with regional diabetes educator networks.
Continuous glucose monitoring devices are wearable electrochemical sensor systems that measure interstitial glucose concentrations through enzymatic reactions at the sensor-tissue interface, typically sampling every one to fifteen minutes for real-time metabolic tracking. These systems serve primarily to replace or supplement fingerstick blood glucose testing in intensive insulin therapy management, reducing hypoglycemic episodes through predictive alert algorithms. Receiver devices command the steepest margin pools due to their embedded software licensing and recurring data platform subscriptions. Homecare settings represent the fastest-growing end-user channel as Japan's aging population shifts chronic disease management away from institutional facilities. Real-time monitoring technology leads volume adoption, though flash glucose monitoring differentiates through cost-efficient, on-demand scanning protocols that appeal to price-sensitive Type 2 diabetes segments.
PMDA's QMS ministerial ordinance and JIS T 0601-1 electrical safety standards govern device registration, while METI's medical device industry promotion policies shape domestic manufacturing incentives. The national health insurance reimbursement catalog determines patient out-of-pocket exposure, directly influencing adoption velocity across prefectural healthcare systems. Stakeholders must monitor whether METI expands preferential reimbursement to factory-calibrated sensors, as this policy pivot would reshape competitive positioning between calibration-dependent and calibration-free technology architectures.
Market Dynamics
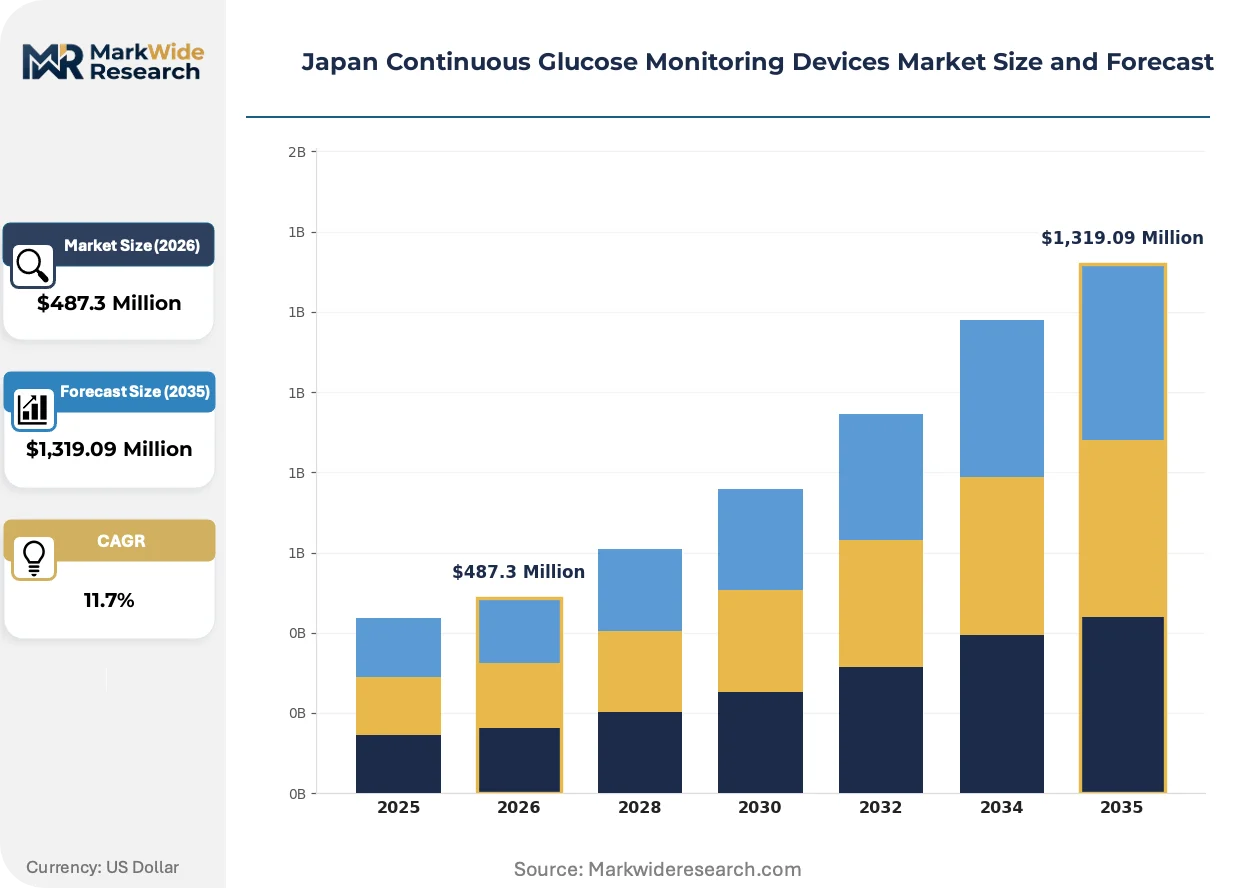
Japan's CGM market is being fundamentally restructured by the Ministry of Health, Labour and Welfare's reimbursement revisions for factory-calibrated wearable sensors, which are compressing patient out-of-pocket costs and accelerating volume migration from clinic-based to home-based monitoring protocols.
Growth Catalysts
- PMDA's software-as-medical-device pathway:Streamlined approval processes for algorithm updates reduce time-to-market for predictive alert features, enabling faster feature rollouts for intensive insulin therapy patients.
- Homecare channel expansion:Japan's aging demographic is shifting chronic disease management away from hospital endocrinology departments toward residential settings with remote physician oversight.
- Flash glucose monitoring technology:On-demand scanning protocols without calibration requirements are broadening addressable patient populations beyond Type 1 diabetes into Type 2 segments.
Market Restraints
- Reimbursement complexity:Prefectural variation in national health insurance catalog implementation creates inconsistent patient access across Kanto, Kansai, and Chubu regions.
- Enzymatic sensor degradation:Interstitial glucose measurement accuracy degrades with sensor wear time, limiting effective device lifespan and increasing replacement frequency costs.
- Transmitter miniaturization costs:Precision manufacturing of compact electrochemical housings concentrates supply among specialized Japanese electronics component suppliers.
Strategic Opportunities
- Subscription-based sensor models:Recurring revenue platforms for data analytics and remote monitoring services create predictable cash flows beyond hardware sales.
- Regional diabetes educator networks:Partnerships with certified educators in Hokkaido and Kyushu accelerate patient onboarding in undersupplied prefectures outside Tokyo's specialist density.
- Integrated data platforms:Convergence of CGM streams with electronic health record systems enables population-level metabolic management for payers.
Industry Challenges
- Embedded software licensing complexity:Multi-layered intellectual property arrangements for predictive algorithms create negotiation friction with hospital procurement channels.
- JIS T 0601-1 electrical safety certification:Extended testing timelines for biocompatibility and electromagnetic compatibility delay product launches by 12-18 months.
- Legacy hospital infrastructure integration:Proprietary data formats from incumbent monitoring systems require costly middleware development for seamless interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Continuous Glucose Monitoring Devices Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Sensors, Transmitters, Receiver Devices, Continuous Glucose Monitors End User: Hospitals, Homecare Settings, Diabetes Clinics, Community Health Centers Technology: Real-Time Monitoring, Flash Glucose Monitoring, Bluetooth Enabled, Wireless Connectivity Application: Type 1 Diabetes Management, Type 2 Diabetes Management, Gestational Diabetes, Research Purposes |
| Companies Covered | Senseonics, Nipro Corporation, Dexcom, ArkRay, Terumo Corporation, Abbott, Ascensia Diabetes Care, Panasonic Healthcare, Medtronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Continuous Glucose Monitoring Devices Market Shifts & Advancements
Sensor miniaturization and algorithmic prediction capabilities are converging to displace episodic fingerstick monitoring, while regulatory frameworks and procurement models adapt to support continuous metabolic surveillance as standard-of-care.
Factory-calibrated electrochemical sensors are unifying glucose measurement workflows by eliminating patient-performed calibration steps. Homecare patients in Osaka and Nagoya prefectures are adopting these systems at accelerating rates. This unification is compressing the competitive advantage window for calibration-dependent architectures and forcing incumbent suppliers to accelerate R&D transitions.
METI's medical device industry promotion policies are redirecting domestic manufacturing incentives toward wearable sensor production. Tax credits for precision electronics assembly are expanding local supply capacity for transmitter components. The Kanto region's device manufacturers are responding by consolidating component sourcing within Japan's domestic industrial clusters.
Patient data ownership preferences are shifting purchasing authority toward individual consumers rather than institutional procurement departments. Subscription direct-to-patient channels are displacing traditional hospital-based dispensing in urban prefectures. This behavioral pivot is most visible in Tokyo's dense specialist network, where endocrinologists now prescribe sensors for home delivery rather than clinic pickup.
Japan Continuous Glucose Monitoring Devices Market Segmentation
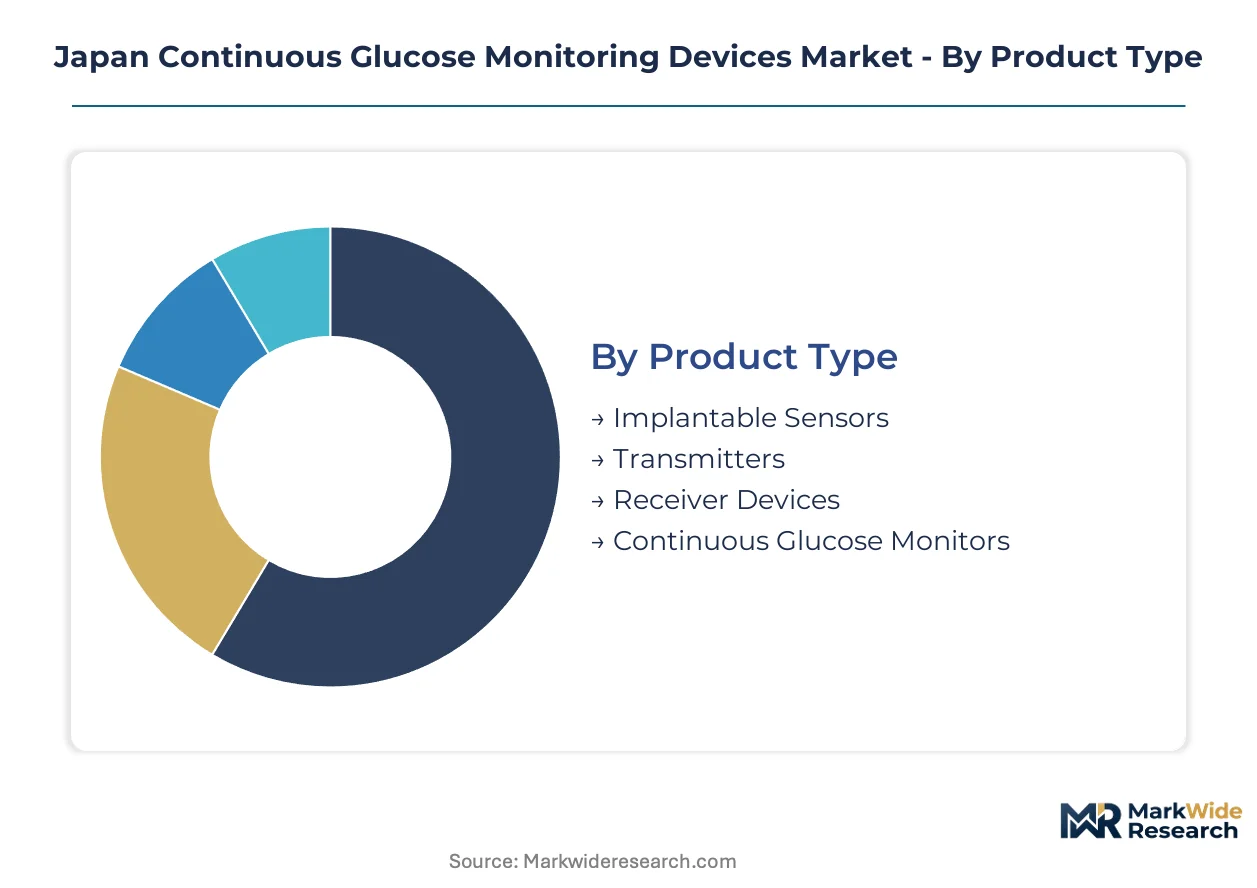
CGM device segmentation in Japan reflects divergent patient workflows across institutional and residential settings. Reimbursement tiers and software integration requirements fragment procurement patterns between prefectural hospital systems and direct-to-patient subscription channels.
Product Type:
Implantable sensors function as standalone consumables requiring periodic replacement, while transmitters and receivers form integrated system architectures with embedded software dependencies.
- Implantable Sensors:Enzymatic electrochemical strips inserted subcutaneously for interstitial glucose measurement. Tokyo's homecare patients drive replacement volume through subscription auto-ship programs tied to PMDA-approved wear durations.
- Transmitters:Miniaturized radio-frequency modules relaying sensor data to display devices. Precision manufacturing constraints in Kanto's electronics clusters limit supplier diversification and sustain premium procurement pricing in hospital channels.
- Receiver Devices:Dedicated handheld or smartphone-integrated displays with embedded predictive algorithms.
- Continuous Glucose Monitors:Fully integrated sensor-transmitter-receiver systems.
Volume placements concentrate in Implantable Sensors; the faster expansion belongs to Transmitters.
End User:
Cost tier stratification separates high-acuity institutional protocols from consumer-directed residential monitoring with remote physician oversight.
- Hospitals:Acute care facilities managing intensive insulin therapy with integrated electronic health record connectivity. Osaka prefecture's tertiary centers anchor procurement volume through centralized endocrinology departments and standardized formulary contracts.
- Homecare Settings:Residential patients self-managing chronic glucose surveillance with telemedicine support. Japan's aging demographic and MHLW reimbursement revisions for wearable devices are accelerating patient migration from clinic-based to home-based protocols in Kanto and Kansai regions.
- Diabetes Clinics:Specialist outpatient facilities prescribing and dispensing CGM systems.
- Community Health Centers:Primary care access points in rural prefectures with limited endocrinology specialist density.
Procurement volume clusters in Hospitals; Homecare Settings are climbing the fastest.
Technology:
Application workflow separates continuous automated streaming from patient-initiated scanning protocols with distinct calibration requirements.
- Real-Time Monitoring:Automated glucose readings transmitted at fixed intervals with predictive alert capabilities. Type 1 diabetes patients in Tokyo's dense specialist network prioritize these systems for hypoglycemia prevention during intensive insulin therapy.
- Flash Glucose Monitoring:On-demand scanning without calibration requirements. Price-sensitive Type 2 segments in Nagoya and Osaka prefectures favor this technology for cost-efficient metabolic awareness without continuous data streams.
- Bluetooth Enabled:Short-range wireless protocols connecting sensors to smartphones or dedicated receivers.
- Wireless Connectivity:Broad-spectrum radio transmission including proprietary and cellular-enabled data relay.
Adoption share concentrates in Real-Time Monitoring; Flash Glucose Monitoring is gaining share fastest.
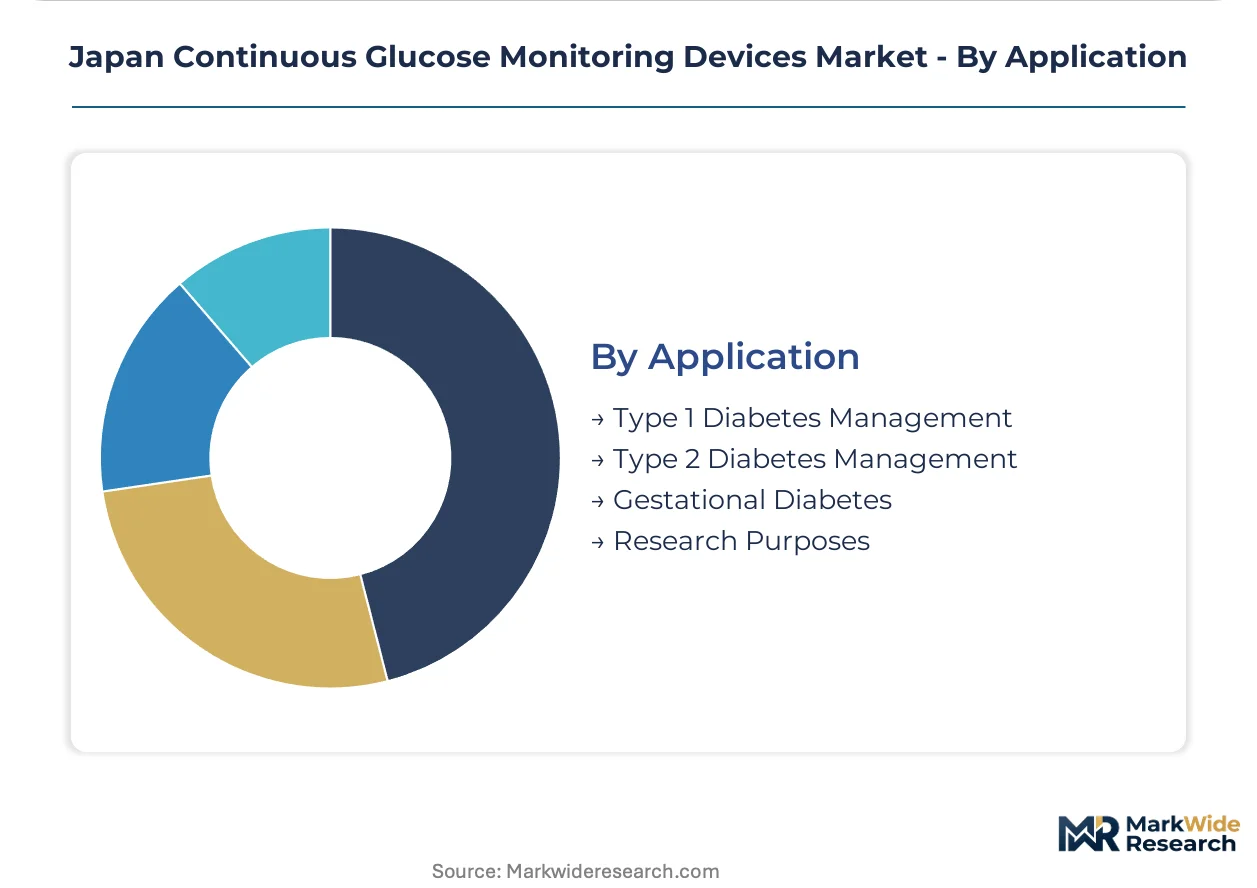
Application:
Disease severity and reimbursement eligibility create divergent patient populations with distinct monitoring intensity requirements and out-of-pocket exposure.
- Type 1 Diabetes Management:Intensive insulin-dependent patients requiring continuous surveillance to prevent hypoglycemic episodes. Kanto region's pediatric and adult endocrinology specialists prioritize factory-calibrated systems for this population under revised MHLW reimbursement tiers.
- Type 2 Diabetes Management:Larger addressable population with variable insulin dependence and price sensitivity. Flash glucose monitoring's calibration-free protocols are expanding penetration among this segment in urban prefectures with direct-to-patient subscription channels.
- Gestational Diabetes:Temporary monitoring protocols during pregnancy with specific safety and accuracy requirements.
- Research Purposes:Academic and pharmaceutical clinical trials requiring standardized metabolic data collection.
Patient volume concentrates in Type 1 Diabetes Management; Type 2 Diabetes Management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's National Strategic Special Zones program channels medical device manufacturing incentives into designated prefectural clusters, concentrating CGM production capacity and patient access infrastructure within Kanto, Kansai, and Chubu economic corridors.
Kanto
Tokyo's dense endocrinology specialist network drives patient onboarding velocity for continuous monitoring protocols. PMDA's streamlined software-as-medical-device pathway accelerates algorithm update approvals for intensive insulin therapy patients. Yokohama's precision electronics manufacturers supply miniaturized transmitter components to domestic device assemblers.
Kansai
Osaka prefecture's tertiary care centers anchor hospital procurement volume through centralized diabetes departments and standardized formulary contracts. MHLW reimbursement revisions for factory-calibrated sensors compress patient out-of-pocket costs in urban Osaka and Kobe. Kyoto's medical device distributors coordinate flash glucose monitoring deployments to residential patients.
Chubu
Nagoya's industrial automation heritage supports electrochemical sensor fabrication for domestic CGM suppliers. METI tax credits for wearable medical device assembly expand local transmitter production capacity. Aichi prefecture's diabetes educator networks accelerate homecare patient migration from clinic-based monitoring protocols.
Kyushu
Fukuoka's aging demographic concentrates demand for residential glucose surveillance with remote physician oversight. Prefectural variation in national health insurance catalog implementation creates patient access gaps that regional educator partnerships seek to bridge. Kumamoto's community health centers serve as primary care access points with limited endocrinology specialist density.
Hokkaido
Sapporo's dispersed population geography favors subscription-based direct-to-patient sensor delivery over hospital-based dispensing. Cold climate conditions influence sensor adhesive performance and replacement frequency calculations. Regional diabetes educator certification programs expand patient onboarding capacity outside major metropolitan corridors.
Japan Continuous Glucose Monitoring Devices Market Competitive Landscape
United States-based manufacturers anchor the premium technology tier; Japanese domestic specialists hold procurement relationships with prefectural hospital systems. The vendor base concentrates around integrated system architectures and calibration-free sensor protocols. Three archetypes dominate: transmitter miniaturization specialists, flash glucose monitoring platform operators, and regional reimbursement navigation partners. Competitive dynamics center on PMDA approval velocity and MHLW reimbursement tier positioning.
Within the integrated system tier, Dexcom and Abbott occupy positions exemplifying divergent technical approaches to patient workflow design. Terumo Corporation represents domestic fabricators navigating Japan's reimbursement complexity through educator network partnerships. These three anchors illustrate how geographic origin and regulatory familiarity shape competitive positioning across hospital procurement and direct-to-patient channels.
| Leading Market Players |
|---|
| Senseonics |
| Nipro Corporation |
| Dexcom |
| ArkRay |
| Terumo Corporation |
| Abbott |
| Ascensia Diabetes Care |
| Panasonic Healthcare |
| Medtronic |
| Others |
Supply & Pricing Matrix
Precision electrochemical sensor substrates, sourced primarily from Kanto-based ceramic foundries, cascade through three pricing tiers as they move from raw wafer processing to finished transmitter assembly for hospital procurement channels.
Pricing Analysis
Short lead-time premiums of 15-20% apply to factory-calibrated sensor orders from Tokyo's homecare subscription channels, while spot inventory in Osaka's distributor networks trades at modest discounts. The dominant pricing model is subscription-based recurring revenue with tiered hardware access fees. Price differentiation rests on calibration-free certification tiers and bundled remote monitoring services. Pricing pressure stems from MHLW reimbursement compression on enzymatic sensor replacements. Type 2 diabetes patients in Nagoya prefecture exhibit highest price sensitivity; intensive insulin therapy patients in Tokyo's specialist network show lowest.
Supply Chain Analysis
Workforce availability constraints in Aichi and Kanagawa prefectures limit expansion of precision transmitter assembly capacity despite METI tax incentives. Supply concentrates in Japan's domestic electronics clusters, with secondary sourcing from South Korean semiconductor packaging houses. Raw material dependencies include platinum-group catalysts for enzymatic electrodes, biocompatible polymers for sensor housings, and rare-earth magnets for transmitter coupling. Single-source vulnerability sits with specialized ceramic substrate suppliers in Yokohama. Distribution runs through regional medical device distributors coordinating with prefectural hospital procurement committees and direct-to-patient subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
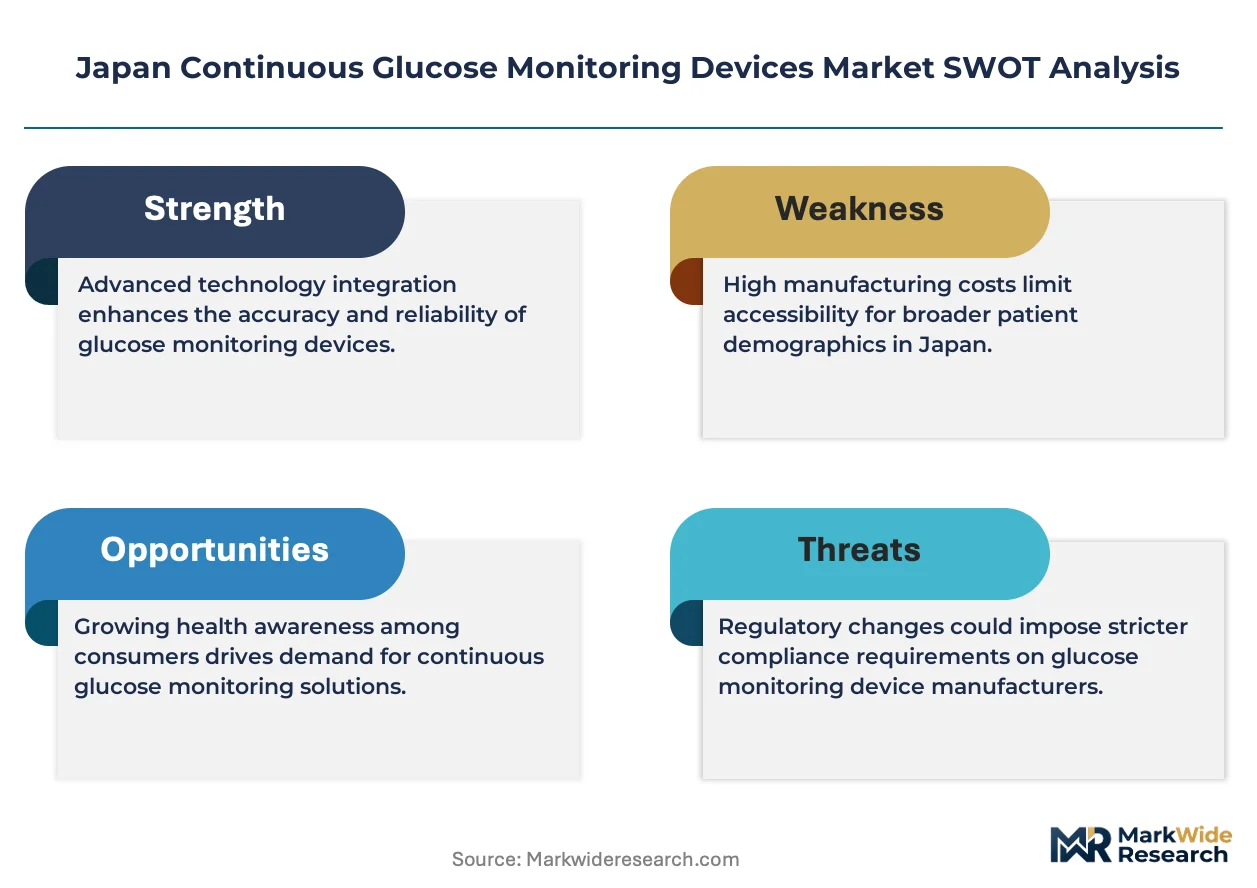
The Japan CGM market is becoming a vertical-integration race as manufacturers pursue captive control over enzymatic sensor substrate production to defend margin structures against reimbursement compression.
For Market Incumbents: Anticipate flash glucose monitoring platform entrants from South Korean electronics conglomerates by accelerating backward integration into ceramic substrate foundries. Secure exclusive supply agreements with Kanto's precision electronics clusters before competitor capacity expansion. Prioritize PMDA software-as-medical-device pathway investments to maintain algorithm update velocity over hardware-centric rivals. For New Entrants and Emerging Players: Launch via direct-to-patient subscription channels in Hokkaido and Kyushu, where regional educator networks create lower patient acquisition costs than Tokyo's saturated specialist corridor. Target gestational diabetes monitoring protocols, an underserved application with distinct reimbursement eligibility and shorter sales cycles. Differentiate through cold-climate adhesive formulations addressing Hokkaido's replacement frequency challenges. For Investors and Strategic Acquirers: METI's expansion of factory-calibrated sensor reimbursement tiers is the leading indicator that subscription-based data platform economics will dominate hardware margins within the decade. Focus acquisition screening on domestic fabricators with embedded educator network partnerships and PMDA approval track records. Watch for PMDA software update velocity divergence between integrated system architects and component suppliers as the inflection signal for sustainable competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Pathway Investment | Accelerates algorithm update approvals for predictive hypoglycemia alerts in Tokyo's intensive therapy patient base. |
| Regional Diabetes Educator Network Partnership | Reduces patient onboarding friction in Kyushu and Hokkaido prefectures with limited endocrinology specialist density. |
| Factory-Calibrated Sensor Reimbursement Strategy | Positions products for MHLW tier upgrades that compress patient out-of-pocket exposure in Kansai urban corridors. |
| Backward Integration into Ceramic Substrate Production | Captures margin pools currently concentrated among Yokohama precision electronics suppliers for transmitter components. |
| Integrated Electronic Health Record Data Platform | Enables population-level metabolic management contracts with prefectural hospital systems and national payer consortia. |
Research Methodology
PMDA approval databases, MHLW reimbursement catalog revisions, and METI industrial promotion policy filings formed the secondary backbone, cross-referenced with primary interviews involving hospital biomedical engineers, GPO contracts managers, diabetes educator certification bodies, and endocrinology department heads. Bottom-up and top-down triangulation validated volume estimates against prefectural procurement records and subscription platform dispensing data.
Bottom-up modeling anchored patient population projections to Japan's National Diabetes Survey cohorts, while top-down analysis cross-checked against medical device import statistics and domestic production value disclosures. Segmentation dimensions included technology architecture, end-user setting, disease application, and prefectural reimbursement implementation tier. CAGRs were derived from fitted adoption curves incorporating MHLW policy revision timelines and demographic aging trajectories. Forecast inputs incorporated enzymatic sensor wear-time degradation rates and transmitter miniaturization cost curves.
The model assumes a particular technology adoption path favoring factory-calibrated sensors; alternative pathways for calibration-dependent architectures with superior accuracy profiles would alter the outlook for incumbent supplier positioning. Forecasts reflect assumptions about PMDA approval velocity and MHLW reimbursement tier stability that may shift with political transitions or safety signal events. Material deviation in METI domestic manufacturing incentive continuity or PMDA software pathway regulatory interpretation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
Australia Blood Glucose Monitoring Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
North America Insulin Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
South Africa Oral Antidiabetic Drug Market