
 Drone Power Sources Market | 2026-2036
Drone Power Sources Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Power Sources Market Analysis
OEM-direct procurement channels for drone power systems is fragmenting as battery specialists bypass traditional component distributors to serve UAV manufacturers directly. DJI leverages captive cell manufacturing to control cost structures across its enterprise drone portfolio. AeroVironment anchors its military-grade power supply chain through US-based qualification protocols. GreenJets specializes in solid-state cell architectures for extended-endurance commercial platforms.
Drone power sources encompass electrochemical and fuel-cell energy systems engineered to deliver specific energy densities exceeding 200 Wh/kg for sustained aerial operation, with voltage architectures ranging from low-voltage consumer packs to ultra high voltage arrays driving heavy-lift cargo rotors. Lithium polymer dominates current commercial deployment due to mature manufacturing economics, while fuel cells represent the fastest-expanding category as hydrogen storage mass ratios improve for beyond-visual-line-of-sight missions. The voltage rating dimension stratifies sharply, with low voltage saturating consumer segments and ultra high voltage capturing margin concentration in military and heavy-payload applications.
The FAA's Part 107 framework and EU CE marking requirements for unmanned aircraft systems shape power system certification pathways, while China's GB standards govern cell safety testing for domestic UAV exports. The EU F-Gas Regulation constrains refrigerant-based thermal management in European-deployed systems, redirecting R&D toward passive cooling architectures. Stakeholders must weigh fuel cell infrastructure investment against solid-state lithium commercialization timelines when committing to next-generation platform designs.
Market Dynamics
Battery chemistry maturation and fuel-cell infrastructure buildout are creating divergent investment pathways for platform developers weighing energy density against refueling logistics.
Growth Catalysts
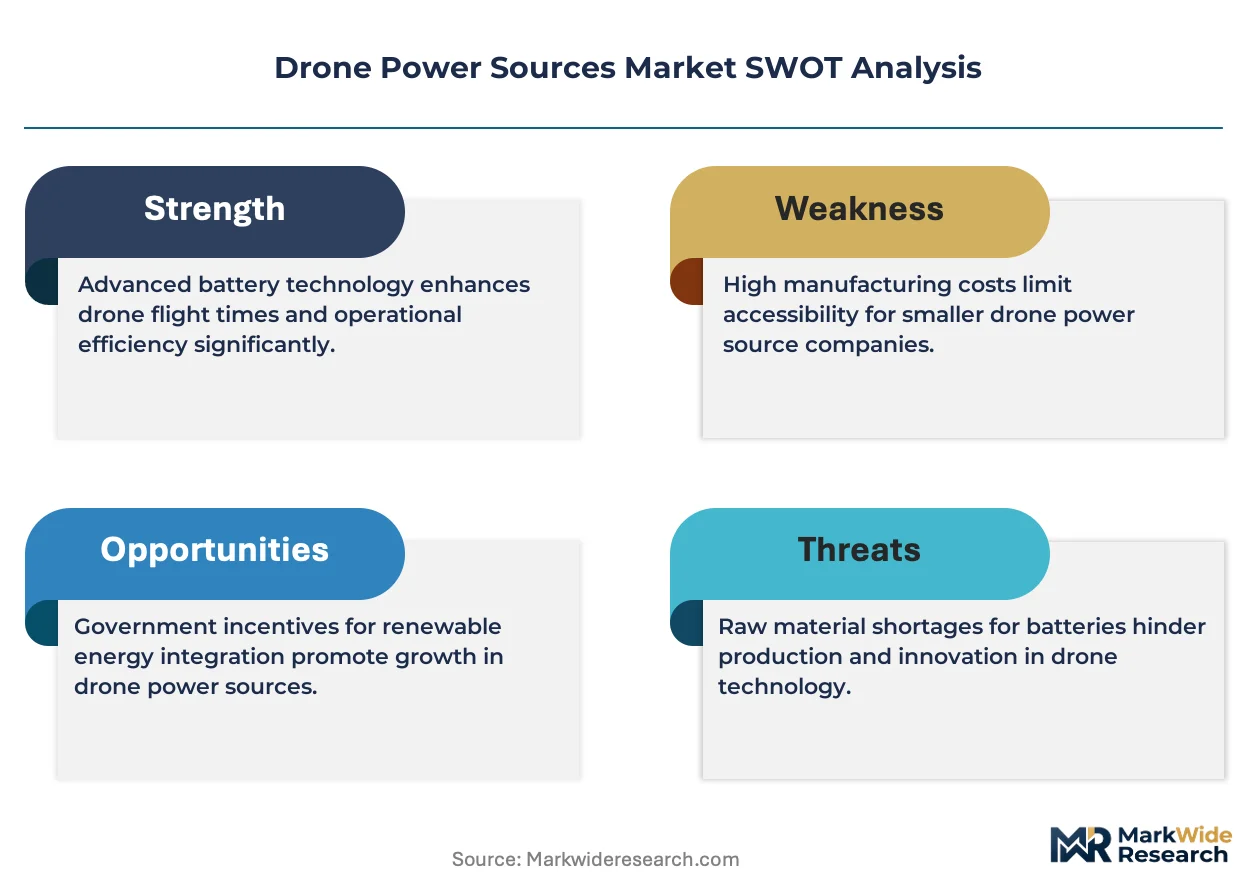
- EU Green Deal mandates:Clean mobility requirements are accelerating hydrogen fuel cell adoption for extended-endurance commercial missions across European airspace.
- Agricultural monitoring fleets:Brazil's crop-spraying operators are scaling battery-swarm architectures to maximize field coverage per charging cycle.
- Guangdong manufacturing corridor concentration:Direct cell-to-drone assembly integration is compressing procurement lead times for OEMs.
Market Restraints
- Cobalt and lithium price volatility:Raw material cost swings in cathode supply chains are compressing margins for lithium polymer pack assemblers.
- Single-region cell production concentration:Dependence on China's battery manufacturing base creates geopolitical exposure for Western UAV supply chains.
- Hydrogen storage mass ratios:Current fuel tank gravimetric efficiency limits fuel cell range advantages to specific payload classes.
Strategic Opportunities
- Beyond-visual-line-of-sight logistics:Hydrogen fuel cells are opening cargo drone routes where battery swapping proves operationally impractical.
- US military qualification protocols:Domestic certification standards are creating captive demand for US-based power system manufacturers.
- Solid-state lithium commercialization:Emerging cell architectures promise 300+ Wh/kg densities for premium endurance platforms.
Industry Challenges
- Multiphysics simulation expertise:Thermal-electrochemical-mechanical modeling for solid-state cell integration outpaces available engineering talent pools.
- Cross-certification timelines:FAA Part 107 and EU CE marking divergence forces redundant testing cycles for dual-market platform developers.
- Legacy voltage architecture incompatibility:Ultra high voltage arrays require complete powertrain redesigns for existing heavy-lift rotor designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Power Sources Market |
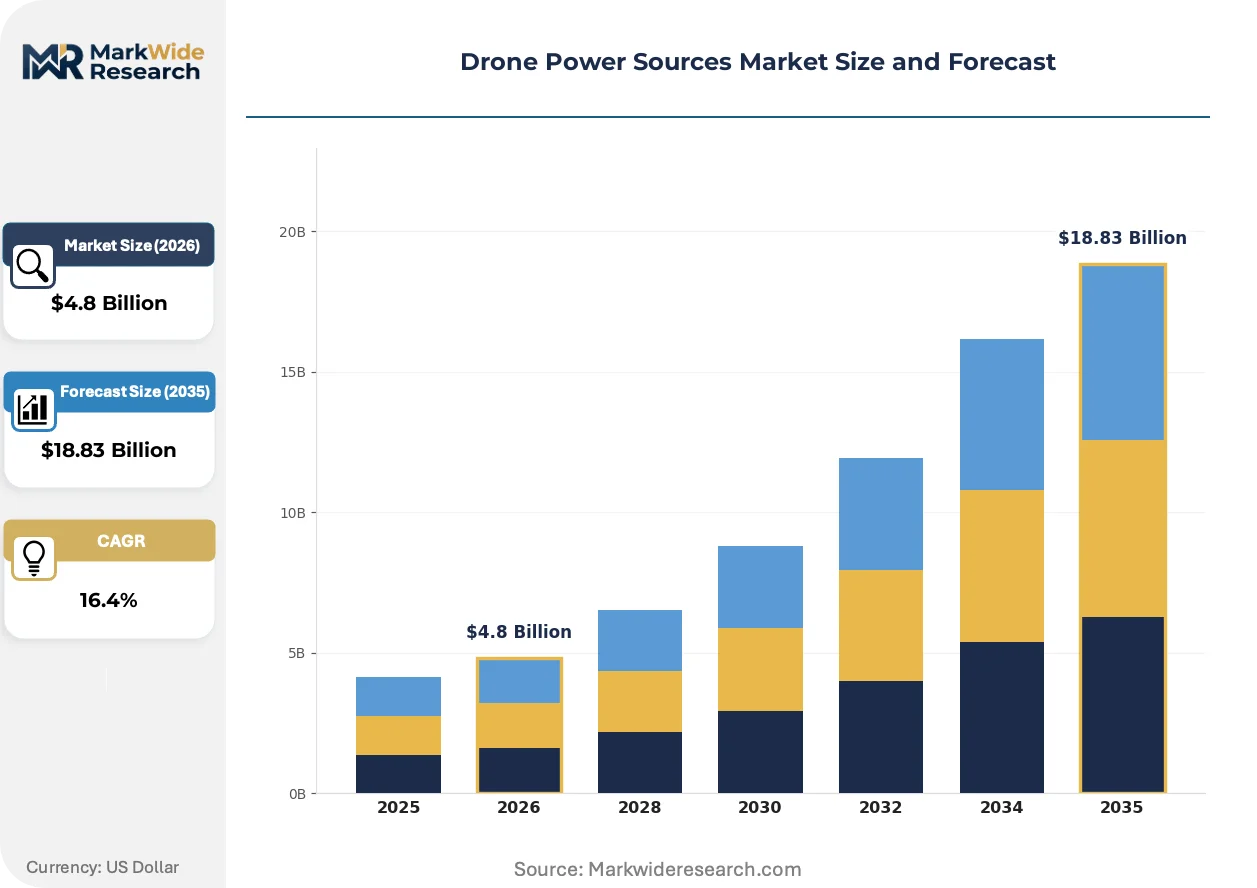
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.83 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: Lithium Polymer, Lithium Ion, Nickel Metal Hydride, Fuel Cells Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage Application: Agricultural Monitoring, Surveillance, Delivery Services, Infrastructure Inspection End User: Commercial, Government, Consumer, Military |
| Companies Covered | JOUAV, Skydio, GreenJets, AeroVironment, DJI, Blueflite, Autel Robotics, Ondas, Ascent AeroSystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Power Sources Market Emerging Trajectories
Power system architectures are bifurcating between incremental lithium polymer optimization and disruptive fuel-cell deployment, with thermal management emerging as the critical integration bottleneck.
Solid-state lithium-metal cells with ceramic electrolyte barriers are rendering obsolete conventional liquid-electrolyte lithium polymer packs in premium commercial segments. Agricultural operators and infrastructure inspection fleets are pilot-testing these architectures for 40% endurance extensions. The technology is rendering obsolete the voltage-degradation tradeoffs that previously forced platform designers to oversized battery masses.
The EU F-Gas Regulation is constraining refrigerant-based active cooling systems in European-deployed UAVs. Developers are redirecting R&D investment toward passive cooling architectures and phase-change materials. Military and heavy-payload segments are absorbing the highest compliance costs while consumer tiers shift to simpler thermal designs.
Direct OEM procurement from cell specialists is displacing traditional component distributor channels across enterprise drone segments. Battery manufacturers are establishing dedicated UAV application engineering teams to bypass electronics wholesalers. China's Guangdong corridor exhibits the most advanced vertical integration, with cell production lines feeding directly into OEM assembly floors.
Drone Power Sources Market Segmentation
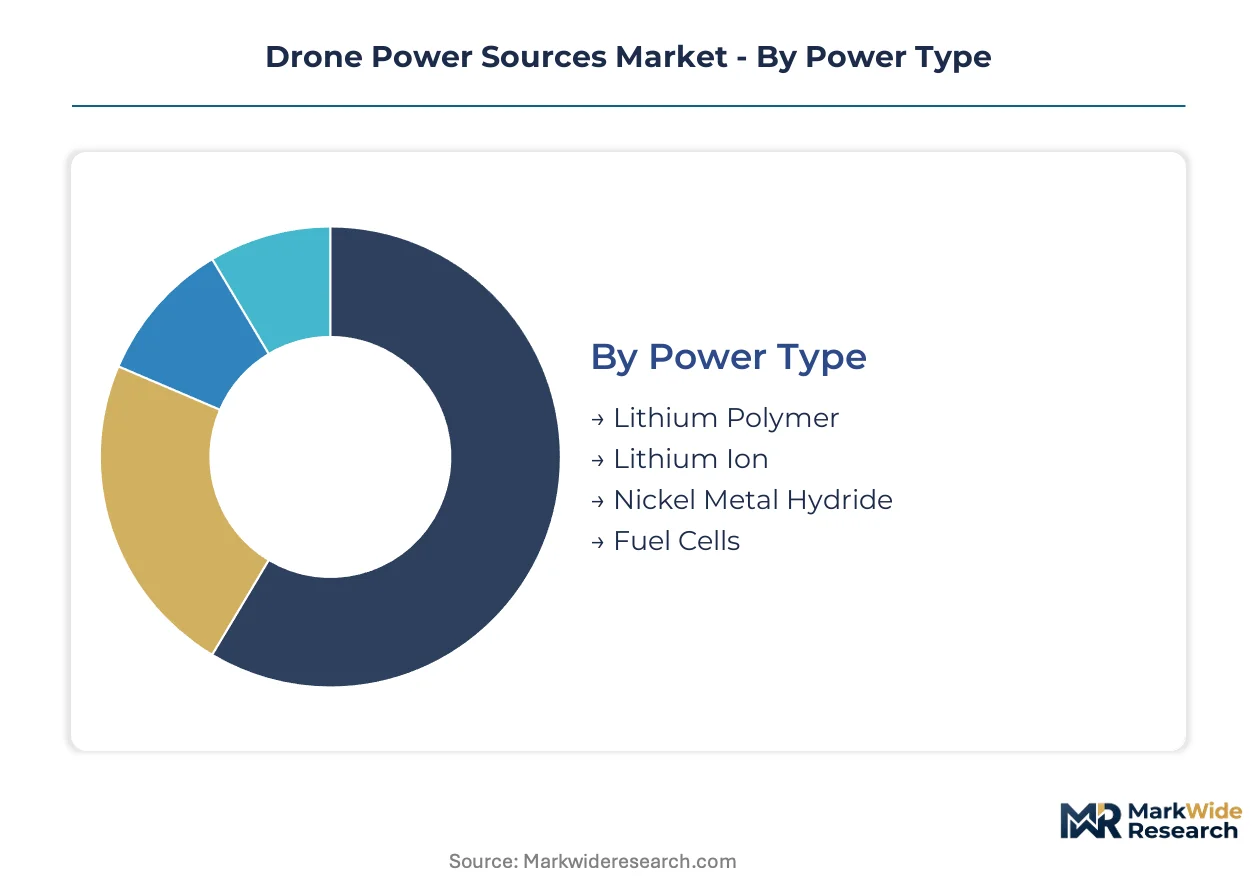
Drone power source segmentation reveals how voltage architecture and chemistry choices map directly to mission economics. Platform developers select energy systems based on payload mass, flight duration requirements, and refueling infrastructure availability.
Power Type:
Chemistry selection determines energy density, cycle life, and thermal management complexity across deployment scenarios.
- Lithium Polymer:Pouch-cell construction delivers superior form-factor flexibility for airframe integration. Agricultural monitoring fleets in Brazil rely on these packs for rapid field-swapping operations where charging infrastructure remains sparse.
- Fuel Cells:Proton-exchange membrane architectures convert hydrogen to electricity with water vapor as sole byproduct. The EU Green Deal's clean mobility mandates are accelerating adoption for beyond-visual-line-of-sight cargo routes where battery swapping proves operationally impractical.
- Lithium Ion:Cylindrical and prismatic formats dominate industrial-grade platforms requiring standardized cell sourcing.
- Nickel Metal Hydride:Mature chemistry retains niche positioning in training and hobbyist segments where energy density requirements remain modest.
Lithium Polymer commands the established base. The steepest expansion runs through Fuel Cells.
Voltage Rating:
Electrical potential tiers stratify sharply between consumer accessibility and industrial performance thresholds.
- Low Voltage:Sub-50V architectures serve hobbyist and entry-level commercial platforms with minimal regulatory burden. Consumer segments saturate here due to simplified safety certification pathways under FAA Part 107.
- Ultra High Voltage:400V+ arrays drive heavy-lift cargo rotors and military platforms where power-to-weight ratios determine mission feasibility. China's Guangdong manufacturing corridor concentrates production of these specialized packs for enterprise OEMs.
- Medium Voltage:50-200V range captures mid-tier commercial inspection and mapping applications.
- High Voltage:200-400V tier bridges professional cinematography and light industrial payload categories.
Low Voltage retains volume leadership. Ultra High Voltage is gaining share fastest in margin-concentrated military and heavy-payload applications.
Application:
Mission profile dictates endurance requirements, cycling frequency, and environmental exposure tolerances.
- Agricultural Monitoring:Crop-spraying platforms demand rapid battery exchange and resistance to chemical exposure. Brazil's operators are scaling swarm architectures to maximize hectare coverage per charging cycle.
- Delivery Services:Last-mile logistics requires predictable range performance across variable payload weights. Hydrogen fuel cells are opening routes where battery energy density limits profitable operation.
- Surveillance:Law enforcement and private security prioritize silent operation and rapid deployment readiness.
- Infrastructure Inspection:Power line and pipeline surveys favor extended loiter times with minimal maintenance intervals.
Agricultural Monitoring anchors current procurement volumes. Delivery Services shows the most aggressive trajectory as fuel cell infrastructure matures.
End User:
Customer category shapes procurement channel preferences, qualification protocols, and total cost of ownership calculations.
- Commercial:Enterprise operators prioritize operational uptime and predictable replacement schedules. Direct OEM procurement from cell specialists is displacing traditional distributor channels across this segment.
- Military:Defense applications mandate US-based qualification protocols and supply chain provenance. AeroVironment and comparable contractors anchor captive demand for domestically certified power systems.
- Government:Civil agency procurement balances performance specifications with public-sector budget cycles.
- Consumer:Retail purchasers prioritize upfront cost over lifecycle economics, concentrating demand in low-voltage lithium polymer configurations.
Commercial end users dominate procurement value. Military contracts deliver the highest per-unit margins through specialized qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's Guangdong manufacturing corridor while Western UAV developers absorb premium qualification costs. Brazil's agricultural operators exploit local labor arbitrage for battery-swarm field servicing. The EU Green Deal's clean mobility mandates redirect procurement budgets toward hydrogen infrastructure.
United States
Military qualification protocols under FAA Part 107 create captive demand for domestically certified power systems. Defense contractors anchor supply chains through US-based cell testing and assembly operations. California's aerospace clusters concentrate fuel-cell R&D investment for extended-endurance cargo platforms.
China
Guangdong's cell-to-drone assembly integration compresses procurement lead times for enterprise OEMs. GB standards govern cell safety testing for domestic UAV exports to global markets. Shenzhen's manufacturing floors feed directly into DJI's captive power system production lines.
Germany
EU F-Gas Regulation constrains refrigerant-based thermal management in European-deployed systems. Industrial inspection fleets drive demand for solid-state lithium architectures with passive cooling. Bavaria's automotive battery expertise migrates into UAV power system engineering teams.
Brazil
Agricultural monitoring fleets scale battery-swarm operations for crop-spraying coverage across soybean and sugarcane belts. ANVISA chemical exposure standards shape pack sealing requirements for agrochemical environments. São Paulo state's equipment distributors stock rapid-exchange lithium polymer inventories for harvest-season uptime.
Japan
METI funding programs accelerate solid-state lithium commercialization timelines for industrial UAV segments. Precision agriculture and infrastructure inspection operators pilot-test ceramic electrolyte cells. Nagoya's materials science institutes transfer automotive battery know-how to aerial platform developers.
Drone Power Sources Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in chemistry and cell manufacturing. The vendor base stratifies between captive producers serving single OEMs and independent suppliers selling across multiple drone manufacturers. Three archetypes dominate: vertically integrated platform owners, independent cell specialists, and military qualification holders. Competitive moves center on backward integration into cell production and geographic diversification of assembly operations to escape single-region supply exposure.
Within the platform-integrator tier, DJI leverages captive cell manufacturing to control cost structures across its enterprise portfolio. AeroVironment anchors military-grade positioning through US-based qualification protocols. GreenJets occupies the independent specialist position with solid-state cell architectures for extended-endurance commercial platforms.
| Leading Market Players |
|---|
| JOUAV |
| Skydio |
| GreenJets |
| AeroVironment |
| DJI |
| Blueflite |
| Autel Robotics |
| Ondas |
| Ascent AeroSystems |
| Others |
Supply Flow & Price Mechanics
China's Guangdong manufacturing corridor concentrates cell-to-drone assembly capacity, compressing procurement lead times for OEMs while compressing margins for pack assemblers outside this cluster. Downstream pricing power flows to platform integrators with captive supply lines, leaving independent battery specialists exposed to raw material cost swings.
Pricing Analysis
Configured-to-order pricing for ultra high voltage military arrays commands substantial premiums over standard low-voltage consumer packs. Three-tier pricing structure across premium, standard, and economy levels separates US-qualified military systems from enterprise-grade commercial platforms and hobbyist lithium polymer configurations. Price differentiation hinges on certification grade and geographic delivery cost, with EU F-Gas compliance adding thermal management expense to European-deployed units. Pricing pressure stems from cobalt and lithium price volatility in cathode supply chains, with lithium polymer pack assemblers absorbing the steepest margin compression. Consumer segments exhibit highest price sensitivity, while military end users prioritize qualification provenance over unit economics.
Supply Chain Analysis
Upstream feedstock flows for lithium polymer cells draw from Chilean lithium brine operations, Australian spodumene mines, and Indonesian nickel laterite deposits. Cell manufacturing concentrates in China, South Korea, and Japan, with China's Guangdong corridor hosting the deepest UAV-specific integration. Raw material dependencies rest on cobalt cathode chemistries, ceramic electrolyte precursors for solid-state architectures, and hydrogen storage alloys for fuel cell systems. Single-source vulnerability in China's battery manufacturing base creates geopolitical exposure for Western UAV supply chains. Distribution runs through direct OEM procurement channels displacing traditional electronics wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone power source incumbents face substitution defense imperatives as hydrogen fuel cell architectures threaten to displace lithium polymer dominance in beyond-visual-line-of-sight logistics. Solid-state lithium commercialization timelines represent a second wave of chemistry substitution requiring strategic positioning.
For Market Incumbents: Harden supply chain resilience through backward integration into cell production or captive offtake agreements with qualified suppliers outside China's manufacturing base. Deepen US-based qualification protocol investment to defend military contract positioning against AeroVironment's anchored supply chain. Solid-state lithium R&D partnerships with Japan's METI-funded institutes offer technology hedge against fuel cell range advantages.
For New Entrants and Emerging Players: Brazil's agricultural monitoring corridors present underpenetration for rapid-exchange battery-swarm servicing infrastructure, where local labor arbitrage supports field-level operations. Target solid-state lithium pilot programs with European infrastructure inspection fleets constrained by EU F-Gas thermal management rules. Go-to-market through OEM application engineering teams bypassing traditional distributor channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors independent cell specialists with solid-state lithium-metal architectures and fuel cell membrane expertise over commodity lithium polymer assemblers. Long-term viability across the projection horizon hinges on chemistry transition timing and hydrogen infrastructure buildout pace. Acquisition target archetypes include ceramic electrolyte developers and US-based qualification holders. Signal to watch: FAA Part 107 revisions addressing beyond-visual-line-of-sight power system certification pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Cell Commercialization | Ceramic electrolyte barriers enable 300+ Wh/kg densities for premium endurance platforms. |
| Hydrogen Infrastructure Partnership | Fuel cell range advantages open cargo routes where battery swapping proves operationally impractical. |
| US Qualification Protocol Investment | FAA Part 107 compliance creates captive demand for domestically certified power systems. |
| Backward Integration into Cell Production | DJI's captive manufacturing demonstrates cost control across enterprise drone portfolios. |
| Passive Cooling Architecture Development | EU F-Gas Regulation redirects R&D toward refrigerant-free thermal management systems. |
Methodological Framework
Desk research of customs and trade data, SEC filings from publicly traded UAV manufacturers, and FAA certification databases preceded structured interviews with drone OEM procurement directors, battery pack engineering leads, fuel cell system architects, and agricultural fleet operations managers. Secondary validation drew from EU CE marking documentation, China's GB standards publications, and hydrogen infrastructure development filings. Bottom-up cell production capacity estimates triangulated against top-down platform deployment forecasts.
Assumption sets held fixed the EU Green Deal clean mobility mandate trajectory and China's dual carbon goals for manufacturing emissions, while varying solid-state lithium commercialization timelines and hydrogen storage mass ratio improvement curves. Segmentation dimensions modeled across the analysis window encompassed chemistry type, voltage architecture tier, application mission profile, and end-user procurement channel. CAGRs derived from production capacity expansion announcements, OEM platform launch schedules, and regulatory pathway acceleration signals.
Practitioners should monitor cobalt and lithium commodity price movements, FAA Part 107 revision drafts, and solid-state lithium pilot program results for early signals warranting forecast revision. Cross-checking against IEA hydrogen infrastructure deployment benchmarks and automotive battery cost curve trajectories is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Liquid Metal Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Automotive Starting Battery Market
Batteries
Zinc-Manganese Oxide Batteries Market
Batteries
Portable Battery Powered Products Market
Batteries
Behind-The-Meter (BTM) Battery Market
Batteries
Aluminum Based Battery Market
Batteries
India Micro Batteries Market
Batteries
Hybrid Flow Battery Market
Batteries
India Battery Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Europe Battery Cell Market
Batteries
High Temperature NiMH Battery Market
Batteries
SLI Battery Market
Batteries
Power Battery Cells Market
Batteries
Iron-Chromium Flow Battery Market