
 Battery Raw Materials Market | 2026-2036
Battery Raw Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Raw Materials Market Analysis
Project finance tied to offtake agreements is reconfiguring entry barriers for mid-scale miners and refiners. Albemarle leverages its brine extraction dominance in South America to sustain long-term lithium carbonate supply security. POSCO Future M anchors Korean cathode precursor output through integrated nickel-to-NCM processing. Sumitomo Metal Mining Co., Ltd. competes via captive cobalt and nickel assets spanning Southeast Asian and African sources.
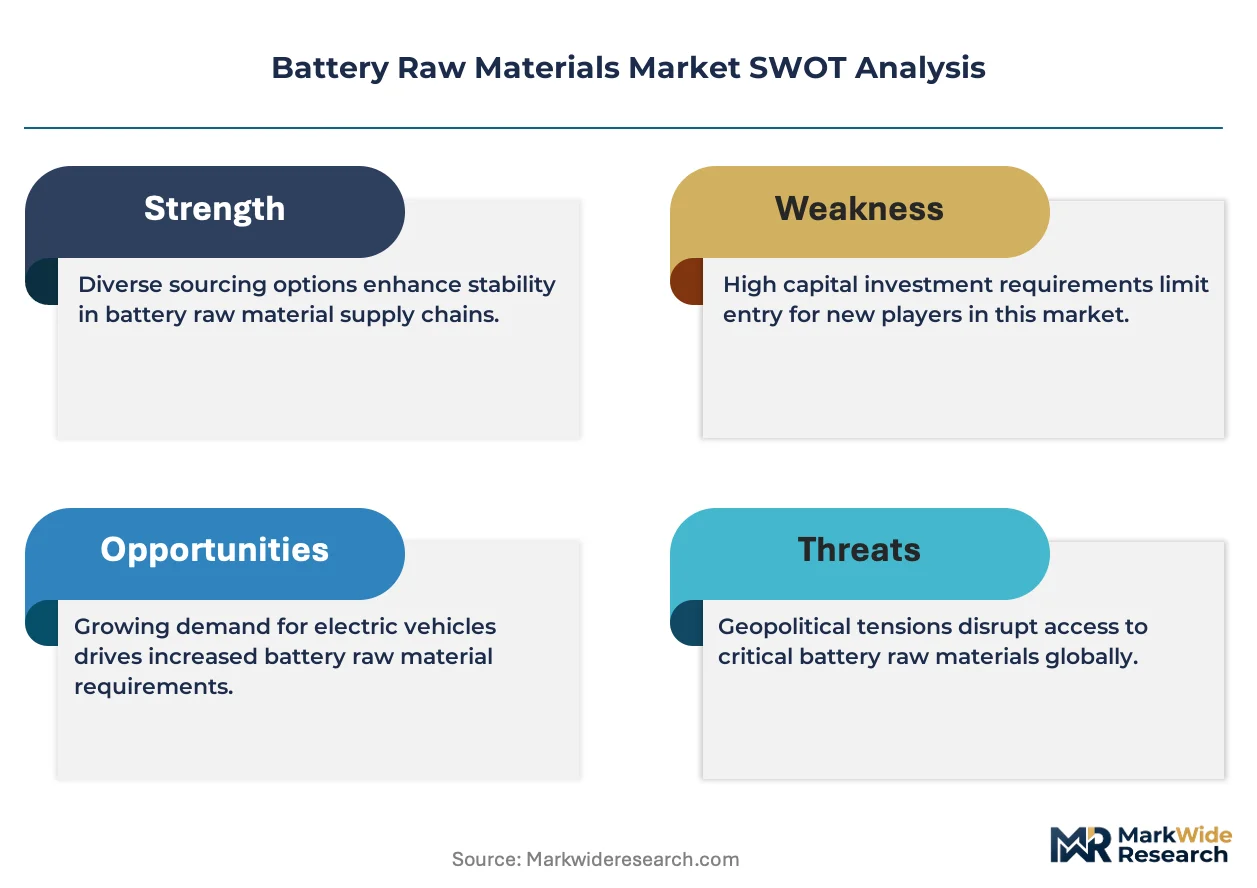
Battery raw materials encompass the refined metals, minerals, and chemical precursors—lithium carbonate or hydroxide, cobalt sulfate, nickel sulfate, and spheronized graphite—that constitute cathodes, anodes, electrolytes, and separators in rechargeable cells, typically requiring purity thresholds above 99.5% for battery-grade qualification and serving as the foundational feedstock for electrochemical energy storage systems. Lithium retains the largest value pool among material types due to irreplaceable ionic conductivity in high-density cells, while nickel commands the fastest growth trajectory as NCM and NCA cathode formulations push toward higher nickel ratios to reduce cobalt dependency. Electric Vehicles dominate application-level demand by absorbing the majority of mined lithium and refined nickel output, whereas Energy Storage represents the emerging margin segment as grid-scale battery deployments accelerate.
The EU Battery Regulation and REACH framework impose due diligence, recycled content mandates, and carbon footprint thresholds on material placed within the European market. China's MIIT and GB standards enforce domestic battery-grade purity specifications and capacity utilization benchmarks that shape global supply qualification. The US IRA provides production tax credits contingent on North American or free-trade-agreement sourcing, redirecting investment toward compliant jurisdictions. Stakeholders must monitor evolving regulatory fragmentation between carbon-accounting regimes and critical mineral security designations to align procurement geography with compliance exposure.
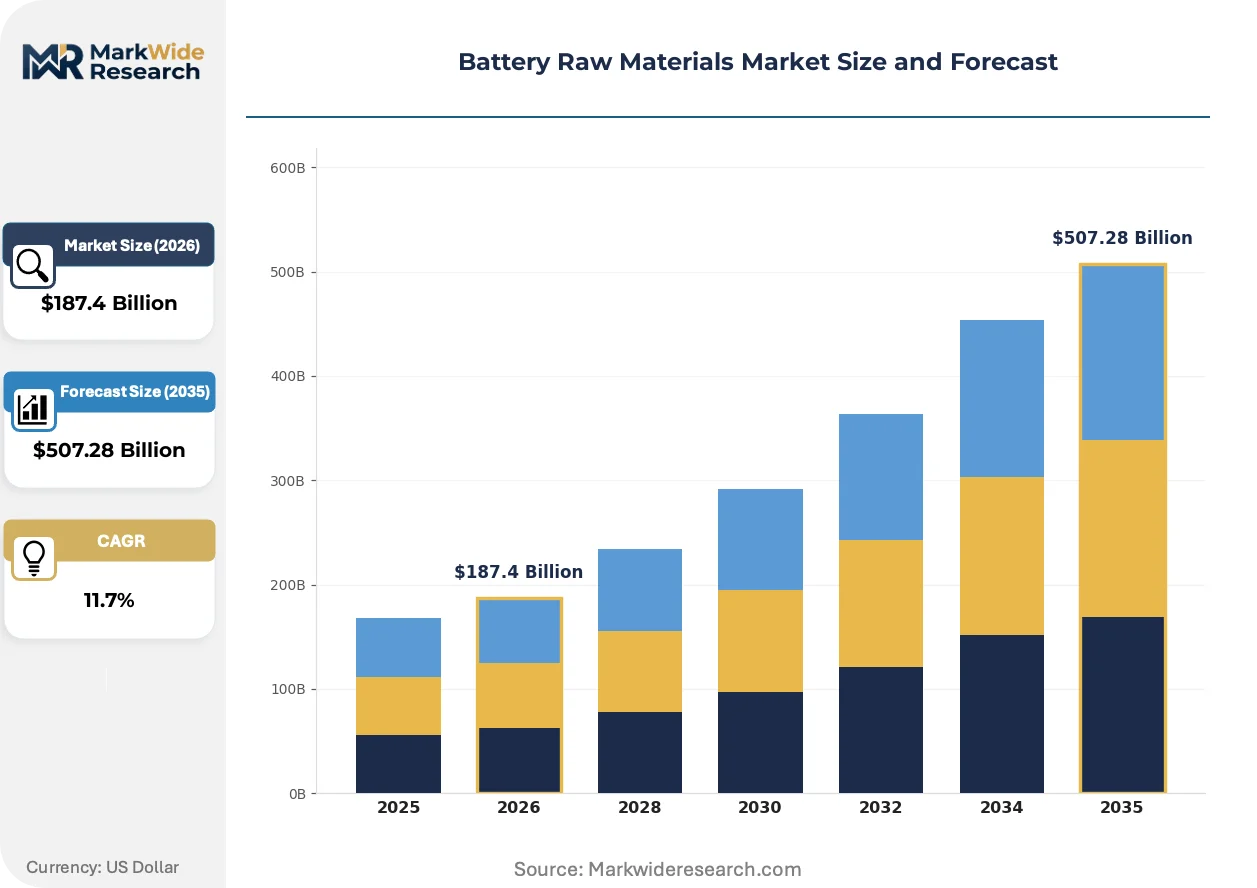
Market Dynamics
Electric vehicle OEMs are consolidating cathode precursor procurement around integrated refiners capable of delivering carbon-accounted nickel sulfate and lithium hydroxide, compressing the supplier base while elevating purity and traceability requirements above 99.5% battery-grade thresholds.
Growth Catalysts
- EU Battery Regulation recycled content mandates:The framework requires minimum recycled lithium, cobalt, and nickel in batteries placed on the European market, compelling refiners to invest in closed-loop hydrometallurgical recovery infrastructure.
- NCM 811 and 9.5.5 cathode chemistry migration:Automakers are specifying higher nickel ratios to reduce cobalt dependency, pulling demand toward Class 1 nickel briquettes and away from stainless steel feedstock.
- Chile and Argentina brine expansion:Salar operators are commissioning direct shipping ore and on-site conversion plants, shortening the lithium carbonate supply chain for Asian cathode manufacturers.
Market Restraints
- DRC cobalt concentration:Over seventy percent of mined cobalt originates from artisanal and industrial sources in the Democratic Republic of Congo, exposing supply chains to ESG audit failures and offtake suspension risk.
- Sulfuric acid and reagent cost volatility:Heap leaching and solvent extraction operations for nickel laterite processing face margin compression when sulfur and ammonia prices spike, particularly affecting HPAL projects in Indonesia.
- Lithium-ion solid-state substitution timeline:Sulfide and oxide solid electrolyte chemistries may eventually displace liquid electrolyte architectures, threatening long-term demand for carbonate solvents and separator materials.
Strategic Opportunities
- US IRA production tax credits:The Inflation Reduction Act's critical mineral and battery component credits are redirecting refinery investment toward North American and free-trade-agreement jurisdictions, particularly Quebec and Ontario.
- Grid-scale energy storage procurement:Utility IPPs are issuing ten-year lithium iron phosphate offtake contracts, creating a secondary demand anchor distinct from automotive qualification cycles.
- Direct lithium extraction from geothermal brines:Salton Sea and Upper Rhine Valley projects are piloting selective adsorption and electrochemical separation, potentially eliminating evaporation pond footprints and accelerating project timelines.
Industry Challenges
- Battery-grade purity certification timelines:Cathode precursor qualification with Chinese MIIT and Korean KATS standards requires eighteen to twenty-four months of continuous production samples, delaying revenue recognition for new entrants.
- HPAL construction and commissioning complexity:High-pressure acid leach facilities for nickel laterite processing face cost overruns and ramp failures due to titanium autoclave welding defects and acid handling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Raw Materials Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium, Cobalt, Nickel, Graphite Application: Electric Vehicles, Consumer Electronics, Energy Storage, Power Tools End User: Automotive, Electronics Manufacturers, Renewable Energy Sector, Industrial Equipment Source: Mining, Recycling, Synthetic Production, Others |
| Companies Covered | Umicore, Asahi Kasei Corporation, BASF SE, Johnson Matthey, Sumitomo Chemical Co., Ltd., Mitsubishi Chemical Corporation, POSCO Future M, Sumitomo Metal Mining Co., Ltd., Albemarle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Raw Materials Market Emerging Trajectories
Digital traceability platforms and electrochemical processing advances are compressing qualification timelines while regulatory carbon-accounting frameworks are rewriting procurement geography for cathode active materials.
Artificial intelligence-driven mineral sorting and sensor-based ore classification is digitizing upstream lithium and nickel operations. Hard-rock spodumene producers in Western Australia are deploying X-ray transmission and laser-induced breakdown spectroscopy to upgrade run-of-mine feed before milling, cutting energy intensity per ton of lithium carbonate equivalent. This technology is digitizing grade control decisions, enabling real-time blending to smelter specifications and reducing downstream reprocessing costs.
REACH and the EU Battery Regulation's carbon footprint declaration requirements are forcing importers to deploy lifecycle assessment software and third-party verification. Battery manufacturers placing products in Germany, France, and the Netherlands must now document kg CO2 equivalent per kWh across mining, refining, and active material production. European automotive OEMs are responding by dual-sourcing from Canadian and Australian jurisdictions with lower grid carbon intensity, shifting contract volumes away from coal-dependent refining hubs.
Long-term offtake contracting is displacing spot market purchasing for lithium hydroxide and nickel sulfate. Korean and Japanese cathode producers are locking in five to seven-year supply agreements with embedded price collars and volume flex provisions, transferring price risk to integrated miners while securing qualification continuity. This pattern is most visible in binding precedents between Australian spodumene concentrators and Chinese lithium conversion facilities, where take-or-pay structures now dominate investment-grade project finance.
Battery Raw Materials Market Segmentation
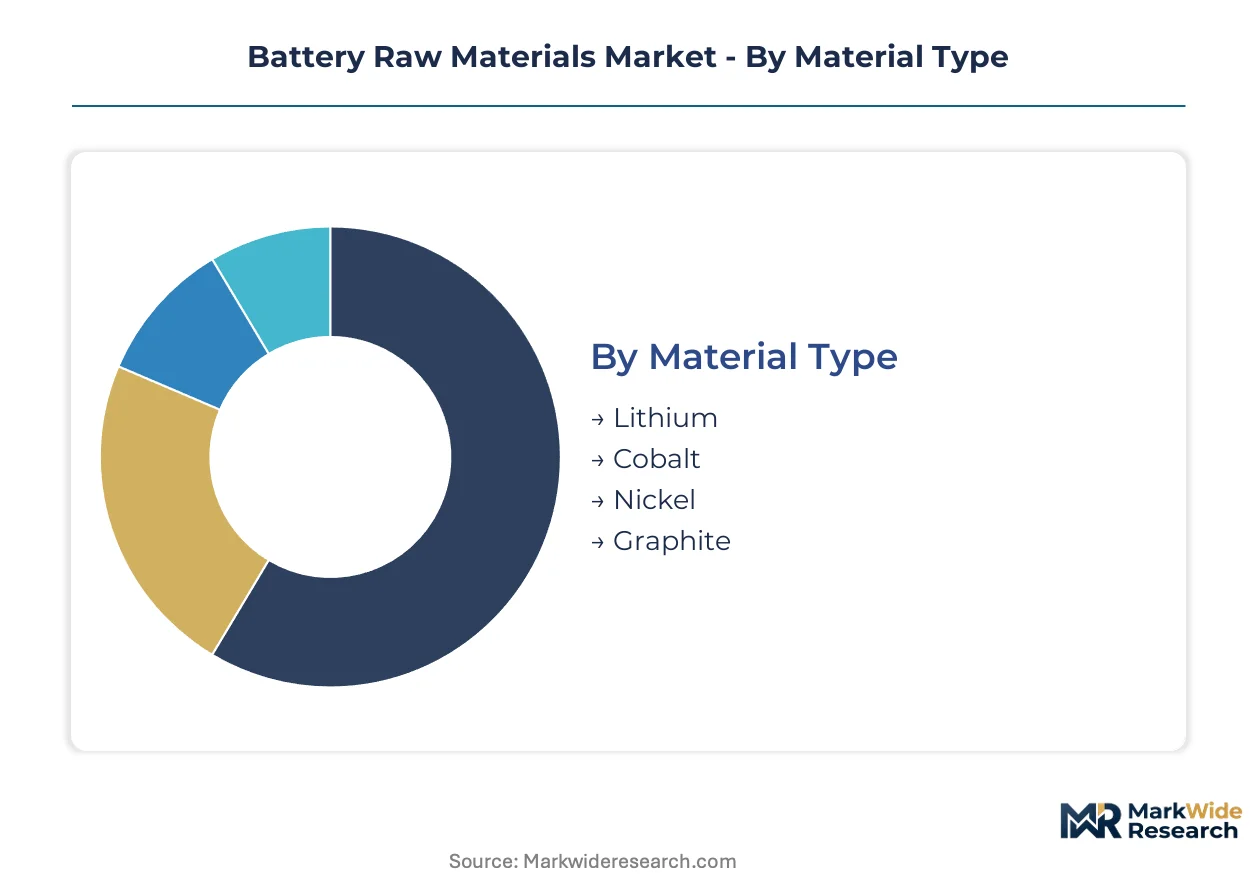
Segmentation in battery raw materials determines procurement geography, purity specifications, and contract structuring. Cathode precursor buyers source differently by material chemistry, while end-use qualification cycles vary dramatically between automotive and grid storage applications.
Material Type:
Mature extraction methods dominate lithium and nickel, while cobalt and graphite face emerging supply concentration pressures.
- Lithium:Brine evaporation from South American salars and hard-rock spodumene crushing in Western Australia supply battery-grade carbonate and hydroxide. Chinese conversion facilities in Sichuan and Jiangxi process the majority of global feedstock, with automakers now demanding direct shipping ore to shorten supply chains.
- Nickel:Class 1 briquettes and nickel sulfate derived from laterite HPAL processing in Indonesia and matte refining in Canada feed NCM cathode production. Korean cathode makers are locking in offtake from integrated Indonesian operations to secure volumes for high-nickel chemistries.
- Cobalt:DRC artisanal and industrial mining feeds hydroxide refining in China and Finland, with ESG audit requirements tightening qualification.
- Graphite:Spheronized natural flake from Mozambique and Madagascar and synthetic production from petroleum coke in China constitute anode material supply.
Lithium handles the majority of throughput; nickel is gaining share fastest as cathode formulations push toward higher ratios.
Application:
Volume concentration and margin structure diverge sharply across end-use segments.
- Electric Vehicles:Automotive OEMs absorb the majority of lithium hydroxide and nickel sulfate output, with binding offtake agreements now spanning five to seven years. Cell qualification with individual OEMs requires eighteen to twenty-four months of continuous production samples, elevating supplier switching costs.
- Energy Storage:Utility-scale lithium iron phosphate deployments are creating a secondary demand anchor with distinct procurement cycles. Ten-year offtake contracts from independent power producers are emerging, separate from automotive qualification requirements.
- Consumer Electronics:Cobalt-dense LCO cathodes for smartphones and laptops draw from established supply chains with shorter contract horizons.
- Power Tools:Cylindrical cell formats for cordless equipment source blended cathode materials with less stringent traceability requirements.
Electric Vehicles command the dominant share of qualified volumes; Energy Storage is climbing the fastest on contract issuance.
End User:
Procurement sophistication and compliance exposure vary by customer type.
- Automotive:OEMs are consolidating supplier bases around integrated refiners capable of carbon-accounted nickel sulfate and lithium hydroxide. EU Battery Regulation compliance now requires recycled content documentation and lifecycle carbon declarations.
- Electronics Manufacturers:Consumer device makers prioritize cobalt supply security with less emphasis on carbon footprint accounting compared to automotive buyers.
- Renewable Energy Sector:Utility IPPs and storage developers are issuing long-duration offtake contracts for lithium iron phosphate systems, with procurement teams less experienced in battery-grade material qualification.
- Industrial Equipment:Forklift and stationary power applications source from secondary material streams with relaxed purity thresholds.
Automotive directs the largest qualified volumes; Renewable Energy Sector is expanding most quickly on new contract formation.
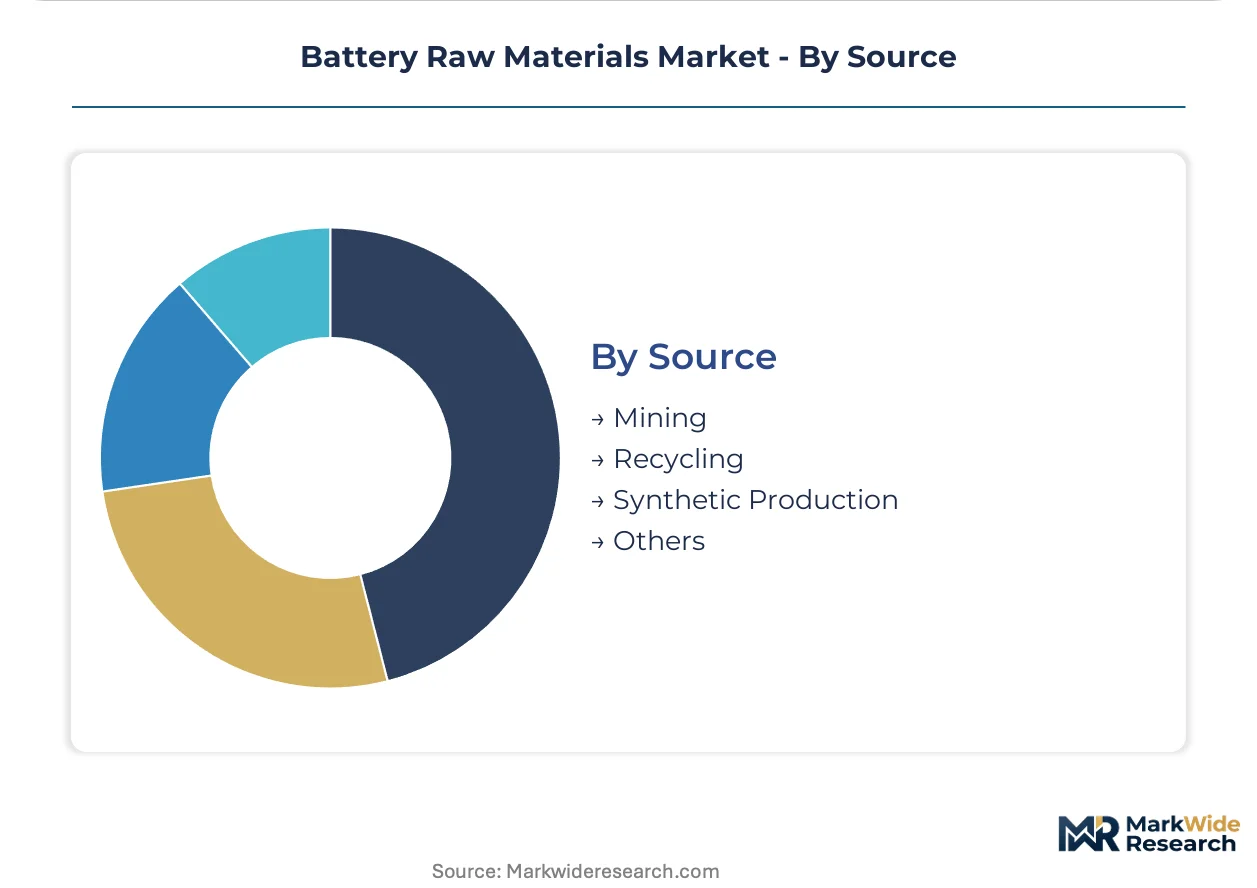
Source:
Primary extraction still dominates, but regulatory mandates are accelerating recycling infrastructure.
- Mining:Hard-rock and brine operations in Australia, Chile, and Argentina remain the foundation for lithium, with Indonesian laterite and DRC cobalt completing the primary supply base.
- Recycling:Closed-loop hydrometallurgical recovery is scaling in Germany, Canada, and China to meet EU Battery Regulation recycled content minimums. Black mass processing and direct cathode regeneration are competing technical routes.
- Synthetic Production:Petroleum coke graphitization in Inner Mongolia and Shandong supplies anode material with controlled purity specifications.
- Others:Direct lithium extraction from geothermal brines in the Salton Sea and Upper Rhine Valley represents pre-commercial supply potential.
Mining underpins the majority of current supply; Recycling is accelerating fastest on regulatory pull.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's critical mineral provisions are redirecting refinery investment toward North American jurisdictions with compliant sourcing requirements. Battery-grade material demand concentrates in jurisdictions with integrated cathode precursor capacity and favorable regulatory treatment.
China
Jiangxi and Sichuan provinces process the majority of global lithium feedstock through integrated conversion facilities serving Korean and Japanese cathode makers. MIIT battery-grade purity specifications enforce continuous production sampling protocols that extend qualification timelines. The Yangtze River Delta anchors NCM precursor output with direct pipeline connections to cell assembly plants.
United States
IRA production tax credits are pulling refinery investment toward Quebec and Ontario to satisfy North American content thresholds. The Salton Sea geothermal corridor hosts direct lithium extraction pilots targeting selective adsorption scale-up. Nevada's Clayton Valley brine operations supply domestic carbonate requirements for western cell manufacturing.
Germany
EU Battery Regulation recycled content mandates are accelerating closed-loop hydrometallurgical recovery infrastructure in Saxony and North Rhine-Westphalia. ECHA REACH compliance requires kg CO2 equivalent documentation per kWh across material supply chains. The country's national automotive regulator enforces due diligence audits on cobalt and nickel sourcing.
Indonesia
HPAL processing corridors in Sulawesi and Halmahera are commissioning Class 1 nickel sulfate output for NCM 811 cathode formulations. The country's national mining regulator oversees export restrictions on unprocessed laterite ore. Morowali Industrial Park integrates nickel matte refining with precursor manufacturing for Korean offtake partners.
Australia
Western Australian spodumene concentrators in the Pilbara and Goldfields regions supply direct shipping ore to Chinese conversion facilities. The country's national resources regulator monitors tailings management for hard-rock lithium operations. Greenbushes and Wodgina anchor global hard-rock lithium supply with take-or-pay contract structures dominating project finance.
Battery Raw Materials Market Vendor Landscape
Channel-controlling players compete with product-specialist players across cathode precursor, lithium conversion, and nickel refining segments. The supplier base compresses around integrated refiners capable of carbon-accounted material qualification. Three archetypes dominate: South American brine operators with captive carbonate output, Korean-Japanese integrated precursors with locked-in offtake, and European recyclers with hydrometallurgical recovery infrastructure. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs consolidate procurement around fewer qualified suppliers.
Among South American brine operators, Albemarle exemplifies the integrated lithium carbonate archetype with salar-based extraction dominance. POSCO Future M and Sumitomo Metal Mining Co., Ltd. anchor the Asian integrated precursor tier, representing Korean and Japanese cathode supply security strategies respectively. These three occupy positions spanning extraction through active material qualification.
| Leading Market Players |
|---|
| Umicore |
| Asahi Kasei Corporation |
| BASF SE |
| Johnson Matthey |
| Sumitomo Chemical Co., Ltd. |
| Mitsubishi Chemical Corporation |
| POSCO Future M |
| Sumitomo Metal Mining Co., Ltd. |
| Albemarle |
| Others |
Supply Flow & Price Mechanics
Chilean and Argentine brine concentration anchors upstream lithium carbonate supply, compressing margin capture downstream into Chinese conversion facilities and Korean cathode precursor operations. Battery-grade material premiums flow to integrated refiners capable of MIIT qualification and carbon-accounted output, while spot market exposure concentrates in unqualified converter tiers.
Pricing Analysis
Battery-grade purity certification creates the primary spread between qualified and unqualified material tiers. Long-term offtake contracting dominates pricing structures, with Korean and Japanese cathode producers embedding five to seven-year price collars and volume flex provisions. Cost compression in conversion tiers intensifies because sulfuric acid and reagent volatility erodes heap leaching margins, particularly affecting Indonesian HPAL projects. Automotive OEMs exhibit the least price sensitivity due to qualification switching costs, while utility-scale energy storage developers negotiate aggressively on lithium iron phosphate feedstock.
Supply Chain Analysis
Tariff exposure between Indonesia and North American jurisdictions dominates supply chain risk calculations under IRA compliance thresholds. Raw material extraction concentrates in Australia, Chile, and the Democratic Republic of Congo, with Chinese conversion facilities processing the majority of lithium and cobalt intermediates. Feedstock dependencies rest on spodumene concentrate, laterite ore, and artisanal cobalt hydroxide. Distribution runs through integrated precursor manufacturers in the Yangtze River Delta and Morowali Industrial Park before cell assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery raw materials are exiting a supply-investment trough as electric vehicle procurement cycles tighten and regulatory mandates accelerate qualified capacity builds. Lithium carbonate price volatility and cathode chemistry migration constitute the cyclical recovery drivers.
For Market Incumbents: Pre-empt solid-state electrolyte substitution risk by locking NCM 811 and 9.5.5 chemistry offtake through 2030. Secure backward integration into Indonesian HPAL corridors or South American brine expansions to defend margin pools against Chinese converter consolidation. Invest in closed-loop hydrometallurgical recovery infrastructure to satisfy EU Battery Regulation recycled content minimums before qualification deadlines tighten.
For New Entrants and Emerging Players: North American direct lithium extraction from geothermal brines offers the most penetrable white-space target, with Salton Sea and Upper Rhine Valley projects advancing selective adsorption pilots. Utility-scale energy storage procurement cycles run shorter than automotive qualification, enabling faster revenue recognition for lithium iron phosphate suppliers. Target grid-scale IPP offtake with ten-year contract structures distinct from OEM qualification requirements.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Australian spodumene concentrators seeking exit liquidity as take-or-pay contract structures mature. Five-to-ten-year viability hinges on carbon-accounted output and FTA-compliant sourcing for IRA eligibility. Monitor EU Battery Regulation enforcement actions as the inflection signal for recycled content infrastructure valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Korean cathode makers lock Indonesian HPAL output for NCM 811 chemistry security. |
| Backward Integration | Automotive OEMs acquire stakes in South American brine operations to secure carbonate supply. |
| Green Manufacturing Transition | Canadian and Australian refiners leverage low-carbon grids for EU Battery Regulation compliance. |
| Capacity Expansion | Indonesian HPAL corridors commission Class 1 nickel sulfate for high-nickel cathode demand. |
| Joint Venture | Geothermal brine operators partner with selective adsorption technology providers to accelerate DLE scale-up. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cathode precursor procurement directors, lithium conversion plant managers, HPAL project developers, and utility-scale energy storage procurement leads. Secondary validation drew from MIIT battery-grade purity filings, ECHA REACH carbon footprint declarations, US IRA critical mineral guidance, and customs trade data for spodumene concentrate and nickel laterite flows. Bottom-up project pipeline assessments were triangulated against top-down electric vehicle production forecasts across the analysis window.
Calibration against historical capacity utilization rates and offtake contract formation patterns shaped the projection framework. Segmentation modeling spanned material chemistry, application end-use, and regional regulatory cluster dimensions. CAGRs were derived from supply-demand balance analysis incorporating cathode formulation migration timelines and recycled content mandate implementation schedules. Direct lithium extraction commercialization curves and solid-state battery substitution scenarios served as industry-specific sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in electric vehicle penetration rates, battery pack cost curves, or critical mineral trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding HPAL project commissioning timelines, brine expansion permitting velocity, and EU Battery Regulation enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market