
 Europe Solar Charging Station Market | 2026-2036
Europe Solar Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Solar Charging Station Market Analytics
Market Context
The EU Green Deal is hardening emission reduction mandates across European transport infrastructure, compelling fleet operators and municipal utilities to source renewable-powered charging assets. ABB leverages its electrification software stack to anchor large-scale solar-integrated deployments across Nordic utility networks. Siemens competes through grid-edge hardware that synchronizes photovoltaic generation with high-capacity vehicle charging protocols. EVBox sustains market presence via modular hardware architectures that simplify on-street and commercial installations.
Technical Definition and Segment Structure
A solar charging station combines photovoltaic panels, inverters, and charge controllers to convert incident solar radiation into direct-current or alternating-current output suitable for electric vehicle battery replenishment, typically operating at power levels from 3.7 kW residential units to 350 kW fast-charging terminals for commercial depot use. Fast Charger installations command premium margin pools due to higher capital intensity and specialized grid interconnection requirements, while Battery Storage integration is accelerating as station operators seek to buffer intermittency and reduce demand-charge exposure. Residential deployment remains mature with slower growth, whereas Fleet-oriented installations represent the fastest-expanding end-user category as logistics operators electrify last-mile and regional haul operations.
Regulatory Framework and Outlook
The EU Green Deal, REACH chemical compliance for photovoltaic component sourcing, and CE marking for electrical safety collectively shape product standards and market access conditions across member states. Germany's KBA enforces type-approval protocols for grid-connected charging hardware, while France's ANSM-relevant energy regulators influence distributed generation interconnection rules that affect station economics. Stakeholders must monitor evolving F-Gas Regulation impacts on inverter cooling systems and anticipate how the EU AI Act could reshape predictive load-management algorithms embedded in charging network software.
Market Dynamics
Fleet electrification mandates under the EU Green Deal are compressing deployment timelines for photovoltaic-integrated charging infrastructure, forcing municipal utilities and logistics operators to synchronize procurement with renewable generation assets.
Growth Catalysts
- France's ANSM-influenced energy interconnection rules:Distributed generation frameworks are accelerating grid-access approvals for commercial depot installations, reducing permitting friction for fleet operators.
- Last-mile logistics electrification:Parcel carriers and urban freight operators are mandating renewable-powered depot charging to meet Scope 3 emission reduction targets.
- Germany's KBA type-approval protocols:Standardized certification for grid-connected hardware is reducing technical barriers to cross-border equipment deployment.
Market Restraints
- Polysilicon supply concentration:Photovoltaic module production relies on concentrated upstream refining capacity, exposing project developers to input cost volatility and supply disruption risks.
- F-Gas Regulation compliance costs:Inverter cooling system redesign requirements are adding capital intensity to high-capacity charging hardware manufacturing.
- Grid interconnection queuing:Utility-scale solar charging depots face extended timeline uncertainty from distribution network operators in congested industrial corridors.
Strategic Opportunities
- Poland's emerging fleet electrification corridor:Underpenetrated commercial vehicle charging infrastructure presents first-mover positioning for integrated solar-battery systems.
- Vehicle-to-grid protocol convergence:Bidirectional charging standards are unlocking new revenue streams from grid services and peak demand management.
- Spain's renewable energy auction mechanisms:Allocation rules favoring distributed generation are creating procurement tailwinds for solar-integrated transport infrastructure.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized inverter and charge controller design expertise is concentrated among a limited pool of experienced practitioners, constraining product development velocity.
- CE marking timeline compression:Evolving electrical safety and electromagnetic compatibility standards are extending certification cycles for new hardware platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Solar Charging Station Market |
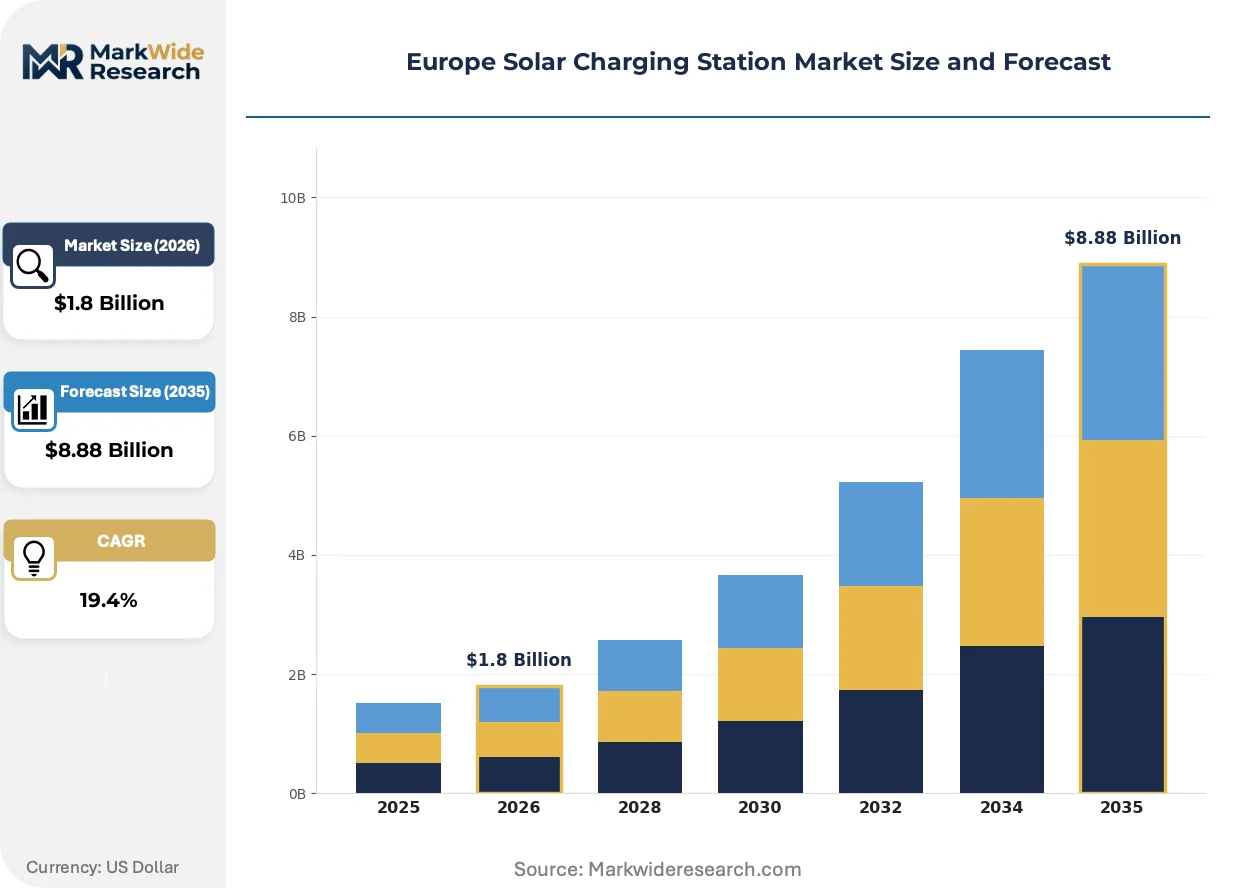
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1, Level 2, Fast Charger, Portable Charger Technology: Photovoltaic Panels, Inverters, Charge Controllers, Battery Storage Installation: Residential, Commercial, Public, On-Street End User: Private Vehicles, Fleets, Electric Buses, Taxi Services |
| Companies Covered | ABB, EVBox, Siemens, Schneider Electric, Webasto, EFACEC, Allego, Shell Recharge, KEBA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Solar Charging Station Market Evolving Landscape
Integrated battery storage is fundamentally altering station economics by buffering photovoltaic intermittency and enabling demand-charge arbitrage for commercial operators.
Solid-state inverter architectures are overtaking conventional silicon-based designs in high-capacity charging applications. German industrial fleet operators are specifying these systems for new depot installations to achieve higher conversion efficiency and reduced thermal management footprint. This technology shift is compressing maintenance cost structures and extending equipment replacement cycles for station owners.
The EU AI Act is imposing algorithmic transparency requirements on predictive load-management software embedded in charging network control systems. Station operators must now document decision logic for grid-interaction protocols and demand forecasting models. French utility networks are most exposed given their early deployment of machine-learning-based charging optimization platforms.
Asset-light service contracts are displacing capital purchase models for municipal fleet charging infrastructure. Dutch and Belgian transit authorities are procuring charging-as-a-service arrangements that transfer ownership and performance risk to specialized operators. This shift concentrates purchasing influence among integrated service providers and reduces equipment vendor direct sales opportunities.
Europe Solar Charging Station Market Segmentation
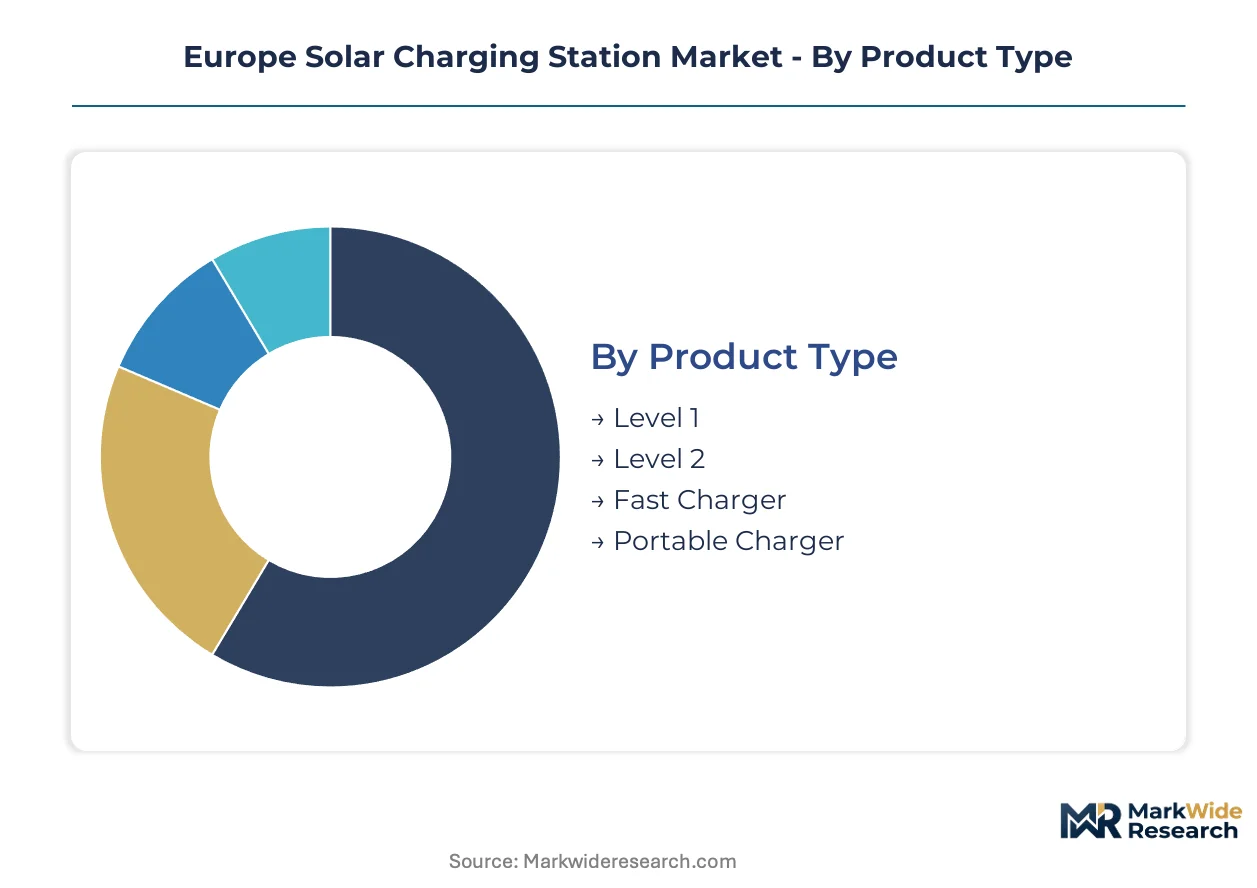
Segmentation in the Europe Solar Charging Station Market reveals how technology choices, installation contexts, and end-use requirements fragment procurement patterns across the region. Understanding these divisions helps suppliers align product portfolios with the divergent economics of depot-scale fleet infrastructure versus distributed public charging networks.
Product Type:
Supply concentration in power electronics manufacturing shapes competitive dynamics across charging hardware tiers, with specialized semiconductor foundries limiting production scalability for high-capacity units.
- Level 1:These 3.7 kW alternating-current units rely on standard residential electrical infrastructure without dedicated grid upgrades. German single-family housing stock and rural French municipalities absorb most installations, constrained by slow replenishment speeds that limit commercial viability.
- Level 2:Operating at 7-22 kW, these systems dominate workplace and multi-unit dwelling deployments across the Netherlands and Belgium. Parking structure operators in Rotterdam and Antwerp specify these units for employee and tenant charging, balancing capital cost against throughput requirements.
- Fast Charger:High-power direct-current terminals from 50-350 kW serve commercial depot and highway corridor applications.
- Portable Charger:Mobile units with integrated photovoltaic arrays target emergency and off-grid use cases.
Fast Charger installations absorb the bulk of installed capacity; Portable Charger applications are expanding most quickly among disaster response and remote construction fleets.
Technology:
Cost tier differentiation separates mature photovoltaic components from emerging battery integration architectures that command premium positioning in commercial deployments.
- Photovoltaic Panels:Monocrystalline silicon modules with 20-22% conversion efficiency anchor station economics. Spanish and Italian project developers favor these panels for high-irradiance locations, though polysilicon supply bottlenecks constrain procurement timelines.
- Inverters:Power conversion hardware transforms direct-current panel output to grid-synchronous alternating current. Nordic utility networks specify transformerless designs for reduced footprint, while German industrial operators demand galvanic isolation for fault protection.
- Charge Controllers:These devices regulate voltage and current flow to protect battery systems from overcharging conditions.
- Battery Storage:Lithium-ion buffer systems enable demand-charge arbitrage and solar generation time-shifting.
Photovoltaic Panels absorb the bulk of installed capacity; Battery Storage integration is climbing the fastest as depot operators seek to buffer intermittency and reduce grid dependency.
Installation:
Application context determines regulatory pathway complexity, with public infrastructure facing extended permitting cycles compared to private commercial deployments.
- Residential:Single-point installations attached to owner-occupied dwellings represent a mature category with slower expansion. Austrian and Swiss alpine municipalities show concentrated deployment where grid extension costs favor distributed generation.
- Commercial:Fleet depot and workplace charging infrastructure is gaining share fastest across Germany's industrial corridor. Logistics operators in the Ruhr region and Stuttgart metropolitan area anchor procurement volume for integrated solar-battery systems.
- Public:Municipal-owned charging plazas and highway service station deployments serve general vehicle access.
- On-Street:Curbside installations integrate photovoltaic canopies with urban furniture constraints.
Commercial installations absorb the bulk of installed capacity; On-Street deployment is expanding most quickly as Paris, Copenhagen, and Barcelona accelerate curbside electrification programs.
End User:
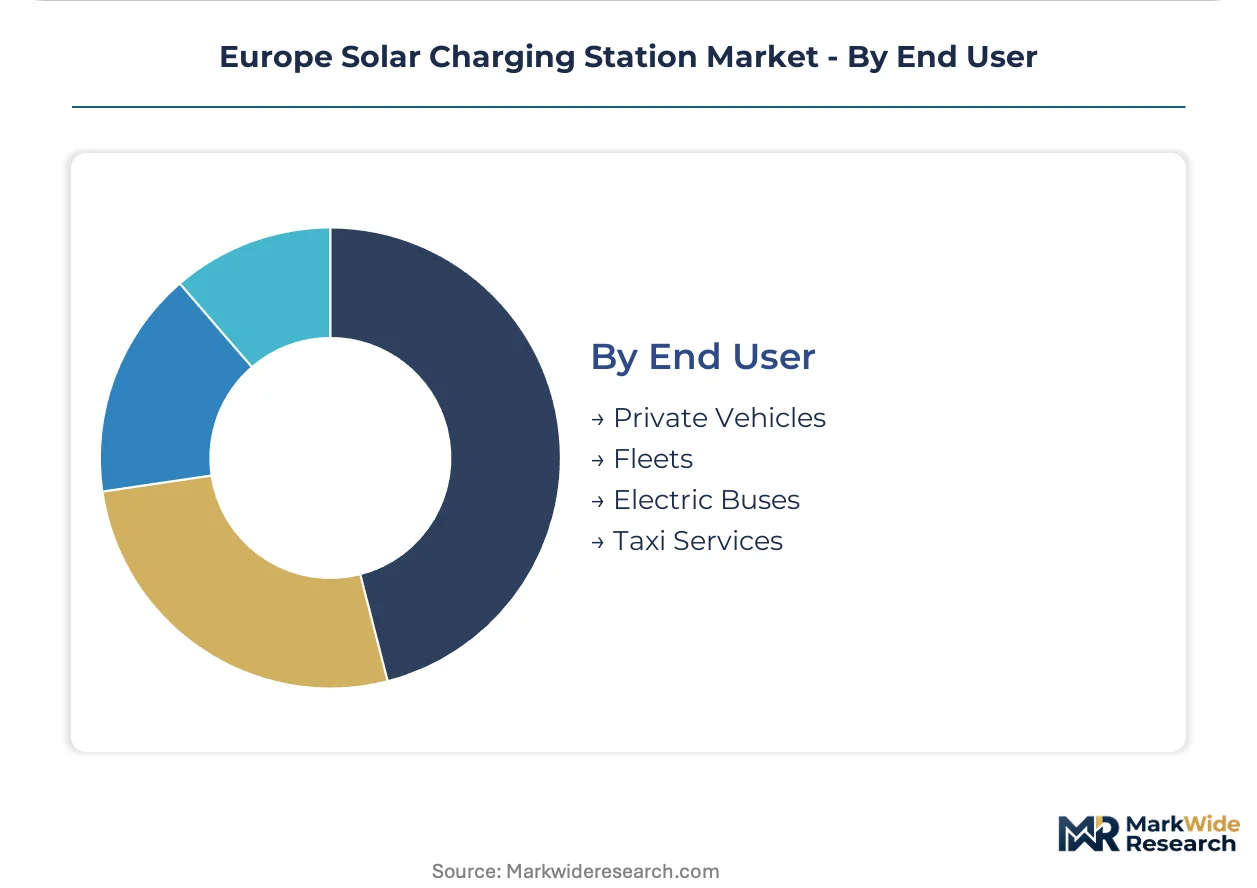
Customer type segmentation separates individual vehicle owners from organized fleet operators with divergent procurement scale and performance requirements.
- Private Vehicles:Individual owner-operators purchase residential and workplace charging access. Italian and Portuguese households with rooftop solar installations show highest attachment rates for co-located vehicle charging.
- Fleets:Commercial logistics and delivery operators command the steepest expansion trajectory. DHL and DPD depot networks across Poland and the Czech Republic are mandating renewable-powered charging to meet corporate emission reduction commitments.
- Electric Buses:Municipal transit authorities specify overnight depot charging with integrated solar generation.
- Taxi Services:Ride-hail and traditional taxi cooperatives procure dedicated charging infrastructure for high-utilization vehicle pools.
Fleet operators absorb the bulk of installed capacity; Electric Bus infrastructure is expanding most quickly as EU Green Deal funding accelerates municipal transit electrification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of photovoltaic modules and power electronics concentrates in Asia, while deployment of solar charging infrastructure clusters in Western European industrial corridors where fleet electrification mandates bite hardest.
Germany
Ruhr Valley logistics operators and Stuttgart metropolitan fleet depots anchor procurement volume for integrated solar-battery systems. The KBA enforces type-approval protocols that standardize grid-connected hardware certification, reducing technical barriers for cross-border equipment deployment. North Rhine-Westphalia's municipal utilities are bundling photovoltaic generation with high-capacity charging terminals for electric bus networks.
France
ANSM-influenced energy interconnection rules are accelerating grid-access approvals for commercial depot installations, cutting permitting friction for parcel carriers. The EU Green Deal's transport decarbonization targets harden procurement mandates for renewable-powered infrastructure. Paris and Lyon metropolitan transit authorities are specifying overnight depot charging with integrated solar generation for electric bus fleets.
Netherlands
Rotterdam and Antwerp parking structure operators specify Level 2 workplace charging units, balancing capital cost against throughput requirements for employee and tenant access. The country's distributed generation auction mechanisms favor solar-integrated transport infrastructure allocation. Dutch transit authorities are procuring charging-as-a-service arrangements that transfer ownership risk to specialized operators.
Spain
High-irradiance locations in Madrid and Barcelona favor monocrystalline silicon module deployments with superior conversion efficiency. Renewable energy auction allocation rules create procurement tailwinds for solar-integrated charging networks. Catalan logistics hubs are mandating renewable-powered depot charging to meet corporate emission reduction commitments.
Poland
Underpenetrated commercial vehicle charging infrastructure presents first-mover positioning for integrated solar-battery systems in Warsaw and Krakow metropolitan areas. DHL and DPD depot networks are mandating renewable-powered charging to meet Scope 3 targets. The emerging fleet electrification corridor is absorbing integrated photovoltaic generation faster than grid interconnection capacity can expand.
Europe Solar Charging Station Market Competitive Landscape
The competitive structure tilts toward industrial electrification conglomerates with embedded software stacks and grid-edge hardware capabilities. Three archetypes dominate: diversified industrial technology groups with power electronics heritage, specialized charging infrastructure pure-plays with modular hardware architectures, and energy majors leveraging retail fuel network conversion. Competitive moves concentrate on strategic partnerships with fleet operators and municipal utilities, plus technology licensing arrangements that accelerate geographic coverage without direct capital deployment.
Among diversified industrial technology groups, ABB and Siemens occupy positions exemplifying the integrated electrification software-hardware stack archetype. EVBox represents the specialized charging infrastructure pure-play model with modular deployment capabilities. These three anchors illustrate how vendor positioning splits between comprehensive industrial system integration and focused charging hardware specialization.
| Leading Market Players |
|---|
| ABB |
| EVBox |
| Siemens |
| Schneider Electric |
| Webasto |
| EFACEC |
| Allego |
| Shell Recharge |
| KEBA |
| Others |
Value Network & Pricing Analysis
Fast charger premium tiers diverge sharply from Level 1 commodity hardware on both cost structure and sourcing geography, with CE-marked grid-synchronous units commanding three-to-five-fold procurement multiples while drawing from German and Nordic power electronics foundries versus Asian residential-grade component suppliers.
Pricing Analysis
Margin tightening in residential Level 1 hardware reflects polysilicon module oversupply and inverter commoditization, while fast charger premiums hold firm due to KBA type-approval scarcity and solid-state inverter engineering talent concentration. Three-tier pricing structure across premium fast-charging depots, standard commercial workplace installations, and economy residential units stratifies procurement. Fleet operators show lowest price sensitivity given EU Green Deal compliance mandates, whereas municipal utilities face acute budget constraints on public infrastructure tenders.
Supply Chain Analysis
Dual-sourcing requirements for photovoltaic inverters and charge controllers now dominate procurement protocols, with fleet operators mandating qualified secondary suppliers to mitigate disruption exposure. Manufacturing concentrates in China for polysilicon refining and module assembly, Germany for power electronics and grid-interconnection hardware, and South Korea for lithium-ion battery cells. Raw material dependencies span high-purity silicon, copper busbar, and rare-earth magnet feedstocks. Single-source vulnerability concentrates in transformerless inverter semiconductor fabrication. Distribution runs through specialized EPC contractors and direct OEM relationships with depot operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's hardening transport decarbonization mandates erect a cost-of-compliance barrier that favors incumbents with pre-qualified hardware and certified software stacks, locking out undercapitalized entrants unable to absorb REACH chemical compliance and F-Gas Regulation redesign cycles.
For Market Incumbents: Lock in fleet operator relationships through charging-as-a-service contract structures that transfer performance risk and capture long-term revenue visibility. Prioritize backward integration into solid-state inverter semiconductor sourcing to defend margin position against polysilicon cost volatility and power electronics foundry bottlenecks. Neutralize emerging pure-play charging specialists by bundling grid-edge hardware with predictive load-management software that satisfies impending EU AI Act algorithmic transparency requirements. For New Entrants and Emerging Players: Begin with Poland's underpenetrated commercial vehicle charging corridor, where grid interconnection queue delays have suppressed incumbent deployment velocity and created first-mover windows for integrated solar-battery depot systems. Target municipal electric bus authorities in secondary French and Spanish metropolitan areas where procurement timelines lag primary cities. Lead with modular hardware architectures that compress CE marking cycles and accelerate field deployment against established competitors. For Investors and Strategic Acquirers: Re-rating potential sits with specialized charging infrastructure pure-plays possessing embedded software stacks and fleet operator contract backlogs, given vehicle-to-grid protocol convergence and bidirectional charging standardization as valuation catalysts. Long-term viability hinges on five-to-ten-year contract duration and regulatory compliance moat sustainability. Monitor F-Gas Regulation implementation timelines as the critical inflection signal for hardware redesign capital requirements and competitive shakeout velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Charging-as-a-Service Contract Expansion | Transfers ownership risk to operators while securing decade-long revenue streams from municipal utilities. |
| Backward Integration into Inverter Semiconductors | Captures margin pool and insulates against Taiwan foundry concentration in power electronics supply. |
| EU AI Act Compliance Investment | Positions predictive load-management software for mandatory algorithmic transparency documentation requirements. |
| Poland Corridor First-Mover Deployment | Exploits grid interconnection bottlenecks that delay incumbent expansion into underpenetrated fleet infrastructure. |
| Vehicle-to-Grid Protocol Certification | Unlocks grid services revenue streams as bidirectional charging standards converge across French and German utility networks. |
Research Methodology
Multi-period observation of fleet electrification procurement volumes, photovoltaic module pricing indices, and grid interconnection queue durations anchored the trend analysis, supplemented by interviews with depot charging infrastructure procurement managers, municipal utility planning officers, power electronics engineering directors, and EPC contractor project leads. Secondary validation drew from EU Green Deal implementation tracking, KBA type-approval registries, ECHA REACH compliance databases, and F-Gas Regulation impact assessments. Bottom-up installation forecasts triangulated against top-down EU transport decarbonization spending allocations.
Segment-weighting across product type, installation context, technology integration level, and end-user procurement scale shaped the analytical framework across the projection horizon. Modeled dimensions included Level 1 through fast charger power tiers, residential through commercial deployment settings, standalone versus battery-integrated system architectures, and private vehicle versus fleet operator demand segments. CAGRs were derived from installation run-rate trajectories, equipment cost curves, and regulatory mandate enforcement timelines. Forecast inputs incorporated polysilicon supply elasticity, inverter semiconductor foundry capacity expansion, and EU AI Act implementation pacing.
Underlying measurement precision varies by segment; fast charger commercial deployments carry tighter precision than nascent portable charger emergency applications due to established procurement reporting channels. Forecasts reflect documented assumptions regarding EU Green Deal funding continuity, F-Gas Regulation compliance cost pass-through, and grid interconnection approval velocity. Deviation in REACH chemical compliance enforcement or polysilicon supply disruption severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Smart Solar Solutions Market
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
Global Dye-Sensitized Solar Cells (Dssc) Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Spain Solar Energy Market
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Bifacial Solar Cells Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
Indonesia Renewable Energy Market