
 India Battery Market | 2026-2036
India Battery Market Size, Share, and Industry Trends Forecast 2026-2036
India Battery Market Outlook
Modular battery pack architectures is recalibrating buyer choice across automotive and stationary storage segments in India. Exide Industries Ltd leverages its lead-acid manufacturing scale to defend commercial vehicle aftermarket positions. Amara Raja Energy & Mobility Limited anchors its expansion through lithium-ion cell assembly partnerships and energy storage system integration. Tata AutoComp GY Batteries Pvt. Ltd. competes on captive supply relationships within the Tata Group's electric mobility ecosystem.
A battery is an electrochemical device comprising cathode, anode, electrolyte, and separator that converts stored chemical energy into electrical energy through reversible redox reactions, with energy density ranging from 30-50 Wh/kg for lead-acid to 150-300 Wh/kg for lithium-ion variants. Its primary purpose is to provide portable, rechargeable power for transportation, grid stabilization, and uninterruptible backup systems. Lithium-ion chemistry leads product type dynamics due to falling cell costs and electric vehicle mandates, while lead-acid retains margin pools in automotive starter and telecom tower applications. Energy storage systems application is expanding fastest as state distribution companies procure grid-scale batteries for renewable integration under central government tenders.
BIS certification requirements and the PLI scheme for advanced chemistry cells are tightening product standards while subsidizing domestic manufacturing capacity. CEA technical standards for grid-connected battery storage and state-level electric vehicle policies in Maharashtra, Delhi, and Karnataka are fragmenting procurement specifications across jurisdictions. Stakeholders must monitor tariff rationalization for battery swapping versus charging infrastructure, as this policy divergence will determine capital allocation between asset-light and asset-heavy business models.
Market Dynamics
India's PLI scheme for advanced chemistry cells is compressing import dependency by subsidizing domestic gigafactory construction, while state-level electric vehicle mandates in Maharashtra and Delhi are fragmenting procurement specifications across jurisdictions.
Growth Catalysts
- FAME-II subsidy framework:Central government outlays for electric two-wheelers and commercial fleets are pulling forward lithium-ion pack demand from fleet operators and last-mile logistics providers.
- Gujarat-Tamil Nadu industrial corridor clustering:Port-linked battery manufacturing zones are concentrating cathode active material processing and cell assembly within 200 kilometers of Mundra and Ennore ports.
- Renewable purchase obligations:State distribution companies must procure grid-scale storage for solar-wind integration, opening procurement pipelines for containerized lithium-ion systems.
Market Restraints
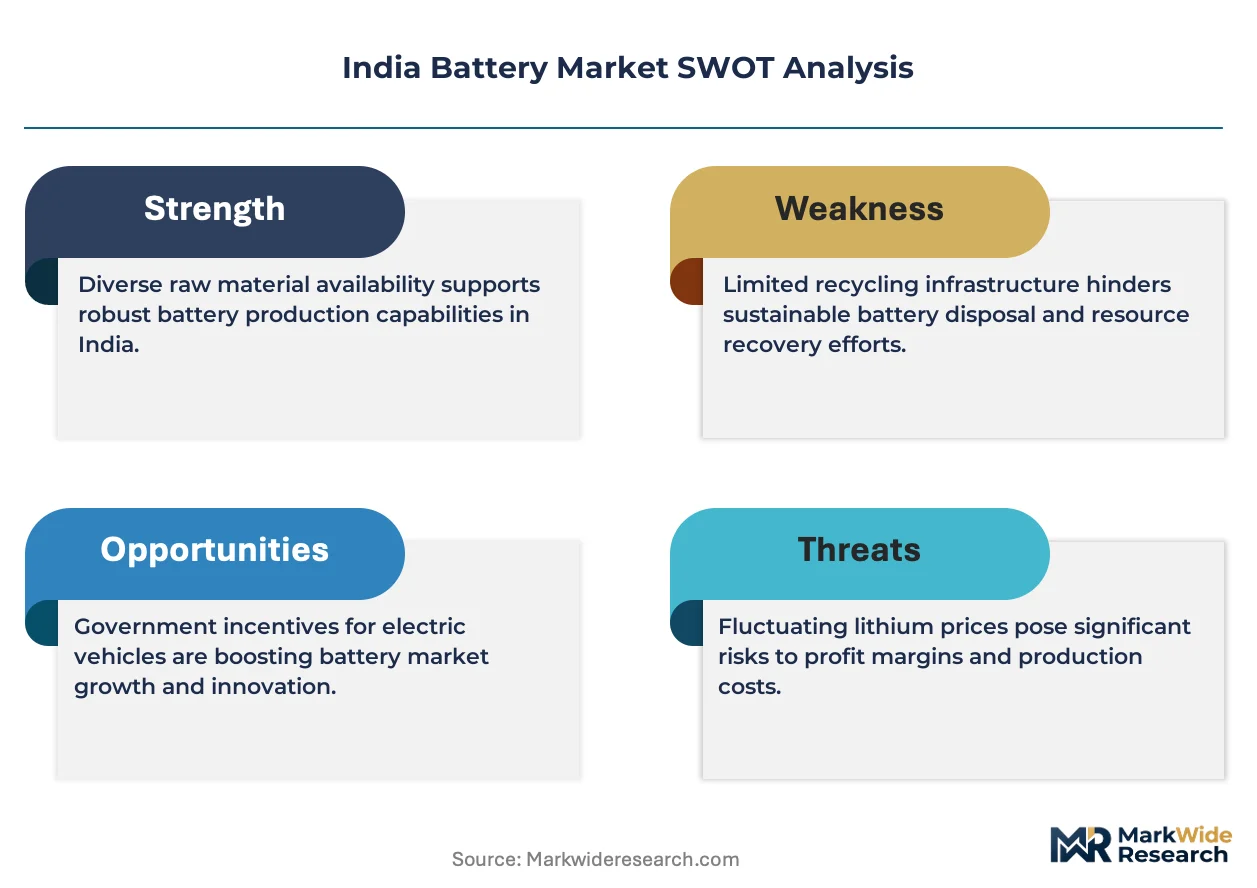
- Lithium carbonate import concentration:Over 90 percent of cell-grade lithium feedstock arrives through Chinese refiners, exposing pack assemblers to currency and tariff volatility.
- BIS certification timelines:Bureau of Indian Standards testing protocols for lithium-ion cells stretch 12-18 months, delaying product launches for domestic manufacturers.
- Lead-acid substitution ceiling:Automotive starter battery replacement cycles and telecom tower backup applications retain cost advantages that lithium-ion cannot undercut below 50 Ah capacities.
Strategic Opportunities
- Battery-as-a-service models:Swapping infrastructure operators in Delhi and Bengaluru are decoupling asset ownership from energy access, lowering fleet operator capex barriers.
- Sodium-ion chemistry convergence:Hard carbon anode and Prussian blue cathode combinations promise thermal stability for stationary storage without lithium supply chain exposure.
- Rural microgrid deployment:Unelectrified hamlets in Bihar and Uttar Pradesh represent unserved demand for solar-plus-storage kits below 5 kWh capacity.
Industry Challenges
- Electrolyte formulation expertise gap:Domestic talent pools lack experience in high-voltage additive packages for nickel-rich cathode systems.
- Thermal runaway testing infrastructure:Only two BIS-accredited labs operate nail penetration and crush test facilities for large-format pouch cells.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Battery Market |
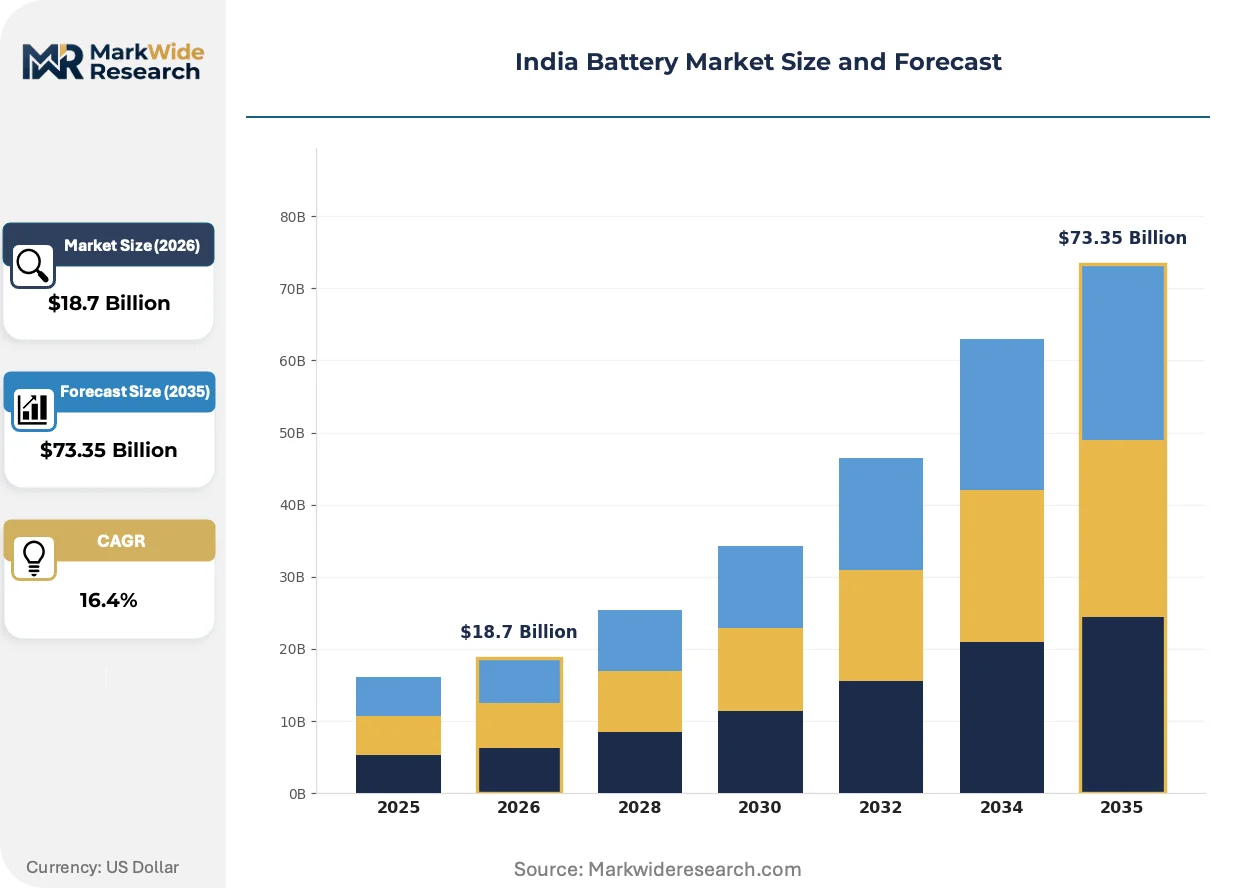
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Flow Batteries End User: Automotive, Consumer Electronics, Renewable Energy, Telecommunications Application: Electric Vehicles, Backup Power, Energy Storage Systems, Grid Management Technology: Rechargeable, Non-Rechargeable, Solid-State, Hybrid |
| Companies Covered | Exide Industries Ltd, Amara Raja Energy & Mobility Limited, HBL Power Systems Ltd, Luminous Power Technologies Pvt. Ltd., Eveready Industries India Ltd, TATA AutoComp GY Batteries Pvt. Ltd., Okaya Power Pvt. Ltd., Livguard Energy Technologies Pvt Ltd, Indo National Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Battery Market Strategic Shifts
Modular pack architectures and solid-state electrolyte research are compressing development cycles, while policy arbitrage between central and state regulations is reshaping capital allocation patterns.
Solid-state battery prototyping is decentralizing cell manufacturing footprints by enabling dry electrode coating that eliminates toxic solvent handling. Automotive OEMs in Chennai and Pune are piloting sulfide-based electrolyte cells for premium electric sport-utility vehicles. This chemistry is decentralizing the traditional wet-coating equipment supply chain dominated by Korean and Japanese machinery vendors.
The CEA technical standards for grid-connected battery storage mandate fire suppression systems and remote monitoring protocols for installations above 10 MWh. These requirements are elevating engineering costs for integrators but creating compliance moats for certified domestic system providers. Maharashtra State Electricity Distribution Company tenders now specify these standards, forcing international suppliers to establish local assembly partnerships.
Fleet operators are consolidating procurement through long-term offtake agreements directly with cell manufacturers, bypassing traditional trading houses. This direct contracting is compressing working capital cycles for pack assemblers while concentrating volume commitments among Gujarat-based gigafactory operators. The shift is most visible in Bengaluru's electric two-wheeler leasing market, where operators now negotiate annual cell supply contracts rather than spot purchases.
India Battery Market Segmentation
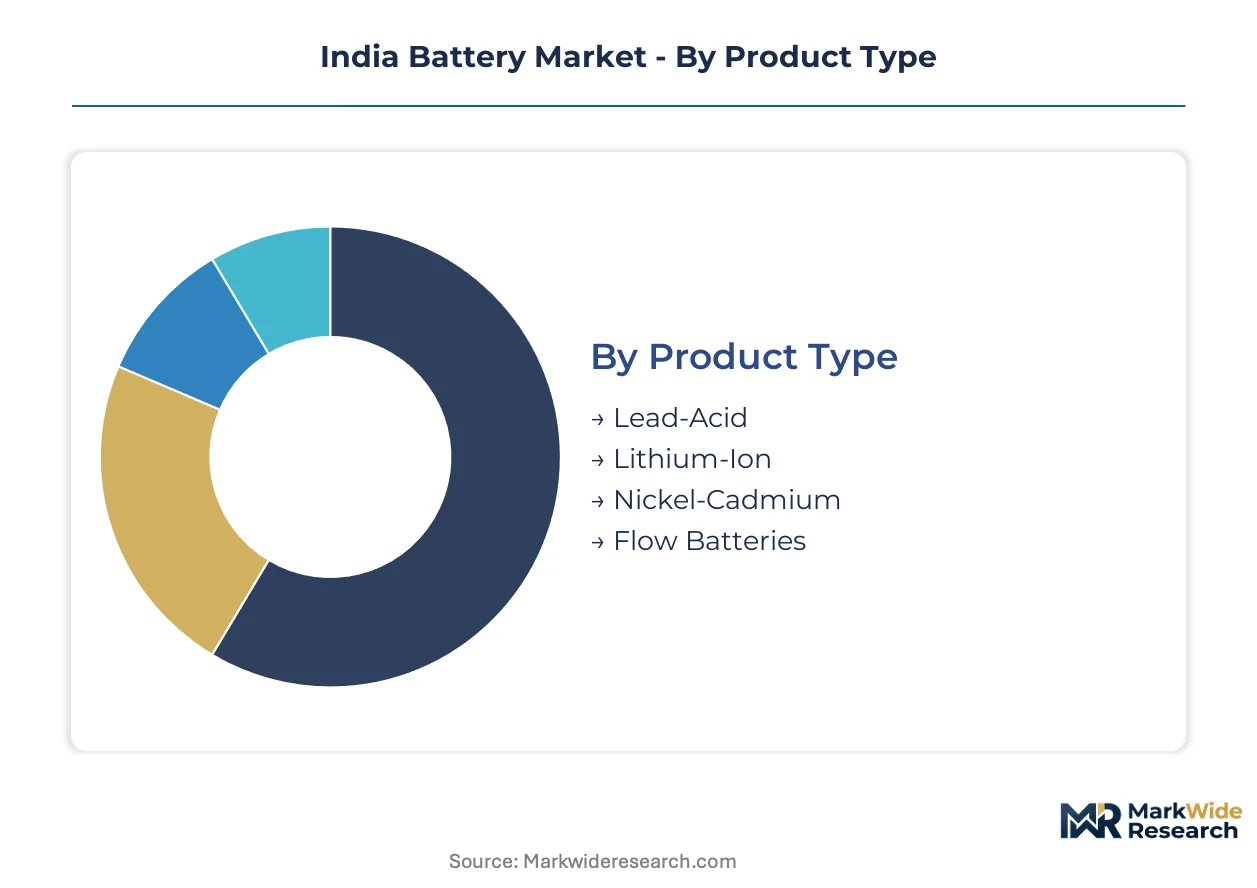
Battery procurement in India fragments across chemistry types, end-use sectors, and application contexts, each carrying distinct certification burdens from BIS, CEA, and state-level electric vehicle authorities. Segmentation clarity enables suppliers to align manufacturing investments with subsidy eligibility and technical standards compliance.
Product Type:
BIS certification timelines and PLI scheme eligibility criteria vary sharply across chemistries, with lithium-ion facing 12-18 month approval windows while lead-acid operates under grandfathered standards.
- Lithium-Ion:Nickel-cobalt-manganese and lithium-iron-phosphate cathode formulations dominate cell imports, with energy densities of 150-300 Wh/kg enabling electric two-wheeler range targets. Gujarat and Tamil Nadu gigafactory clusters concentrate pack assembly operations serving fleet operators under FAME-II subsidies.
- Lead-Acid:Flooded and valve-regulated lead-acid designs retain cost advantages below 50 Ah capacities, with Exide Industries and Amara Raja defending aftermarket positions in commercial vehicle starter applications through established distributor networks in Maharashtra and Delhi.
- Nickel-Cadmium:Sintered plate construction delivers cycle stability for railway signaling and defense applications requiring temperature resilience between minus 20 and plus 50 degrees Celsius.
- Flow Batteries:Vanadium redox systems exceed 10 MWh scalability for grid storage tenders issued by state distribution companies under renewable purchase obligations.
Lithium-ion sits at the top of the volume ranking, with flow batteries climbing the fastest as state distribution companies tender containerized systems for solar-wind integration.
End User:
Cost tier segmentation separates premium-certified supply for automotive OEMs from price-sensitive procurement in telecom tower operations.
- Automotive:Passenger electric vehicles and commercial fleets drive cell-grade lithium demand, with Tata Motors and Mahindra sourcing packs through captive supplier relationships. BIS certification for automotive cells mandates nail penetration and crush testing at accredited labs in Bengaluru and Pune.
- Renewable Energy:Solar developers in Rajasthan and Gujarat procure lithium-ion and flow battery systems for peak shifting and frequency regulation, with CEA technical standards mandating fire suppression and remote monitoring above 10 MWh installations.
- Telecommunications:Tower operators in rural Bihar and Uttar Pradesh prioritize lead-acid for backup power below 4-hour discharge durations, substituting with lithium-ion only where diesel logistics costs exceed battery replacement cycles.
- Consumer Electronics:Smartphone and laptop manufacturers import cylindrical and pouch cells through DGFT licensing frameworks, with BIS marking requirements extending to power banks above 20 Wh capacity.
Automotive commands the highest absolute cell consumption, with renewable energy expanding most quickly as state tenders aggregate multi-gigawatt-hour procurement pipelines.
Application:
Application segmentation tracks capital intensity divergence between asset-heavy charging infrastructure and asset-light battery swapping models.
- Electric Vehicles:Two-wheeler and three-wheeler electrification dominates unit volumes, with Bengaluru and Delhi fleet operators negotiating direct offtake contracts with Gujarat-based cell assemblers to bypass trading house margins.
- Energy Storage Systems:Containerized lithium-ion installations integrate with solar parks in Karnataka and Andhra Pradesh, with Maharashtra State Electricity Distribution Company tenders specifying CEA fire safety protocols that favor domestic system integrators.
- Backup Power:Data centers and hospitals in Mumbai and Chennai specify valve-regulated lead-acid for uninterruptible power supply redundancy, with 15-20 minute discharge ratings sufficient for diesel generator sequencing.
- Grid Management:Frequency regulation and peak shaving applications deploy lithium-ion and sodium-ion pilot projects, with SECI tenders testing 100 MWh standalone storage configurations in Gujarat.
Electric vehicles anchor current procurement volumes, with energy storage systems gaining share fastest as renewable purchase obligations harden across state jurisdictions.
Technology:
Technology maturity curves separate commercialized rechargeable formats from pre-commercial solid-state prototypes.
- Rechargeable:Lithium-ion and lead-acid chemistries enable 500-2000 cycle lifespans, with warranty terms of 3-5 years standard for automotive and stationary applications. BIS testing protocols validate cycle degradation curves for domestic pack assemblers.
- Solid-State:Sulfide and oxide electrolyte research in Chennai and Pune automotive labs targets 400 Wh/kg energy density for premium sport-utility vehicle segments, with dry electrode coating eliminating toxic solvent handling from manufacturing footprints.
- Non-Rechargeable:Alkaline and lithium primary cells serve medical devices and remote sensors where charging infrastructure is unavailable, with import dependency concentrated in Chinese cylindrical cell supply.
- Hybrid:Supercapacitor-battery combinations address high-rate discharge requirements in hybrid electric bus regenerative braking systems, with pilot deployments in Bengaluru municipal transport fleets.
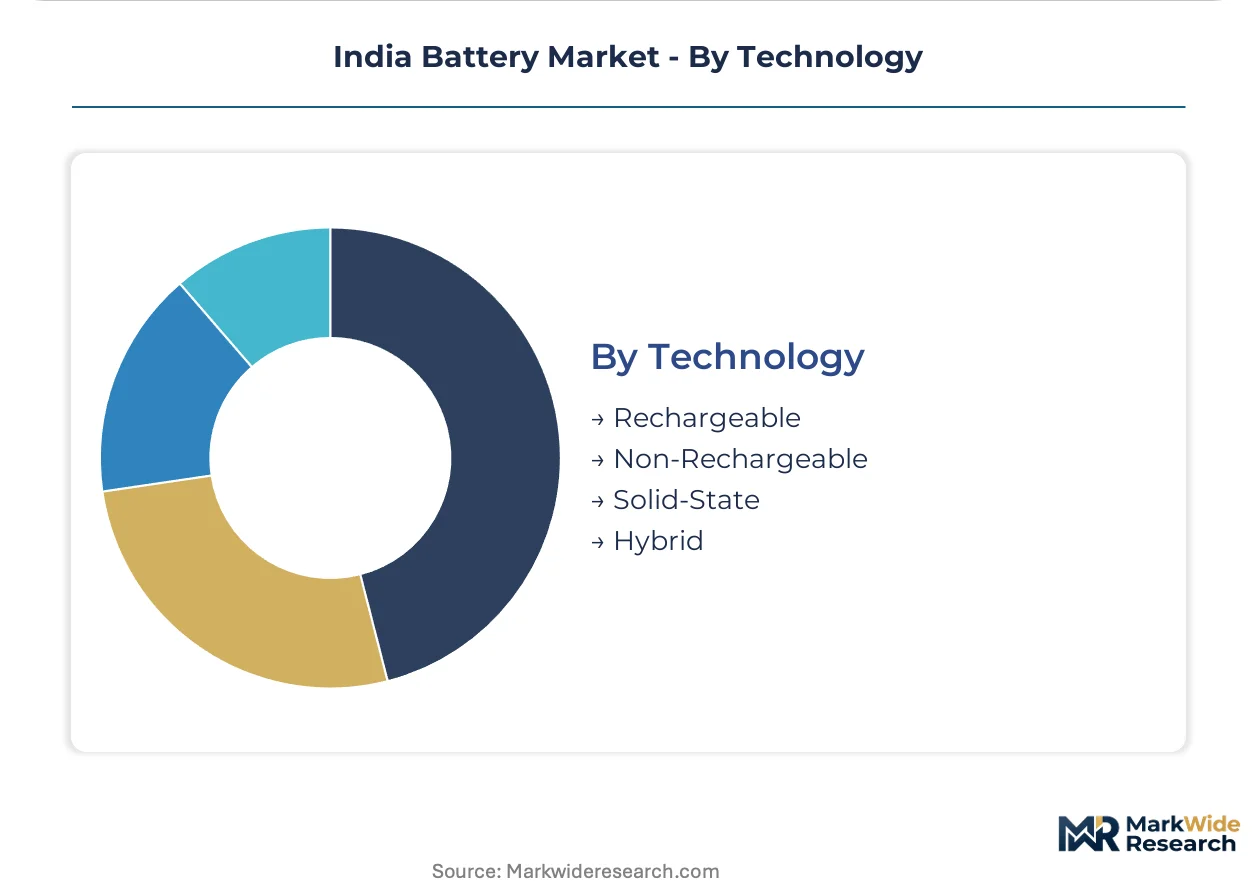
Rechargeable technology captures overwhelming volume share, with solid-state formats tracking the steepest development trajectory as OEMs pilot sulfide electrolyte cells for premium vehicle segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's battery industry traces its commercial origins to lead-acid manufacturing clusters established in Maharashtra and Tamil Nadu during the 1960s, with subsequent lithium-ion capacity emerging around Gujarat's port infrastructure after 2015.
Gujarat
Electric vehicle pack assembly and cathode active material processing dominate industrial demand in this western state. The PLI scheme for advanced chemistry cells channels subsidy flows into Mundra-adjacent manufacturing zones. Reliance Industries and Tata Group affiliates anchor gigafactory construction within 200 kilometers of the port, concentrating cell production and module assembly operations.
Tamil Nadu
Automotive OEM procurement pulls lithium-ion demand toward Chennai's industrial corridor. State electric vehicle policy incentives complement central FAME-II subsidies for two-wheeler and three-wheeler fleet electrification. Ennore port-linked zones host cathode precursor processing facilities serving battery pack integrators supplying Bengaluru-based electric mobility operators.
Maharashtra
Commercial vehicle aftermarket demand and data center backup power sustain lead-acid volume in this western state. Maharashtra State Electricity Distribution Company tenders for grid-scale storage mandate CEA fire safety protocols above 10 MWh installations. Mumbai and Pune house BIS-accredited testing laboratories validating cell certification for automotive applications.
Karnataka
Renewable energy integration tenders drive containerized battery procurement from solar developers in this southern state. Bengaluru's electric two-wheeler leasing market pioneered direct offtake contracting between fleet operators and Gujarat-based cell assemblers. State electric vehicle policy frameworks support battery swapping infrastructure deployment across the capital region.
Delhi-NCR
Last-mile logistics electrification and battery swapping infrastructure concentrate demand in this northern metro cluster. Delhi's electric vehicle mandate and FAME-II subsidy eligibility shape procurement specifications for lithium-ion pack suppliers. Noida and Gurugram host pack assembly operations serving national capital region fleet operators.
India Battery Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and chemistry specialization dimensions. The vendor base separates into three distinct strata: integrated conglomerates with captive supply relationships, standalone battery specialists defending aftermarket positions, and emerging lithium-ion assemblers scaling through PLI-linked capacity. Strategic moves concentrate on backward integration into cell manufacturing and geographic clustering around Gujarat-Tamil Nadu industrial corridors.
Among established Indian battery manufacturers, Exide Industries Ltd and Amara Raja Energy & Mobility Limited occupy positions in the lead-acid defense tier, while TATA AutoComp GY Batteries Pvt. Ltd. sits within the conglomerate-anchored ecosystem. These three entities exemplify distinct competitive archetypes: the legacy aftermarket defender, the chemistry-transitioning specialist, and the captive supply integrator respectively.
| Leading Market Players |
|---|
| Exide Industries Ltd |
| Amara Raja Energy & Mobility Limited |
| HBL Power Systems Ltd |
| Luminous Power Technologies Pvt. Ltd. |
| Eveready Industries India Ltd |
| TATA AutoComp GY Batteries Pvt. Ltd. |
| Okaya Power Pvt. Ltd. |
| Livguard Energy Technologies Pvt Ltd |
| Indo National Ltd |
| Others |
Value Chain & Pricing Dynamics
Electrolyte formulation specialists concentrated in Chennai and Pune command wage premiums that widen spreads between premium-certified automotive cells and economy-grade stationary storage packs. Labor-cost differentials between these technical clusters and commodity assembly zones in Gujarat create pricing-tier separation that buyers navigate through certification-grade selection.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification burden and performance warranty. Price differentiation separates BIS-accredited automotive cells with nail penetration validation from uncertified telecom backup units. Cost compression in economy lithium-ion tiers is intensifying because Chinese cell imports undercut domestic pack assemblers on raw material sourcing. Fleet operators in Bengaluru exhibit highest price sensitivity through direct offtake contracting, while data center operators in Mumbai absorb premiums for fire-rated valve-regulated lead-acid systems.
Supply Chain Analysis
Domestic-content mandates under the PLI scheme for advanced chemistry cells are reshaping sourcing patterns toward Gujarat-based cathode active material processing. Cell-grade lithium carbonate feeds from Chinese refiners, with South Korean and Japanese machinery vendors dominating coating equipment supply. Supply chain risk centers on single-source vulnerability for high-purity electrolyte salts through Tianjin and Qingdao ports. Distribution runs through captive supplier relationships within Tata and Mahindra ecosystems, alongside independent trading houses serving aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with FAME-II subsidy extensions and renewable purchase obligations creating demand visibility that outpaces adjacent industrial components.
For Market Incumbents: Anticipate sodium-ion chemistry substitution in stationary storage tenders by hardening lithium-ion cost positions through backward integration into cathode precursor processing. Defend automotive aftermarket margins against emerging lithium-ion assemblers by extending lead-acid warranty terms and locking distributor exclusivity in Maharashtra commercial vehicle corridors. Certification investment in BIS-accredited testing partnerships creates switching costs for fleet operator procurement committees. For New Entrants and Emerging Players: The price-point gap between premium automotive cells and economy telecom backup batteries opens white-space targeting for mid-tier energy storage integrators. Rural microgrid deployment in Bihar and Uttar Pradesh represents the most penetrable segment, with solar-plus-storage kits below 5 kWh capacity underserved by established Gujarat pack assemblers. A go-to-market angle through state distribution company tender participation, leveraging CEA fire safety protocol compliance as qualification barrier, accelerates reference customer acquisition. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone battery specialists lacking PLI-linked capacity commitments or captive OEM relationships. Long-term viability across the projection horizon favors integrators with demonstrated BIS certification timelines and port-adjacent manufacturing footprints. Acquisition target archetype: mid-scale lithium-ion pack assemblers with Maharashtra or Karnataka state tender wins but constrained working capital for cell inventory build. The signal to watch is tariff rationalization between battery swapping and charging infrastructure, which would re-rate asset-light operators against capital-intensive gigafactory developers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Active Material | PLI scheme subsidies for domestic precursor processing reduce lithium carbonate import exposure through Mundra-adjacent zones. |
| BIS Certification Fast-Track Investment | Accelerated testing protocols at Pune and Bengaluru labs compress product launch timelines for automotive cell suppliers. |
| Battery-as-a-Service Platform Launch | Swapping infrastructure in Delhi-NCR decouples asset ownership from energy access for last-mile logistics fleets. |
| Sodium-Ion Chemistry Pilot Deployment | Prussian blue cathode systems for grid storage tenders eliminate supply chain concentration in Chinese lithium refiners. |
| Direct Offtake Contracting with Fleet Operators | Bypassing trading house margins compresses working capital cycles for Gujarat-based pack assemblers serving Bengaluru. |
Study Parameters
Bottom-up electric vehicle fleet modeling reconciled against top-down cathode active material import tracking forms the analytical core of this study. Primary interviews with cell manufacturing executives, PLI scheme implementation officers at the Ministry of Heavy Industries, state distribution company procurement heads, and BIS certification laboratory directors combined with secondary validation from DGFT import records, CEA technical standard filings, SECI tender documentation, and state electric vehicle policy gazettes. Triangulation across these sources calibrated volume estimates against actual gigafactory commissioning timelines and FAME-II disbursement patterns.
Historical trendline analysis of lead-acid replacement cycles and lithium-ion adoption curves in automotive and stationary storage segments informed projection mechanics across the analysis window. Segmentation dimensions modeled include chemistry type, end-use sector, application context, and state-level regulatory cluster. CAGRs derived from fitted growth curves adjusted for PLI capacity ramp schedules and renewable purchase obligation enforcement trajectories. Industry-specific forecast inputs incorporated solar-wind integration targets from state electricity regulatory commission orders and electric two-wheeler penetration assumptions from municipal transport authority fleet electrification mandates.
Caveats apply where BIS certification timeline delays, lithium carbonate price volatility, or state-level policy fragmentation could materially shift the outlook. Forecasts reflect assumptions about subsidy continuity and import tariff stability that warrant monitoring against central government fiscal consolidation pressures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Primary Lithium Battery for Industrial Market
Batteries
Yacht Battery Market
Batteries
Power-Sports Batteries Market
Batteries
Battery Binders Market
Batteries
North America Rechargeable Battery Market
Batteries
Battery Simulator Market
Batteries
Battery Materials Market
Batteries
Power Battery Sealant Market
Batteries
Vanadium Redox Batteries Market
Batteries
Utility Battery Market
Batteries
East Africa Battery Market
Batteries
Europe Consumer Battery Market
Batteries
France Rechargeable Battery Market
Batteries
3D-Printed Battery Market
Batteries
Global Solar Battery Charger Market
Batteries
Absorbent Glass Mat (AGM) Battery Market