
 SLI Battery Market | 2026-2036
SLI Battery Market Size, Share, and Industry Trends Forecast 2026-2036
SLI Battery Market Analysis
The aftermarket distribution channel for SLI batteries is narrowing as OEM-tied service networks consolidate procurement. Clarios leverages its captive supply of recycled lead to control cost structures across North American service bays. Johnson Controls International anchors fleet maintenance contracts through direct-installation partnerships with commercial vehicle operators. Exide Technologies competes in price-sensitive replacement cycles across independent auto parts retailers.
An SLI battery is a rechargeable power unit engineered to deliver short-duration high-current bursts for engine cranking, with lead-acid chemistry dominating due to its cold-cranking amperage tolerance above 600A at negative eighteen degrees Celsius. Its commercial purpose centers on reliable starting performance in internal combustion powertrains across passenger cars, trucks, and marine vessels. The lead-acid segment remains the mature volume base, though absorbent glass mat variants are capturing margin pools in premium automotive applications where vibration resistance and cycle durability command price premiums. Lithium-ion chemistries are displacing conventional units in motorcycle and powersport niches where weight reduction directly improves vehicle dynamics.
The EPA governs lead recycling mandates under the Resource Conservation and Recovery Act, while the EU's REACH framework restricts hazardous substance thresholds in battery manufacturing inputs. China's SAMR enforces GB standards for SLI product safety certification, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor how dual carbon goals across Beijing and Brussels reshape material sourcing requirements for lead smelting and plastic casing production.
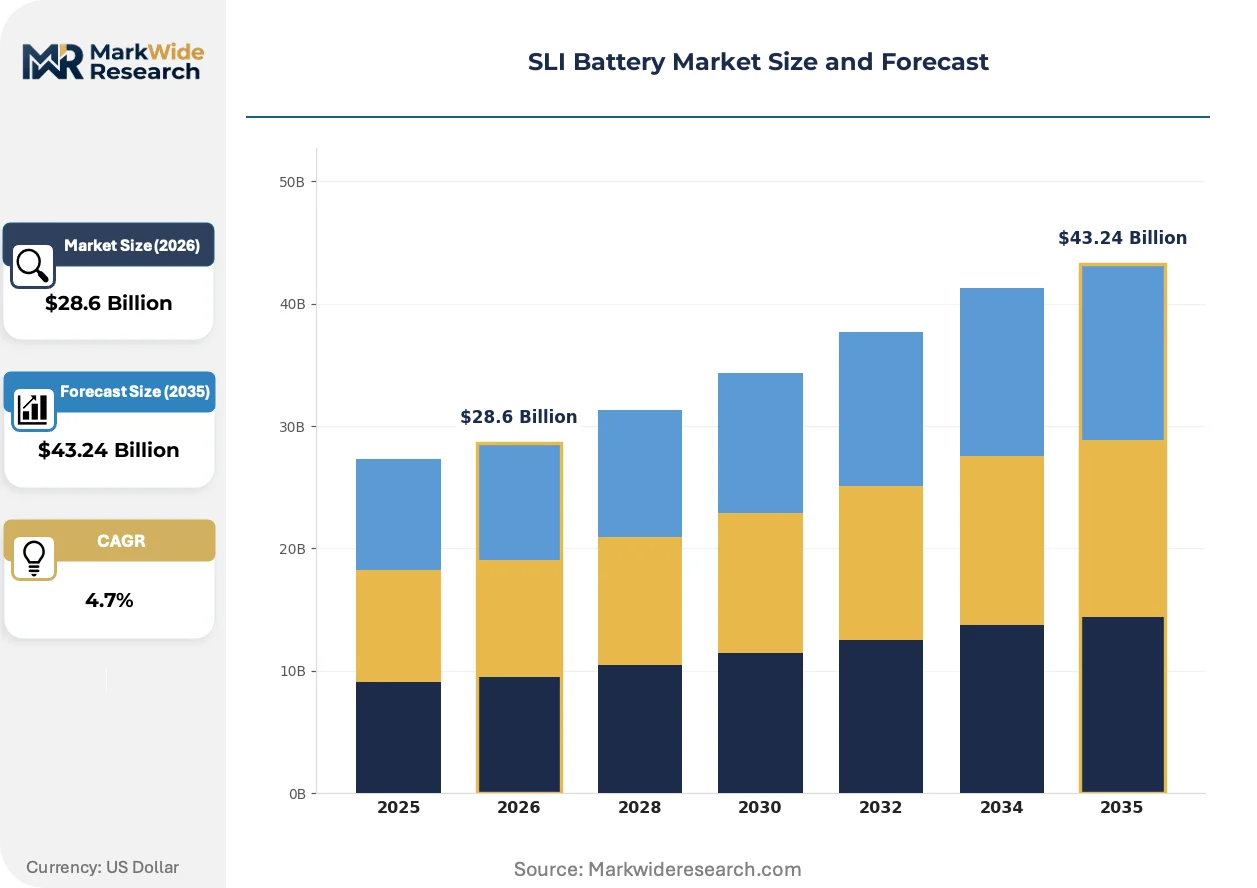
Market Dynamics
Fleet electrification timelines and dual carbon mandates in Beijing and Brussels are compressing replacement cycles for conventional starting-lighting-ignition units while fragmenting demand between lead-acid maintenance and lithium-ion conversion pathways.
Growth Catalysts
- India's PLI scheme for auto components:Battery manufacturers are establishing production facilities in Tamil Nadu and Maharashtra corridors to capture localized procurement mandates from OEM assembly plants.
- Absorbent glass mat chemistry:Premium automotive segments are absorbing vibration-resistant variants for start-stop powertrains, expanding margin pools beyond conventional flooded designs.
- REACH substance restrictions:EU battery producers are retrofitting smelting operations to eliminate restricted hazardous inputs, creating compliance-driven replacement demand across European service networks.
Market Restraints
- Lead price volatility:Secondary smelter concentrate costs fluctuate with LME pricing, squeezing gross margins for producers without captive recycling infrastructure.
- Substitution by lithium-ion:Motorcycle and powersport manufacturers are specifying lithium-manganese-oxide packs where weight reduction exceeds cold-cranking priorities.
- China's GB standards certification:Non-domestic suppliers face extended approval timelines under SAMR enforcement, limiting market access velocity.
Strategic Opportunities
- Brazil's independent aftermarket:ANVISA-regulated battery distributors are penetrating price-sensitive replacement cycles where OEM service network coverage remains thin.
- Marine start-stop applications:Yacht and commercial vessel operators are specifying deep-cycle SLI hybrids for auxiliary power management during anchoring operations.
- EU F-Gas Regulation phase-down:Battery casing manufacturers are qualifying fluorinated-gas-free molding processes to secure automotive OEM qualification.
Industry Challenges
- Lead-acid technician scarcity:Maintenance facilities lack personnel trained in specific gravity testing and cell balancing for flooded battery servicing.
- Cross-border hazardous waste documentation:RCRA-mandated manifests for spent battery transport are creating customs clearance friction between US and Mexican recycling operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SLI Battery Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Absorbent Glass Mat, Gel End User: Automotive, Marine, Motorcycle, Commercial Vehicles Application: Starting, Lighting, Ignition, Backup Power Installation Type: OEM, Aftermarket, DIY, Professional |
| Companies Covered | East Penn Manufacturing, Amara Raja Energy & Mobility Limited, Clarios, Leoch International Technology Limited, Johnson Controls International, Exide Technologies, EnerSys, ACDelco, GS Yuasa International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SLI Battery Market Emerging Trajectories
Battery management systems and predictive maintenance algorithms are penetrating commercial fleet operations, converting SLI units from commodity hardware into data-generating assets with service-interval optimization.
Smart battery sensors embedded within terminal posts are digitizing state-of-charge telemetry for remote monitoring platforms. Logistics operators with centralized maintenance depots are adopting these units fastest, compressing unplanned downtime through predictive failure alerts. The technology is digitizing fleet procurement from reactive replacement toward condition-based scheduling.
China's NMPA battery safety standards are mandating thermal runaway propagation testing for all automotive battery categories including SLI variants. Domestic manufacturers are redesigning cell separation barriers and venting mechanisms to satisfy GB certification. The regulation is reshaping product development timelines, with European exporters facing additional validation cycles before market entry.
Commercial vehicle operators are consolidating procurement through direct-installation partnerships with battery producers, bypassing traditional distributor markups. Large fleet managers with centralized maintenance operations are negotiating volume contracts that bundle installation labor with unit supply. This concentration is most visible across North American long-haul trucking corridors where telematics integration enables usage-based pricing negotiations.
SLI Battery Market Segmentation
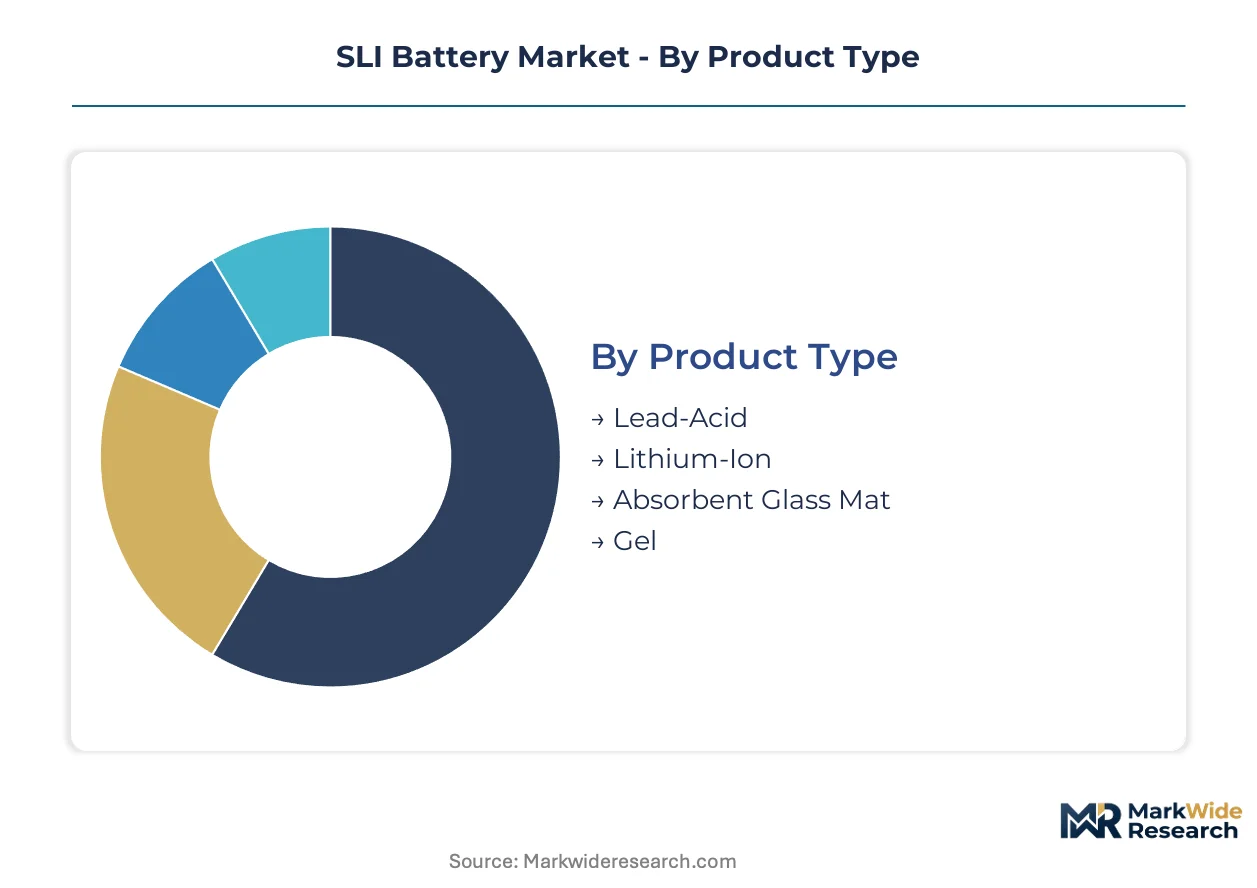
SLI battery procurement patterns diverge sharply across chemistry types and installation channels. Fleet operators prioritize lifecycle cost over upfront expenditure, while independent consumers respond to cold-cranking specifications and warranty terms. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization dominates.
Product Type:
After-sales service intensity varies dramatically by chemistry, with flooded lead-acid demanding periodic electrolyte maintenance while sealed variants shift revenue toward replacement rather than upkeep.
- Lead-Acid:Flooded-cell construction with sulfuric acid electrolyte delivers cold-cranking amperage above 600A at sub-zero temperatures. Demand concentrates in India's commercial vehicle corridors around Chennai and Pune where cost-sensitive fleet operators prioritize unit replacement over chemistry upgrade.
- Lithium-Ion:Lithium-manganese-oxide cathodes enable 60-70% weight reduction versus lead-acid equivalents. Motorcycle manufacturers in Japan and Italy specify these packs where vehicle dynamics improvement justifies premium positioning and eliminates acid spillage liability.
- Absorbent Glass Mat:Electrolyte suspended in fiberglass matting eliminates free liquid while tolerating deep discharge cycles. Start-stop powertrain adoption in EU passenger vehicles drives specification where vibration resistance commands price premiums.
- Gel:Silica-thickened electrolyte prevents stratification in marine applications where tilting and rough seas challenge conventional designs. Yacht operators in Mediterranean charter fleets specify gel variants for auxiliary power reliability.
By volume, Lead-Acid leads. By growth pace, Absorbent Glass Mat is gaining share fastest.
End User:
Cost tier stratification separates premium OEM-specified units from price-driven replacement cycles in mature vehicle populations.
- Automotive:Passenger car OEMs specify start-stop compatible AGM variants for fuel efficiency compliance under EU CO2 regulations. Independent aftermarket channels in Brazil favor conventional flooded designs for vehicles outside warranty coverage.
- Marine:Deep-cycle SLI hybrids serve dual starting and house-load functions aboard commercial fishing vessels. Battery management systems with remote monitoring penetrate charter fleets where unplanned downtime carries penalty clauses.
- Motorcycle:Lithium-ion displacement accelerates in powersport segments where weight reduction directly improves handling metrics. Lead-acid retains dominance in emerging market commuter bikes where distributor network density supports low-cost replacement.
- Commercial Vehicles:Long-haul trucking operators in North America consolidate procurement through direct-installation partnerships. Telematics integration enables usage-based pricing negotiations that bundle installation labor with unit supply.
Commercial Vehicles generate the highest service revenue per installed unit. Motorcycle applications show the steepest chemistry transition trajectory.
Application:
Functional criticality determines margin structure, with starting applications commanding premium pricing for failure-avoidance while backup power tolerates longer lead times.
- Starting:Engine cranking demands instantaneous high-current discharge with minimal voltage sag. Cold-climate specifications in Canada and Scandinavia drive oversized capacity ratings that expand material content and unit pricing.
- Lighting:Continuous discharge tolerance matters more than peak output for auxiliary illumination systems. Marine and commercial vehicle operators specify dual-purpose designs that sacrifice some cranking capacity for reserve capacity depth.
- Ignition:Coil saturation requirements in modern electronic ignition systems need sustained voltage stability. Motorcycle applications prioritize compact terminal configurations that fit confined frame geometries.
- Backup Power:Standby float service in emergency vehicle and telecom applications emphasizes calendar life over cycle durability. China's SAMR enforces GB standards certification that extends validation timelines for non-domestic suppliers targeting this segment.
Starting applications dominate unit volume. Backup Power shows the most rapid specification evolution toward smart monitoring integration.
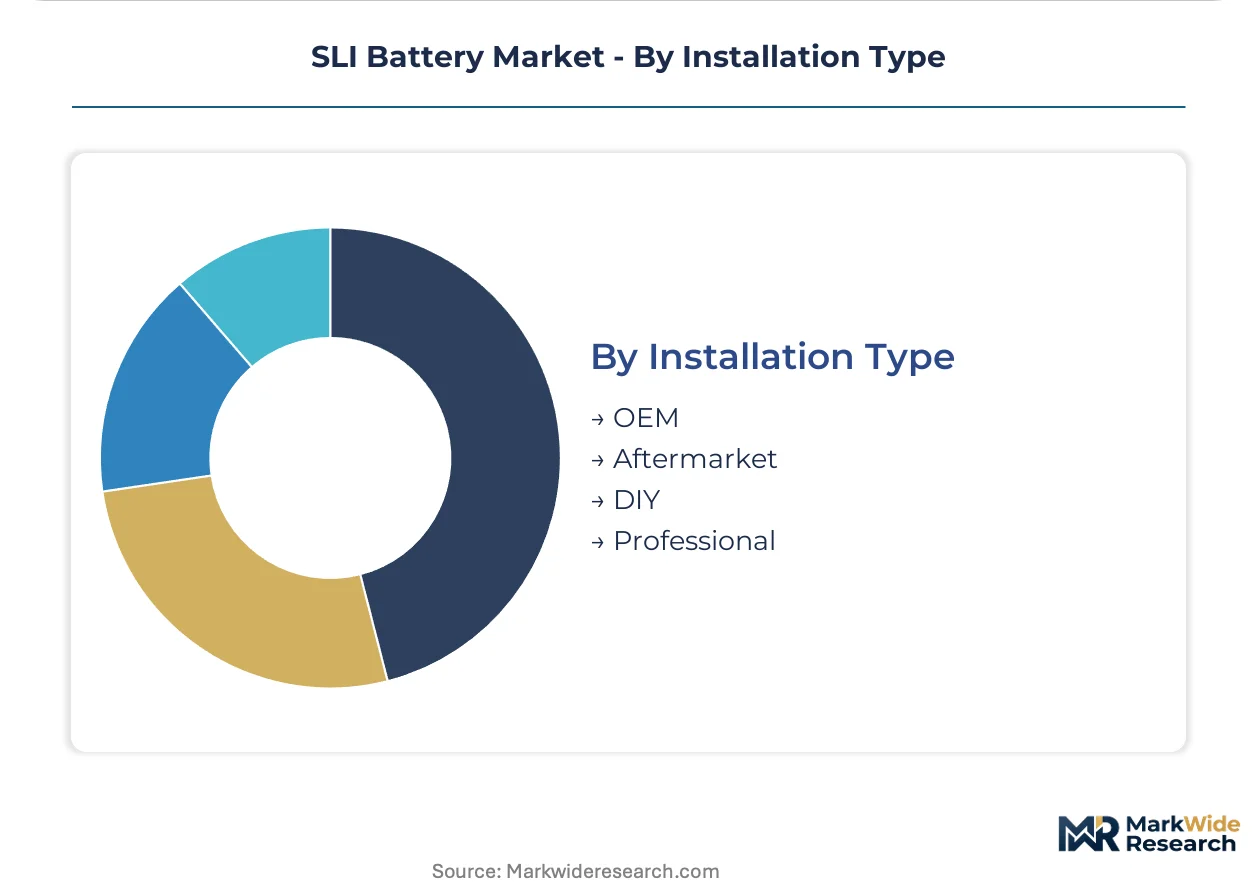
Installation Type:
Customer type segmentation separates skilled technician dependency from consumer self-selection, reshaping distribution margin capture.
- OEM:Vehicle manufacturers specify certified supplier programs with traceable production batch documentation. India's PLI scheme for auto components incentivizes localized battery production in Tamil Nadu and Maharashtra corridors.
- Aftermarket:Service networks consolidate procurement as fleet operators bypass traditional distributor markups. Clarios leverages captive recycled lead supply to control cost structures across North American service bay installations.
- DIY:Independent auto parts retailers compete on price-sensitive replacement cycles with standardized group size availability. Consumer education gaps around proper disposal create regulatory exposure under EPA RCRA manifest requirements.
- Professional:Certified installation with warranty registration captures service revenue beyond hardware margin. EU REACH substance restrictions drive retrofitting of smelting operations, creating compliance-driven replacement demand across European professional service networks.
Aftermarket channels move the highest unit volumes. Professional installation is climbing fastest as fleet centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in automotive battery exports, while the Rhine-Main-Danube corridor channels German manufacturing output across Central Europe. India's Dedicated Freight Corridors are compressing inland transit times from Tamil Nadu assembly plants to northern consumption centers.
China
Domestic EV adoption and commercial fleet electrification are fragmenting SLI demand between lead-acid maintenance and lithium conversion pathways. SAMR enforces GB standards certification that extends validation timelines for non-domestic suppliers. Manufacturing concentrates in the Yangtze River Delta around Ningbo and Suzhou where battery casing producers qualify fluorinated-gas-free molding processes.
United States
Long-haul trucking operators consolidate procurement through direct-installation partnerships that bundle installation labor with unit supply. EPA governs lead recycling mandates under RCRA, creating documentation friction for cross-border Mexican recycling operations. Production gravity sits in the industrial Midwest around Detroit and Chicago where captive lead recycling infrastructure controls cost structures.
Germany
Start-stop powertrain adoption in EU passenger vehicles drives AGM specification where vibration resistance commands price premiums. ECHA's REACH framework restricts hazardous substance thresholds, forcing smelting operation retrofits. The Rhine-Ruhr corridor hosts qualified suppliers redesigning cell separation barriers to satisfy thermal runaway propagation testing.
India
Commercial vehicle corridors around Chennai and Pune concentrate cost-sensitive fleet operator demand prioritizing unit replacement over chemistry upgrade. The PLI scheme for auto components incentivizes localized production in Tamil Nadu and Maharashtra. Battery manufacturers are establishing facilities to capture localized procurement mandates from OEM assembly plants.
Brazil
Independent aftermarket channels penetrate price-sensitive replacement cycles where OEM service network coverage remains thin. ANVISA regulates battery distribution standards for commercial logistics applications. São Paulo and Minas Gerais anchor domestic demand as fleet operators expand replacement schedules for starting-lighting-ignition units.
SLI Battery Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated lead recyclers and chemistry specialists with captive raw material access. Tiered competitive positioning separates premium AGM producers from commodity flooded-cell manufacturers serving price-driven replacement cycles. Three archetypes dominate: integrated recyclers controlling secondary lead costs, chemistry innovators capturing start-stop premiums, and regional assemblers serving fragmented aftermarket channels. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure installation network access.
Within the integrated recycler archetype, Clarios and East Penn Manufacturing exemplify supply-side consolidation through captive lead recovery infrastructure. Johnson Controls International anchors the direct-installation partnership model with fleet operators, while GS Yuasa International occupies a position bridging OEM specification and aftermarket replacement. Amara Raja Energy & Mobility Limited and Leoch International Technology Limited represent regional scale players competing on localized production economics. Exide Technologies and EnerSys sit within the diversified energy storage tier where SLI units complement industrial battery portfolios.
| Leading Market Players |
|---|
| East Penn Manufacturing |
| Amara Raja Energy & Mobility Limited |
| Clarios |
| Leoch International Technology Limited |
| Johnson Controls International |
| Exide Technologies |
| EnerSys |
| ACDelco |
| GS Yuasa International |
| Others |
Supply Flow & Price Mechanics
Lead price volatility on the London Metal Exchange determines both margin compression in commodity flooded-cell tiers and the geographic clustering of secondary smelter capacity. This input cost instability widens pricing spreads between captive-recycler integrated producers and merchant-lead dependent assemblers while reshaping procurement patterns toward long-term concentrate offtake agreements.
Pricing Analysis
Volume-discount tiering structures separate fleet-direct contracts from independent aftermarket transactions. Three-tier pricing stratifies across AGM premium specifications, standard flooded designs, and economy private-label units, with cold-cranking amperage certification and warranty duration as primary differentiation drivers. Pricing pressure stems from lithium-ion substitution in motorcycle segments where weight reduction commands design priority. Fleet operators exhibit lowest price sensitivity due to lifecycle cost modeling, while DIY consumers in emerging markets drive economy tier volume.
Supply Chain Analysis
Export-control regime friction around battery-grade lead concentrate flows complicates raw material security for non-integrated producers. Supply concentrates in China, South Korea, and Germany, with secondary lead recovery feeding from spent battery collection networks. The chain draws from mined lead concentrate, recycled secondary metal, and polypropylene casing resins. Single-source vulnerability concentrates in China's Yangtze River Delta smelting complexes. Distribution runs through OEM-tied service networks, independent auto parts retailers, and direct-installation fleet partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to commercial vehicle fleet replacement schedules. OEM assembly rate normalization and deferred maintenance backlogs from prior contraction periods justify the cyclical framing.
For Market Incumbents: Build captive recycling moats through secondary smelter capacity additions in North American industrial corridors. Secure long-term concentrate offtake agreements to buffer LME price swings. Deepen direct-installation partnerships with telematics-enabled fleet operators to lock out distributor intermediaries. Invest in AGM production line certification for EU start-stop powertrain qualification ahead of REACH substance restriction deadlines.
For New Entrants and Emerging Players: Build out lithium-ion assembly capacity targeting powersport and motorcycle OEM specification where lead-acid displacement accelerates. Penetrate Brazil's independent aftermarket through ANVISA-compliant distribution partnerships where OEM service network coverage remains thin. Target marine start-stop applications in Mediterranean charter fleets with deep-cycle SLI hybrid designs. Lead with smart battery sensor integration as a service-differentiation wedge.
For Investors and Strategic Acquirers: China's GB standards certification reshapes the acquisition landscape by extending validation timelines for non-domestic suppliers. Long-term viability favors vertically integrated producers with captive lead recovery and established SAMR compliance infrastructure. Target mid-cap regional assemblers in India's Tamil Nadu and Maharashtra corridors with PLI scheme qualification. Monitor EU F-Gas Regulation phase-down implementation as the signal for fluorinated-gas-free casing process investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Lead Recycling Infrastructure | Secondary smelter ownership buffers LME volatility for Clarios and East Penn Manufacturing cost structures. |
| AGM Chemistry Line Certification | EU start-stop powertrain qualification under ECHA REACH unlocks premium margin pools in German automotive supply. |
| Direct-Installation Fleet Partnerships | Telematics integration enables usage-based pricing with North American long-haul trucking operators. |
| Smart Battery Sensor Integration | Predictive maintenance algorithms convert SLI units into data assets for logistics fleet condition monitoring. |
| Fluorinated-Gas-Free Casing Process | EU F-Gas Regulation compliance secures automotive OEM qualification for battery housing manufacturers. |
Methodological Framework
Operator-level perspectives from fleet maintenance directors, aftermarket distributor procurement leads, battery plant operations managers, and OEM platform engineering teams anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against customs trade records, EPA RCRA manifest filings, SAMR GB certification databases, and vehicle production registries. Bottom-up unit demand modeling triangulated against top-down macroeconomic drivers across the analysis window.
Scenario-bracketing framed volume and value outputs across conservative, baseline, and accelerated electrification pathways. Segmentation dimensions modeled chemistry type, end-user vertical, installation channel, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to segment-level baselines, with lead price trajectories and fleet electrification timelines as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed producers or accelerated lithium-ion substitution in commercial vehicle segments would shift outcomes. Material shifts in EU REACH substance restriction enforcement timelines or SAMR certification approval velocities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Solid-State Car Battery Market
Batteries
Denmark Rechargeable Battery Market
Batteries
Power Battery Cells Market
Batteries
South Africa Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Alkaline Secondary Battery Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
North America Battery Market
Batteries
South and Central America Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Lithium-Based Battery Charger Market
Batteries
Proton Battery Market
Batteries
Leisure Battery Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
East Europe Battery Market
Batteries
UAV Battery Pack Market