
 Automotive Starting Battery Market | 2026-2036
Automotive Starting Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Starting Battery Market Analysis
The premium absorbed glass mat segment is decoupling from commodity flooded lead-acid on cold-cranking amperage and cycle-life metrics. Clarios leverages its vertically integrated recycling network across North American smelters to secure lead supply. GS Yuasa Corporation anchors Japanese OEM just-in-time contracts with plant proximity to Toyota and Honda assembly sites. East Penn Manufacturing Company sustains domestic production scale through its Pennsylvania-based foundry and formation facilities.
An automotive starting battery converts chemical energy into electrical current to crank internal combustion engines, typically delivering 12 volts at 400–600 cold-cranking amperes through lead-dioxide and sponge-lead plates submerged in sulfuric acid electrolyte. Flooded lead-acid technology dominates aftermarket replacement due to cost structure, while lithium-ion chemistry gains share in start-stop and micro-hybrid configurations where weight reduction and deeper cycling justify premium positioning. Absorbent glass mat variants command margin pools in premium passenger vehicles and commercial trucks requiring vibration resistance and extended service life.
EPA tailpipe standards and NHTSA corporate average fuel economy rules pressure OEMs toward start-stop systems, which in turn elevates battery duty-cycle requirements. China's MIIT enforces GB standards for battery recycling traceability, reshaping material recovery obligations for suppliers serving domestic automakers. India's BIS certification mandates for automotive batteries restrict import pathways and strengthen Amara Raja's domestic manufacturing position. Stakeholders must monitor how dual regulatory pressures on emissions and circularity reshape chemistry selection and regional sourcing strategies.
Market Dynamics
Start-stop system mandates from EPA and NHTSA are forcing battery chemistry upgrades across OEM platforms, while China's MIIT recycling traceability rules reshape supplier compliance costs. This dual regulatory pressure concentrates procurement power with vertically integrated manufacturers who control lead recovery networks.
Growth Catalysts
- EPA Tier 3 Emissions Standards:Tailpipe regulations compel OEMs to deploy start-stop systems, elevating absorbed glass mat battery specifications for deeper cycling duty. Passenger and commercial vehicle platforms now require enhanced cold-cranking performance.
- China's Eastern Manufacturing Corridor:Local OEM sourcing for gasoline and hybrid assembly lines concentrates demand in Jiangsu and Zhejiang provinces. Battery suppliers co-locate formation facilities to match just-in-time delivery windows.
- Lead Recovery Infrastructure:Secondary lead smelters in North America and China secure raw material supply for battery manufacturers. Closed-loop recycling economics improve feedstock cost stability against primary lead volatility.
Market Restraints
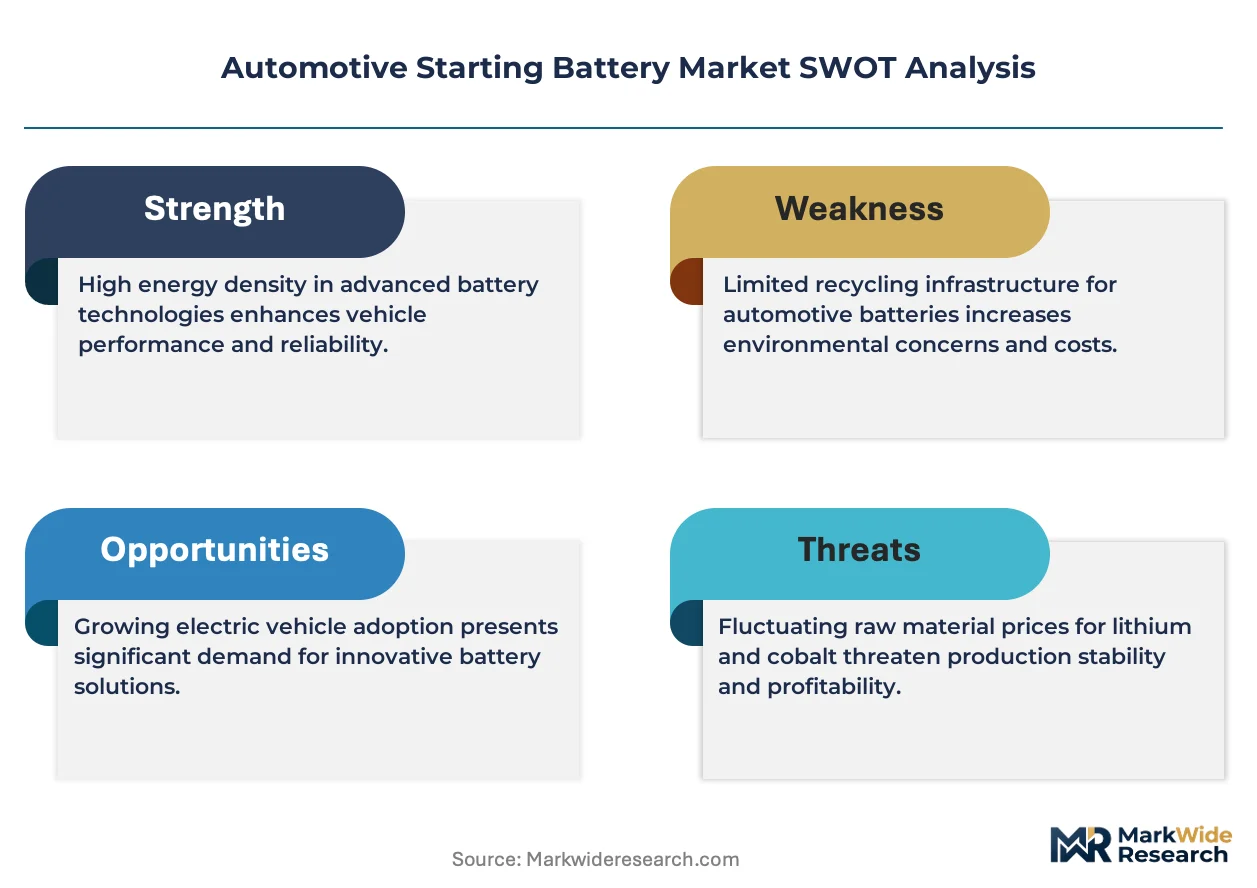
- Lead Price Volatility:Primary lead concentrate supply from Australian and Chinese mines fluctuates with currency and energy costs. Battery manufacturers face margin compression when hedging strategies fail.
- Lithium-Ion Substitution in Premium Segments:Start-stop and micro-hybrid configurations in European and Japanese passenger vehicles adopt lighter lithium-ion packs. This chemistry shift caps lead-acid volume growth in high-margin applications.
- China Smelter Concentration:Secondary lead production clusters in Henan and Anhui provinces create geographic supply risk. Environmental enforcement actions at single facilities disrupt regional battery material flows.
Strategic Opportunities
- India BIS Certification Barriers:Import restrictions strengthen domestic manufacturing positions for suppliers establishing local assembly. Amara Raja and Exide Industries expand capacity to capture replacement demand.
- Commercial Fleet Electrification Pathways:Hybrid commercial vehicles retain internal combustion engines requiring starting batteries. Fleet operators extending replacement intervals create service-contract revenue pools.
- EU Battery Regulation Traceability:Digital passport requirements for recycled content create competitive advantage for suppliers with verified recovery chains. Early compliance investments differentiate premium positioning.
Industry Challenges
- Formation Process Skill Shortage:Battery formation technicians with sulfuric acid handling and electrical testing expertise are scarce in emerging manufacturing regions. Training programs lag capacity expansion timelines.
- Multi-Chemistry Platform Integration:OEMs managing parallel lead-acid and lithium-ion supply chains face inventory complexity and warranty tracking systems. Engineering teams must validate charging algorithms for both chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Starting Battery Market |
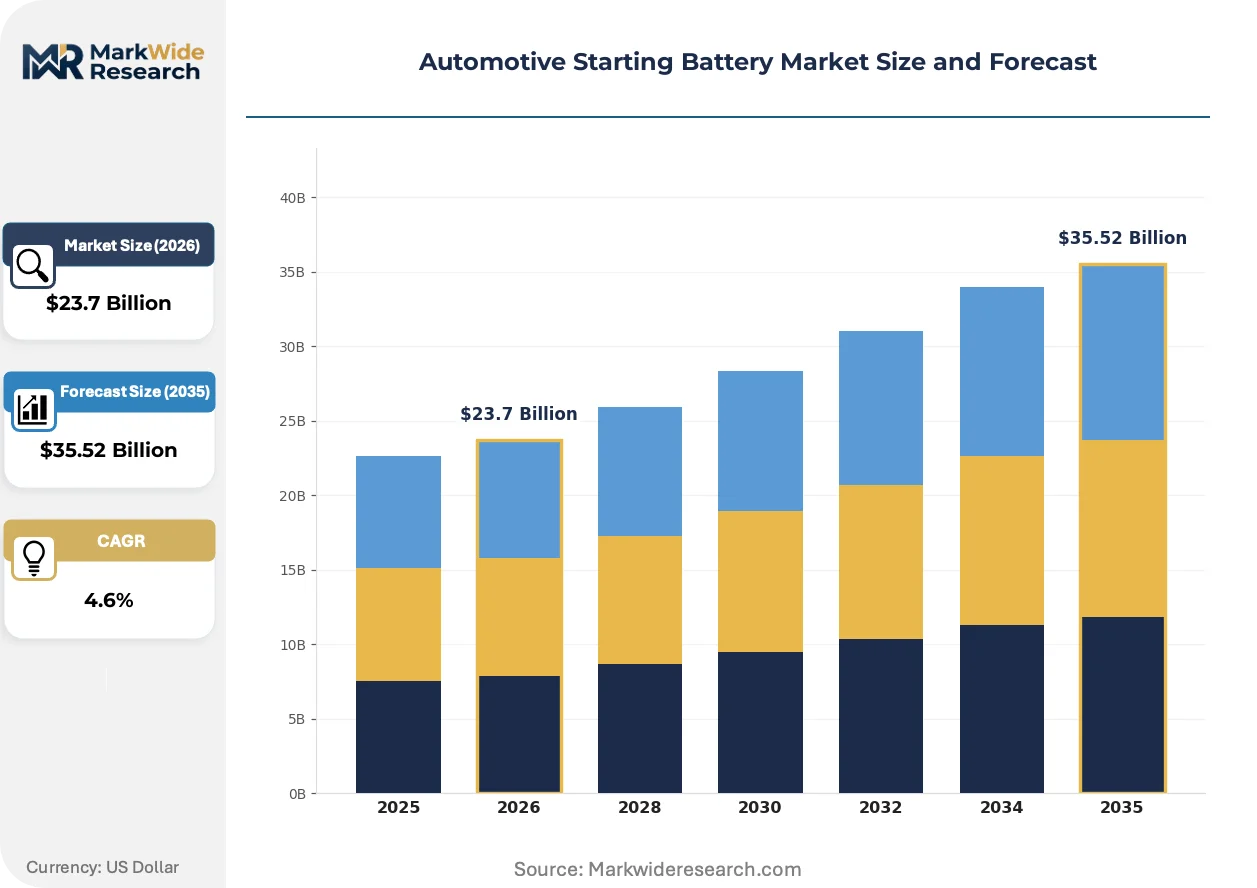
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $35.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Absorbent Glass Mat End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Motorcycles Technology: Flooded, VRLA, Lithium Polymer, Gel Distribution Channel: Online Retail, Wholesalers, Auto Parts Stores, Dealers |
| Companies Covered | Clarios, Exide Technologies, GS Yuasa Corporation, East Penn Manufacturing Company, Johnson Controls, Robert Bosch GmbH, Panasonic Corporation, Amara Raja, Crown Battery Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Starting Battery Market Emerging Trajectories
Battery architecture is bifurcating between commodity flooded lead-acid for aftermarket replacement and advanced absorbed glass mat designs for OEM start-stop platforms. This technical divergence reshapes R&D allocation and manufacturing footprints.
Absorbed glass mat technology is expanding into commercial vehicle and premium passenger segments requiring vibration resistance and extended cycle life. Fleet operators in North America and Europe specify AGM for trucks operating on rough terrain or with auxiliary electrical loads. The technology is expanding into territory previously dominated by conventional flooded designs, compressing margin pools at the commodity tier.
China's MIIT enforcement of GB standards for battery recycling traceability mandates digital tracking from manufacture through recovery. Suppliers serving domestic automakers must integrate blockchain or QR-code systems for lead provenance documentation. The regulation most affects imported battery brands lacking established Chinese recovery partnerships, forcing joint ventures with local smelters.
Fleet procurement teams are consolidating battery suppliers to reduce SKU complexity and capture volume pricing. Large commercial operators in the United States negotiate multi-year agreements with single-source providers for standardized specifications. This concentration is most visible in long-haul trucking where uptime guarantees override brand preferences, shifting power to manufacturers with national distribution networks.
Automotive Starting Battery Market Segmentation
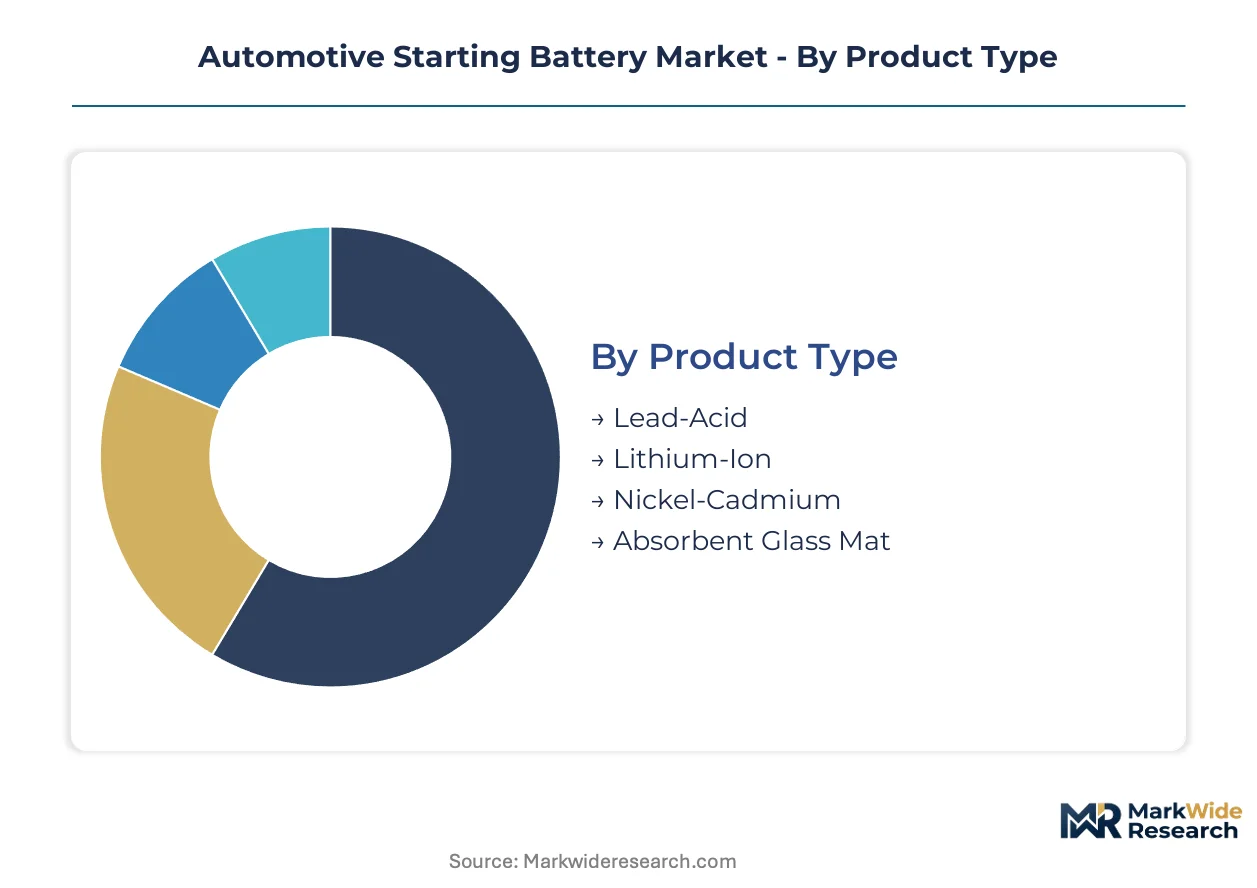
Automotive starting battery segmentation reveals how chemistry selection, distribution economics, and vehicle electrification pathways create distinct competitive arenas. Manufacturers must align R&D spending and capacity allocation with the technical requirements and margin profiles of each segment cluster.
Product Type:
Technology and specification axes define product differentiation, with chemistry choice determining cycle-life duty, cold-cranking performance, and recycling economics.
- Lead-Acid:Flooded and VRLA variants using lead-dioxide and sponge-lead plates deliver 400–600 cold-cranking amperes at 12 volts. Demand concentrates in China's Jiangsu and Zhejiang provinces where local OEMs source for gasoline-powered passenger vehicles and hybrid assembly lines, constrained by lead price volatility from Australian and Chinese mine supply.
- Lithium-Ion:Lithium iron phosphate and NMC cathode configurations achieve 60–70% weight reduction versus lead-acid equivalents. European and Japanese passenger vehicle start-stop systems specify these packs for deeper cycling duty, though premium positioning limits volume penetration in cost-sensitive replacement channels.
- Nickel-Cadmium:Sintered plate construction delivers extreme temperature tolerance for military and aviation starting applications. Niche demand persists in cold-climate commercial fleets where reliability overrides disposal cost concerns.
- Absorbent Glass Mat:Fiberglass mat separators immobilize sulfuric acid electrolyte for vibration resistance and extended service life. North American long-haul trucking fleets specify AGM for rough-terrain operations and auxiliary electrical loads.
Lead-Acid leads on scale; Lithium-Ion leads on momentum.
End User:
Vehicle platform characteristics dictate battery duty cycles, replacement intervals, and procurement channel preferences across customer categories.
- Passenger Vehicles:OEM start-stop mandates from EPA and NHTSA elevate absorbed glass mat specifications for deeper cycling. China's domestic automakers in the eastern manufacturing corridor drive volume concentration for both gasoline and hybrid powertrains.
- Commercial Vehicles:Fleet operators negotiate multi-year single-source agreements for standardized specifications. Extended replacement intervals under EPA emissions enforcement create service-contract revenue pools for suppliers with national distribution networks.
- Electric Vehicles:Retain auxiliary 12-volt starting batteries for safety-critical systems separate from traction packs. Hybrid commercial vehicles require starting batteries alongside electric drive components.
- Motorcycles:Compact form factors favor sealed lead-acid and small lithium-ion packs. India's BIS certification restrictions strengthen domestic manufacturing positions for local suppliers.
Commercial Vehicles concentrate procurement power; Electric Vehicles expand the addressable market.
Technology:
Electrolyte management and cell construction methods determine maintenance requirements, mounting flexibility, and operating environment suitability.
- Flooded:Free-flowing sulfuric acid electrolyte requires upright mounting and periodic water replenishment. Aftermarket replacement channels in emerging markets favor this technology for first-cost sensitivity.
- VRLA:Valve-regulated lead-acid designs recombine gases internally for maintenance-free operation. Start-stop system proliferation drives OEM adoption where space constraints prohibit venting infrastructure.
- Lithium Polymer:Pouch cell construction enables packaging flexibility for cabin-mounted auxiliary batteries. Premium European passenger vehicles specify these for weight-critical micro-hybrid configurations.
- Gel:Silica-thickened electrolyte resists stratification and enables deep-cycle duty. Marine and recreational vehicle applications specify gel technology for vibration tolerance and occasional-use tolerance.
Flooded dominates replacement volume; VRLA captures OEM platform share.
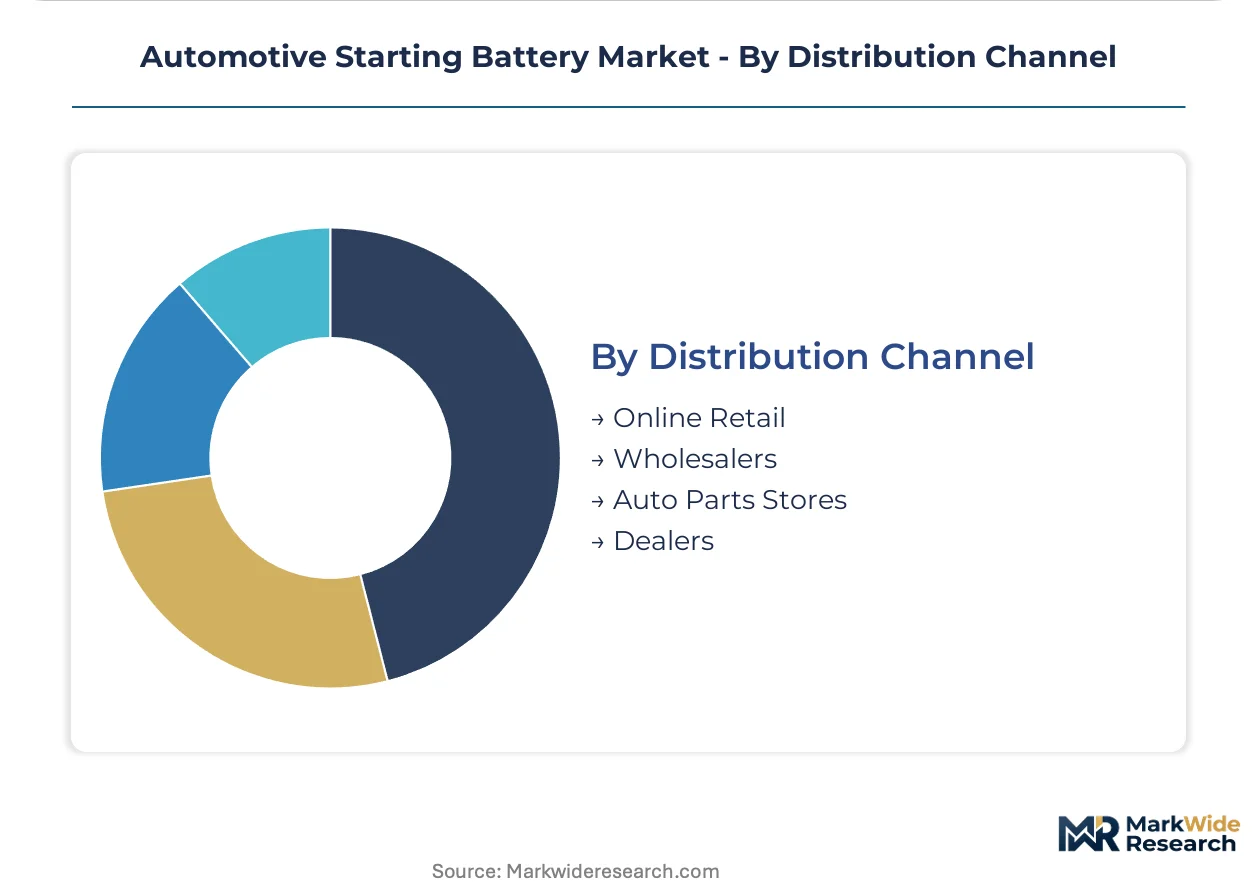
Distribution Channel:
Channel selection reflects purchase urgency, technical support requirements, and fleet procurement centralization trends.
- Online Retail:E-commerce platforms capture DIY replacement demand with specification lookup tools and competitive pricing transparency. Delivery speed competes with immediate availability at physical channels.
- Wholesalers:Independent repair shops and smaller fleet operators source through regional distributors carrying multiple brands. Inventory breadth and credit terms drive supplier selection.
- Auto Parts Stores:National chains provide immediate replacement for failed batteries with core exchange programs. Technical counter staff assist consumer specification matching.
- Dealers:OEM-authorized service networks handle warranty replacements and platform-specific battery programming. Start-stop system complexity elevates dealer share for newer vehicle populations.
Auto Parts Stores anchor volume throughput; Online Retail climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled battery formation technicians cluster around legacy manufacturing centers in Pennsylvania, Japan's Kansai corridor, and China's Jiangsu province, anchoring regional production capacity.
United States
Long-haul trucking fleets drive absorbed glass mat adoption for vibration resistance on rough terrain. EPA Tier 3 emissions enforcement compels start-stop system deployment across passenger and commercial platforms. Pennsylvania's Lehigh Valley hosts East Penn Manufacturing's foundry and formation facilities serving domestic OEM just-in-time contracts.
China
Local automakers in Jiangsu and Zhejiang provinces source starting batteries for gasoline-powered passenger vehicles alongside hybrid assembly lines. MIIT enforces GB standards for battery recycling traceability, mandating digital tracking from manufacture through recovery. Henan and Anhui provinces concentrate secondary lead smelters, creating geographic supply risk from environmental enforcement actions.
Germany
Premium passenger vehicle manufacturers specify lithium-ion packs for micro-hybrid configurations where weight reduction justifies premium positioning. EU Battery Regulation traceability requirements for recycled content pressure suppliers to verify recovery chains. Stuttgart and Munich anchor OEM engineering centers driving chemistry selection for start-stop platforms.
Japan
Toyota and Honda assembly sites near Osaka and Nagoya anchor just-in-time battery contracts with plant-proximate suppliers. METI industrial policy supports domestic manufacturing scale against lithium-ion substitution pressure. Kyoto-based GS Yuasa Corporation exemplifies vertical integration into regional OEM supply chains.
India
BIS certification mandates for automotive batteries restrict import pathways and strengthen domestic manufacturing positions. Amara Raja expands capacity to capture replacement demand from motorcycle and passenger vehicle segments. Tamil Nadu and Haryana states concentrate assembly plants serving Maruti Suzuki and Hyundai domestic production.
Automotive Starting Battery Market Vendor Landscape
Top-tier vendors anchor OEM just-in-time contracts, while mid-tier specialists capture aftermarket replacement volume through regional distribution networks. The vendor base stratifies across vertically integrated lead smelter operators, technology licensors, and pure-play assemblers. Three archetypes dominate: captive recyclers controlling raw material supply, formation specialists with acid-handling expertise, and diversified industrials spanning multiple chemistries. Competitive moves concentrate on capacity co-location near OEM assembly sites and backward integration into secondary lead recovery.
Among North American vertically integrated manufacturers, Clarios and East Penn Manufacturing Company represent the captive recycler archetype with smelter networks securing feedstock cost stability. GS Yuasa Corporation anchors the Japanese precision-formation tier with plant proximity to Toyota and Honda assembly corridors. These three exemplify how geographic co-location with OEM engineering centers and control over secondary material flows construct defensible positioning against commodity price volatility.
| Leading Market Players |
|---|
| Clarios |
| Exide Technologies |
| GS Yuasa Corporation |
| East Penn Manufacturing Company |
| Johnson Controls |
| Robert Bosch GmbH |
| Panasonic Corporation |
| Amara Raja |
| Crown Battery Manufacturing |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists anchor lead-acid battery production across Pennsylvania's Lehigh Valley and China's Jiangsu corridor, translating captive smelter ownership into pricing discipline that resists commodity lead volatility. Their control over secondary lead recovery networks insulates contract pricing from spot market swings while forcing unintegrated assemblers toward thinner margins.
Pricing Analysis
Bundled core-exchange programs versus unbundled battery-only transactions split pricing architectures across aftermarket channels. Three-tier pricing structure across premium AGM, standard VRLA, and economy flooded levels reflects cold-cranking performance certification and vibration-resistance ratings. Cost compression in flooded lead-acid intensifies because Chinese OEMs pressure suppliers for gasoline-vehicle platform sourcing. DIY consumers at auto parts stores exhibit highest price sensitivity, while long-haul fleet procurement teams prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with secondary lead smelter concentration in Henan and Anhui provinces, where environmental enforcement actions disrupt regional material flows without warning. Battery manufacturing draws from Australian primary lead concentrate, Chinese secondary smelter output, and Korean separator membrane production. Tariff exposure on Chinese-sourced lead oxide strains margin structures for North American assemblers lacking captive recycling. Distribution runs through national auto parts chains with immediate availability guarantees, bypassing slower wholesale channels for emergency replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory pressure into structural demand expansion, with EPA Tier 3 tailpipe standards forcing start-stop system deployment across passenger and commercial platforms regardless of fuel price cycles.
For Market Incumbents: Anticipate lithium-ion substitution in European and Japanese premium passenger segments by deepening AGM capacity for North American commercial fleet contracts. Secure formation technician pipelines through Pennsylvania and Jiangsu training partnerships before skill scarcity constrains expansion. Backward integration into secondary lead smelting remains the priority defensive lever against feedstock volatility. For New Entrants and Emerging Players: Independent repair shops in India's Tamil Nadu and Haryana manufacturing belts represent an underserved buyer archetype bypassed by national auto parts chains. Capture BIS-certified assembly capacity before import restrictions harden. Lead with mobile installation services and core-collection logistics that incumbent distributors neglect. For Investors and Strategic Acquirers: Valuations sit cheapest among single-chemistry assemblers lacking recycling infrastructure, as integrated competitors widen margin spreads during lead price spikes. Five-to-ten-year viability hinges on dual-chemistry platform capability spanning lead-acid and lithium-ion. Monitor EPA enforcement intensity on commercial fleet emissions as the inflection signal for accelerated replacement cycle demand.| Strategic Initiative | Industry Significance |
|---|---|
| Secondary Lead Smelter Acquisition | Captive feedstock supply insulates margin structures against Australian concentrate volatility. |
| AGM Formation Facility Co-location | Plant proximity to Toyota and Honda assembly corridors secures just-in-time contract renewals. |
| Digital Recycling Traceability Platform | Blockchain-based lead provenance documentation satisfies China's MIIT GB standard enforcement. |
| Multi-Chemistry Engineering Validation | Parallel lead-acid and lithium-ion charging algorithm development reduces OEM inventory complexity. |
| Commercial Fleet Service Contract Expansion | Extended replacement interval guarantees under EPA enforcement create recurring revenue pools. |
Methodological Framework
Bottom-up vehicle platform modeling reconciled against top-down smelter capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, aftermarket distributor procurement heads, secondary lead smelter operations managers, and commercial fleet maintenance directors combined with secondary validation from EPA enforcement databases, NHTSA CAFE compliance filings, China MIIT GB standard documentation, and vehicle production registration data. Triangulation between demand-side battery specifications and supply-side formation capacity ensures segment-level precision.
Input-output matrices map chemistry-specific content per vehicle across passenger, commercial, and hybrid electric platforms, with value outputs derived from contract pricing disclosures and spot lead market indices. Segmentation dimensions include product chemistry, electrolyte management technology, end-use vehicle class, and distribution channel structure. CAGRs emerge from modeled replacement cycle compression under emissions enforcement and fleet electrification pathways. Forecast inputs incorporate MIIT recycling traceability compliance costs and BIS certification barrier effects on import competition.
Underlying measurement precision varies by segment; aftermarket replacement volume carries tighter precision than emerging lithium-ion start-stop penetration estimates. Forecasts reflect documented assumptions about EPA enforcement continuity, lead price volatility bands, and OEM platform standardization timelines. Specific risk factors include accelerated lithium-ion cost reduction disrupting lead-acid share, sudden environmental enforcement halting Chinese smelter output, and trade policy shifts affecting concentrate supply. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Romania Rechargeable Battery Market
Batteries
Vanadium Redox Batteries Market
Batteries
Yacht Battery Market
Batteries
Forklift Battery Market
Batteries
Redox Flow Battery Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
North Africa Battery Market
Batteries
Zinc-Ion Battery Cells Market
Batteries
Automotive Start-Stop Battery Market
Batteries
South America Rechargeable Battery Market
Batteries
Grid-Scale Battery Market
Batteries
Europe Industrial Battery Market
Batteries
East Africa Battery Market
Batteries
Aluminium-Sulfur Battery Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Thin Film Photovoltaic and Batteries Market