
 Behind-The-Meter (BTM) Battery Market | 2026-2036
Behind-The-Meter (BTM) Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Behind-The-Meter (BTM) Battery Market Outlook
Lithium iron phosphate chemistry is fragmenting the technology stack as developers move away from nickel-cobalt configurations toward safer, longer-cycle alternatives. Tesla, Inc. leverages its integrated software-hardware ecosystem to control residential installation workflows. LG Energy Solution Ltd. anchors utility-scale deployments through manufacturing scale in Michigan and Arizona. Samsung SDI Co., Ltd. competes in premium commercial segments with high-density pouch cell architectures.
Behind-the-meter batteries are electrochemical storage systems installed on the customer side of the utility meter, typically rated from five kilowatt-hours to multiple megawatt-hours, designed to store electricity for later discharge during peak pricing periods or grid outages. The lithium-ion product category dominates current deployments due to declining cell costs and established recycling infrastructure, while flow batteries occupy niche industrial applications requiring daily deep cycling without degradation. Residential end users represent the fastest-growing segment as net metering revisions in multiple states push homeowners toward self-consumption models, though industrial customers retain the deepest margin pools through demand charge management.
The US Federal Energy Regulatory Commission shapes interstate market participation rules for distributed storage aggregations, while state-level public utility commissions in New York and Massachusetts mandate storage targets within clean energy standards. The EPA's greenhouse gas reporting requirements for commercial buildings indirectly accelerate BTM adoption as tenants seek emissions reductions. Stakeholders must monitor evolving interconnection standards and wholesale market tariff reforms that determine whether aggregated battery fleets capture full capacity value streams.
Market Dynamics
The US Inflation Reduction Act's standalone storage investment tax credit is restructuring project economics by decoupling battery incentives from solar pairing requirements, accelerating deployment timelines for commercial and industrial adopters seeking demand charge arbitrage.
Growth Catalysts
- Time-of-use rate structures:California's Pacific Gas & Electric and Southern California Edison tariffs create 4-6 hour daily price spreads that compress BTM battery payback periods below five years for commercial building operators.
- FERC Order 2222 implementation:Distributed storage aggregations now qualify for wholesale capacity markets across US independent system operators, unlocking stacked revenue streams from energy, ancillary services, and capacity payments.
- Lithium iron phosphate chemistry maturation:Cell suppliers in Michigan and Arizona have achieved 6,000+ cycle life ratings at 80% depth of discharge, eliminating cobalt supply chain exposure while reducing thermal runaway risk for indoor commercial installations.
Market Restraints
- Transformer upgrade bottlenecks:Pacific Gas & Electric's interconnection queue in California's Central Valley extends 18-24 months for commercial projects exceeding 500 kW, freezing capital deployment.
- Lithium carbonate price volatility:Australian spodumene concentrate contract pricing swings of 40% annually transmit directly to battery pack costs, eroding developer margin predictability on fixed-price EPC contracts.
- Fire code fragmentation:NFPA 855 adoption varies across California counties, with Los Angeles County requiring 4-hour fire-rated enclosures while neighboring jurisdictions mandate only 2-hour ratings, complicating standardized product design.
Strategic Opportunities
- Virtual power plant aggregation:Tesla's Autobidder platform and Sunrun's Grid Services demonstrate residential fleet dispatch to ISO-NE and CAISO markets, creating software-margin opportunities independent of hardware sales.
- Massachusetts SMART program expansion:The Solar Massachusetts Renewable Target incentive adder for paired storage increases base compensation rates by $0.03/kWh for commercial projects, attracting national developers to the Northeast corridor.
- EV bidirectional charging convergence:Ford F-150 Lightning and Hyundai Ioniq 5 vehicle-to-home capabilities are hybridizing transportation and stationary storage assets, enabling residential customers to defer dedicated battery purchases.
Industry Challenges
- Commissioning engineer scarcity:The North American Board of Certified Energy Practitioners storage certification pathway has produced fewer than 3,000 certified installers nationwide, constraining deployment velocity for commercial projects requiring utility intercoordination.
- Revenue stacking complexity:Developers must simultaneously optimize for demand charge reduction, time-of-use arbitrage, and wholesale market participation across incompatible software platforms, increasing operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Behind-The-Meter (BTM) Battery Market |
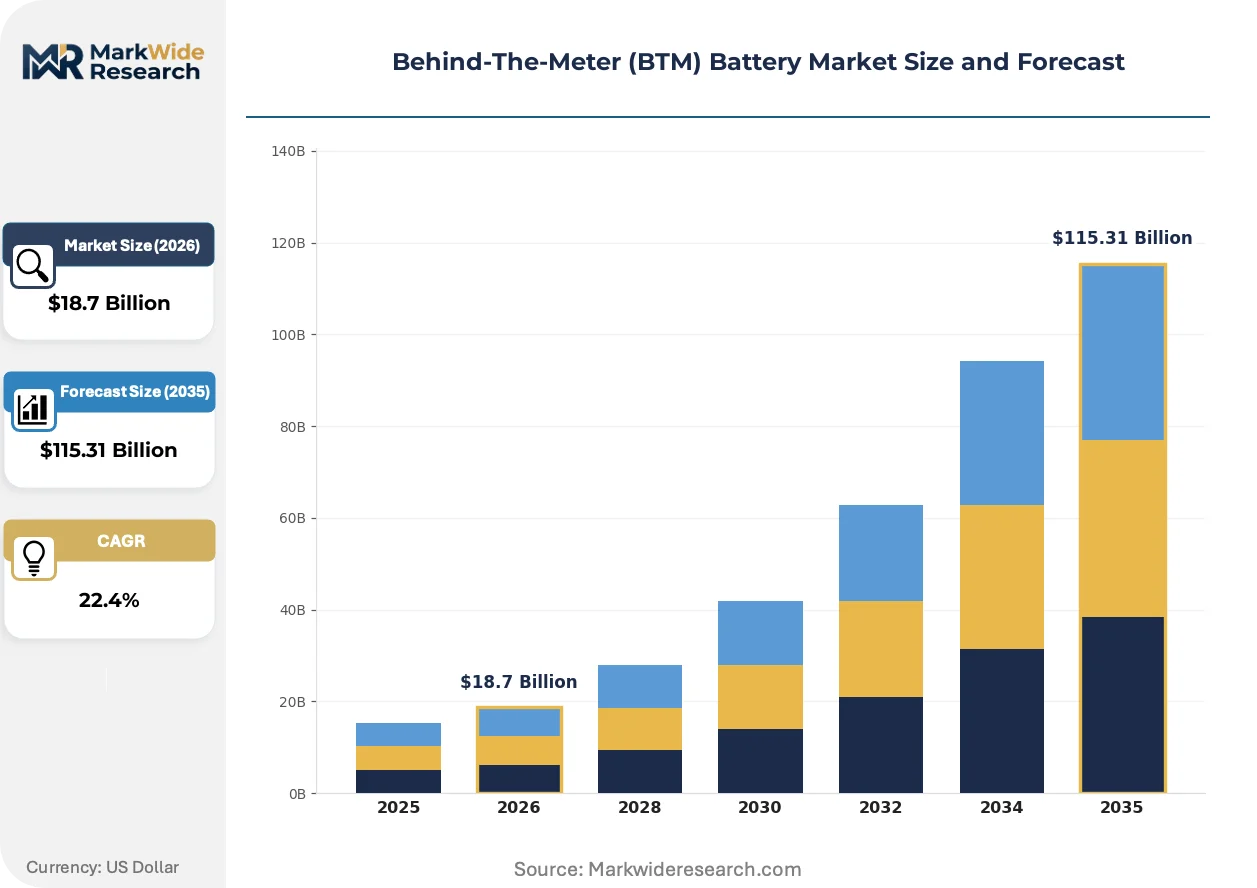
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Flow Batteries, Sodium-ion End User: Residential, Commercial, Industrial, Utilities Technology: Grid-tie, Off-grid, Hybrid, Virtual Power Plant Installation Type: Standalone, Integrated System, Networked, Others |
| Companies Covered | Tesla, Inc., LG Energy Solution Ltd., BYD Company Ltd., Enphase Energy, Inc., Schneider Electric SE, Panasonic Holdings Corporation, SolarEdge Technologies, Inc., Siemens AG, Samsung SDI Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Behind-The-Meter (BTM) Battery Market Strategic Shifts
Solid-state electrolyte research and artificial intelligence-driven predictive control systems are converging to redefine battery system architecture, while regulatory frameworks race to accommodate aggregated distributed resources.
Lithium metal anodes paired with sulfide-based solid electrolytes are hybridizing conventional lithium-ion manufacturing with next-generation energy density targets. Solid Power and QuantumScape pilot lines in Colorado and California are supplying automotive-qualified cells for stationary storage evaluation. This convergence is compressing the performance gap between automotive and grid-scale battery specifications, enabling shared component sourcing.
The EPA's greenhouse gas reporting requirements for commercial buildings exceeding 25,000 metric tons CO2 equivalent annually are mandating granular electricity consumption disclosure. Building owners in New York and Massachusetts must now report hourly meter data, creating audit trails that favor on-site storage for emissions reduction claims. Industrial tenants in these states are inserting storage requirements into lease negotiations to secure green building certifications.
Third-party ownership structures are displacing direct capital purchases among commercial building operators. Sunnova and Sunrun lease-to-own contracts now cover 60% of residential deployments in California, with similar models penetrating the commercial segment through power purchase agreement variants. This financing shift concentrates credit risk with national installers while transferring operational responsibility away from facility managers.
Behind-The-Meter (BTM) Battery Market Segmentation
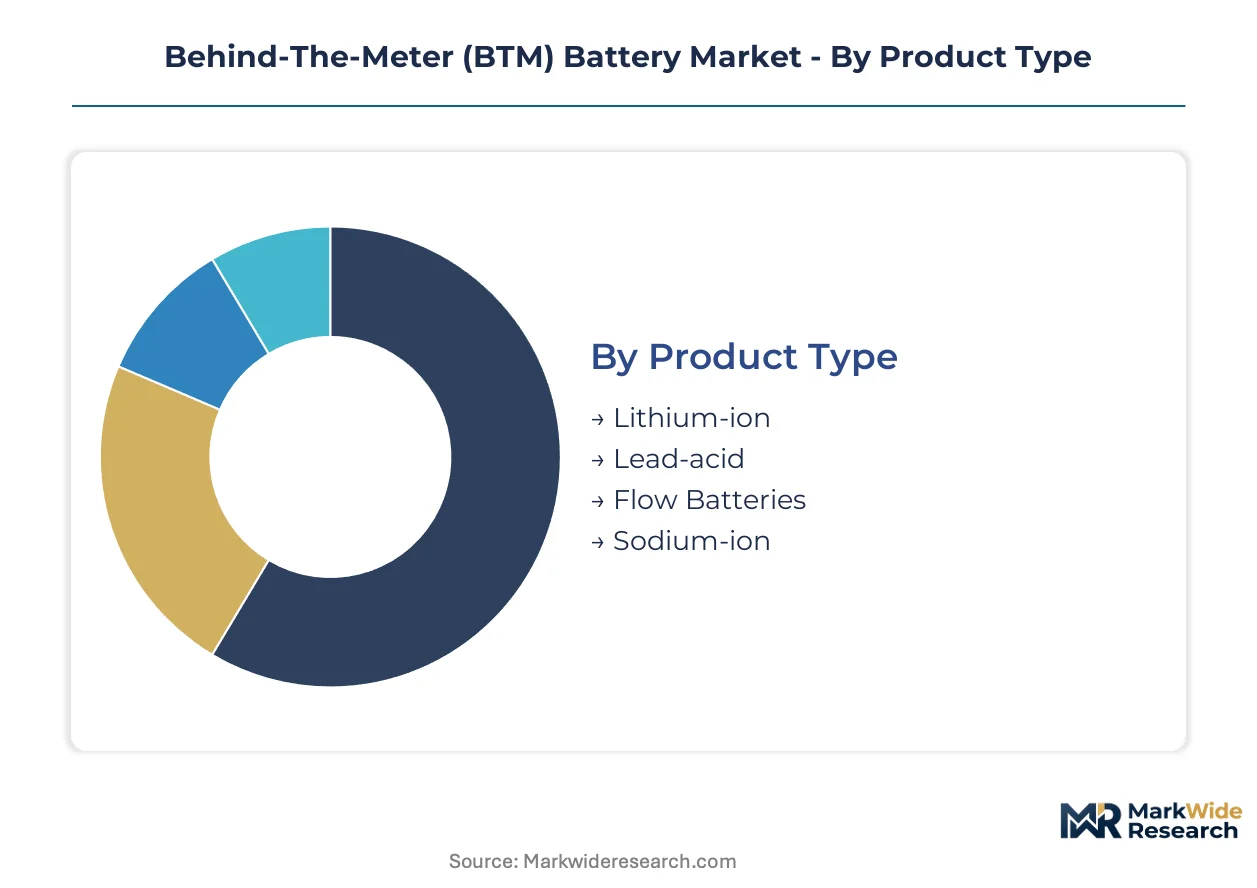
Segmentation in the BTM battery market reveals distinct technology-cost-performance tradeoffs that shape procurement decisions across customer tiers. Chemistry selection, end-use application, and grid-interconnection strategy each create divergent margin structures and deployment timelines.
Product Type:
Chemistry choice determines cycle life, thermal safety, and supply chain exposure for installers and operators.
- Lithium-ion:Dominates deployments through lithium iron phosphate and nickel-manganese-cobalt variants offering 4,000-6,000 cycle ratings at 80% depth of discharge. California commercial building operators favor this chemistry for indoor installations where NFPA 855 fire codes apply, though lithium carbonate price volatility from Australian spodumene contracts compresses developer margins on fixed-price EPC agreements.
- Flow Batteries:Vanadium and zinc-bromine configurations enable daily deep cycling without capacity fade, suiting industrial microgrids requiring 20+ year operational horizons. Demand concentrates in remote mining operations and data center campuses where replacement downtime costs exceed premium upfront capital.
- Lead-acid:Mature recycling infrastructure and low acquisition cost sustain niche residential backup applications in price-sensitive markets, though limited cycle life restricts economic viability beyond emergency standby use.
- Sodium-ion:Emerging chemistry eliminates lithium and cobalt supply constraints through abundant raw material inputs, with pilot deployments beginning in grid-scale buffering where energy density requirements remain modest.
Lithium-ion holds installed capacity. Sodium-ion is rotating up the share rankings.
End User:
Customer scale determines revenue stacking complexity and software integration requirements.
- Residential:Systems rated 5-20 kWh serve self-consumption models as net metering revisions in California and Hawaii push homeowners toward solar-plus-storage configurations. Sunrun and Sunnova lease-to-own contracts now dominate procurement, transferring operational risk to national installers.
- Commercial:Building operators pursue demand charge arbitrage and resilience through 100 kW-2 MW installations, with Pacific Gas & Electric time-of-use spreads compressing payback below five years for Class A office properties in San Francisco and Los Angeles.
- Industrial:Manufacturing campuses and cold storage facilities deploy multi-megawatt systems for peak shaving and power quality management, capturing the deepest margin pools through stacked revenue from wholesale market participation.
- Utilities:Distribution utilities aggregate behind-the-meter assets as non-wires alternatives to transformer upgrades, with FERC Order 2222 enabling capacity market qualification for distributed storage fleets.
Commercial applications are climbing the fastest. Residential is gaining share fastest among new deployments.
Technology:
Grid-interconnection architecture shapes software requirements and regulatory compliance burdens.
- Grid-tie:Systems synchronize with utility frequency for net metering export and time-of-use arbitrage, requiring IEEE 1547-compliant inverters and intercoordination with local distribution operators.
- Off-grid:Islanded configurations serve remote properties and critical facilities where grid extension costs prove prohibitive, demanding oversized battery capacity to cover multi-day autonomy periods.
- Hybrid:Dual-mode operation enables seamless transition between grid-connected and islanded states, suiting resilience-focused commercial adopters in California wildfire-prone territories.
- Virtual Power Plant:Aggregated fleet dispatch through Tesla Autobidder and Sunrun Grid Services platforms qualifies residential and commercial batteries for ISO-NE and CAISO capacity markets, creating software-margin opportunities independent of hardware sales.
Grid-tie configurations hold installed capacity. Virtual Power Plant is rotating up the share rankings.
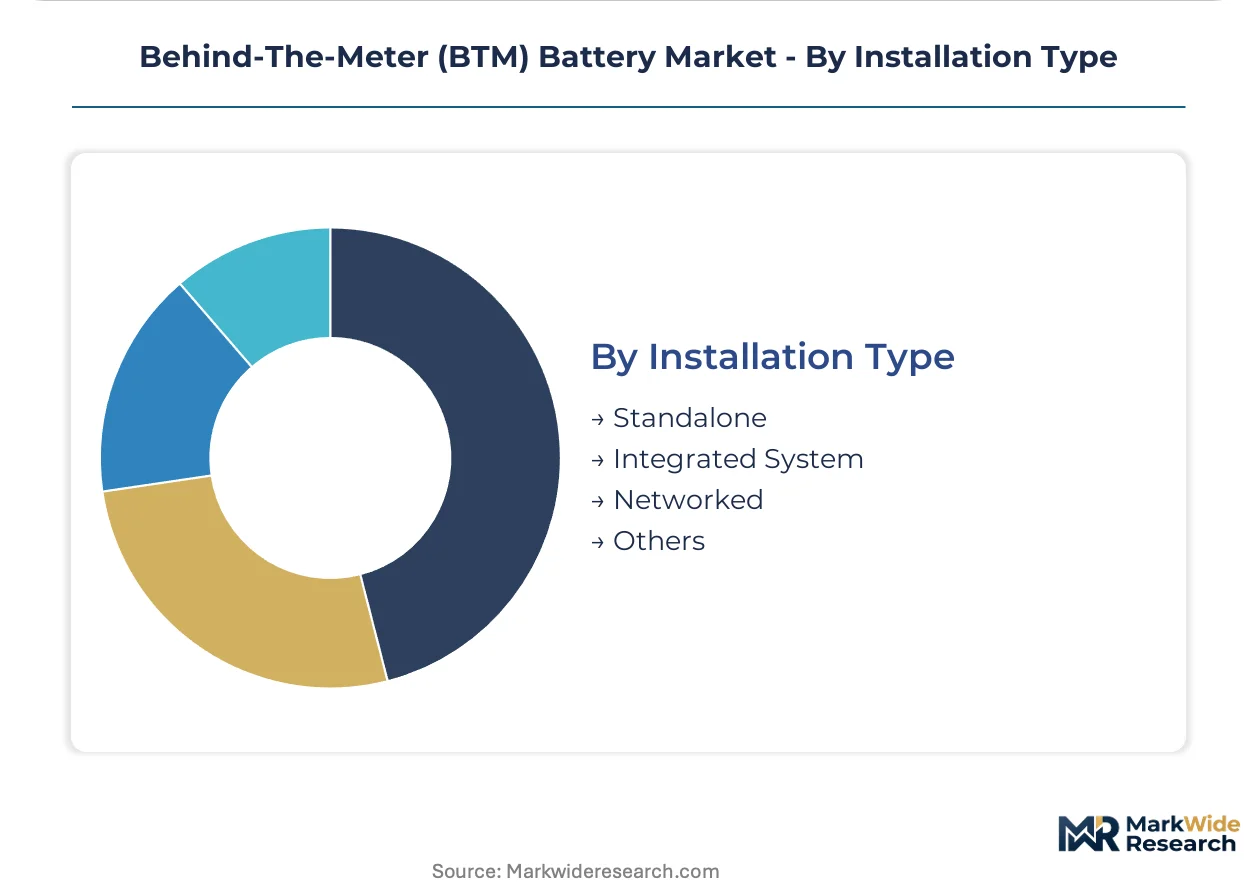
Installation Type:
System packaging determines project development velocity and standardization potential.
- Standalone:Decoupled storage assets qualify for the US Inflation Reduction Act's standalone investment tax credit, accelerating deployment timelines for commercial adopters no longer requiring solar pairing.
- Integrated System:Factory-assembled solar-plus-storage packages reduce field commissioning complexity and soft costs, dominating residential deployments where NABCEP-certified installer scarcity constrains deployment velocity.
- Networked:Fleet-managed installations enable coordinated dispatch and predictive maintenance, penetrating commercial segments where operational oversight justifies software subscription fees.
- Others:Custom-engineered solutions address specialized industrial applications with non-standard voltage requirements or hazardous location classifications.
Standalone installations hold installed capacity. Networked systems are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial BTM battery trade deficit, importing lithium cells from South Korean and Japanese suppliers while exporting integrated storage systems to Canada and Mexico. Domestic assembly capacity concentrates in Michigan and Arizona manufacturing corridors.
United States
California commercial building operators drive demand through Pacific Gas & Electric time-of-use arbitrage, with payback periods compressing below five years for Class A properties. The Inflation Reduction Act's standalone storage investment tax credit decouples battery incentives from solar pairing requirements. Tesla's integrated software-hardware ecosystem controls residential installation workflows across the San Francisco Bay Area and Los Angeles metropolitan clusters.
Germany
Industrial microgrid deployments accelerate as manufacturing campuses pursue power quality management and peak shaving. The EU Green Deal's storage targets within national energy and climate plans mandate gigawatt-hour scale buildouts by 2030. Bavarian automotive suppliers anchor demand in the Munich-Stuttgart corridor, integrating behind-the-meter assets with on-site renewable generation.
China
Dual carbon goals drive commercial and industrial storage adoption as grid operators incentivize demand-side flexibility. The National Energy Administration's distributed energy regulations enable aggregated battery participation in provincial power markets. Yangtze River Delta manufacturing hubs in Jiangsu and Zhejiang provinces concentrate deployment activity for export-oriented facilities.
South Korea
Utility-scale manufacturing scale supports both domestic deployment and export supply to North American markets. The Ministry of Trade, Industry and Energy's renewable energy certificate scheme rewards storage-paired solar installations. Metropolitan Seoul's dense commercial districts host premium high-density pouch cell architectures for space-constrained building retrofits.
Australia
Remote mining operations and data center campuses sustain flow battery demand for daily deep cycling without degradation. The Australian Energy Market Commission's rule changes enable distributed storage aggregation in wholesale markets. Western Australia's Pilbara region concentrates industrial deployments where grid extension costs prove prohibitive.
Behind-The-Meter (BTM) Battery Market Competitive Environment
On the supply side, the industry is consolidating around integrated technology stacks that couple hardware manufacturing with software control platforms. Tiered competitive positioning separates vertically integrated cell producers from system integrators and pure-play software aggregators. Dominant competitive moves include capacity expansion in Michigan and Arizona manufacturing corridors and strategic partnerships between automotive cell suppliers and stationary storage developers.
Within the integrated technology tier, Tesla, Inc. and LG Energy Solution Ltd. exemplify divergent geographic and segment strategies. Tesla's Autobidder platform represents the software-margin archetype independent of hardware sales, while LG Energy Solution Ltd. anchors utility-scale deployments through captive manufacturing presence. Samsung SDI Co., Ltd. occupies a position in premium commercial segments, completing a competitive map that spans residential, commercial, and industrial end-use categories.
| Leading Market Players |
|---|
| Tesla, Inc. |
| LG Energy Solution Ltd. |
| BYD Company Ltd. |
| Enphase Energy, Inc. |
| Schneider Electric SE |
| Panasonic Holdings Corporation |
| SolarEdge Technologies, Inc. |
| Siemens AG |
| Samsung SDI Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
The Port of Long Beach-San Pedro logistics corridor transmits container drayage and customs clearance costs directly into landed cell prices, amplifying pricing power for South Korean and Japanese suppliers while forcing California-based integrators toward premium tier positioning or volume-scaled contract structures.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with UL-certified lithium iron phosphate systems commanding spreads against uncertified alternatives. Price differentiation hinges on cycle life certification and software integration depth. Cost compression in the economy tier is intensifying because Australian spodumene contract volatility transmits downstream. Residential lease-to-own customers exhibit highest price sensitivity; utility-scale offtakers show lowest.
Supply Chain Analysis
Australian spodumene concentrate, Chilean lithium carbonate, and South Korean cathode active material feed into cell production concentrated in China, South Korea, and Japan. The North American assembly base draws from these inputs for pack integration in Michigan and Arizona manufacturing corridors. Single-source vulnerability in cobalt-free chemistry precursors creates structural exposure. Distribution runs through national installer networks and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as FERC Order 2222 implementation unlocks wholesale market participation for aggregated distributed assets, accelerating penetration beyond early-adopter commercial segments into mass-market residential deployment.
For Market Incumbents: Harden software control platform differentiation against automotive cell suppliers encroaching from adjacent mobility markets. Deepen captive supply of lithium iron phosphate cells through Arizona manufacturing expansion. Secure NABCEP certification pathways to lock installer channel access before scarcity constraints deployment velocity.
For New Entrants and Emerging Players: Build out virtual power plant aggregation capabilities in Massachusetts and New York regulatory corridors where incentive structures favor new software-first entrants. Target commercial building operators in wildfire-prone California territories seeking hybrid resilience configurations. Lead with subscription-based operational management rather than hardware sales.
For Investors and Strategic Acquirers: Carve-out targets emerge from automotive Tier 1 suppliers with stranded stationary storage divisions lacking software control layers. Long-term viability favors integrated technology stacks coupling hardware manufacturing with dispatch optimization platforms. Watch FERC interconnection rulemaking progress as the inflection signal for distributed resource market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Power Plant Platform Development | Tesla Autobidder and Sunrun Grid Services demonstrate software-margin capture independent of hardware sales in ISO-NE and CAISO markets. |
| Standalone Storage ITC Monetization | The Inflation Reduction Act's decoupled incentive accelerates commercial deployment timelines without solar pairing requirements. |
| Lithium Iron Phosphate Capacity Expansion | LG Energy Solution's Michigan and Arizona manufacturing corridors target 6,000+ cycle life ratings for indoor commercial installations. |
| Third-Party Ownership Model Penetration | Sunnova and Sunrun lease structures now cover residential procurement, transferring operational risk to national installers. |
| NABCEP Certification Pathway Investment | Storage installer scarcity below 3,000 certified practitioners nationwide constrains commercial deployment velocity. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EIA deployment databases, FERC regulatory filings, and utility interconnection queue records. The research program combined structured interviews with IPP project developers, EPC contractors, utility planning officers, and grid operators with bottom-up triangulation against top-down market sizing.
Forecast inputs span chemistry type, end-user scale, grid-interconnection architecture, and installation packaging across the analysis window. Segmentation dimensions include product chemistry, customer tier, technology configuration, and ownership structure. CAGRs were derived from installed capacity buildout trajectories and project development pipeline analysis, incorporating Inflation Reduction Act incentive phase-in schedules and state-level storage mandate progression.
Stress conditions across lithium carbonate price bands, interconnection queue durations, and fire code adoption timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding FERC Order 2222 implementation pace and state utility commission rulemaking calendars. Cross-checking against EIA Annual Energy Outlook storage projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
Global Bio Compatible Battery Market
Batteries
Primary Lithium Battery Market
Batteries
Battery Separators Market
Batteries
Electric Battery Market
Batteries
Battery Simulator Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Battery Swapping Market
Batteries
Floor Scrubber Battery Market
Batteries
Zinc Carbon Battery Market
Batteries
Secondary Battery Market
Batteries
Battery Coolant-Antifreeze Refractometer Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
48 Volt Battery System Market
Batteries
South and Central America Battery Market