
 Maintenance-Free Lead-Acid Battery Market | 2026-2036
Maintenance-Free Lead-Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Maintenance-Free Lead-Acid Battery Market Insights
Aftermarket distribution networks for replacement automotive batteries is reconfiguring around consolidated logistics hubs and direct OEM partnerships. Clarios leverages its vertically integrated recycling infrastructure to secure raw material access across North American and European supply corridors. EnerSys competes through specialized industrial energy storage applications, anchoring its position in mission-critical backup power systems. GS Yuasa dominates Asian original equipment channels, extending its manufacturing footprint to serve Japanese and Southeast Asian automotive assembly plants.
Maintenance-free lead-acid batteries employ sealed recombinant designs that immobilize electrolyte within absorbed glass mat or gel matrices, eliminating water loss and enabling operation in any orientation without terminal corrosion. Their primary purpose centers on delivering reliable starting, lighting, and ignition power alongside deep-cycle reserve capacity for vehicles, uninterruptible power supplies, and off-grid renewable installations. AGM product types command the largest installed base across automotive and UPS applications, where vibration resistance and high-rate discharge performance justify premium positioning. Gel cell configurations occupy niche marine and remote telecom roles, sustaining margins through low self-discharge and extended temperature tolerance. Deep cycle variants are gaining share in renewable energy storage as solar and wind installations require durable daily cycling capability.
Federal EPA guidelines in the United States mandate closed-loop lead recycling, directly shaping battery collection infrastructure and manufacturing cost structures for domestic producers. ECHA REACH restrictions in Europe limit hazardous substance content, compelling reformulation of separator materials and casing compounds to maintain market access. China's MIIT enforces GB standards for battery performance and environmental compliance, creating certification barriers for imported products. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional recycling quotas that will determine competitive positioning in maintenance-free lead-acid supply chains.
Market Dynamics
Sealed recombinant designs are displacing conventional flooded batteries across automotive assembly lines as OEMs confront REACH-mandated recycling quotas and vibration-resistant performance requirements. The technology shift compresses water-refill service revenue while redistributing margin toward separator material suppliers and closed-loop recyclers.
Growth Catalysts
- EU Green Deal battery mandates:REACH and the EU Green Deal accelerate OEM transitions to maintenance-free designs by penalizing flooded battery disposal and rewarding sealed-cell recyclability across passenger vehicle platforms.
- Telecom backup power expansion:Remote 5G base station deployments in Southeast Asia absorb gel-cell configurations for temperature-tolerant deep cycling in off-grid installations.
- Absorbed glass mat advances:Improved AGM separator porosity extends cycle life for start-stop vehicle applications, justifying premium positioning in compact car segments.
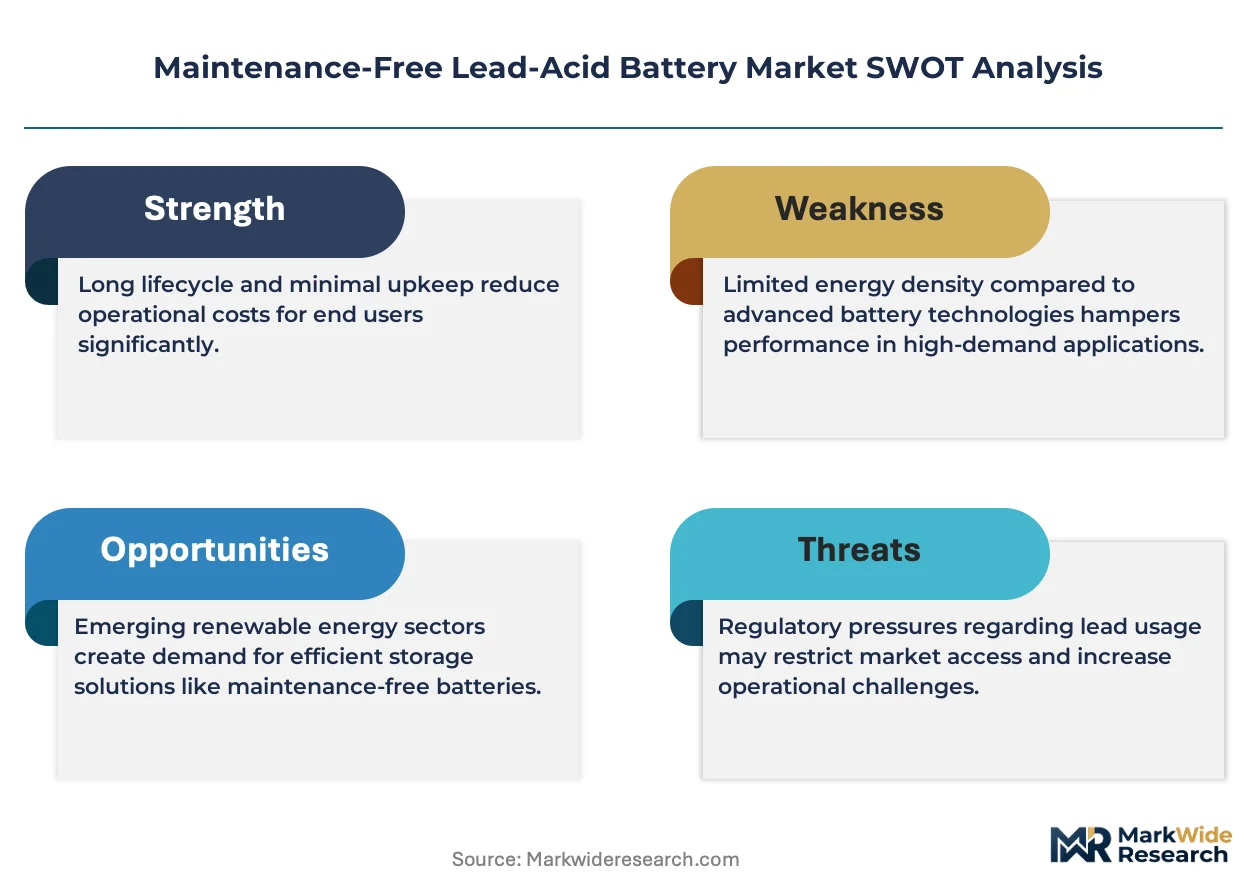
Market Restraints
- Lead price volatility:Primary lead ingot costs fluctuate with LME trading patterns, compressing margin predictability for battery assemblers dependent on spot-market raw material procurement.
- Chinese production concentration:Domestic manufacturing clusters under MIIT oversight supply over half of global AGM capacity, creating geographic supply risk for non-Chinese OEMs.
- Lithium-ion substitution:Falling lithium iron phosphate pack costs erode lead-acid's historical cost advantage in residential solar storage applications.
Strategic Opportunities
- Indian renewable microgrids:Village-level solar installations under CEA rural electrification programs represent underpenetrated demand for deep-cycle maintenance-free storage.
- Marine lithium-lead hybridization:Yacht builders combine lithium propulsion banks with lead-acid house batteries to balance energy density against fire-safety certification requirements.
- US closed-loop recycling infrastructure:EPA-mandated collection networks create captive feedstock access for domestic smelters with backward integration into battery manufacturing.
Industry Challenges
- Separator material certification delays:ECHA substance-of-very-high-concern screenings extend qualification timelines for new AGM glass-mat formulations.
- Legacy charging system incompatibility:Start-stop vehicle electrical architectures require voltage-regulation recalibration, complicating aftermarket replacement battery fitment.
- Specialized electrochemistry talent scarcity:Recombinant cell design expertise concentrates among retiring engineers at Japanese and European incumbent manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maintenance-Free Lead-Acid Battery Market |
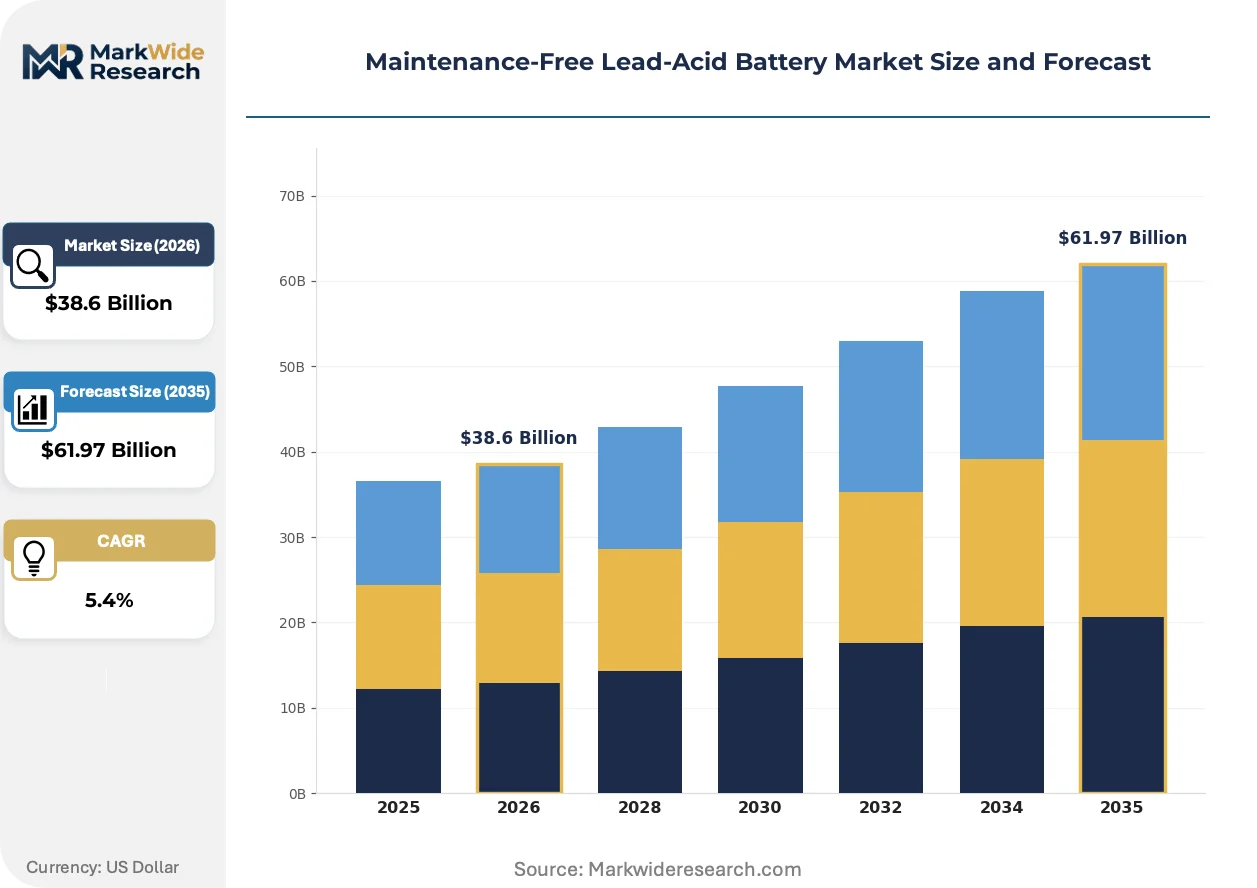
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AGM, Gel Cell, SLI, Deep Cycle Application: Automotive, UPS, Renewable Energy, Telecommunications End User: Consumer Electronics, Industrial Equipment, Automotive OEMs, Marine Installation: Fixed, Portable, Modular, Grid-Tied |
| Companies Covered | Clarios, EnerSys, Exide Industries, GS Yuasa, East Penn Manufacturing, Amara Raja Batteries, CSB Energy Technology, Fiamm, Power Sonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maintenance-Free Lead-Acid Battery Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to redefine cell construction and end-of-life recovery protocols. The competitive frontier shifts toward separator innovation and recycling yield rates rather than incremental capacity scaling.
Thin-film ceramic coatings on AGM separators is hybridizing traditional glass-mat construction with solid-state electrolyte concepts. Start-stop vehicle OEMs in Germany and South Korea are qualifying these formulations for 60,000-cycle durability targets. The technology is hybridizing cost structures by reducing lead active material requirements while increasing separator unit value capture.
China's MIIT enforcement of GB/T 32504 performance standards and carbon-intensity disclosure rules is compelling domestic exporters to document lifecycle emissions for EU-bound shipments. Battery manufacturers must retrofit smelter operations with MEE-monitored emission controls to maintain market access. European importers now demand third-party carbon verification alongside traditional capacity warranties.
Fleet operators are consolidating replacement battery procurement through direct OEM partnerships rather than fragmented distributor networks. Commercial vehicle leasing companies in North America negotiate multi-year supply agreements with fixed recycling credit terms. This concentration is most visible in long-haul trucking segments where total cost of ownership modeling favors predictable maintenance intervals over lowest unit pricing.
Maintenance-Free Lead-Acid Battery Market Segmentation
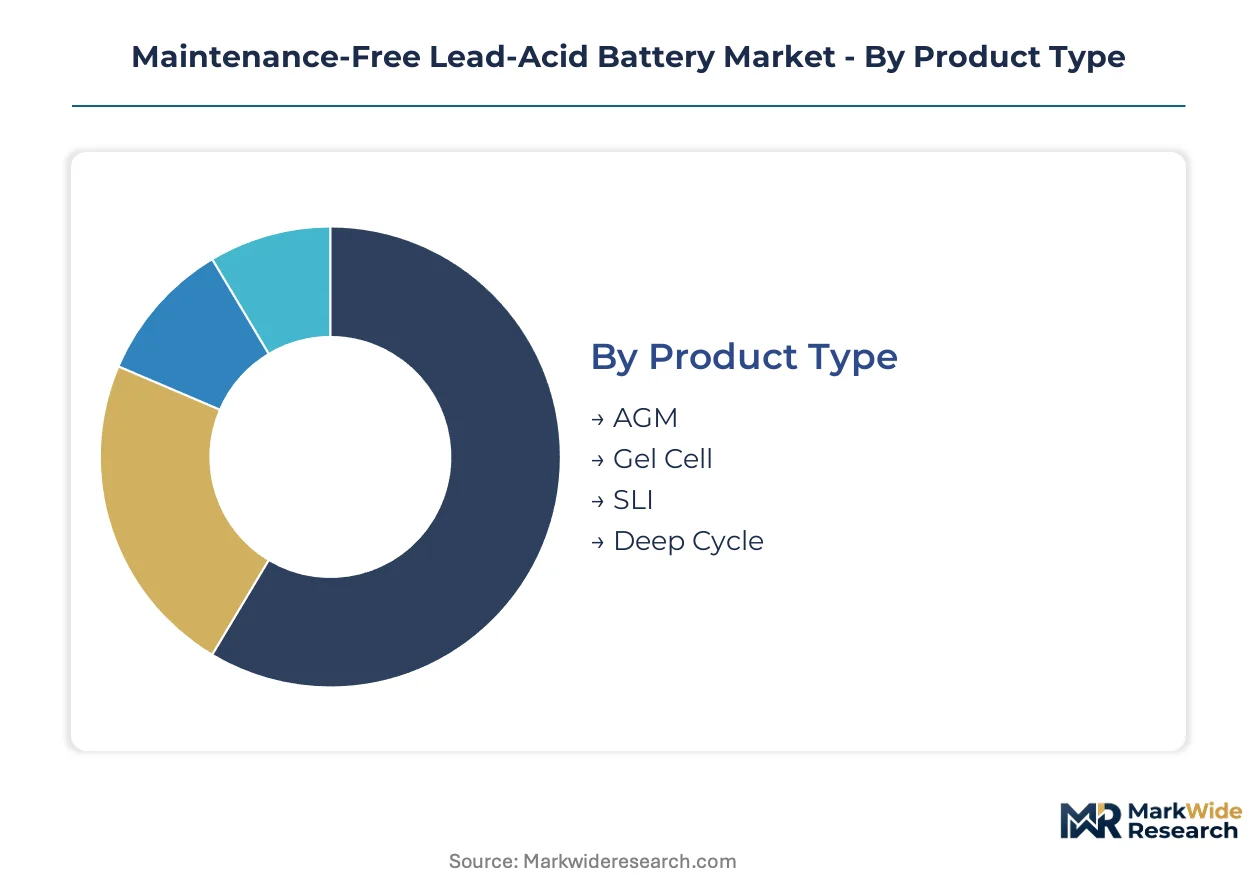
Segmentation in the maintenance-free lead-acid battery market reveals divergent replacement cycles and margin profiles across product architectures and end-use applications. Understanding these temporal patterns enables suppliers to align inventory positioning with demand velocity and warranty exposure.
Product Type:
Replacement intervals vary dramatically across sealed recombinant designs, from 3-5 year automotive SLI turnover to 10-15 year stationary gel cell deployments.
- AGM:Absorbed glass mat construction immobilizes electrolyte in microfiber separators, enabling high-rate discharge and vibration tolerance. Passenger vehicle start-stop systems in Germany and South Korea absorb the majority of OEM-specified AGM volume, driven by CO2 reduction mandates and engine-off coasting functionality.
- Deep Cycle:Thicker lead plates and optimized active material formulations sustain repeated 80% depth-of-discharge cycling. Solar-plus-storage microgrids in rural India under CEA electrification programs represent the steepest expansion trajectory, displacing diesel gensets in off-grid installations.
- Gel Cell:Silica-thickened electrolyte eliminates stratification and extends temperature tolerance for remote telecom towers.
- SLI:Starting-lighting-ignition configurations prioritize cold-cranking amps for conventional internal combustion engine starting duty.
AGM dominates installed base across automotive and UPS applications. Deep Cycle is where expansion concentrates as renewable integration accelerates.
Application:
Cost tier stratification separates mission-critical backup power premiums from commodity automotive replacement pricing.
- Automotive:OEM assembly line demand concentrates in AGM formats for start-stop vehicles, while aftermarket replacement favors cost-optimized SLI designs. European REACH recycling quotas and the EU Green Deal penalize flooded battery disposal, accelerating sealed-cell penetration across passenger and commercial vehicle platforms.
- UPS:Uninterruptible power supply installations require high-rate discharge capability and 5-10 year design life for data center and healthcare facility backup. EMEA enterprise infrastructure spending sustains premium pricing for AGM-based rack-mounted systems.
- Renewable Energy:Daily cycling duty for solar and wind storage favors deep-cycle lead-acid where lithium-ion cost premiums remain prohibitive.
- Telecommunications:Remote 5G base station deployments in Southeast Asia absorb gel-cell configurations for temperature-tolerant operation in off-grid installations.
Automotive commands the largest revenue pool. Renewable Energy is climbing the fastest as grid-edge storage deployments multiply.
End User:
Customer type determines procurement modality, from consolidated OEM supply agreements to fragmented distributor aftermarket channels.
- Automotive OEMs:Assembly line procurement runs through multi-year supply agreements with fixed recycling credit terms and total cost of ownership modeling. North American long-haul trucking fleet operators negotiate direct partnerships with Clarios and East Penn, bypassing traditional distributor networks.
- Industrial Equipment:Forklift, mining vehicle, and material handling applications demand vibration-resistant AGM configurations for harsh operating environments.
- Marine:Yacht builders combine lithium propulsion banks with lead-acid house batteries to balance energy density against fire-safety certification requirements from classification societies.
- Consumer Electronics:Niche applications include portable power stations and emergency lighting with limited volume concentration.
Automotive OEMs anchor volume demand. Marine is where hybrid battery architectures are gaining traction fastest.
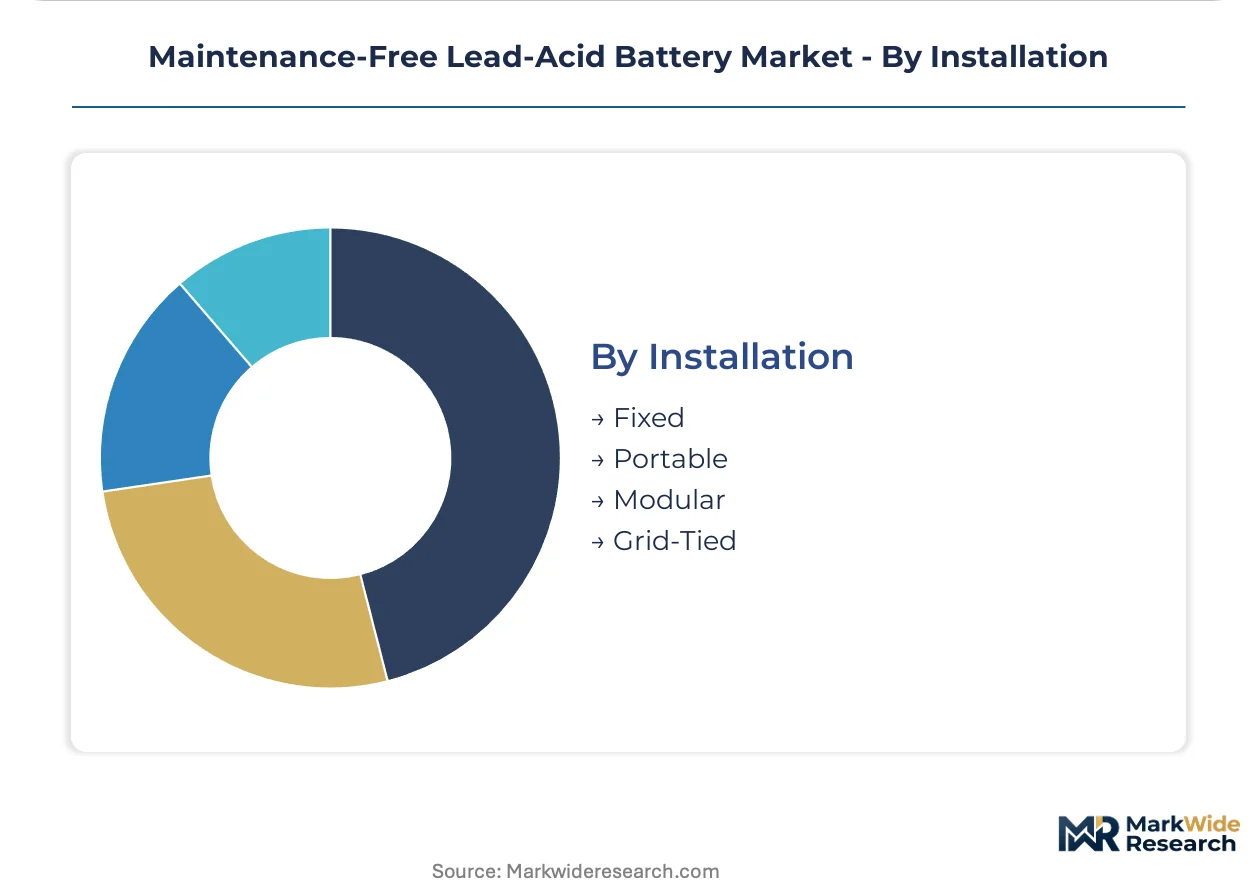
Installation:
Physical configuration dictates supply chain topology, from centralized factory integration to distributed field deployment.
- Fixed:Permanent rack-mounted installations dominate data center UPS and telecom central office applications, requiring engineered seismic bracing and thermal management.
- Modular:Containerized battery energy storage systems enable rapid deployment and capacity scaling for utility-scale solar farms.
- Portable:Mobile power units serve construction sites and emergency response with wheeled enclosure designs.
- Grid-Tied:Behind-the-meter installations for commercial demand charge management require utility interconnection approval and net metering compatibility.
Fixed installations represent the mature revenue base. Modular configurations are expanding most quickly as prefabricated energy storage standardizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers command pricing leverage through MIIT-supervised production clusters, while European assemblers absorb premium costs from ECHA REACH compliance and carbon border adjustments. This asymmetry redistributes margin toward raw material recyclers in North America.
China
Domestic OEM demand for start-stop AGM batteries absorbs the majority of regional capacity under MIIT's GB/T 32504 standards. The Yangtze River Delta manufacturing corridor concentrates separator material production and closed-loop smelter operations. Exporters now document lifecycle emissions for EU-bound shipments to satisfy emerging carbon verification requirements.
Germany
Automotive assembly lines at Stuttgart and Wolfsburg facilities specify AGM formats for CO2 reduction mandates and engine-off coasting functionality. KBA type-approval processes enforce vibration-resistance testing that favors sealed recombinant designs over conventional flooded alternatives. Bavarian industrial zones host specialized charging system calibration facilities for start-stop vehicle architectures.
United States
Long-haul trucking fleet operators negotiate direct supply agreements with fixed recycling credit terms under EPA closed-loop mandates. The Southeast manufacturing belt anchors domestic AGM assembly capacity serving Detroit Three automakers. Michigan-based R&D clusters address legacy charging system incompatibility through voltage-regulation recalibration protocols.
India
CEA rural electrification programs drive deep-cycle battery procurement for village-level solar microgrids displacing diesel gensets. Tamil Nadu and Gujarat host emerging assembly operations targeting renewable energy storage applications. BIS certification requirements for battery performance create qualification barriers for imported products.
Japan
Tokyo and Osaka metropolitan areas concentrate recombinant cell design expertise among incumbent engineering teams. METI industrial policy supports advanced separator material development for next-generation AGM porosity improvements. Kansai-region manufacturing plants serve Southeast Asian automotive assembly operations through extended supply corridors.
Maintenance-Free Lead-Acid Battery Market Competitive Landscape
Vertically integrated recyclers and specialized industrial fabricators split the market between captive raw material access and mission-critical application expertise. The structure concentrates around three strategic archetypes: closed-loop smelter-integrators, automotive OEM channel specialists, and industrial backup power engineers. Consolidation pressures favor multi-year supply agreements with fixed recycling terms over spot-market procurement. Geographic expansion and separator technology licensing represent the dominant competitive moves reshaping positioning.
Within the closed-loop recycling tier, Clarios anchors North American and European supply corridors through backward integration into smelter operations. EnerSys occupies a position among industrial backup power specialists serving data center and healthcare facility applications. GS Yuasa exemplifies the Asian OEM channel archetype with manufacturing footprint extension into Southeast Asian automotive assembly zones.
| Leading Market Players |
|---|
| Clarios |
| EnerSys |
| Exide Industries |
| GS Yuasa |
| East Penn Manufacturing |
| Amara Raja Batteries |
| CSB Energy Technology |
| Fiamm |
| Power Sonic Corporation |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta manufacturing corridor concentrates over half of global AGM separator production and closed-loop smelter capacity, granting Chinese exporters significant leverage over international pricing benchmarks. This geographic clustering compresses margins for non-integrated assemblers while amplifying volatility exposure for buyers dependent on spot-market lead procurement.
Pricing Analysis
Configured-to-order pricing for specialized AGM separators and gel formulations commands substantial premiums over standard SLI commodity offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under ECHA REACH and GB/T 32504 standards. Price differentiation stems from separator porosity specifications and volume scale commitments. Cost compression in economy-tier automotive replacement batteries is intensifying because Chinese production clusters leverage captive lead recycling. Fleet operators exhibit lowest price sensitivity due to total cost of ownership modeling, while independent aftermarket distributors face acute margin pressure.
Supply Chain Analysis
Export-control regimes under China's MIIT oversight restrict technology transfer for advanced AGM separator manufacturing processes, constraining capacity replication outside domestic clusters. Geographic supply concentration centers on China, South Korea, and Germany for separator materials and recombinant cell assembly. The supply chain draws from primary lead smelters, microfiber glass-mat suppliers, and silica gelling agents. Single-source vulnerability pervades thin-film ceramic coating technologies qualified for 60,000-cycle durability targets. Distribution runs through consolidated logistics hubs serving OEM assembly lines and fragmented distributor networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Closed-loop recycling mandates under EPA and REACH guidelines create structural barriers that substitute technologies cannot easily replicate.
For Market Incumbents: Insulate core margin pools by securing captive separator supply through backward integration into glass-mat manufacturing or long-term offtake agreements with Yangtze Delta suppliers. Deepen recycling infrastructure ownership to neutralize lead price volatility exposure. Lithium-ion substitution in residential solar storage represents the most acute threat requiring monitoring. For New Entrants and Emerging Players: Rural Indian solar microgrids under CEA electrification programs offer the most penetrable white-space target for deep-cycle maintenance-free configurations. Marine lithium-lead hybridization segments in Southeast Asian yacht construction present secondary entry points with lower certification barriers. A direct OEM partnership model bypassing traditional distributor networks accelerates initial traction. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized battery divisions lacking closed-loop recycling integration. Long-term viability hinges on regulatory durability of lead-acid chemistry exemptions in automotive start-stop applications and carbon border adjustment mechanics. Monitor ECHA substance-of-very-high-concern screening outcomes for separator material reformulation costs as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Infrastructure Expansion | EPA-mandated collection networks secure captive lead feedstock access for domestic smelters against LME volatility. |
| Advanced Separator Material Licensing | Thin-film ceramic coating technology transfers from Japanese engineering clusters enable 60,000-cycle durability qualification. |
| Direct OEM Supply Agreement Consolidation | Multi-year contracts with fixed recycling credit terms lock in fleet operator procurement for North American trucking. |
| Carbon Verification Documentation Investment | Third-party lifecycle emissions certification satisfies EU importer demands under emerging border adjustment mechanisms. |
| Rural Electrification Channel Development | CEA program alignment positions deep-cycle inventory for Indian village-level solar microgrid displacement of diesel. |
Research Methodology
A spread of perspectives from automotive OEM procurement directors, lead smelter operations managers, separator material R&D heads, and aftermarket distributor network leads converged on the working assumptions. Primary field engagement combined with secondary validation against MIIT GB standard filings, ECHA REACH substance registrations, EPA hazardous waste manifests, and customs trade flow data. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across product architectures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application vertical, end-user procurement modality, and installation configuration. CAGRs derived from regression analysis against vehicle production databases, renewable energy deployment trackers, and telecom infrastructure spend patterns. Lead price elasticity coefficients and separator material cost curves informed margin trajectory projections.
Practitioners should monitor ECHA SVHC screening outcomes, MIIT carbon-intensity disclosure enforcement, and lithium iron phosphate pack cost curves for early signals of forecast deviation. Material shifts in regulatory chemistry restrictions or substitute technology cost parity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Absorbent Glass Mat (AGM) Battery Market
Batteries
Nimh Battery Market
Batteries
Semi-Solid Flow Battery Market
Batteries
Battery Separators Market
Batteries
USA Forklift Battery Market
Batteries
Nickel Cadmium Battery Market
Batteries
North America Battery Market
Batteries
GCC Rechargeable Battery Market
Batteries
Battery Materials Market
Batteries
Liquid Metal Battery Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Global Primary Cells Market
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
Mobile Battery Market
Batteries
Middle-East Battery Market