
 High Temperature NiMH Battery Market | 2026-2036
High Temperature NiMH Battery Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature NiMH Battery Market Insights
China's expanding electrode manufacturing corridor is fragmenting as domestic and foreign producers race to secure thermal-grade cell capacity. Panasonic Holdings leverages its proprietary sintered electrode process to sustain premium positioning in aerospace-qualified cells. FDK Corporation anchors Japanese supply through dedicated high-temperature lines serving METI-backed industrial projects. BYD Company competes on scale, extending cylindrical output for downhole instrumentation.
High temperature NiMH batteries employ nickel hydroxide positive electrodes paired with hydrogen-absorbing alloy negatives, engineered to maintain electrochemical stability above 70°C through modified electrolyte formulations and ceramic-coated separators. Cylindrical cells dominate current military procurement due to established form-factor compatibility with legacy thermal battery replacement programs. Enhanced electrolyte technology represents the fastest-improving segment, as defense contractors demand wider operating windows for desert and subterranean deployment. Thermal management systems command margin concentration because integration with battery management electronics reduces system-level qualification costs for aircraft manufacturers.
Japan's METI enforces JIS standards for industrial battery safety, while China's SAMR administers GB certification for extreme-environment cells; both frameworks elevate barriers for uncertified suppliers seeking defense or aerospace qualification. The EU AI Act and CSRD indirectly shape procurement by requiring supply-chain traceability documentation from electronics makers sourcing for European industrial automation. Stakeholders must monitor evolving thermal runaway test protocols across multiple jurisdictions before committing to next-generation separator investments.
Market Dynamics
Defense procurement cycles are compressing qualification timelines for thermal-grade cells, forcing electrode manufacturers to front-load capital into dual-use production lines that satisfy both aerospace and downhole drilling specifications.
Growth Catalysts
- Downhole instrumentation demand:Oil and gas operators in the Permian Basin and North Sea are retrofitting measurement-while-drilling tools with high-temperature NiMH packs to replace primary lithium thermal batteries in extended-reach laterals.
- Japan's METI industrial battery incentives:Subsidies for domestic production of extreme-environment cells are accelerating capacity expansion at dedicated high-temperature lines serving defense and heavy industrial automation.
- Sintered electrode process maturation:Advances in controlled-atmosphere sintering are improving nickel hydroxide active material utilization above 85°C, extending cycle life for subterranean deployment.
Market Restraints
- Rare earth alloy supply concentration:Hydrogen-absorbing negative electrode formulations depend on lanthanum and cerium processed primarily through Chinese separation facilities, creating single-source vulnerability.
- GB certification timeline friction:China's SAMR has extended extreme-environment cell testing protocols to 18 months, delaying market entry for uncertified foreign suppliers seeking industrial automation contracts.
- Primary lithium thermal battery substitution:Solid-electrolyte lithium metal cells with 200°C+ operating windows are capturing military procurement share in applications requiring absolute energy density priority.
Strategic Opportunities
- German industrial automation corridor:Automotive press shops and steel rolling mills in the Ruhr region are standardizing on high-temperature NiMH for backup power in furnace-adjacent control systems.
- EU CSRD supply-chain traceability:Mandatory disclosure requirements are creating first-mover advantage for cell producers with documented conflict-mineral-free rare earth sourcing.
- Ceramic separator-ceramic coating convergence:Integration of zirconia-based separator substrates with alumina-coated current collectors is opening 120°C continuous operation for next-generation aerospace auxiliary power units.
Industry Challenges
- Electrochemical engineer talent scarcity:Specialized expertise in high-temperature electrolyte degradation mechanisms is concentrated among retiring researchers at Japanese national laboratories.
- Dual-use qualification capex intensity:Parallel MIL-STD-810 and IEC 62660 testing programs require redundant environmental chamber investments exceeding $4 million per facility.
- Legacy thermal battery replacement integration:Mechanical form-factor mismatches between cylindrical NiMH cells and obsolete lithium thermal battery housings demand custom adapter engineering for each aircraft platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature NiMH Battery Market |
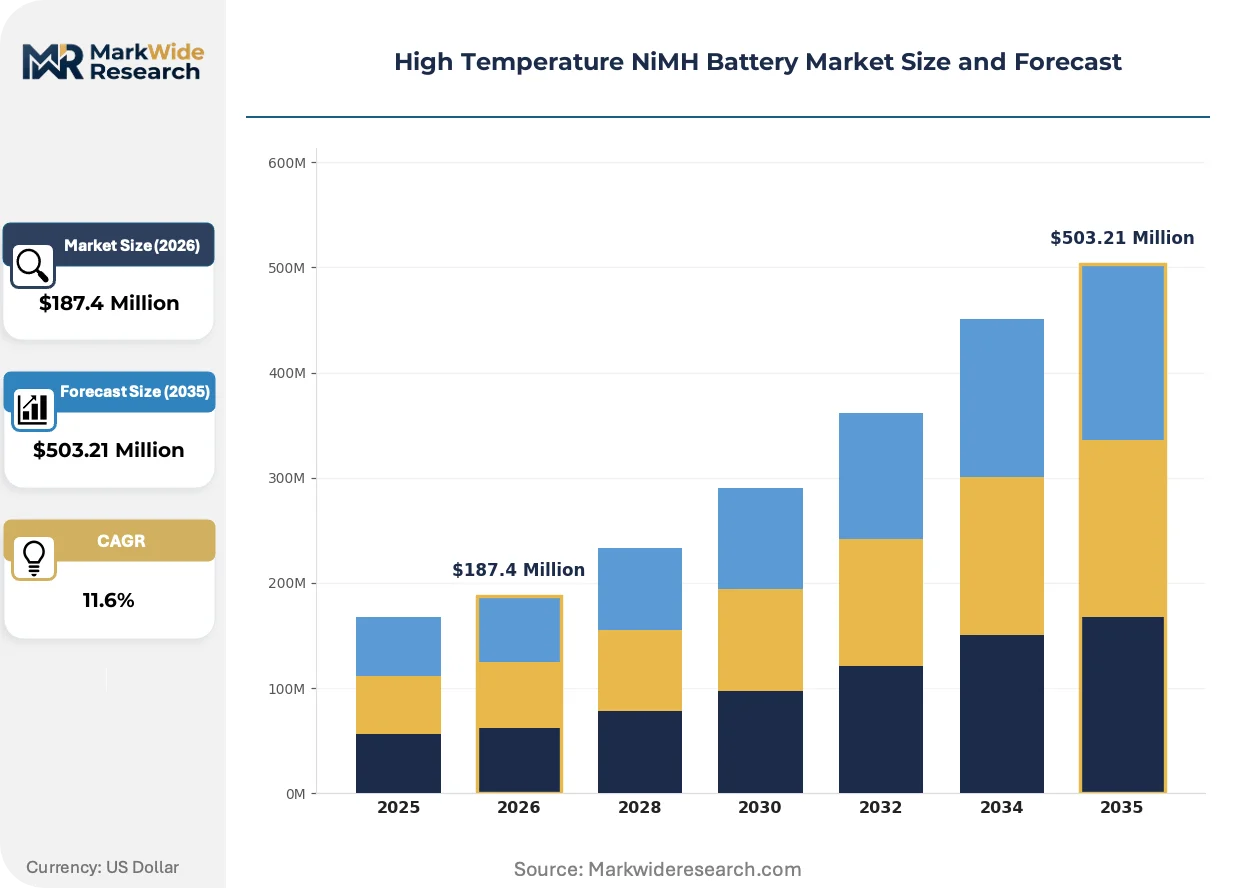
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical Cells, Prismatic Cells, Button Cells, Polymer Cells Technology: Advanced Electrode, Enhanced Electrolyte, Thermal Management Systems, Improved Separator Application: Military Devices, Aerospace Systems, Industrial Equipment, Consumer Electronics End User: Defense Contractors, Aircraft Manufacturers, Manufacturing Plants, Electronics Makers |
| Companies Covered | Panasonic Holdings, GS Yuasa, FDK Corporation, BYD Company, Energizer Holdings, Duracell, GP Batteries International, VARTA AG, Saft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature NiMH Battery Market Trends and Innovations
Solid-state electrolyte research is migrating from lithium-ion to NiMH architectures, while regulatory pressure on supply-chain provenance is rewriting procurement specifications for defense and aerospace buyers.
Advanced ceramic-coated separators with zirconia nanoparticle layers are rendering obsolete conventional polyolefin separators in downhole drilling applications. Oilfield service companies in the Permian Basin and North Sea are specifying these separators for measurement-while-drilling tools operating above 100°C. The technology is compressing battery replacement intervals from 90 days to 12 months in extended-reach laterals.
China's SAMR has tightened GB/T 36276 testing protocols for extreme-environment cells, mandating thermal runaway propagation resistance at 150°C ambient. Industrial battery pack assemblers must now submit separator material certificates of origin. German automotive suppliers sourcing for furnace-adjacent automation are delaying procurement decisions until third-party GB compliance documentation is available.
Defense contractors are consolidating supplier relationships around qualified cell producers with in-house electrode manufacturing. Long-term supply agreements with 5-year volume commitments are displacing spot purchasing for aerospace auxiliary power units. The shift is most visible in Japan, where METI-backed industrial projects require documented domestic content ratios above 60%.
High Temperature NiMH Battery Market Segmentation
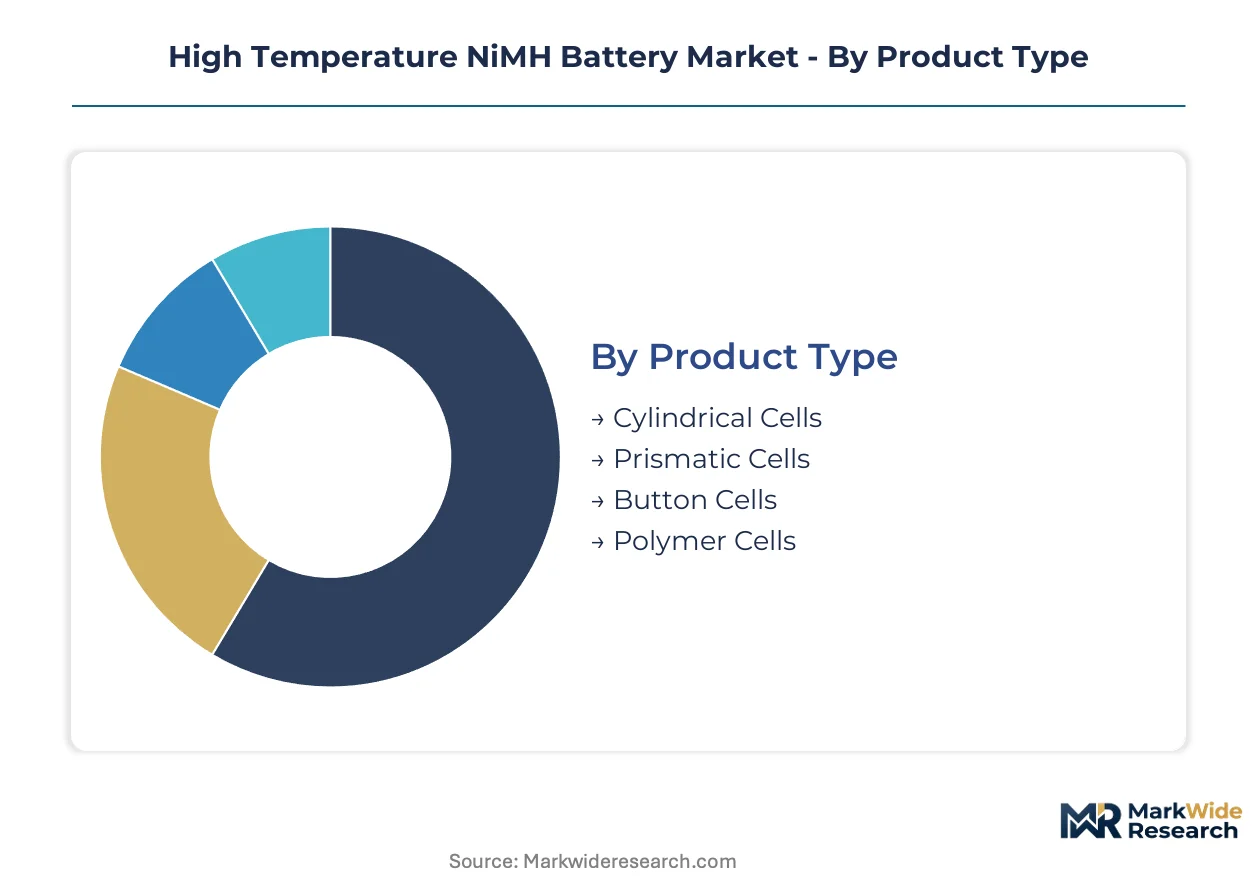
High temperature NiMH battery configurations diverge sharply across thermal envelope requirements and qualification pathways. Cell geometry and electrolyte chemistry choices cascade through procurement specifications for defense, aerospace, and heavy industrial automation buyers.
Product Type:
Cost tier determines form factor adoption, with cylindrical cells dominating volume procurement and prismatic variants commanding premium positioning in space-constrained applications.
- Cylindrical Cells:Standardized diameters from AA to D formats accommodate legacy thermal battery replacement programs in military procurement. Established winding equipment and mature sealing processes keep unit economics favorable for downhole drilling instrumentation deployed in Permian Basin extended-reach laterals.
- Prismatic Cells:Rectangular aluminum-laminate housings maximize volumetric energy density for aircraft auxiliary power units where bay geometry is fixed. German aircraft manufacturers specify prismatic formats for furnace-adjacent electronics bays in regional jet platforms.
- Button Cells:Coin-shaped configurations serve compact sensor applications in industrial automation with limited depth clearance.
- Polymer Cells:Flexible laminate packaging adapts to irregular mounting surfaces in wearable military electronics and curved aerospace interior panels.
Cylindrical cells hold installed capacity. Prismatic cells are rotating up the share rankings.
Technology:
Application requirements dictate which subsystem receives engineering priority, with thermal management and electrolyte chemistry representing the steepest expansion trajectories.
- Advanced Electrode:Sintered nickel hydroxide positive electrodes with controlled porosity above 70% active material utilization sustain capacity retention through 500+ cycles at 85°C. Japanese national laboratory research on hydrogen-absorbing alloy surface modification is extending cycle life for METI-backed industrial automation projects.
- Enhanced Electrolyte:Potassium hydroxide solutions with lithium hydroxide additives and proprietary organic stabilizers widen operating windows to 120°C ambient. Defense contractors in desert deployment programs are qualifying enhanced electrolyte formulations as primary lithium thermal battery alternatives.
- Thermal Management Systems:Integrated battery management electronics with cell-level temperature sensing reduce system-level qualification costs for aerospace manufacturers.
- Improved Separator:Ceramic-coated polyolefin and zirconia-based nonwoven substrates prevent dendrite penetration above 100°C continuous operation.
Enhanced electrolyte technology is climbing the fastest. Thermal management systems hold established share in aerospace procurement.
Application:
End-use thermal severity separates qualification tiers, with military and aerospace specifications imposing the most stringent environmental chamber testing protocols.
- Military Devices:Portable power for soldier-worn electronics and unmanned ground vehicles requires MIL-STD-810H compliance for thermal shock and sand exposure. US defense procurement is consolidating supplier relationships around qualified cell producers with documented domestic content ratios.
- Aerospace Systems:Auxiliary power units and emergency lighting systems in commercial and defense aircraft demand FAA and EASA dual certification for flammability resistance. Ceramic separator technology is compressing replacement intervals from 90 days to 12 months in extended-deployment platforms.
- Industrial Equipment:Backup power for furnace-adjacent control systems in steel rolling mills and automotive press shops.
- Consumer Electronics:Limited adoption confined to professional-grade devices with extreme-environment specifications.
Military devices hold installed capacity. Aerospace systems are gaining share fastest.
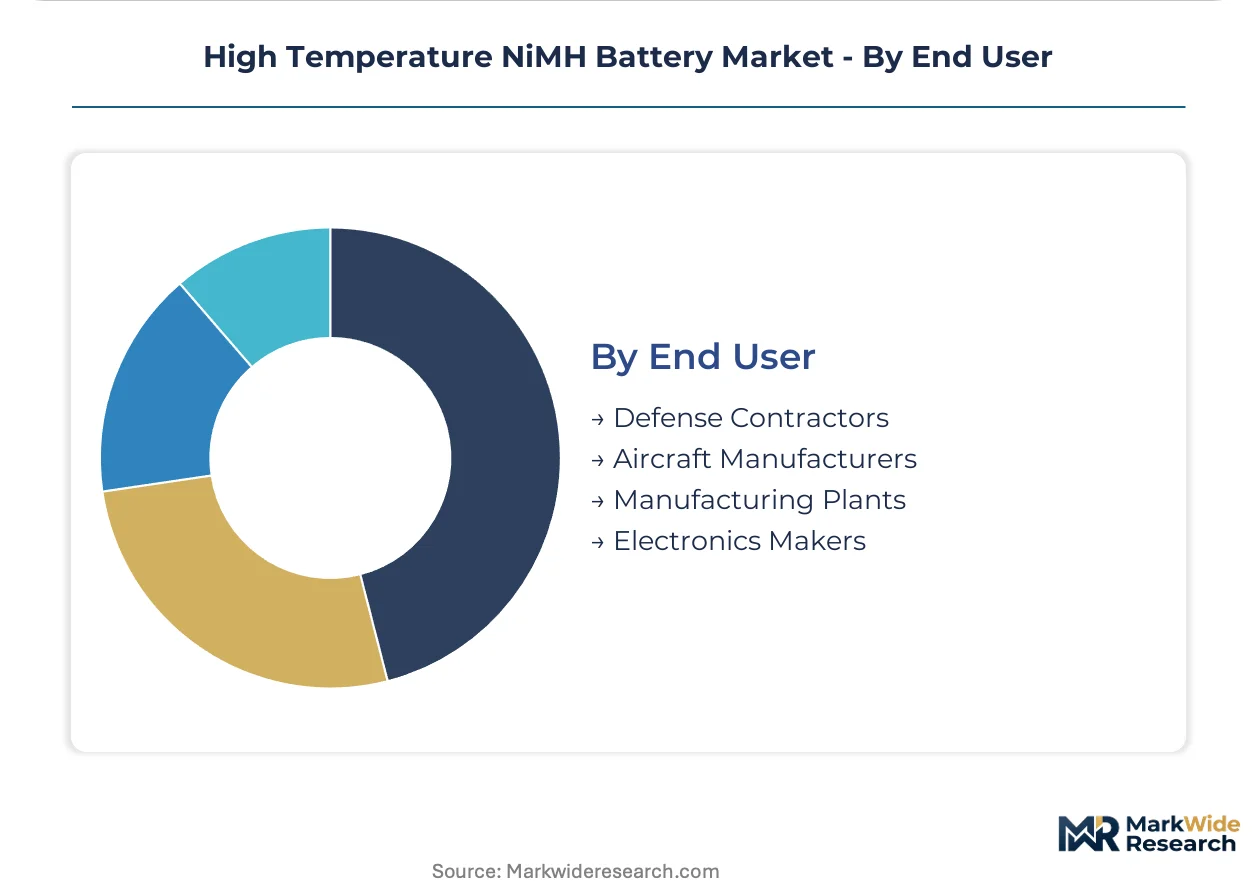
End User:
Customer procurement sophistication determines specification depth, with defense and aircraft OEMs driving qualification standardization across supplier bases.
- Defense Contractors:Prime systems integrators for ground vehicles and unmanned platforms mandate 5-year volume commitments with documented supply-chain provenance. Long-term agreements are displacing spot purchasing as CSRD traceability requirements propagate through European procurement.
- Aircraft Manufacturers:Airframers and tier-1 avionics suppliers specify cell-level thermal runaway propagation resistance per GB/T 36276 and JIS standards. China's SAMR 18-month certification timeline is delaying market entry for uncertified foreign suppliers.
- Manufacturing Plants:Automotive and steel producers in Germany's Ruhr industrial corridor standardize on high-temperature NiMH for backup power reliability.
- Electronics Makers:Industrial battery pack assemblers serving automation OEMs require separator material certificates of origin under tightened GB protocols.
Defense contractors hold installed capacity. Aircraft manufacturers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrode manufacturing clusters in Japan and China dominate upstream capacity, while German industrial automation corridors and US defense procurement channels concentrate downstream demand. Regulatory divergence across SAMR, METI, and FAA jurisdictions fragments certification pathways.
China
Downhole instrumentation manufacturers in Sichuan-Chongqing and Yangtze River Delta clusters drive cylindrical cell procurement for oilfield service companies. SAMR's extended GB/T 36276 certification timeline to 18 months delays foreign supplier entry. Shenzhen and Dongguan electronics assemblers stockpile separator material certificates to satisfy tightened origin documentation rules.
Japan
METI subsidies for extreme-environment cell production accelerate dedicated high-temperature line investments at Kansai and Chubu region facilities. JIS standards enforcement elevates barriers for uncertified imports. Osaka-based industrial battery pack integrators consolidate 5-year volume commitments with domestic electrode producers to satisfy 60% domestic content ratios.
Germany
Ruhr region automotive press shops and steel rolling mills standardize high-temperature NiMH backup power for furnace-adjacent control systems. EU CSRD supply-chain traceability mandates propagate through procurement specifications. Bavarian aircraft manufacturers specify prismatic cell formats for regional jet auxiliary power units.
United States
Permian Basin oilfield operators retrofit measurement-while-drilling tools with high-temperature NiMH packs to replace primary lithium thermal batteries. FAA dual certification requirements with EASA compress qualification timelines for aerospace auxiliary power units. Defense contractors in Texas and California consolidate supplier relationships around MIL-STD-810H qualified cell producers.
South Korea
Daegu-Gyeongbuk industrial automation corridors adopt high-temperature NiMH for semiconductor fabrication facility backup systems. MFDS-aligned safety protocols shape procurement specifications for extreme-environment cells. Seoul Capital Area battery pack assemblers source ceramic-coated separators for 120°C continuous operation applications.
High Temperature NiMH Battery Market Competitive Landscape
Integrated electrode manufacturers and specialized cell producers split the market between captive supply security and flexible procurement relationships. Tier-1 aerospace and defense qualification requirements consolidate procurement around dual-use capable suppliers. Three archetypes dominate: Japanese sintered-electrode specialists, Chinese scale-driven cylindrical producers, and European system integrators with thermal management expertise. Competitive moves concentrate on backward integration into rare earth alloy processing and parallel MIL-STD-810/IEC 62660 qualification investments.
Within the Japanese specialist tier, Panasonic Holdings and FDK Corporation exemplify sintered-electrode process maturity. BYD Company anchors the scale-driven cylindrical segment. VARTA AG occupies a position bridging European industrial automation demand with aerospace qualification pathways.
| Leading Market Players |
|---|
| Panasonic Holdings |
| GS Yuasa |
| FDK Corporation |
| BYD Company |
| Energizer Holdings |
| Duracell |
| GP Batteries International |
| VARTA AG |
| Saft |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Japanese sintered electrode facilities is compressing supplier margins while amplifying pricing power for qualified domestic producers serving METI-backed defense contracts. This utilization squeeze cascades through procurement negotiations, with buyers accepting premium positioning to secure allocation in certified supply channels.
Pricing Analysis
GB/T 36276 certification dictates the pricing tier structure across the high temperature NiMH battery market, separating aerospace-qualified suppliers from industrial-grade competitors. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal envelope rating and documented domestic content ratios. Cost compression in the standard tier is intensifying because Chinese cylindrical producers are scaling unqualified capacity ahead of SAMR's extended 18-month approval timeline. Defense contractors exhibit the lowest price sensitivity due to MIL-STD-810H qualification requirements, while industrial automation buyers in Germany's Ruhr corridor negotiate aggressively on volume commitments.
Supply Chain Analysis
BYD Company and FDK Corporation anchor contract-manufacturing concentration for high-temperature cylindrical and prismatic formats respectively. Electrode active materials draw from Japanese sintering facilities and Chinese rare earth separation plants, with hydrogen-absorbing alloys resting on lanthanum and cerium processed primarily through Chinese facilities. Single-source vulnerability in rare earth alloy supply creates structural exposure to export restriction risk. Distribution runs through qualified battery pack assemblers serving defense prime contractors and industrial automation OEMs with documented separator origin certificates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection as ceramic separator standards consolidate around zirconia-based substrates, creating interoperability lock-in for qualified suppliers. The shift toward documented supply-chain provenance under EU CSRD and China's GB protocols is rewiring procurement specifications toward ecosystem-wide certification.
For Market Incumbents: Build certification moats through parallel MIL-STD-810 and IEC 62660 qualification investments exceeding $4 million per environmental chamber facility. Backward integration into rare earth alloy processing secures supply continuity against Chinese export restriction risk. Anchor long-term supply agreements with 5-year volume commitments to displace spot purchasing in aerospace auxiliary power unit procurement.
For New Entrants and Emerging Players: German industrial automation corridors in the Ruhr region represent the most penetrable entry point for unqualified suppliers seeking furnace-adjacent backup power contracts. Downhole instrumentation retrofit programs in the Permian Basin offer second-mover positioning behind established cylindrical producers. Pursue ceramic-coated separator technology licensing from Japanese national laboratory spinouts to compress qualification timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across dual-use production lines satisfying both aerospace and downhole drilling specifications. Long-term viability across the analysis window favors suppliers with in-house electrode manufacturing and documented conflict-mineral-free rare earth sourcing. Target acquisition archetypes include sintered-electrode specialists with METI-backed industrial project relationships. Quarterly review of SAMR certification queue depth and METI subsidy allocation rates is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Captive lanthanum-cerium supply insulates against Chinese separation facility concentration risk. |
| Parallel MIL-STD-810/IEC 62660 Qualification | Dual certification unlocks defense and aerospace procurement channels with consolidated supplier relationships. |
| Ceramic Separator Technology Licensing | Zirconia-based substrate adoption compresses replacement intervals from 90 days to 12 months in downhole applications. |
| Long-term Supply Agreement Structuring | Five-year volume commitments with documented provenance satisfy CSRD traceability mandates in European procurement. |
| Dedicated High-Temperature Line Investment | Specialized capacity serving METI-backed projects secures 60% domestic content ratio compliance in Japanese defense contracts. |
Research Methodology
A spread of perspectives from defense procurement officers, aerospace battery qualification engineers, oilfield service company technical directors, industrial automation plant managers, and electrode manufacturing executives converged on the working assumptions. Primary interview findings were cross-referenced against SAMR GB/T 36276 filing databases, METI industrial battery subsidy disclosure records, FAA TSO certification registries, and customs trade data for rare earth alloy imports. Bottom-up cell production estimates and top-down end-use demand modeling were reconciled through iterative triangulation.
Demand-supply balance dynamics across the projection horizon were modeled through cell geometry, electrolyte chemistry, and thermal envelope segmentation. The analytical framework incorporated qualification pathway tiering, regional regulatory cluster differentiation, and end-use thermal severity grading. CAGRs were derived from installed base replacement cycles and new adoption penetration curves. Forecast inputs included defense procurement cycle compression rates and ceramic separator technology adoption slopes in downhole drilling applications.
Macroeconomic conditions sit as an overlay; deviation in oilfield capital expenditure cycles or aerospace production rates would shift the trajectory. Forecasts reflect working assumptions on certification timeline stability and rare earth supply continuity. Quarterly review of SAMR queue clearance rates and METI subsidy disbursement velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Power-Sports Batteries Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Lithium Pouch Cell Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Custom Battery Pack Market
Batteries
Printed Batteries Market
Batteries
Battery Anode Materials Market
Batteries
Nimh Battery Market
Batteries
3D-Printed Battery Market
Batteries
Nickel Cadmium Battery Market
Batteries
Smart Battery Charger Market
Batteries
Alkaline Battery Market
Batteries
Electrolyte Solutions for Li-Ion Batteries Market
Batteries
Forklift Battery Charger Market
Batteries
East Asia Battery Market
Batteries
Stationary Lead-Acid Battery Market