
 India Micro Batteries Market | 2026-2036
India Micro Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
India Micro Batteries Market Insights
India's PLI scheme for advanced chemistry cell manufacturing is recalibrating investment flows toward localized micro battery production. Eveready Industries India Ltd leverages its established dry-cell distribution network to anchor rural market penetration for emerging formats. Panasonic Energy Co. Ltd competes through technology leadership in solid-state miniaturization, while VARTA Microbattery specializes in medical-grade power solutions for implantable devices.
India micro batteries are electrochemical energy storage devices with form factors below twenty millimeters, typically employing lithium or silver oxide chemistries in layered or wound electrode architectures to deliver stable voltage output for milliwatt-scale loads. Their primary purpose is to power compact electronics where space constraints exclude conventional cylindrical or prismatic cells. Lithium-Ion product types dominate current manufacturing volumes due to established supply chains and energy density advantages, though Solid-State technology segments attract disproportionate R&D allocation as thermal stability requirements tighten across Aerospace end user applications. Wearables application segments command premium pricing, while IoT Devices segments scale through volume contracts with smart city infrastructure deployers.
BIS certification mandates for lithium-ion imports, CDSCO medical device regulations, and the Ministry of Electronics and Information Technology's hardware incentive frameworks collectively reshape product standards and market access conditions for domestic and foreign suppliers. Compliance with these overlapping requirements demands dedicated regulatory teams and localized testing partnerships. Stakeholders must monitor how forthcoming battery waste management rules alter Extended Producer Responsibility obligations and recycling infrastructure investments.
Market Dynamics
BIS certification mandates for lithium-ion imports are compressing procurement timelines and forcing domestic assembly investments across Maharashtra and Karnataka electronics corridors.
Growth Catalysts
- Wearable Health Monitor Proliferation:Medical device manufacturers in Bengaluru and Hyderabad are scaling orders for silver oxide micro cells to power continuous glucose monitors and cardiac patches.
- PLI Scheme for Advanced Chemistry Cells:India's production-linked incentive framework is redirecting capital toward localized electrode coating and cell assembly operations.
- Smart City Infrastructure Deployment:Municipal corporations across Delhi-Mumbai industrial belt are tendering volume contracts for IoT sensor networks requiring milliwatt-scale lithium primary cells.
Market Restraints
- Cobalt and Lithium Carbonate Volatility:Raw material price swings in spot markets are compressing margin structures for domestic assemblers dependent on imported cathode precursors.
- Single-Source Separator Supply:Polypropylene membrane production concentrates in East Asian suppliers, exposing Indian cell manufacturers to shipping disruption risks.
- Energy Density Ceiling in Solid-State:Current ceramic electrolyte formulations limit volumetric performance for implantable medical applications requiring sub-10mm form factors.
Strategic Opportunities
- Rural Wearables Penetration:Tier-3 and Tier-4 towns in Uttar Pradesh and Bihar present unmet demand for low-cost health monitoring devices powered by alkaline button cells.
- CDSCO Fast-Track Pathways:India's medical device regulator is streamlining approval timelines for indigenously manufactured implantable power sources.
- AI-Enabled Predictive Maintenance Convergence:Integration of edge computing with micro battery telemetry is opening service-contract revenue models for industrial IoT deployers.
Industry Challenges
- Electrolyte Formulation Talent Scarcity:Indian chemical engineering programs produce insufficient specialists in non-aqueous lithium salt chemistry for high-voltage micro cells.
- BIS Testing Queue Backlogs:Certification timelines for new cell formats currently extend six to nine months, delaying product launches for domestic manufacturers.
- Legacy Dry-Cell Distribution Integration:Established rural networks optimized for zinc-carbon batteries require reconfiguration to handle lithium primary cell storage and handling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Micro Batteries Market |
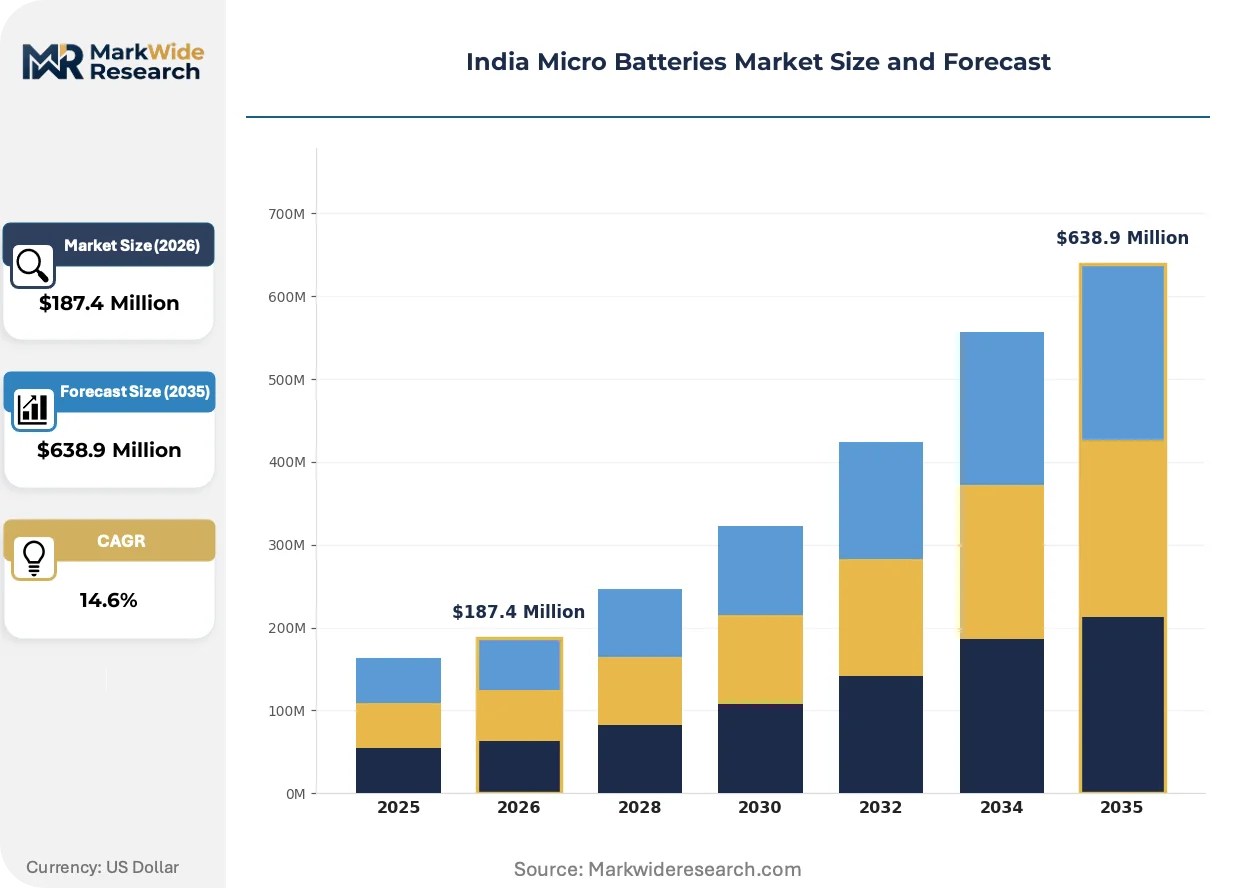
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
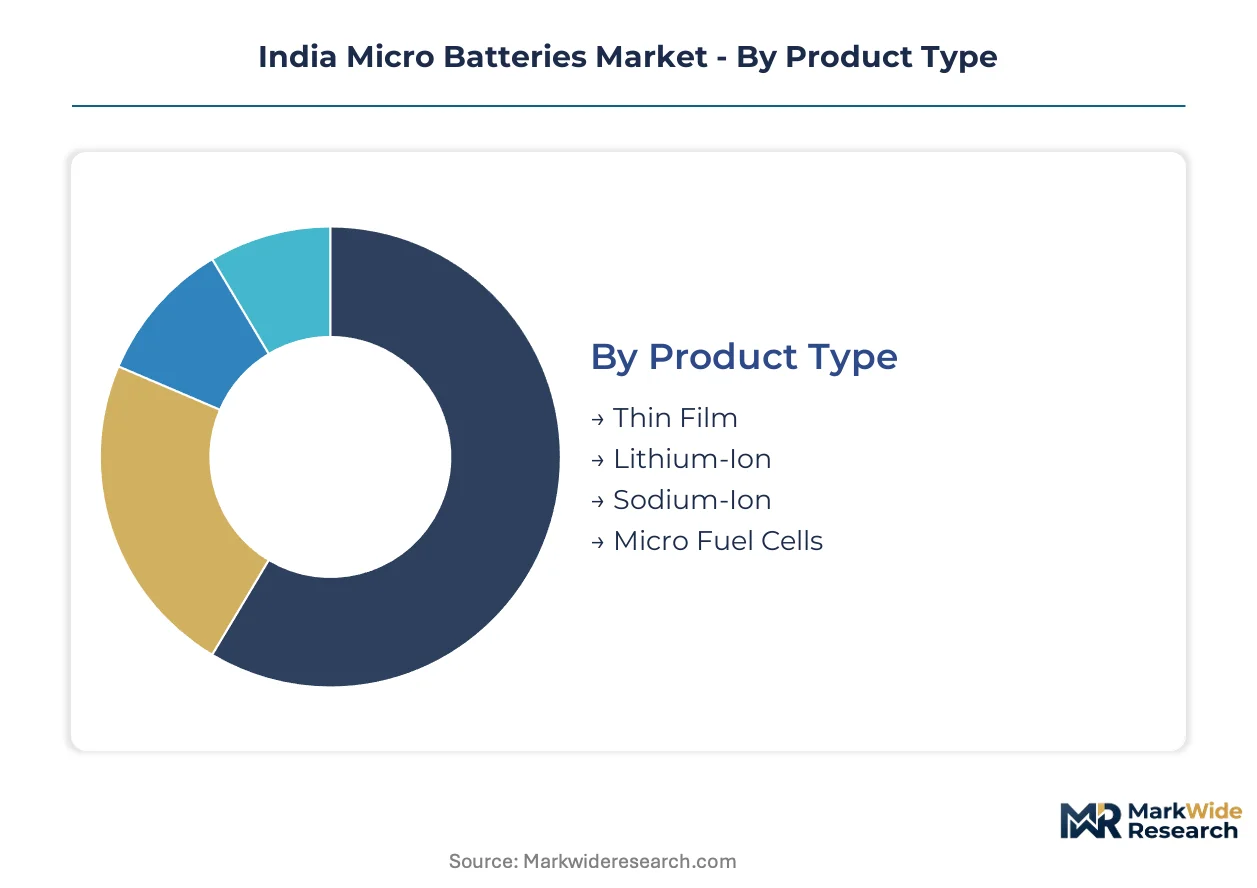
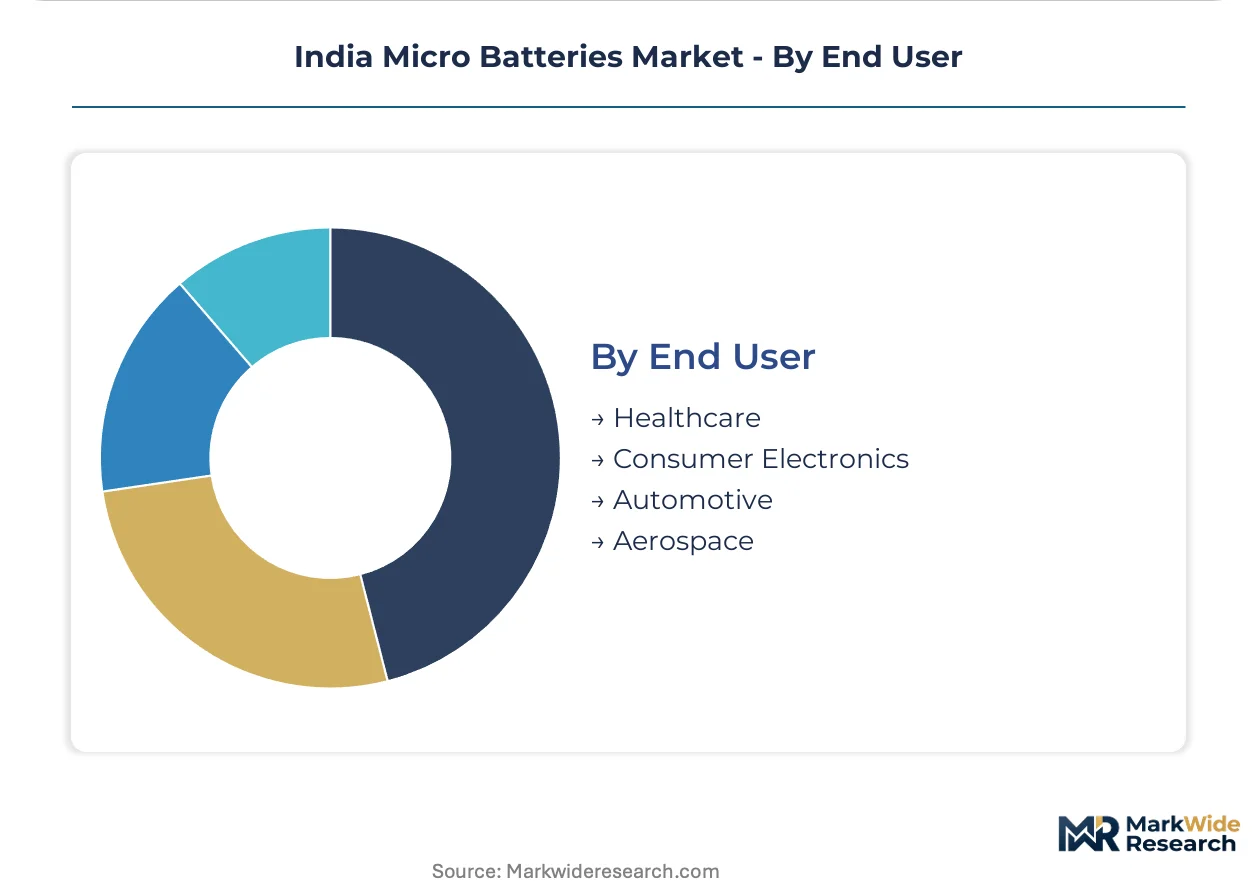
| Segmentation | Product Type: Thin Film, Lithium-Ion, Sodium-Ion, Micro Fuel Cells Application: Wearables, IoT Devices, Medical Devices, Smart Sensors Technology: Solid-State, Polymer Electrolyte, Hybrid Systems, Nano-Structured End User: Healthcare, Consumer Electronics, Automotive, Aerospace |
| Companies Covered | Eveready Industries India Ltd, Indo National Ltd, Duracell Inc., Panasonic Energy Co. Ltd, Energizer Holdings Inc., VARTA Microbattery, Sony Corporation, Murata Manufacturing Co. Ltd, Renata Battery, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Micro Batteries Market Trends and Innovations
Solid-state electrolyte research and automated electrode manufacturing are compressing production cycles while BIS regulatory tightening reshapes import substitution strategies across the value chain.
Printed battery manufacturing is automating roll-to-roll deposition of zinc-manganese and lithium-polymer layers onto flexible polymer substrates. Wearable patch manufacturers in Bengaluru's electronics manufacturing corridor are piloting these lines at pilot scale. The technology is automating electrode alignment precision previously requiring manual assembly, reducing unit costs for disposable medical sensors.
CDSCO's revised Medical Device Rules are mandating traceable supply chains for implantable power sources. Domestic assemblers must now document cell genealogy from electrode coating through final sterilization. Cardiac rhythm management device manufacturers in Hyderabad are responding by qualifying second-source Indian cell suppliers to reduce import dependency.
Direct procurement from cell manufacturers is displacing multi-tier distribution for high-volume IoT deployers. Smart city infrastructure operators in the Delhi-Mumbai industrial belt are negotiating annual volume contracts with Bengaluru-based assemblers, bypassing traditional component distributors. This pattern concentrates most visibly in Maharashtra municipal sensor deployments where total cost of ownership calculations favor origin-direct sourcing over stocked inventory models.
India Micro Batteries Market Segmentation
Micro battery procurement patterns diverge sharply between standalone disposable units and embedded rechargeable systems. Understanding these integration pathways clarifies why certain chemistries dominate specific device architectures while others remain confined to pilot-scale deployment.
Product Type:
Standalone primary cells power field-replaceable medical patches and industrial sensors, whereas embedded rechargeable formats dominate sealed consumer wearables requiring multi-year lifecycles.
- Lithium-Ion:Layered oxide cathodes paired with graphite anodes deliver 3.6V nominal output in prismatic and pouch formats. Demand concentrates in Bengaluru's wearables manufacturing corridor where PLI-supported assembly lines require stable high-volume cell supply.
- Thin Film:Sputtered lithium-phosphorus-oxynitride electrolytes enable sub-millimeter form factors for implantable cardiac monitors. Hyderabad medical device clusters are qualifying these for CDSCO Class D implantable pathways.
- Sodium-Ion:Prussian blue analog cathodes with hard carbon anodes trade energy density for raw material security. Domestic pilot lines in Tamil Nadu are testing these for grid-tied IoT sensors.
- Micro Fuel Cells:Direct methanol architectures deliver continuous power for remote monitoring stations. Defence Research and Development Organisation laboratories are evaluating these for Himalayan border surveillance networks.
Volume placements concentrate in Lithium-Ion; the faster expansion belongs to Thin Film.
Application:
Application segments stratify by power budget volatility—continuous monitoring demands stable microamp loads while intermittent telemetry tolerates pulse discharge architectures.
- Medical Devices:Implantable neurostimulators and continuous glucose monitors require hermetic sealing and decade-long shelf stability. CDSCO's tightened traceability mandates are pushing cardiac rhythm management manufacturers toward dual-source Indian cell qualification.
- Wearables:Smartwatches and fitness bands prioritize volumetric energy density over cycle life. Maharashtra's electronics manufacturing clusters are absorbing the majority of domestic lithium polymer cell output.
- IoT Devices:Smart city environmental sensors and agricultural monitors operate on microamp standby currents. Municipal corporations across Karnataka are tendering ten-year primary cell contracts for streetlight-integrated air quality nodes.
- Smart Sensors:Industrial predictive maintenance tags require wide temperature tolerance. Oil and gas pipeline operators in Gujarat are deploying these for corrosion monitoring in desert and offshore environments.
Medical Devices command premium unit economics; IoT Devices scale through municipal volume aggregation.
Technology:
Technology choices reflect thermal runaway tolerance requirements—implantable applications demand non-flammable electrolytes while consumer devices prioritize manufacturing throughput.
- Solid-State:Ceramic and sulfide electrolytes eliminate flammability risks for subcutaneous power sources. Indian Institute of Science research partnerships are advancing oxide-based formulations for cardiac pacemaker applications.
- Polymer Electrolyte:Gelified lithium salt complexes enable flexible form factors for skin-adherent patches. Bengaluru wearables manufacturers are qualifying these for CDSCO Class B non-implantable pathways.
- Hybrid Systems:Combined solid-liquid architectures balance ionic conductivity with manufacturing compatibility. Defence applications are driving development for extreme temperature cycling.
- Nano-Structured:Silicon nanowire anodes and sulfur composite cathodes push gravimetric limits. Academic consortia are transferring these from laboratory to pilot production.
Polymer Electrolyte dominates current manufacturing volumes; Solid-State is climbing the fastest toward commercial implantable deployment.
End User:
End user procurement patterns separate regulated medical channels requiring sterilization compatibility from consumer electronics driven by cost-per-milliwatt metrics.
- Healthcare:Implantable and wearable therapeutic devices demand ISO 13485 quality systems and sterilization-stable packaging. CDSCO's 2023 Medical Device Rules amendments are accelerating domestic cell supplier qualification timelines.
- Consumer Electronics:Hearing aids, wireless earbuds, and smart jewelry prioritize acoustic and aesthetic integration. Delhi-Mumbai industrial belt distributors are consolidating procurement for these high-volume, low-margin segments.
- Automotive:Tire pressure monitoring systems and key fobs require wide temperature tolerance. Tamil Nadu automotive component clusters are integrating micro cells into connected vehicle subsystems.
- Aerospace:Satellite subsystems and unmanned aerial vehicle payloads demand radiation tolerance and altitude pressure resilience. Indian Space Research Organisation vendor development programs are qualifying domestic sources.
Healthcare sustains premium pricing tiers; Consumer Electronics absorbs the greatest absolute cell volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic assembly capacity concentrates in western and southern states while northern and eastern regions remain net consumption zones dependent on interstate supply chains.
Maharashtra
Mumbai-Pune electronics corridor absorbs the majority of lithium-ion micro cell output for wearables manufacturing. The state government's electronics policy offers capital subsidies for electrode coating facilities. Ambernath and Chakan industrial zones host emerging domestic assembly operations serving medical device clusters.
Karnataka
Bengaluru's medical technology corridor drives silver oxide demand for implantable cardiac monitors and continuous glucose sensors. CDSCO's regional office in the city accelerates qualification timelines for domestic cell suppliers. Electronics City and Peenya industrial areas concentrate printed battery pilot lines for disposable medical patches.
Tamil Nadu
Sriperumbudur-Oragadam automotive belt integrates micro cells into tire pressure monitoring systems and connected vehicle subsystems. The state's advanced manufacturing incentives attract cathode precursor investments. Hosur electronics manufacturing cluster is qualifying sodium-ion alternatives for grid-tied IoT sensors.
Telangana
Hyderabad's medical device manufacturing zone specializes in cardiac rhythm management devices requiring decade-stable power sources. CDSCO fast-track pathways for indigenously manufactured implantable cells are compressing approval timelines. Genome Valley life sciences corridor is driving demand for hermetically sealed micro batteries.
Gujarat
Vadodara-Surat industrial belt deploys smart sensors for oil and gas pipeline corrosion monitoring in desert and offshore environments. The state's petroleum and natural gas infrastructure requires wide-temperature-tolerance micro cells. Dahej PCPIR chemical hub is evaluating localized electrolyte formulation capabilities.
India Micro Batteries Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with established dry-cell distribution networks repurposed for lithium formats. Market concentration remains moderate with no single entity commanding dominant share. Three strategic archetypes populate the landscape: legacy battery manufacturers with rural distribution depth, Japanese and German technology specialists with medical-grade certifications, and emerging domestic assemblers leveraging PLI scheme incentives. Capacity expansion and strategic partnerships with electronics manufacturing service providers constitute the dominant competitive moves.
Among diversified Indian manufacturers, Eveready Industries India Ltd and Indo National Ltd occupy positions anchored by established zinc-carbon distribution networks requiring reconfiguration for lithium handling protocols. Panasonic Energy Co. Ltd exemplifies the technology-led archetype with solid-state miniaturization capabilities. VARTA Microbattery represents the medical-grade specialization vector with implantable power source expertise. These three entities collectively illustrate the tripartite competitive structure: domestic scale players, multinational technology leaders, and niche medical specialists.
| Leading Market Players |
|---|
| Eveready Industries India Ltd |
| Indo National Ltd |
| Duracell Inc. |
| Panasonic Energy Co. Ltd |
| Energizer Holdings Inc. |
| VARTA Microbattery |
| Sony Corporation |
| Murata Manufacturing Co. Ltd |
| Renata Battery |
| Others |
Pricing and Supply Chain Analysis
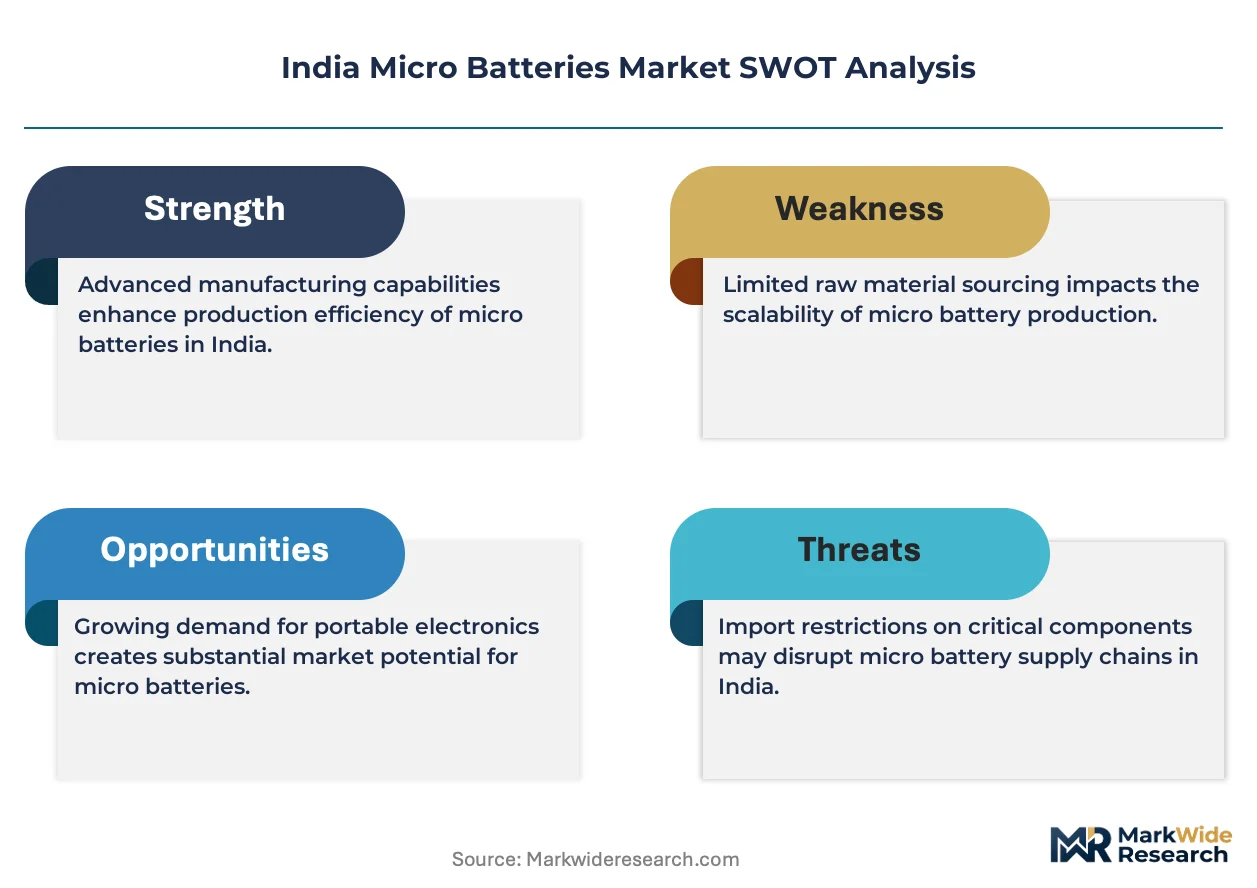
Cobalt carbonate and lithium hydroxide feedstock costs cascade through electrode coating operations to stratify final cell pricing across medical-grade, industrial, and consumer tiers. BIS certification queue delays compress margin structures for domestic assemblers competing against landed imports from East Asian suppliers.
Pricing Analysis
Value-based pricing anchored to device uptime guarantees dominates medical implant contracts, particularly for cardiac rhythm management applications requiring decade-stable power delivery. Three-tier pricing structure across premium, standard, and economy levels separates CDSCO-certified hermetic cells from industrial IoT primary cells and consumer alkaline button formats. Cost compression in the standard tier is intensifying because domestic electrode coating capacity expansion outpaces BIS qualification throughput. Municipal IoT deployers exhibit highest price sensitivity, while implantable device manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Container freight rates from South Korean and Japanese cathode precursor suppliers determine landed cost volatility for Maharashtra and Karnataka assembly operations. Raw material sourcing draws from Chilean lithium brine, Indonesian nickel laterite, and Chinese cobalt hydroxide refining. Single-source polypropylene separator membrane production concentrates in East Asian suppliers, exposing Indian cell manufacturers to shipping disruption risks. Distribution runs through electronics manufacturing service providers in Bengaluru and direct procurement contracts with Delhi-Mumbai industrial belt municipal corporations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state electrolyte architectures are displacing conventional lithium-ion formats in implantable medical applications, compressing the window for legacy chemistry investments. This technology transition favors players with CDSCO regulatory navigation capabilities and hermetic sealing expertise.
For Market Incumbents: To counter solid-state technology displacement in premium medical segments, Eveready and Indo National should accelerate backward integration into electrode coating facilities in Ambernath and Chakan industrial zones. Certification investment in CDSCO Class D implantable pathways provides defensive moats against Panasonic and VARTA technology leadership.
For New Entrants and Emerging Players: Sodium-ion pilot production capabilities offer a technology-first wedge into grid-tied IoT sensor applications where energy density requirements remain modest. Tamil Nadu's Hosur electronics cluster presents the most penetrable geography, with state advanced manufacturing incentives reducing capital barriers. Direct municipal contracting with Karnataka streetlight-integrated air quality node tenders bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: CDSCO fast-track pathway announcements for indigenously manufactured implantable cells are the leading indicator that domestic medical-grade assembly will achieve regulatory parity with imports. Five-to-ten-year viability favors acquisition targets possessing BIS testing partnerships and sterilization-compatible packaging capabilities. The signal to monitor is qualification timeline compression for solid-state ceramic electrolyte formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Fast-Track Qualification | Accelerates domestic cell supplier approval for cardiac rhythm management devices in Hyderabad. |
| Electrode Coating Facility Expansion | Captures PLI scheme incentives while reducing dependency on imported cathode precursors from South Korea. |
| Solid-State Electrolyte R&D Partnership | Indian Institute of Science collaborations advance oxide formulations for sub-10mm implantable form factors. |
| Municipal IoT Direct Contracting | Bypasses traditional distributors for Maharashtra smart city sensor deployments via annual volume agreements. |
| Sodium-Ion Pilot Line Commissioning | Tamil Nadu testing of Prussian blue cathodes addresses raw material security for grid-tied agricultural monitors. |
Research Methodology
Trade databases, BIS certification registries, and CDSCO medical device filings formed the secondary backbone, supplemented by primary interviews with electrode coating facility managers, biomedical engineers at Hyderabad cardiac device manufacturers, and procurement leads at Maharashtra municipal corporations. Bottom-up and top-down triangulation validated volume estimates across lithium-ion, thin film, and sodium-ion product categories.
Bottom-up modeling aggregated unit economics across Bengaluru wearables clusters, Hyderabad implantable device manufacturers, and Tamil Nadu automotive component suppliers. Segmentation dimensions included product chemistry, application power budget, technology architecture, and end-user regulatory intensity. CAGRs were derived from installed base projections for continuous glucose monitors and smart city sensor node deployments.
Several conditions sit outside the modeled scope, including unforeseen BIS regulatory amendments, raw material export restrictions from Chile or Indonesia, and breakthrough solid-state energy density improvements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Medical Batteries Market
Batteries
South America Consumer Battery Market
Batteries
Disposable Batteries Market
Batteries
Molten Salt Battery Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Romania Rechargeable Battery Market
Batteries
Behind-The-Meter (BTM) Battery Market
Batteries
Myanmar Battery Market
Batteries
Malaysia Battery Market
Batteries
West Europe Battery Market
Batteries
Dry Cell Battery Market
Batteries
Portable Battery Market
Batteries
East Asia Battery Market
Batteries
France Rechargeable Battery Market
Batteries
Watch Battery Market