
 Portable Battery Powered Products Market | 2026-2036
Portable Battery Powered Products Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Battery Powered Products Market Analytics
Subscription-based battery health monitoring and software-defined charging protocols is hardening as a distinct revenue layer above hardware sales. Samsung Electronics leverages its semiconductor ecosystem to integrate proprietary power management chips across portable speaker and power bank lines. Panasonic Holdings Corp. anchors industrial-grade cordless tool battery packs through captive cell chemistry expertise. BYD Co. Ltd. extends its automotive cell scale into consumer-facing power stations, competing on cost structure rather than brand premium.
Portable battery powered products encompass self-contained electrochemical energy storage devices designed for mobility, typically incorporating lithium-ion cells with nominal voltages between 3.6V and 14.4V, battery management systems with temperature cutoff thresholds, and DC-AC inversion circuitry for AC output models. These systems serve commercial and consumer purposes ranging from jobsite cordless operation to off-grid recreation and emergency backup. Power banks occupy the highest volume tier but face margin compression as USB-C Power Delivery standardizes across tiers. Solar charging represents the fastest-expanding technology segment as photovoltaic conversion efficiency improvements reduce panel surface area requirements for meaningful trickle charging. Hand tools command premium pricing through contractor-grade durability certifications and proprietary battery platform lock-in strategies.
China's SAMR enforces GB standards for lithium-ion transport safety and cell cycle life disclosure, directly shaping export eligibility for manufacturers serving EU and US destinations. The EU Battery Regulation mandates recycled content thresholds and digital passport requirements, forcing redesign of supply chain traceability systems for products entering European distribution channels. India's BIS certification requirements for lithium-ion cells create a compliance gate for power bank imports targeting price-sensitive consumer segments. Stakeholders must monitor which regulatory jurisdiction moves first on solid-state battery safety standards, as this will determine where next-generation product launches face accelerated or delayed market access.
Market Dynamics
Energy density improvements in lithium-ion cells and solid-state battery prototyping are compressing form factors while extending runtime, forcing incumbents to redesign thermal management architectures and triggering platform consolidation across cordless tool and portable power station portfolios.
Growth Catalysts
- GB Standards Enforcement:China's SAMR mandates for lithium-ion transport safety and cycle life disclosure are filtering non-compliant manufacturers from export pipelines, tightening supply discipline for products bound for EU and US destinations.
- Off-Grid Recreation Surge:Outdoor enthusiasts are expanding purchases of camping lights and portable power stations, creating pull-through demand for higher-capacity battery packs with solar charging integration.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements are enabling 20-30% capacity increases within identical physical footprints, allowing product designers to shrink housings or extend runtime without redesigning chassis dimensions.
Market Restraints
- Cobalt and Lithium Price Volatility:Raw material input swings compress margin predictability for battery pack assemblers, particularly those locked into fixed-price retail contracts with big-box distributors.
- Cell Manufacturing Concentration:Cylindrical and prismatic cell production clusters heavily in Chinese industrial zones, exposing supply continuity to single-geography logistics disruptions and tariff exposure.
- USB-C Power Delivery Standardization:Universal fast-charging protocols eliminate proprietary connector lock-in, eroding brand switching costs and accelerating margin compression in power bank tiers.
Strategic Opportunities
- Subscription Battery Health Monitoring:Software-defined charging protocols and predictive cell degradation analytics represent a recurring revenue layer above hardware sales, particularly for contractor-grade cordless tool fleets.
- EU Battery Regulation Compliance Services:Recycled content thresholds and digital passport mandates are forcing supply chain traceability redesigns, creating consulting and certification service openings for logistics technology providers.
- Solar Charging Integration:Photovoltaic conversion efficiency improvements are reducing panel surface area requirements, enabling meaningful trickle charging in portable power stations for emergency backup and recreational applications.
Industry Challenges
- Solid-State Battery Certification Timelines:Absence of harmonized safety standards across SAMR, EU Battery Regulation, and FAA frameworks delays product launch windows and fragments R&D investment across multiple compliance pathways.
- Battery Management System Firmware Talent Scarcity:Shortage of embedded systems engineers with electrochemical safety expertise constrains development velocity for temperature cutoff threshold optimization and cell balancing algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Battery Powered Products Market |
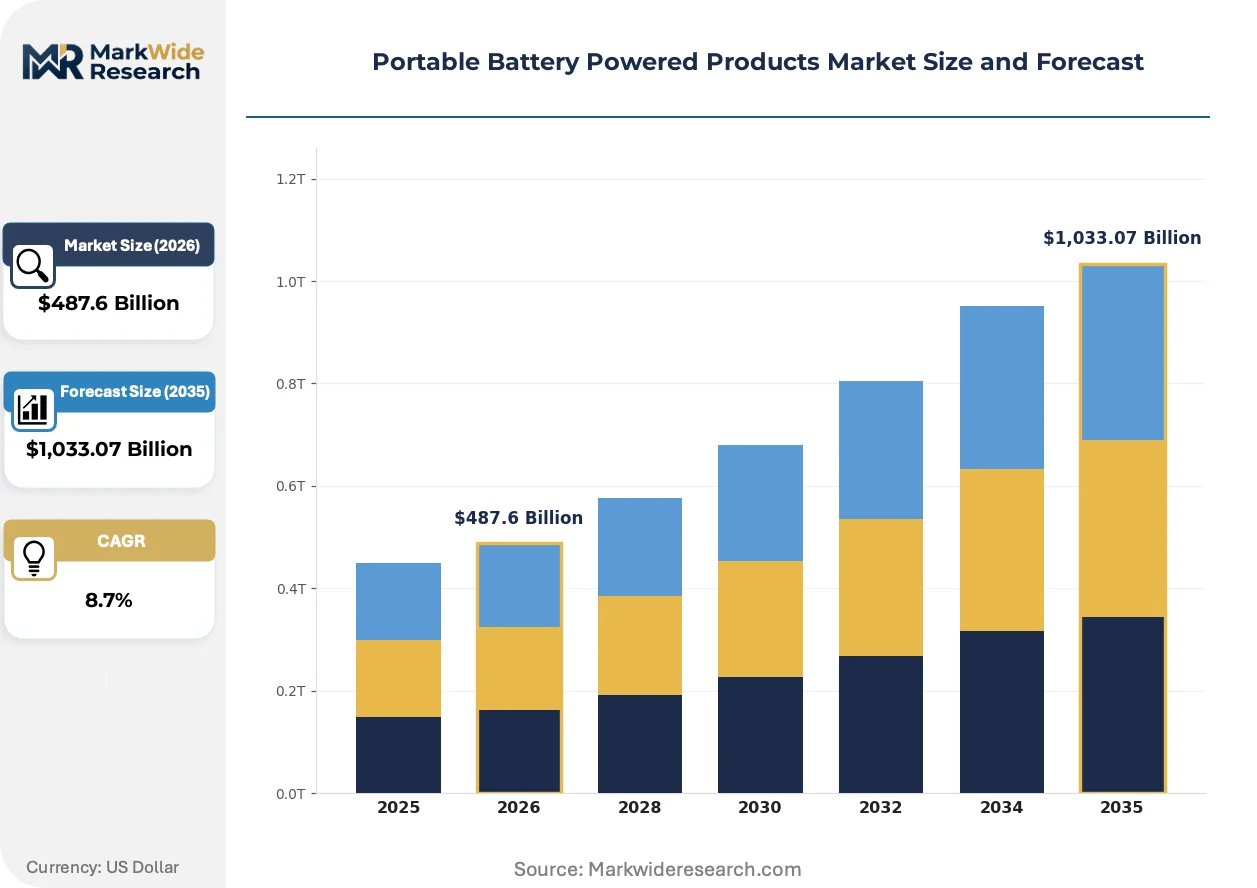
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,033.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Banks, Portable Speakers, Hand Tools, Camping Lights End User: Consumers, Contractors, Outdoor Enthusiasts, Event Planners Application: Emergency Use, Recreational Activities, Outdoor Events, Industrial Applications Technology: Li-ion Batteries, NiMH Batteries, Solar Charging, Wireless Charging |
| Companies Covered | Anker Technology Co. Ltd., Beijing Xiaomi Technology Co., Ltd., Samsung Electronics Co. Ltd., Panasonic Holdings Corp., LG Chem Ltd., Sony Group Corp., ASUSTeK Computer Inc., Energizer Holdings Inc., BYD Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Battery Powered Products Market Evolving Landscape
Electrochemical storage architectures are fragmenting across competing chemistry pathways while regulatory jurisdictions race to establish solid-state safety precedents, compressing product development cycles and forcing simultaneous bets on multiple technology generations.
Solid-state battery prototyping is consolidating performance benchmarks for next-generation portable power products. Automotive cell suppliers are transferring ceramic electrolyte and silicon-anode architectures into consumer-facing form factors. This chemistry transition is consolidating competitive positioning around thermal runaway immunity and energy density thresholds that legacy liquid-electrolyte cells cannot match.
The EU Battery Regulation is mandating recycled content thresholds and digital passport traceability for lithium-ion products entering European distribution. Industrial designers must reconfigure supply chain visibility systems to document cell origin, chemistry composition, and end-of-life handling protocols. Portable power station manufacturers serving German and French contractor channels are accelerating compliance investments ahead of enforcement deadlines.
Contractor procurement patterns are fragmenting across rental, lease-to-own, and outright purchase models for cordless tool systems. Independent tradesmen are gravitating toward platform subscription services that bundle battery pack refresh cycles with tool access, displacing traditional retail replacement purchases. This shift is most visible in North American residential construction verticals where crew sizes fluctuate seasonally.
Portable Battery Powered Products Market Segmentation
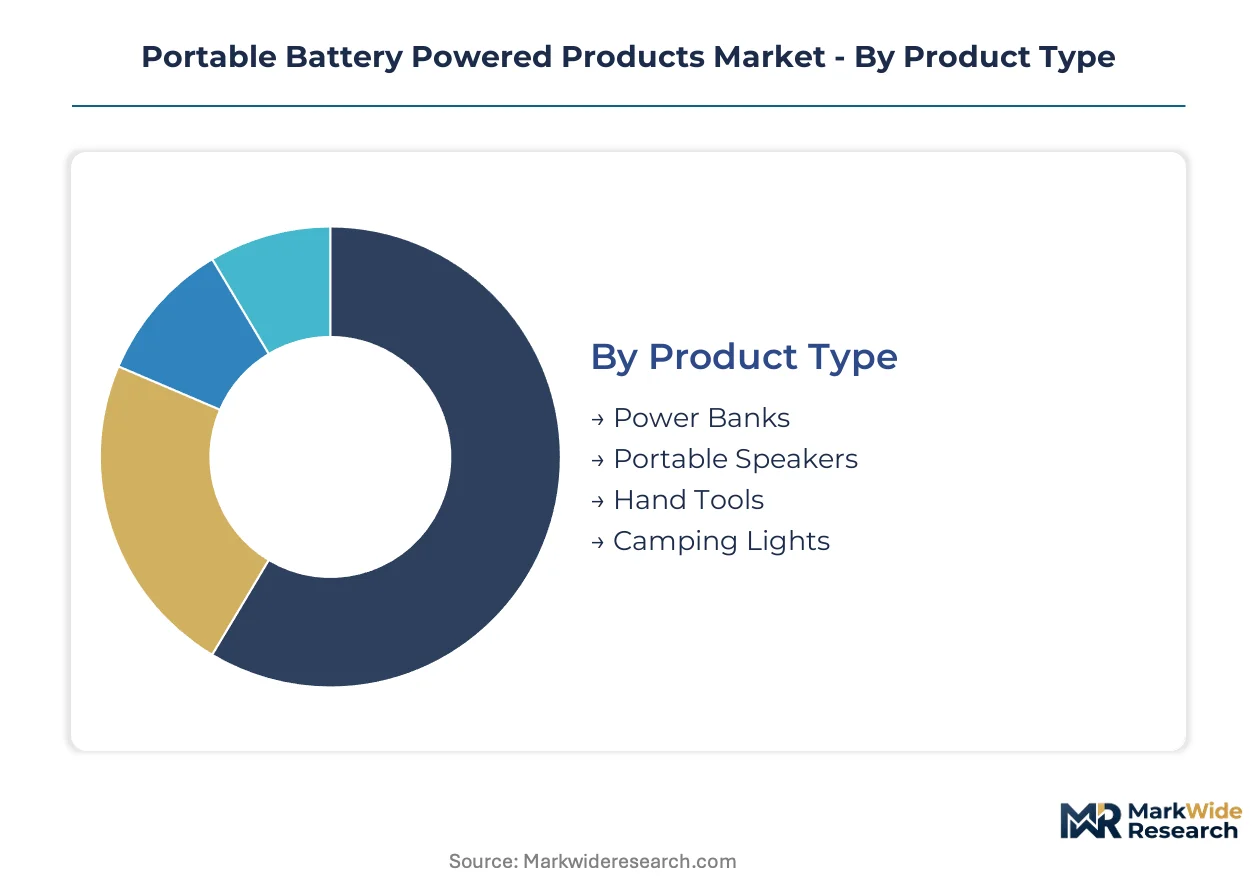
Portable battery powered products fragment across four critical dimensions where volume concentration, margin architecture, and technology substitution create divergent competitive dynamics. Understanding these splits reveals where cell chemistry investments and distribution channel strategies must align.
Product Type:
Volume leadership concentrates in commoditized categories while premium pricing persists in professional-grade segments with proprietary platform lock-in.
- Power Banks:Cylindrical and pouch cell configurations dominate this highest-volume tier. Demand clusters in urban consumer corridors across China and India, where USB-C Power Delivery standardization has collapsed switching costs and compressed retail margins.
- Hand Tools:Contractor-grade durability certifications and proprietary battery platform ecosystems sustain premium pricing. North American residential construction crews drive replacement cycles through seasonal crew size fluctuations and platform subscription services.
- Portable Speakers:Semiconductor-integrated power management chips enable runtime differentiation in compact form factors. Samsung Electronics leverages captive chip design to consolidate positioning in this segment.
- Camping Lights:Solar charging integration and IP-rated weatherproofing command recreational price premiums. Outdoor enthusiasts in German and French markets accelerate adoption of higher-capacity battery packs with photovoltaic trickle charging.
Today's leader: Power Banks. Tomorrow's challenger: Hand Tools.
End User:
Procurement patterns diverge sharply between individual purchase decisions and fleet-scale refresh cycles managed through subscription or lease structures.
- Contractors:Platform subscription services bundling battery pack refresh cycles with tool access are displacing traditional retail replacement purchases. This shift is most visible in North American residential construction verticals.
- Outdoor Enthusiasts:Off-grid recreation surge creates pull-through demand for higher-capacity battery packs with solar charging integration. Camping lights and portable power stations dominate purchase baskets in this segment.
- Consumers:Price-sensitive mass market segment where USB-C Power Delivery standardization has eliminated proprietary connector lock-in. Margin compression is most severe in power bank tiers serving this user base.
- Event Planners:Temporary power requirements for outdoor events drive rental and short-term lease demand. Silent operation and zero-emission positioning differentiate battery solutions from generator alternatives.
Contractors anchor premium revenue. Outdoor enthusiasts are climbing the fastest.
Application:
Use case intensity determines thermal management requirements and duty cycle specifications that separate consumer-grade from industrial-grade product architectures.
- Industrial Applications:Continuous duty cycles and harsh operating environments mandate contractor-grade durability certifications. Cordless tool systems serving this application command the highest per-unit pricing through proprietary battery platform lock-in.
- Emergency Use:Reliability under grid failure conditions prioritizes battery management system sophistication and temperature cutoff threshold optimization. Stationary backup power stations with AC inversion circuitry dominate this application.
- Recreational Activities:Weight-constrained portability and solar charging compatibility shape product design. Camping lights and compact power banks with photovoltaic integration serve this expanding use case.
- Outdoor Events:Temporary, mobile power requirements favor rental and lease-to-own procurement models. Silent operation requirements exclude combustion alternatives from this application.
Industrial Applications defend margin concentration. Recreational Activities are gaining share fastest.
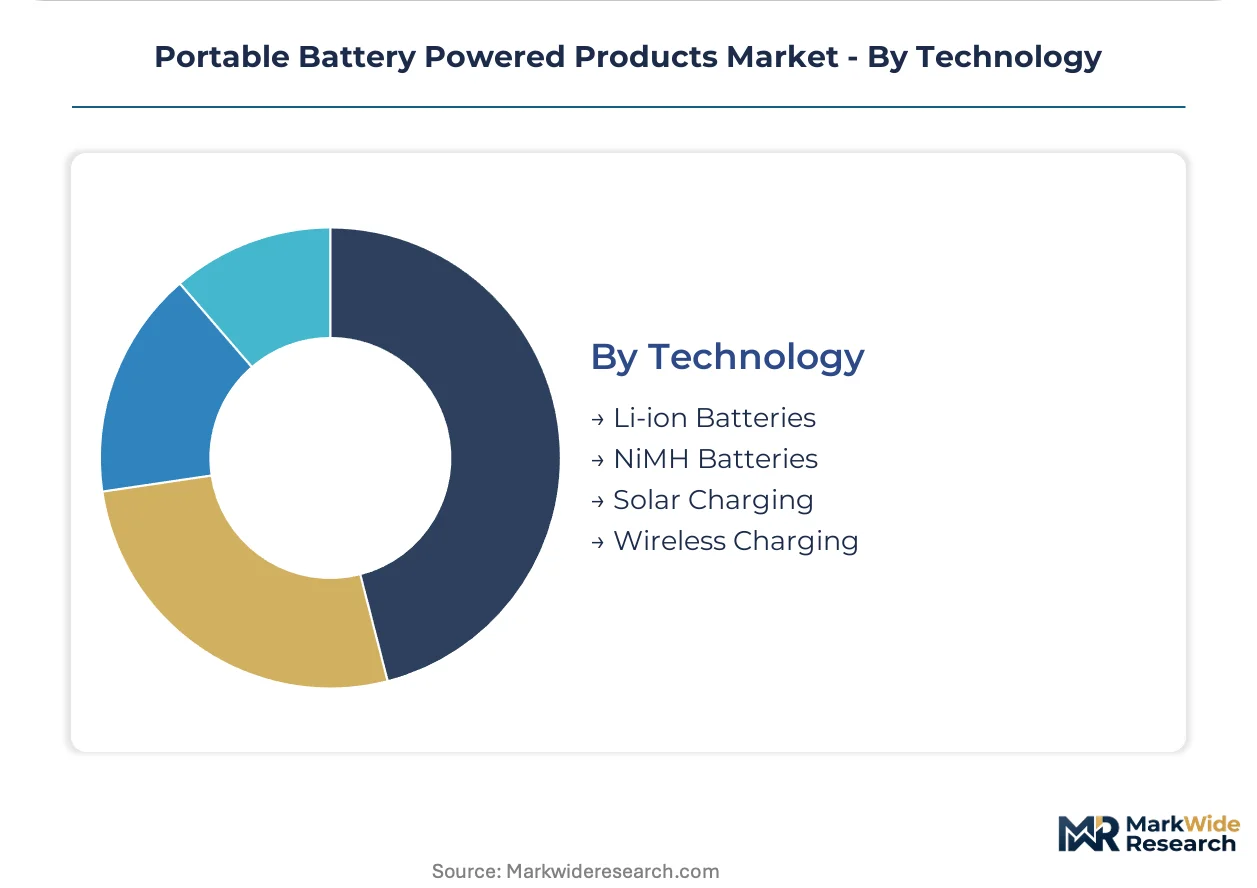
Technology:
Cell chemistry and charging modality choices determine energy density ceilings, thermal runaway risk profiles, and supply chain exposure to raw material volatility.
- Li-ion Batteries:NMC and LFP chemistries deliver 20-30% capacity increases within identical physical footprints through ongoing energy density improvements. Solid-state battery prototyping is consolidating next-generation performance benchmarks around thermal runaway immunity.
- Solar Charging:Photovoltaic conversion efficiency improvements are reducing panel surface area requirements for meaningful trickle charging. This modality represents the steepest expansion trajectory across portable power station and camping light categories.
- NiMH Batteries:Legacy chemistry retaining presence in price-sensitive consumer segments and specific cordless tool legacy platforms. Energy density limitations constrain new product development investment.
- Wireless Charging:Inductive and resonant architectures eliminate connector wear points in sealed, weatherproof designs. Adoption concentrates in premium portable speaker and power bank tiers where convenience commands price premiums.
Li-ion Batteries maintain installed base dominance. Solar Charging is reshaping competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and the United States diverge sharply in portable battery market maturity, with Chinese manufacturing clusters driving cost-efficient scale while US demand centers on premium contractor-grade cordless platforms and outdoor recreation equipment.
China
Shenzhen and Dongguan manufacturing corridors supply the majority of global lithium-ion cells and assembled power banks. SAMR enforces GB standards for transport safety and cycle life disclosure, filtering export eligibility for EU and US-bound products. BYD anchors automotive-scale cell production in Shenzhen, extending cost structures into consumer-facing power stations.
United States
Residential construction crews and outdoor enthusiasts drive parallel demand vectors for cordless tool systems and camping power stations. FAA regulations on lithium-ion air transport shape product packaging and labeling requirements for cross-border e-commerce channels. Milwaukee and Chicago industrial distribution hubs concentrate contractor procurement through platform subscription services.
Germany
EU Battery Regulation mandates for recycled content thresholds and digital passport traceability force supply chain redesigns for products entering European distribution. Stuttgart and Munich engineering clusters specialize in battery management system firmware development for industrial-grade applications. German contractor channels accelerate compliance investments ahead of enforcement deadlines.
Japan
METI oversight of battery safety standards and energy efficiency labeling shapes domestic product requirements and export specifications. Osaka and Nagoya industrial zones maintain precision manufacturing capabilities for cylindrical cell architectures and power management semiconductors. Japanese semiconductor-integrated designs consolidate positioning in premium portable speaker segments.
India
BIS certification requirements for lithium-ion cells create compliance gates for power bank imports targeting price-sensitive consumer segments. Noida and Pune electronics manufacturing clusters assemble entry-tier products for domestic distribution and regional export. India's PLI scheme for battery cell manufacturing is attracting investment toward localized supply chain development.
Portable Battery Powered Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium tiers consolidating around proprietary platform ecosystems while commoditized categories fragment across OEM assemblers. The vendor base organizes into three strategic archetypes: automotive-scale cell suppliers extending into consumer form factors, semiconductor-integrated electronics conglomerates, and pure-play power bank specialists facing margin compression. Capacity expansion and backward integration into captive cell chemistry represent the dominant competitive moves reshaping cost structures.
Within the automotive-scale extension archetype, BYD Co. Ltd. and LG Chem Ltd. occupy positions leveraging manufacturing scale to compress consumer power station pricing. Among semiconductor-integrated conglomerates, Samsung Electronics Co. Ltd. exemplifies the captive chip design strategy that differentiates runtime performance in compact form factors. Panasonic Holdings Corp. sits within the industrial-grade specialist tier, anchoring contractor-grade cordless tool battery platforms through chemistry expertise rather than brand premium in consumer channels.
| Leading Market Players |
|---|
| Anker Technology Co. Ltd. |
| Beijing Xiaomi Technology Co., Ltd. |
| Samsung Electronics Co. Ltd. |
| Panasonic Holdings Corp. |
| LG Chem Ltd. |
| Sony Group Corp. |
| ASUSTeK Computer Inc. |
| Energizer Holdings Inc. |
| BYD Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Embedded systems engineers with electrochemical safety expertise cluster in Shenzhen and Stuttgart, creating labor-cost differentials that widen pricing-tier spreads between premium battery management system firmware and commoditized power bank assembly.
Pricing Analysis
Capacity additions in China are reshaping price floors across cylindrical and prismatic cell tiers. Three-tier pricing structure across premium, standard, and economy levels separates contractor-grade cordless platforms with proprietary lock-in from USB-C Power Delivery commoditized units. Price differentiation rests on certification grade and volume scale. Cost compression in power bank tiers is intensifying because USB-C standardization eliminated switching costs. Consumers show highest price sensitivity; contractors demonstrate lowest sensitivity due to platform subscription bundling.
Supply Chain Analysis
Cobalt and lithium carbonate supply rests on Chilean mining operations and Chinese refining complexes. Cell manufacturing draws from China, South Korea, and Japan for cathode active materials and separator films. Raw material/component dependencies include lithium carbonate, cobalt sulfate, and electrolyte formulations. Single-source vulnerability in Chinese cylindrical cell production clusters exposes continuity to logistics disruptions. Distribution runs through big-box retail chains and industrial distributor platforms for contractor segments, direct-to-consumer e-commerce for power banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Battery Regulation recycled content thresholds and digital passport mandates are accelerating compliance investments ahead of enforcement deadlines.
For Market Incumbents: Lock in proprietary battery platform ecosystems through backward integration into captive cell chemistry and firmware development. Anchor contractor-grade cordless tool lines with subscription services bundling battery refresh cycles. Defend against automotive-scale cell suppliers extending into consumer power stations by deepening certification investments for EU Battery Regulation compliance.
For New Entrants and Emerging Players: Enter via solar charging integration for portable power stations serving German and French outdoor enthusiast channels. Target underpenetrated event planner rental segments where silent operation requirements exclude combustion alternatives. Pursue white-label assembly partnerships with Shenzhen manufacturing clusters to compress cost structures.
For Investors and Strategic Acquirers: Semiconductor-integrated electronics conglomerates are the most active acquirer in this space, seeking battery management system firmware capabilities. Long-term viability over the coming decade hinges on solid-state battery certification timeline acceleration. Monitor which regulatory jurisdiction moves first on solid-state safety standards as the inflection indicator for next-generation product launch windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Chemistry | BYD leverages automotive-scale production to compress consumer power station cost structures. |
| Subscription Battery Health Monitoring Launch | Predictive analytics layer creates recurring revenue above hardware sales for contractor fleets. |
| EU Battery Regulation Compliance Certification | Digital passport traceability systems unlock German and French distribution channel access. |
| Solar Charging Module Integration | Photovoltaic efficiency gains enable meaningful trickle charging in camping power stations. |
| Platform Subscription Service Rollout | Battery refresh bundling displaces retail replacement purchases in North American construction. |
Research Methodology
Coverage spans China, the United States, Germany, Japan, and India, with primary inputs from each market cluster. Primary interviews with battery management system firmware engineers, cordless tool procurement managers at construction firms, power bank category buyers at consumer electronics retailers, and solar charging module product developers were combined with secondary validation. Secondary sources include SAMR GB standards filings, EU Battery Regulation implementation guidance, BIS certification databases, FAA lithium-ion transport regulations, and customs trade data for cell and pack imports. Bottom-up unit shipment estimates and top-down value triangulation were cross-referenced for convergence.
Rate-of-change decomposition across the analysis window isolates volume growth from price-mix effects. Segmentation dimensions modeled include product type, end user archetype, application intensity, and cell chemistry pathway. CAGRs were derived through logistic diffusion curves for technology substitution and S-curve penetration modeling for solar charging adoption. Industry-specific forecast inputs incorporate SAMR enforcement timeline assumptions for export eligibility and photovoltaic conversion efficiency improvement trajectories.
Inputs from regulatory agency guidance documents and primary field contacts were available through the study window; gaps in solid-state battery certification timeline clarity introduce uncertainty bands around next-generation product launch assumptions. Forecasts reflect documented assumptions regarding SAMR, EU Battery Regulation, and FAA framework harmonization progress. Raw material price volatility and single-geography supply concentration represent material deviation triggers warranting pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Portable Battery Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
Battery Diagnostics and Repair Market
Batteries
Middle-East Battery Market
Batteries
Military Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Battery Pack Balancer Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
Netherlands Rechargeable Battery Market
Batteries
Li-Ion Pouch Battery Market
Batteries
VRLA Batteries Market
Batteries
GCC Rechargeable Battery Market
Batteries
Global Primary Cells Market
Batteries
Lead Carbon Battery Market
Batteries
Aluminum Based Battery Market
Batteries
US Motive Lead Acid Battery Market