
 Driving Simulator Market | 2026-2036
Driving Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Driving Simulator Market Intelligence
The ISO 26262 functional safety standard is reorganizing the competitive landscape for driving simulators used in automotive validation. IPG Automotive specializes in software solutions for virtual test driving that adhere to this standard. VI-Grade leverages its expertise in hardware-in-the-loop systems to serve major automotive OEMs. Ansible Motion differentiates with its high-fidelity dynamic simulators for vehicle engineering.
A driving simulator is an integrated system combining vehicle dynamics software, control hardware like steering and pedals, and a visual system to replicate real-world driving. These platforms provide a controlled environment for driver training, vehicle engineering, and research applications without physical prototypes. The research and development application segment commands the highest value, requiring sophisticated motion-based and full-cab simulators. Conversely, the driver training segment favors more accessible fixed-base and desktop simulators for broad deployment.
Regulations from bodies like the US National Highway Traffic Safety Administration (NHTSA) and compliance with UNECE vehicle standards drive simulator use for safety validation. In China, GB standards for intelligent connected vehicles also necessitate extensive virtual testing before road deployment. Vendor success will depend on the ability to accurately model complex sensor interactions and real-world edge cases in a virtual environment.
Market Dynamics
The imperative to validate advanced driver-assistance systems (ADAS) and autonomous vehicle software is the central force shaping the driving simulator market. This pressure, codified by functional safety standards like ISO 26262, is compelling a structural shift from physical to virtual testing environments.
Growth Catalysts
- Regulatory Mandates:The enforcement of UNECE vehicle regulations and NHTSA safety guidelines necessitates exhaustive testing of ADAS features, making virtual simulation a prerequisite for homologation and market access in Europe and the United States.
- ADAS Proliferation:The integration of increasingly complex sensor suites, including LiDAR, radar, and cameras, in mass-market vehicles requires simulation platforms capable of testing millions of virtual miles to validate software performance and safety.
- Automotive R&D Investment:Concentrated investment in vehicle engineering centers in Germany, Japan, and the United States creates persistent demand for high-fidelity, dynamic simulators to accelerate development cycles and reduce reliance on physical prototypes.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for sophisticated motion-based and full-cab simulators presents a substantial barrier to entry for smaller automotive suppliers, research institutions, and startups.
- Simulation Fidelity Gaps:Accurately modeling the complex physics of sensor perception and unpredictable human driver behavior in edge-case scenarios remains a significant technical limitation, impacting the reliability of virtual validation.
- Hardware Specialization:The supply of high-performance motion systems and control-loading hardware is concentrated among a few specialist manufacturers, creating potential supply chain bottlenecks and limiting OEM negotiating power.
Strategic Opportunities
- AI Model Training:The use of simulators to generate vast synthetic datasets for training and validating artificial intelligence and machine learning algorithms for autonomous driving represents a major growth vector beyond traditional vehicle dynamics.
- Immersive Technology Integration:Combining driving simulators with virtual reality (VR) and augmented reality (AR) headsets offers new possibilities for driver-in-the-loop studies, human-machine interface (HMI) design, and more realistic training environments.
- Emerging Market Adoption:Automotive industries in nations like India and Brazil are beginning to adopt stricter safety standards, creating new demand for cost-effective desktop and fixed-base simulators for engineering and training applications.
Industry Challenges
- Software Integration Complexity:Integrating disparate software models for vehicle dynamics, sensor simulation, and traffic environments into a single, cohesive, real-time platform is a major technical hurdle for vendors and users alike.
- Scenario Standardization Deficit:A lack of industry-wide standards for test scenarios, sensor models, and data formats hinders the seamless exchange of simulation data between automotive OEMs and their Tier-1 suppliers, causing project delays.
- Specialized Talent Scarcity:The market faces a shortage of engineers who possess the cross-disciplinary skills in vehicle dynamics, mechatronics, software engineering, and data science required to develop and operate advanced simulation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driving Simulator Market |
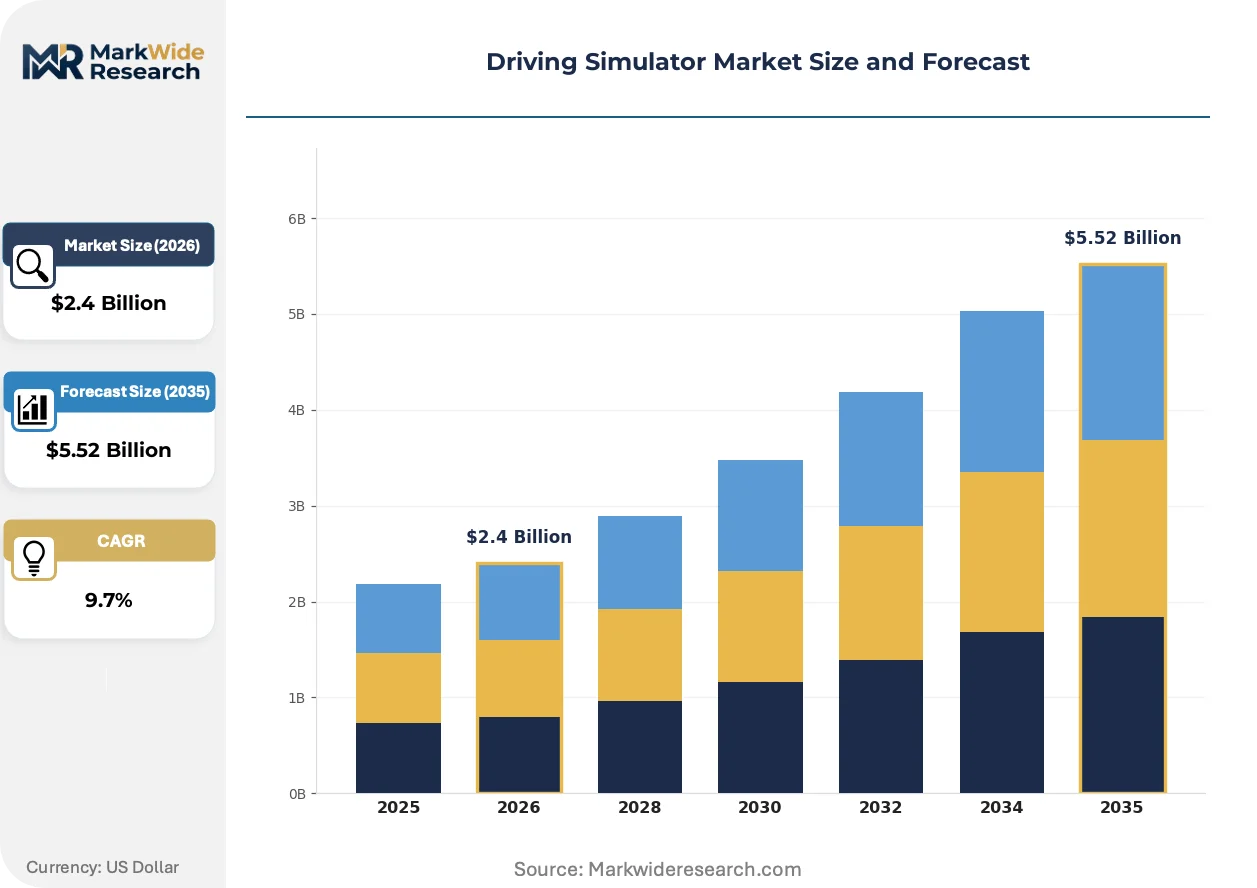
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Cab Simulators, Fixed-Base Simulators, Motion-Based Simulators, Desktop Simulators Technology: Virtual Reality, Augmented Reality, Mixed Reality, 3D Graphics Application: Driver Training, Research & Development, Vehicle Testing, Entertainment End User: Driver Schools, Automotive Manufacturers, Research Institutes, Fleet Operators |
| Companies Covered | Cruden, Ansible Motion, VI-Grade, Zen Technologies, AV Simulation, L3Harris Technologies, IPG Automotive, XPI Simulation, ECA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driving Simulator Market Strategic Shifts & Innovations
The market's evolution is defined by the automotive industry's pivot to a software-defined vehicle architecture. This transition elevates virtual testing from a supplementary tool to a core component of the development, validation, and certification process for modern vehicles.
Cloud-Based Simulation
Cloud-based simulation platforms provide scalable, on-demand computing power for running millions of test scenarios in parallel. Automotive OEMs and software-focused startups are rapidly adopting these platforms for large-scale validation of ADAS and autonomous driving software stacks. This flexible, opex-based model is supplanting the limitations of on-premise, hardware-constrained simulation clusters for mass-scale verification.
Regulation-Driven Virtual Proving Grounds
China's GB standards for intelligent connected vehicles (ICVs) are a powerful example of policy shaping technology adoption. These regulations require automakers to conduct extensive virtual testing in simulated Chinese traffic environments before any on-road testing is permitted. Consequently, any OEM targeting the Chinese market must invest in simulation tools capable of accurately modeling local driving behaviors, signage, and infrastructure.
Shift to Service-Based Models
Automotive startups and Tier-2 suppliers are increasingly moving away from large capital purchases of simulator hardware. Instead, they favor subscription-based Simulation-as-a-Service (SaaS) offerings that provide access to virtual testing environments and tools. This trend, most visible in the autonomous vehicle development hubs of the United States and Germany, lowers the barrier to entry and aligns costs with project-based usage.
Driving Simulator Market Segmentation
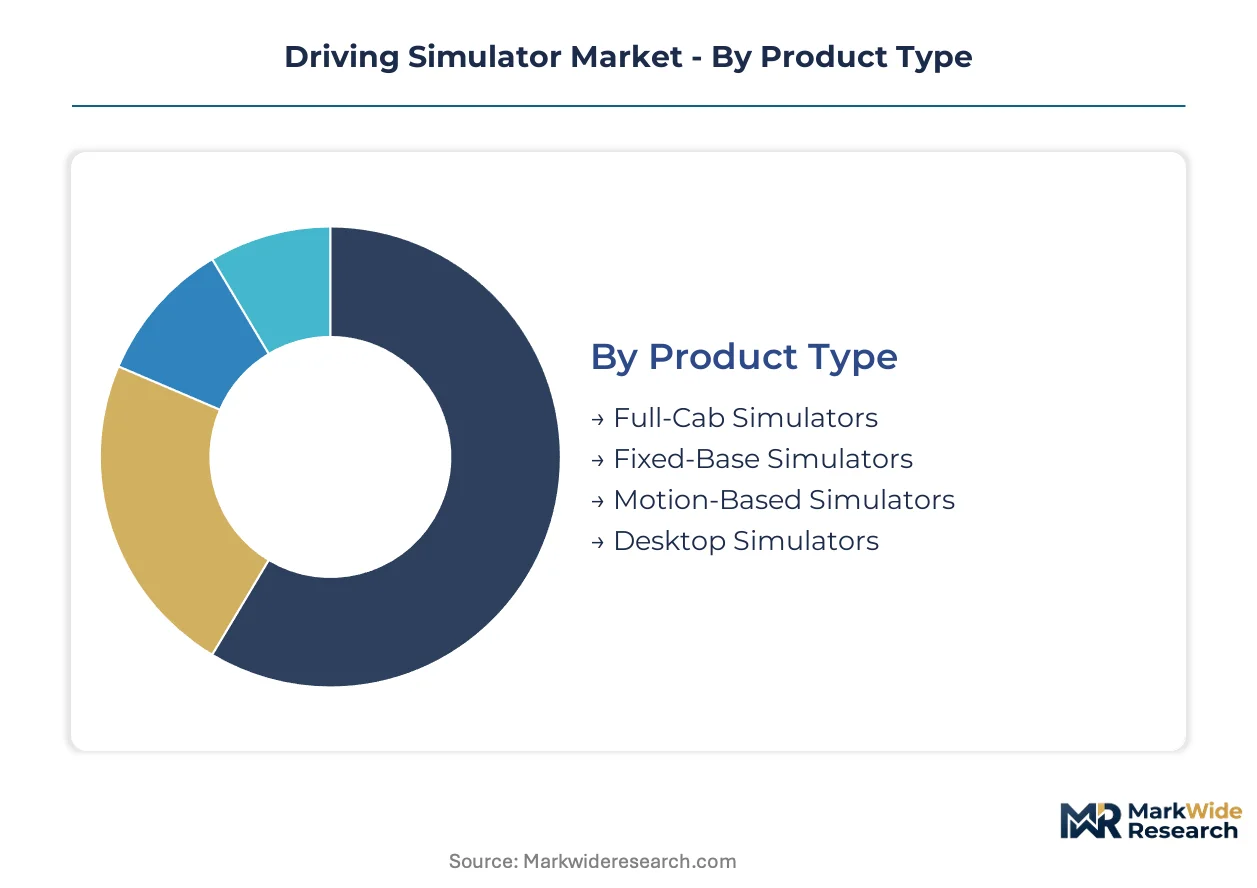
The driving simulator market categorizes its offerings to address diverse user requirements and technological advancements. Understanding these segments helps stakeholders identify specific demand patterns, assess competitive dynamics, and pinpoint areas for innovation within the automotive validation and training ecosystem.
Product Type:
The distribution of driving simulators varies significantly based on their physical configuration and complexity, influencing procurement channels.
- Full-Cab Simulators:These highly immersive systems replicate a complete vehicle interior, providing realistic physical and visual cues for advanced research and development. Demand concentrates in German and Japanese automotive engineering centers for complex vehicle dynamics and HMI validation.
- Motion-Based Simulators:These platforms incorporate sophisticated motion systems to simulate g-forces and vehicle movements, crucial for high-fidelity vehicle testing and ADAS validation. Automotive manufacturers in the United States prioritize these for validating autonomous driving software and sensor fusion algorithms.
- Fixed-Base Simulators:Lacking significant motion platforms, these simulators offer a static yet interactive driving environment, suitable for driver training and initial concept validation.
- Desktop Simulators:Comprising a computer, steering wheel, and pedals, these entry-level systems provide basic driving simulation for educational purposes or preliminary software testing.
By volume, Desktop Simulators lead. By growth pace, Motion-Based Simulators are ahead.
Technology:
The underlying technological components define the level of immersion and realism offered by driving simulators for various applications.
- Virtual Reality:This technology provides a fully immersive digital environment, crucial for driver-in-the-loop studies and designing human-machine interfaces. Automotive OEMs use VR extensively to evaluate user experience and interaction with new ADAS features.
- 3D Graphics:This foundational technology renders realistic visual environments, essential for accurately simulating complex traffic scenarios and diverse road conditions. Research institutes leverage advanced 3D graphics for creating detailed virtual proving grounds for autonomous vehicle testing.
- Augmented Reality:AR overlays digital information onto the real-world view, offering potential for hybrid physical-virtual testing environments and advanced training modules.
- Mixed Reality:MR blends virtual and real-world elements interactively, enabling new forms of collaborative design and real-time interaction with physical prototypes.
Virtual Reality technology contributes the highest value. 3D Graphics technology demonstrates consistent, foundational importance.
Application:
Different user types drive simulator adoption based on their specific needs, from research to training.
- Research & Development:This segment requires high-fidelity, customizable simulators for exploring new vehicle concepts, advanced control algorithms, and human factors. Automotive manufacturers and research institutes drive demand for these sophisticated platforms for cutting-edge innovation.
- Vehicle Testing:This application focuses on validating vehicle performance, safety systems, and ADAS/AV software before physical prototyping. German and Japanese automotive engineering centers heavily invest in simulators for regulatory compliance and accelerated development cycles.
- Driver Training:This segment utilizes simulators to educate new drivers, provide refresher courses, and train for specific hazardous conditions in a safe, controlled environment.
- Entertainment:Simulators in this category prioritize engaging user experiences and recreational driving, often found in arcades or consumer markets.
Research & Development applications command the highest value. Vehicle Testing applications are expanding most quickly.
End User:
The scale of investment and operational requirements vary significantly among end-user categories, influencing procurement volumes.
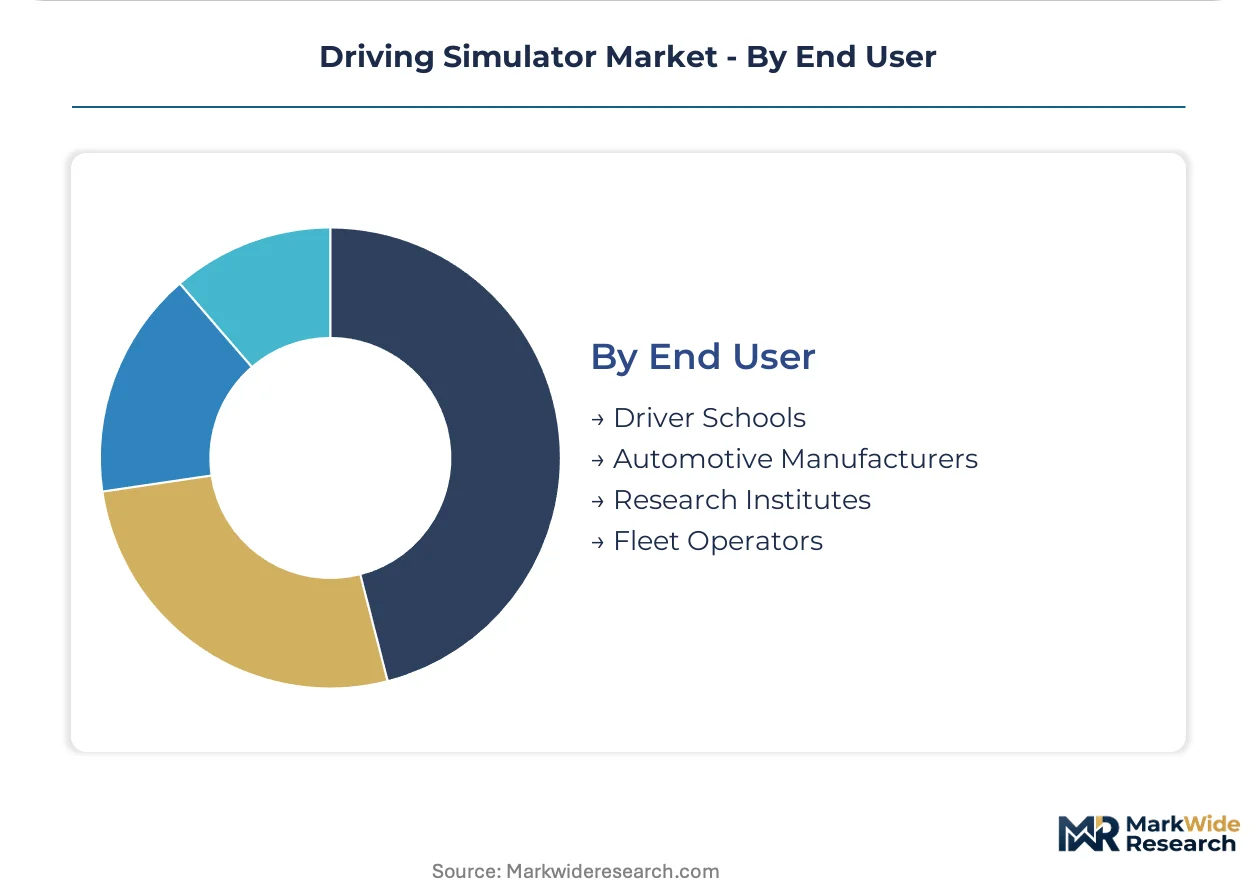
- Automotive Manufacturers:These entities represent the largest procurement volume, utilizing simulators across their entire product development lifecycle, from concept to validation. Large OEMs in the United States and Germany invest heavily in motion-based and full-cab systems for ADAS and autonomous vehicle development.
- Research Institutes:Academic and private research bodies employ simulators for specialized studies in vehicle dynamics, human factors, and traffic safety. These institutes often collaborate with manufacturers, driving demand for flexible, high-precision simulation environments.
- Driver Schools:These educational institutions acquire simulators primarily for cost-effective and safe driver instruction, focusing on fixed-base and desktop solutions.
- Fleet Operators:Commercial fleet companies use simulators for driver assessment, training for specific vehicle types, and promoting fuel-efficient driving practices.
Automotive Manufacturers represent the largest strategic focus. Research Institutes demonstrate consistent demand for specialized solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The extensive global automotive manufacturing infrastructure underwrites significant demand for driving simulators across key regions. These sophisticated platforms are indispensable for validating advanced vehicle technologies and training skilled personnel. This strategic investment in virtual testing environments accelerates product development cycles.
United States
United States demand for driving simulators centers on validating advanced driver-assistance systems and autonomous vehicle software. NHTSA safety guidelines mandate rigorous virtual testing for new vehicle features. Detroit, Michigan, serves as a major hub for automotive research and development, driving simulator procurement.
Germany
German automotive engineering centers require high-fidelity simulators for vehicle dynamics and ISO 26262 functional safety validation. UNECE vehicle regulations necessitate extensive virtual testing for market access. The Stuttgart region, home to major OEMs, consistently invests in advanced simulation platforms.
Japan
Japanese automotive manufacturers prioritize driving simulators for advanced research and development and human-machine interface validation. METI initiatives support the development of connected and autonomous vehicle technologies, encouraging virtual testing. Toyota City, a core automotive cluster, drives demand for cutting-edge simulation tools.
China
China's market for driving simulators is shaped by the need for extensive virtual testing of intelligent connected vehicles. GB standards mandate rigorous simulation in local traffic environments before road deployment. The Yangtze River Delta region, a hub for electric vehicle production, sees significant simulator adoption.
India
Indian automotive industries increasingly adopt driving simulators for driver training and cost-effective engineering solutions. Government initiatives promoting road safety and BIS standards for vehicle components drive simulator procurement. Chennai, a prominent automotive manufacturing center, demonstrates rising demand for these platforms.
Driving Simulator Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of driving simulator complexity and fidelity. The market structure is tiered, with highly specialized vendors focusing on niche applications. Strategic archetypes include software-centric providers, hardware-focused integrators, and full-solution developers. Dominant competitive moves involve strategic partnerships with automotive OEMs and portfolio diversification into Simulation-as-a-Service offerings.
Specialists in high-fidelity motion systems include Cruden, known for advanced dynamic platforms and immersive experiences. Ansible Motion exemplifies providers focusing on driver-in-the-loop simulators for vehicle engineering and human factors research. VI-Grade occupies a position as a key supplier leveraging expertise in hardware-in-the-loop systems for major automotive OEMs. These entities anchor the premium segment of the market, offering sophisticated solutions for complex validation tasks and accelerating development cycles for automotive manufacturers globally. Their offerings address the demanding requirements for autonomous vehicle and ADAS testing.
| Leading Market Players |
|---|
| Cruden |
| Ansible Motion |
| VI-Grade |
| Zen Technologies |
| AV Simulation |
| L3Harris Technologies |
| IPG Automotive |
| XPI Simulation |
| ECA Group |
| Others |
Cost & Logistics Intelligence
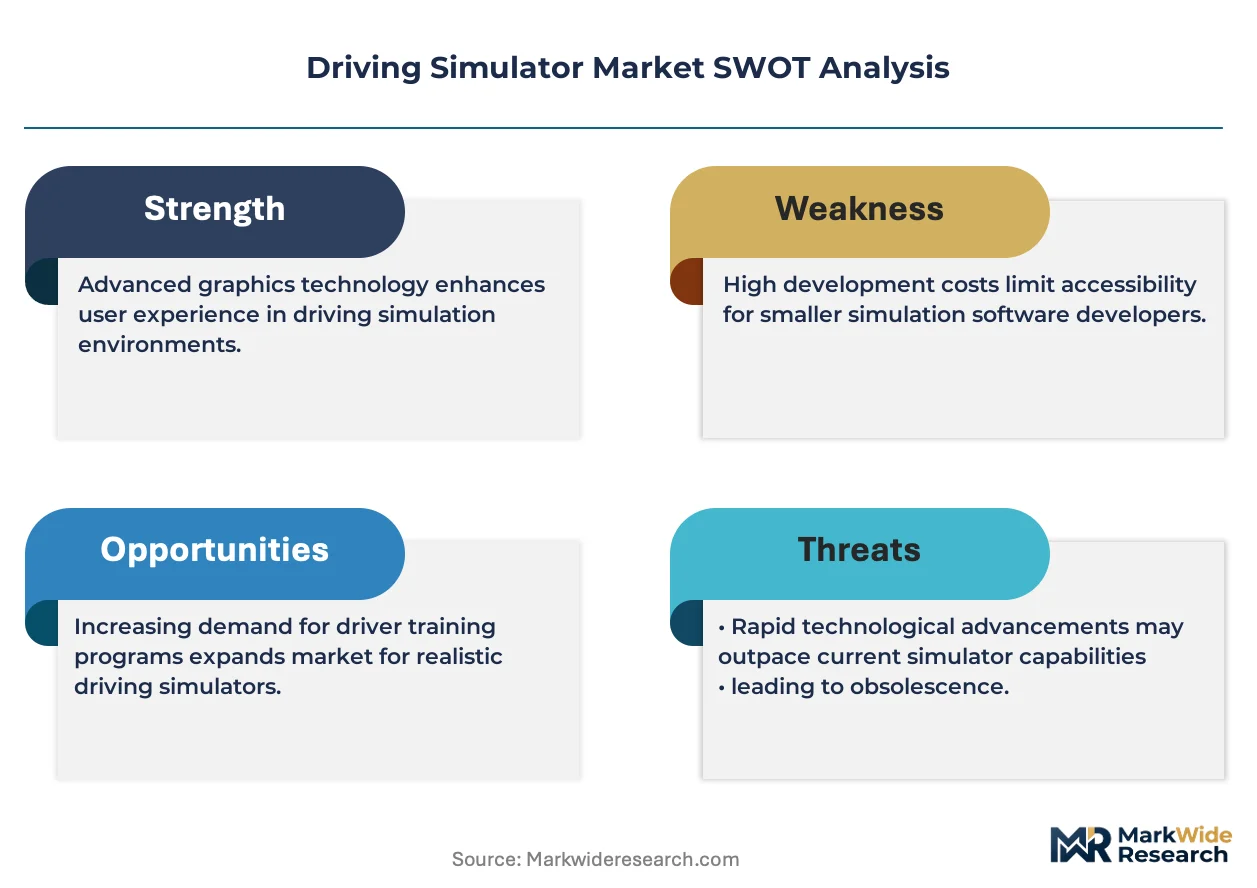
ISO 26262 functional safety standard gates both supply qualification and price differentiation for driving simulators. This critical standard requires advanced validation capabilities, driving up hardware and software costs across the ecosystem.
Pricing Analysis
Volume-based licensing for software and tiered hardware configurations dominate driving simulator pricing structures. Price differentiation stems from the ISO 26262 certification level for software modules and the performance fidelity of motion systems. Pricing pressure intensifies from cloud-based Simulation-as-a-Service (SaaS) models offering lower upfront capital expenditure. Driver schools exhibit the most price sensitivity, while automotive manufacturers demonstrate the least due to validation imperatives.
Supply Chain Analysis
Germany, Japan, and the United States anchor high-fidelity motion system and specialized software development for driving simulators. The supply chain relies heavily on high-performance motion systems, control-loading hardware, and advanced vehicle dynamics software libraries. Single-source vulnerability for niche, high-performance components presents a structural supply chain risk. Distribution runs primarily through direct sales channels and specialized system integrators serving automotive engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a high-growth disruption, with the imperative to validate advanced driver-assistance systems acting as a key technological inflection point.
For Market Incumbents:Compound existing expertise in vehicle dynamics software and hardware integration. Deepen vertical integration into specialized motion system manufacturing to control component quality and supply. Secure long-term software licensing agreements with major automotive OEMs for predictable revenue streams. Invest in AI model training capabilities for synthetic data generation to counter emerging cloud-based simulation providers.
For New Entrants and Emerging Players:Underserved segments requiring cost-effective desktop and fixed-base simulators present clear entry points. Target driver training applications in nations like India and Brazil, alongside preliminary software testing for Tier-2 automotive suppliers. Offer subscription-based Simulation-as-a-Service (SaaS) models to lower the barrier to entry for smaller organizations. Focus on specialized sensor simulation or scenario generation tools.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting downwards across the software-defined vehicle validation segment, favoring flexible solutions. Long-term value creation resides in platforms supporting AI/ML training and scalable cloud infrastructure. Target specialized software firms offering advanced sensor simulation or scenario generation tools for strategic acquisition. Increasing adoption rates of SaaS models by smaller automotive players is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Development | Accelerates large-scale ADAS validation for automotive OEMs. |
| Synthetic Data Generation Investment | Enhances AI model training for autonomous driving software. |
| Strategic OEM Partnerships | Secures long-term contracts for high-fidelity simulator sales. |
| Subscription Service Expansion | Lowers entry barriers for Tier-2 suppliers and startups. |
| Immersive Technology Integration | Improves human-machine interface design and driver-in-the-loop studies. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during this analysis, combining primary interviews with secondary validation. Stakeholders included automotive OEM R&D directors, Tier-1 ADAS engineers, simulation software developers, and driver training school administrators. Secondary data sources comprised industry reports, technical papers, automotive association publications, and regulatory body guidelines from NHTSA, UNECE, and ISO. This approach involved bottom-up market sizing and top-down validation.
The analysis window extends over the projection horizon, utilizing a robust analytical framework. Segmentation dimensions modeled include product type, technology, application, end-user, and geographic region. Compound Annual Growth Rates (CAGRs) were derived through regression analysis and expert consensus. Key industry-specific forecast inputs included vehicle production forecasts and ADAS penetration rates across major automotive markets.
Forecasts assume regulatory continuity in US NHTSA and EU UNECE regimes; material policy shifts would require re-modeling. Specific risk factors include rapid technological obsolescence or unforeseen changes in global automotive safety standards. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Driving Simulators Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Automotive Battery Testing Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market
Automotive Testing and Simulation
Automotive TIC Market