
 Vehicle Chassis Dynamometers Market | 2026-2036
Vehicle Chassis Dynamometers Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Chassis Dynamometers Market Insights
Consolidation among automotive OEM testing departments is repositioning procurement authority toward centralized powertrain validation centers. HORIBA leverages its emission measurement integration to dominate integrated test cell contracts. AVL List GmbH sustains technology leadership through R&D intensity in electric drivetrain simulation. Mustang Dynamometer anchors the North American aftermarket segment with specialized motorcycle and performance automotive equipment.
A vehicle chassis dynamometer is a test apparatus consisting of electrically, hydraulically, or mechanically loaded rollers that simulate road load conditions to measure power output, fuel consumption, and exhaust emissions from complete vehicles under controlled laboratory conditions. The primary commercial purpose is to provide repeatable, standardized test environments for regulatory certification and product development. Four-Wheel Drive and All-Wheel Drive configurations are capturing disproportionate investment as electrified all-wheel powertrains proliferate across passenger and light-commercial segments. Electric technology leads the technology split due to precision torque control and energy recuperation capabilities, while Hybrid systems serve transitional powertrain portfolios where OEMs require flexible loading profiles.
EPA test procedures in the United States, Euro 7 standards under EMA frameworks, and China's GB emission regulations collectively mandate increasingly granular chassis dynamometer accuracy for type-approval testing. These regulatory layers directly shape equipment refresh cycles and calibration service demand across national markets. Stakeholders must monitor how real-driving emission supplement protocols alter the boundary between laboratory dynamometer testing and portable emission measurement systems.
Market Dynamics
Electrification of powertrain architectures is forcing chassis dynamometer manufacturers to rebuild loading systems around bidirectional energy flows and regenerative braking simulation. EPA and Euro 7 protocols now mandate traceable torque measurement precision that legacy mechanical systems cannot achieve.
Growth Catalysts
- EPA Emission Certification:United States type-approval testing requires chassis dynamometer validation for all light-duty vehicles, creating mandatory equipment refresh cycles at OEM facilities and independent labs.
- Electric Drivetrain Proliferation:Battery-electric and hybrid powertrains demand multi-axle dynamometer configurations with synchronized torque vectoring simulation across all four wheels.
- China GB Standards Enforcement:The country's national environmental regulator tightened laboratory testing requirements, accelerating domestic dynamometer installation rates at vehicle manufacturing centers.
Market Restraints
- Copper and Rare Earth Input Costs:Electric dynamometer systems depend on permanent magnet motors and high-conductivity windings, exposing manufacturers to commodity price volatility in magnet supply chains concentrated in China.
- Calibration Infrastructure Concentration:ISO 17025-accredited calibration laboratories for chassis dynamometer traceability cluster in Germany, Japan, and the United States, creating service access barriers for facilities in emerging markets.
- Mechanical System Obsolescence Risk:Eddy-current and hydraulic loading technologies face accelerated displacement by electric motor-based systems, stranding capital in installed mechanical bases.
Strategic Opportunities
- India Automotive Testing Expansion:The country's PLI scheme for electric vehicle manufacturing is stimulating demand for localized chassis dynamometer capacity at new powertrain validation centers.
- Real-Driving Emissions Correlation:Portable emission measurement system integration with laboratory dynamometer protocols creates service revenue streams in test-cycle harmonization consulting.
- Used Vehicle Inspection Mandates:Periodic technical inspection regulations in European Union member states are expanding aftermarket dynamometer installation for roadworthiness testing stations.
Industry Challenges
- Power Electronics Specialist Scarcity:Electric dynamometer development requires engineers proficient in motor control algorithms and grid-tied inverter design, talent pools that automotive test equipment manufacturers compete for against renewable energy and industrial automation sectors.
- Multi-Protocol Certification Timelines:Simultaneous validation against EPA, Euro 7, and China GB test cycles extends product development cycles and strains engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Chassis Dynamometers Market |
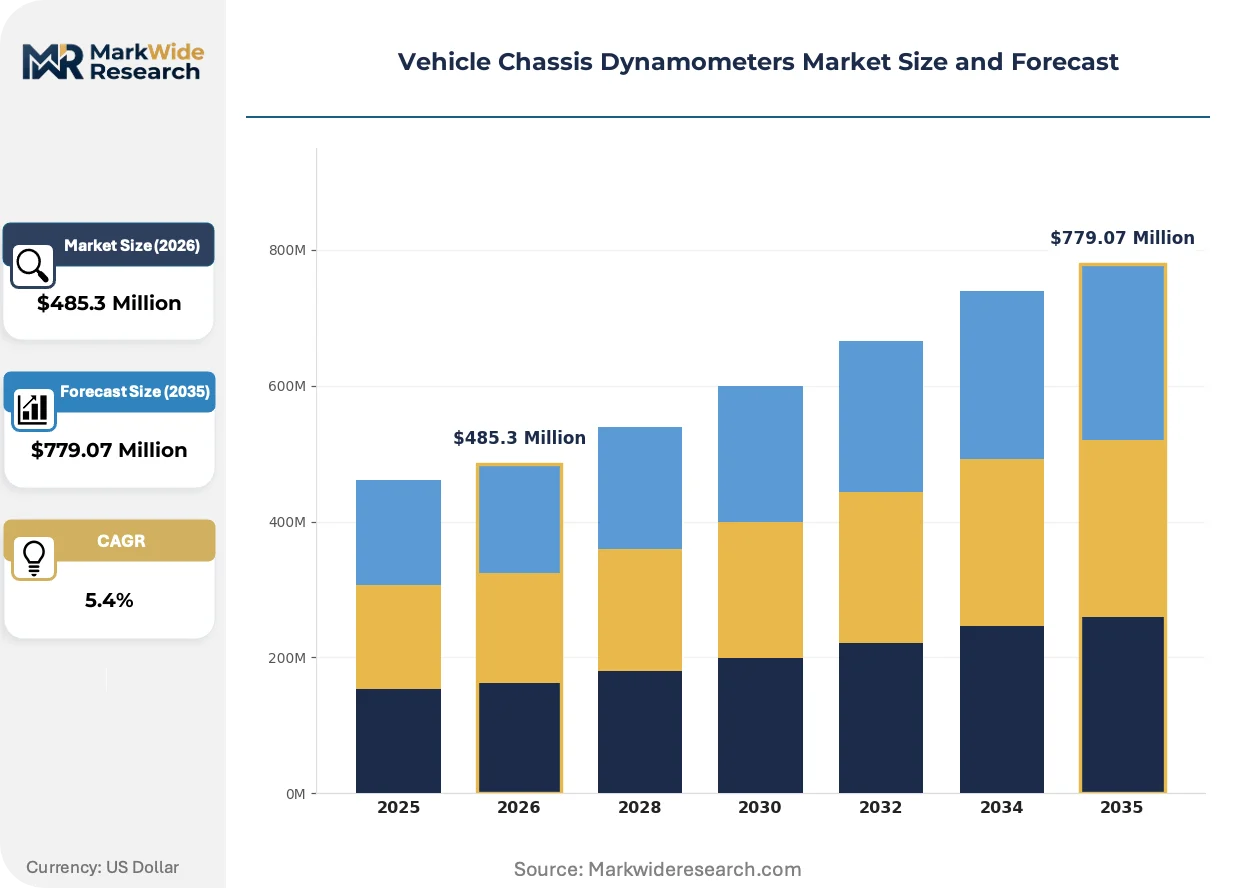
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $779.07 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Wheel Drive, Four-Wheel Drive, All-Wheel Drive, Heavy-Duty Technology: Electric, Hydraulic, Mechanical, Hybrid End User: OEMs, Aftermarket Providers, Research Institutions, Fleet Operators Application: Performance Testing, Emission Testing, Calibration, Research & Development |
| Companies Covered | HORIBA, AVL List GmbH, Mustang Dynamometer, MTS Systems Corporation, Meidensha Corporation, MAHA Maschinenbau Haldenwang, Rototest, Dynojet Research, SuperFlow Dynamometers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Chassis Dynamometers Market Trends and Innovations
Digital twin integration is compressing the boundary between physical dynamometer testing and virtual powertrain simulation. Equipment suppliers now compete on software-defined loading profile flexibility rather than mechanical hardware specifications alone.
Electric motor-based dynamometer systems is overtaking legacy eddy-current and hydraulic alternatives in new installations. Tier 1 suppliers and OEM validation centers specify permanent magnet synchronous motor architectures for their nanosecond torque response and energy recuperation capabilities. This displacement is compressing the addressable market for mechanical loading component suppliers.
Euro 7 standards under EMA frameworks mandate expanded cold-start emission testing and extended durability cycles. The regulation forces dynamometer manufacturers to extend climatic chamber integration and automate prolonged test sequences. Passenger car powertrain divisions in European OEMs are prioritizing equipment with 24/7 unmanned operation capability.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts. End-users in North American aftermarket segments now procure calibration and software update services through third-party metrology providers rather than original equipment manufacturers. This pattern is most visible in performance automotive tuning shops and motorcycle certification facilities.
Vehicle Chassis Dynamometers Market Segmentation
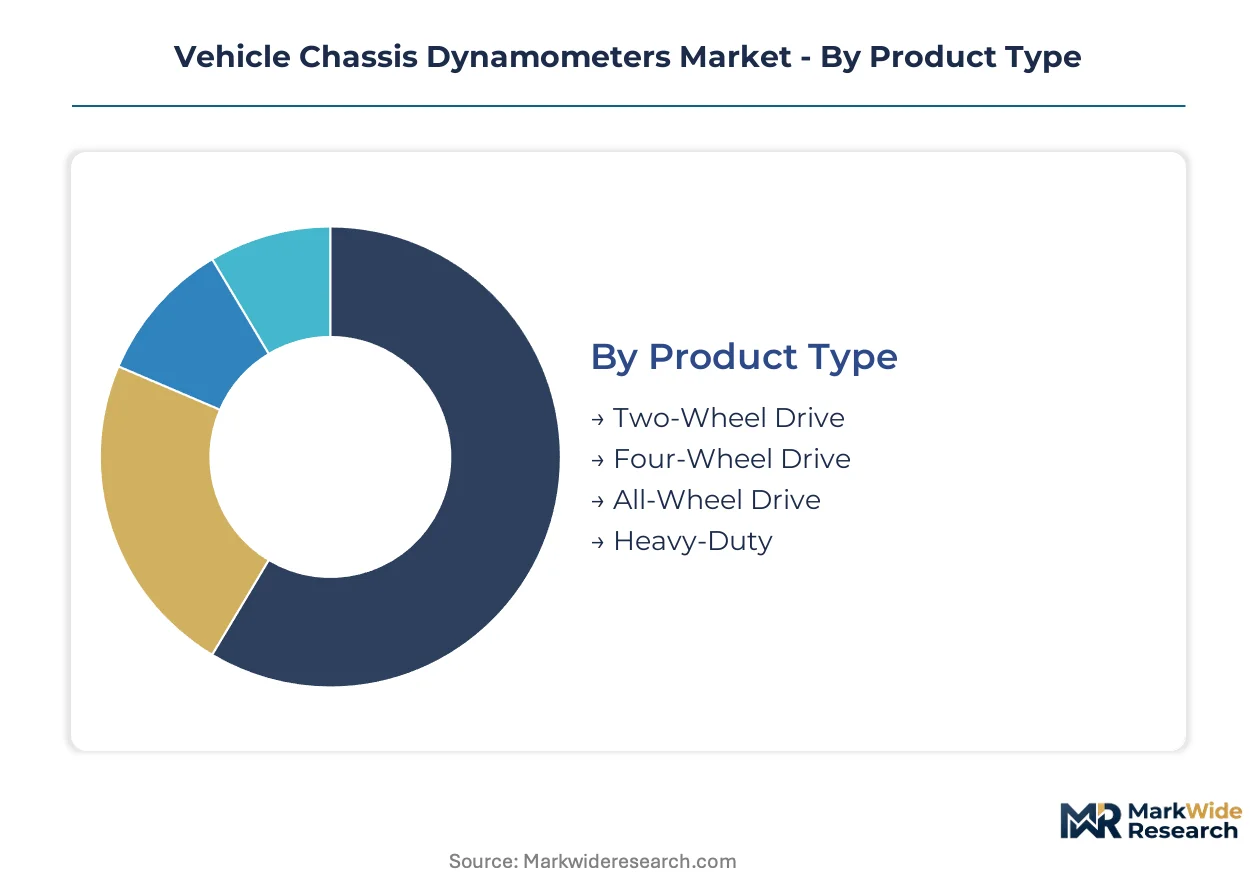
Chassis dynamometer procurement decisions hinge on certification scope, powertrain architecture, and operational throughput requirements. Equipment specifications diverge sharply between regulatory compliance mandates and product development workflows, creating distinct value tiers across each segmentation axis.
Product Type:
EPA, Euro 7, and China GB emission certifications each impose distinct axle-loading requirements that reshape equipment specifications across configurations.
- Four-Wheel Drive:Synchronized roller sets simulate torque vectoring across front and rear axles with nanosecond response times. European OEM validation centers in Germany and Spain are concentrating investment here as electrified all-wheel powertrains proliferate across premium passenger segments.
- Two-Wheel Drive:Single-axle roller assemblies dominate entry-level certification workflows for front-wheel-drive urban vehicles. Fleet testing facilities in India and Brazil specify these configurations for high-throughput periodic inspection stations where capital constraints limit equipment spend.
- All-Wheel Drive:Independent motor control per wheel enables dynamic torque distribution simulation for advanced drivetrain development.
- Heavy-Duty:Reinforced roller beds and expanded power electronics accommodate commercial vehicle mass and torque loads.
Leading the category by volume: Two-Wheel Drive. Growing fastest: Four-Wheel Drive.
Technology:
Capital deployment patterns reflect a structural migration from mechanical loading toward precision motor architectures, with cost tiers stratifying across installation scale.
- Electric:Permanent magnet synchronous motors deliver bidirectional energy flow and regenerative braking simulation with sub-millisecond torque control. OEM testing facilities in Japan, South Korea, and the United States are standardizing on electric systems to meet traceability mandates under tightening EPA and Euro 7 protocols.
- Hybrid:Combines electric precision with hydraulic peak-loading capacity for transitional powertrain portfolios. Chinese domestic manufacturers favor hybrid architectures to accommodate both legacy internal combustion and emerging electric validation requirements within single test cells.
- Hydraulic:Piston-based loading systems persist in heavy-duty applications where sustained high-torque operation outweighs precision demands.
- Mechanical:Eddy-current and friction-based systems face accelerated obsolescence as calibration traceability requirements tighten.
Highest margin concentration: Electric. Steepest expansion trajectory: Hybrid.
End User:
Customer procurement authority is consolidating toward centralized validation centers, fragmenting traditional equipment sales channels.
- OEMs:Integrated powertrain validation centers in Germany, Japan, and the United States command multi-million-dollar test cell contracts with 24/7 unmanned operation specifications. These facilities prioritize equipment with seamless climatic chamber integration and automated test sequencing under Euro 7 and EPA cold-start protocols.
- Aftermarket Providers:Performance tuning shops and motorcycle certification facilities in North America procure specialized single-axle systems. Service unbundling trends drive these customers toward third-party calibration providers rather than manufacturer maintenance contracts.
- Research Institutions:University and national laboratory facilities prioritize software-defined loading flexibility for academic powertrain research.
- Fleet Operators:Commercial vehicle maintenance depots deploy dynamometers for periodic roadworthiness verification and fuel consumption monitoring.
Dominant revenue share: OEMs. Fastest procurement growth: Aftermarket Providers.
Application:
Regulatory test cycles and product development timelines impose divergent equipment performance specifications across use cases.
- Emission Testing:Standardized drive cycles for EPA, Euro 7, and China GB type-approval demand repeatable road-load simulation with documented traceability chains. Equipment serving this application requires ISO 17025-accredited calibration infrastructure concentrated in Germany, Japan, and the United States.
- Research & Development:Virtual powertrain correlation and digital twin integration compress development cycles for battery-electric architectures. R&D facilities in South Korea and Sweden specify dynamometers with real-time software-defined loading profile adjustment.
- Performance Testing:Maximum power verification and drivetrain durability assessment for motorsport and premium automotive segments.
- Calibration:Periodic metrology services for installed equipment bases generate recurring revenue streams independent of new hardware sales.
Largest installed base: Emission Testing. Gaining share fastest: Research & Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest share of new chassis dynamometer installations among single-country markets, with OEM testing facilities expanding capacity to handle electric vehicle powertrain validation. The United States and Germany follow as concentrated centers for emission certification equipment demand driven by EPA and Euro 7 protocols.
China
Domestic vehicle manufacturers are scaling powertrain validation centers in Shanghai and Beijing to meet GB standards enforcement from the national environmental regulator. The country's PLI scheme for electric vehicle manufacturing accelerates localized chassis dynamometer procurement. Industrial clusters in the Yangtze River Delta concentrate new installation activity for battery-electric drivetrain testing.
United States
EPA emission certification requirements mandate chassis dynamometer validation for all light-duty vehicles, creating mandatory equipment refresh cycles at OEM facilities in Michigan and California. Independent testing laboratories in the Detroit metro area expand capacity to serve type-approval workflows. The Southwest region sees aftermarket dynamometer demand from performance automotive tuning shops.
Germany
Euro 7 standards under EMA frameworks tighten test-cycle accuracy demands for cold-start emission testing and extended durability cycles. OEM validation centers in Stuttgart and Munich prioritize equipment with 24/7 unmanned operation capability. ISO 17025-accredited calibration laboratories cluster in Bavaria and Baden-Württemberg, creating service infrastructure concentration.
Japan
Automotive OEMs in the Nagoya and Tokyo regions standardize on electric motor-based dynamometer systems to meet traceability mandates under tightening emission protocols. METI industrial policy supports powertrain electrification R&D facilities requiring multi-axle configurations. Tier 1 suppliers concentrate validation investment in the Chubu region for synchronized torque vectoring simulation.
India
The PLI scheme for electric vehicle manufacturing stimulates demand for localized chassis dynamometer capacity at new powertrain validation centers in Maharashtra and Tamil Nadu. Fleet testing facilities in Gujarat specify two-wheel drive configurations for high-throughput periodic inspection stations. Domestic installation rates accelerate as OEMs establish emission testing compliance for export markets.
Vehicle Chassis Dynamometers Market Competitive Landscape
German and Japanese producers anchor one tier; North American specialists hold aftermarket positioning. The vendor base splits between integrated test cell contractors serving OEM validation centers and equipment fabricators targeting independent laboratories. Three archetypes dominate: emission measurement integrators, electric drivetrain simulation specialists, and performance automotive equipment providers. Competitive moves concentrate on strategic partnerships for climatic chamber integration and geographic expansion into emerging Asian markets.
Among Germany-based fabricators, HORIBA and AVL List GmbH exemplify the integrated systems tier, with HORIBA representing emission measurement convergence and AVL List GmbH occupying a position in electric drivetrain simulation development. Mustang Dynamometer anchors the North American aftermarket segment. These three names illustrate how competitive positioning splits between regulatory compliance infrastructure and specialized performance equipment channels.
| Leading Market Players |
|---|
| HORIBA |
| AVL List GmbH |
| Mustang Dynamometer |
| MTS Systems Corporation |
| Meidensha Corporation |
| MAHA Maschinenbau Haldenwang |
| Rototest |
| Dynojet Research |
| SuperFlow Dynamometers |
| Others |
Pricing and Supply Chain Analysis
Backward integration into permanent magnet motor production anchors pricing power for Japanese and German equipment fabricators serving EPA and Euro 7 certification workflows. OEM validation centers concentrate procurement authority toward multi-year test cell contracts, compressing margin flexibility for component suppliers locked into spot-market rare earth sourcing.
Pricing Analysis
Volume concentrates in two-wheel drive configurations for fleet inspection stations, while margin pools in four-wheel electric systems for OEM powertrain validation. Pricing stratifies across certification-grade tiers, with ISO 17025-accredited equipment commanding substantial premiums over uncertified alternatives. Cost compression in the mechanical loading segment intensifies as electric motor architectures displace legacy eddy-current systems. Aftermarket providers in North America exhibit highest price sensitivity, whereas integrated test cell contractors prioritize traceability compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Tier 1 automotive suppliers mandate qualified second sources for permanent magnet synchronous motors and high-conductivity windings. Manufacturing concentrates in Germany, Japan, and China, with precision machining of roller assemblies anchored in Bavarian and Nagoya industrial clusters. Copper and neodymium dependencies expose producers to commodity volatility concentrated in Chinese processing facilities. Single-source vulnerability in rare earth magnet supply chains represents the dominant structural risk. Distribution runs through direct OEM test cell contracting and regional equipment distributor networks serving independent laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics specialist scarcity constrains capacity expansion across electric dynamometer manufacturing, propping pricing for qualified system integrators. This bottleneck limits supply response to accelerating demand from electrified powertrain validation centers.
For Market Incumbents: Deepen captive supply control over permanent magnet motor windings to insulate margins from rare earth price volatility. Consolidate calibration service infrastructure in emerging markets to preempt third-party metrology entrants. The displacement of hydraulic loading technologies by electric architectures threatens stranded capital in installed mechanical bases. For New Entrants and Emerging Players: Euro 7 in the European Union opens a window for climatic chamber integration specialists to capture share from incumbent test cell contractors. Target India's PLI-stimulated powertrain validation centers for localized assembly partnerships. Pursue software-defined loading profile development as a differentiated entry vector against hardware-centric competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial automation conglomerates seeking automotive test exposure. The five-to-ten-year viability window favors electric drivetrain simulation capabilities over mechanical loading legacy. Acquisition targets should demonstrate ISO 17025-accredited calibration infrastructure or permanent magnet motor control IP. Monitor EPA protocol amendments as the critical inflection signal for equipment refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | Captures margin premium from EPA torque traceability mandates displacing hydraulic alternatives. |
| Climatic Chamber Partnership | Secures Euro 7 cold-start testing contracts requiring extended temperature range simulation. |
| Calibration Infrastructure Expansion | Addresses ISO 17025 laboratory concentration in Germany, Japan, and United States. |
| Software-Defined Loading Platform | Enables real-time profile adjustment for digital twin correlation in R&D workflows. |
| India Manufacturing Localization | Aligns with PLI scheme requirements for domestic electric vehicle testing capacity. |
Research Methodology
Document review covered EPA test procedure filings, Euro 7 regulatory drafts, and China GB standard updates, complemented by interviews with OEM powertrain validation directors, Tier 1 supplier procurement managers, and independent testing laboratory operators. Secondary sources included vehicle production databases, customs trade records for dynamometer equipment, and SEC filings from listed test equipment manufacturers. Bottom-up equipment installation tracking and top-down OEM R&D expenditure analysis were triangulated against regulatory mandate timelines.
Cross-referencing historical installation patterns against expert panel inputs shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, loading technology architecture, end-user procurement authority, and application workflow type. CAGRs were derived from regression analysis of equipment refresh cycles correlated with regulatory phase-in schedules. Industry-specific inputs incorporated electric vehicle platform rollout timelines and emission certification protocol amendment trajectories.
The model assumes a particular technology adoption path; alternative pathways for permanent magnet motor architectures would alter the outlook if rare earth supply constraints accelerate hydraulic system retention. Forecasts reflect assumptions regarding EPA, Euro 7, and China GB implementation timelines. A model refresh is warranted upon material change in regulatory protocol harmonization or electric vehicle production target revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Electric Vehicle Test Equipment Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Vehicle Crash Testing System Market
Automotive Testing and Simulation
Autonomous Valet Parking System Scenario-Based Test Equipment Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market