
 Automotive TIC Market | 2026-2036
Automotive TIC Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive TIC Market Analysis
UN ECE R155 cybersecurity certification is bifurcating the competitive landscape between incumbents with vehicle-type approval authority and newer entrants lacking homologation credentials. Bureau Veritas leverages its marine and industrial heritage to extend testing protocols into electric powertrain validation. DEKRA SE anchors German market access through its longstanding relationship with KBA and deep bench of vehicle inspectors. SGS Group competes on geographic breadth, sustaining accreditation density across ASEAN manufacturing clusters where Japanese OEMs source components.
Automotive TIC encompasses the independent verification of vehicle systems, components, and production processes against safety, environmental, and performance benchmarks through physical testing, document review, and witness auditing. Laboratories execute electromagnetic compatibility testing to 100 V/m radiated immunity levels, crash structural validation per FMVSS 214 side-impact criteria, and chemical analysis of interior materials for VOC emissions. Testing services command the largest revenue share given the capital intensity of dynamometer cells and environmental chambers, while Certification margins expand fastest as OEMs outsource type-approval documentation for new energy vehicle platforms. Client concentration among Tier-1 Suppliers intensifies pricing pressure, though OEM direct contracts sustain premium positioning for cybersecurity and autonomous system validation.
EU Green Deal emission targets and the EU AI Act liability frameworks are reshaping demand, with EMA and national type-approval authorities expanding scope to cover algorithmic decision-making in advanced driver assistance. EPA tailpipe standards and NHTSA FMVSS updates in the United States force parallel certification tracks for models sold across Atlantic markets. Stakeholders must monitor regulatory divergence between Brussels and Washington on software-defined vehicle compliance, as dual-homologation costs threaten margin structures for mid-volume manufacturers.
Market Dynamics
Software-defined vehicle architectures are fragmenting testing protocols across cybersecurity, over-the-air validation, and functional safety domains that previously operated in isolation. TIC providers must now integrate ISO/SAE 21434 security audits with UN ECE R155 homologation workflows to retain OEM contracts.
Growth Catalysts
- EU Battery Regulation:Mandatory third-party conformity assessment for battery passports and carbon footprint declarations is expanding validation service contracts for European EV supply chains.
- Over-the-air software updates:OEMs require continuous cybersecurity monitoring and regression testing throughout vehicle lifecycles, creating recurring revenue streams for TIC laboratories.
- Thailand and Vietnam:Japanese and Korean OEMs are relocating component manufacturing to ASEAN clusters, driving demand for local electromagnetic compatibility and environmental testing facilities.
Market Restraints
- Capital intensity of dynamometer cells:High-voltage EV powertrain testing requires 800V-capable equipment that costs significantly more than legacy 400V infrastructure, raising barriers for mid-size laboratories.
- Homologation authority concentration:Only KBA, RDW, and a handful of national type-approval bodies hold UN ECE vehicle-type approval credentials, limiting competitive entry for newer TIC entrants.
- Silicon carbide semiconductor shortage:Testing equipment manufacturers face extended lead times for wide-bandgap components essential to next-generation inverter validation systems.
Strategic Opportunities
- India:BIS implementation of AIS-156 electric vehicle safety standards and PLI scheme incentives for local battery manufacturing is opening first-mover opportunities for accredited testing laboratories.
- Algorithmic validation:EU AI Act liability frameworks for automated decision-making in ADAS systems are creating demand for independent verification of neural network training datasets and edge-case performance.
- Blockchain-enabled certification:Immutable test-result documentation is supplanting paper-based type-approval records, enabling real-time verification by regulators and downstream buyers.
Industry Challenges
- Cybersecurity engineering talent:Shortages of engineers with ISO/SAE 21434 implementation experience are constraining laboratory capacity expansion for R155 certification services.
- Dual-homologation complexity:Divergent EPA and EU Green Deal compliance timelines force parallel testing tracks that compress program schedules and strain project management resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive TIC Market |
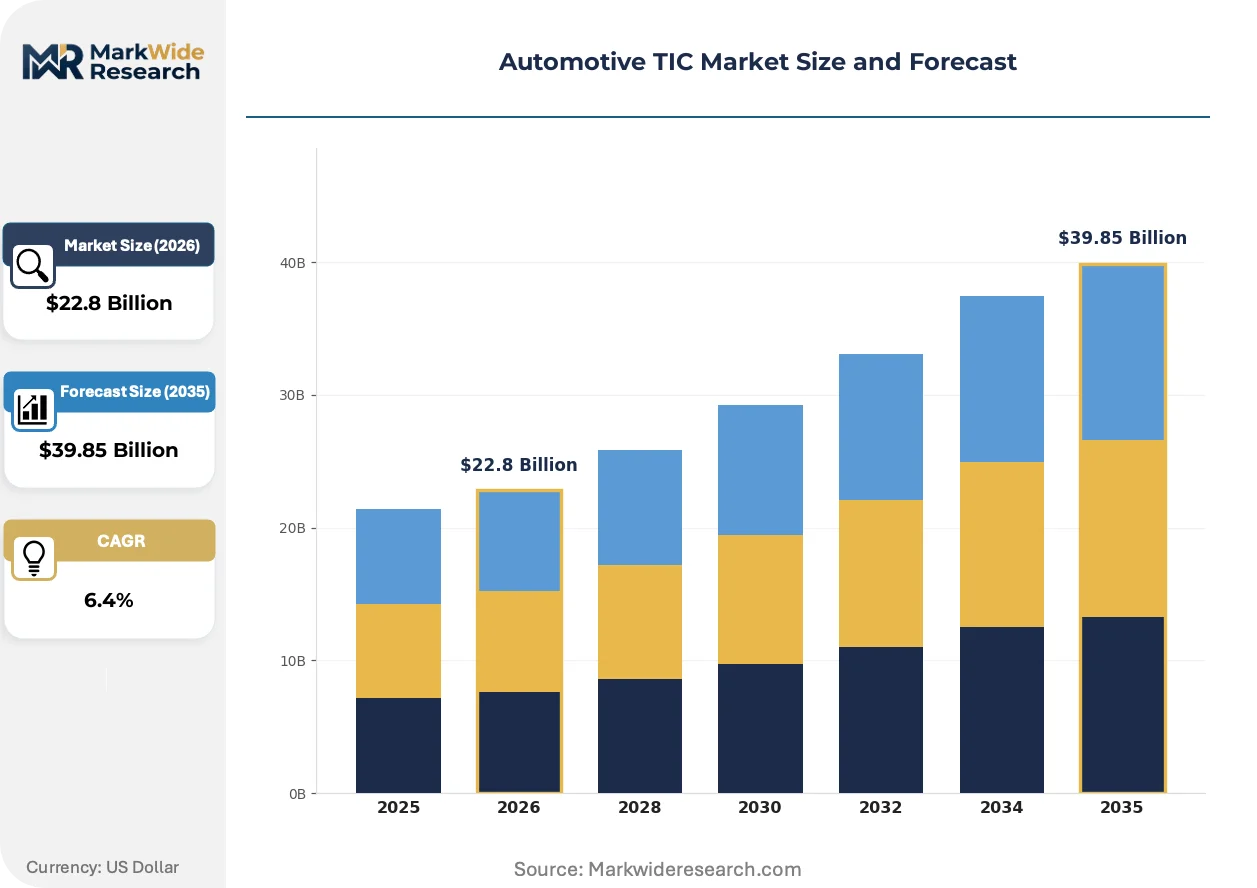
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Testing, Inspection, Certification, Compliance Client Type: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Technology: Non-Destructive Testing, Quality Control, Standards Compliance, Auditing End User: Manufacturers, Logistics Providers, Regulatory Bodies, Automotive Assemblers |
| Companies Covered | TÜV Rheinland Group, Bureau Veritas, SGS Group, Eurofins Scientific, Intertek, TÜV SÜD Group, Applus+, DNV, DEKRA SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive TIC Market Emerging Trajectories
Digital twin-based testing methodologies are compressing physical prototype requirements while expanding the scope of virtual validation prior to homologation submissions. Laboratories are investing in simulation-to-hardware correlation protocols that satisfy both OEM internal gates and regulatory type-approval authorities.
Hardware-in-the-loop simulation environments are supplanting track-based validation for advanced driver assistance system performance verification. Tier-1 suppliers at Magna and Bosch adopt SIL/HIL workflows for iterative sensor fusion tuning before committing to physical crash-test prototypes. This shift is compressing development cycles from 18-month hardware iterations to 6-week software releases while maintaining FMVSS 127 compliance documentation.
REACH chemical substance restrictions are forcing reformulation of interior adhesives, foams, and synthetic leathers used in automotive cabins. Suppliers must resubmit material safety data sheets and VOC emission profiles for each trim variant, expanding chemical analysis laboratory backlogs. German OEMs are responding by consolidating supplier qualification programs under single TIC providers with pan-European ECHA notification capabilities.
Subscription-based certification models are displacing transactional project pricing for long-term vehicle platform validation. Fleet operators and mobility providers in California negotiate multi-year cybersecurity monitoring contracts that bundle initial R155 certification with continuous threat assessment. This reconfiguration concentrates revenue predictability with incumbent laboratories possessing 24/7 security operations centers.
Automotive TIC Market Segmentation
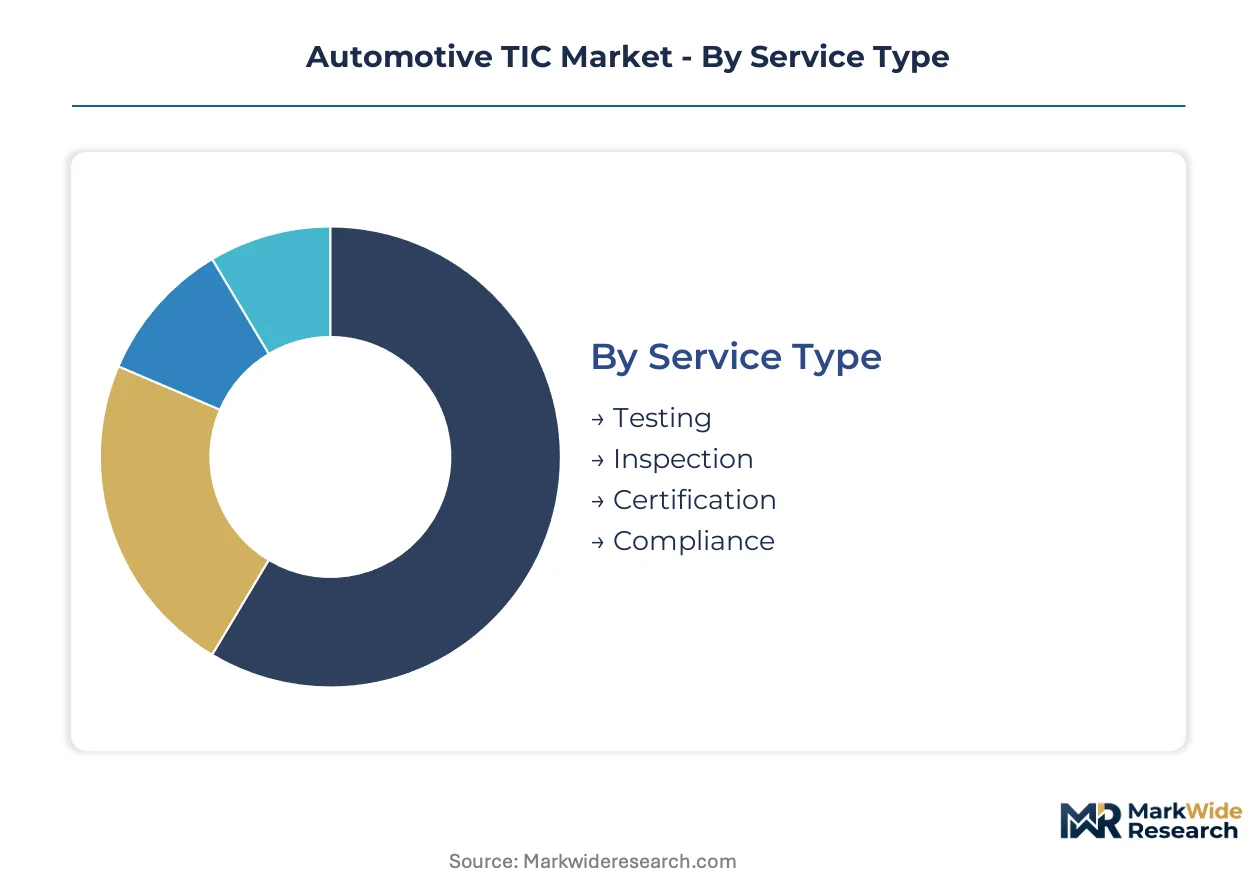
Service mix and client concentration patterns determine margin capture in Automotive TIC. Laboratories with diversified technology portfolios offset cyclicality in any single validation domain.
Service Type:
Testing commands the deepest margin pools given capital barriers in dynamometer infrastructure and environmental chamber deployment.
- Testing:Physical validation of vehicle systems through crash simulation, electromagnetic compatibility assessment, and powertrain endurance cycles. Demand concentrates in Germany where TÜV entities anchor certification workflows for automotive exports facing EU Battery Regulation requirements.
- Certification:Type-approval documentation and conformity assessment against UN ECE regulations, EPA standards, and FMVSS criteria. Laboratories with KBA or RDW delegated authority capture premium pricing for homologation services that newer entrants cannot replicate.
- Inspection:Witness auditing of production processes and supplier facility assessments. Tier-1 suppliers at Magna and Bosch drive volume through consolidated qualification programs.
- Compliance:Regulatory monitoring and ongoing conformity maintenance across evolving emission and safety standards. Fleet operators in California negotiate multi-year contracts bundling initial validation with continuous oversight.
Testing holds installed capacity. Certification is rotating up the share rankings.
Client Type:
OEM direct relationships sustain premium positioning, while supplier concentration intensifies pricing pressure.
- OEMs:Vehicle manufacturers outsourcing cybersecurity validation and autonomous system verification. German OEMs consolidate supplier qualification under single TIC providers with pan-European ECHA notification capabilities.
- Tier-1 Suppliers:Component manufacturers requiring electromagnetic compatibility and environmental testing for ASEAN manufacturing clusters. Japanese and Korean OEMs relocating production to Thailand and Vietnam drive facility expansion.
- Aftermarket Providers:Independent service networks seeking parts certification and repair procedure validation. California mobility providers bundle cybersecurity monitoring with fleet management contracts.
- Dealerships:Retail networks conducting pre-delivery inspections and warranty claim documentation. Regional density limits scale economics for specialized laboratory services.
OEM contracts anchor revenue stability. Tier-1 supplier volume is climbing the fastest.
Technology:
Non-destructive testing and simulation-based methods are displacing physical prototype requirements.
- Non-Destructive Testing:Material integrity assessment without component destruction through ultrasonic, radiographic, and eddy current methods. Battery cell manufacturers apply these techniques to detect internal defects in high-voltage EV powertrains.
- Quality Control:Statistical process monitoring and defect prevention in manufacturing lines. REACH chemical substance restrictions force reformulation of interior adhesives and foams, expanding material safety data sheet validation.
- Standards Compliance:Verification against ISO, IEC, and regional regulatory frameworks. EU AI Act liability frameworks for automated decision-making create demand for neural network training dataset verification.
- Auditing:Systematic evaluation of management systems and supply chain practices. Blockchain-enabled certification is supplanting paper-based type-approval records for real-time regulator verification.
Non-destructive testing holds installed capacity. Quality control is expanding most quickly.
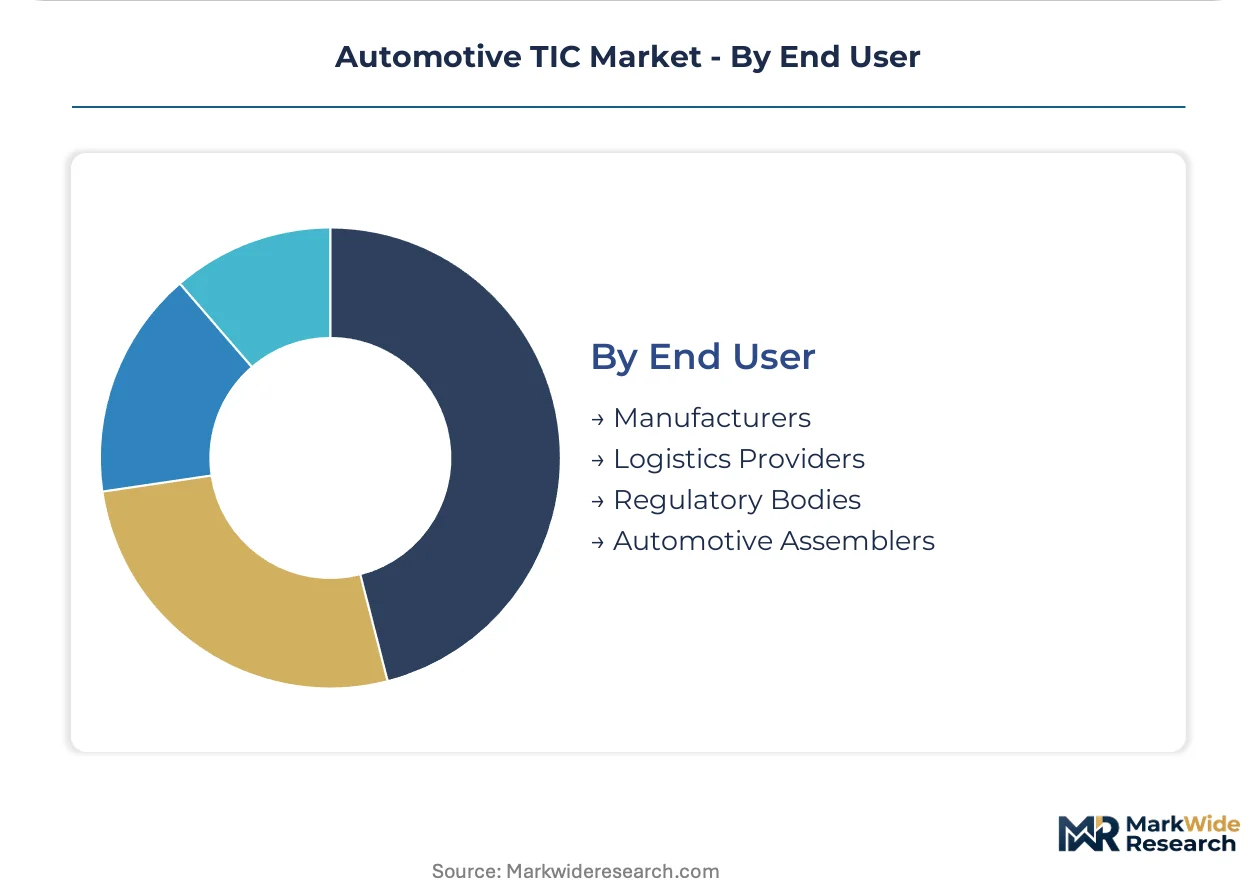
End User:
Manufacturer validation requirements dominate volume, while regulatory body relationships determine market access.
- Manufacturers:Vehicle and component producers requiring comprehensive validation across safety, environmental, and performance benchmarks. Software-defined vehicle architectures fragment testing protocols across cybersecurity, over-the-air validation, and functional safety domains.
- Regulatory Bodies:National type-approval authorities and delegated entities conducting conformity assessment. KBA, RDW, and limited UN ECE vehicle-type approval credentials concentrate competitive entry.
- Logistics Providers:Fleet operators seeking vehicle condition monitoring and damage assessment protocols. Subscription-based certification models displace transactional pricing for long-term platform validation.
- Automotive Assemblers:Final assembly facilities conducting end-of-line testing and quality gates. Hardware-in-the-loop simulation environments compress development cycles from hardware iterations to software releases.
Manufacturer relationships anchor volume concentration. Regulatory body contracts are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Battery Regulation conformity assessment mandates and NHTSA cybersecurity rulemakings are redirecting capital toward accredited laboratories in Germany and the United States. OEMs now require parallel validation tracks for Atlantic-crossing vehicle platforms.
Germany
KBA delegated authority concentrates homologation workflows around Stuttgart and Munich corridors. TÜV entities leverage their UN ECE vehicle-type approval credentials to capture premium pricing for EV battery passport validation under EU Battery Regulation carbon footprint declarations. The Wolfsburg-Ingolstadt manufacturing belt generates recurring certification demand for powertrain endurance testing.
United States
EPA tailpipe standard updates and NHTSA FMVSS 127 automatic emergency braking mandates force Detroit Three OEMs to expand third-party validation contracts. California Air Resources Board zero-emission vehicle credits create specialized testing demand in the Los Angeles-San Diego corridor for hydrogen fuel cell and battery-electric platforms. Michigan-based laboratories anchor crash structural validation for North American production.
China
MIIT new energy vehicle准入 regulations and GB standards for battery safety drive laboratory expansion in Shanghai and Shenzhen. Domestic OEMs BYD and NIO require electromagnetic compatibility testing for 800V architectures before export to European markets. The Yangtze River Delta cluster concentrates dynamometer capacity for high-voltage powertrain endurance cycles.
Japan
METI carbon neutrality roadmaps and JIS standards for solid-state batteries redirect Toyota and Honda validation spending toward domestic TIC providers. Nagoya-based laboratories specialize in hardware-in-the-loop simulation for advanced driver assistance systems. Kyushu manufacturing zones generate demand for supplier facility auditing under consolidated qualification programs.
India
BIS implementation of AIS-156 electric vehicle safety standards and PLI scheme battery manufacturing incentives open first-mover opportunities in Pune and Chennai. Tata Motors and Mahindra require electromagnetic compatibility testing for export-bound platforms. The Delhi-Mumbai industrial corridor attracts laboratory investment for component validation serving ASEAN supply chains.
Automotive TIC Market Vendor Landscape
Player mix skews toward European-origin technical service organizations with delegated homologation authority. Three archetypes dominate: TÜV-affiliated entities with KBA credentials, diversified inspection conglomerates with marine and industrial heritage, and geographic specialists with ASEAN accreditation density. Competitive moves concentrate on cybersecurity engineering talent acquisition and 800V-capable dynamometer deployment.
Within the TÜV-affiliated tier, TÜV Rheinland Group and TÜV SÜD Group exemplify the homologation-authority archetype through their Stuttgart and Munich heritage. Bureau Veritas occupies a diversified position spanning marine, industrial, and automotive validation. SGS Group anchors the geographic-breadth archetype with accreditation density across ASEAN manufacturing clusters. DEKRA SE represents the vehicle-inspector heritage model with deep KBA relationships. Eurofins Scientific and Intertek sit within the laboratory-network specialists tier. DNV exemplifies the maritime-to-mobility extension pattern. Applus+ occupies a position in the Spanish-origin technical services segment.
| Leading Market Players |
|---|
| TÜV Rheinland Group |
| Bureau Veritas |
| SGS Group |
| Eurofins Scientific |
| Intertek |
| TÜV SÜD Group |
| Applus+ |
| DNV |
| DEKRA SE |
| Others |
Supply Flow & Price Mechanics
UN ECE R155 cybersecurity certification gates both laboratory qualification and pricing power simultaneously, as only KBA-delegated entities capture premium homologation contracts while uncredentialed competitors face margin compression in transactional testing tiers.
Pricing Analysis
Certification level creates the primary spread across the Automotive TIC landscape. Three-tier pricing structure across premium, standard, and economy levels segments the market: KBA-authorized laboratories command premium rates for type-approval documentation, mid-tier operators compete on electromagnetic compatibility testing volume, and regional facilities price aggressively for inspection services. Pricing pressure stems from Tier-1 supplier consolidation of qualification programs, which compresses margins in environmental testing. OEM direct contracts show lowest price sensitivity due to cybersecurity liability exposure, while aftermarket providers negotiate hardest on per-project rates.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for testing equipment manufacturers awaiting silicon carbide semiconductor deliveries from Japanese and Korean foundries. Equipment supply concentrates in Germany, China, and Japan, with dynamometer cell production anchored in Stuttgart and Shanghai manufacturing clusters. Wide-bandgap component dependencies create single-source vulnerability for 800V-capable validation systems. Distribution runs through OEM-approved vendor lists and Tier-1 supplier consolidated qualification programs rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO/SAE 21434 cybersecurity engineering talent scarcity constrains laboratory capacity expansion across all tiers, creating asymmetric returns for stakeholders who secure credentialed personnel ahead of R155 certification demand inflections.
For Market Incumbents: Fortify homologation authority positions by deepening KBA and RDW delegated relationships while adding 800V-capable dynamometer capacity in the Yangtze River Delta. Cybersecurity engineering talent poaching from automotive OEMs represents the primary threat to margin structures. Vertical integration into hardware-in-the-loop simulation software reduces reliance on third-party platform licenses. For New Entrants and Emerging Players: Anchor in India's Pune-Chennai corridor where BIS AIS-156 implementation creates first-mover accreditation opportunities before domestic laboratory saturation. Algorithmic validation for EU AI Act ADAS compliance offers the most penetrable service line, as incumbent TIC providers lack neural network training dataset verification capabilities. Pursue joint-venture structures with established ASEAN electromagnetic compatibility facilities to bypass capital barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 800V powertrain validation infrastructure, favoring asset-light cybersecurity auditing platforms over heavy dynamometer investments. Acquisition target archetype: mid-size laboratories with KBA delegated authority but underutilized capacity in secondary German manufacturing corridors. Watch for silicon carbide equipment delivery lead times normalizing as the signal for laboratory expansion cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Homologation Authority Acquisition | KBA-delegated credentials unlock premium pricing for EU Battery Regulation carbon footprint declarations. |
| 800V Dynamometer Deployment | High-voltage EV powertrain testing capacity captures contracts from BYD and NIO export programs. |
| Cybersecurity Engineering Hiring | ISO/SAE 21434 credentialed talent enables R155 certification service expansion ahead of competitors. |
| Hardware-in-the-Loop Platform Investment | Virtual validation capabilities compress client development cycles from hardware iterations to software releases. |
| ASEAN Accreditation Expansion | Thailand and Vietnam facility certification captures Japanese and Korean OEM component manufacturing relocation. |
Methodological Framework
Desk research of UN ECE regulatory filings, EPA tailpipe standard dockets, and MIIT new energy vehicle准入 records preceded structured interviews with OEM platform engineers, Tier-1 supplier procurement leads, TIC laboratory technical directors, and KBA homologation officers. Primary intelligence combined with secondary validation from IHS Markit vehicle production databases, customs equipment import records, and national type-approval authority annual reports. Bottom-up service-line revenue estimates triangulated against top-down market sizing from accreditation body membership data.
Variance decomposition across service type, client tier, technology method, and regional production cluster shaped the analytical framework over the projection horizon. Modeled dimensions included testing versus certification revenue mix, OEM versus Tier-1 supplier contract concentration, and propulsion architecture validation requirements. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EU Battery Regulation implementation timelines and NHTSA FMVSS 127 automatic emergency braking mandate compliance schedules.
Material uncertainties — regulatory divergence between Brussels and Washington on software-defined vehicle compliance, silicon carbide semiconductor supply normalization timing, and cybersecurity engineering talent availability — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding delegated authority credential concentration and OEM outsourcing propensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Driving Simulators Market
Automotive Testing and Simulation
Torque Testers Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market
Automotive Testing and Simulation
Vehicle Crash Testing System Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market