
 Automotive Simulation Software Market | 2026-2036
Automotive Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Simulation Software Market Insights
Germany's automotive engineering base is fragmenting across specialized simulation platforms as OEMs reduce physical prototyping cycles. Ansys leverages multiphysics integration to anchor high-end crash and thermal analysis workflows for premium manufacturers. Siemens sustains dominance in vehicle dynamics through its Simcenter portfolio and deep ties to German OEM validation pipelines. Altair Engineering competes on solver speed and cloud elasticity, positioning its HyperWorks suite for mid-tier suppliers seeking scalable compute access.
Automotive simulation software encompasses computer-aided engineering tools that model vehicle behavior through finite element analysis, computational fluid dynamics, and multi-body dynamics solvers running against ISO and SAE performance parameters. These platforms replicate crash structures, aerodynamic loads, and powertrain thermal profiles to compress development timelines and reduce prototype expenditure. CAE Software captures the largest revenue pool given its centrality to structural and thermal validation across OEM programs. Cloud-Based deployment represents the fastest-expanding access mode as Tier-1 suppliers migrate from capital-intensive on-premise licenses to consumption-based GPU clusters. Vehicle Dynamics Software occupies a mature but defensible niche where real-time hardware-in-the-loop testing from dSPACE and The MathWorks sustains recurring demand.
FDA oversight of automotive-adjacent health monitoring systems, EPA fuel economy certification protocols, and NHTSA crashworthiness standards collectively raise the fidelity threshold for simulation outputs in the US market. EMA and ECHA frameworks in Europe add chemical and materials compliance layers that feed into battery and interior substance modeling requirements. Stakeholders must monitor how Euro 7 and evolving EPA greenhouse gas rules recalibrate the boundary conditions that simulation suites must validate before regulatory submission.
Market Dynamics
OEM engineering departments are compressing physical prototype cycles by expanding GPU-cluster investments for real-time multiphysics validation ahead of Euro 7 and EPA certification deadlines.
Growth Catalysts
- Euro 7 emission standards:Tightened NOx and particulate limits in Europe are forcing powertrain thermal simulation depth that physical testing cannot achieve within compressed development windows.
- Hardware-in-the-loop testing:dSPACE and The MathWorks platforms are anchoring recurring demand for real-time vehicle dynamics validation across German OEM validation pipelines.
- Cloud elasticity:Tier-1 suppliers are migrating from capital-intensive on-premise licenses to consumption-based GPU clusters for scalable crash and aerodynamic compute access.
Market Restraints
- Specialized solver licensing costs:Multiphysics integration fees from Ansys and Siemens Simcenter portfolios strain mid-tier supplier R&D budgets below fifty million euros annual revenue.
- Computational infrastructure concentration:GPU cluster supply chains concentrate in Taiwan semiconductor foundries and US cloud hyperscalers, creating input volatility for European simulation centers.
- Legacy toolchain lock-in:Deep Simcenter and HyperWorks integration across BMW and Mercedes-Benz validation pipelines creates switching friction for alternative platform adoption.
Strategic Opportunities
- Indian PLI scheme for automotive:Domestic engineering centers in Pune and Chennai are expanding CAE capacity for export component validation with limited incumbent software penetration.
- Battery thermal runaway modeling:ECHA chemical compliance layers and UN ECE R100 safety protocols are creating dedicated simulation modules for lithium-ion pack propagation analysis.
- Digital twin convergence:Real-time sensor fusion from vehicle telemetry with finite element models is enabling predictive maintenance overlays for fleet operators.
Industry Challenges
- Multiphysics solver expertise scarcity:Crash-thermal-electromagnetic coupling proficiency remains concentrated among senior CAE engineers with ten-plus years platform-specific experience.
- ISO 26262 functional safety certification:Tool qualification for autonomous driving simulation suites extends validation timelines by eight to fourteen months for ASIL-D rated components.
- Legacy HIL rig integration:dSPACE and National Instruments hardware from prior generation vehicle programs requires custom middleware development for cloud-native solver connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Simulation Software Market |
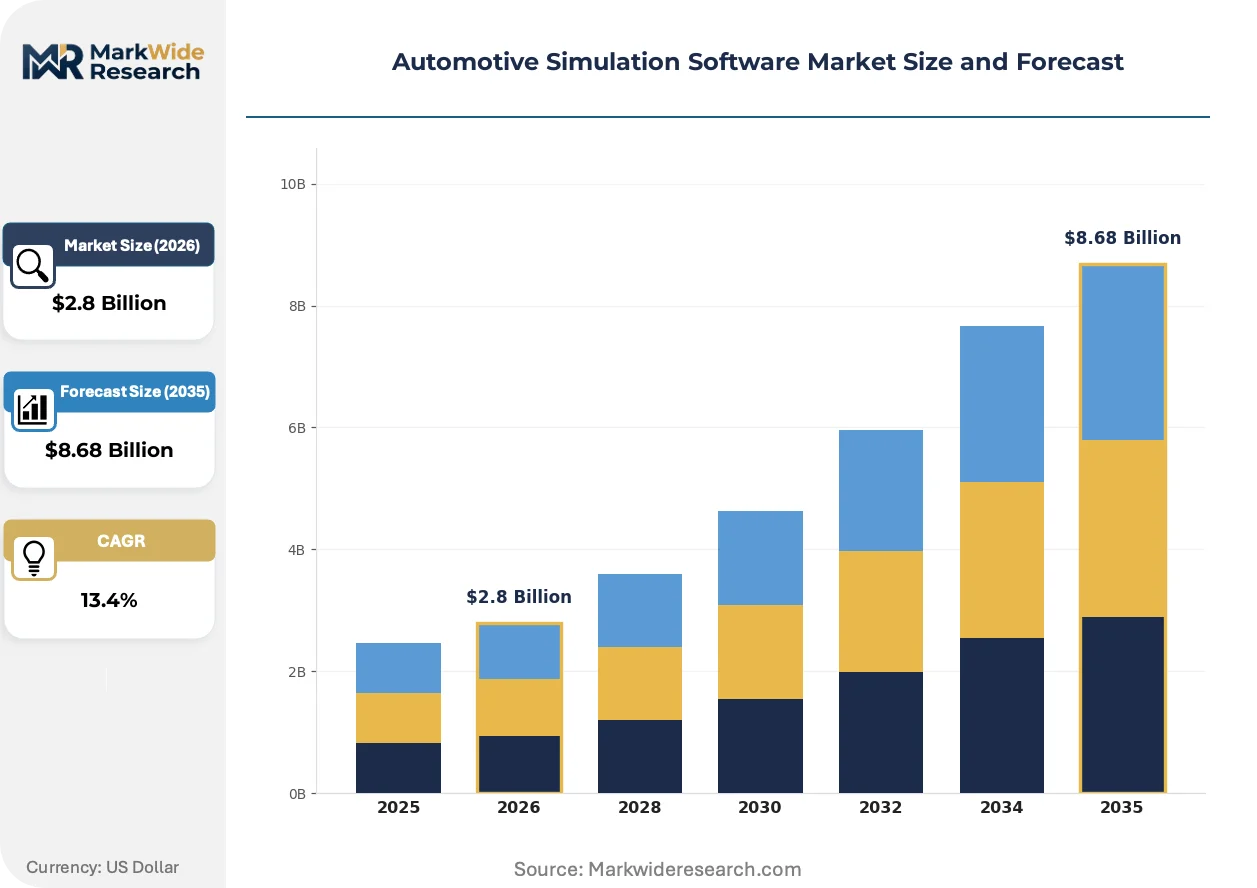
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.68 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAD Software,CAE Software,Vehicle Dynamics Software,Testing Software Application: Crash Simulation,Performance Analysis,Fuel Efficiency Optimization,Noise Vibration Harshness Testing End User: OEMs,Tier-1 Suppliers,Research Institutions,Aftermarket Providers Deployment: On-Premise,Cloud-Based,Hybrid,Desktop |
| Companies Covered | Ansys, Dassault Systèmes, Siemens, Autodesk, PTC, Altair Engineering, ESI Group, dSPACE, The MathWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Simulation Software Market Trends and Innovations
Simulation workloads are fragmenting across specialized physics engines while regulatory validation timelines compress development cycles. Three structural shifts are reshaping how engineering teams architect their CAE infrastructure and procurement relationships.
Reduced-order modeling is migrating from aerodynamic optimization into powertrain thermal management and cabin comfort prediction. Tier-1 HVAC suppliers are adopting neural network surrogates for refrigerant cycle simulation to compress CFD solve times from hours to minutes. This velocity gain is enabling overnight design iteration loops that previously required week-long physical wind tunnel sessions.
EPA greenhouse gas rules and NHTSA crashworthiness standards are recalibrating boundary condition libraries that simulation suites must validate before regulatory submission. US-based OEMs are expanding pedestrian impact and offset frontal collision model fidelity to meet updated NCAP protocols. The structural consequence is dedicated solver module development for soft-tissue biomechanics and battery enclosure intrusion resistance.
Subscription consumption models are displacing perpetual license structures across mid-market engineering consultancies. German automotive suppliers in Baden-Württemberg and Bavaria are negotiating enterprise token pools for seasonal peak demand during platform launch windows. This procurement evolution is concentrating vendor negotiation leverage among holding company procurement functions rather than individual engineering department budgets.
Automotive Simulation Software Market Segmentation
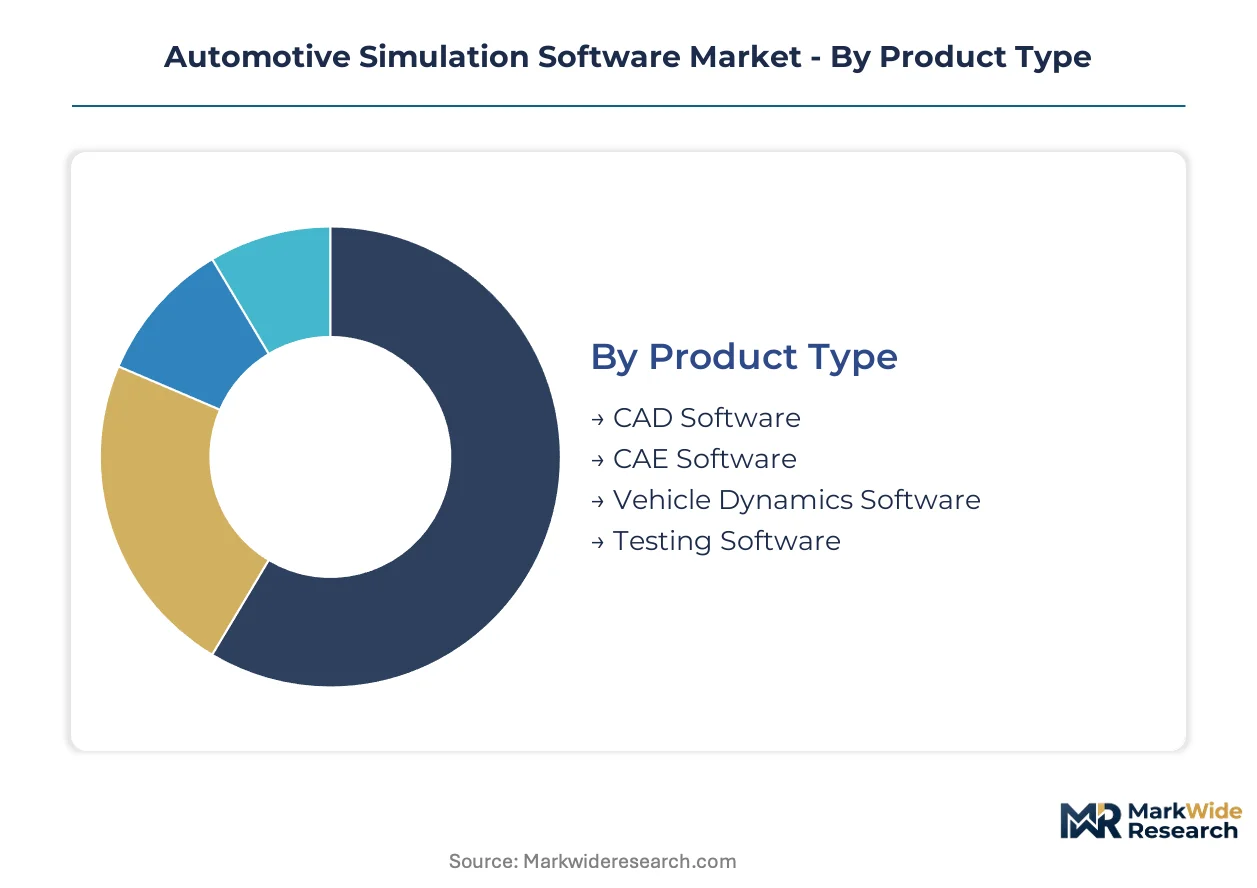
Automotive simulation software segments reflect divergent technical requirements across the vehicle development lifecycle. OEM procurement patterns favor integrated multiphysics platforms while Tier-1 suppliers prioritize modular, consumption-priced access to specific solver capabilities.
Product Type:
Mature structural validation tools anchor current spending, though emerging solver categories are capturing incremental budgets for electrification and autonomous system development.
- CAE Software:Finite element analysis and computational fluid dynamics solvers handle crash structure validation, thermal management, and aerodynamic optimization against Euro 7 and EPA certification protocols. German OEM engineering centers in Wolfsburg, Munich, and Stuttgart concentrate demand for high-fidelity multiphysics integration ahead of physical prototype reduction mandates.
- CAD Software:Geometric modeling platforms provide the foundational mesh generation and parametric design infrastructure that feeds downstream simulation workflows. Solid geometry preparation for crash and NVH analysis consumes the majority of preprocessing hours in BMW and Mercedes-Benz development pipelines.
- Vehicle Dynamics Software:Multi-body dynamics solvers model suspension kinematics, steering response, and chassis behavior against ISO and SAE performance parameters. Real-time hardware-in-the-loop testing from dSPACE sustains recurring demand across German validation centers.
- Testing Software:Test automation and data acquisition platforms manage physical prototype correlation and simulation-to-test validation loops. Post-processing visualization and reporting tools compress the feedback cycle between virtual prediction and empirical measurement.
CAE Software handles the majority of throughput; Cloud-Based deployment is climbing the fastest on share.
Application:
Application demand concentrates where regulatory pressure intersects with prototype elimination economics, creating tiered investment intensity across validation domains.
- Crash Simulation:Nonlinear explicit solvers model vehicle structure deformation, occupant kinematics, and pedestrian impact against NHTSA and Euro NCAP protocols. Offset frontal and side pole intrusion analysis commands the largest solver-hour allocations in premium OEM safety engineering departments.
- Performance Analysis:Vehicle dynamics and powertrain simulation validates acceleration, braking, and handling attributes against homologation requirements. Lap-time optimization and thermal derating prediction support motorsport and high-performance road car programs.
- Fuel Efficiency Optimization:Aerodynamic drag reduction and powertrain thermal management simulation addresses EPA greenhouse gas and Euro 7 CO2 targets. Reduced-order modeling is migrating from external aerodynamics into underhood thermal packaging workflows.
- Noise Vibration Harshness Testing:Vibro-acoustic simulation predicts cabin noise paths, powertrain mount isolation, and road-induced vibration comfort. Electrification is shifting NVH priorities from powertrain masking to wind and tire noise dominance.
Crash Simulation absorbs the dominant share of CAE licensing expenditure; Fuel Efficiency Optimization is expanding most quickly as electrification reshapes thermal validation requirements.
End User:
Customer segmentation reveals divergent procurement leverage, with consolidated OEMs negotiating enterprise platforms while fragmented suppliers seek elastic access models.
- OEMs:Integrated vehicle manufacturers operate centralized simulation centers with dedicated solver farms and specialized CAE engineering teams. Volkswagen, BMW, and Mercedes-Benz maintain captive multiphysics capabilities spanning crash, thermal, and aerodynamic validation.
- Tier-1 Suppliers:Component and system specialists including brake, suspension, and HVAC manufacturers license targeted solver modules for customer program support. Mid-tier revenue constraints below fifty million euros annually drive preference for token-based consumption over perpetual licenses.
- Research Institutions:University and national laboratory users advance solver methodology, material modeling, and biomechanics research through academic licensing programs. Public funding for battery safety and autonomous system validation is expanding simulation infrastructure at technical universities.
- Aftermarket Providers:Tuning and retrofit specialists apply simulation for performance upgrade validation and regulatory compliance demonstration. Limited penetration reflects cost barriers and narrow application scope relative to development-stage engineering.
OEMs command the largest absolute spending; Tier-1 Suppliers are gaining share fastest as outsourcing and platform sharing concentrate component-level simulation responsibility.
Deployment:
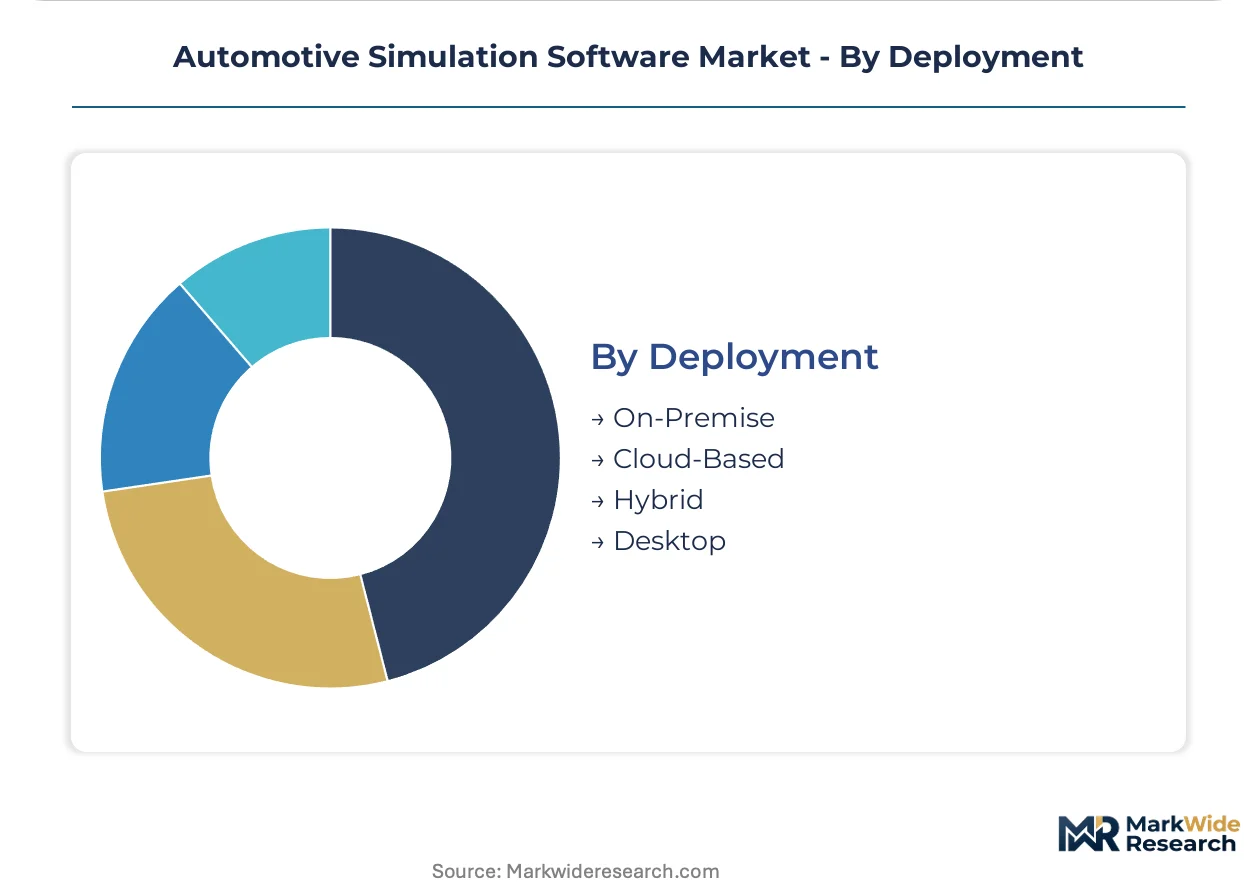
Deployment architecture is shifting from capital-intensive on-premise infrastructure toward consumption-based cloud access, though latency and data sovereignty constraints preserve hybrid configurations.
- Cloud-Based:GPU-cluster access via hyperscale providers enables elastic scaling for seasonal peak demand during platform launch windows. German automotive suppliers in Baden-Württemberg and Bavaria are negotiating enterprise token pools to replace fixed license commitments.
- On-Premise:Dedicated solver farms maintain data control and minimize latency for iterative design workflows in centralized OEM engineering centers. Security-sensitive crash and autonomous system development favors air-gapped infrastructure.
- Hybrid:Combined on-premise and cloud deployment partitions steady-state preprocessing from burst compute for large-scale optimization studies. Workflow orchestration middleware manages data synchronization between local workstations and remote clusters.
- Desktop:Single-workstation licensing persists for preliminary design exploration, small model preprocessing, and field engineering support. Limited core counts restrict application to reduced-order models and linear analysis domains.
On-Premise retains the installed base majority; Cloud-Based deployment shows the steepest expansion trajectory as procurement functions centralize negotiation leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GPU cluster supply chains concentrate in Taiwanese semiconductor foundries and US cloud hyperscalers, creating geographic asymmetry in simulation infrastructure access. European engineering centers maintain captive solver farms while Asian markets expand domestic CAE capacity for component export validation.
United States
EPA greenhouse gas rules and NHTSA crashworthiness standards recalibrate boundary condition libraries for regulatory submission. US-based OEMs expand pedestrian impact and offset frontal collision model fidelity to meet updated NCAP protocols. Detroit and Silicon Valley engineering clusters anchor autonomous system simulation development for ASIL-D rated components.
Germany
Volkswagen, BMW, and Mercedes-Benz operate centralized simulation centers with dedicated multiphysics capabilities. Euro 7 emission standards tighten NOx and particulate validation requirements that powertrain thermal simulation must address. Wolfsburg, Munich, and Stuttgart engineering hubs concentrate demand for high-fidelity crash and aerodynamic solvers ahead of physical prototype reduction mandates.
China
Domestic OEMs accelerate virtual prototyping adoption to compress development timelines for NEV platform launches. MIIT new energy vehicle certification protocols raise simulation fidelity thresholds for battery thermal management and electromagnetic compatibility. Yangtze River Delta engineering centers in Shanghai and Suzhou expand CAE hiring for export component validation.
Japan
Keiretsu-affiliated suppliers maintain legacy Simcenter and dSPACE integrations across Toyota and Honda validation pipelines. METI carbon neutrality roadmaps drive powertrain electrification simulation investment for hybrid and fuel cell architectures. Nagoya and Tokyo engineering clusters specialize in hardware-in-the-loop testing for chassis control system development.
India
PLI scheme incentives expand domestic automotive engineering capacity for global Tier-1 supplier programs. BIS automotive component standards create compliance simulation requirements for brake, suspension, and HVAC system exports. Pune and Chennai technical centers recruit CAE engineers for crash and NVH validation of export-bound components.
Automotive Simulation Software Market Competitive Landscape
Integrated multiphysics platforms and modular solver specialists split the market across divergent procurement strategies. OEM engineering departments favor enterprise-wide portfolios with deep validation pipeline integration, while mid-tier suppliers prioritize consumption-priced access to specific physics engines. Two strategic archetypes dominate: full-stack multiphysics vendors anchoring premium manufacturer workflows, and cloud-native specialists capturing Tier-1 elastic compute demand. Competitive positioning hinges on solver speed benchmarks, GPU cluster partnership terms, and legacy toolchain migration support.
Within the full-stack tier, Ansys and Siemens exemplify integrated platform strategies spanning crash, thermal, and electromagnetic domains. Altair Engineering occupies a position emphasizing solver elasticity and cloud deployment flexibility for mid-market engineering consultancies. dSPACE and The MathWorks anchor the hardware-in-the-loop specialization vector where real-time validation sustains recurring demand across German OEM centers. These three archetypes represent the competitive structure governing procurement negotiation leverage and R&D partnership formation.
| Leading Market Players |
|---|
| Ansys |
| Dassault Systèmes |
| Siemens |
| Autodesk |
| PTC |
| Altair Engineering |
| ESI Group |
| dSPACE |
| The MathWorks |
| Others |
Pricing and Supply Chain Analysis
GPU cluster undercapacity in European engineering centers is forcing German OEMs into multi-year cloud compute commitments that reshape both supplier negotiation leverage and licensing cost structures across the simulation software stack.
Pricing Analysis
Euro 7 emission standards dictate the pricing tier structure across automotive simulation suites, with multiphysics platforms commanding premium positioning against modular solver alternatives. Three-tier pricing structure across enterprise, professional, and developer levels separates perpetual license holders from token-based consumption models. Pricing pressure stems from Tier-1 supplier procurement consolidation as holding companies centralize enterprise-wide negotiations. Mid-tier engineering consultancies below fifty million euros annual revenue exhibit highest price sensitivity, while Volkswagen and BMW captive centers demonstrate lowest elasticity due to validation pipeline lock-in.
Supply Chain Analysis
Semiconductor foundry output from Taiwan, South Korea, and the United States feeds the GPU clusters anchoring simulation compute capacity. NVIDIA H100 and AMD MI300X accelerators draw from TSMC advanced packaging lines, while memory subsystems rest on SK Hynix and Micron supply. Single-source vulnerability concentrates in CoWoS packaging capacity, creating bottleneck risk for European simulation center expansion. Distribution runs through hyperscale cloud providers—AWS, Azure, and Google Cloud—delivering elastic GPU access to Tier-1 suppliers migrating from on-premise infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive simulation software sits at an inflection where Euro 7 and EPA greenhouse gas deadlines compress physical prototyping cycles, creating structural demand expansion for GPU-accelerated multiphysics validation.
For Market Incumbents: Build certification moats around ISO 26262 tool qualification for autonomous driving simulation suites. Deepen Simcenter and HyperWorks integration across BMW and Mercedes-Benz validation pipelines to heighten switching friction. Invest in solver speed benchmarks against Ansys multiphysics portfolios to defend high-end crash and thermal analysis market share.
For New Entrants and Emerging Players: Establish a beachhead in Indian PLI scheme automotive engineering centers where incumbent penetration remains limited. Target Pune and Chennai technical clusters seeking CAE capacity for export component validation. Lead with cloud-native solver elasticity and consumption-based GPU pricing to differentiate from legacy perpetual license structures.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-locked infrastructure play because emission and safety certification deadlines create non-discretionary demand regardless of automotive cycle volatility. Prioritize acquisition targets with battery thermal runaway modeling capabilities aligned to UN ECE R100 protocols. Monitor EPA rulemaking velocity as the key inflection signal for US market expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Multiphysics Platform Integration | Ansys and Siemens anchor premium OEM workflows through crash-thermal-electromagnetic coupling capabilities. |
| Cloud-Native Solver Deployment | Altair Engineering captures Tier-1 elastic compute demand via GPU cluster partnerships with AWS and Azure. |
| Hardware-in-the-Loop Expansion | dSPACE sustains recurring revenue through real-time validation integration across German OEM centers. |
| Battery Safety Module Development | ECHA compliance layers and UN ECE R100 protocols create dedicated lithium-ion propagation analysis demand. |
| Reduced-Order Modeling Investment | Neural network surrogates compress CFD solve times from hours to minutes for HVAC refrigerant cycle simulation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, hyperscaler capex disclosures, and automotive production databases. Primary interviews engaged OEM platform engineers, Tier-1 supplier procurement leads, and CAE technical directors at engineering consultancies. Secondary validation drew from EPA certification protocols, Euro 7 regulatory texts, SEC 10-K software segment disclosures, and IHS Markit vehicle registration data. Bottom-up segmentation modeling triangulated against top-down market sizing from GPU cluster deployment tracking.
Forecast inputs span deployment architecture shifts, regulatory deadline phasing, and OEM captive versus outsourced simulation capacity ratios. Segmentation dimensions include product type, application domain, end-user tier, and regional production cluster concentration. CAGRs derive from elasticity-adjusted adoption curves across the projection horizon. Battery thermal management solver demand and autonomous system validation complexity serve as automotive-specific forecast modifiers.
Sensitivities concentrate around Taiwan semiconductor foundry capacity allocation and Euro 7 implementation timeline adjustments. Forecasts reflect assumptions regarding cloud migration velocity and Tier-1 supplier consolidation patterns. Cross-checking against hyperscaler automotive vertical revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Vehicle Crash Testing System Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Vehicle Scanner Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Electric Vehicle Test Equipment Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Autonomous Valet Parking System Scenario-Based Test Equipment Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market