
 Electric Parking Brake Actuator Components Market | 2026-2036
Electric Parking Brake Actuator Components Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Parking Brake Actuator Components Market Insights
China's manufacturing corridor expansion is reshaping supply dynamics for electric parking brake actuator components. Robert Bosch leverages its Stuttgart engineering base to sustain electromechanical system leadership across European OEM programs. Continental anchors North American demand through integrated brake-by-wire development with Detroit automakers. ZF Friedrichshafen competes on gearbox miniaturization for premium vehicle platforms.
Electric parking brake actuator components encompass motor-driven caliper mechanisms, electronic control modules, and force-sensing feedback systems that replace conventional mechanical handbrake linkages; these assemblies typically operate at twelve-volt vehicle electrical architecture with clamping forces exceeding twenty kilonewtons to secure stationary vehicles on gradients. The primary commercial purpose centers on eliminating cabin-mounted levers, reducing vehicle weight, and enabling automated hold functions during stop-start traffic. Actuator motor segments dominate current value pools due to permanent-magnet DC motor complexity and thermal management requirements, while sensor unit integration is expanding fastest as automakers demand clamp-force verification for autonomous parking protocols. Control module categories concentrate margin capture through firmware differentiation and diagnostic capability expansion.
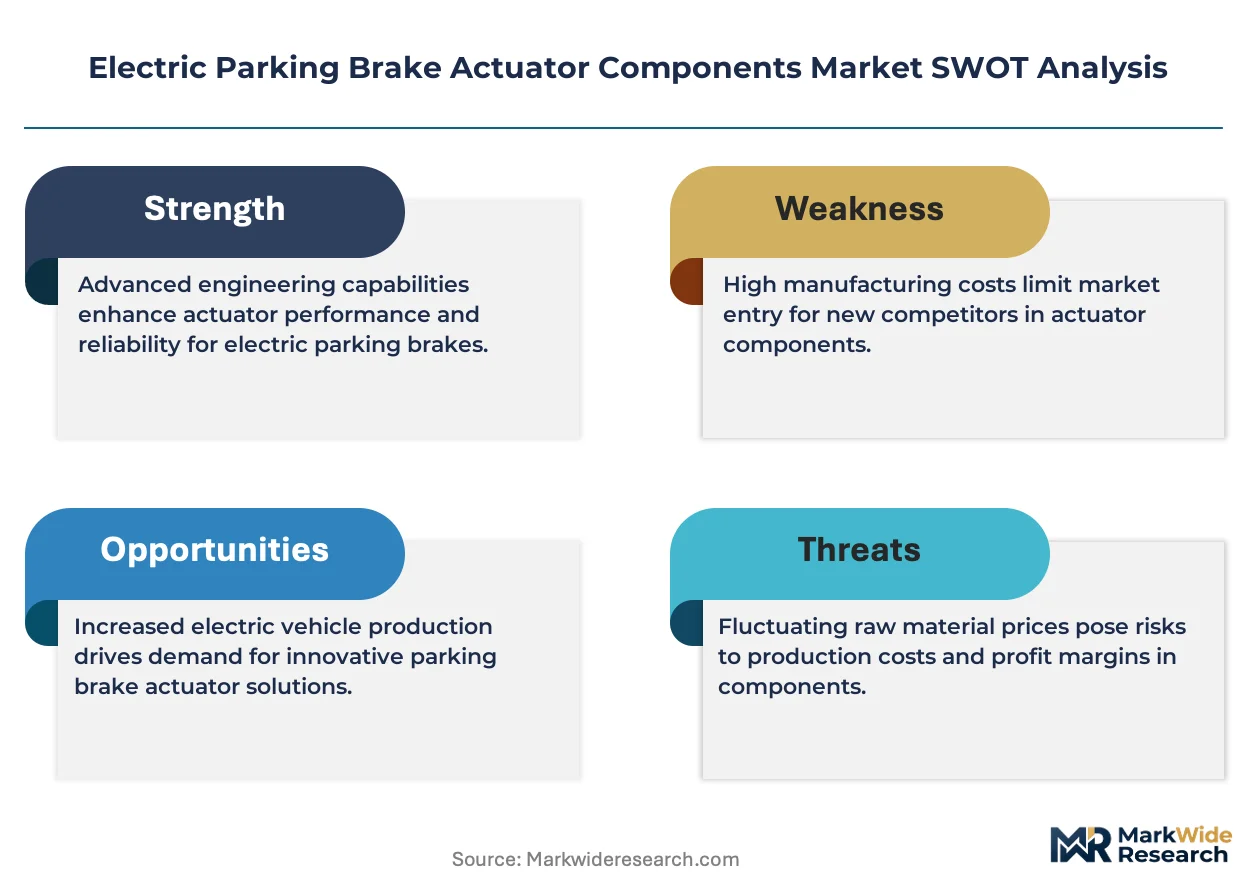
NHTSA brake performance standards, ECE R13-H homologation requirements, and China's GB/T vehicle safety mandates collectively mandate failsafe engagement protocols and redundancy architecture for electronic parking systems. These frameworks compel tier-1 suppliers to maintain dual-channel motor control and independent sensor validation, elevating engineering barriers for aftermarket entrants. Stakeholders must monitor software-defined vehicle architectures that could disaggregate parking brake functions into domain controllers, altering component procurement boundaries and supplier value capture.
Market Dynamics
Automakers' elimination of mechanical handbrake linkages in favor of electromechanical systems is restructuring procurement relationships between tier-1 brake suppliers and OEM platform engineering teams.
Growth Catalysts
- EU F-Gas Regulation:Vehicle weight reduction mandates accelerate cabin-lever deletion programs across European OEM portfolios.
- China MIIT fuel-consumption standards:Electrified brake architectures help domestic EV manufacturers meet tightening corporate average fuel economy thresholds.
- Autonomous parking protocols:Clamp-force verification requirements drive sensor integration into actuator modules for hands-free valet functions.
Market Restraints
- Dual-channel motor control:NHTSA brake performance standards mandate redundant electronics that elevate BOM costs versus mechanical alternatives.
- Permanent-magnet DC motor supply:Rare-earth material concentration in Chinese processing facilities creates input cost volatility for actuator manufacturers.
- Thermal management complexity:High clamping force generation generates heat dissipation challenges that limit motor downsizing potential.
Strategic Opportunities
- Software-defined vehicle architectures:Domain controller integration could disaggregate parking brake functions into centralized compute platforms.
- South Korean tier-1 supplier corridors:Volume procurement partnerships with Hyundai-Kia and emerging EV specialists offer scale economies.
- India BIS safety mandates:Upcoming vehicle electrification standards create first-mover advantage for actuator module localization.
Industry Challenges
- Firmware diagnostic capability:OEM demands for predictive maintenance algorithms strain tier-1 software engineering capacity.
- ECE R13-H homologation timelines:Validation protocols for failsafe engagement extend development cycles versus mechanical systems.
- Legacy platform compatibility:Twelve-volt electrical architecture constraints limit performance upgrades on older vehicle programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Parking Brake Actuator Components Market |
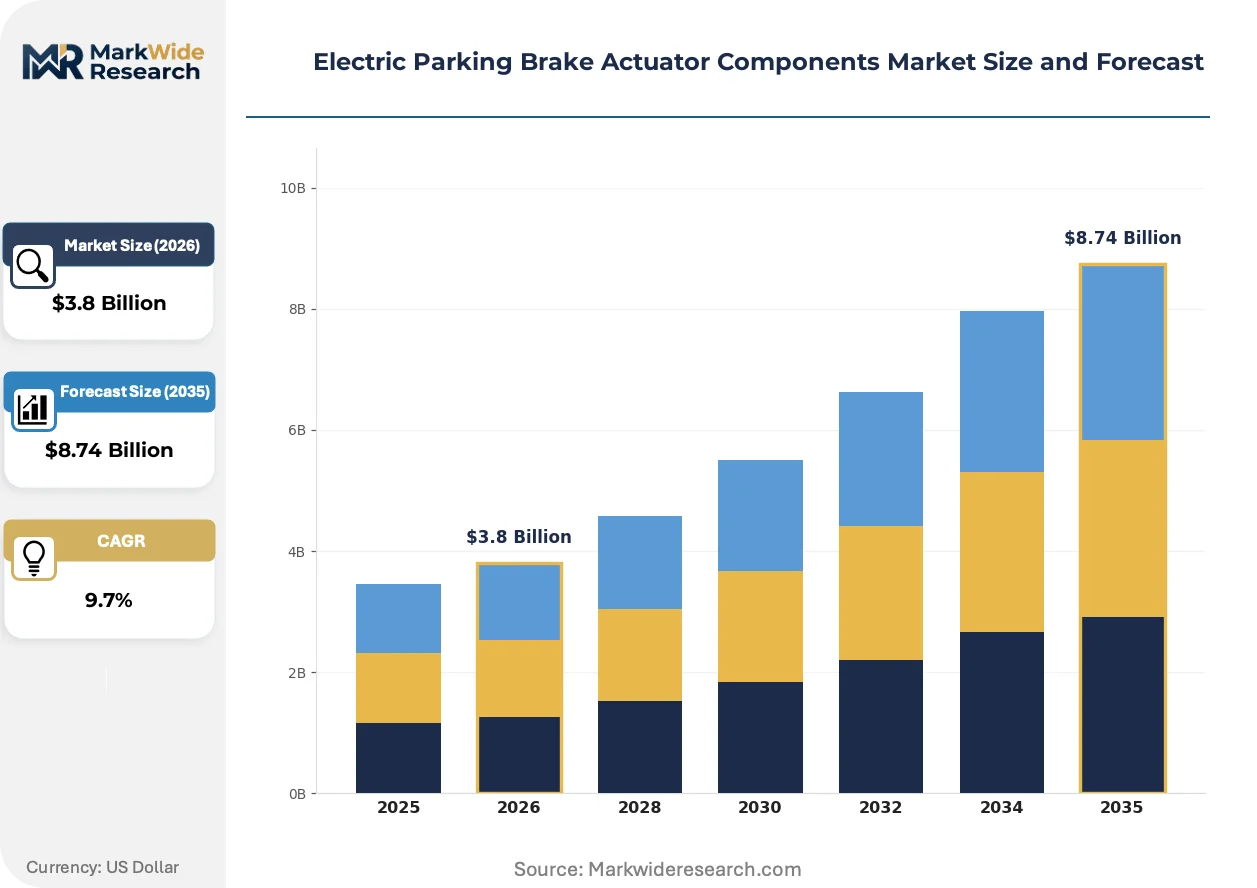
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Actuator Motor, Control Module, Gearbox, Sensor Unit, Cable Assembly Technology: Electromechanical, Electromagnetic, Hydraulic Assist, Pneumatic Assist, Electrohydraulic Vehicle Class: Passenger Cars, Light Commercial Vehicles, Heavy Duty Trucks, Electric Vehicles, Hybrid Vehicles Distribution Channel: OEM Supply, Aftermarket, Tier-1 Suppliers, Direct Sales, Authorized Dealers |
| Companies Covered | Robert Bosch, Continental, ZF Friedrichshafen, Aisin, ADVICS, Hyundai Mobis, DENSO, Mando, TBK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Parking Brake Actuator Components Market Trends and Innovations
Brake system electrification is compressing the traditional tier-1 supply hierarchy as OEMs seek direct relationships with motor and sensor specialists.
Brushless DC motor technology with integrated thermal sensors is rendering obsolete conventional brushed motor designs in premium vehicle caliper mechanisms. German and Japanese OEMs have adopted these modules across their flagship platforms since 2022. The shift is rendering obsolete standalone motor suppliers who lack control electronics integration capabilities.
China's GB/T vehicle safety mandates now require independent sensor validation for all electronic parking systems sold domestically. This compels foreign tier-1 suppliers to establish local firmware calibration centers. Domestic Chinese EV manufacturers are responding fastest by sourcing integrated modules from South Korean joint ventures.
Fleet operators now specify outcome-based brake performance contracts rather than component procurement for commercial vehicle programs. This unbundles hardware from maintenance liability and shifts risk to actuator suppliers. The pattern is most visible in North American last-mile delivery vehicle segments where uptime guarantees dominate purchasing criteria.
Electric Parking Brake Actuator Components Market Segmentation
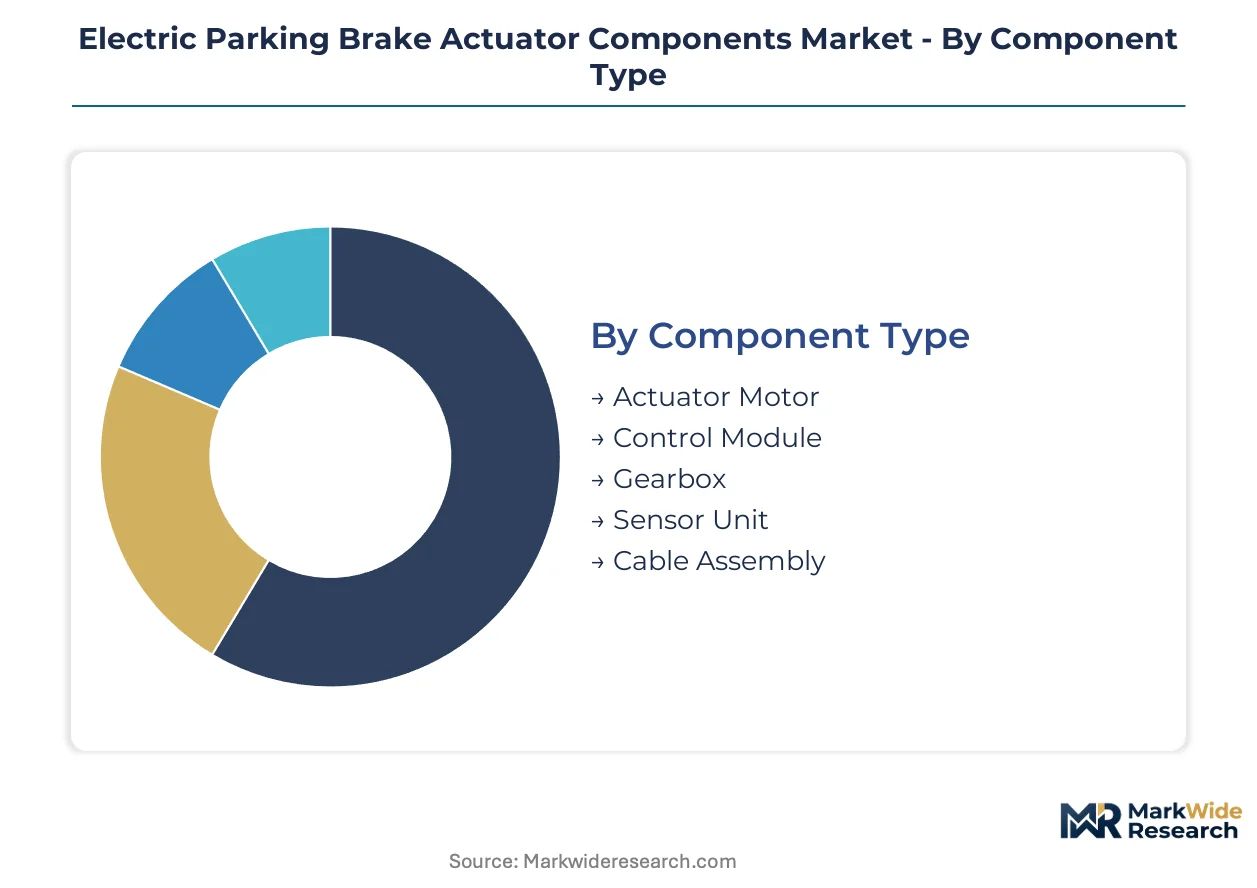
Component specialization across electric parking brake systems determines supplier value capture and procurement boundaries. Tier-1 suppliers structure their engineering organizations around specific actuator subsystems, creating distinct competitive arenas within the broader market.
Component Type:
Mature motor technologies coexist with emerging sensor integration requirements across this category.
- Actuator Motor:Permanent-magnet DC motors generate clamping forces exceeding twenty kilonewtons through gearbox multiplication. German premium OEMs specify these units for flagship sedan platforms where thermal management complexity elevates engineering barriers.
- Sensor Unit:Force-sensing feedback systems verify clamp-force achievement for autonomous parking protocols. South Korean tier-1 suppliers and Chinese EV manufacturers drive procurement volume as hands-free valet functions proliferate across East Asian vehicle programs.
- Control Module:Firmware-differentiated units with diagnostic capability expansion capture margin through embedded algorithm development.
- Gearbox:Miniaturized planetary gear trains enable caliper integration constraints on premium vehicle platforms.
- Cable Assembly:Shielded conductor bundles connect actuator mechanisms to vehicle electrical architecture with twelve-volt compatibility.
Actuator Motor retains volume leadership; Sensor Unit holds the steepest expansion curve.
Technology:
Cost tier stratification separates proven electromechanical systems from emerging hybrid actuation methods.
- Electromechanical:Motor-driven caliper mechanisms with electronic control modules dominate current installations. Stuttgart engineering bases sustain European OEM program leadership through permanent-magnet DC motor complexity.
- Electromagnetic:Direct electromagnetic actuation eliminates mechanical transmission elements. Japanese OEMs have adopted these modules across flagship platforms since brushless DC motor technology with integrated thermal sensors rendered conventional brushed designs obsolete.
- Electrohydraulic:Hybrid architectures combine hydraulic pressure generation with electronic valve control for heavy-duty applications.
- Hydraulic Assist:Supplementary hydraulic boosters augment electromechanical clamping force for commercial vehicle gradients.
- Pneumatic Assist:Compressed air augmentation serves specialized industrial vehicle segments with existing pneumatic infrastructure.
Electromechanical systems command the dominant revenue share; Electromagnetic configurations are climbing the fastest as OEMs delete mechanical handbrake linkages.
Vehicle Class:
Application intensity varies sharply between mass-market passenger programs and electrified commercial platforms.
- Passenger Cars:Cabin-lever deletion programs accelerate across European OEM portfolios as EU F-Gas Regulation mandates vehicle weight reduction. Premium German manufacturers anchor demand for integrated actuator modules with automated hold functions.
- Electric Vehicles:Native twelve-volt electrical architecture and regenerative braking integration create design synergies for electromechanical parking systems. Chinese EV manufacturers source integrated modules from South Korean joint ventures to satisfy domestic GB/T safety mandates.
- Hybrid Vehicles:Dual powertrain complexity demands failsafe engagement protocols with redundant electronics per NHTSA brake performance standards.
- Light Commercial Vehicles:Fleet operators in North American last-mile delivery segments now specify outcome-based brake performance contracts rather than component procurement.
- Heavy Duty Trucks:Gradient holding requirements exceed twenty kilonewtons and thermal management challenges limit motor downsizing potential.
Passenger Cars sustain the largest absolute demand; Electric Vehicles are gaining share fastest as China's MIIT fuel-consumption standards tighten.
Distribution Channel:
Supply concentration shapes procurement relationships between actuator specialists and vehicle manufacturers.
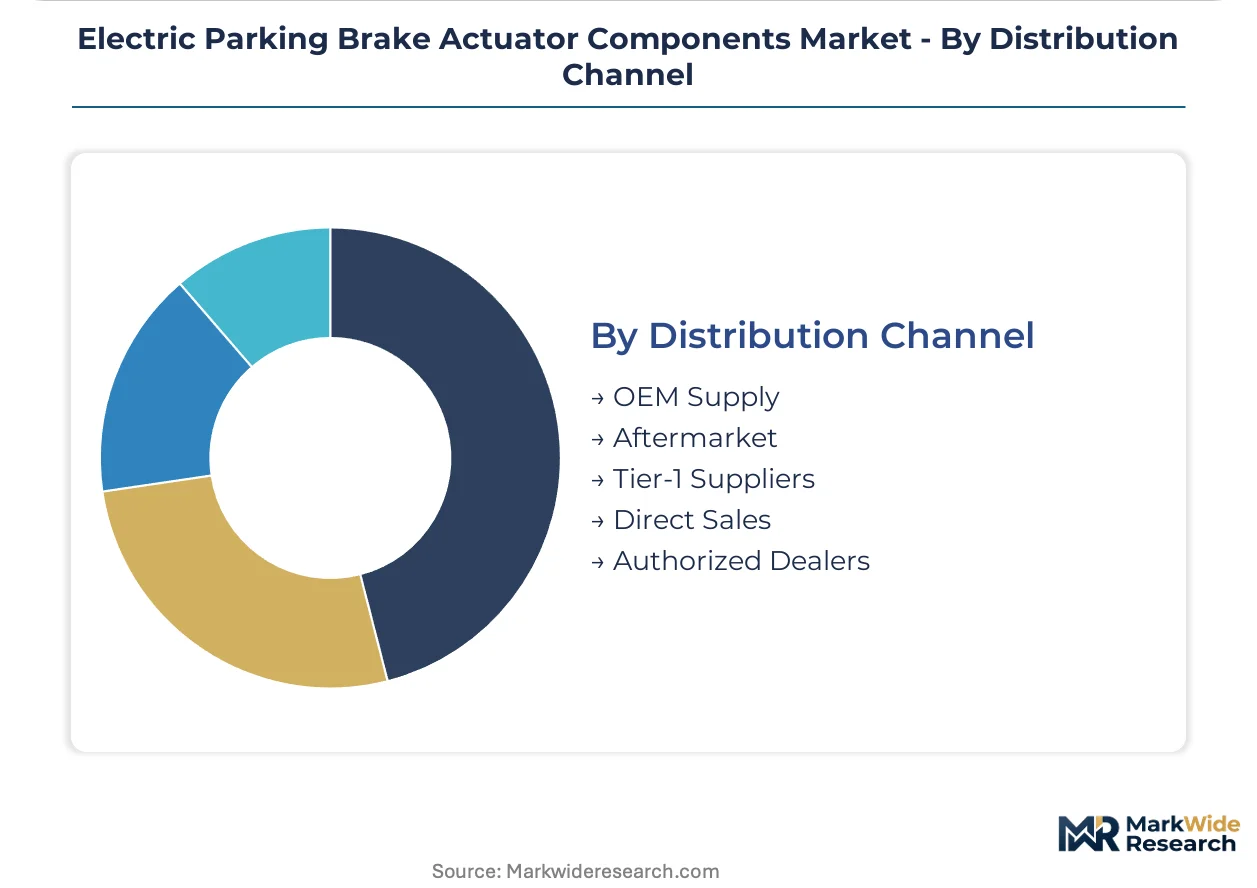
- OEM Supply:Direct platform engineering relationships with Detroit automakers and European premium manufacturers concentrate volume through integrated brake-by-wire development programs.
- Tier-1 Suppliers:South Korean corridors and Chinese manufacturing bases aggregate component sourcing for volume vehicle programs. Continental anchors North American demand through these relationships.
- Aftermarket:Dual-channel motor control and ECE R13-H homologation requirements elevate engineering barriers for non-original entrants.
- Direct Sales:Specialized industrial vehicle manufacturers procure actuator modules outside traditional tier-1 hierarchies.
- Authorized Dealers:Service network channels support replacement demand with OEM-validated firmware calibration.
OEM Supply channels dominate value capture; Tier-1 Supplier relationships are expanding most quickly as software-defined vehicle architectures disaggregate procurement boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart engineering bases and South Korean tier-1 corridors concentrate electromechanical brake actuator manufacturing. Chinese EV manufacturers source integrated modules through joint ventures. Japanese OEMs anchor electromagnetic system adoption across flagship platforms.
China
Domestic EV manufacturers drive volume procurement of integrated actuator modules. MIIT fuel-consumption mandates compel electrified brake architectures for corporate average fuel economy compliance. Yangtze River Delta manufacturing clusters host South Korean joint ventures serving GB/T safety mandate requirements.
Germany
Premium passenger car OEMs accelerate cabin-lever deletion programs across European portfolios. EU F-Gas Regulation mandates vehicle weight reduction that favors electromechanical systems over mechanical linkages. Stuttgart engineering bases sustain permanent-magnet DC motor development for flagship sedan platforms.
United States
Detroit automakers anchor North American demand through integrated brake-by-wire development programs. NHTSA brake performance standards mandate dual-channel motor control and failsafe engagement protocols. Midwest automotive corridors concentrate tier-1 supplier relationships for commercial vehicle applications.
Japan
Flagship OEM platforms adopted brushless DC motor technology with integrated thermal sensors since 2022. METI industrial policy supports brake system electrification for vehicle weight reduction targets. Nagoya and Tokyo metropolitan clusters concentrate electromagnetic actuation module development.
South Korea
Hyundai-Kia and emerging EV specialists drive volume procurement partnerships for actuator modules. MFDS automotive safety standards align with international homologation requirements for electronic parking systems. Busan-Ulsan industrial corridors aggregate component sourcing for export-oriented vehicle programs.
Electric Parking Brake Actuator Components Market Competitive Landscape
Stuttgart-based engineering conglomerates and South Korean tier-1 suppliers split the market between premium European OEM programs and East Asian volume manufacturing. The structure concentrates around integrated system providers with in-house motor and control module capabilities. Two archetypes dominate: diversified automotive suppliers with brake system heritage, and specialized electromechanical component manufacturers. Competitive moves center on gearbox miniaturization for premium platforms and firmware differentiation for diagnostic capability expansion.
Within the diversified supplier tier, Robert Bosch and Continental occupy positions exemplifying European engineering-base concentration, while ZF Friedrichshafen represents German gearbox miniaturization specialization. These three entities anchor the competitive structure through their respective Stuttgart and Hanover operational footprints. Hyundai Mobis exemplifies the South Korean tier-1 corridor archetype, serving volume procurement relationships with domestic OEMs and Chinese joint ventures. Aisin and DENSO represent Japanese keiretsu-affiliated suppliers with electromagnetic system capabilities. Mando and TBK occupy positions within the specialized electromechanical component manufacturer segment, particularly for East Asian market penetration.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental |
| ZF Friedrichshafen |
| Aisin |
| ADVICS |
| Hyundai Mobis |
| DENSO |
| Mando |
| TBK |
| Others |
Pricing and Supply Chain Analysis
Rare-earth material concentration in Chinese processing facilities determines both pricing tier spreads and supply chain shape for electric parking brake actuator components. Permanent-magnet DC motor complexity elevates BOM costs for tier-1 suppliers while thermal management requirements compress margin pools across all manufacturing tiers.
Pricing Analysis
ECE R13-H homologation requirements dictate the pricing tier structure across the electric parking brake actuator market. Three-tier pricing separates premium German OEM programs from volume East Asian vehicle lines and economy aftermarket alternatives. Price differentiation rests on certification grade and firmware diagnostic capability rather than hardware cost alone. Cost compression in the economy tier is intensifying because South Korean joint ventures are scaling integrated module production for Chinese EV manufacturers. Fleet operators in North American last-mile delivery segments demonstrate the least price sensitivity due to outcome-based brake performance contracts, while aftermarket distributors face the highest margin pressure from dual-channel motor control mandates.
Supply Chain Analysis
Extended payment terms from South Korean tier-1 suppliers are reshaping working capital requirements for component specialists across the electric parking brake actuator supply chain. Manufacturing gravity centers on China, Germany, and South Korea, with Yangtze River Delta clusters hosting joint ventures for GB/T compliance and Stuttgart engineering bases sustaining permanent-magnet DC motor development. The supply chain draws from rare-earth processing facilities, permanent-magnet DC motor assemblies, and force-sensing feedback systems. Single-source vulnerability in Chinese rare-earth material concentration creates structural exposure for actuator manufacturers dependent on neodymium and dysprosium inputs. Distribution runs through OEM platform engineering relationships and tier-1 supplier corridors rather than open aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric parking brake actuator components represent a high-growth disruption as software-defined vehicle architectures threaten to disaggregate parking brake functions into domain controllers. The EU F-Gas Regulation and China's MIIT fuel-consumption standards are accelerating the elimination of mechanical handbrake linkages across premium and volume vehicle programs alike.
For Market Incumbents: Entrench firmware differentiation capabilities as the primary defensive moat against domain controller disaggregation. Robert Bosch and Continental should deepen in-house production of control module algorithms to capture diagnostic capability expansion value pools. Capacity addition in South Korean manufacturing corridors will anchor volume procurement relationships with Hyundai-Kia and Chinese EV joint ventures. Certification investment in India's upcoming BIS safety mandates creates first-mover positioning before localization requirements harden. For New Entrants and Emerging Players: Establish a beachhead in sensor unit integration for autonomous parking protocols, the steepest expansion curve within component categories. The most penetrable segment lies in force-sensing feedback systems for hands-free valet functions, where South Korean tier-1 suppliers and Chinese EV manufacturers are driving procurement volume. A direct go-to-market angle through firmware calibration centers in China satisfies GB/T safety mandate requirements while bypassing established tier-1 hierarchies. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors specialized electromechanical component manufacturers with brushless DC motor capabilities. Long-term viability over the next decade hinges on software-defined vehicle architecture adaptation rather than hardware scale alone. Acquisition targets should demonstrate integrated thermal sensor development and control module firmware differentiation. The signal to watch is OEM platform engineering team restructuring around domain controller integration, which would compress traditional tier-1 supplier value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Domain controller integration threatens to disaggregate parking brake functions from standalone actuator modules. |
| Geographic Manufacturing Footprint | Yangtze River Delta clusters enable GB/T compliance for Chinese EV manufacturer procurement. |
| Platform Standardization | Twelve-volt electrical architecture constraints limit performance upgrades on legacy vehicle programs. |
| Long-term Supply Agreement | Rare-earth material concentration in Chinese processing facilities creates input cost volatility for tier-1 suppliers. |
| Joint Venture | South Korean tier-1 corridors aggregate component sourcing for Hyundai-Kia and Chinese EV specialist volume programs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted to construct the analytical foundation for this study. Primary interviews engaged OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and dealership service operations. Secondary validation drew from vehicle production databases, IHS Markit registration data, NHTSA brake performance filings, and ECE homologation records. Bottom-up component segmentation was triangulated against top-down OEM program forecasts to ensure methodological consistency.
Calibration across the projection horizon employed a structured analytical framework modeling vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived through regression analysis of historical adoption curves and forward scenario weighting. Industry-specific forecast inputs included MIIT fuel-consumption mandate compliance trajectories and EU F-Gas Regulation implementation timelines.
Stress conditions across rare-earth material price volatility, domain controller adoption rates, and regulatory homologation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM platform engineering team structures and tier-1 supplier relationship durability. Macroeconomic contraction, accelerated software-defined vehicle migration, or unilateral regulatory revision would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Industrial V Belt Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Automotive Crankcase Additives Market
Automotive Parts
Wiper Blade Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Brake Friction Materials Market
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
Japan Ceramic Ball Bearings Market
Automotive Parts
India Brake Pads Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market