
 On Board Diagnostics Device Market | 2026-2036
On Board Diagnostics Device Market Size, Share, and Industry Trends Forecast 2026-2036
On Board Diagnostics Device Market Analytics
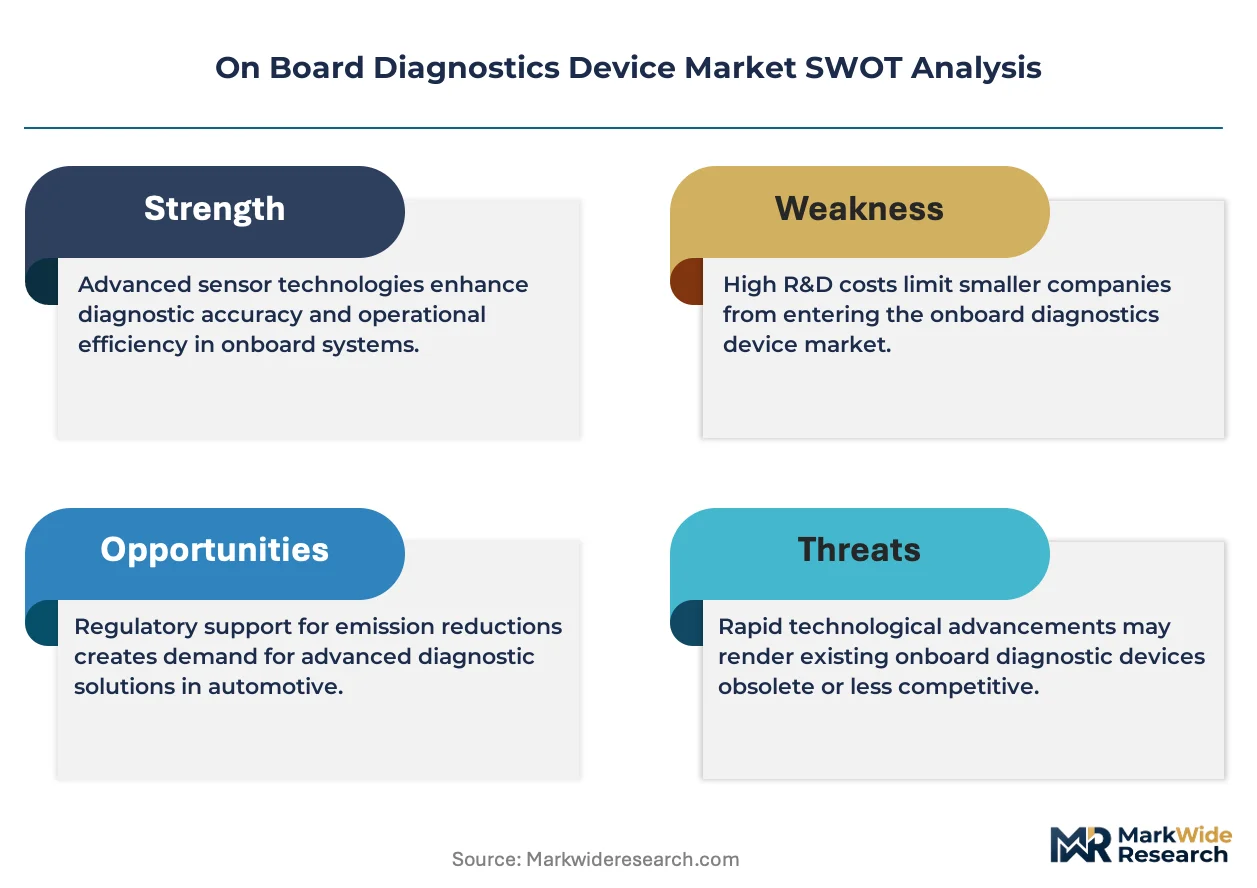
Asset-light leasing models for diagnostic hardware is fragmenting competitive barriers across the aftermarket. Robert Bosch GmbH leverages its embedded systems heritage to dominate integrated OBD-II scanner production for European OEM channels. Innova Electronics Corp. specializes in consumer-grade Bluetooth-enabled tools that occupy the DIY enthusiast segment through retail distribution. CalAmp Corporation sustains recurring revenue by anchoring its fleet telematics platform with captive diagnostic subscriptions.
On Board Diagnostics Devices are electronic systems that monitor vehicle powertrain, emissions, and chassis performance through standardized SAE J1962 and ISO 15031 protocols, triggering malfunction indicator lamps when sensor readings exceed calibrated thresholds. Their primary commercial purpose is enabling regulatory emissions verification, predictive maintenance scheduling, and warranty claim validation across automotive service workflows. Wired connectivity retains margin concentration in heavy-duty vehicle applications where electromagnetic interference resistance outweighs convenience premiums, while wireless Bluetooth configurations capture the fastest expansion in passenger vehicle aftermarket channels. The emissions tester category remains structurally mature in developed markets with established inspection regimes, whereas on-board monitors embedded at factory build represent the emerging margin pool as OEMs bundle predictive analytics into new vehicle sales.
The EPA enforces OBD-II compliance through Title 40 CFR Part 86, compelling manufacturers to maintain standardized diagnostic trouble code architectures across all US-market vehicles. California's Air Resources Board extends these mandates through supplemental LEV III requirements that shape hardware calibration for devices sold into the country's largest state vehicle market. EMA's MDR framework and the EU's F-Gas Regulation indirectly condition diagnostic device specifications by linking refrigerant leak detection to broader emissions monitoring protocols. Stakeholders must weigh whether to prioritize backward integration into sensor manufacturing or deepen software differentiation as regulatory data logging requirements expand beyond powertrain into battery electric vehicle thermal management systems.
Market Dynamics
California's CARB standards and EPA enforcement under Title 40 CFR Part 86 are compressing hardware refresh cycles as manufacturers scramble to certify devices against tightening emissions verification protocols before 2027 model-year mandates take effect.
Growth Catalysts
- Fleet telematics mandates:Commercial operators in Germany face TÜV inspection requirements that accelerate replacement of non-connected diagnostic hardware with cellular-enabled units capable of real-time emissions logging.
- Title 40 CFR Part 86:EPA enforcement of standardized diagnostic trouble code architectures compels aftermarket device manufacturers to maintain protocol compatibility across all US-market vehicles, expanding addressable hardware demand.
- Bluetooth Low Energy integration:Consumer-grade diagnostic tools are capturing DIY enthusiast segments through smartphone-native interfaces that eliminate dedicated display costs.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries control critical microcontroller supply for OBD-II protocol processors, exposing device manufacturers to allocation volatility.
- SAE J1962 connector standardization:Physical interface lock-in prevents form-factor innovation and limits premium differentiation to software layers alone.
- Right-to-repair legislative friction:Pending state-level repair access laws in Massachusetts and other jurisdictions create compliance uncertainty for OEM-integrated diagnostic systems.
Strategic Opportunities
- Battery electric vehicle thermal management:EU F-Gas Regulation linkages between refrigerant leak detection and emissions monitoring are opening diagnostic device applications beyond traditional powertrain systems.
- India BIS certification pathways:Domestic commercial vehicle production growth under PLI scheme incentives creates first-mover positioning for localized diagnostic hardware assembly.
- Subscription telemetry bundling:Fleet operators are accepting captive diagnostic subscriptions as part of bundled telematics platforms, shifting revenue from hardware margins to recurring software fees.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of engineers proficient in ISO 15031 protocol stacks is extending product development timelines and inflating compensation costs.
- Cross-platform certification complexity:Separate EPA, CARB, and EU type-approval processes for emissions verification functionality multiply testing expenditure before market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On Board Diagnostics Device Market |
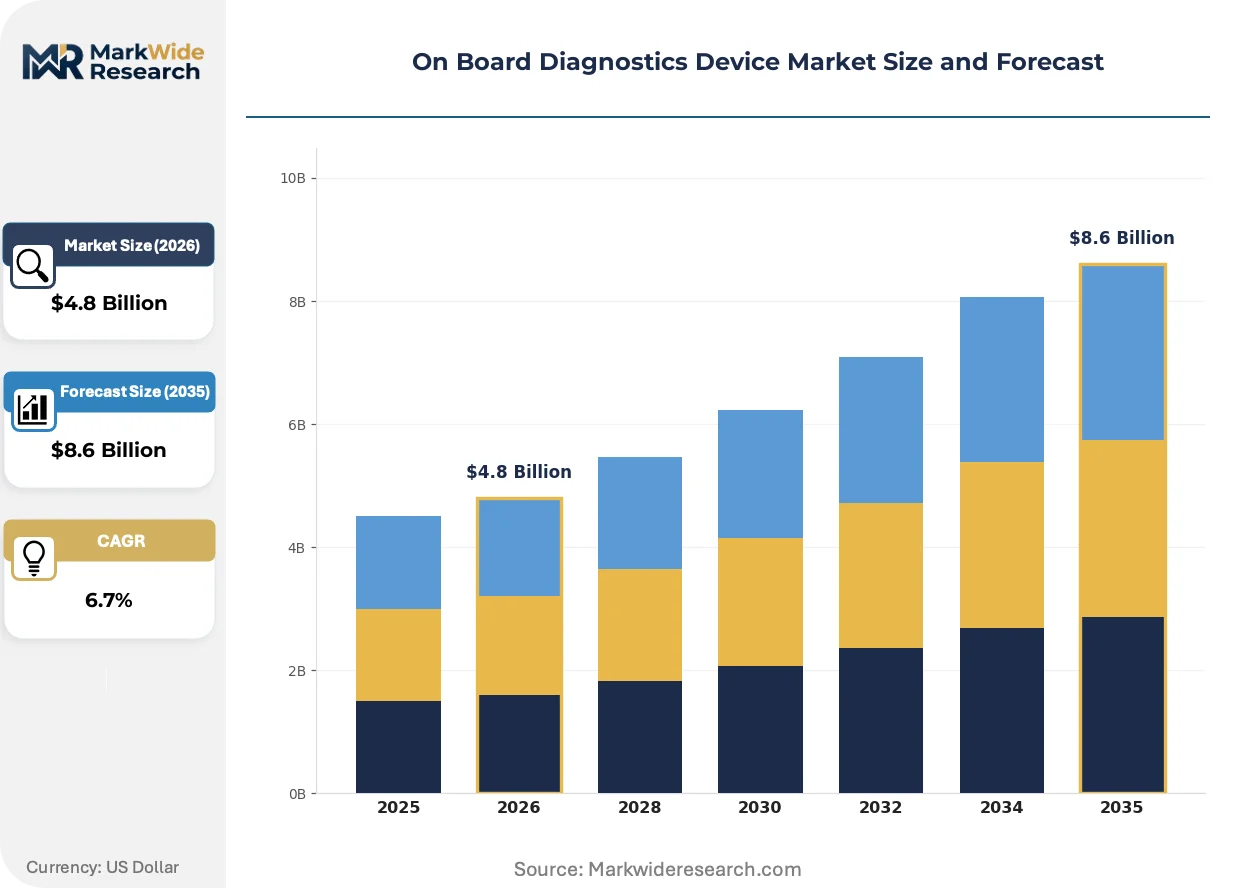
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: OBD-II Scanner, On-Board Monitor, Emissions Tester, Diagnostic Tool Connectivity: Wired, Wireless, Bluetooth, Wi-Fi Vehicle Category: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles End User: Automotive Service Centers, Fleet Operators, OEMs, DIY Enthusiasts |
| Companies Covered | Autel Intelligent Technology Corp., Ltd., Robert Bosch GmbH, Innova Electronics Corp., Denso Corporation, Vector Informatik, AVL DiTEST GmbH, Continental AG, Geotab Inc., CalAmp Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On Board Diagnostics Device Market Evolving Landscape
Cloud-native diagnostic architectures are compressing the value capture window for standalone hardware vendors while elevating software and data analytics as the primary margin pools in vehicle service workflows.
Edge computing modules with onboard neural inference engines are enabling real-time pattern recognition in powertrain sensor arrays without cloud dependency. Heavy-duty fleet operators in North American long-haul corridors are piloting these units for predictive fault isolation during route operation. Standalone code reader devices without local processing capability are rendering obsolete in commercial applications where downtime costs exceed hardware premiums.
California's Air Resources Board supplemental LEV III requirements are forcing device manufacturers to recalibrate sensor thresholds for nitrogen oxide detection ahead of 2027 enforcement. Hardware vendors must maintain dual firmware tracks to serve California and federal markets from common production lines. Aftermarket suppliers serving the US West Coast face compressed certification windows compared to national distribution strategies.
Leasing models for diagnostic hardware are displacing outright purchase in European commercial fleet procurement. Asset-light operators in Germany and the Netherlands prefer operational expenditure treatment for connected diagnostic subscriptions bundled with maintenance management software. This preference shift concentrates purchasing authority with fleet management platform providers rather than independent service garages.
On Board Diagnostics Device Market Segmentation
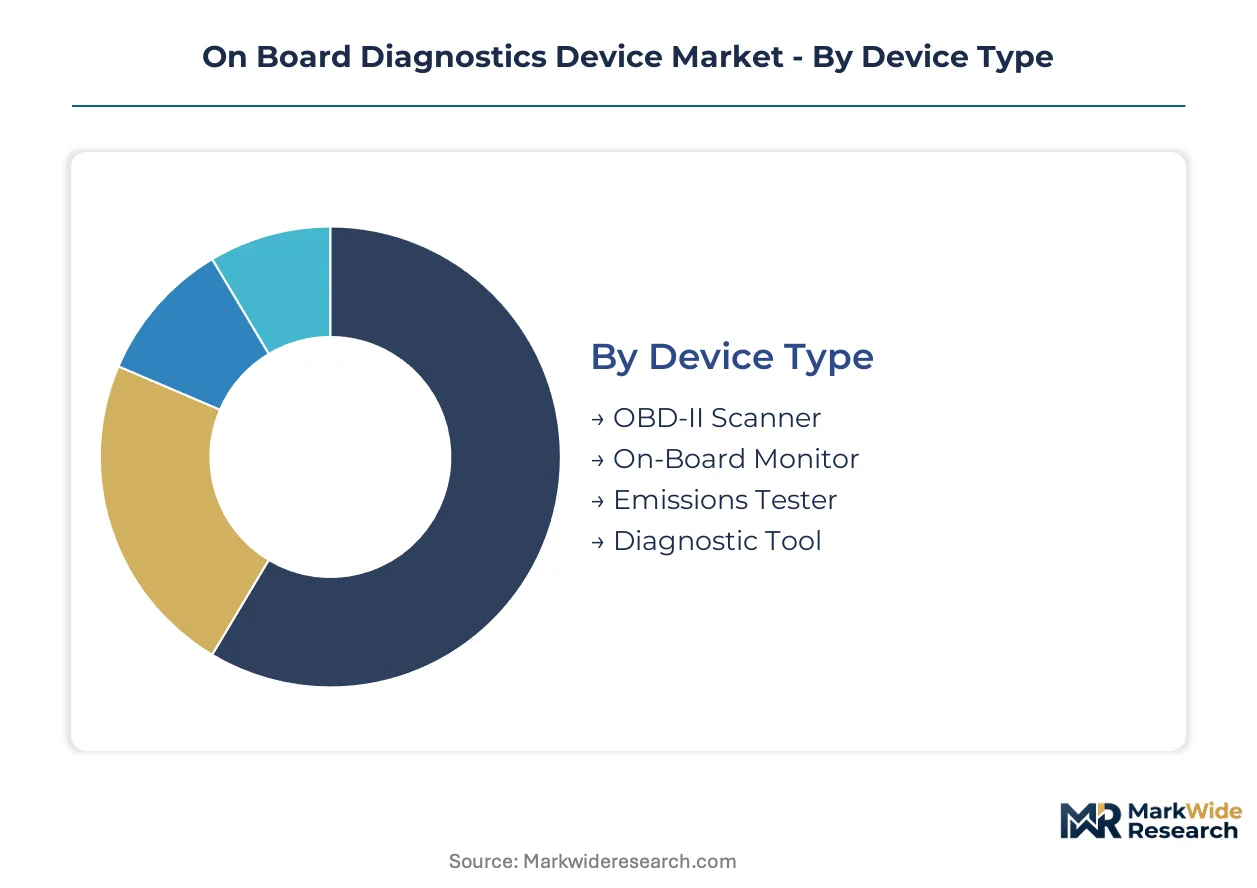
Device categorization in this market tracks divergent margin structures across hardware generations and connectivity protocols. Segment boundaries increasingly blur as fleet operators demand integrated platforms spanning multiple diagnostic functions.
Device Type:
Cost tier stratification separates mature hardware categories from emerging embedded systems commanding software-linked premiums.
- OBD-II Scanner:Handheld units decode standardized diagnostic trouble codes through SAE J1962 interfaces. Procurement concentrates among automotive service centers in Germany facing TÜV inspection mandates that accelerate replacement cycles for non-connected hardware.
- On-Board Monitor:Factory-embedded systems integrate predictive analytics at vehicle build. OEMs in California calibrate these units against CARB LEV III nitrogen oxide thresholds ahead of federal enforcement, creating dual firmware requirements.
- Emissions Tester:Stationary inspection bay equipment dominates established regulatory regimes.
- Diagnostic Tool:Multi-function devices span code reading, live data streaming, and bidirectional control.
Emissions tester hardware commands the established base. The steepest expansion runs through on-board monitors bundled with new vehicle sales.
Connectivity:
Application environment dictates physical layer selection, with electromagnetic resilience outweighing convenience in commercial duty cycles.
- Wired:Shielded cable connections resist interference in heavy-duty vehicle engine compartments. North American long-haul fleet operators specify these configurations where downtime costs exceed hardware premiums.
- Bluetooth:Low-energy protocols enable smartphone-native interfaces eliminating dedicated display costs. DIY enthusiasts in US retail channels drive volume for consumer-grade tools priced below professional equivalents.
- Wireless:Cellular-enabled units support real-time telemetry for distributed fleet assets.
- Wi-Fi:Higher bandwidth suits workshop environments with multiple simultaneous connections.
Wired configurations anchor commercial procurement. Bluetooth connectivity is expanding most quickly through aftermarket retail.
Vehicle Category:
Customer type differentiation separates owner-operator contexts from centralized fleet management purchasing authority.
- Commercial Vehicles:Light and medium-duty trucks require emissions verification under EPA Title 40 CFR Part 86. Fleet operators in the Netherlands prefer operational expenditure treatment for diagnostic subscriptions bundled with maintenance software.
- Heavy-Duty Vehicles:Class 8 trucks and vocational equipment demand ruggedized hardware. Edge computing modules with neural inference engines enable real-time pattern recognition during route operation across North American corridors.
- Passenger Vehicles:Individual ownership drives aftermarket tool demand.
- Two-Wheelers:Motorcycles and scooters present compact form-factor constraints.
Passenger vehicle applications represent the volume base. Heavy-duty vehicle integration shows the steepest technology premium expansion.
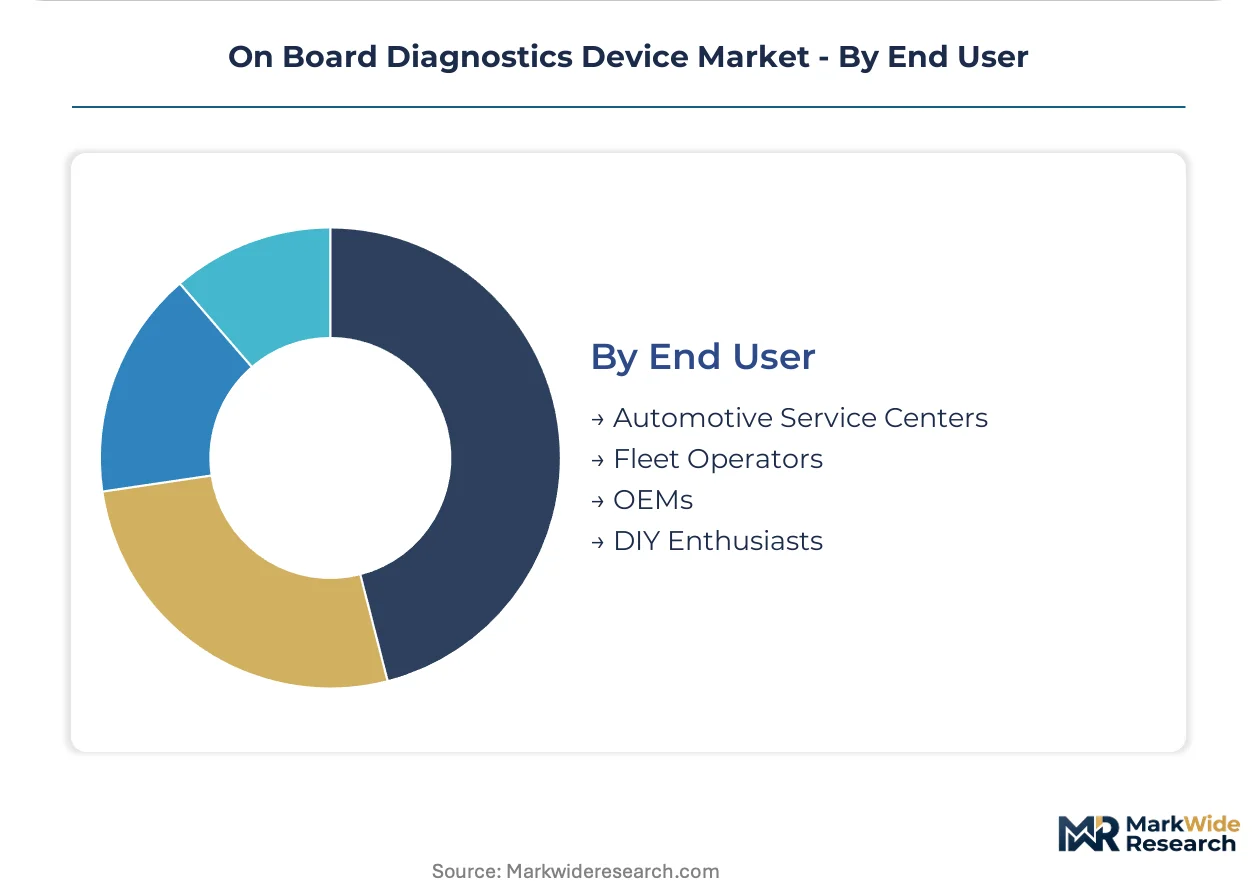
End User:
Volume concentration varies sharply between fragmented service networks and consolidated fleet procurement.
- Fleet Operators:Centralized purchasing authority favors bundled telematics platforms with captive diagnostic subscriptions. German commercial fleets under TÜV mandates sustain high replacement rates for cellular-enabled hardware.
- Automotive Service Centers:Independent garages face margin pressure from platform providers concentrating diagnostic purchasing authority.
- OEMs:Factory integration of predictive analytics shifts revenue from aftermarket hardware to embedded software fees.
- DIY Enthusiasts:Price-sensitive consumers drive Bluetooth tool volume through retail distribution.
Automotive service centers retain the installed base. Fleet operator procurement is climbing the fastest as telematics bundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement under Title 40 CFR Part 86 and California's CARB LEV III mandates are compressing hardware refresh cycles across multiple jurisdictions as manufacturers race to certify devices against tightening emissions protocols before 2027 model-year requirements take effect.
United States
Fleet operators in California face CARB supplemental LEV III nitrogen oxide detection thresholds that force recalibration of sensor firmware ahead of federal enforcement. The EPA's Title 40 CFR Part 86 mandates standardized diagnostic trouble code architectures that expand addressable hardware demand for aftermarket device manufacturers. Heavy-duty fleet corridors across Texas and the Pacific Northwest are piloting edge computing modules with neural inference engines for real-time pattern recognition during long-haul operations.
Germany
Commercial vehicle fleets under TÜV inspection mandates sustain high replacement rates for cellular-enabled diagnostic hardware capable of real-time emissions logging. The KBA enforces type-approval processes that multiply testing expenditure for emissions verification functionality before market entry. Industrial clusters in Baden-Württemberg and Bavaria concentrate embedded systems firmware talent scarce across ISO 15031 protocol stacks.
China
Domestic commercial vehicle production growth creates positioning opportunities for localized diagnostic hardware assembly under MIIT certification pathways. GB standards and SAMR regulations condition device specifications for the country's expanding heavy-duty fleet base. Manufacturing gravity in the Yangtze River Delta and Pearl River Delta supports captive supply of microcontroller components for OBD-II protocol processors.
India
Commercial vehicle production expansion under PLI scheme incentives generates first-mover positioning for localized diagnostic hardware assembly. The BIS certification framework governs device specifications for domestic fleet operators managing emissions compliance. Industrial corridors in Maharashtra and Gujarat concentrate automotive electronics manufacturing capacity serving both domestic and export markets.
Netherlands
Asset-light fleet operators prefer operational expenditure treatment for diagnostic subscriptions bundled with maintenance management software. EU F-Gas Regulation linkages between refrigerant leak detection and emissions monitoring open diagnostic device applications beyond traditional powertrain systems. Logistics hubs in Rotterdam and Amsterdam anchor procurement authority for telematics platform providers consolidating diagnostic purchasing decisions.
On Board Diagnostics Device Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority. The vendor base spans consolidated platform providers with recurring revenue models and hardware specialists serving discrete diagnostic functions. Three archetypes dominate: embedded systems heritage players, consumer-grade retail specialists, and fleet telematics platform operators. Competitive moves concentrate on backward integration into sensor manufacturing and deepening software differentiation as regulatory data logging requirements expand.
Among embedded systems heritage players, Robert Bosch GmbH exemplifies the integrated OBD-II scanner archetype for European OEM channels. Innova Electronics Corp. occupies the consumer-grade Bluetooth-enabled tool segment serving DIY enthusiasts through retail distribution. CalAmp Corporation anchors the fleet telematics platform operator archetype with captive diagnostic subscriptions generating recurring revenue streams.
| Leading Market Players |
|---|
| Autel Intelligent Technology Corp., Ltd. |
| Robert Bosch GmbH |
| Innova Electronics Corp. |
| Denso Corporation |
| Vector Informatik |
| AVL DiTEST GmbH |
| Continental AG |
| Geotab Inc. |
| CalAmp Corporation |
| Others |
Value Network & Pricing Analysis
Taiwan-based foundry concentration for OBD-II protocol microcontrollers concentrates upstream bargaining power with semiconductor suppliers, compressing hardware margins for device manufacturers while pushing value capture downstream toward firmware and subscription services. Fleet operators' shift toward operational expenditure treatment for diagnostic subscriptions has restructured margin pools away from unit sales.
Pricing Analysis
Certification level creates the primary spread across pricing tiers, with EPA Title 40 CARB dual-track firmware commanding premiums over single-certification hardware. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by connectivity protocol and software analytics depth. Cost compression in consumer-grade Bluetooth tools is intensifying because smartphone-native interfaces eliminate dedicated display costs. DIY enthusiasts through US retail channels exhibit highest price sensitivity, while German fleet operators under TÜV mandates show lowest sensitivity due to compliance-driven procurement.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries to downstream device assemblers have become standard, with supply-chain finance facilities bridging working capital gaps for mid-tier manufacturers. Taiwan, China, and South Korea anchor microcontroller and sensor component supply. Raw material dependencies center on silicon wafers, rare earth magnets for sensor assemblies, and copper for shielded cable production. Single-source vulnerability from TSMC concentration for automotive-grade processors poses structural risk. Distribution runs through OEM direct channels, aftermarket distributors, and fleet telematics platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable barriers—EPA and CARB certification requirements lock in incumbent positions through multi-year approval timelines that new entrants cannot bypass.
For Market Incumbents: Insulate core revenue streams by deepening backward integration into sensor manufacturing to reduce Taiwan foundry exposure, and anchor fleet relationships through multi-year telematics bundling that raises switching costs. The threat of cloud-native diagnostic architectures displacing standalone hardware demands accelerated software differentiation investment. Certification investment in EU F-Gas Regulation compliance for thermal management applications represents the priority lever for margin expansion.
For New Entrants and Emerging Players: India's PLI scheme corridors present the most penetrable geographic entry point, with localized BIS certification pathways offering first-mover positioning before incumbent production relocation. Target commercial vehicle fleet operators in Maharashtra and Gujarat industrial corridors with hardware-as-a-service models that mirror European operational expenditure preferences. Partner with domestic electronics manufacturing service providers to bypass capital-intensive fab relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fleet telematics platform operators holding captive diagnostic subscription revenue but lacking embedded systems heritage. The five-to-ten year viability window favors targets with ISO 15031 protocol stack capabilities and existing EPA or CARB certifications. Watch for inflection in India BIS certification velocity as signal of competitive repositioning opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Reduces Taiwan foundry dependency and captures margin from microcontroller supply. |
| Dual-Track Firmware Development | Enables simultaneous EPA and CARB certification, compressing time-to-market for California-bound hardware. |
| Subscription Telemetry Bundling | Shifts revenue from hardware margins to recurring software fees with fleet operators. |
| Edge Computing Module Deployment | Captures predictive maintenance premiums from heavy-duty fleet operators in North American corridors. |
| Localized Assembly Under PLI Schemes | Positions first-mover advantage in India's expanding commercial vehicle production base. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, CARB certification databases, and automotive production statistics. Primary interviews engaged fleet operations managers, Tier 1 supplier procurement leads, embedded systems firmware engineers, and aftermarket distribution channel heads. Secondary validation drew from SAE International protocol documentation, EU type-approval registries, and customs trade data for diagnostic device imports. Bottom-up unit shipment estimates triangulate against top-down fleet penetration models.
Forecast inputs include vehicle production volumes by propulsion architecture, regulatory mandate enforcement timelines, and fleet telematics adoption curves across the analysis window. Segmentation dimensions span device type, connectivity protocol, vehicle category, and end-user purchasing authority. CAGRs derive from regression against historical replacement cycles and projected compliance-driven refresh demand. Battery electric vehicle thermal management integration and refrigerant leak detection under F-Gas Regulation shape forward-looking application expansion.
Macroeconomic conditions sit as an overlay; deviation in semiconductor allocation volatility, commercial vehicle production cycles, or regulatory enforcement timing would shift the trajectory. Forecasts reflect documented assumptions regarding certification pathway durations and fleet procurement pattern continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Global Track Geometry Measurement System (TGMS) Market
Automotive Testing and Simulation
Automotive Battery Testing Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
Automated Guided Cart Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market