
 Automotive Driving Simulators Market | 2026-2036
Automotive Driving Simulators Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Driving Simulators Market Analysis
High-fidelity motion cueing is rotating the Automotive Driving Simulators market toward professional-grade installations. VI-grade GmbH leverages proprietary motion-platform engineering to dominate motorsport and OEM validation segments. IPG Automotive GmbH sustains leadership in software-defined vehicle dynamics modeling for German automakers. Moog Inc. anchors the supply base through electromechanical actuation systems that power tier-one simulator platforms.
An automotive driving simulator is a hardware-in-the-loop system integrating real-time vehicle dynamics software, motion platforms, and visual projection arrays to replicate road conditions without physical prototypes; systems typically achieve latency below 20 milliseconds to preserve driver immersion and valid behavioral response. Motion-based deployments command premium positioning due to their structural complexity and institutional buyer concentration in OEM research centers. PC-based and console-based categories occupy volume tiers where driving schools and entertainment centers prioritize capital efficiency over fidelity depth.
Euro NCAP protocols, NHTSA Federal Motor Vehicle Safety Standards, and China's GB/T autonomous vehicle testing mandates collectively shape product specifications and market access requirements for simulator manufacturers. EMA-equivalent technical standards in Europe and NHTSA guidance documents in the United States create divergent compliance pathways that vendors must navigate simultaneously. Stakeholders should monitor regulatory convergence on virtual homologation as the decisive variable for platform standardization and cross-border sales eligibility.
Market Dynamics
Virtual homologation mandates are compressing physical prototype cycles across automotive development pipelines. Euro NCAP protocols and NHTSA guidance documents are forcing OEMs to front-load simulation investment before regulatory submission deadlines.
Growth Catalysts
- Euro NCAP virtual validation mandates:European safety protocols now accept simulator data for pedestrian protection and crash-structure pre-certification, eliminating months from development timelines.
- Autonomous vehicle sensor fusion testing:LiDAR-camera-radar integration in synthetic environments allows edge-case scenario replication impossible on public roads.
- China GB/T testing standards:Domestic certification requirements for intelligent connected vehicles specify simulator-based validation for complex urban traffic scenarios.
Market Restraints
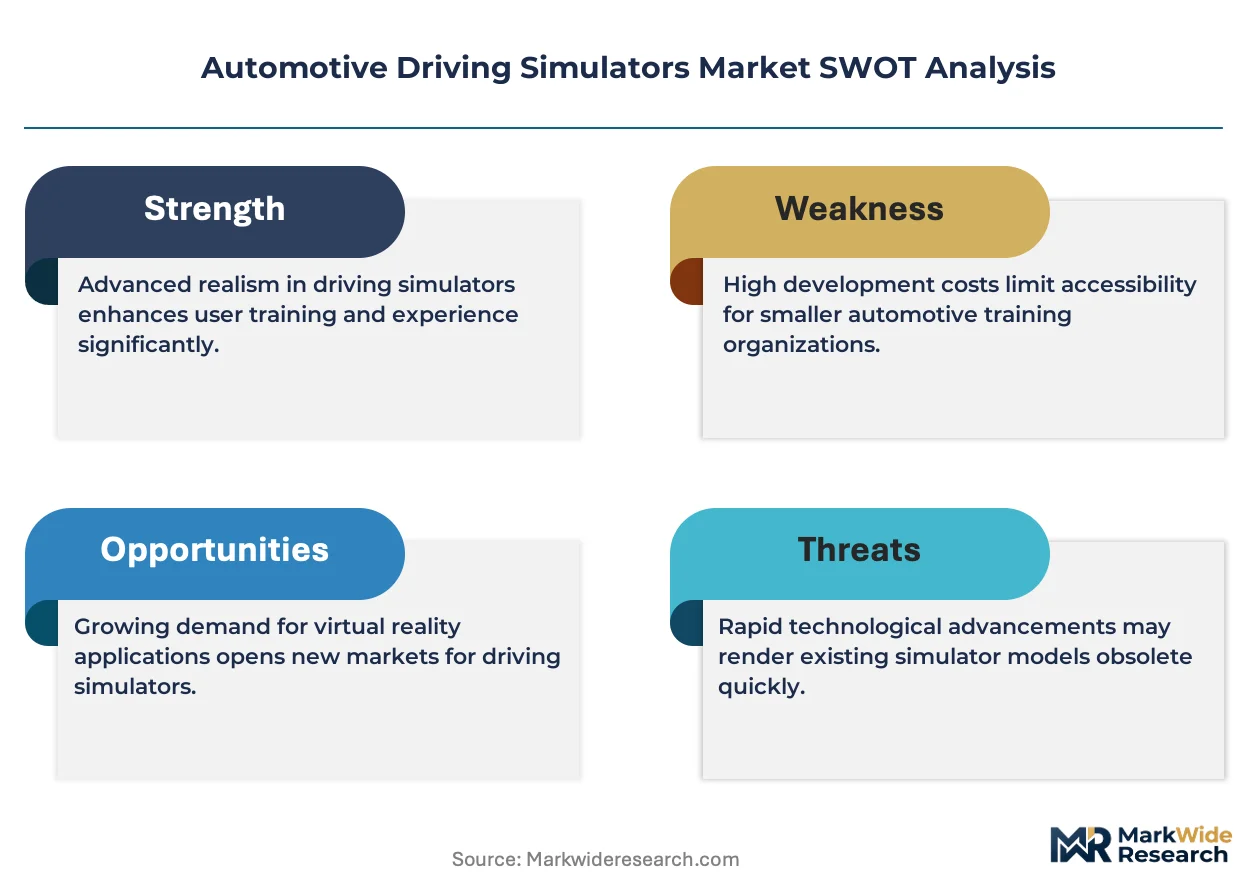
- Electromechanical actuator supply concentration:Precision motion-platform components depend on a limited supplier base concentrated in Germany and Japan, creating delivery bottlenecks during OEM facility expansions.
- High-fidelity visual projection costs:LED dome arrays and laser phosphor systems represent 40-60% of total system capex, restricting adoption among independent driving schools.
- Latency standard fragmentation:Divergent millisecond-threshold definitions across NHTSA, Euro NCAP, and GB/T protocols force redundant hardware configurations for multi-market vendors.
Strategic Opportunities
- India driving school digitization:State transport authorities in Maharashtra and Karnataka are piloting mandatory simulator hours for commercial license certification, opening volume-tier demand.
- Software-as-a-service motion cueing:Cloud-rendered vehicle dynamics models delivered via subscription reduce upfront hardware requirements for tier-two automotive suppliers.
- EU AI Act compliance tooling:Automated scenario generation for autonomous system validation addresses emerging algorithmic transparency requirements in European type-approval processes.
Industry Challenges
- Real-time physics engine talent scarcity:Specialized expertise in multibody dynamics and tire modeling concentrates among legacy automotive software houses, constraining vendor expansion.
- Legacy HIL integration complexity:Proprietary CAN bus architectures from incumbent OEMs require custom interface development for each simulator deployment, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Driving Simulators Market |
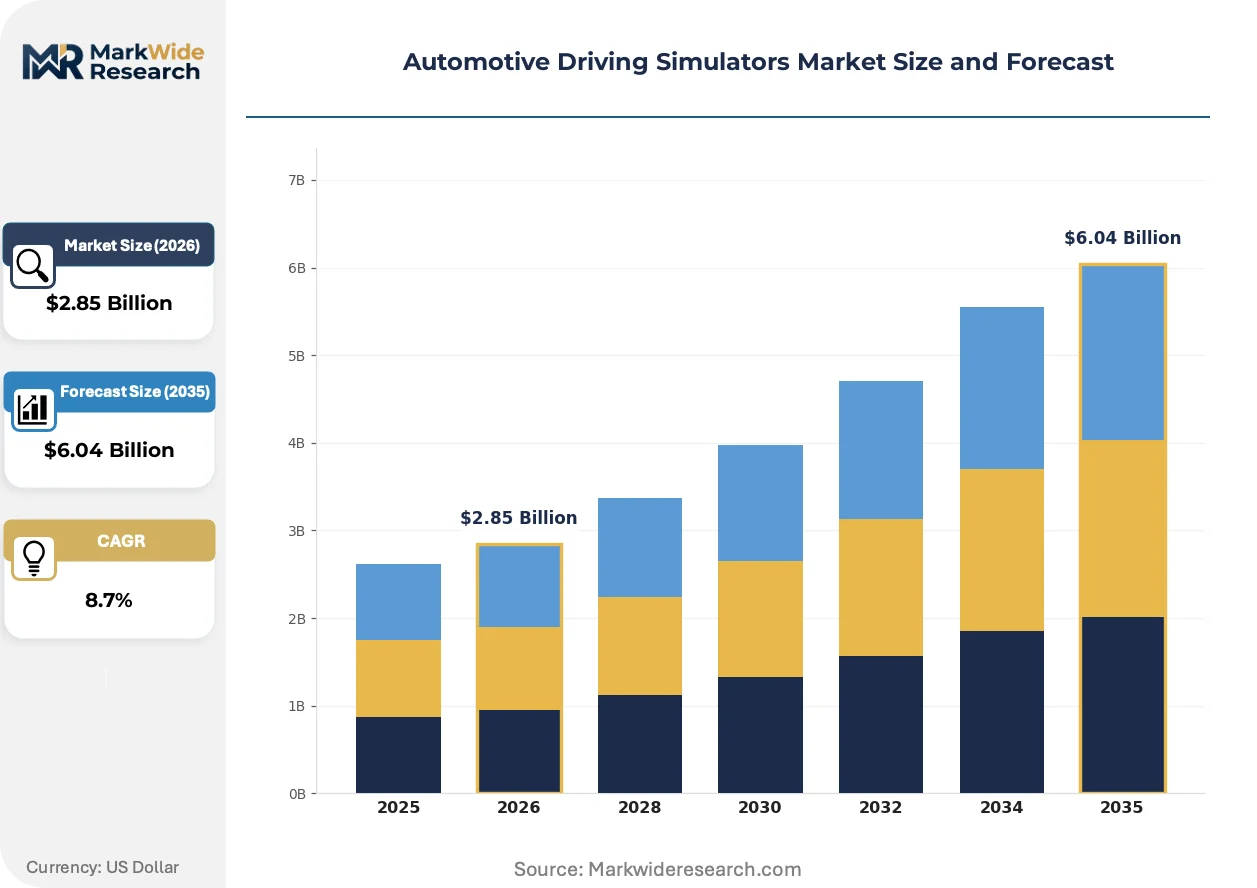
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $6.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PC-based, Console-based, Motion-based, VR-based End User: Research Institutions, Automotive OEMs, Driving Schools, Entertainment Centers Deployment: On-premise, Cloud-based, Hybrid, Mobile Feature: Real-time Feedback, Multi-user Capability, Customizable Scenarios, Data Analytics |
| Companies Covered | AVSimulation, VI-grade GmbH, IPG Automotive GmbH, AB Dynamics, FAAC Incorporated, Cruden BV, Ansible Motion, Moog Inc., Mechanical Simulation Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Driving Simulators Market Emerging Trajectories
Generative scenario synthesis is displacing manually-scripted test catalogs across validation workflows. Synthetic environment creation now operates at machine-speed rather than engineering-hour speed.
Digital twin architectures are decomposing the traditional separation between vehicle dynamics software and physical motion platforms. OEM research centers in Stuttgart, Detroit, and Shanghai are adopting unified real-time operating systems that collapse latency buffers between computation and mechanical response. This convergence is decomposing the historical vendor stack into interchangeable software and hardware layers.
NHTSA Federal Motor Vehicle Safety Standards updates are incorporating explicit provisions for simulated pedestrian-autonomous vehicle interaction testing. The regulatory expansion compels simulator vendors to enhance biomechanical human-model fidelity. Tier-one suppliers serving the US market are accelerating partnerships with anthropometric simulation specialists to maintain homologation eligibility.
Consolidated procurement by multi-brand automotive groups is compressing vendor negotiation cycles. Volkswagen Group, Stellantis, and Hyundai-Kia are centralizing simulator acquisition through single-source framework agreements that bundle motion platforms, software licenses, and maintenance across global R&D sites. This concentration is most visible in Germany and South Korea, where OEM headquarters proximity to simulator engineering clusters enables just-in-time specification adjustments.
Automotive Driving Simulators Market Segmentation
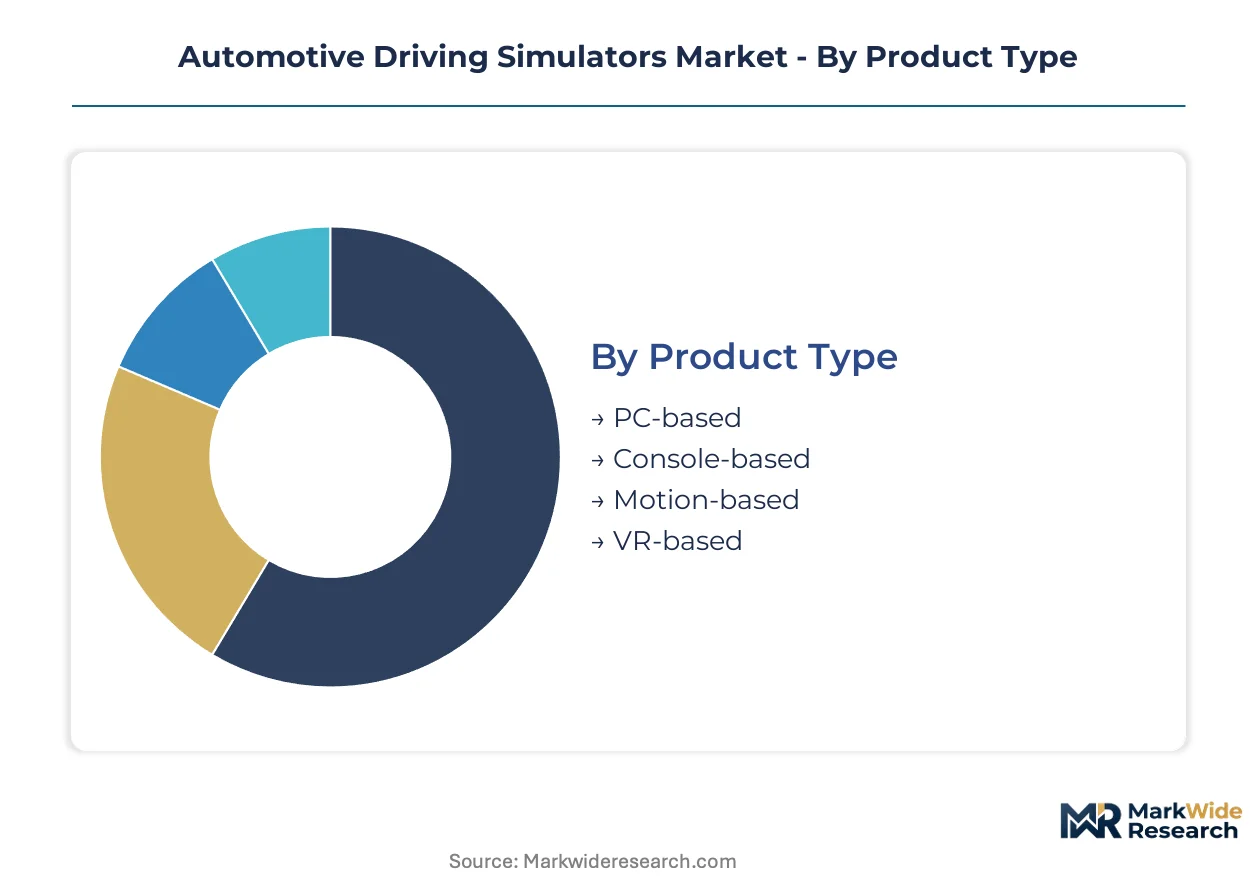
Segmentation in automotive driving simulators reveals distinct margin architectures across hardware fidelity tiers and institutional buyer profiles. Each category maps to specific validation workflows, from regulatory homologation to commercial driver certification.
Product Type:
Margin pools concentrate in electromechanical motion platforms where actuator precision and latency engineering command premium pricing.
- Motion-based:Hardware-in-the-loop systems integrate six-degree-of-freedom platforms with sub-20 millisecond latency thresholds. OEM research centers in Germany and Japan anchor demand as Euro NCAP and GB/T protocols tighten virtual validation requirements.
- VR-based:Head-mounted displays with inside-out tracking reduce physical footprint while preserving immersion depth. Driving schools in Maharashtra and Karnataka are piloting VR deployments for commercial license training under state transport authority mandates.
- PC-based:Desktop configurations using consumer-grade GPUs serve budget-constrained independent driving schools.
- Console-based:Modified gaming hardware occupies entertainment center installations where capital efficiency outweighs fidelity demands.
Motion-based systems hold installed capacity. VR-based configurations are rotating up the share rankings.
End User:
Volume concentration sits with institutional buyers consolidating procurement through multi-site framework agreements.
- Automotive OEMs:Volkswagen Group, Stellantis, and Hyundai-Kia centralize acquisition across Stuttgart, Detroit, and Shanghai R&D sites. NHTSA Federal Motor Vehicle Safety Standards updates compel enhanced pedestrian-interaction simulation capabilities.
- Driving Schools:State-mandated simulator hours for commercial certification in India are opening volume-tier demand previously served by behind-the-wheel instruction alone.
- Research Institutions:University automotive engineering programs deploy mid-fidelity systems for human factors studies.
- Entertainment Centers:Location-based entertainment venues prioritize throughput over behavioral validation accuracy.
Automotive OEMs dominate capital deployment. Driving Schools are climbing the fastest as regulatory mandates expand.
Deployment:
Customer type determines infrastructure preference, with security-sensitive buyers resisting off-premise computation.
- On-premise:Dedicated server installations preserve data sovereignty for autonomous vehicle algorithm development. German OEMs insist on local hardware to satisfy KBA type-approval documentation requirements.
- Hybrid:Edge-rendered vehicle dynamics with cloud-orchestrated scenario libraries balance latency and scalability. Tier-two automotive suppliers in South Korea are adopting this architecture to reduce upfront hardware requirements.
- Cloud-based:Fully remote rendering enables subscription pricing for smaller validation consultancies.
- Mobile:Containerized simulator units deploy to temporary test sites for motorsport calibration.
On-premise installations retain the majority of high-value contracts. Hybrid deployments are gaining share fastest among mid-tier suppliers.
Feature:
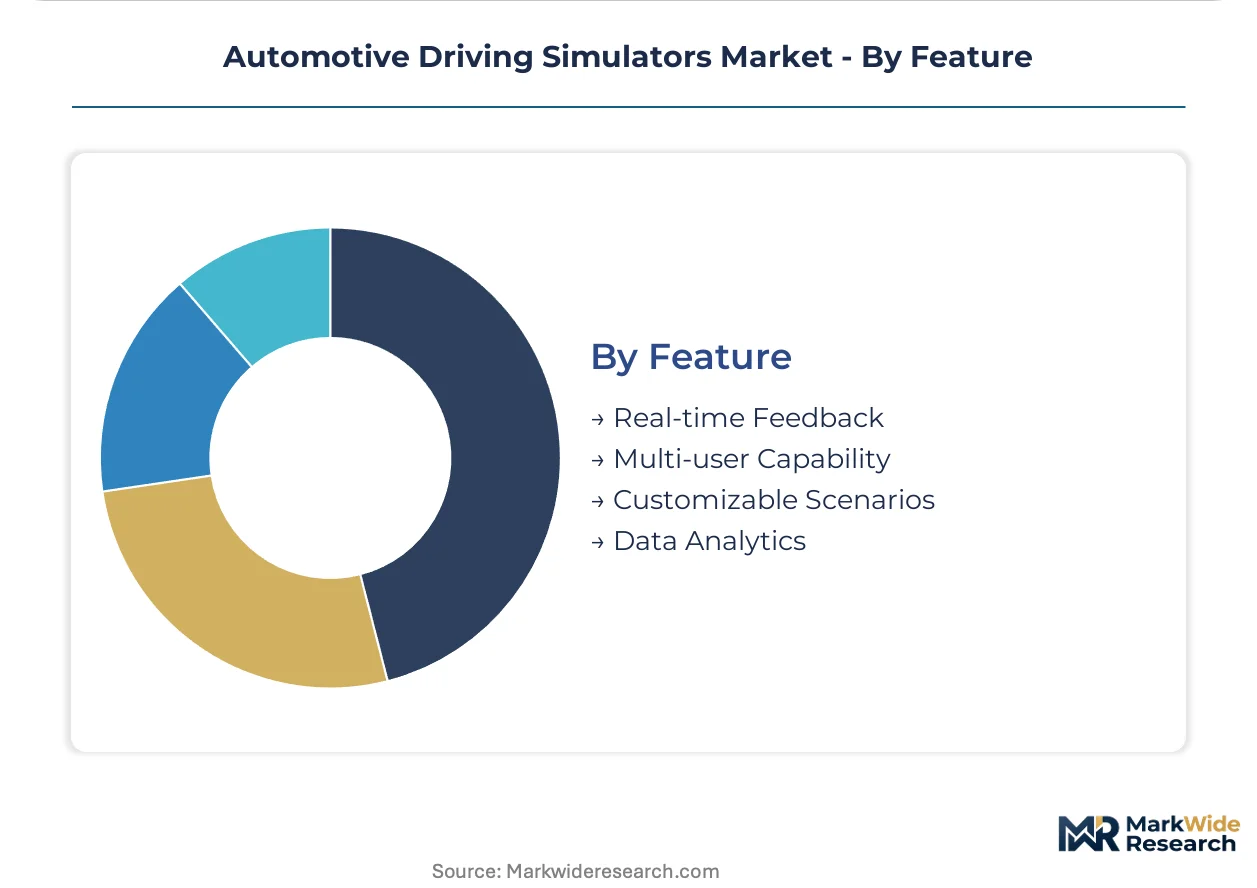
Functional differentiation increasingly concentrates in software-layer capabilities rather than hardware specifications.
- Data Analytics:Telemetry pipelines capturing steering torque, gaze tracking, and physiological response enable predictive driver modeling. EU AI Act compliance tooling is emerging as a requirement for algorithmic transparency in autonomous system validation.
- Customizable Scenarios:Generative synthesis engines displace manually-scripted test catalogs, operating at machine-speed for edge-case replication impossible on public roads.
- Real-time Feedback:Instantaneous performance scoring supports driving school instruction workflows.
- Multi-user Capability:Networked environments enable V2X interaction testing for connected vehicle protocols.
Data Analytics capabilities anchor premium positioning. Customizable Scenarios are expanding most quickly as generative methods mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German simulator manufacturers export precision motion platforms to OEM validation centers in Detroit, Stuttgart, and Shanghai, anchoring the primary trade corridor in this capital-goods market.
United States
NHTSA Federal Motor Vehicle Safety Standards updates mandate simulated pedestrian-autonomous vehicle interaction testing, compelling OEMs to enhance biomechanical human-model fidelity. The Detroit-Warren automotive corridor concentrates demand from Ford, General Motors, and Stellantis North America as these manufacturers centralize virtual validation procurement.
Germany
KBA type-approval documentation requirements force German OEMs to insist on dedicated on-premise server installations for data sovereignty. The Stuttgart engineering cluster anchors motion-platform engineering expertise, with Baden-Württemberg hosting VI-grade GmbH and IPG Automotive GmbH headquarters adjacent to Porsche, Mercedes-Benz, and Bosch research facilities.
China
GB/T autonomous vehicle testing standards specify simulator-based validation for complex urban traffic scenarios, accelerating domestic manufacturing capacity expansion. The Yangtze River Delta concentration in Shanghai and surrounding provinces draws investment from BYD, NIO, and SAIC as these OEMs build captive validation centers.
Japan
METI industrial policy supports domestic simulator component supply chains for electromechanical actuation systems. The Nagoya-Toyota City corridor concentrates Toyota, Honda, and Denso validation operations, with tier-one suppliers adopting hybrid cloud-edge architectures to reduce upfront hardware requirements.
South Korea
MFDS-equivalent automotive certification alignment with Euro NCAP protocols drives simulator adoption for export-market homologation. The Seoul Capital Area hosts Hyundai-Kia and Mando Corporation R&D centers, with centralized procurement frameworks bundling motion platforms across global sites.
Automotive Driving Simulators Market Vendor Landscape
Listed leaders compete with private specialists across hardware-software integration depth, creating a tiered structure where scale advantages concentrate in motion-platform electromechanics while agility concentrates in scenario-generation software. Three archetypes dominate: full-stack integrators owning proprietary motion engineering, software-defined dynamics specialists licensing vehicle models, and component suppliers capturing actuator margins through tier-one relationships. Competitive moves center on multi-site framework agreements consolidating procurement and generative scenario synthesis capabilities displacing manual test-catalog development.
Within the full-stack integrator tier, VI-grade GmbH and Moog Inc. exemplify contrasting geographic anchoring—German precision engineering against American electromechanical systems manufacturing. IPG Automotive GmbH occupies a position among software-defined specialists, representing the archetype of vehicle-dynamics modeling houses that decouple computation from physical motion hardware. These three entities collectively illustrate the vendor-stack decomposition underway as OEMs adopt unified real-time operating systems.
| Leading Market Players |
|---|
| AVSimulation |
| VI-grade GmbH |
| IPG Automotive GmbH |
| AB Dynamics |
| FAAC Incorporated |
| Cruden BV |
| Ansible Motion |
| Moog Inc. |
| Mechanical Simulation Corporation |
| Others |
Supply Flow & Price Mechanics
Electromechanical actuator manufacturing scale in Germany and Japan anchors price floors across motion-platform tiers, compressing margins for second-tier suppliers while enabling premium capture by integrated incumbents serving OEM validation centers. This concentration forces volume-tier buyers toward VR-based and PC-based alternatives as electromechanical supply tightens during facility expansion cycles.
Pricing Analysis
Next-generation LED dome arrays and laser phosphor projection systems command substantial premiums over prior-generation lamp-based installations, while legacy motion-platform configurations face cost compression from cloud-rendered SaaS alternatives. Three-tier pricing structure across premium, standard, and economy levels separates OEM research center specifications from driving school deployments and entertainment center installations. Price differentiation centers on latency certification thresholds and Euro NCAP compliance documentation. Pricing pressure stems from LED dome array cost concentration representing 40-60% of system capex. Independent driving schools exhibit highest price sensitivity, while German OEMs prioritize specification compliance over unit economics.
Supply Chain Analysis
Electromechanical actuator inventory cycles extend delivery timelines during OEM facility expansions, compressing procurement windows for multi-site framework agreements. Precision motion-platform component manufacturing concentrates in Germany and Japan, with China accelerating domestic capacity expansion under GB/T testing mandates. Raw material dependencies span high-grade steel forgings, rare-earth magnetic materials, and specialized servo motors. Single-source vulnerability concentrates in precision gearbox assemblies from Baden-Württemberg engineering clusters. Distribution runs through tier-one simulator integrators bundling hardware, software licenses, and maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in mid-tier validation consultancies and regional driving school digitization mandates, as regulatory divergence between NHTSA, Euro NCAP, and GB/T protocols prevents vendor consolidation.
For Market Incumbents: Secure multi-site framework agreements with Volkswagen Group, Stellantis, and Hyundai-Kia before procurement centralization completes, while acquiring generative scenario synthesis capabilities to displace manual test-catalog development. Threat from cloud-rendered SaaS motion cueing demands backward integration into vehicle dynamics software to preserve hardware attach rates. Certification investment in EU AI Act compliance tooling represents the critical lever for European type-approval eligibility. For New Entrants and Emerging Players: Lead with software-defined vehicle dynamics licensing to bypass electromechanical actuator supply constraints, targeting tier-two automotive suppliers in South Korea and India driving school digitization pilots. White-space concentrates in hybrid cloud-edge architectures reducing upfront hardware requirements. Go-to-market angle emphasizes subscription pricing against capital-intensive incumbent offerings. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-defined dynamics specialists licensing vehicle models rather than hardware integrators. Long-term viability favors vendors with scenario-generation IP and regulatory compliance documentation capabilities. Acquisition target archetype: mid-cap generative synthesis engine developers with Euro NCAP validation relationships. Signal to watch: regulatory convergence on virtual homologation standards enabling cross-border sales eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Generative Scenario Synthesis Investment | Machine-speed edge-case replication displaces manual test-catalog development for autonomous validation. |
| Multi-Site Framework Agreement Consolidation | Centralized procurement across Stuttgart, Detroit, and Shanghai R&D sites compresses vendor negotiation cycles. |
| EU AI Act Compliance Tooling Development | Automated transparency documentation addresses emerging algorithmic requirements in European type-approval. |
| Hybrid Cloud-Edge Architecture Deployment | Edge-rendered dynamics with cloud-orchestrated libraries reduce upfront hardware for tier-two suppliers. |
| Backward Integration into Motion Actuation | In-house production of electromechanical components mitigates supply concentration in Germany and Japan. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, driving school operators, and simulator integration specialists; and secondary validation against SEC filings, vehicle production databases, IHS Markit registration data, and regulatory submission documents. Triangulation between bottom-up segment sizing and top-down market reconciliation tested internal consistency across hardware fidelity tiers and geographic deployment patterns.
Across the analysis window, projections incorporate segmentation by product type, end user category, deployment architecture, and feature capability, with CAGRs derived from regression analysis of historical adoption curves and regulatory mandate timelines. Industry-specific forecast inputs include Euro NCAP protocol revision schedules, NHTSA Federal Motor Vehicle Safety Standards update trajectories, and China GB/T intelligent connected vehicle certification expansion rates.
The analysis sits within stated boundaries; outcomes outside continued regulatory acceptance of virtual validation data or sustained OEM R&D expenditure levels would require recalibration. Forecasts reflect documented assumptions regarding electromechanical actuator supply elasticity and latency standard convergence timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market
Automotive Testing and Simulation
Automated Guided Cart Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Autonomous Valet Parking System Scenario-Based Test Equipment Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Vehicle Crash Testing System Market
Automotive Testing and Simulation
Dynamometer Market