
 Automotive Durability Testing Market | 2026-2036
Automotive Durability Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Durability Testing Market Insights
Buyer concentration among electric vehicle OEMs is expanding as legacy automakers spin off dedicated EV divisions and battery-electric startups scale production volumes. SGS leverages its global laboratory network to serve these consolidated validation programs across multiple continents. HORIBA anchors its position through deep specialization in powertrain test systems, particularly for hybrid and electric drivetrain durability cycles. MTS Systems competes by controlling the structural dynamics testing segment with servo-hydraulic and electric simulation platforms.
Automotive durability testing encompasses the accelerated evaluation of vehicle components and systems under replicated operational stresses including thermal cycling, vibration profiles, corrosion exposure, and fatigue loading to predict service life and warranty performance. Environmental durability tests now dominate capital allocation as climate chamber investments surge to simulate extreme temperature and humidity combinations. Among components, chassis and suspension testing sustains the largest revenue pool due to persistent loads from road surface interaction, while virtual simulations represent the fastest-expanding segment as digital twin adoption reduces physical prototype requirements.
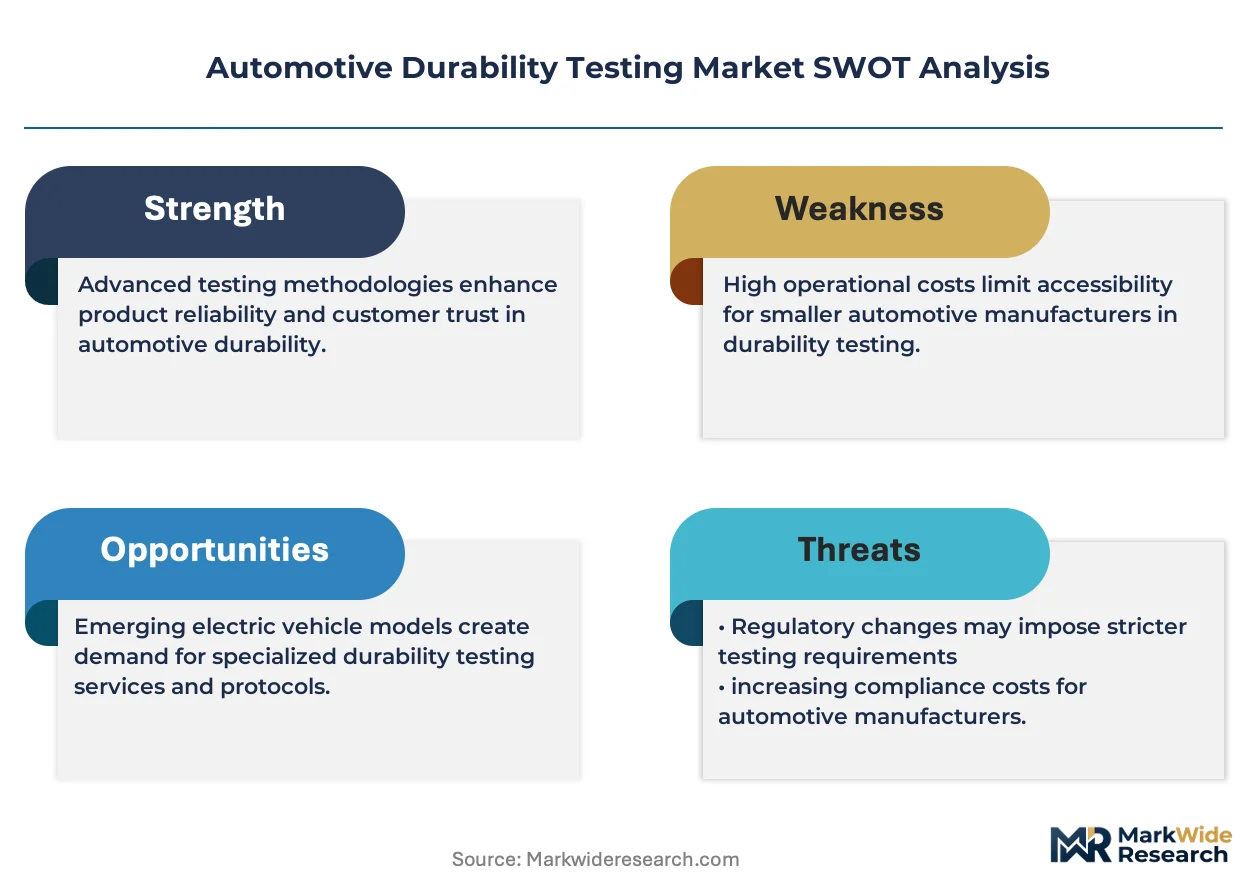
FAA guidelines for autonomous vehicle testing infrastructure, EPA durability requirements for emission system certification, and NHTSA crashworthiness standards collectively mandate comprehensive validation protocols that shape laboratory demand. The EU Green Deal and associated CSRD reporting obligations further extend testing scope to cover full lifecycle carbon accountability for automotive suppliers. Stakeholders must decide whether to build captive testing capacity or outsource to accredited third-party providers as regulatory complexity outpaces in-house capability development.
Market Dynamics
Electric vehicle platform proliferation is fragmenting validation protocols as battery-electric architectures demand entirely new fatigue, thermal, and corrosion test cycles distinct from internal combustion legacy standards.
Growth Catalysts
- Euro 7 Emission Standards:The European Union's tightened particulate and NOx limits mandate extended powertrain durability verification, expanding test cycle volume for emission-critical components.
- WLTP Protocol Harmonization:Worldwide Harmonized Light Vehicles Test Procedure adoption across multiple jurisdictions forces OEMs to replicate real-world driving profiles in laboratory conditions, boosting chassis dynamometer utilization.
- Silicon Carbide Inverter Adoption:Wide-bandgap semiconductor deployment in 800V architectures introduces new thermal cycling stress patterns that accelerate inverter module validation requirements.
Market Restraints
- Lithium Price Volatility:Battery pack raw material cost swings compress EV program budgets, forcing deferred or reduced physical prototype testing cycles.
- Chamber Manufacturing Concentration:German and Japanese environmental simulation equipment suppliers control critical climate chamber supply, creating 18-24 month lead time bottlenecks for expansion projects.
- Physical-Digital Validation Gap:Correlation uncertainty between virtual twin predictions and actual component failure modes limits full substitution of hardware testing, maintaining captive capital requirements.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for automotive and advanced chemistry cell manufacturing attract test facility investment to serve localized EV supply chains.
- Autonomous Vehicle Sensor Validation:LiDAR and camera module durability under thermal shock and vibration loads represents an emerging test category with limited established protocol standardization.
- CSRD Lifecycle Reporting:EU Corporate Sustainability Reporting Directive obligations extend supplier accountability to full product carbon footprint, creating demand for embodied energy verification testing.
Industry Challenges
- Multiphysics Simulation Expertise Shortage:Coupled thermal-mechanical-electrical modeling competency gaps constrain digital twin deployment timelines for Tier 2 suppliers.
- Cross-Platform Test Standard Harmonization:Divergent OEM-specific durability protocols prevent test result portability, forcing redundant validation cycles for multi-customer component manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Durability Testing Market |
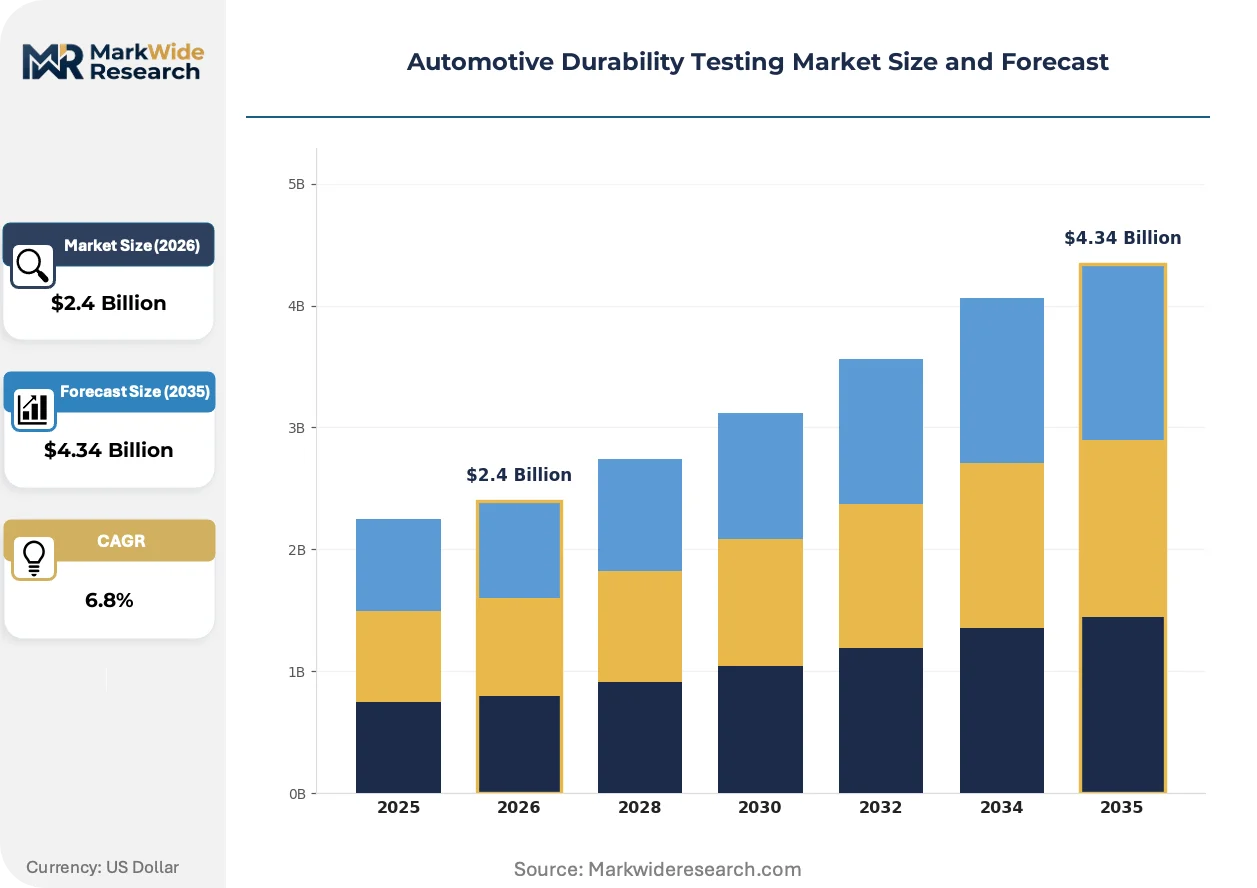
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Type: Static Tests, Dynamic Tests, Environmental Durability Tests, Virtual Simulations Component: Chassis, Suspension, Engine, Transmission End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Institutions Service Type: Consulting, Testing Services, Certification, Support Services |
| Companies Covered | Intertek, Kistler, SGS, MTS Systems, Millbrook, TÜV SÜD, HORIBA, Applus+, Element Materials Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Durability Testing Market Trends and Innovations
Digital twin technology is compressing development cycles by enabling predictive failure modeling before physical prototype construction, fundamentally altering capital allocation between simulation software and hardware test assets.
Cloud-based durability simulation platforms are decentralizing computational workload distribution across engineering teams. Tier 1 suppliers in Germany and the United States now run distributed fatigue analysis on remote server clusters rather than captive HPC installations. This architecture is decentralizing test data ownership and enabling real-time collaboration between OEM validation engineers and component suppliers.
EPA emission certification durability requirements are extending test mileage thresholds for heavy-duty vehicles, forcing powertrain suppliers to operate extended dynamometer cycles. The regulatory burden falls most heavily on diesel aftertreatment system manufacturers serving the US commercial vehicle segment, which is responding by investing in accelerated aging catalyst test cells.
Subscription-based test equipment access is displacing traditional capital purchase models among mid-volume EV startups. Battery-electric entrants in California and Bavaria now lease servo-hydraulic road simulation rigs rather than acquiring permanent capacity. This behavioral shift concentrates most visibly among Series C-stage mobility companies lacking balance sheet depth for captive laboratory investment.
Automotive Durability Testing Market Segmentation
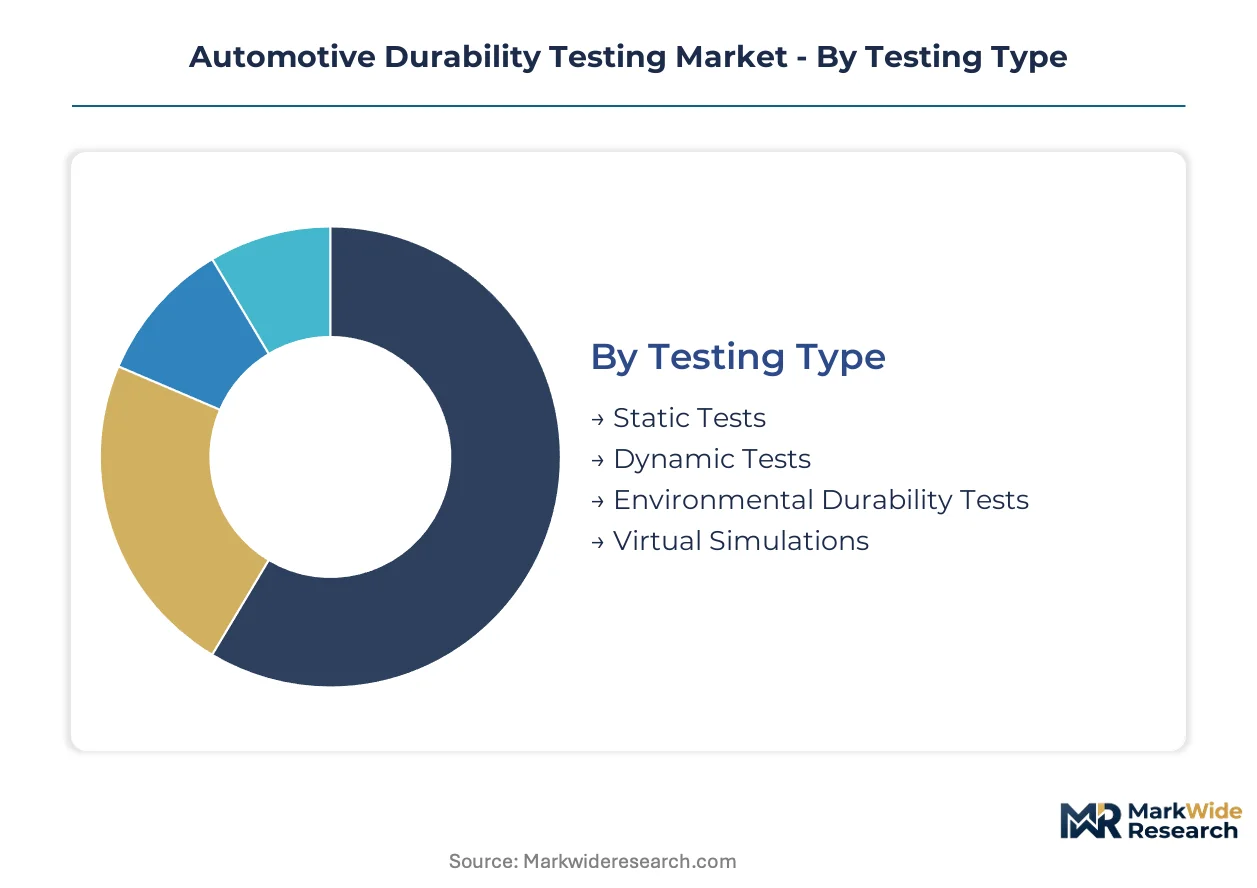
Automotive durability testing segments reflect divergent capital intensity and regulatory exposure across the validation value chain. Testing type determines equipment requirements, while end-user concentration shapes contract structures and pricing power distribution.
Testing Type:
Volume-driven physical testing commands the largest capital allocation, while premium-priced virtual simulations capture expanding software budgets.
- Environmental Durability Tests:Climate chamber validation replicates thermal cycling, humidity exposure, and corrosive atmospheres to accelerate aging predictions. Investment concentrates in Germany and Japan where chamber manufacturers face 18-24 month order backlogs. Euro 7 emission standards and WLTP protocol harmonization are forcing expanded thermal range requirements.
- Virtual Simulations:Digital twin platforms model fatigue, thermal, and vibration failure modes before physical prototype construction. Demand clusters among California and Bavaria-based EV startups seeking to compress development timelines. Cloud-based deployment is displacing captive HPC installations at Tier 1 suppliers.
- Dynamic Tests:Servo-hydraulic and electromechanical systems replicate road load profiles on chassis dynamometers and vibration tables.
- Static Tests:Structural load frame validation assesses component stiffness and ultimate strength under controlled displacement conditions.
Today's leader: Environmental Durability Tests. Tomorrow's challenger: Virtual Simulations.
Component:
Application-specific test protocols align with warranty exposure and load severity across vehicle architectures.
- Chassis:Frame and body structure validation under combined bending, torsion, and impact loading dominates physical test cell utilization. German and US commercial vehicle manufacturers operate the most severe durability cycles due to EPA heavy-duty mileage thresholds. Extended dynamometer programs for diesel aftertreatment integration add complexity.
- Suspension:Control arm, spring, and damper testing sustains persistent demand from road surface interaction loads. Investment concentrates in China and Germany where OEMs replicate cobblestone and Belgian block profiles. 800V electric architectures introduce new unsprung mass validation requirements.
- Engine:Powertrain dynamometer validation covers thermal mechanical fatigue and emission system aging.
- Transmission:Gearbox and driveline testing addresses contact fatigue and synchronizer wear under torque reversal conditions.
Chassis testing anchors current revenue pools. Suspension validation is climbing the fastest as EV platform proliferation fragments load case specifications.
End User:
Customer type determines contract duration, technical specification control, and captive versus outsourced testing decisions.
- OEMs:Vehicle manufacturers operate the largest captive validation programs with direct regulatory accountability for type approval. Euro 7 and EPA certification requirements force integrated powertrain-chassis test sequences. SGS and HORIBA capture outsourced overflow from capacity-constrained programs.
- Tier-1 Suppliers:Component manufacturers face redundant validation cycles across divergent OEM protocols. Cross-platform test standard harmonization gaps prevent result portability. MTS Systems targets this segment with flexible servo-hydraulic platform configurations.
- Aftermarket Providers:Warranty validation and reverse engineering testing serves replacement part certification.
- Research Institutions:Academic and government laboratories conduct fundamental fatigue research and protocol development.
OEMs retain specification authority. Tier-1 Suppliers represent the steepest expansion trajectory as outsourcing pressure intensifies.
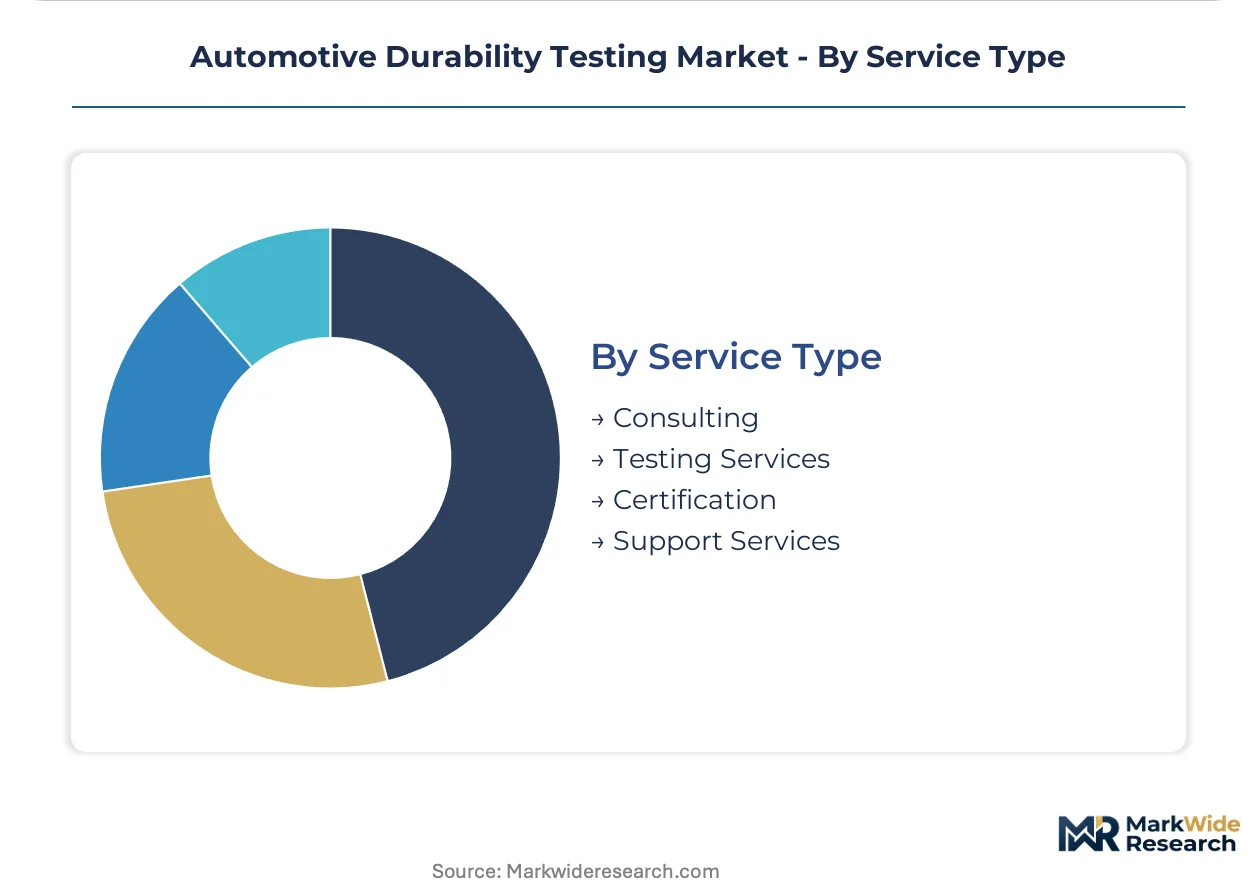
Service Type:
Margin structure varies sharply between asset-heavy testing execution and knowledge-based consulting delivery.
- Testing Services:Laboratory execution of prescribed protocols generates recurring revenue tied to program volumes. Subscription-based equipment access is displacing capital purchases among California and Bavaria EV startups. Chamber manufacturing bottlenecks constrain expansion timing.
- Certification:Third-party accreditation for regulatory submission commands premium pricing with high barriers to entry. CSRD lifecycle reporting obligations extend scope to embodied energy verification. EU Green Deal compliance creates new service categories.
- Consulting:Test program design and failure analysis expertise addresses multiphysics simulation competency gaps.
- Support Services:Equipment maintenance, calibration, and protocol training sustain long-term customer relationships.
Testing Services dominate transaction volume. Certification is gaining share fastest as regulatory complexity outpaces in-house capability development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools and specialized technician concentrations anchor regional durability testing capacity across major automotive manufacturing clusters. Germany, China, and the United States concentrate the bulk of new test facility investment as electric vehicle platforms proliferate.
United States
EPA emission certification requirements and NHTSA crashworthiness standards mandate comprehensive validation protocols for domestic OEMs. Heavy-duty vehicle manufacturers face extended dynamometer cycles for diesel aftertreatment system verification. Michigan and California test corridors absorb the majority of new chassis dynamometer installations serving Detroit Three and Silicon Valley EV entrants.
Germany
KBA type approval enforcement and Euro 7 emission standards force rigorous powertrain-chassis integrated test sequences. WLTP protocol harmonization drives chassis dynamometer utilization at unprecedented levels. Bavaria and Baden-Württemberg host concentrated environmental chamber manufacturing capacity facing 18-24 month order backlogs.
China
MIIT new energy vehicle certification and dual carbon goals accelerate battery-electric validation program expansion. Domestic OEMs and joint ventures operate the world's largest captive durability laboratory networks. Yangtze River Delta and Pearl River Delta clusters concentrate new climate chamber investments serving localized EV supply chains.
India
PLI scheme production-linked incentives for automotive and advanced chemistry cell manufacturing attract test facility investment. BIS standards compliance and expanding domestic EV production create validation capacity gaps. Maharashtra and Tamil Nadu industrial corridors host emerging third-party testing infrastructure serving localized Tier-1 suppliers.
Japan
METI technology roadmaps and JIS standards sustain precision-focused durability testing demand for hybrid powertrain architectures. Domestic OEMs maintain vertically integrated validation programs with limited outsourcing penetration. Aichi Prefecture and Kanto region concentrate servo-hydraulic simulation equipment manufacturing serving regional automotive customers.
Automotive Durability Testing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented service tiers. Third-party testing providers capture outsourced overflow from capacity-constrained OEM captive programs. Strategic archetypes include global laboratory network operators, powertrain test system specialists, and structural dynamics platform manufacturers. Capacity expansion and strategic partnerships dominate competitive moves as regulatory complexity outpaces in-house capability development.
Within the diversified network operator tier, SGS leverages its global laboratory footprint to serve consolidated validation programs across multiple continents. HORIBA anchors the powertrain specialization vector through deep expertise in hybrid and electric drivetrain durability cycles. MTS Systems occupies a position at the structural dynamics end with servo-hydraulic and electromechanical simulation platform control.
| Leading Market Players |
|---|
| Intertek |
| Kistler |
| SGS |
| MTS Systems |
| Millbrook |
| TÜV SÜD |
| HORIBA |
| Applus+ |
| Element Materials Technology |
| Others |
Pricing and Supply Chain Analysis
EV startup concentration in California and Bavaria is compressing pricing models toward subscription-based equipment access rather than capital purchase structures. This buyer archetype shift concentrates negotiation leverage with third-party testing providers offering flexible utilization terms.
Pricing Analysis
Bundled certification-plus-testing packages command premiums over unbundled protocol execution, with Euro 7 compliance verification and CSRD lifecycle reporting driving tiered service differentiation. Price differentiation rests on accreditation tier and geographic proximity to OEM engineering centers. Pricing pressure intensifies among mid-volume EV entrants as lithium cost volatility compresses program budgets. Tier-1 suppliers exhibit highest price sensitivity due to redundant validation cycles across divergent OEM protocols, while captive OEM laboratories show lowest sensitivity given regulatory accountability requirements.
Supply Chain Analysis
Reverse logistics for climate chamber refurbishment and servo-hydraulic system remanufacturing extend equipment lifecycles and delay new capital procurement. Manufacturing concentrates in Germany and Japan for environmental simulation equipment, with China expanding domestic production capacity. Critical component dependencies include precision sensors, wide-bandgap semiconductors for inverter testing, and specialized hydraulic actuators. Single-source vulnerability concentrates in German chamber manufacturers facing extended order backlogs. Distribution runs through direct OEM relationships for large installations and regional distributor networks for aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Euro 7 emission standards and WLTP protocol harmonization continuously expand mandatory test cycle volumes. Compliance milestones generate durable demand expansion independent of vehicle production cyclicality.
For Market Incumbents: To counter digital twin substitution threats, deepen software-hardware integration capabilities and expand climate chamber manufacturing partnerships in India to bypass German-Japanese supply bottlenecks. Prioritize CSRD lifecycle reporting certification investments to capture emerging embodied energy verification demand.
For New Entrants and Emerging Players: Series C-stage EV startups in California and Bavaria represent an underserved buyer archetype seeking subscription-based equipment access without capital deployment. Autonomous vehicle sensor validation protocols offer penetrable white space with limited standardization. Pursue cloud-based simulation platform partnerships to establish credibility before physical laboratory investment.
For Investors and Strategic Acquirers: Tier-1 automotive suppliers are the most active acquirer in this space, seeking to internalize validation capabilities and reduce outsourced testing dependency. Long-term viability favors asset-light simulation software providers over capital-intensive laboratory operators. Monitor WLTP protocol adoption rates in emerging markets as inflection indicators for regional capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | SGS and HORIBA compress development timelines by coupling virtual predictions with physical validation protocols. |
| Climate Chamber Manufacturing Partnership | MTS Systems addresses 18-24 month order backlogs through localized production agreements in India and China. |
| CSRD Certification Investment | Intertek and TÜV SÜD capture premium pricing for EU Green Deal compliance verification services. |
| Subscription Equipment Access Model | Millbrook targets California EV startups with leased servo-hydraulic rigs replacing capital purchases. |
| Autonomous Sensor Validation Development | Applus+ and Element Materials Technology establish protocol standards for LiDAR thermal shock testing. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, environmental chamber manufacturers, and third-party testing laboratory directors grounded qualitative insights. Secondary validation drew from EPA emission certification databases, KBA type approval records, MIIT new energy vehicle filings, and IHS Markit vehicle production data. Bottom-up test facility capacity modeling and top-down regulatory mandate analysis were triangulated to ensure consistency.
Bottom-up segmentation by testing type, component category, and end-user archetype anchored volume projections across the analysis window. The analytical framework modeled propulsion architecture transitions, regional regulatory adoption curves, and digital twin penetration rates as primary demand drivers. CAGRs were derived from facility utilization trends and capital expenditure patterns rather than extrapolated historical growth.
Underlying measurement precision varies by segment; virtual simulations and certification services carry tighter precision than physical testing execution due to software revenue transparency. Forecasts reflect assumptions about Euro 7 implementation timing and WLTP jurisdictional expansion. Practitioners should monitor silicon carbide inverter adoption rates and battery-electric platform launch schedules for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Global Track Geometry Measurement System (TGMS) Market
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Automotive Driving Simulators Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Dynamometer Market