
 Automotive on-Board Diagnostics Market | 2026-2036
Automotive on-Board Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive on-Board Diagnostics Market Analysis
ISO 26262-grade diagnostic reliability is rotating toward the center of procurement decisions for fleet-grade OBD platforms. Robert Bosch GmbH leverages its captive semiconductor fabrication to anchor supply security for ECU-integrated diagnostic modules. Continental AG sustains engineering intensity across Ethernet backbone architectures for next-generation vehicle networks. Denso Corporation dominates thermal and powertrain sensor integration within Japanese OEM supply chains.
Automotive on-Board Diagnostics comprises embedded electronic systems that monitor powertrain, emissions, and chassis subsystems via standardized data ports, typically operating through 16-pin OBD-II connectors transmitting fault codes over Controller Area Network protocols at baud rates up to 500 kbit/s. The primary purpose is real-time vehicle health assessment enabling predictive maintenance and regulatory compliance verification. Diagnostic Scanners and Software Solutions capture expanding margin pools as wireless and Bluetooth-enabled platforms displace tethered hardware among aftermarket providers. CAN Bus technology retains volume leadership in legacy fleet retrofits while Ethernet architectures claim share in electric vehicle platforms requiring higher bandwidth for battery management telemetry.
EPA emission enforcement and CARB OBD-II mandates in the United States, alongside EU Green Deal decarbonization frameworks and China MIIT new energy vehicle data reporting standards, collectively tighten product certification requirements and force continuous firmware update cycles. NHTSA cybersecurity guidance for connected vehicles adds a compliance layer that shapes supplier qualification criteria. Stakeholders must weigh backward integration into diagnostic software stacks against partnership models with cloud analytics platforms as vehicle data monetization architectures mature.
Market Dynamics
Fleet electrification is compressing diagnostic refresh cycles as battery management systems demand real-time telemetry bandwidth that legacy CAN Bus architectures cannot provision. This structural pressure is fragmenting supplier tiers between legacy retrofit specialists and Ethernet-native platform developers.
Growth Catalysts
- EPA emission enforcement:Heavy-duty diesel fleet operators in the United States face mandatory OBD-II compliance audits that accelerate hardware replacement schedules.
- China MIIT data standards:New energy vehicle manufacturers must transmit battery health telemetry to centralized monitoring platforms, creating captive demand for integrated diagnostic modules.
- Fleet telematics convergence:Commercial vehicle operators are consolidating diagnostic data streams with route optimization and driver behavior analytics into unified cloud architectures.
Market Restraints
- Semiconductor supply concentration:ECU-integrated diagnostic controllers depend on 40nm automotive-grade microcontroller supply from concentrated East Asian foundry capacity.
- Ethernet retrofit cost barriers:Legacy internal combustion fleet operators face prohibitive wiring harness replacement costs to enable DOIP diagnostic protocols.
- Cybersecurity certification friction:NHTSA guidance for connected vehicle data protection extends firmware validation timelines by 8-14 months for aftermarket scanner providers.
Strategic Opportunities
- India commercial vehicle penetration:BS-VI emission mandates have created a diagnostic hardware installation gap across 2.3 million unconnected medium and heavy trucks.
- Predictive maintenance unbundling:Independent service channels are separating diagnostic software subscriptions from hardware purchases, enabling recurring revenue models.
- ISO 26262 functional safety:ASIL-D certification requirements for autonomous vehicle diagnostic redundancy are creating premium tier positioning for fault-tolerant architectures.
Industry Challenges
- Embedded systems talent scarcity:Firmware engineering for real-time diagnostic kernels requires specialized automotive Ethernet stack expertise that outpaces vocational pipeline output.
- Multi-protocol integration complexity:Service bay equipment must simultaneously support CAN FD, LIN, FlexRay, and Automotive Ethernet without technician reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive on-Board Diagnostics Market |
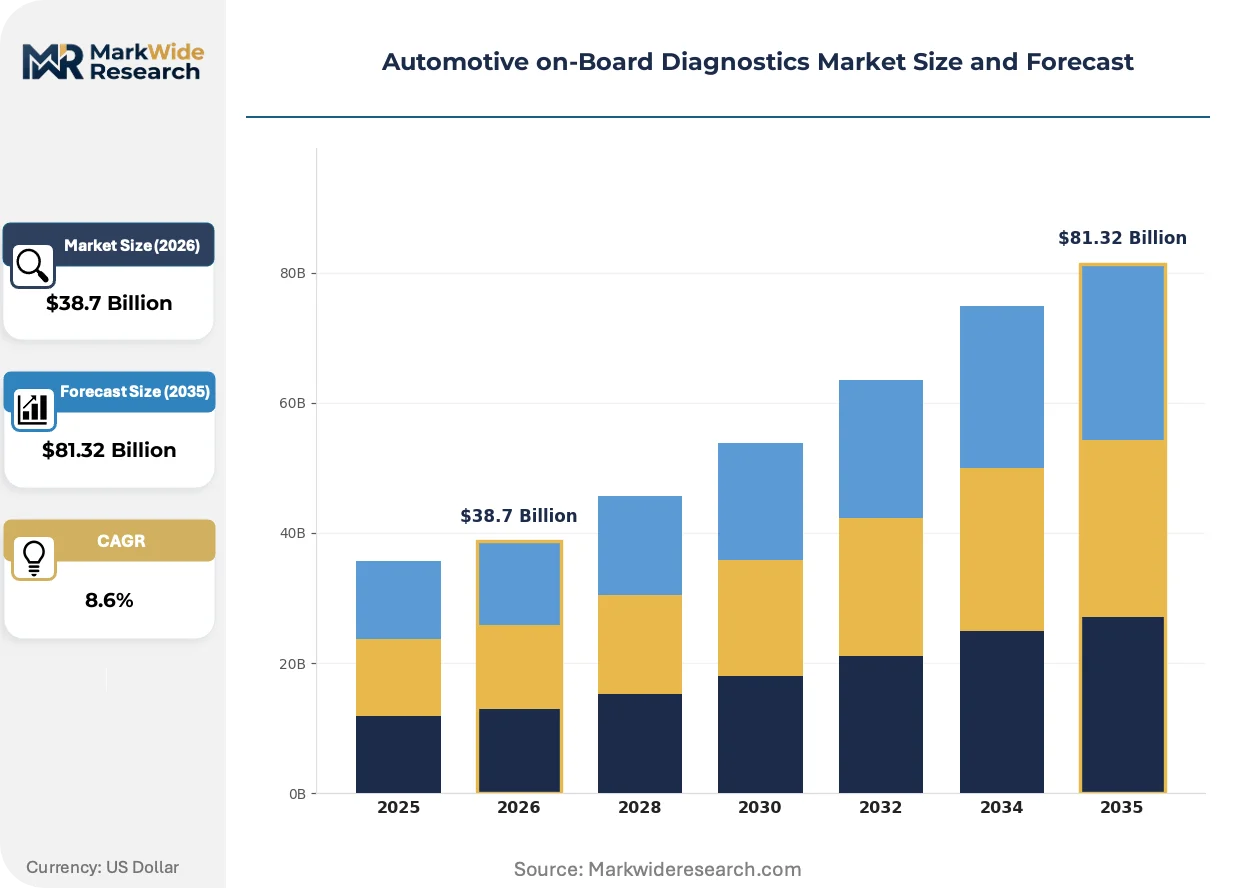
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OBD-II Devices, Diagnostic Scanners, Software Solutions, Data Loggers Technology: Wireless Diagnostics, Bluetooth Connectivity, CAN Bus, Ethernet Application: Vehicle Monitoring, Emission Testing, Fleet Management, Maintenance End User: Automotive Repair Shops, Fleet Operators, OEMs, Aftermarket Providers |
| Companies Covered | Robert Bosch GmbH, Continental AG, Delphi Technologies, Snap-on Incorporated, Denso Corporation, Autel Intelligent Technology, Launch Tech, Softing AG, Vector Informatik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive on-Board Diagnostics Market Emerging Trajectories
Diagnostic hardware form factors are collapsing toward smartphone-integrated interfaces while cloud analytics layers absorb computational workloads previously executed locally. This architectural redistribution is compressing traditional scanner OEM margins and elevating software monetization priority.
Wireless diagnostic dongles are miniaturizing toward credit-card footprints while retaining full OBD-II pin compatibility and multi-protocol translation capability. Fleet maintenance providers are adopting these devices for driver-initiated pre-trip inspections without bay occupancy. The physical footprint compression is miniaturizing the addressable market for benchtop diagnostic equipment and expanding mobile-first service model viability.
EU Green Deal decarbonization frameworks are mandating standardized battery state-of-health reporting for end-of-life electric vehicle processing. This creates interoperable data format obligations that span OEM captive systems and independent aftermarket platforms. European recycling consortiums are now the primary demand channel for unified diagnostic data exporters.
Commercial fleet procurement departments are consolidating diagnostic service contracts under total cost of ownership frameworks rather than capital expenditure approvals. Leasing companies and mobility-as-a-service operators are the buyer segments most aggressively unbundling hardware from analytics subscriptions. Germany and the Netherlands exhibit the most advanced procurement model transition, with fleet management companies capturing diagnostic decision authority from maintenance shops.
Automotive on-Board Diagnostics Market Segmentation
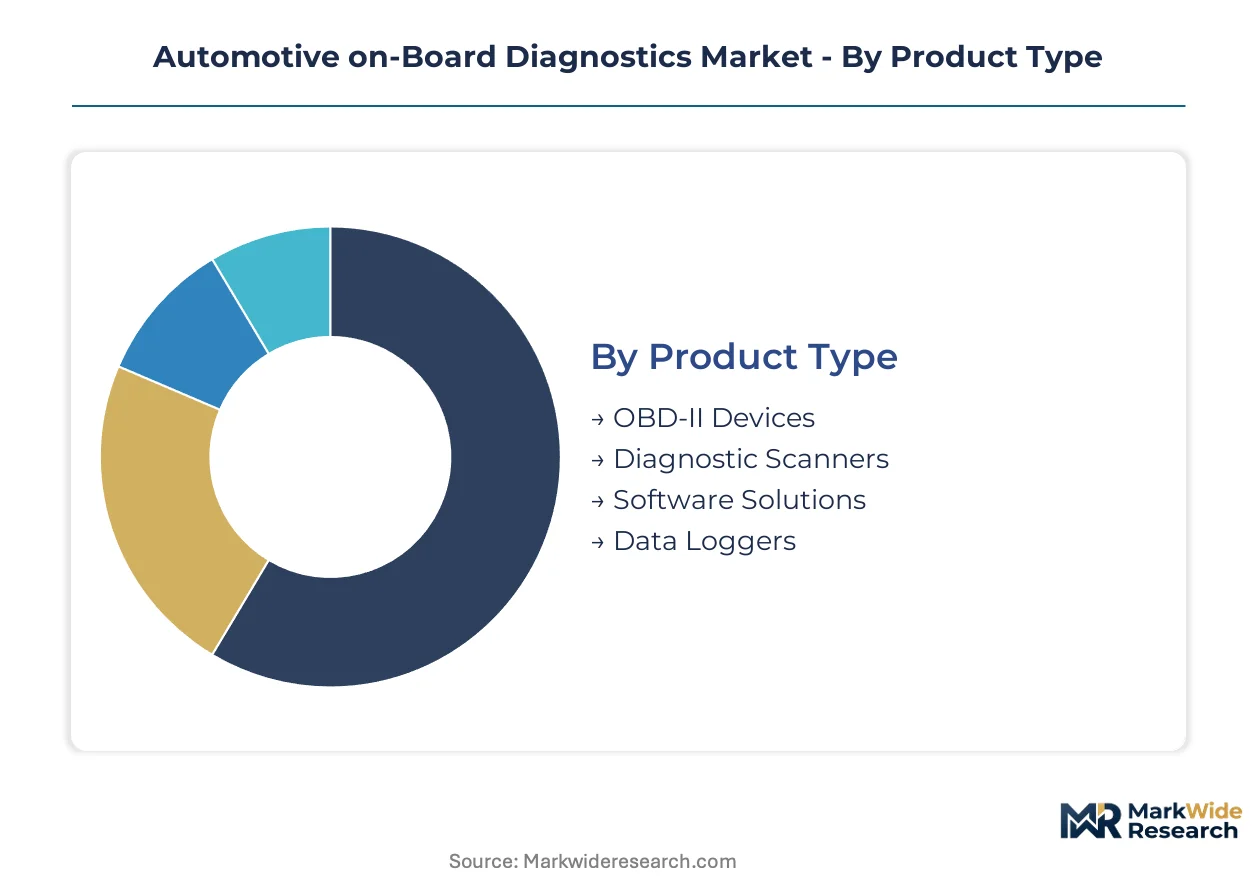
Product architecture and connectivity standards fragment the Automotive on-Board Diagnostics market into distinct margin pools. Procurement patterns diverge sharply between fleet operators prioritizing recurring software revenue and repair shops optimizing capital expenditure on hardware.
Product Type:
Software Solutions command expanding margin pools as subscription models displace perpetual licenses across fleet procurement departments.
- Diagnostic Scanners:Handheld and tablet-based hardware units execute fault code retrieval and live data streaming through 16-pin OBD-II interfaces. Fleet operators in Germany and the Netherlands consolidate scanner procurement under total cost of ownership frameworks rather than capital expenditure approvals.
- Software Solutions:Cloud-native platforms aggregate multi-vehicle telemetry into predictive maintenance algorithms and compliance dashboards. Leasing companies and mobility-as-a-service operators aggressively unbundle analytics subscriptions from hardware purchases.
- OBD-II Devices:Compact dongles providing standardized vehicle interface for aftermarket connectivity.
- Data Loggers:Continuous recording systems capturing extended drive-cycle parameters for emissions certification.
Diagnostic Scanners hold installed capacity. Software Solutions is rotating up the share rankings.
Technology:
Bandwidth requirements from battery management telemetry are accelerating Ethernet adoption while CAN Bus retains retrofit volume leadership.
- Ethernet:Automotive-grade twisted-pair architectures deliver diagnostic data rates exceeding 100 Mbit/s for electric vehicle battery management and autonomous sensor fusion. China MIIT new energy vehicle data reporting standards mandate real-time telemetry bandwidth that legacy protocols cannot provision.
- Wireless Diagnostics:Cellular and Wi-Fi-enabled platforms eliminate physical bay occupancy for fleet pre-trip inspections. EPA emission enforcement audits for heavy-duty diesel fleets accelerate replacement of tethered diagnostic equipment.
- Bluetooth Connectivity:Short-range wireless bridging between OBD-II ports and technician smartphones or tablets.
- CAN Bus:Legacy controller area network protocol dominating internal combustion vehicle fleets and aftermarket retrofit installations.
CAN Bus retains volume dominance. Ethernet is climbing the fastest among connectivity standards.
Application:
Fleet management applications concentrate recurring revenue potential as telematics convergence unifies diagnostic data with route optimization analytics.
- Fleet Management:Integrated platforms combining vehicle health monitoring with driver behavior analytics and regulatory compliance verification. Commercial vehicle operators in North America face mandatory OBD-II compliance audits that accelerate hardware refresh schedules.
- Emission Testing:Standardized drive-cycle verification for EPA, CARB, and EU Green Deal decarbonization frameworks. European recycling consortiums now drive demand for unified battery state-of-health data exporters.
- Vehicle Monitoring:Continuous powertrain and chassis subsystem surveillance for warranty validation and predictive maintenance triggering.
- Maintenance:Service bay execution of fault isolation, component replacement verification, and repair documentation.
Emission Testing holds regulatory-mandated installed base. Fleet Management is gaining share fastest through subscription monetization.
End User:
Fleet Operators capture decision authority as procurement centralizes under leasing companies and mobility-as-a-service platforms.
- Fleet Operators:Commercial vehicle and passenger car fleet managers consolidating diagnostic service contracts under unified telematics architectures. India BS-VI emission mandates have created a diagnostic hardware installation gap across unconnected medium and heavy trucks.
- Automotive Repair Shops:Independent and dealership-affiliated service bays requiring multi-protocol support for heterogeneous vehicle populations. NHTSA cybersecurity guidance extends firmware validation timelines for aftermarket scanner providers.
- OEMs:Vehicle manufacturers integrating diagnostic modules into original ECU architectures for warranty and remote diagnostics.
- Aftermarket Providers:Independent distributors and service chains supplying retrofit diagnostic equipment and software.
Automotive Repair Shops hold fragmented installed capacity. Fleet Operators is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic module fabrication concentrates in German and Chinese industrial corridors, with tier-1 suppliers anchoring ECU-integrated production near OEM assembly plants. Taiwan and South Korea supply concentrated automotive-grade microcontroller foundry capacity. Japan retains sensor integration dominance for powertrain telemetry.
United States
Heavy-duty diesel fleet operators drive hardware replacement cycles under EPA emission enforcement audits and CARB OBD-II mandates. NHTSA cybersecurity guidance extends firmware validation timelines for aftermarket scanner providers. Michigan and Ohio host concentrated OEM diagnostic module engineering centers serving domestic truck manufacturers.
Germany
OEM integration of CAN Bus and Ethernet-based OBD systems accelerates as EU Green Deal decarbonization frameworks tighten certification requirements. KBA type-approval protocols enforce ISO 26262-grade diagnostic reliability standards. Stuttgart and Munich anchor captive semiconductor fabrication for ECU-integrated diagnostic modules.
China
New energy vehicle manufacturers transmit battery health telemetry to centralized monitoring platforms under MIIT data reporting standards. Real-time bandwidth demands fragment supplier tiers between legacy retrofit specialists and Ethernet-native developers. Shanghai and Shenzhen concentrate diagnostic software engineering for domestic EV platforms.
Japan
Denso Corporation dominates thermal and powertrain sensor integration within domestic OEM supply chains. METI industrial standards shape functional safety certification requirements for autonomous vehicle diagnostic redundancy. Nagoya and Tokyo metropolitan areas concentrate firmware engineering for real-time diagnostic kernels.
India
BS-VI emission mandates have created a diagnostic hardware installation gap across 2.3 million unconnected medium and heavy trucks. The country's national automotive regulator enforces phased compliance deadlines for commercial vehicle telematics. Maharashtra and Gujarat host emerging fleet management platform development centers serving domestic logistics operators.
Automotive on-Board Diagnostics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with tier-1 suppliers commanding premium positioning through captive semiconductor supply while aftermarket specialists compete on hardware accessibility. The market structure consolidates around integrated module suppliers serving OEMs and fragmented scanner providers addressing independent repair channels. Two dominant strategic archetypes emerge: ECU-integrated system architects and wireless-enabled aftermarket platform developers. M&A activity concentrates on diagnostic software stack acquisitions, while capacity expansion focuses on automotive-grade Ethernet controller foundry investments.
Within the tier-1 integrated module tier, Robert Bosch GmbH and Continental AG exemplify supply-secured positioning through captive fabrication assets. Denso Corporation anchors the Japanese OEM supply chain archetype with sensor-integrated diagnostic architectures. Among aftermarket specialists, Autel Intelligent Technology and Launch Tech occupy positions on the hardware accessibility vector, with Snap-on Incorporated representing the established North American service equipment channel. These five named entities collectively span the supplier spectrum from semiconductor-anchored OEM integration to mobile-first aftermarket penetration.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Delphi Technologies |
| Snap-on Incorporated |
| Denso Corporation |
| Autel Intelligent Technology |
| Launch Tech |
| Softing AG |
| Vector Informatik |
| Others |
Supply Flow & Price Mechanics
Ethernet-native diagnostic controllers displacing CAN Bus retrofit modules simultaneously concentrate procurement authority in German and Chinese OEM engineering centers and compress margin pools for legacy hardware specialists. This substitution dynamic redraws supply geography toward automotive-grade foundry corridors while pricing power accumulates with subscription-software platforms unbundled from capital equipment.
Pricing Analysis
EPA emission enforcement and CARB OBD-II mandates dictate the pricing tier structure across the North American aftermarket. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262 ASIL-D certified modules from commercial-grade scanners and unbranded import hardware. Cost compression in the economy tier is intensifying because semiconductor supply concentration limits controller availability for price-sensitive retrofit providers. Fleet operators exhibit the least price sensitivity due to total cost of ownership procurement frameworks, while independent repair shops face acute budget constraints for multi-protocol bay equipment.
Supply Chain Analysis
Port congestion on transpacific trade lanes from Shanghai and Shenzhen to Long Beach and Rotterdam elevates inbound logistics costs for diagnostic dongle assemblers sourcing from East Asian contract manufacturers. Taiwan, South Korea, and China anchor automotive-grade microcontroller supply for ECU-integrated modules. Raw material dependencies center on 40nm automotive silicon wafers, copper alloy OBD-II connector housings, and flame-retardant wiring harness compounds. Single-source vulnerability concentrates in Taiwan foundry capacity for Ethernet PHY controllers. Distribution runs through tier-1 supplier direct OEM channels and fragmented aftermarket distributor networks serving independent service bays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a platform-economics inflection where battery telemetry interoperability standards create winner-take-most dynamics for cloud-native diagnostic aggregators. EU Green Deal battery state-of-health reporting mandates and China MIIT data standardization collectively force architectural convergence around unified data exporters.
For Market Incumbents: Secure captive semiconductor supply through foundry partnerships or backward integration into automotive-grade controller fabrication. Anchor OEM relationships with Ethernet-native platform engineering ahead of legacy CAN Bus obsolescence. Threat substitution from wireless dongle miniaturization demands firmware stack differentiation to preserve scanner attach rates. For New Entrants and Emerging Players: Differentiate on predictive maintenance algorithm accuracy for fleet telematics convergence. Target India's 2.3 million unconnected medium and heavy trucks under BS-VI emission mandates as the most penetrable geography. Pursue driver-initiated pre-trip inspection service models bypassing traditional bay occupancy economics. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors software-stack acquisition targets over hardware-centric assets. Long-term viability hinges on recurring revenue attachment rates exceeding 60% across fleet operator contracts. Watch for Ethernet controller foundry capacity expansion announcements as the inflection signal for supply security premiums dissipating.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | EU Green Deal battery telemetry mandates force interoperable data format adoption across OEM captive and aftermarket systems. |
| Software-Defined Vehicle Investment | OEM engineering centers in Stuttgart and Shanghai prioritize over-the-air diagnostic firmware update architectures. |
| Geographic Manufacturing Footprint | India BS-VI compliance deadlines attract diagnostic hardware assembly capacity to Maharashtra and Gujarat industrial corridors. |
| Strategic Partnership | Fleet management companies in Germany and the Netherlands consolidate diagnostic contracts under unified telematics vendors. |
| Acquisition of Specialist Firm | Cloud analytics platform providers acquire predictive maintenance algorithm developers to deepen subscription value propositions. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-1 supplier procurement directors, aftermarket distributor operations heads, and fleet telematics managers converged on the working assumptions shaping this analysis. Primary interview intelligence combined with secondary validation from EPA enforcement action records, China MIIT new energy vehicle data reporting filings, EU Green Deal regulatory texts, and vehicle production registration databases. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Segmentation dimensions modeled span product architecture, connectivity protocol, vehicle propulsion type, and procurement authority concentration. CAGRs derived from installed base replacement cycles, regulatory compliance deadline clustering, and technology substitution elasticity coefficients. Forecast inputs incorporated battery management system telemetry bandwidth requirements and semiconductor supply lead time volatility.
Material uncertainties — semiconductor foundry capacity allocation shifts, cybersecurity certification timeline extensions, and emission mandate enforcement intensity variations — sit outside the modeled envelope. Forecasts reflect documented assumptions about protocol transition velocities and fleet electrification penetration curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Railway Maintenance Machinery Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
Vehicle Scanner Market