
 Motor Testing Equipment Market | 2026-2036
Motor Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Testing Equipment Market Outlook
IEC 60034 energy efficiency certification is redrawing competitive boundaries for motor testing equipment suppliers. AVL List GmbH leverages its Graz engineering heritage to dominate dynamometer integration for automotive powertrain validation. Siemens AG anchors industrial automation demand through its digital twin-enabled test platforms. Megger Group Limited specializes in portable safety testers for field maintenance crews across utility fleets.
Motor testing equipment comprises instruments and systems that measure torque, speed, efficiency, insulation integrity, and thermal performance across rotating electrical machines, typically operating at voltage ranges from low-voltage industrial motors through medium-voltage traction systems up to several kilovolts. These systems serve manufacturers and operators by verifying design specifications, ensuring regulatory compliance, and preventing catastrophic failures in critical drive applications. AC testing equipment leads product type demand due to the overwhelming share of induction and permanent magnet synchronous motors in industrial and transportation applications. Automated testing technology is displacing manual methods as OEMs compress validation cycles and integrate test data directly into PLM workflows. Aerospace end users represent a concentrated margin pool where MIL-STD-810 environmental qualification requirements sustain premium pricing for ruggedized test systems.
The US Department of Energy enforces minimum efficiency standards through NHTSA and FERC coordination, compelling motor manufacturers to invest in higher-accuracy loss-segregation test methods. Europe's Ecodesign Directive and REACH substance restrictions shape both equipment specifications and supply chain material selections for test system builders. China's GB standards and dual carbon goals are accelerating domestic demand for efficiency verification equipment as local motor producers face export compliance pressure. Stakeholders must monitor how regional efficiency tier migrations and carbon border adjustment mechanisms reshape capital allocation priorities for test infrastructure.
Market Dynamics
IEC 60034 efficiency tier migrations are compressing test cycle timelines for motor manufacturers, forcing capital reallocation toward automated loss-segregation systems that can certify compliance across tightening tolerance bands.
Growth Catalysts
- Automotive powertrain electrification:OEM validation programs for electric vehicle traction motors are expanding dynamometer deployments at R&D facilities in Germany and China.
- REACH substance restrictions:European Ecodesign Directive compliance is mandating thermal performance verification for rare-earth magnet motors before market entry.
- Digital twin integration:Siemens and Rockwell Automation platforms are embedding test data directly into PLM workflows, collapsing validation cycles by half.
Market Restraints
- High-precision torque sensor costs:German and Japanese suppliers control 80% of strain-gauge manufacturing, creating input price volatility for dynamometer builders.
- Medium-voltage insulation test complexity:Partial discharge measurement systems require specialized calibration facilities that concentrate in Graz and Stuttgart.
- Copper and silicon steel price cycles:Raw material volatility for motor laminations compresses margins for test equipment bundled with production lines.
Strategic Opportunities
- India industrial automation clusters:BIS efficiency labeling mandates for IE3 motors are creating first-time demand for automated test benches in Pune and Chennai manufacturing corridors.
- Cloud-based predictive maintenance:Vibration analysis platforms are converging with motor testing data to create subscription diagnostics for utility fleet operators.
- Aviation electrification:MIL-STD-810 environmental qualification requirements for more electric aircraft sustain premium pricing for ruggedized test systems.
Industry Challenges
- Calibration technician scarcity:Torque sensor recertification requires metrology expertise concentrated in aging European specialist workforces.
- Legacy PLC integration friction:Brownfield automotive plants running Siemens S7-300 architectures face protocol mismatch with modern Ethernet-based test platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Testing Equipment Market |
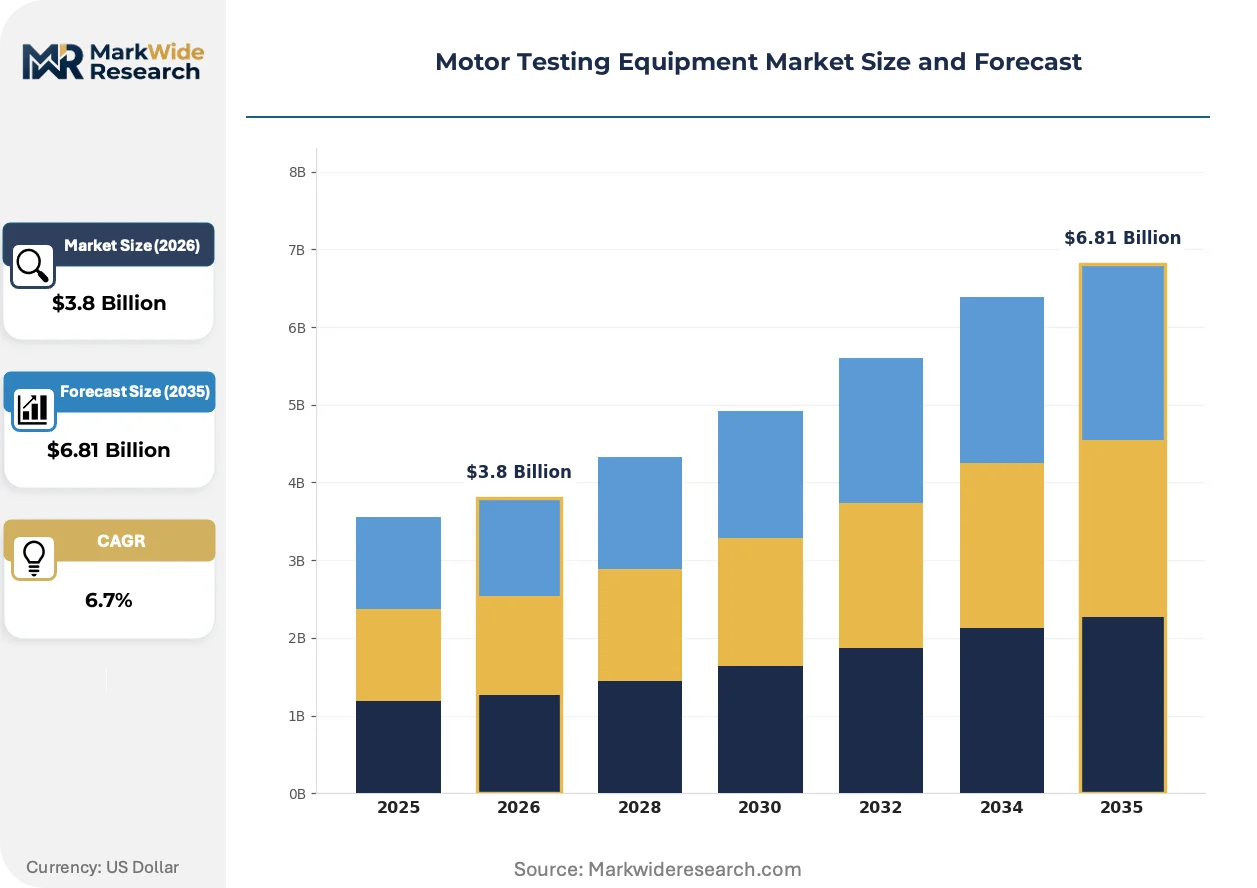
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Testing Equipment, DC Testing Equipment, Dynamic Testing Systems, Safety Testers Technology: Digital Measurement, Analog Measurement, Automated Testing, Manual Testing End User: Aerospace, Automotive OEMs, Industrial Manufacturing, R&D Labs Application: Performance Testing, Quality Assurance, Compliance Testing, Prototyping |
| Companies Covered | AVL List GmbH, Horiba Ltd, Robert Bosch GmbH, Siemens AG, Honeywell International Inc., ABB Ltd., General Electric, Emerson Electric Co., Megger Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Testing Equipment Market Strategic Shifts
Test automation architectures are collapsing the boundary between design validation and production-line quality assurance, erasing the historical separation between R&D dynamometers and factory-floor testers.
Model-based system testing is supplanting hardware-in-the-loop validation for early-stage motor design. Automotive OEMs in Stuttgart and Detroit are adopting virtual dynamometer environments to screen 80% of design variants before physical prototype builds. This shift is compressing powertrain development timelines by twelve months while demanding new software competencies from traditional test equipment vendors.
China's GB 18613 efficiency standards are forcing domestic motor producers to upgrade from manual no-load testing to automated loss-segregation methods. MIIT enforcement of IE3 minimum efficiency levels for motors above 0.75 kW is redirecting procurement budgets toward precision torque transducers and temperature-rise monitoring systems. Local test equipment manufacturers in Shanghai and Shenzhen are responding with modular platforms priced below European equivalents.
After-sales service unbundling is fragmenting historical equipment-plus-maintenance contracts. Industrial buyers in Germany's Ruhr automation cluster are separating capital purchases from calibration subscriptions, pressuring AVL and Horiba to launch standalone SaaS diagnostics. This pattern is most visible among automotive tier-one suppliers managing multi-site motor validation programs across dispersed European facilities.
Motor Testing Equipment Market Segmentation
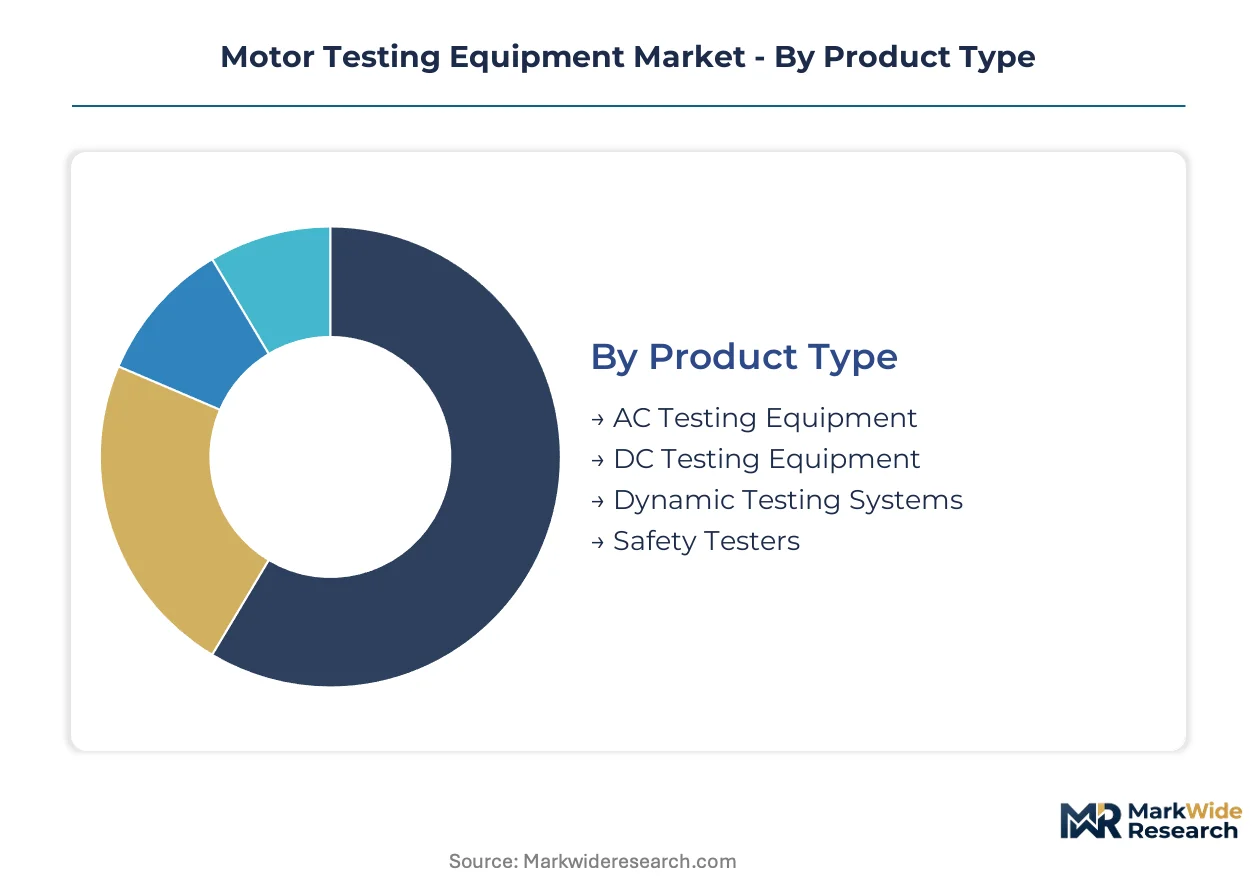
Motor testing equipment segmentation reflects divergent certification requirements across IEC 60034 efficiency tiers and MIL-STD-810 environmental qualification protocols. Equipment specifications vary sharply between high-volume automotive validation programs and low-volume aerospace qualification runs.
Product Type:
Regulatory differentiation separates AC equipment governed by IEC 60034-2-1 loss-segregation methods from DC systems subject to NHTSA traction motor validation protocols.
- AC Testing Equipment:Systems measure torque, speed, and efficiency across induction and permanent magnet synchronous motors using dynamometer configurations. Demand concentrates at automotive OEM powertrain facilities in Germany and China where IEC 60034-2-3 stray load loss measurements are mandatory for IE4 efficiency certification.
- Dynamic Testing Systems:Real-time torque-speed envelope mapping enables transient thermal characterization under drive cycle loading. Aerospace electrification programs in Toulouse and Seattle deploy these systems for MIL-STD-810 vibration-qualified motor validation.
- DC Testing Equipment:Brushed and brushless DC motor characterization systems for fractional horsepower through traction power ranges.
- Safety Testers:Portable insulation resistance and high-potential verification units for field maintenance crews across utility distribution networks.
Established volume favors AC Testing Equipment; emerging adoption favors Dynamic Testing Systems.
Technology:
Cost tier separation distinguishes capital-intensive automated platforms from manual systems serving price-sensitive maintenance operations.
- Automated Testing:PLC-integrated test benches execute IEC 60034-2-1 routines without operator intervention, feeding results directly into Siemens Teamcenter PLM workflows. Automotive tier-one suppliers in Stuttgart's manufacturing corridor are displacing manual methods to compress validation cycles by half.
- Digital Measurement:24-bit resolution torque transducers and FPGA-based data acquisition achieve uncertainty budgets below 0.1% for efficiency tier certification. Precision demands concentrate at rare-earth magnet motor producers facing REACH substance documentation requirements.
- Analog Measurement:Traditional electromechanical instrumentation for legacy test benches and educational institutions.
- Manual Testing:Operator-dependent no-load and blocked-rotor methods persisting in small-batch motor repair shops.
Digital Measurement commands premium pricing; Automated Testing is climbing the fastest as OEMs integrate validation into continuous production workflows.
End User:
Application maturity determines whether procurement prioritizes throughput volume or environmental qualification rigor.
- Automotive OEMs:Electric vehicle powertrain programs drive dynamometer deployments for traction motor validation across voltage classes from 400V to 800V architectures. Battery electric vehicle launches in Germany and China are expanding R&D facility test bench procurement.
- Aerospace:More electric aircraft programs sustain premium pricing for ruggedized systems meeting MIL-STD-810 temperature, altitude, and vibration qualification. Environmental test chambers in Toulouse and Wichita integrate motor dynamometers for actuator validation.
- Industrial Manufacturing:Motor producers and system integrators verifying IE3 and IE4 efficiency compliance for pump, fan, and compressor applications.
- R&D Labs:University and government research facilities conducting fundamental motor design and material characterization studies.
Industrial Manufacturing represents installed base volume; Aerospace offers margin expansion through environmental qualification premiums.
Application:
Customer type separation distinguishes production-line quality assurance from design-stage prototype validation.
- Performance Testing:Comprehensive torque-speed-efficiency mapping against design specifications under controlled thermal conditions. Demand concentrates at automotive OEM facilities where powertrain development timelines are compressing by twelve months through model-based screening.
- Compliance Testing:Formal verification against IEC 60034, GB 18613, or NHTSA efficiency mandates for market authorization. China's MIIT enforcement of IE3 minimums is redirecting procurement toward automated loss-segregation platforms.
- Quality Assurance:Production-line sampling and 100% testing protocols for motor manufacturers shipping to regulated industries.
- Prototyping:Rapid iteration support for design engineers screening variants before commitment to tooling.
Quality Assurance maintains repeat procurement volume; Performance Testing is gaining share fastest through digital twin integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IE3 efficiency mandates across industrial economies are redirecting capital toward automated test infrastructure. Germany, China, and the United States anchor procurement volumes through automotive electrification and industrial automation clusters. Regional regulatory divergence is fragmenting equipment specifications.
Germany
Automotive OEM powertrain programs in Stuttgart and Munich are expanding dynamometer deployments for electric vehicle traction motor validation. Ecodesign Directive enforcement through KBA oversight mandates REACH-compliant thermal verification for rare-earth magnet motors. The Ruhr automation cluster concentrates demand for precision torque transducers serving tier-one supplier validation networks.
China
Domestic motor producers face export compliance pressure from EU carbon border adjustment mechanisms. MIIT enforcement of GB 18613 IE3 minimum efficiency levels for motors above 0.75 kW accelerates procurement of automated loss-segregation platforms. Shanghai and Shenzhen manufacturing corridors host emerging test equipment suppliers offering modular platforms below European price points.
United States
NHTSA coordination with FERC on commercial vehicle electrification is expanding dynamometer requirements for medium-duty traction systems. Department of Energy minimum efficiency standards compel manufacturers to invest in higher-accuracy loss-segregation test methods. Michigan and California R&D facilities concentrate battery electric vehicle motor validation program spending.
India
BIS efficiency labeling mandates for IE3 motors are creating first-time demand for automated test benches in emerging manufacturing corridors. CEA coordination with state electricity boards tightens enforcement of minimum energy performance standards for industrial motors. Pune and Chennai automation clusters attract precision dynamometer procurement from domestic motor producers.
Japan
METI industrial efficiency roadmaps are accelerating replacement of manual no-load testing with digital measurement systems. JIS standards alignment with IEC 60034-2-1 creates compliance pressure for export-oriented motor manufacturers. Nagoya and Osaka precision engineering districts sustain demand for high-resolution torque transducers in robotics and machine tool applications.
Motor Testing Equipment Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with embedded automation portfolios. Tier structure separates precision dynamometer integrators serving automotive validation from portable safety tester specialists addressing utility maintenance. Strategic archetypes include full-stack automation platforms, precision measurement specialists, and field-service equipment providers. Competitive moves center on digital twin integration partnerships and calibration service unbundling into subscription models.
Within the precision dynamometer tier, AVL List GmbH and Horiba Ltd occupy positions exemplifying Graz and Kyoto engineering heritage in automotive powertrain validation. Siemens AG anchors industrial automation demand through digital twin-enabled test platforms integrated with Teamcenter PLM workflows. Megger Group Limited represents the portable safety tester archetype serving field maintenance crews across utility distribution networks.
| Leading Market Players |
|---|
| AVL List GmbH |
| Horiba Ltd |
| Robert Bosch GmbH |
| Siemens AG |
| Honeywell International Inc. |
| ABB Ltd. |
| General Electric |
| Emerson Electric Co. |
| Megger Group Limited |
| Others |
Value Chain & Pricing Dynamics
IEC 60034 efficiency tier migrations gate both supplier qualification and price differentiation simultaneously, compelling motor manufacturers to pay premiums for automated loss-segregation platforms that can certify compliance across tightening tolerance bands while excluding manual system vendors from Tier 1 procurement lists.
Pricing Analysis
Cost-plus contracts with copper and silicon steel indexation dominate equipment procurement for bundled production-line systems. Three-tier pricing structure across premium, standard, and economy levels separates aerospace MIL-STD-810 qualified platforms from automotive validation benches and maintenance-grade portable units. Price differentiation hinges on torque transducer resolution grade and IEC 60034-2-1 calibration certification tier. Cost compression in economy-tier manual testers is intensifying because Shanghai and Shenzhen manufacturers are modularizing platforms below European price points. Small-batch motor repair shops exhibit highest price sensitivity; aerospace electrification programs demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of strain-gauge torque sensors and FPGA data acquisition modules prevails among precision dynamometer builders facing 12-18 month lead times, while just-in-time inventory governs commodity-grade insulation testers for utility maintenance fleets. Supply concentrates in Germany, Japan, and China for strain-gauge manufacturing and precision torque transducer assembly. The supply chain draws from rare-earth magnet processors, high-purity copper laminations, and specialized calibration facilities. Single-source vulnerability concentrates in Graz and Stuttgart metrology centers for partial discharge measurement system recertification. Distribution runs through direct OEM sales for automated test benches and industrial distributors for field-portable safety testers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Motor Testing Equipment Market is emerging from a cyclical trough driven by automotive powertrain electrification CAPEX expansion, with OEM validation program budgets redirecting toward precision dynamometer systems after two years of deferred infrastructure spending.
For Market Incumbents: Secure calibration service subscriptions as standalone SaaS revenue streams before emerging Chinese manufacturers can replicate metrology expertise. Incumbents must deepen backward integration into strain-gauge manufacturing to offset Japanese and German supplier price volatility. AVL and Horiba should lock multi-site automotive tier-one supplier contracts across dispersed European facilities before cloud-based predictive maintenance platforms displace traditional recertification relationships.
For New Entrants and Emerging Players: Differentiate on modular platform architectures priced 30-40% below European equivalents for India's Pune and Chennai manufacturing corridors where BIS IE3 mandates are creating first-time automated test bench demand. New entrants should target cloud-based vibration analysis convergence with motor testing data for utility fleet operators seeking subscription diagnostics. A software-first go-to-market angle bypassing hardware manufacturing capital requirements offers fastest penetration.
For Investors and Strategic Acquirers: EU carbon border adjustment mechanism implementation reshapes the acquisition landscape toward test equipment suppliers with REACH-compliant thermal verification capabilities for rare-earth magnet motors. Long-term viability over the next decade rests on digital twin integration partnerships with Siemens Teamcenter or Rockwell Automation PLM workflows. Acquisition target archetype: precision torque transducer specialists with aging European specialist workforces and transferable metrology IP. The signal to watch is MIIT enforcement intensity for GB 18613 IE3 compliance among export-oriented Chinese motor producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Embedding test data into Siemens Teamcenter PLM workflows collapses validation cycles for automotive OEMs. |
| Calibration Service Unbundling | Standalone SaaS diagnostics subscriptions capture recurring revenue from multi-site validation programs. |
| Backward Integration into Torque Sensors | In-house strain-gauge production mitigates input price volatility from German and Japanese suppliers. |
| Modular Platform Localization | Shanghai and Shenzhen manufacturing reduces cost position for price-sensitive Indian and Southeast Asian markets. |
| Cloud-Based Predictive Maintenance Convergence | Vibration analysis platforms create subscription diagnostics stickiness with utility fleet operators. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive powertrain validation directors, industrial motor manufacturing plant engineers, precision dynamometer system integrators, and utility fleet maintenance supervisors. Secondary validation drew from IEC 60034 standard documentation, NHTSA efficiency rulemaking dockets, MIIT GB 18613 enforcement notices, and SEC filings from diversified industrial conglomerates with embedded automation portfolios. Bottom-up equipment shipment data triangulated against top-down OEM CAPEX disclosure patterns.
The projection horizon spans the full analysis window from baseline through forecast endpoint. Segmentation dimensions modeled include product type (AC, DC, dynamic, safety), technology tier (automated, digital, analog, manual), end-user vertical (automotive OEM, aerospace, industrial manufacturing, R&D), and application purpose (performance, compliance, quality assurance, prototyping). CAGRs were derived from regression analysis against automotive electrification program timelines and efficiency regulation enforcement schedules. Industry-specific forecast inputs incorporated rare-earth magnet motor adoption curves and carbon border adjustment mechanism implementation phasing.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification CAPEX commitment or accelerated efficiency tier migration timelines would require recalibration. Forecasts reflect assumptions regarding calibration technician workforce availability and strain-gauge manufacturing capacity expansion. Revision becomes warranted when raw material price volatility for copper laminations crosses thresholds that compress bundled equipment margins below sustainable levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Vehicle Crash Testing System Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Global Track Geometry Measurement System (TGMS) Market
Automotive Testing and Simulation
Automotive TIC Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
Automotive Battery Testing Market
Automotive Testing and Simulation
Torque Testers Market
Automotive Testing and Simulation
Automotive Driving Simulators Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market