
 Automotive Exhaust Analyzer Market | 2026-2036
Automotive Exhaust Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exhaust Analyzer Market Analysis
Certified reference-grade measurement capability is redrawing competitive boundaries in automotive exhaust analysis. HORIBA, Ltd. leverages its spectroscopic heritage to dominate high-precision regulatory compliance installations. Robert Bosch GmbH anchors the European aftermarket through dense service-station distribution and integrated diagnostic platforms. AVL List GmbH specializes in powertrain development systems, sustaining premium positioning among OEM research centers.
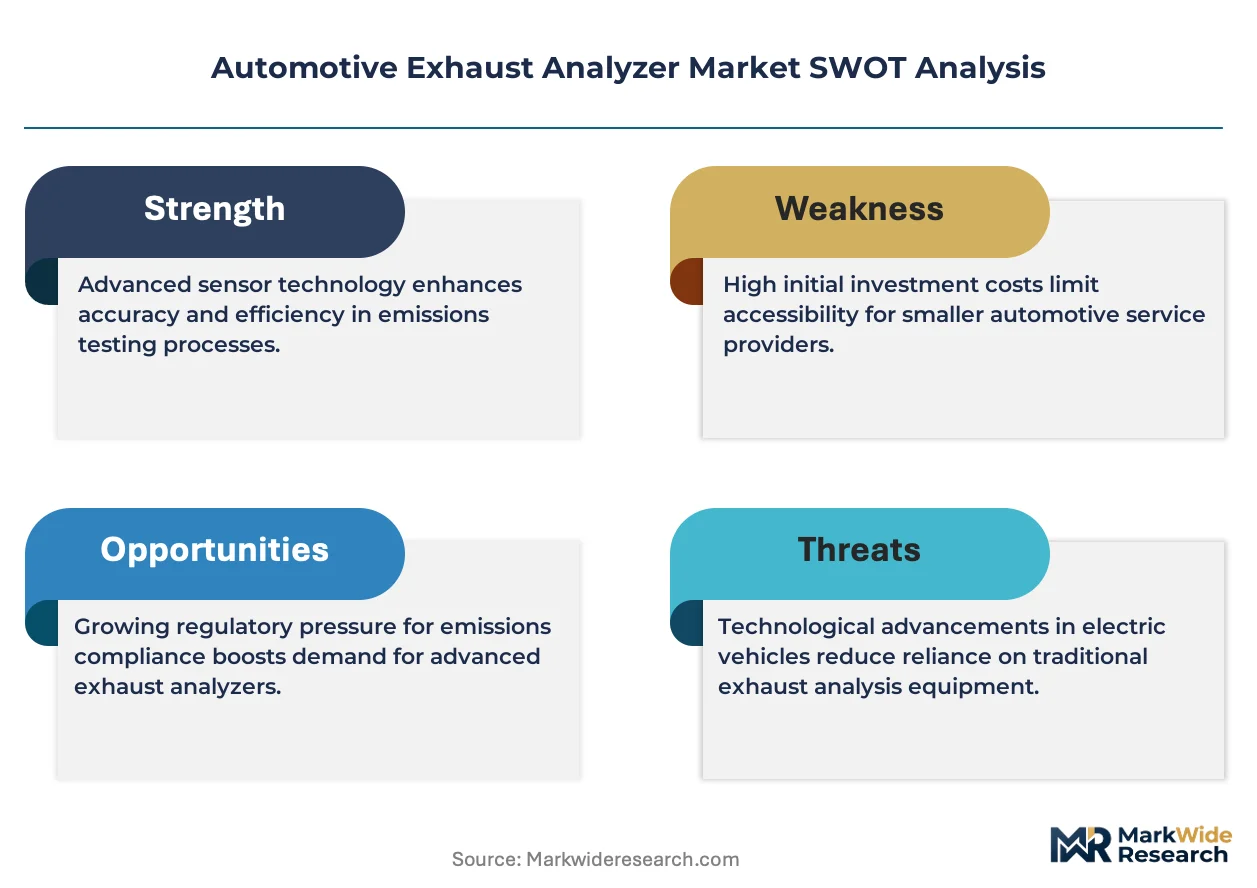
An automotive exhaust analyzer is a precision instrument that quantifies constituent gases—carbon monoxide, hydrocarbons, nitrogen oxides, carbon dioxide, and oxygen—within engine exhaust streams, typically achieving detection thresholds in parts-per-million using non-dispersive infrared or chemiluminescence detection principles; its primary purpose is to verify emissions compliance, diagnose combustion inefficiencies, and certify vehicles against environmental standards. Stationary analyzers command the largest installed base due to permanent inspection lane deployments, while portable analyzers represent the fastest-expanding category as mobile enforcement and remote fleet auditing gain traction. Infrared sensors occupy the dominant measurement technology position for CO and CO2 quantification, though electrochemical architectures persist in cost-sensitive service station tiers where margin pools remain thin.
The EPA tailpipe standards and California Air Resources Board protocols shape product specifications for any analyzer sold into US compliance channels, while the EU Green Deal and Euro 7 preparatory frameworks at EMA level are forcing manufacturers to expand detection ranges toward ultra-low NOx thresholds. Germany's KBA type-approval requirements and TÜV inspection cadence sustain replacement demand that outpaces Southern European markets. Stakeholders must monitor whether Euro 7 implementation accelerates analyzer refresh cycles or triggers consolidation among regional equipment suppliers unable to fund R&D for next-generation sensor platforms.
Market Dynamics
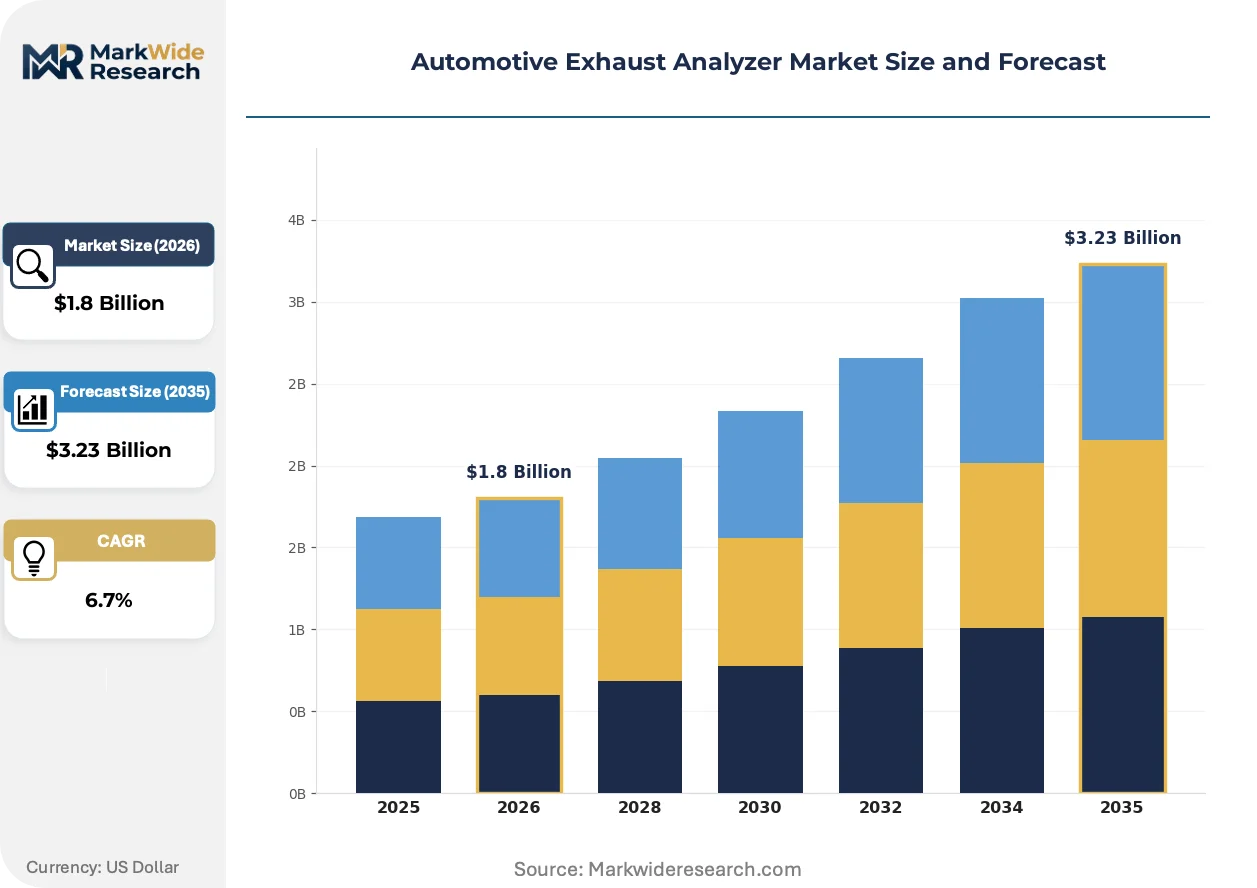
Analyzer procurement is accelerating as Euro 7 preparatory frameworks and EPA tailpipe standards force equipment refresh cycles across inspection networks and OEM validation labs. Fleet operators now face simultaneous pressure from enforcement agencies and corporate decarbonization targets.
Growth Catalysts
- EU Green Deal enforcement:Member states are expanding certified inspection lane capacity ahead of Euro 7 implementation, creating sustained replacement demand for multi-gas precision systems.
- Commercial fleet electrification auditing:Mixed-powertrain fleets require exhaust validation for remaining combustion assets, extending analyzer utilization into transitional vehicle pools.
- Remote diagnostics proliferation:Portable analyzer adoption is accelerating among mobile enforcement units conducting roadside emissions verification without fixed infrastructure.
Market Restraints
- Sensor platform R&D intensity:Electrochemical and infrared sensor development for ultra-low NOx thresholds demands capital commitments that strain regional equipment suppliers.
- Supply concentration in precision optics:Non-dispersive infrared source components depend on a limited supplier base concentrated in German and Japanese manufacturing clusters.
- REACH compliance friction:Substance restrictions on sensor materials and calibration gases complicate cross-border equipment certification and inventory management.
Strategic Opportunities
- India vehicle inspection expansion:The country's national automotive regulator is mandating centralized testing centers in tier-2 cities, opening procurement channels for certified analyzer systems.
- Blockchain-integrated certification:Immutable emissions record-keeping is converging with analyzer data streams, creating premium positioning for tamper-evident measurement platforms.
- Subscription-based calibration services:Equipment vendors are unbundling maintenance from hardware sales, capturing recurring revenue from inspection station operators.
Industry Challenges
- Metrology talent scarcity:Qualified technicians capable of traceable calibration against NIST or PTB reference standards are concentrated in aging workforce pools across developed markets.
- Legacy system integration complexity:New chemiluminescence detection modules must interface with decades-old inspection lane software architectures without disrupting throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exhaust Analyzer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Stationary Analyzers, Hybrid Analyzers, On-board Diagnostics Measurement Technology: Infrared Sensors, Electrochemical Sensors, Chemiluminescence, Mass Spectrometry End User: Service Stations, OEMs, Government Agencies, Environmental Testing Labs Application: Emission Testing, Engine Tuning, Research & Development, Regulatory Compliance |
| Companies Covered | Sensors, Inc., Fuji Electric, HORIBA, Ltd., Testo SE & Co. KGaA, MRU GmbH, AVL List GmbH, EOS S.r.l., Teledyne Technologies Incorporated, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exhaust Analyzer Market Emerging Trajectories
Measurement architectures are fragmenting as regulatory thresholds tighten and end-users demand operational flexibility beyond traditional fixed-lane deployments. Three distinct vectors are reshaping how exhaust quantification capabilities are packaged and consumed.
Chemiluminescence detection for nitrogen oxides is displacing electrochemical alternatives in inspection-grade installations. German TÜV stations and California Bureau of Automotive Repair facilities are completing platform transitions ahead of enforcement date certainty. The technology is displacing margin pools in cost-sensitive service tiers as certification requirements harden against lower-precision methods.
The EPA's phased NOx and particulate matter standards are compressing detection range requirements toward single-digit parts-per-million resolution. Equipment manufacturers must expand dynamic range without sacrificing cross-gas selectivity or calibration stability. Aftermarket garage operators in the US face the steepest adaptation curve as basic smoke meters lose regulatory recognition.
Outcome-based equipment utilization contracts are replacing outright purchase models among municipal inspection authorities. Brazilian state environmental agencies and South Korean district offices now specify measurement-certainty guarantees rather than hardware specifications. This procurement evolution is most visible in Latin America and East Asia, where capital constraints favor operational expenditure structures over upfront analyzer investment.
Automotive Exhaust Analyzer Market Segmentation
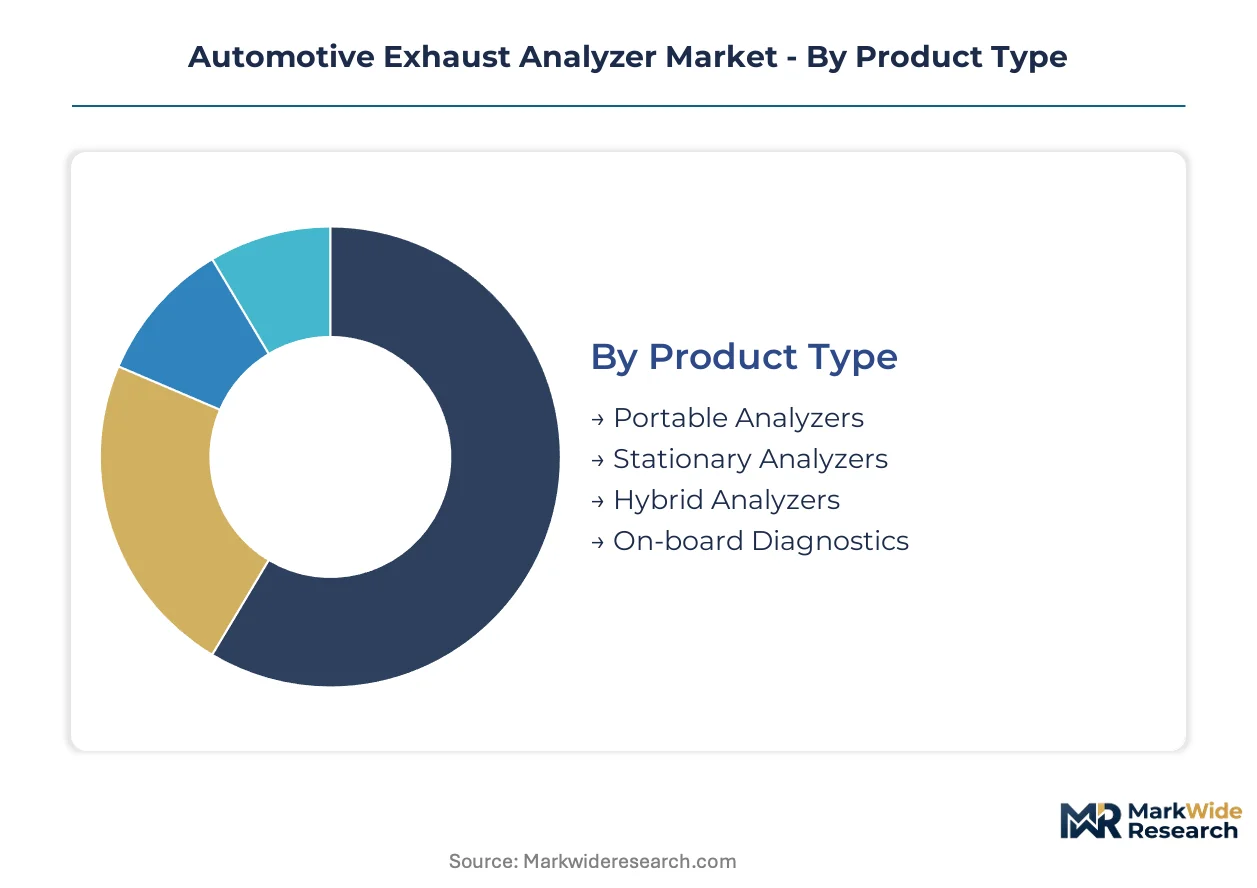
Exhaust analyzer procurement patterns diverge sharply across installation permanence, detection methodology, and compliance intensity. Equipment specifications must align with distinct regulatory recognition tiers and operational mobility requirements that separate fixed inspection infrastructure from field-deployable validation systems.
Product Type:
Stationary systems dominate domestic certification networks in Germany and Japan, while portable units capture cross-border enforcement contracts and fleet auditing mandates in Brazil and India.
- Portable Analyzers:Battery-powered units weighing under 15 kilograms enable roadside verification and remote fleet audits without fixed lane infrastructure. Indian state transport departments and Brazilian environmental agencies are expanding procurement for mobile enforcement units operating beyond urban testing centers.
- Stationary Analyzers:Permanent installations integrate multi-gas detection benches with automated vehicle positioning systems for high-throughput inspection lanes. German TÜV stations and California Bureau of Automotive Repair facilities anchor replacement demand as Euro 7 and EPA standards tighten detection thresholds.
- Hybrid Analyzers:Modular architectures allow field redeployment between fixed and mobile configurations.
- On-board Diagnostics:Embedded sensors provide continuous emissions monitoring during real-world driving cycles.
Stationary analyzers command the established base. The steepest expansion runs through portable analyzers.
Measurement Technology:
Cost tiers separate laboratory-grade precision from service-station affordability, with mid-range electrochemical platforms losing ground to chemiluminescence upgrades.
- Infrared Sensors:Non-dispersive infrared detection achieves parts-per-million resolution for carbon monoxide and carbon dioxide quantification. OEM validation labs in Japan and Germany specify these architectures for powertrain development cycles requiring cross-gas stability.
- Chemiluminescence:Nitric oxide-nitrogen dioxide reaction detection reaches single-digit parts-per-billion thresholds mandatory for ultra-low NOx certification. California and German regulatory channels are completing platform transitions ahead of enforcement deadlines.
- Electrochemical Sensors:Lower-cost amperometric cells persist in price-sensitive aftermarket tiers.
- Mass Spectrometry:Research-grade resolution supports detailed hydrocarbon speciation for advanced combustion studies.
Infrared sensors anchor current installed capacity. Chemiluminescence platforms are climbing the fastest as certification thresholds harden.
End User:
Volume concentration sits with government-mandated inspection networks, though margin capture favors environmental testing labs performing litigation-grade measurement.
- Government Agencies:Centralized testing authorities in India, Brazil, and South Korea specify certified equipment for statutory periodic inspection regimes. Procurement runs through centralized tenders with multi-year calibration service attachments.
- Environmental Testing Labs:Third-party validation facilities serve OEM homologation and regulatory dispute resolution with traceable metrology chains. German DEKRA and TÜV Rheinland operations sustain premium equipment specifications.
- Service Stations:Independent garages face steepest adaptation curves as basic smoke meters lose regulatory recognition.
- OEMs:Powertrain development centers require research-grade precision for pre-production validation.
Government agencies anchor procurement volume. Environmental testing labs are gaining share fastest on litigation-grade measurement demand.
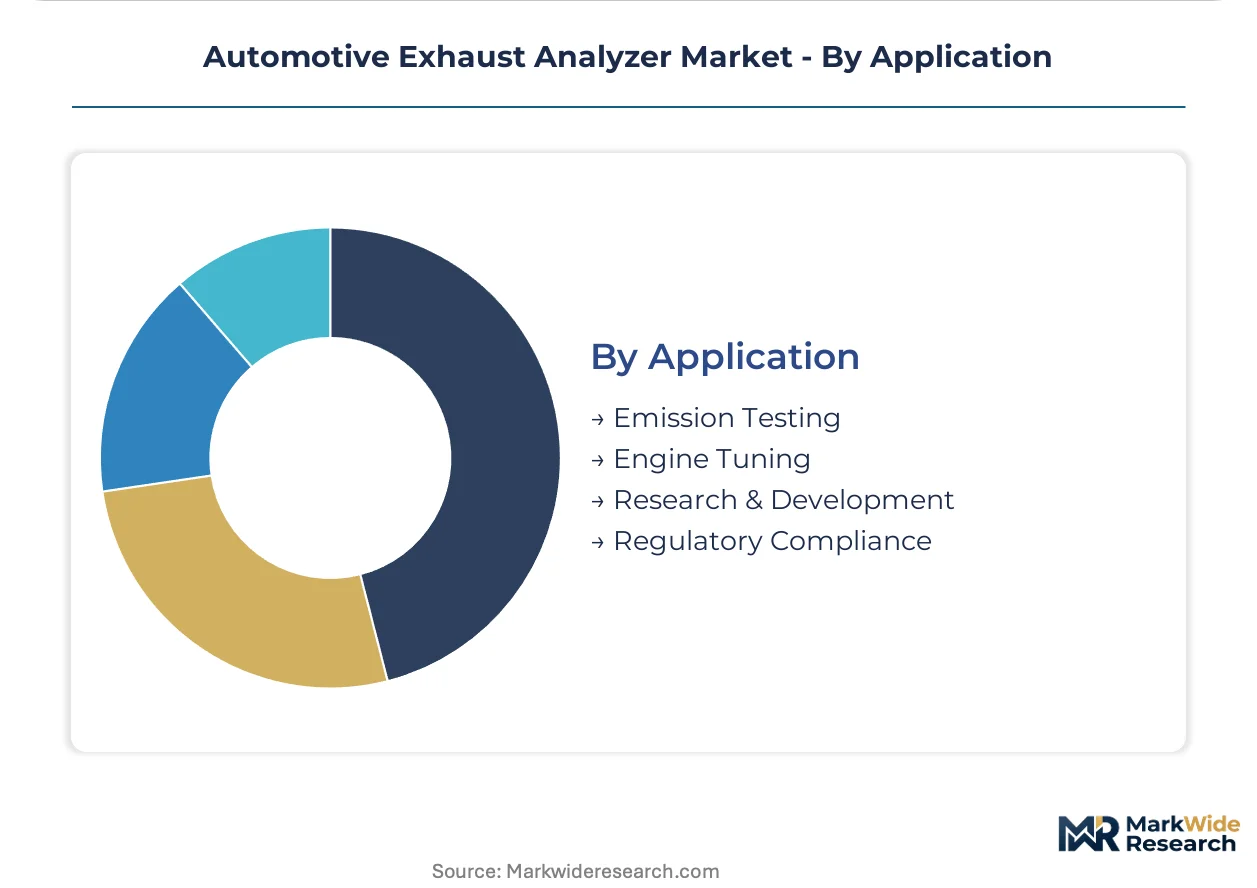
Application:
Maturity gradients separate established emission testing infrastructure from emerging research frontiers in alternative fuel combustion validation.
- Emission Testing:Periodic inspection and type-approval verification constitute the core installed base across all regulatory jurisdictions. Indian centralized testing centers and German TÜV lanes represent concentrated replacement demand.
- Research & Development:Advanced powertrain laboratories in Japan and Germany deploy multi-species analyzers for hydrogen combustion and synthetic fuel characterization. Equipment specifications exceed regulatory minimums by orders of magnitude.
- Engine Tuning:Aftermarket optimization shops require portable validation for performance modification verification.
- Regulatory Compliance:Documentation and certification workflows integrate analyzer data streams with blockchain-anchored record systems.
Emission testing commands the established base. Research and development applications are expanding most quickly on alternative fuel validation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Analyzer manufacturing clusters concentrate in Germany and Japan, where precision optics suppliers and metrology infrastructure sustain high-specification production. Demand dispersion follows regulatory enforcement intensity rather than vehicle production volume alone.
United States
California's Bureau of Automotive Repair mandates chemiluminescence detection for official inspection lanes, forcing equipment upgrades ahead of EPA tailpipe standard phases. The EPA's phased NOx thresholds compress detection range requirements toward single-digit parts-per-million resolution. Detroit-area OEM validation labs anchor replacement demand for multi-gas precision systems serving powertrain development cycles.
Germany
TÜV inspection stations sustain Europe's densest installed base of certified analyzers, with KBA type-approval requirements triggering predictable replacement cycles. The EU Green Deal and Euro 7 preparatory frameworks at EMA level expand detection range specifications toward ultra-low NOx thresholds. Stuttgart and Munich industrial clusters concentrate OEM research center procurement for powertrain development applications.
Japan
METI emissions certification protocols require traceable calibration chains against national measurement standards, sustaining premium equipment specifications. JIS standards govern analyzer performance validation for domestic inspection networks. Tokyo and Nagoya metropolitan areas concentrate OEM validation lab demand alongside government-mandated testing center procurement.
India
The country's national automotive regulator mandates centralized testing centers in tier-2 cities, opening procurement channels for certified analyzer systems. BIS certification requirements for measurement equipment create entry barriers against uncertified imports. Maharashtra and Karnataka state transport departments lead mobile enforcement unit expansion for roadside emissions verification.
Brazil
State environmental agencies specify measurement-certainty guarantees rather than hardware specifications, favoring outcome-based procurement structures. ANVISA-equivalent environmental enforcement at state level drives portable analyzer adoption for mobile verification beyond fixed urban centers. São Paulo state anchors inspection network density, with Rio de Janeiro and Minas Gerais expanding lane capacity.
Automotive Exhaust Analyzer Market Vendor Landscape
Concentration sits with diversified industrial conglomerates possessing spectroscopic heritage and dense service distribution networks. The vendor base stratifies across three tiers: precision instrumentation specialists serving regulatory compliance channels, integrated diagnostic platform providers anchoring aftermarket service stations, and regional fabricators supplying cost-sensitive inspection tiers. Competitive moves center on sensor platform R&D partnerships and unbundled calibration service models that capture recurring revenue streams.
Within the precision instrumentation tier, HORIBA, Ltd. and AVL List GmbH occupy positions defined by spectroscopic measurement heritage and powertrain development specialization respectively. Robert Bosch GmbH anchors the European aftermarket through service-station distribution density and integrated diagnostic platforms. MRU GmbH represents the mid-tier specialist archetype, while Fuji Electric and Teledyne Technologies Incorporated exemplify diversified industrial conglomerates with cross-sector measurement capabilities.
| Leading Market Players |
|---|
| Sensors, Inc. |
| Fuji Electric |
| HORIBA, Ltd. |
| Testo SE & Co. KGaA |
| MRU GmbH |
| AVL List GmbH |
| EOS S.r.l. |
| Teledyne Technologies Incorporated |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Chemiluminescence detection modules replacing electrochemical architectures in German TÜV stations and California BAR facilities simultaneously concentrate precision optics demand in Japanese and German manufacturing clusters and compress margin pools in cost-sensitive service tiers where basic smoke meters lose regulatory recognition.
Pricing Analysis
Euro 7 preparatory frameworks and EPA tailpipe standards dictate the pricing tier structure across inspection-grade installations. Three-tier pricing structure across certified reference-grade, mid-tier multi-gas, and basic smoke-meter levels separates TÜV-compliant precision systems from aftermarket garage equipment. Price differentiation rests on certification grade against KBA or California BAR protocols and bundled calibration service contracts. Cost compression in the mid-tier is intensifying because electrochemical platforms face displacement by chemiluminescence upgrades. Independent service stations exhibit highest price sensitivity, while environmental testing labs demonstrate lowest sensitivity due to litigation-grade traceability requirements.
Supply Chain Analysis
Inventory cycles for non-dispersive infrared source components extend twelve to eighteen months, constraining equipment manufacturers' ability to respond to Euro 7 specification shifts. Geographic supply concentration centers on Germany and Japan for precision optics, with electrochemical sensor fabrication anchored in Chinese manufacturing zones. Raw material dependencies include germanium substrates for infrared detection, platinum catalysts for chemiluminescence reaction chambers, and specialized calibration gas mixtures. Single-source vulnerability in German-Japanese optics clusters exposes analyzer producers to regional disruption risk. Distribution runs through OEM direct sales for powertrain development labs and authorized distributor networks for aftermarket service stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration service unbundling from hardware sales creates a recurring-revenue layer expanding faster than equipment procurement as inspection authorities shift toward outcome-based measurement-certainty contracts.
For Market Incumbents: Shield installed base relationships by embedding subscription calibration services before regional competitors replicate the model. Deepen backward integration into precision optics through partnerships with German-Japanese substrate suppliers to secure chemiluminescence module supply. Counter emerging portable analyzer specialists by pre-empting mobile enforcement procurement channels in India and Brazil with field-deployable platform variants. For New Entrants and Emerging Players: BIS certification fast-track for Indian centralized testing center tenders offers the most penetrable regulatory entry point among major procurement channels. Target Maharashtra and Karnataka state transport departments with battery-powered portable units for roadside enforcement beyond urban fixed lanes. Pursue white-label manufacturing partnerships with established European brands seeking cost-competitive portable platform sourcing. For Investors and Strategic Acquirers: The market sits at a standards-transition phase that favors precision instrumentation specialists with spectroscopic heritage over diversified industrial conglomerates. Long-term viability across the projection horizon hinges on R&D capacity for ultra-low NOx detection thresholds. Acquisition target archetype: mid-tier regional fabricators possessing inspection network relationships but lacking capital for chemiluminescence platform development. Monitor Euro 7 implementation timing as the critical inflection signal for analyzer refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Unbundling | Captures recurring revenue from TÜV stations and California BAR facilities seeking operational expenditure structures. |
| Chemiluminescence Platform Migration | Positions equipment vendors ahead of EPA and Euro 7 enforcement deadlines displacing electrochemical alternatives. |
| Portable Analyzer Development | Addresses Indian state transport and Brazilian environmental agency procurement for mobile enforcement expansion. |
| Precision Optics Backward Integration | Secures germanium substrate and infrared source supply against German-Japanese supplier concentration risk. |
| Blockchain-Integrated Certification | Creates premium positioning for tamper-evident measurement platforms serving litigation-grade documentation requirements. |
Methodological Framework
A standing panel of TÜV station operators, OEM powertrain validation engineers, environmental testing lab metrologists, and state transport department procurement officers provided ongoing calibration against secondary data validation. Primary fieldwork combined structured interviews with equipment manufacturers and inspection network operators across Germany, Japan, California, and India. Secondary sources encompassed EPA regulatory filings, KBA type-approval documentation, BIS certification records, and automotive production databases. Bottom-up equipment procurement tracking and top-down regulatory mandate analysis were triangulated for consistency.
Forecast outputs were validated against external benchmarks including vehicle inspection lane deployment schedules, Euro 7 preparatory framework timelines, and commercial fleet electrification auditing requirements. The analytical framework modeled segmentation across product type (stationary, portable, hybrid, on-board), measurement technology (infrared, chemiluminescence, electrochemical, mass spectrometry), end user (government agencies, environmental testing labs, service stations, OEMs), and application (emission testing, research and development, engine tuning, regulatory compliance). CAGRs were derived from equipment replacement cycle analysis and regulatory enforcement intensity indices. Industry-specific inputs included TÜV inspection cadence data and EPA tailpipe standard phase-in schedules.
Underlying assumptions cover sustained regulatory enforcement intensity, stable precision optics supply availability, and inspection network capacity expansion timelines, with deviation risk concentrated in Euro 7 implementation delays or sensor platform R&D funding constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Vehicle Crash Testing System Market
Automotive Testing and Simulation
Vehicle Scanner Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Automated Guided Cart Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Automotive Battery Testing Market
Automotive Testing and Simulation
Torque Testers Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market