
 Autonomous Driving Technology Market | 2026-2036
Autonomous Driving Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Driving Technology Market Analysis
The direct-to-fleet sales channel is fragmenting as autonomous vehicle developers bypass traditional dealerships and sell integrated drive systems straight to mobility operators and logistics contractors. NVIDIA dominates the data center training infrastructure for neural networks that power perception stacks. Tesla sustains its position through vertical control over camera-based full self-driving compute and over-the-air deployment. Waymo leverages its captive ride-hail fleet in Arizona and California to accumulate real-world mileage at scale.
Autonomous driving technology encompasses sensor fusion architectures, redundant compute platforms, and decision algorithms that enable vehicles to navigate without human intervention, typically requiring sub-10-millisecond latency for safety-critical path planning. Sensor systems and software platforms capture the largest share of current procurement budgets as OEMs prioritize perception hardware and operating system licensing. Machine learning and lidar represent the fastest-expanding technology segments, with neural network training costs and solid-state lidar unit economics improving through manufacturing scale.
The National Highway Traffic Safety Administration in the United States and UNECE WP.29 in Europe set divergent testing protocols that force developers to maintain dual validation pipelines for cross-border deployment. China's Ministry of Industry and Information Technology governs connected vehicle standards and mapping permissions, creating a regulatory moat around domestic operators. Stakeholders must monitor how jurisdictional fragmentation in liability frameworks and data localization rules reshapes the economics of multi-market fleet rollouts.
Market Dynamics
Sensor fusion architectures are compressing development timelines as lidar, radar, and camera inputs merge into unified perception stacks, forcing suppliers to choose between modular component sales and full-stack system integration.
Growth Catalysts
- EU AI Act validation mandates:Tier-1 suppliers in Germany and France are accelerating homologation investments to secure type approval for Level 3+ systems before the 2026 enforcement window closes.
- Robotaxi fleet procurement:Mobility operators in San Francisco and Phoenix are signing multi-year sensor procurement contracts that lock in volume commitments for solid-state lidar arrays.
- Edge computing silicon:Automotive-grade GPUs and neural processing units from Taiwan and South Korea are achieving automotive safety integrity levels that enable in-vehicle inference without cloud dependency.
Market Restraints
- High-purity silicon carbide substrate shortage:Power electronics for redundant compute platforms face 40-week lead times as substrate manufacturers in Japan and Germany ration capacity among automotive and industrial buyers.
- UNECE WP.29 dual-homologation burden:Developers targeting both European and Chinese deployments must maintain separate validation pipelines for cybersecurity and software update management, doubling certification overhead.
- Camera-only perception ceilings:Vision systems struggle with occlusion edge cases in adverse weather, preserving lidar demand despite unit cost compression.
Strategic Opportunities
- India's connected vehicle mandate:The country's compulsory AIS-140 telematics standard creates embedded compute demand for fleet operators upgrading commercial vehicles to support future autonomy retrofits.
- Sensor-to-cloud subscription models:Per-mile data licensing agreements are emerging as fleet operators prefer operational expenditure structures over upfront hardware capital outlays.
- V2X infrastructure convergence:5G roadside units and edge servers in South Korea and Japan are creating data exchange protocols that reduce onboard perception complexity for urban robotaxi corridors.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 certification expertise concentrates among semiconductor vendors in Germany and Japan, constraining Tier-2 supplier scaling.
- Mapping data localization requirements:China's Surveying and Mapping Law forces foreign operators to partner with domestic license holders, fragmenting HD map coverage across jurisdictional boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Driving Technology Market |
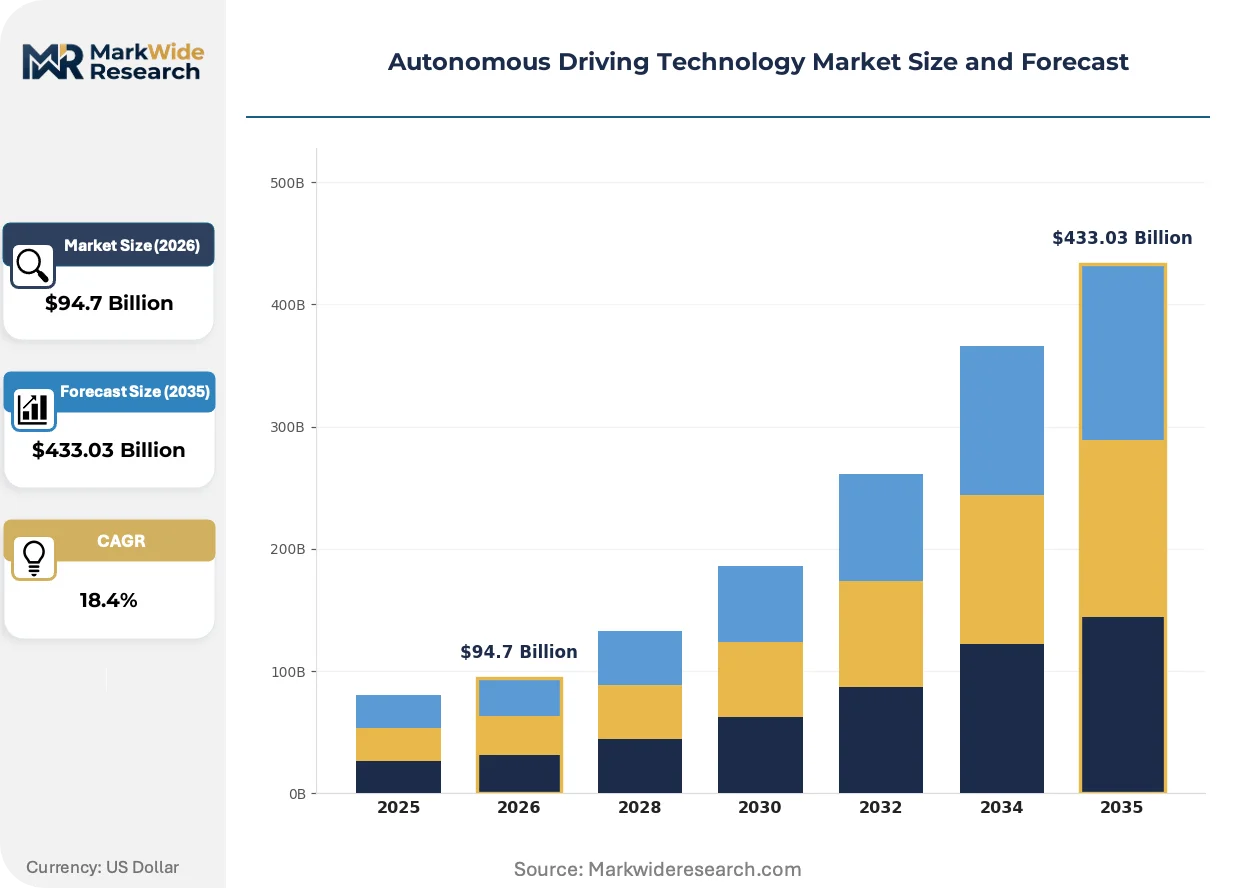
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $433.03 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor Systems, Control Units, Software Platforms, Communication Interfaces End User: Passenger Vehicles, Commercial Vehicles, Public Transport, Freight Vehicles Technology: Computer Vision, Lidar, Radar, Machine Learning Application: Highway Navigation, Urban Driving, Automated Parking, Fleet Management |
| Companies Covered | Waymo (Alphabet), Tesla, NVIDIA, Baidu Apollo, Intel (Mobileye), Renesas Electronics, NXP Semiconductors, Aurora Innovation, Amazon (Zoox), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Driving Technology Market Emerging Trajectories
Neural network training methodologies are migrating from pure simulation toward hybrid real-synthetic data pipelines, compressing the cost curve for perception model development while raising new validation complexities.
Lidar point cloud processing is hybridizing with transformer-based vision architectures to enable unified 3D scene understanding without separate sensor-specific pipelines. Tier-1 suppliers in Germany and California are deploying these fused perception stacks in 2024 production programs. The convergence is compressing hardware bill-of-materials by eliminating redundant compute layers previously dedicated to sensor-specific preprocessing.
The EU AI Act's risk-based classification system is mandating conformity assessments for autonomous driving systems before market placement, forcing developers to document training data provenance and model performance across edge case libraries. European OEMs are responding by establishing captive algorithm audit functions that interface directly with notified bodies in Germany and the Netherlands. This regulatory friction is advantaging incumbent suppliers with existing type approval relationships over venture-backed perception startups.
Fleet operators are unbundling sensor procurement from full vehicle purchases, signing direct maintenance and calibration contracts with lidar and radar vendors that bypass traditional OEM service networks. This channel disintermediation is most visible in Arizona and Texas, where robotaxi operators maintain captive technician workforces for overnight sensor recalibration. The shift is forcing component suppliers to build field service organizations that mirror enterprise IT hardware support models rather than automotive aftermarket structures.
Autonomous Driving Technology Market Segmentation
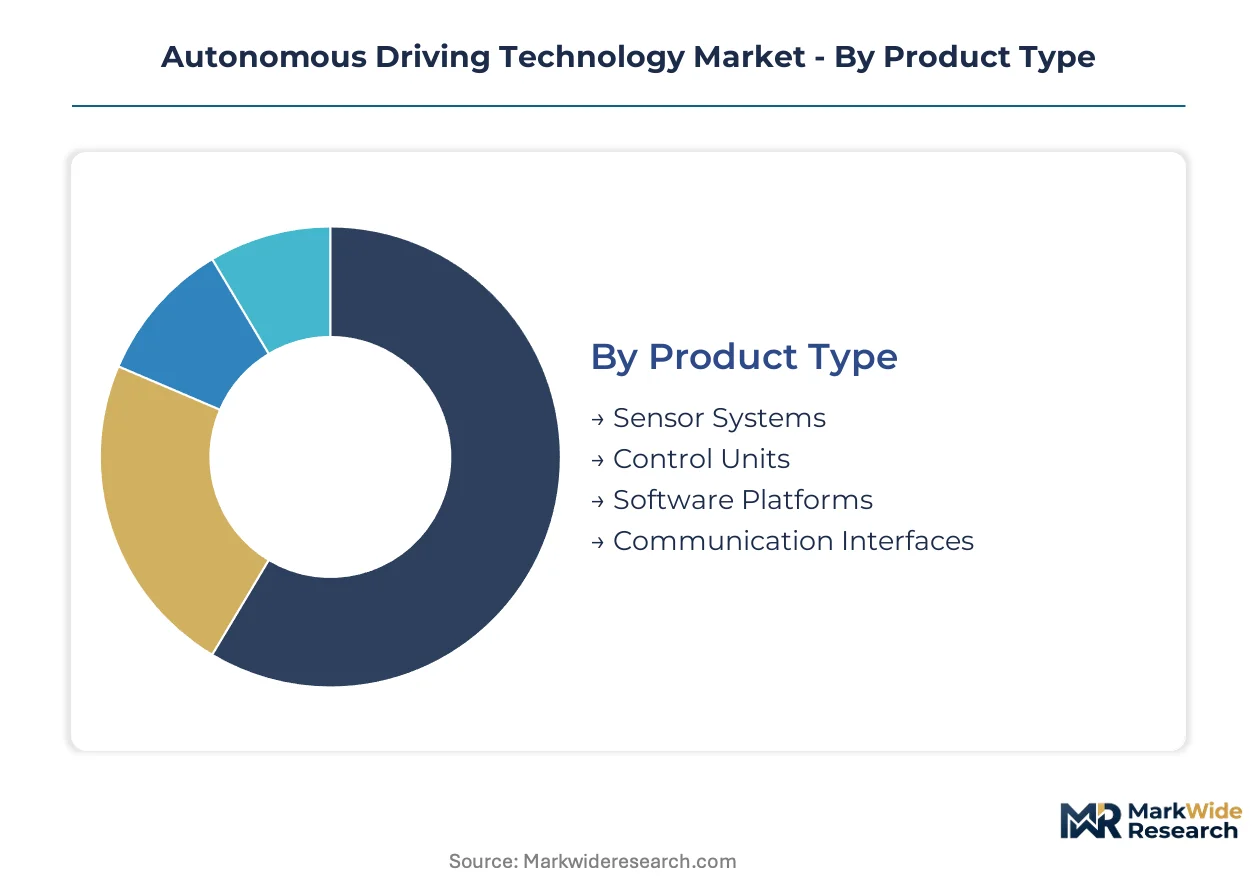
Segmentation in autonomous driving technology reveals how procurement priorities diverge across hardware-centric and software-centric buyers, with sensor systems commanding capital expenditure from traditional OEMs while software platforms attract recurring revenue from fleet operators and mobility services.
Product Type:
Mature hardware categories dominate current procurement volumes, though software platforms are accelerating fastest as developers decouple perception stacks from vehicle-integrated electronics.
- Sensor Systems:Camera arrays, radar modules, and lidar units constitute the physical perception layer, with solid-state lidar arrays seeing concentrated demand from robotaxi operators in San Francisco and Phoenix seeking weather-resilient redundancy. Procurement contracts now span multi-year sensor maintenance agreements that bypass traditional OEM service networks.
- Software Platforms:Operating systems and middleware enabling sensor fusion and path planning are shifting toward subscription licensing models, with fleet operators in Arizona and Texas preferring per-mile data fees over upfront capital outlays. The EU AI Act's conformity assessment requirements are advantaging established suppliers with existing type approval relationships.
- Control Units:Automotive-grade compute platforms integrating GPUs and neural processing units from Taiwan and South Korea achieve ASIL-D safety integrity levels for in-vehicle inference.
- Communication Interfaces:V2X modules and 5G connectivity hardware enable data exchange with roadside infrastructure in South Korea and Japan.
Sensor Systems handles the majority of throughput; Software Platforms is the fastest mover on share.
End User:
Cost tier differentiation separates premium autonomous deployments from mass-market assisted driving, with commercial vehicle operators accepting higher per-unit costs in exchange for operational labor savings.
- Passenger Vehicles:Consumer-grade autonomous features concentrate in Level 2+ highway assistance systems, with European OEMs prioritizing Level 3 homologation ahead of EU AI Act enforcement windows. Germany's KBA and France's regulatory bodies are processing type approvals for conditional automation systems.
- Commercial Vehicles:Long-haul freight operators in the United States are deploying lidar-enabled highway platooning systems, with NHTSA validation protocols governing cross-state deployment. The segment accepts premium hardware costs given driver shortage economics and fuel efficiency gains from aerodynamic drafting.
- Public Transport:Fixed-route shuttle services in controlled environments represent the most constrained application scope.
- Freight Vehicles:Last-mile delivery robotics and warehouse automation systems integrate autonomous navigation for hub-to-hub logistics.
Passenger Vehicles absorbs the largest share of component volumes; Commercial Vehicles is expanding most quickly as logistics operators automate highway corridors.
Technology:
Application context determines technology selection, with highway navigation favoring camera-radar fusion while urban robotaxi deployments require lidar for occlusion handling.
- Computer Vision:Camera-based perception leveraging transformer architectures enables unified 3D scene understanding, though vision-only systems face performance ceilings in adverse weather conditions that preserve demand for complementary sensor modalities.
- Machine Learning:Neural network training methodologies are migrating toward hybrid real-synthetic data pipelines, compressing development costs while raising validation complexities for edge case coverage. NVIDIA's data center infrastructure dominates the training compute layer.
- Lidar:Solid-state arrays are achieving unit economics through manufacturing scale, with point cloud processing hybridizing with vision architectures.
- Radar:4D imaging radar provides velocity resolution and weather penetration at lower cost than lidar for highway applications.
Computer Vision commands the widest deployment base; Machine Learning is climbing the fastest as training infrastructure commoditizes.
Application:
Geography of deployment shapes system architecture, with dense urban environments demanding the highest sensor redundancy and compute allocation.
- Urban Driving:Complex intersection handling and pedestrian prediction requirements drive the most intensive perception compute loads, with robotaxi operators in San Francisco and Phoenix maintaining captive technician workforces for overnight sensor recalibration. China's MIIT governs mapping permissions that fragment HD map coverage for foreign operators.
- Highway Navigation:Structured road environments with predictable traffic patterns enable lower-cost sensor configurations, with German OEMs leading Level 3 conditional automation deployment on controlled-access motorways. UNECE WP.29 regulations establish the harmonized framework for cross-border European deployment.
- Automated Parking:Low-speed confined environments permit ultrasonic and camera-only perception stacks.
- Fleet Management:Telematics and remote monitoring systems create embedded compute demand for future autonomy retrofits, particularly under India's AIS-140 mandate.
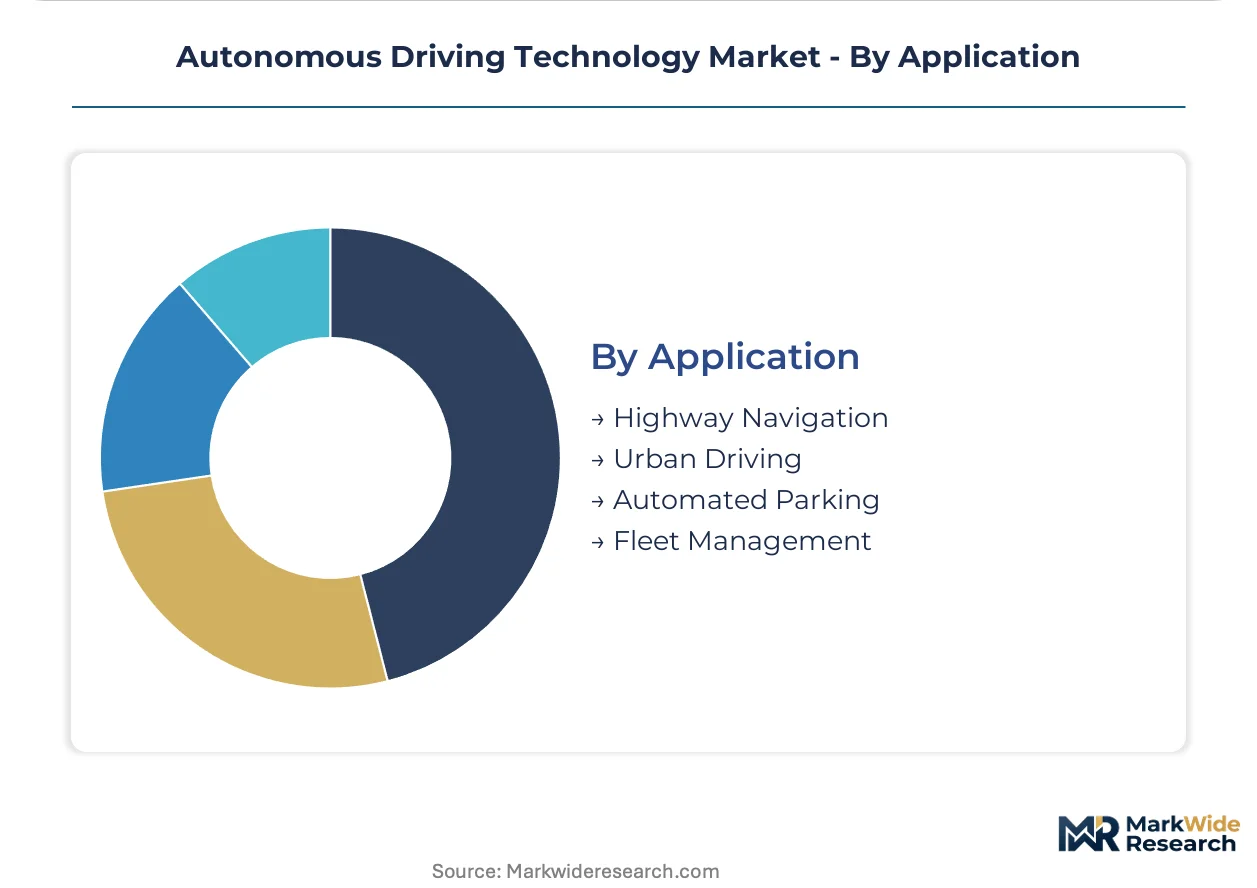
Highway Navigation generates the highest unit volumes; Urban Driving is gaining share fastest as robotaxi fleets scale in Arizona, California, and Chinese cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA governs validation protocols for the United States, establishing baseline testing requirements that shape developer investment priorities across North American deployment corridors. The regulatory divergence between NHTSA and UNECE WP.29 forces dual-homologation strategies that concentrate engineering resources in jurisdictions with the clearest commercialization pathways.
United States
Robotaxi fleet operators in San Francisco and Phoenix are scaling autonomous vehicle deployments through direct sensor procurement contracts that bypass traditional OEM channels. NHTSA maintains jurisdiction over cross-state commercial deployment while California's Department of Motor Vehicles processes separate permits for driverless testing on public roads. Arizona's permissive regulatory environment attracts concentrated fleet operations in the Phoenix metropolitan area where operators accumulate real-world mileage at scale.
China
Baidu Apollo and domestic OEMs are deploying robotaxi services across multiple cities under MIIT governance of connected vehicle standards and mapping permissions. The Ministry of Industry and Information Technology's Surveying and Mapping Law creates regulatory moats that force foreign operators into domestic partnerships for HD map coverage. Shanghai and Beijing host the densest concentrations of autonomous vehicle testing zones where developers validate perception systems under controlled urban conditions.
Germany
KBA processes type approvals for Level 3 conditional automation systems ahead of EU AI Act enforcement windows that mandate conformity assessments for autonomous driving algorithms. Germany's Federal Motor Transport Authority requires documented training data provenance and edge case performance libraries that advantage incumbent suppliers with established homologation relationships. Stuttgart and Munich anchor industrial clusters where Tier-1 suppliers integrate solid-state lidar into production vehicle programs.
Japan
METI coordinates V2X infrastructure deployment through 5G roadside units and edge servers that reduce onboard perception complexity for urban robotaxi corridors. Japan's Ministry of Economy, Trade and Industry funds connected vehicle pilot programs in Tokyo and Osaka where automakers test sensor fusion architectures against dense pedestrian environments. Nagoya's automotive manufacturing belt supplies automotive-grade GPUs and neural processing units achieving ASIL-D safety integrity levels.
South Korea
Seoul's metropolitan government partners with domestic semiconductor fabricators to deploy autonomous shuttle services on fixed-route corridors. MFDS-equivalent automotive safety regulators collaborate with MIIT on cross-border data exchange protocols for multi-market fleet validation. Busan and Ulsan host manufacturing clusters where edge computing silicon achieves automotive safety integrity levels that enable in-vehicle inference without cloud dependency.
Autonomous Driving Technology Market Vendor Landscape
Technology integrators and component specialists split the market along vertical integration boundaries, with full-stack developers capturing fleet operator relationships while modular suppliers penetrate OEM supply chains. The vendor base concentrates around three strategic archetypes: captive technology divisions of mobility platforms, independent perception stack vendors, and automotive-grade semiconductor fabricators. Consolidation pressures favor players with existing type approval relationships and captive training data pipelines. Competitive positioning hinges on algorithm audit capabilities and field service organization scale rather than hardware unit economics alone.
Within the captive technology tier, Waymo and Tesla exemplify divergent architectural philosophies that anchor opposing ends of the sensor modality spectrum. NVIDIA occupies a position as the dominant data center training infrastructure provider for neural network development across the developer ecosystem. Baidu Apollo represents the integrated platform archetype within China's regulatory environment, where domestic mapping permissions create structural advantages for local operators.
| Leading Market Players |
|---|
| Waymo (Alphabet) |
| Tesla |
| NVIDIA |
| Baidu Apollo |
| Intel (Mobileye) |
| Renesas Electronics |
| NXP Semiconductors |
| Aurora Innovation |
| Amazon (Zoox) |
| Others |
Supply Flow & Price Mechanics
High-purity silicon carbide substrate manufacturing in Japan and Germany concentrates upstream margin capture for automotive-grade compute platforms, with downstream pricing power accumulating among fleet operators in Arizona and California who negotiate multi-year sensor procurement contracts directly with lidar vendors.
Pricing Analysis
Geographic price spreads separate European Level 3 homologation premiums from Chinese robotaxi volume discounts, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and after-sales service bundling. Price differentiation hinges on ISO 26262 ASIL-D safety integrity certification and field service organization scale, with margins tightening in solid-state lidar arrays due to manufacturing scale improvements. Fleet operators exhibit lowest price sensitivity given operational labor savings, while Tier-2 suppliers face highest procurement pressure.
Supply Chain Analysis
TSMC and Samsung Foundry hold captive capacity for automotive neural processing units, with supply concentration in Taiwan, South Korea, and Japan feeding the compute layer for perception stacks. Raw material dependencies center on high-purity silicon carbide substrates, rare-earth magnet materials for lidar actuators, and automotive-grade DRAM. Single-source vulnerability in substrate manufacturing creates structural risk. Distribution runs through direct-to-fleet channels that bypass traditional OEM service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where sensor-to-cloud data exchange protocols are displacing standalone hardware procurement, with V2X infrastructure convergence in South Korea and Japan demonstrating interoperability shifts that reshape competitive boundaries.
For Market Incumbents: Harden algorithm audit capabilities to satisfy EU AI Act conformity assessment mandates before enforcement windows close, while securing captive training data pipelines through fleet operator partnerships that lock out venture-backed perception startups. Vertical integration into solid-state lidar manufacturing mitigates substrate shortage exposure.
For New Entrants and Emerging Players: Build out field service organizations mirroring enterprise IT hardware support models to serve robotaxi operators in Texas and Arizona, targeting the sensor maintenance and overnight recalibration segment that incumbent automotive suppliers have ceded. A per-mile data licensing go-to-market angle bypasses upfront capital barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward Tier-1 suppliers with existing KBA and Netherlands notified body relationships, as regulatory friction advantages incumbents with homologation infrastructure. Long-term viability rests on algorithm audit capabilities and multi-jurisdictional validation pipelines. Watch for MIIT mapping permission liberalization as inflection signal for foreign operator entry into Chinese robotaxi corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Cloud Platform Integration | Enables per-mile pricing models that shift fleet operator procurement from CapEx to OpEx structures. |
| EU AI Act Conformity Investment | Secures type approval pathways through Germany's KBA ahead of regulatory enforcement windows. |
| Solid-State Lidar Manufacturing Scale-Up | Compresses unit economics for robotaxi operators in San Francisco and Phoenix. |
| V2X Infrastructure Partnership | Reduces onboard perception complexity through 5G roadside units in South Korea and Japan. |
| HD Map Localization Joint Venture | Navigates China's Surveying and Mapping Law constraints for foreign operators. |
Methodological Framework
Desk research of regulatory filings from NHTSA and UNECE WP.29, automotive production databases, and SEC disclosures from semiconductor fabricators preceded structured interviews with Tier-1 supplier procurement leads, OEM platform engineers, robotaxi fleet operations directors, and functional safety certification specialists. Primary fieldwork combined with secondary validation from customs records and vehicle registration data. Bottom-up segment sizing triangulated against top-down market estimates.
Assumptions held regulatory timelines and technology cost curves within observed trajectories while varying fleet deployment scale and cross-border homologation friction. The analytical framework modeled segmentation across sensor modality, automation level, vehicle class, and regional regulatory cluster throughout the projection horizon. CAGRs derived from volume-outcome sensitivity analysis incorporating neural network training cost compression and solid-state lidar manufacturing yield improvements.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by hyperscaler-backed entrants would shift outcomes. Quarterly review of MIIT mapping permission announcements, KBA type approval volumes, and silicon carbide substrate lead times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automotive Predictive Technology Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
India Autonomous Navigation Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Automotive Lidar Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
Europe ADAS Market