
 Automotive Crash Test Dummies Market | 2026-2036
Automotive Crash Test Dummies Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Crash Test Dummies Market Analysis
Modular dummy configurations that separate sensor arrays from base anthropomorphic structures is realigning how automakers and test houses configure procurement budgets. Humanetics Innovative Solutions leverages its integrated sensor-dummy platforms to dominate high-end regulatory compliance workflows. JASTI Co., Ltd. anchors Asian supply chains through specialized production of Hybrid III variants for domestic vehicle testing protocols.
Automotive crash test dummies are instrumented anthropomorphic devices constructed from steel skeletons, vinyl skin, and foam flesh with embedded accelerometers, load cells, and strain gauges calibrated to replicate human biomechanical response during collision events. Their commercial purpose centers on quantifying occupant injury risk for regulatory certification and vehicle safety rating programs. Hybrid III platforms still occupy the largest installed base across vehicle testing applications, while THOR architectures represent the fastest-growing segment as NHTSA and Euro NCAP transition toward more biofidelic injury assessment standards. Digital Sensors and Data Acquisition Systems capture expanding margin pools as dummy instrumentation complexity rises with multi-point measurement requirements.
NHTSA, Euro NCAP, and Japan's National Agency for Automotive Safety and Victim's Aid shape product standards through iterative updates to frontal and side-impact test protocols that mandate new dummy specifications. These frameworks directly determine market access by specifying which dummy families qualify for official certification submissions. Stakeholders must monitor regulatory divergence between U.S. THOR adoption timelines and European biofidelity requirements when allocating R&D and manufacturing capacity across regional test house demand.
Market Dynamics
The transition from Hybrid III to THOR and biofidelic dummy architectures is compressing replacement cycles across certification laboratories while elevating instrumentation density requirements per unit.
Growth Catalysts
- THOR Mandate Trajectory:NHTSA's phased THOR adoption timeline for frontal impact testing is compelling US-based automakers to accelerate facility retrofit investments and expand dummy procurement volumes.
- Euro NCAP Protocol Evolution:The European safety body's continuous updates to side-impact and far-side occupant assessment standards are expanding sensor channel counts per dummy and driving replacement demand.
- Active Safety Integration:Pre-crash braking systems and autonomous emergency braking are creating new test scenarios requiring dummies instrumented for low-speed collision kinematics and restraints deployment timing.
Market Restraints
- Calibration Infrastructure Concentration:Only three certified calibration laboratories in Germany, Japan, and the United States can validate THOR biofidelity specifications, creating geographic bottlenecks for new market entrants.
- Specialized Polymer Supply:Vinyl skin formulations meeting ISO biomechanical response specifications depend on petrochemical feedstocks subject to price volatility and limited qualified suppliers.
- Hybrid III Stranded Assets:Decades of accumulated Hybrid III inventory across Asian test houses faces accelerated obsolescence as Euro NCAP and NHTSA disqualify legacy platforms from new certification submissions.
Strategic Opportunities
- India Regulatory Emergence:Bharat NCAP's 2023 launch and the country's Automotive Industry Standard crash test protocols are opening procurement channels for mid-tier dummy configurations previously excluded from premium markets.
- Digital Twin Convergence:Physics-based human body models from Humanetics and Dassault Systèmes are converging with physical dummy data streams, enabling hybrid virtual-physical certification workflows that reduce per-test dummy wear.
- Aftermarket Sensor Retrofit:Modular data acquisition architectures allow test houses to upgrade existing dummy fleets with additional accelerometer channels rather than full platform replacement.
Industry Challenges
- Biofidelity Engineering Talent:The specialized intersection of biomechanics, sensor integration, and regulatory compliance commands premium compensation and limited graduate pipeline output.
- Multi-Jurisdictional Certification Lag:Dummy platforms validated for NHTSA protocols require separate Euro NCAP biofidelity testing, extending product development timelines and freezing capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Crash Test Dummies Market |
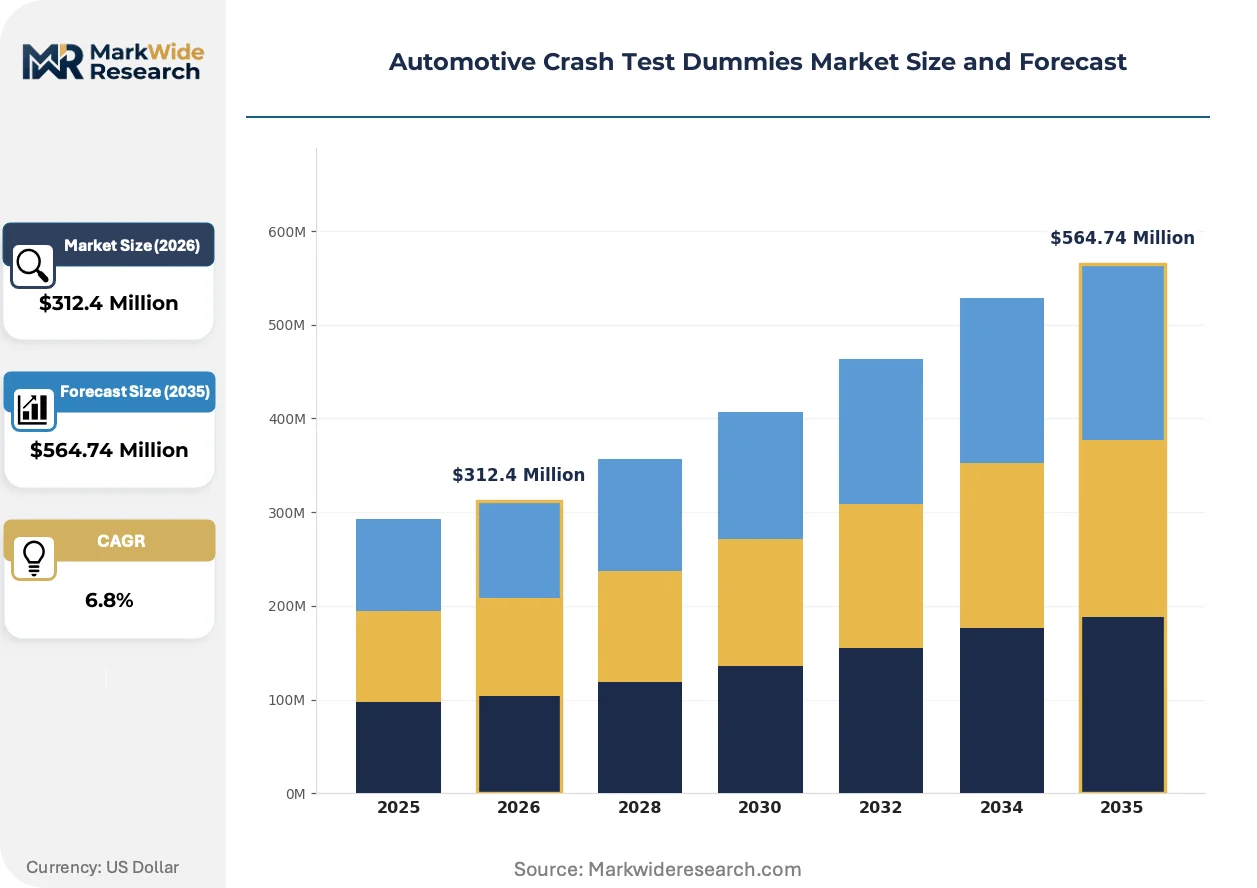
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid III, SID, FAZIL, THOR Application: Vehicle Testing, Safety Research, Regulatory Compliance, Consumer Testing End User: Automakers, Research Institutes, Government Agencies, Safety Organizations Technology: Digital Sensors, Data Acquisition Systems, Biomechanical Modeling, Crash Simulation |
| Companies Covered | 4activeSystems GmbH, GESAC Inc., Humanetics Innovative Solutions, Autoliv Inc., AB Dynamics plc, TASS International, Cellbond, DEKRA SE, JASTI Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Crash Test Dummies Market Emerging Trajectories
Computational biomechanics and embedded sensor miniaturization are dissolving the boundary between physical dummy testing and virtual human modeling, restructuring how automakers allocate validation budgets across hardware and software.
THOR-50M and THOR-5F platforms are overtaking Hybrid III architectures in regulatory submission workflows. Euro NCAP's 2023-2025 protocol updates have made THOR mandatory for frontal impact star ratings, compelling German and Swedish OEMs to convert entire test cell inventories. The shift is compressing replacement revenue into concentrated procurement windows while elevating average unit values through denser sensor packaging.
REACH Annex XVII restrictions on certain phthalate plasticizers are compelling vinyl skin reformulation across European-sourced dummies. The chemical compliance burden is falling most heavily on JASTI and smaller Asian manufacturers lacking in-house polymer chemistry capabilities, forcing partnerships with specialized compounders or exclusion from EU certification supply chains.
Test house purchasing patterns are consolidating around multi-year framework agreements with integrated sensor-dummy suppliers. Tier-1 automakers in Michigan and Stuttgart are bypassing traditional equipment distributors to contract directly with Humanetics for fleet-wide instrumentation standardization, collapsing channel margins and privileging vendors with captive calibration and repair services.
Automotive Crash Test Dummies Market Segmentation
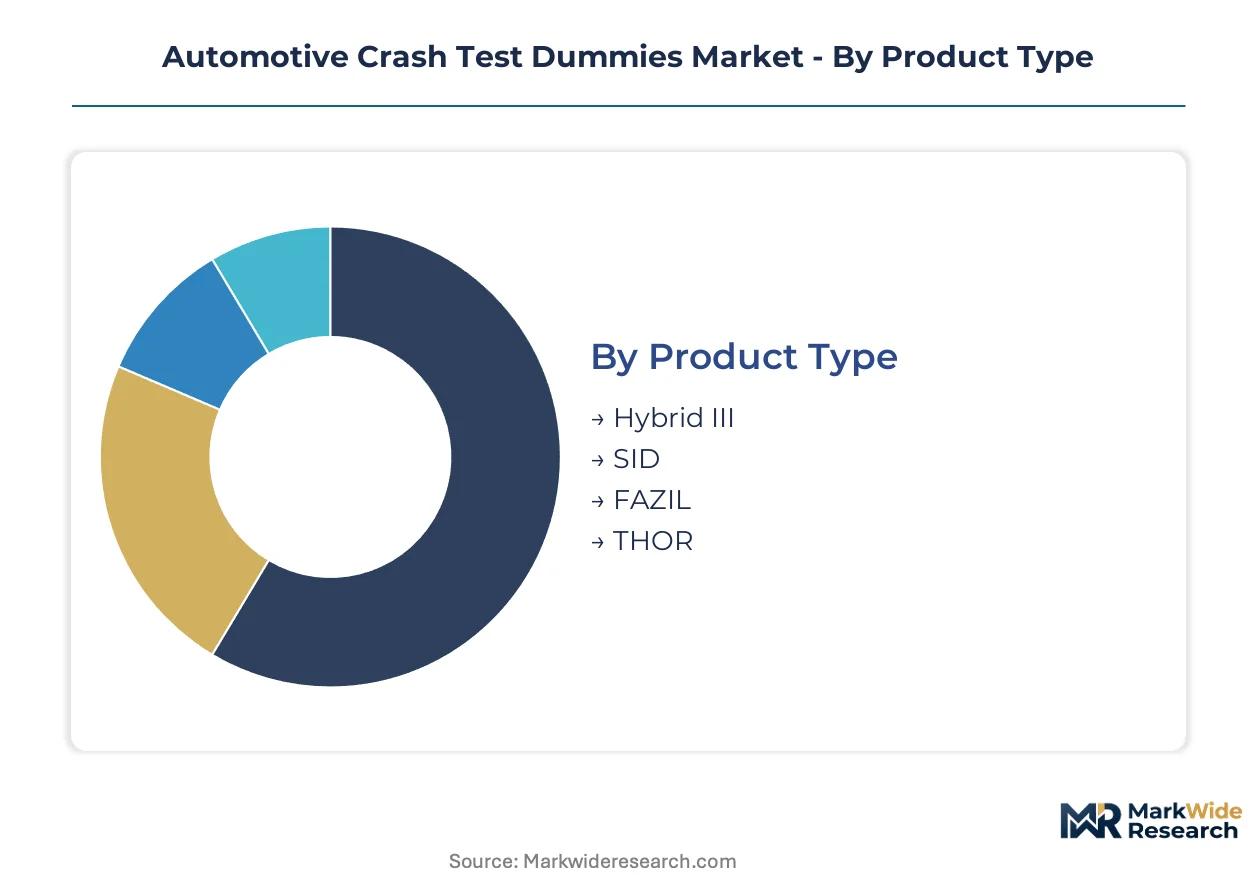
Segmentation in the Automotive Crash Test Dummies Market reveals how procurement budgets fragment across legacy platforms and next-generation architectures. Automakers allocate capital differently depending on whether their priority is regulatory compliance, research innovation, or consumer safety validation.
Product Type:
Supply concentration among certified calibration laboratories in Germany, Japan, and the United States privileges dummy families with established biofidelity validation pathways, compressing viable sourcing options for test houses.
- THOR:Advanced frontal impact dummies with enhanced thoracic and pelvic instrumentation calibrated to human biomechanical response curves. NHTSA's phased mandate timeline is concentrating procurement volumes among US-based automakers retrofitting test facilities in Michigan and California.
- Hybrid III:Vinyl-skinned anthropomorphic platforms with steel skeletons and embedded accelerometers representing the largest installed base across Asian test houses. Euro NCAP's disqualification of legacy platforms from new certification submissions is accelerating obsolescence of accumulated inventory in Japan and South Korea.
- SID:Side Impact Dummy configurations optimized for lateral collision kinematics and door intrusion scenarios.
- FAZIL:Specialized child dummy platforms scaled to pediatric anthropometry for restraint system validation.
Today's leader: Hybrid III. Tomorrow's challenger: THOR.
Application:
Cost tier differentiation separates premium regulatory certification workflows from mid-tier research budgets, with sensor channel density and calibration frequency driving pricing stratification.
- Regulatory Compliance:Formal submission testing for NHTSA Federal Motor Vehicle Safety Standards and Euro NCAP star rating protocols. German certification labs in Stuttgart and Wolfsburg anchor demand for THOR-50M platforms with maximum instrumentation density.
- Vehicle Testing:Internal validation programs at OEM facilities evaluating restraint performance and structural integrity. Japanese automakers in Toyota City and Hiroshima concentrate procurement for multi-point measurement configurations supporting active safety integration.
- Safety Research:Academic and institutional studies advancing injury biomechanics knowledge beyond current regulatory minimums.
- Consumer Testing:Independent assessment programs generating publicly comparable safety ratings.
Regulatory Compliance commands premium pricing. Vehicle Testing offers volume scale.
End User:
Customer type fragmentation creates divergent procurement patterns, with government agencies demanding standardized platforms while research institutes prioritize modular upgrade paths.
- Automakers:Internal test departments at OEMs managing fleet-wide dummy inventories and calibration schedules. Direct contracting with integrated sensor-dummy suppliers is consolidating purchasing power among Tier-1 manufacturers in Detroit and Stuttgart.
- Government Agencies:National regulators including NHTSA and Japan's National Agency for Automotive Safety and Victim's Aid specifying mandatory dummy families for official submissions.
- Research Institutes:University and institutional laboratories conducting foundational biomechanics research with flexible instrumentation requirements.
- Safety Organizations:Independent bodies such as Euro NCAP and Bharat NCAP executing consumer-facing assessment programs.
Automakers drive platform standardization. Government agencies determine market access.
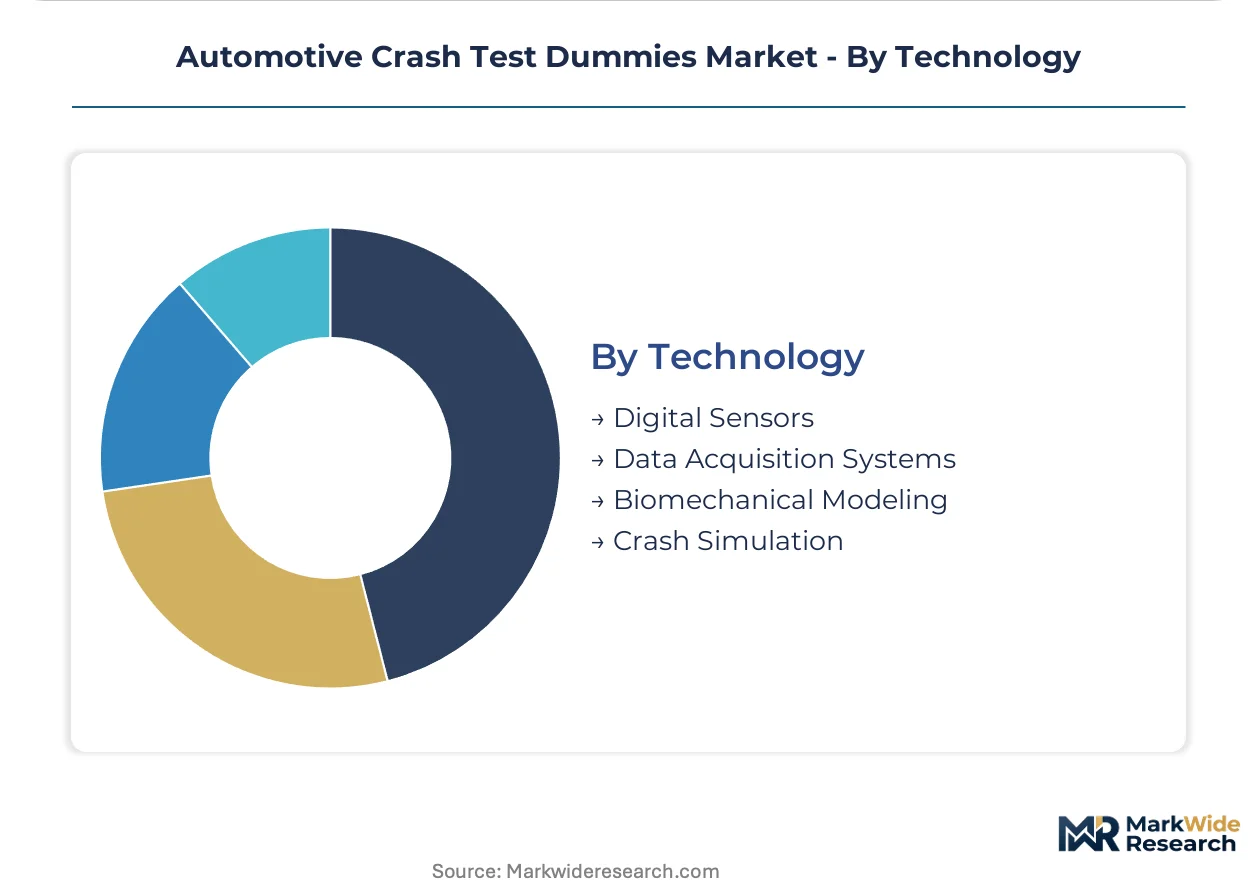
Technology:
Margin concentration is shifting toward data acquisition and embedded sensor systems as physical dummy hardware commoditizes and instrumentation complexity escalates.
- Digital Sensors:Miniaturized accelerometers, load cells, and strain gauges with multi-point measurement capabilities. Euro NCAP's expanded side-impact and far-side occupant protocols are elevating channel count requirements per dummy unit.
- Data Acquisition Systems:Modular architectures enabling aftermarket sensor retrofit and fleet-wide instrumentation standardization. Test houses in the United States are bypassing traditional distributors to contract directly with suppliers for integrated sensor-dummy platforms.
- Biomechanical Modeling:Physics-based human body models converging with physical dummy data streams for hybrid virtual-physical workflows.
- Crash Simulation:Computational tools reducing per-test dummy wear through pre-validation of impact scenarios.
Digital Sensors capture expanding margin pools. Data Acquisition Systems enable fleet modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crash test dummy manufacturing originated in the United States during the 1970s as NHTSA standardized occupant protection protocols, establishing calibration methodologies that German and Japanese laboratories later adopted and refined for their domestic certification workflows.
United States
NHTSA's phased THOR mandate for frontal impact testing is compelling domestic automakers to retrofit Michigan and California test facilities with biofidelic platforms. The regulator's updated Federal Motor Vehicle Safety Standards specify sensor channel counts that disqualify legacy Hybrid III inventory from new submissions. Detroit-area certification labs are consolidating procurement through direct contracts with integrated sensor-dummy suppliers to secure calibration priority.
Germany
Euro NCAP's 2023-2025 protocol updates have made THOR mandatory for star ratings, driving Stuttgart and Wolfsburg OEMs to convert entire test cell inventories. KBA enforcement of REACH Annex XVII phthalate restrictions is forcing vinyl skin reformulation across European-sourced dummies. The country's certified calibration laboratory in Bavaria validates biofidelity specifications that determine market access for THOR platforms.
Japan
The National Agency for Automotive Safety and Victim's Aid specifies mandatory dummy families for official certification submissions, concentrating demand in Toyota City and Hiroshima test facilities. JASTI Co., Ltd. anchors regional supply chains through specialized Hybrid III production for domestic vehicle testing protocols. Accumulated legacy inventory across Asian test houses faces accelerated obsolescence as Euro NCAP and NHTSA disqualify older platforms.
India
Bharat NCAP's 2023 launch and Automotive Industry Standard crash test protocols are opening procurement channels for mid-tier dummy configurations previously excluded from premium markets. The country's national automotive regulator is establishing biofidelity requirements that align with Euro NCAP frameworks while accommodating domestic manufacturing cost structures. Chennai and Pune testing clusters are expanding capacity to serve Maruti Suzuki and Tata Motors validation programs.
South Korea
MFDS-aligned automotive safety standards are elevating instrumentation density requirements for domestic OEM certification workflows. Hyundai and Kia test facilities in Ulsan and Hwaseong are procuring THOR-compatible platforms to maintain export market access under Euro NCAP and NHTSA protocols. The country's calibration infrastructure partnerships with German laboratories are reducing biofidelity validation bottlenecks for new market entrants.
Automotive Crash Test Dummies Market Vendor Landscape
Premium-margin players sit above commodity-margin players across sensor integration and calibration service bundling. The market structures around three tiers: integrated sensor-dummy platforms commanding regulatory compliance premiums, specialized Hybrid III fabricators serving legacy Asian demand, and modular component suppliers enabling aftermarket fleet upgrades. Consolidation pressure is intensifying as direct contracting between Tier-1 automakers and calibration-captive vendors collapses traditional distribution margins. Strategic moves center on multi-year framework agreements and captive repair service networks.
Within the integrated platform tier, Humanetics Innovative Solutions and JASTI Co., Ltd. exemplify divergent geographic anchoring strategies. Humanetics occupies a position aligned with North American and European regulatory compliance workflows, while JASTI represents the specialized production archetype serving domestic Asian testing protocols. Among calibration and validation specialists, DEKRA SE and AB Dynamics plc sit within the service-integrated tier that automakers increasingly favor for fleet-wide standardization contracts.
| Leading Market Players |
|---|
| 4activeSystems GmbH |
| GESAC Inc. |
| Humanetics Innovative Solutions |
| Autoliv Inc. |
| AB Dynamics plc |
| TASS International |
| Cellbond |
| DEKRA SE |
| JASTI Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap calibration specialists in Germany and Japan anchor supply-side discipline through multi-generational biofidelity expertise and captive repair networks, compressing price competition among THOR platform vendors while elevating instrumentation bundling premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NHTSA-certified THOR platforms with full sensor arrays from Euro NCAP-aligned mid-tier configurations and legacy Hybrid III units for research applications. Price differentiation hinges on calibration pedigree and channel density, with German certification labs paying least-sensitive premiums for Bavaria-validated biofidelity while Indian test houses pressure mid-tier suppliers on unit economics. Cost compression in economy-tier Hybrid III inventory is intensifying because Euro NCAP disqualification accelerates obsolescence fire sales across Asian secondary markets.
Supply Chain Analysis
Certification gating through NHTSA, Euro NCAP, and Japan's National Agency for Automotive Safety and Victim's Aid concentrates viable THOR production in Germany, the United States, and Japan, freezing out unvalidated fabricators regardless of manufacturing cost. Vinyl skin formulations rest on specialized petrochemical feedstocks from qualified compounders in Belgium and South Korea, while precision sensor arrays draw from semiconductor fabrication clusters in Taiwan and Japan. Single-source vulnerability runs through the three certified calibration laboratories validating biofidelity specifications. Distribution runs through direct framework agreements between Tier-1 automakers and integrated sensor-dummy suppliers, bypassing traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NHTSA's phased THOR mandate for frontal impact testing locks in replacement demand across US certification labs regardless of macroeconomic cycles.
For Market Incumbents: Anticipate margin compression from modular sensor retrofit providers enabling test houses to upgrade existing Hybrid III fleets rather than full platform replacement. Defend position by deepening captive calibration services in Michigan and Stuttgart while accelerating biofidelity validation partnerships with Bharat NCAP ahead of Indian regulatory maturation. Certification investment in REACH Annex XVII-compliant vinyl skin formulations is essential to maintain EU market access against chemical compliance barriers. For New Entrants and Emerging Players: Mid-tier Indian safety research institutes represent the most penetrable buyer archetype currently excluded from premium calibration-captive supply chains. Target Bharat NCAP-aligned test facilities in Chennai and Pune with THOR-compatible platforms priced below German import tiers while offering localized repair turnaround. A go-to-market angle anchored to Automotive Industry Standard crash test protocol pre-certification consulting reduces buyer switching friction. For Investors and Strategic Acquirers: Tier-1 automakers in Detroit and Stuttgart are the most active acquirer in this space, consolidating fleet-wide instrumentation standardization through direct vendor contracting. Long-term viability over a 5-10 year window depends on positioning within hybrid virtual-physical certification workflows converging computational biomechanics with physical dummy data streams. Acquisition target archetypes include modular data acquisition specialists and REACH-compliant polymer compounders. The signal to watch is Euro NCAP protocol update frequency accelerating replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | Bavaria-certified biofidelity validation reduces NHTSA submission bottlenecks for THOR-50M platforms. |
| REACH-Compliant Polymer Reformulation | Phthalate-free vinyl skin chemistry preserves EU certification supply chain access against Annex XVII restrictions. |
| Modular Sensor Retrofit Development | Aftermarket data acquisition architectures extend Hybrid III fleet utility amid Euro NCAP disqualification pressure. |
| Direct Automaker Framework Agreements | Stuttgart and Detroit OEM contracting collapses distributor margins while securing calibration priority access. |
| Hybrid Virtual-Physical Workflow Integration | Physics-based human body model convergence with physical dummy streams reduces per-test hardware wear. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with NHTSA regulatory affairs officers, Euro NCAP technical directors, Tier-1 automaker platform engineers, and calibration laboratory operations managers with secondary validation against NHTSA Federal Motor Vehicle Safety Standards filings, Euro NCAP protocol documentation, Japan's National Agency for Automotive Safety and Victim's Aid certification records, and vehicle production databases. Bottom-up dummy procurement volume estimates triangulated against top-down regulatory mandate timelines across the analysis window.
Segment-weighting approaches modeled product type fragmentation between THOR and Hybrid III architectures, application tiering across regulatory compliance and vehicle testing workflows, end-user concentration among automakers versus government agencies, and technology intensity gradients in digital sensor channel density. CAGRs were derived from regulatory mandate phase-in schedules and replacement cycle compression dynamics, with forecast inputs incorporating REACH chemical compliance burden trajectories and Bharat NCAP protocol evolution assumptions.
Inputs from NHTSA and Euro NCAP technical documentation were available through the study window; gaps in proprietary calibration laboratory throughput data introduce uncertainty bands around THOR platform adoption velocity assumptions. Forecasts reflect documented regulatory timelines and biofidelity validation bottlenecks. A model refresh is warranted upon material change in Euro NCAP protocol update cadence or NHTSA THOR mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Global Track Geometry Measurement System (TGMS) Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
Vehicle Crash Testing System Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
On Board Diagnostics Device Market