
 Vehicle Testing Equipment Market | 2026-2036
Vehicle Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Testing Equipment Market Analytics
Aluminum is decoupling from traditional cast-iron chassis dynamometer frames, cutting test rig weight and improving rotational inertia precision. AVL leverages captive foundry partnerships to control alloy sourcing for its roller assemblies. HORIBA anchors its position through deep specialization in emissions measurement cells for hybrid powertrains. Robert Bosch GmbH competes by extending its sensor calibration protocols across European OEM validation centers.
Vehicle testing equipment comprises dynamometers, emission analyzers, road simulators, and non-destructive inspection systems engineered to measure powertrain output, pollutant concentration, structural fatigue, and electronic control unit performance against certified protocols. These systems operate at temperature ranges from minus 40 to plus 60 degrees Celsius and simulate altitudes up to 5,000 meters to replicate real-world duty cycles. Emissions testing commands the largest installed base due to regulatory enforcement density, while software-based platforms represent the fastest-expanding technology category as virtual validation reduces physical prototype counts. Automotive manufacturing absorbs the majority of capital expenditure, though aftermarket services are gaining share as aging fleet testing mandates broaden.
EPA tailpipe standards and NHTSA safety certification requirements in the United States compel OEMs to maintain continuous test facility investment, while EMA Euro 7 drafts and REACH chemical restrictions in Europe reshape analyzer sensor specifications and materials compliance. China's MIIT enforces GB standards for new-energy vehicle homologation, forcing foreign suppliers to localize calibration capabilities. Stakeholders must weigh hardware deprecation cycles against software subscription economics as regulatory latency tightens between rule publication and enforcement activation.
Market Dynamics
Software-based diagnostic platforms are compressing capital deployment timelines by enabling virtual validation cycles that slash physical prototype requirements for powertrain certification.
Growth Catalysts
- Euro 7 readiness deadlines:German OEMs are expanding test cell capacity to meet EMA emissions thresholds, driving analyzer retrofit demand across European validation centers.
- MIIT certification mandates:China's eastern province clusters face compulsory new-energy vehicle homologation cycles, forcing localized calibration infrastructure buildouts.
- Aluminum roller assemblies:Lightweight alloy frames are improving rotational inertia precision in chassis dynamometers, displacing cast-iron construction in high-throughput facilities.
Market Restraints
- Sensor supply concentration:Emissions analyzer manufacturers depend on limited German and Japanese suppliers for NOx and particulate matter sensing elements.
- REACH chemical compliance:ECHA restrictions on sensor coatings and thermal materials are forcing reformulation of probe assemblies at elevated R&D cost.
- Hardware depreciation cycles:Test bench obsolescence accelerates as software validation platforms reduce physical asset utilization rates below amortization thresholds.
Strategic Opportunities
- Aftermarket fleet testing:Aging vehicle mandates in North America are broadening service bay demand for portable emission measurement systems.
- Hybrid powertrain specialization:Dual-mode validation protocols create white space for emissions cells capable of switching between electric and combustion duty cycles.
- Cloud-based calibration networks:Remote sensor recertification services enable suppliers to capture recurring revenue from distributed OEM validation sites.
Industry Challenges
- Embedded systems integration:Test equipment must interface with proprietary OEM electronic control unit architectures, creating protocol fragmentation and custom engineering overhead.
- Multi-standard certification timelines:Simultaneous EPA, EMA, and GB standard compliance compresses product launch windows and strains validation bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Testing Equipment Market |
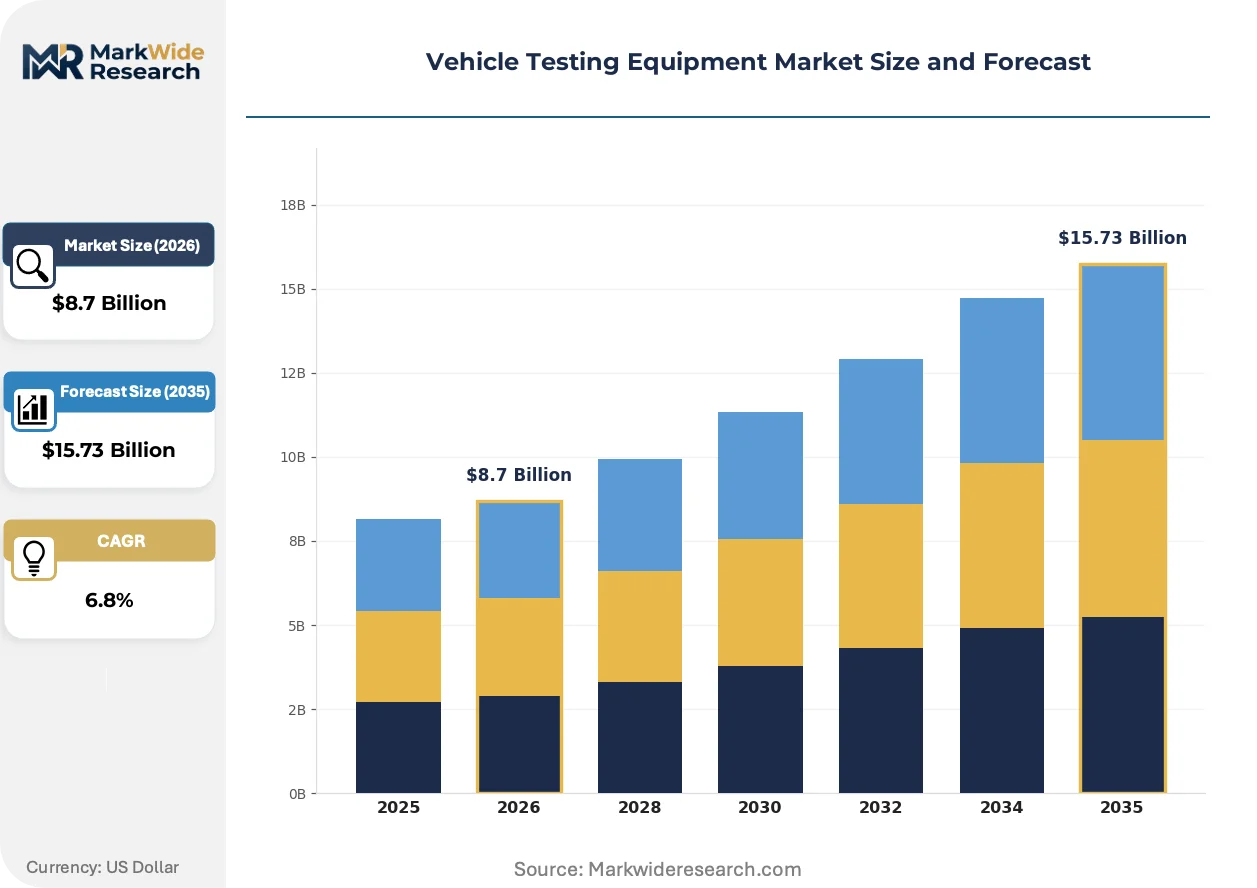
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emissions Testing, Dynamic Testing, Durability Testing, Environmental Testing Technology: Hydraulic, Electronic, Mechanical, Software-based Application: Automotive Manufacturing, Fleet Management, Research Institutions, Aftermarket Services End User: OEMs, Tier-1 Suppliers, Regulatory Bodies, Independent Testing Labs |
| Companies Covered | AVL, HORIBA, Robert Bosch GmbH, PHINIA Inc., Illinois Tool Works, Siemens, ABB, Honeywell International Inc., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Testing Equipment Market Evolving Landscape
Digital twin architectures and edge-computing diagnostics are collapsing the boundary between physical test cells and virtual validation environments, reshaping how OEMs stage certification workflows.
Model-based system testing is decentralizing powertrain validation by embedding simulation capabilities directly into supplier engineering workstations. Tier-1 component manufacturers in Michigan and Stuttgart are adopting these platforms to front-load calibration tasks before hardware prototypes arrive. This compression is reducing central test facility bottlenecks and redistributing analytical workload across distributed engineering networks.
EMA Euro 7 draft specifications are mandating real-driving emission monitoring with portable measurement devices, forcing analyzer suppliers to miniaturize hardware without sacrificing precision. The regulation requires continuous data logging under variable ambient conditions, which strains battery and thermal management in mobile units. European OEM validation centers are responding by retrofitting existing chassis dynamometers with hybrid simulation interfaces that bridge laboratory and on-road testing protocols.
North American fleet operators are unbundling after-sales service contracts from original equipment purchases, treating calibration and maintenance as separately procured commodities. This disintermediation pressures traditional suppliers to compete with independent service networks on response time and technician certification density. The pattern is most pronounced in California and Texas, where state-level emissions enforcement drives recurring certification demand across aging commercial vehicle populations.
Vehicle Testing Equipment Market Segmentation
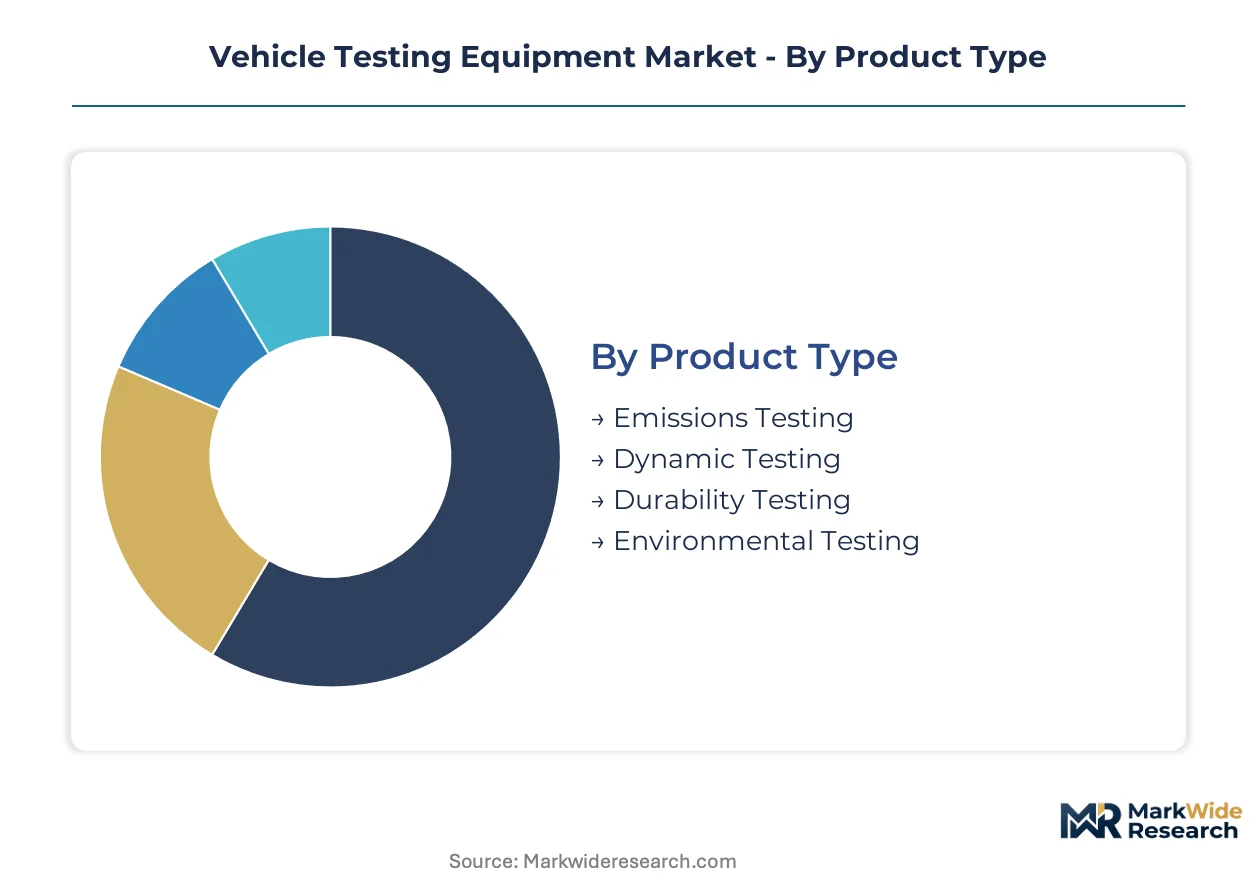
Equipment selection in this market hinges on regulatory certification requirements, powertrain complexity, and the trade-off between physical asset depreciation and software validation economics. Capital allocation patterns diverge sharply between OEM validation centers prioritizing throughput and aftermarket operators seeking portable, lower-investment alternatives.
Product Type:
Emissions testing systems command the heaviest upfront capital outlays due to analyzer precision requirements and continuous regulatory recalibration obligations.
- Emissions Testing:Analyzer cells measuring NOx, particulate matter, and CO2 concentrations operate at temperature ranges from minus 40 to plus 60 degrees Celsius with altitude simulation to 5,000 meters. EPA and EMA enforcement density concentrates demand in Michigan validation corridors and Stuttgart engineering clusters, where Euro 7 readiness deadlines are compressing retrofit timelines.
- Dynamic Testing:Chassis dynamometers and road simulators replicate real-world duty cycles for powertrain output verification. China's eastern province clusters absorb expanding capacity as MIIT mandates new-energy vehicle certification cycles with localized calibration infrastructure.
- Durability Testing:Structural fatigue benches subject components to accelerated lifecycle stress protocols. Fleet operators in California and Texas deploy these systems for aging commercial vehicle compliance under state-level emissions enforcement.
- Environmental Testing:Thermal chambers and altitude simulation units replicate extreme climate conditions. Research institutions leverage these for prototype validation before regulatory submission.
Emissions testing absorbs the bulk of installed capacity; software-integrated dynamic testing is expanding most quickly as virtual validation reduces physical prototype requirements.
Technology:
Technology selection determines operational flexibility, with electronic and software-based platforms enabling faster reconfiguration between certification protocols than fixed mechanical systems.
- Hydraulic:High-force actuation systems dominate durability and heavy-duty vehicle testing where mechanical load precision exceeds electronic alternatives. German OEM test cells retain hydraulic infrastructure for commercial vehicle powertrain validation.
- Electronic:Sensor-driven measurement platforms offer rapid calibration switching between EPA, EMA, and GB standard protocols. Tier-1 suppliers in Michigan and Stuttgart embed these capabilities into distributed engineering workstations.
- Mechanical:Fixed-frame roller assemblies and physical load applicators persist in high-throughput facilities with standardized test matrices. Cast-iron construction is yielding to aluminum frames for improved rotational inertia precision.
- Software-based:Model-based system testing embeds simulation capabilities directly into supplier engineering environments. This category is climbing the fastest as virtual validation front-loads calibration tasks before hardware prototypes arrive.
Electronic platforms anchor current installed base; software-based architectures are gaining share fastest as capital deployment timelines compress.
Application:
Application segmentation reflects divergent procurement authority, with automotive manufacturing centralizing capital decisions and aftermarket services fragmenting across independent service networks.
- Automotive Manufacturing:OEM validation centers maintain continuous test facility investment driven by NHTSA safety certification and EPA tailpipe standards. German manufacturers are expanding test cell capacity to meet EMA Euro 7 thresholds.
- Fleet Management:Commercial vehicle operators unbundle after-sales service contracts from original equipment purchases. North American fleet procurement treats calibration and maintenance as separately procured commodities.
- Research Institutions:Academic and government laboratories pursue pre-competitive validation protocols. These facilities bridge regulatory latency between rule publication and enforcement activation.
- Aftermarket Services:Independent testing networks compete on response time and technician certification density. Aging fleet mandates in North America broaden service bay demand for portable emission measurement systems.
Automotive manufacturing commands the largest capital expenditure share; aftermarket services are expanding most quickly as regulatory mandates broaden across aging vehicle populations.
End User:
End-user structure determines specification authority, with OEMs driving proprietary protocol requirements and regulatory bodies mandating interoperability standards.
- OEMs:Vehicle manufacturers specify embedded systems integration requirements that create protocol fragmentation. Custom engineering overhead accumulates from interfacing with proprietary electronic control unit architectures.
- Tier-1 Suppliers:Component manufacturers adopt model-based testing platforms to decentralize powertrain validation. These stakeholders front-load calibration tasks before hardware prototypes arrive at central facilities.
- Regulatory Bodies:EPA, EMA, and China's MIIT enforce multi-standard certification timelines that compress product launch windows. These entities mandate continuous data logging under variable ambient conditions.
- Independent Testing Labs:Third-party validation centers capture recurring revenue from distributed OEM sites through cloud-based calibration networks. Remote sensor recertification services enable geographic expansion without physical infrastructure replication.
OEMs absorb the majority of equipment procurement volume; independent testing labs are growing fastest as certification outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM validation centers concentrate the heaviest test cell investment as Euro 7 readiness deadlines compress retrofit timelines across Stuttgart and Munich engineering clusters.
United States
EPA tailpipe standards and NHTSA safety certification requirements compel continuous test facility investment across Michigan validation corridors. Detroit-area OEM centers absorb capital for powertrain homologation while California fleet operators drive aftermarket demand for portable emission measurement systems under state-level enforcement.
Germany
EMA Euro 7 draft specifications mandate real-driving emission monitoring with portable measurement devices. Stuttgart and Munich engineering clusters face analyzer retrofit demand as OEMs expand test cell capacity to meet emissions thresholds ahead of enforcement activation.
China
MIIT enforces GB standards for new-energy vehicle homologation across eastern province clusters. Shanghai and Jiangsu manufacturing corridors force foreign suppliers to localize calibration capabilities for compulsory certification cycles.
Japan
METI industrial standards and JIS certification protocols shape analyzer specifications for hybrid powertrain validation. Nagoya and Tokyo metropolitan areas concentrate Tier-1 supplier adoption of model-based testing platforms for distributed engineering networks.
India
BIS automotive testing norms and the PLI scheme for advanced chemistry cell manufacturing accelerate domestic validation infrastructure buildout. Tamil Nadu and Maharashtra industrial corridors attract emission analyzer deployment for local OEM homologation requirements.
Vehicle Testing Equipment Market Competitive Landscape
Capacity expansion dominates the current landscape as German and Japanese manufacturers scale test cell infrastructure to meet compressed regulatory deadlines. The vendor base organizes around three strategic archetypes: integrated automotive conglomerates with captive validation divisions, specialized measurement technology houses, and diversified industrial conglomerates with cross-sector sensor expertise. M&A activity and strategic technology licensing represent the dominant competitive vectors as players seek embedded systems integration capabilities.
Within the specialized measurement tier, AVL and HORIBA occupy positions defined by deep emissions testing specialization and captive foundry control over alloy sourcing. Robert Bosch GmbH exemplifies the integrated conglomerate archetype, leveraging sensor calibration protocol extension across European OEM validation centers. These three entities anchor the competitive structure through differentiated approaches to regulatory compliance bandwidth and hardware-software integration depth.
| Leading Market Players |
|---|
| AVL |
| HORIBA |
| Robert Bosch GmbH |
| PHINIA Inc. |
| Illinois Tool Works |
| Siemens |
| ABB |
| Honeywell International Inc. |
| Continental AG |
| Others |
Value Network & Pricing Analysis
Captive foundry partnerships anchor supply positioning and pricing power for roller assembly manufacturers serving chassis dynamometer producers. AVL's in-house alloy sourcing insulates margin structures from spot-market volatility while enabling premium positioning against competitors dependent on third-party metal procurement.
Pricing Analysis
Volume-scale buyers negotiate project-based equipment contracts while smaller aftermarket operators face SaaS-tiered diagnostic subscriptions. Certification-grade differentiation separates EPA-compliant analyzer cells from economy-tier portable units for fleet service bays. Cost compression in electronic sensor modules is intensifying because REACH reformulation expenses are transferring downstream. Aftermarket distributors exhibit highest price sensitivity; OEM validation centers prioritize throughput reliability over unit cost.
Supply Chain Analysis
MIIT domestic-content mandates are reshaping sourcing for foreign suppliers building calibration infrastructure in China's eastern provinces. Precision sensor elements concentrate in Germany and Japan; aluminum alloy feedstocks center on Chinese and Russian smelter output. Single-source vulnerability runs through NOx sensing element suppliers constrained by ECHA coating restrictions. Distribution feeds from integrated manufacturer-direct channels for OEMs and independent service networks for aftermarket fleet testing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
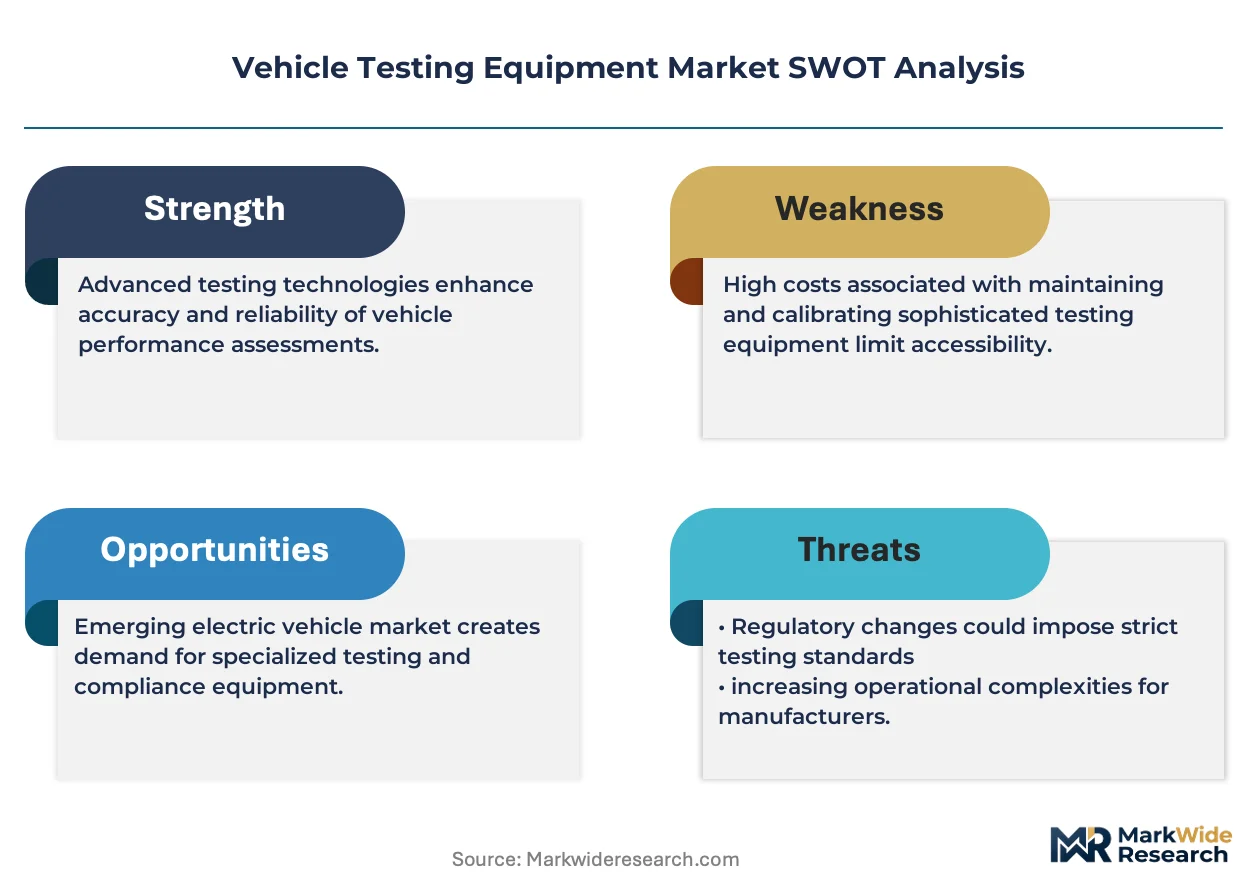
A vertical-integration race is compressing margin structures as players pursue captive control over sensor calibration protocols and alloy foundry capacity to defend against hardware deprecation cycles.
For Market Incumbents: Deploy cloud-based calibration networks to capture recurring revenue from distributed OEM validation sites before independent testing labs consolidate service relationships. Expand test cell capacity in Stuttgart and Munich engineering clusters ahead of EMA Euro 7 enforcement activation. Counter software-based platform substitution by embedding hardware-software bundles that lock in long-term maintenance contracts. For New Entrants and Emerging Players: Begin with portable emission measurement systems for North American fleet operators in California and Texas, where state-level enforcement broadens addressable demand beyond OEM procurement cycles. Target aftermarket service bay networks with technician certification density as the go-to-market wedge against established manufacturer-direct channels. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified industrial conglomerates seeking embedded systems integration capabilities. Five-to-ten year viability hinges on regulatory compliance bandwidth rather than pure hardware scale. Monitor EMA Euro 7 enforcement activation timelines as the critical inflection signal for valuation multiples in emissions testing specialization.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Captive aluminum alloy sourcing secures rotational inertia precision for chassis dynamometer roller assemblies against spot-price volatility. |
| Cloud Calibration Network Deployment | Remote sensor recertification services capture recurring revenue from EPA and EMA validation centers without physical infrastructure replication. |
| Hybrid Powertrain Cell Specialization | Dual-mode validation protocols address white space between electric and combustion duty cycles in Euro 7 readiness programs. |
| Software Platform Integration | Model-based testing front-loads calibration tasks before hardware prototypes arrive at central OEM facilities. |
| Aftermarket Service Network Buildout | Independent technician certification density competes with manufacturer-direct channels for aging fleet mandates in North America. |
Research Methodology
Independent corroboration across OEM platform engineers, Tier 1 supplier procurement leads, aftermarket service heads, and regulatory affairs specialists at EPA and EMA underwrites the qualitative findings. Secondary validation draws from vehicle production databases, SEC filings of listed equipment manufacturers, MIIT certification registries, and customs trade data for aluminum alloy and sensor element flows. Bottom-up equipment shipment analysis triangulates against top-down OEM capital expenditure disclosures.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation modeling incorporates equipment type, technology architecture, application vertical, and regional regulatory cluster dimensions. CAGRs derive from regression analysis of historical capital deployment patterns against regulatory deadline compression. Forecast inputs include Euro 7 enforcement timelines and MIIT localization mandates.
Underlying measurement precision varies by segment; emissions testing systems carry tighter precision than software-based platforms where virtual validation adoption curves remain heterogeneous. Forecasts reflect documented assumptions regarding regulatory latency between rule publication and enforcement activation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Electric Vehicle Test Equipment Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Testing Equipment Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
Railway Maintenance Machinery Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market