
 Vehicle Crash Testing Services Market | 2026-2036
Vehicle Crash Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Crash Testing Services Market Insights
A widening capability gap between full-scale proving ground operators and boutique simulation houses is rotating capital allocation toward integrated physical-digital test platforms. DEKRA SE leverages its sprawling German facilities to anchor European homologation workflows. Calspan Corporation sustains dominance in North American sled and barrier testing through decades of NHTSA contract execution. MGA Research Corporation specializes in niche component-level validation for defense and commercial vehicle crossover applications.
Vehicle crash testing services encompass controlled destructive and non-destructive evaluation of structural integrity, occupant protection systems, and active safety performance against standardized impact protocols using instrumented dummies, high-speed telemetry, and post-test metallurgical analysis. The primary purpose is generating homologation evidence for type approval and consumer safety ratings. Dynamic testing leads service revenue as full-vehicle frontal and side-pole impacts require the most extensive sensor arrays and facility reservation blocks. Electric vehicle testing represents the fastest-expanding segment as battery pack intrusion resistance demands novel barrier designs and thermal runaway monitoring protocols. Component testing occupies a mature margin pool where repeatability and ISO standard adherence command premium pricing from tier-one suppliers.
NHTSA's Federal Motor Vehicle Safety Standards and Euro NCAP's evolving assessment protocols jointly shape demand for simultaneous multi-jurisdiction testing campaigns. The EU AI Act and forthcoming type-approval frameworks for autonomous emergency braking are forcing service providers to integrate active safety validation into traditional crash programs. Stakeholders must monitor how regulatory divergence between NHTSA, Euro NCAP, and China's GB standards reshapes facility certification requirements and capital deployment priorities.
Market Dynamics
Physical-digital test platform convergence is compressing facility utilization cycles as manufacturers demand simultaneous virtual pre-screening and physical validation evidence for homologation workflows.
Growth Catalysts
- Euro NCAP pedestrian protection mandates:Active safety integration requirements are expanding test matrices beyond traditional structural impacts into vulnerable road user scenarios.
- Battery enclosure thermal runaway protocols:Electric vehicle manufacturers require novel barrier designs and specialized sensor arrays for lithium-ion pack intrusion resistance validation.
- Germany:DEKRA SE and TÜV SÜD operate major proving grounds that anchor European type-approval workflows and concentrate regional demand.
Market Restraints
- High-fidelity sensor array costs:Instrumented anthropomorphic test dummies and high-speed telemetry systems require substantial capital commitment per test cell.
- Facility geographic concentration:Major proving grounds cluster in Germany and the US Midwest, creating reservation bottlenecks during peak homologation windows.
- Regulatory divergence friction:NHTSA Federal Motor Vehicle Safety Standards and Euro NCAP protocol misalignment forces redundant test campaigns for multi-jurisdiction certification.
Strategic Opportunities
- India:BIS automotive safety standard adoption and domestic manufacturing incentives are creating demand for localized crash test infrastructure.
- Autonomous emergency braking validation:The EU AI Act and forthcoming type-approval frameworks require active safety integration into traditional crash programs.
- Virtual-physical hybrid workflows:Finite element pre-simulation is converging with sled testing to compress development cycles before full-vehicle barrier impacts.
Industry Challenges
- Metallurgical analysis talent scarcity:Post-test forensic expertise in fracture mechanics and high-strain-rate material behavior is concentrated among aging specialist cohorts.
- Multi-protocol certification timelines:Simaneous NHTSA, Euro NCAP, and GB standards compliance requires sequential facility booking and extended program management.
- Legacy facility retrofit costs:Existing sled tracks and barrier systems require modification for electric vehicle battery pack testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Crash Testing Services Market |
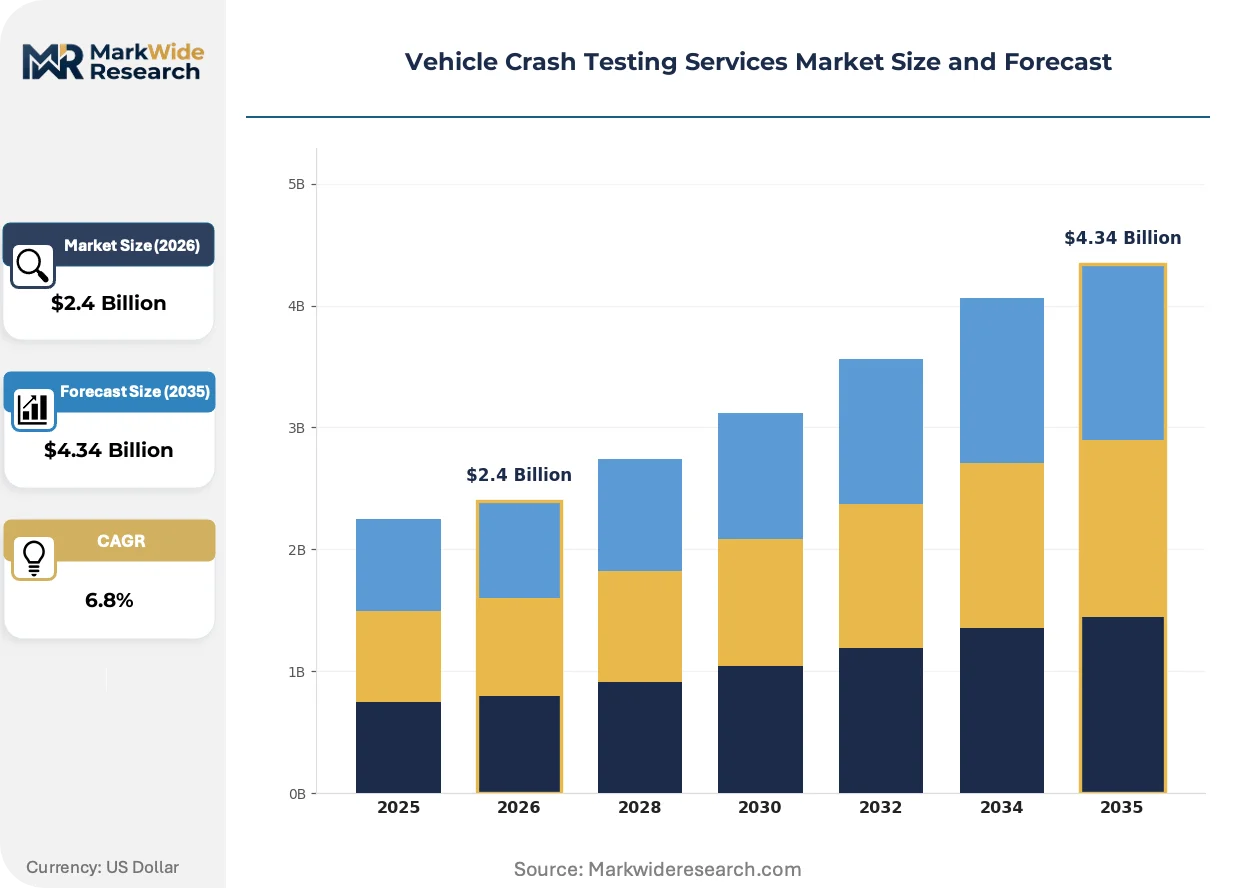
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dynamic Testing, Static Testing, Component Testing, Frontal Impact Testing Client Type: Automotive Manufacturers, Research Institutions, Regulatory Bodies, Aftermarket Providers Testing Standard: NCAP, IIHS, ISO, Euro NCAP Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, SUVs |
| Companies Covered | Applus+ IDIADA, Calspan Corporation, MGA Research Corporation, DEKRA SE, TÜV SÜD, Transportation Research Center Inc., Horiba MIRA Ltd., Millbrook Proving Ground, UTAC CERAM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Crash Testing Services Market Trends and Innovations
Computational pre-validation is displacing physical test volume as finite element models achieve predictive correlation sufficient for regulatory pre-approval.
Digital twin crash simulation is decomposing traditional full-vehicle test schedules into modular component validations. Tier-one suppliers now run virtual pre-screening for intrusion and occupant kinematics before reserving physical sled time. This compression is enabling faster iteration cycles while reducing per-program barrier impact counts.
Euro NCAP's 2026 active safety roadmap is mandating vulnerable road user detection and autonomous emergency braking performance as rating prerequisites. Test service providers must integrate pedestrian target systems and ADAS sensor calibration into frontal impact protocols. Battery electric vehicle manufacturers face the steepest compliance curve as thermal runaway monitoring joins structural integrity assessment.
Buyer consolidation among electric vehicle startups is concentrating procurement with integrated platform providers capable of simultaneous multi-jurisdiction homologation. Boutique simulation houses are losing share to full-service operators with captive proving ground access. Germany and the US Midwest remain the primary geographies where this consolidation is most visible, though India and China's domestic certification growth is fragmenting the historical duopoly.
Vehicle Crash Testing Services Market Segmentation
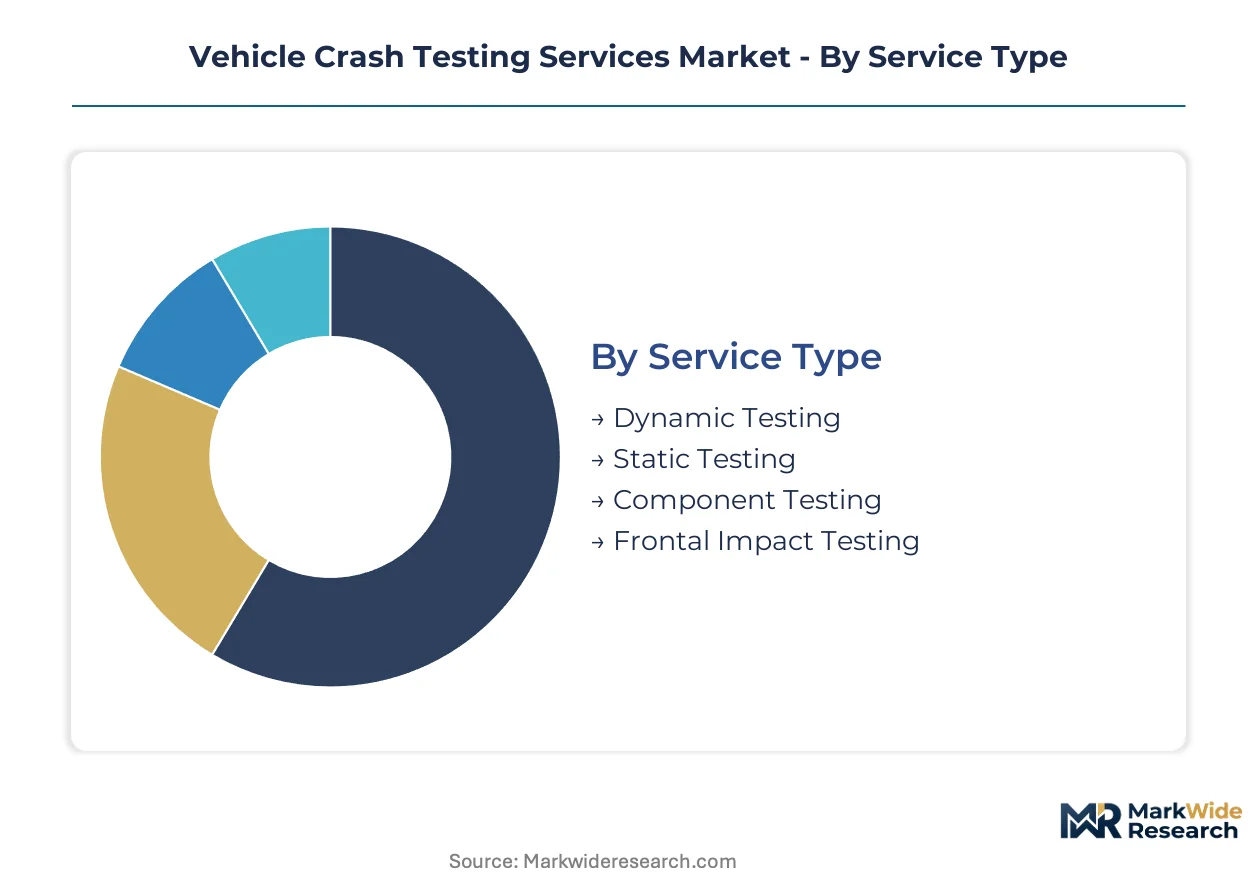
Crash testing services fragment across service modalities, client procurement patterns, regulatory frameworks, and vehicle architectures. Each dimension shapes facility utilization rates, capital requirements, and margin structures differently. Procurement flows through distinct channels depending on whether validation serves homologation, research, or aftermarket retrofit purposes.
Service Type:
Channel mix varies sharply by service modality, with dynamic testing commanding premium facility blocks while static and component work flows through distributed laboratory networks.
- Dynamic Testing:Full-vehicle barrier impacts, sled deceleration runs, and rollover simulations require instrumented dummies, high-speed telemetry, and dedicated proving ground access. Automotive manufacturers in Germany and the US Midwest concentrate procurement here for NHTSA and Euro NCAP homologation evidence. Reservation bottlenecks peak during model-year certification windows.
- Component Testing:Airbag module validation, seat anchorage assessment, and steering column intrusion resistance operate through ISO-accredited laboratories with shorter turnaround cycles. Tier-one suppliers in Michigan and Baden-Württemberg dominate procurement for repeatability-dependent margin pools.
- Static Testing:Door crush resistance, roof strength, and seatbelt anchorage evaluations use hydraulic presses and slow-rate load frames without dynamic facility requirements.
- Frontal Impact Testing:Offset deformable barrier and full-width rigid wall protocols anchor consumer safety ratings and regulatory compliance workflows.
By volume, Component Testing leads due to supplier-tier repeat programs. By growth pace, Dynamic Testing is ahead on electric vehicle battery enclosure validation demand.
Client Type:
Cost tier stratification separates capital-intensive proving ground relationships from budget-constrained research and aftermarket procurement.
- Automotive Manufacturers:OEMs maintain multi-year framework agreements with integrated platform providers for simultaneous NHTSA, Euro NCAP, and GB standards compliance. Procurement concentrates with operators possessing captive sled tracks and barrier engineering capabilities.
- Research Institutions:Universities and government laboratories access shared research infrastructure through consortium memberships and grant-funded facility time. The US Department of Transportation and Germany's KBA sponsor validation programs here.
- Regulatory Bodies:NHTSA, Euro NCAP, and China's CATARC contract external facilities for protocol development and spot-check auditing.
- Aftermarket Providers:Seat retrofitters, armor installers, and accessibility equipment vendors seek one-off validation for niche compliance claims.
By revenue concentration, Automotive Manufacturers dominate facility bookings. By procurement flexibility, Research Institutions are expanding fastest through government-funded electrification safety programs.
Testing Standard:
Application-specific protocol selection determines sensor array specifications, dummy calibration requirements, and post-test documentation depth.
- Euro NCAP:Vulnerable road user protection and active safety integration mandates expand test matrices beyond structural impacts into pedestrian target scenarios and autonomous emergency braking validation. European OEMs anchor procurement here.
- NHTSA:Federal Motor Vehicle Safety Standards govern US type approval with emphasis on full-width frontal and side pole impacts. Domestic manufacturers and import homologation specialists drive volume.
- IIHS:Insurance industry-funded consumer information programs emphasize small overlap frontal and moderate overlap crashworthiness for US market positioning.
- ISO:International standardization protocols enable component-level supplier certification across jurisdictions with harmonized repeatability requirements.
By protocol complexity, Euro NCAP leads with expanding active safety integration. By geographic reach, ISO is gaining share fastest through supplier-tier globalization.
Vehicle Type:
Supply concentration aligns with manufacturing geography, with electric vehicle testing infrastructure retrofitting legacy facilities originally built for internal combustion platforms.
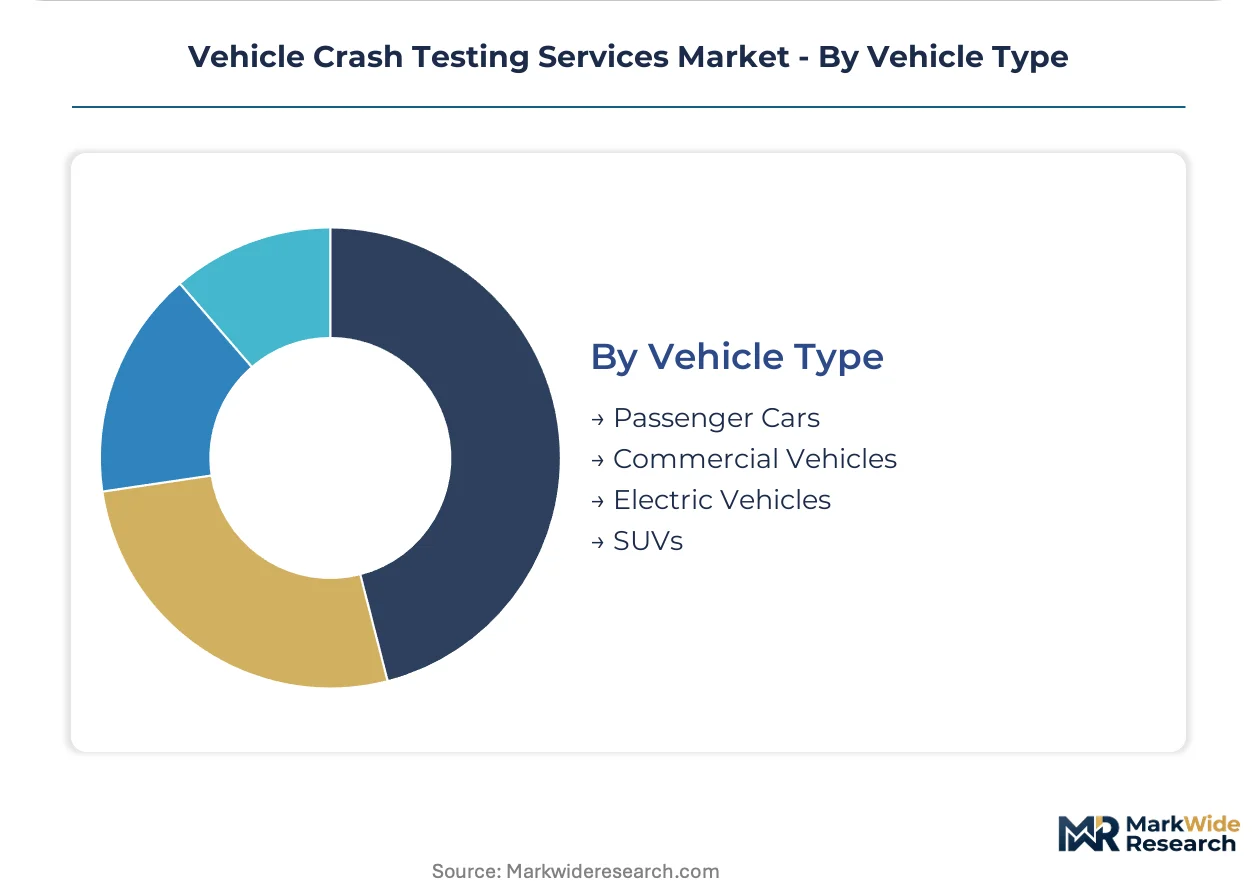
- Electric Vehicles:Battery pack intrusion resistance, thermal runaway monitoring, and high-voltage isolation validation demand novel barrier designs and specialized sensor arrays. Manufacturers in California, Shanghai, and Stuttgart concentrate procurement for platform-specific homologation.
- Passenger Cars:High-volume C-segment and D-segment models generate recurring frontal offset and side pole test schedules for consumer safety rating optimization.
- SUVs:Higher mass and elevated ride height alter barrier interaction kinematics and pedestrian impact severity profiles.
- Commercial Vehicles:Heavy-duty cab integrity and underride guard testing follow distinct NHTSA and UN ECE regulatory tracks with specialized dummy configurations.
By facility retrofit investment, Electric Vehicles command the steepest capital allocation. By test volume stability, Passenger Cars maintains the most predictable scheduling patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where DEKRA SE and TÜV SÜD command premium facility rates for Euro NCAP homologation, while Indian operators compete on cost for emerging BIS compliance workflows. This asymmetry shapes capital deployment toward proven European infrastructure versus speculative Asian expansion.
United States
NHTSA Federal Motor Vehicle Safety Standards drive continuous demand for full-width frontal and side pole validation at Transportation Research Center Inc. facilities in Ohio. The US Department of Transportation funds research programs that sustain shared infrastructure access for domestic manufacturers. Calspan Corporation anchors North American sled and barrier testing through decades of federal contract execution in Buffalo, New York.
Germany
Euro NCAP pedestrian protection mandates and active safety integration requirements expand test matrices beyond structural impacts into vulnerable road user scenarios. KBA sponsorship validates protocol development programs at DEKRA SE's sprawling proving grounds. Stuttgart and Munich clusters concentrate procurement from Daimler, BMW, and Porsche for simultaneous type-approval workflows.
China
GB standards divergence from NHTSA and Euro NCAP protocols forces redundant test campaigns for multi-jurisdiction certification of export-bound vehicles. MIIT oversees domestic type-approval frameworks that increasingly incorporate battery electric vehicle thermal runaway monitoring. Shanghai and Yangtze River Delta manufacturing bases drive localized infrastructure investment for lithium-ion pack intrusion resistance validation.
India
BIS automotive safety standard adoption and domestic manufacturing incentives under the PLI scheme create demand for localized crash test infrastructure. The Ministry of Road Transport and Highways mandates frontal offset and side impact compliance for new vehicle launches. Tamil Nadu and Maharashtra clusters attract facility investment as Maruti Suzuki, Tata Motors, and Mahindra expand validation programs.
Japan
METI coordinates harmonization efforts between domestic JIS standards and evolving UN ECE regulations to reduce redundant testing burdens. PMDA-aligned research institutions access shared proving ground infrastructure for advanced occupant protection development. Nagoya and Tokyo manufacturing corridors sustain steady demand for component-level airbag and seat anchorage validation.
Vehicle Crash Testing Services Market Competitive Landscape
Concentration sits with integrated platform providers possessing captive proving ground access and multi-jurisdiction certification capabilities. Boutique simulation houses are losing procurement share as electric vehicle startup consolidation favors full-service operators. Three archetypes dominate: legacy proving ground operators with decades of regulatory contract execution, tier-one supplier-focused component laboratories emphasizing ISO repeatability, and emerging hybrid virtual-physical platforms compressing development cycles. Dominant competitive moves include facility retrofit investment for battery electric vehicle protocols and strategic partnerships bundling physical testing with finite element pre-simulation services.
Within the integrated platform tier, DEKRA SE and TÜV SÜD represent the European homologation anchor through their German proving ground dominance. Calspan Corporation exemplifies the North American federal contract archetype with sustained NHTSA relationship execution. MGA Research Corporation occupies a specialist position spanning defense and commercial vehicle crossover applications with niche component-level capabilities.
| Leading Market Players |
|---|
| Applus+ IDIADA |
| Calspan Corporation |
| MGA Research Corporation |
| DEKRA SE |
| TÜV SÜD |
| Transportation Research Center Inc. |
| Horiba MIRA Ltd. |
| Millbrook Proving Ground |
| UTAC CERAM |
| Others |
Pricing and Supply Chain Analysis
Virtual pre-screening substitution for physical barrier impacts is redrawing supply geography toward finite element software hubs in California and Stuttgart while compressing pricing premiums for legacy proving ground blocks. This displacement simultaneously elevates rates for integrated virtual-physical platforms and erodes standalone sled facility margins.
Pricing Analysis
The customization-premium spread separates configured-to-order electric vehicle battery validation programs from standard frontal offset compliance packages. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity, with Euro NCAP active safety integration commanding top rates. Pricing pressure stems from virtual pre-simulation reducing physical test volume for repeat component programs. Tier-one suppliers exhibit highest price sensitivity, while OEMs pursuing simultaneous multi-jurisdiction homologation show lowest.
Supply Chain Analysis
Just-in-time facility reservation patterns dominate automotive manufacturer procurement, though strategic stockpiling of sensor arrays and instrumented dummies buffers against Euro NCAP protocol update cycles. Supply concentrates in Germany, the United States, and China, with specialized barrier engineering drawing from steel fabrication in Austria, high-speed camera systems from Japan, and lithium-ion thermal monitoring equipment from South Korea. Single-source vulnerability sits with hydroformed aluminum barrier suppliers. Distribution runs through multi-year framework agreements rather than spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against virtual simulation platforms capturing pre-validation volume before physical testing commitment. Finite element correlation accuracy improvements threaten to displace low-complexity sled programs entirely.
For Market Incumbents: Secure captive proving ground access through long-term lease structures or acquisition of distressed regional facilities. Deepen backward integration into finite element pre-simulation services to capture volume upstream of physical validation commitment. Battery electric vehicle thermal runaway protocols represent the critical certification lever for margin defense against pure-play simulation houses.
For New Entrants and Emerging Players: Lead with India BIS compliance infrastructure buildout as domestic manufacturing incentives concentrate validation demand in Tamil Nadu and Maharashtra. Target aftermarket armor retrofitters and accessibility equipment vendors underserved by major proving ground operators. Position around rapid turnaround component testing for tier-one supplier repeat programs rather than full-vehicle barrier competition.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated platform providers possessing simultaneous NHTSA-Euro NCAP-GB certification capabilities and captive sled track access. Long-term viability favors operators with battery electric vehicle protocol retrofit completion and active safety validation integration. Watch Euro NCAP 2026 roadmap implementation velocity as inflection indicator for facility utilization recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Electric Vehicle Protocol Retrofit | Thermal runaway monitoring and high-voltage isolation validation commands premium facility rates from Stuttgart OEMs. |
| Virtual-Physical Hybrid Workflow Integration | Finite element pre-simulation bundling compresses development cycles and anchors multi-year OEM framework agreements. |
| India Proving Ground Infrastructure Buildout | BIS standard adoption and PLI scheme incentives localize compliance demand away from German reservation bottlenecks. |
| Active Safety Validation Capability Addition | Pedestrian target systems and autonomous emergency braking integration meet Euro NCAP 2026 rating prerequisites. |
| Multi-Jurisdiction Certification Harmonization | Simultaneous NHTSA, Euro NCAP, and GB standards compliance reduces redundant test campaigns for export-bound manufacturers. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings on protocol evolution and facility investment patterns. Conversations with OEM platform engineers, tier-one supplier procurement leads, proving ground operations directors, and NHTSA contract administrators combined with Euro NCAP technical bulletins, UN ECE regulatory updates, and KBA type-approval databases. Bottom-up facility utilization modeling and top-down automotive production forecasting triangulate market sizing.
Sensitivity analysis around electric vehicle penetration rates and virtual simulation adoption curves stress-tests projection robustness across the analysis window. Segmentation dimensions include service modality, client procurement tier, testing standard jurisdiction, and vehicle propulsion architecture. CAGRs derive from facility reservation trend extrapolation and capital expenditure pipeline tracking. Battery pack intrusion resistance protocol development and metallurgical analysis talent availability constitute industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained regulatory divergence or accelerated virtual correlation breakthroughs would require recalibration. Forecasts reflect assumptions on homologation timeline stability and proving ground certification retention. Revision becomes warranted when Euro NCAP protocol update frequency or NHTSA contract reallocation crosses threshold disruption levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Autonomous Valet Parking System Scenario-Based Test Equipment Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Automotive TIC Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Vehicle Scanner Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Electric Vehicle Test Bench Market