
 Drilling and Completion Fluids Market | 2026-2036
Drilling and Completion Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Drilling and Completion Fluids Market Intelligence
API Specification 13A certification is unwinding the competitive landscape for drilling fluid suppliers, raising barriers for regional blenders without in-house testing laboratories. Schlumberger Limited leverages its integrated drilling systems portfolio to bundle fluid services with directional drilling contracts. Baker Hughes Co. anchors its position through proprietary synthetic base fluid technologies developed for high-pressure high-temperature wells. Halliburton Co. competes by controlling barite sourcing through captive mining operations in Nevada and Peru.
Drilling and completion fluids are engineered liquid and slurry systems, typically formulated with weighted clays, polymers, and brines at densities ranging from 8.3 to 22 pounds per gallon, circulated through the borehole to transport cuttings, stabilize formation pressure, and cool the drill bit. Their primary commercial purpose is to maintain wellbore integrity across diverse geological conditions while minimizing non-productive time. Water-based fluids occupy the largest volume share due to lower disposal costs and regulatory acceptance, while synthetic fluids command premium positioning in deepwater and HPHT applications where thermal stability determines operational success. The additive segment concentrates margin pools in viscosifiers and fluid loss additives, as these chemistries require continuous replenishment throughout the drilling cycle.
EPA effluent guidelines and OSHA workplace exposure limits shape formulation choices in the United States, while REACH compliance in Europe restricts certain chrome lignosulfonate chemistries. The BSEE well control regulations in the Gulf of Mexico mandate real-time fluid monitoring, creating demand for automated mud property sensors. Operators and service companies must evaluate how pending PFAS restrictions across multiple jurisdictions will affect legacy synthetic base fluid chemistries and whether bio-derived alternatives can deliver equivalent rheological performance without triggering new regulatory categories.
Market Dynamics
EPA effluent limitation guidelines are forcing operators to abandon legacy synthetic base fluids in favor of water-based formulations with lower toxicity profiles, compressing margins for suppliers dependent on premium synthetic chemistries.
Growth Catalysts
- Deepwater Development Surge:Petrobras continues aggressive field development in Brazil's pre-salt basins, expanding consumption of high-performance synthetic-based fluids for ultra-deepwater wells.
- BSEE Real-Time Monitoring Mandate:Gulf of Mexico well control regulations now require automated mud property sensors, creating pull-through demand for integrated fluid monitoring systems.
- HPHT Well Proliferation:High-pressure high-temperature drilling in the Gulf of Mexico and West Africa is accelerating adoption of thermally stable synthetic formulations.
Market Restraints
- Barite Supply Concentration:Nevada and Peru host the majority of API-grade barite mining operations, creating geographic chokepoints for weighted fluid density additives.
- PFAS Regulatory Uncertainty:Pending restrictions across multiple jurisdictions threaten legacy synthetic base fluid chemistries without clear bio-derived replacement pathways.
- Chrome Lignosulfonate Bans:REACH compliance in Europe restricts certain dispersant chemistries, forcing reformulation of established fluid systems.
Strategic Opportunities
- Pre-Salt Basin Expansion:Brazil's ultra-deepwater fields remain underpenetrated by independent fluid service providers outside integrated oilfield service contracts.
- Bio-Derived Base Fluids:Ester-based synthetic alternatives developed from renewable feedstocks offer regulatory tailwind positioning ahead of PFAS restrictions.
- Automated Mud Labs:Remote testing facilities co-located with drilling operations enable real-time formulation adjustments without centralized laboratory delays.
Industry Challenges
- API 13A Certification Bottleneck:Regional blenders without in-house testing laboratories face extended timelines for product qualification.
- Rheological Performance Gap:Bio-derived alternatives struggle to match the thermal stability and lubricity of petroleum-based synthetics in HPHT conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drilling and Completion Fluids Market |
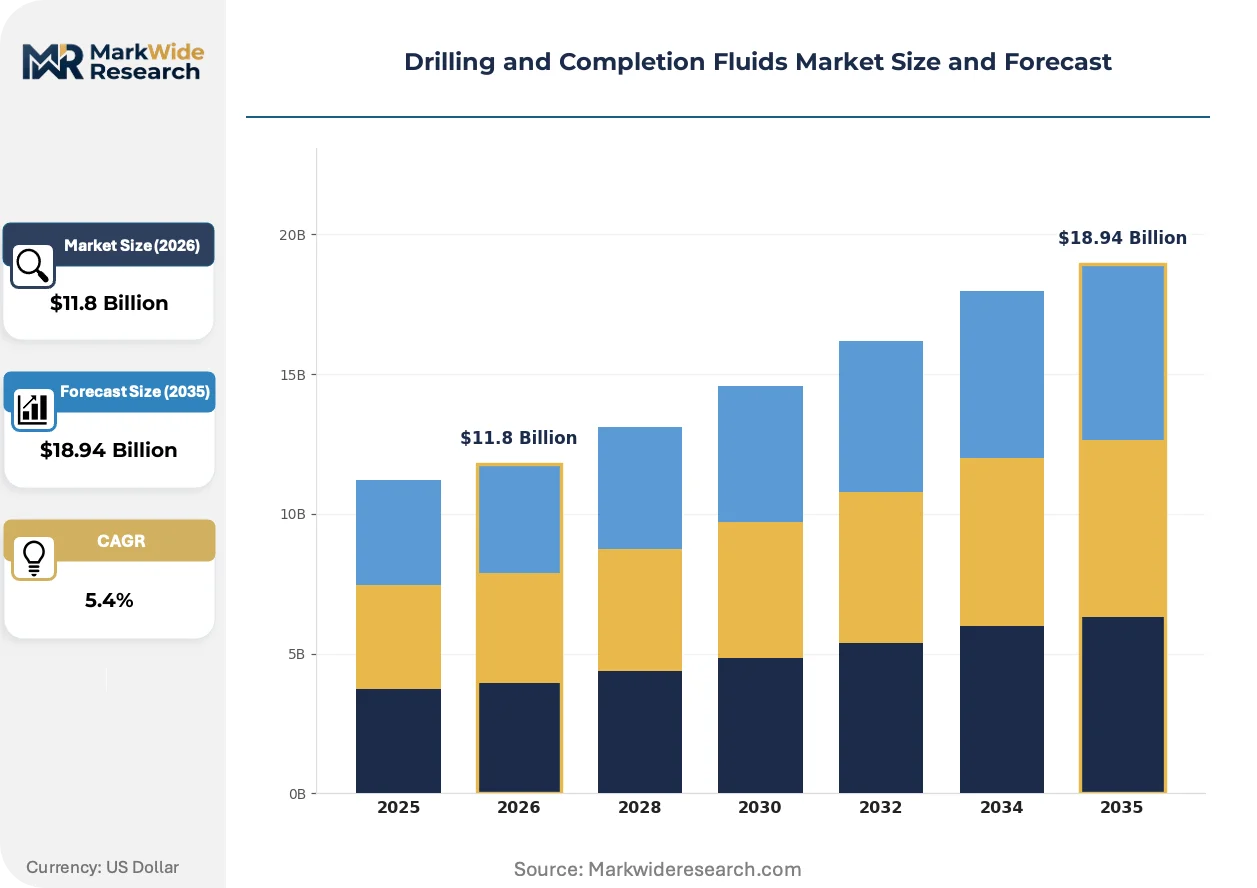
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fluid Type: Water-Based, Oil-Based, Synthetic, Foam Additive Type: Viscosifiers, Lubricants, Corrosion Inhibitors, Fluid Loss Additives Application: Onshore, Offshore, Well Drilling, Completion Operations End User: Oil & Gas Companies, Drilling Contractors, Service Companies, Research Institutions |
| Companies Covered | Schlumberger Limited, Baker Hughes Co., Halliburton Co., Newpark Resources Inc., CES Energy Solutions Corp., NOV Inc., TETRA Technologies Inc., Weatherford International Plc, Chevron Phillips Chemical Co. LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drilling and Completion Fluids Market Strategic Shifts & Innovations
Formulation science is decomposing the traditional synthetic-water-based binary, with hybrid systems and bio-derived chemistries fragmenting established product categories. Real-time monitoring hardware and predictive analytics are embedding into fluid management workflows.
Nanoparticle-enhanced drilling fluids are decomposing conventional viscosifier economics. Operators in the Gulf of Mexico and West Africa deepwater segments are piloting silica and graphene oxide additives at accelerating trial frequency. These materials reduce equivalent circulating density while maintaining suspension properties, compressing the volume of barite and bentonite required per well.
REACH authorization requirements are reshaping additive sourcing patterns for European operators. Chrome lignosulfonate dispersants face sunset dates, forcing service companies to qualify alternative chemistries through ECHA substance evaluation. The additive segment is responding with synthetic polymer substitutes, though these carry 15-30% cost premiums that concentrate margin pressure on independent drilling contractors.
Integrated service bundling is consolidating procurement decisions around directional drilling contracts rather than standalone fluid supply. National oil companies in Brazil and West Africa are consolidating vendor lists, awarding multi-year integrated drilling services agreements that subsume fluid formulation within broader performance guarantees. This concentrates purchasing authority with integrated oilfield service providers and compresses addressable market for standalone fluid specialists.
Drilling and Completion Fluids Market Segmentation
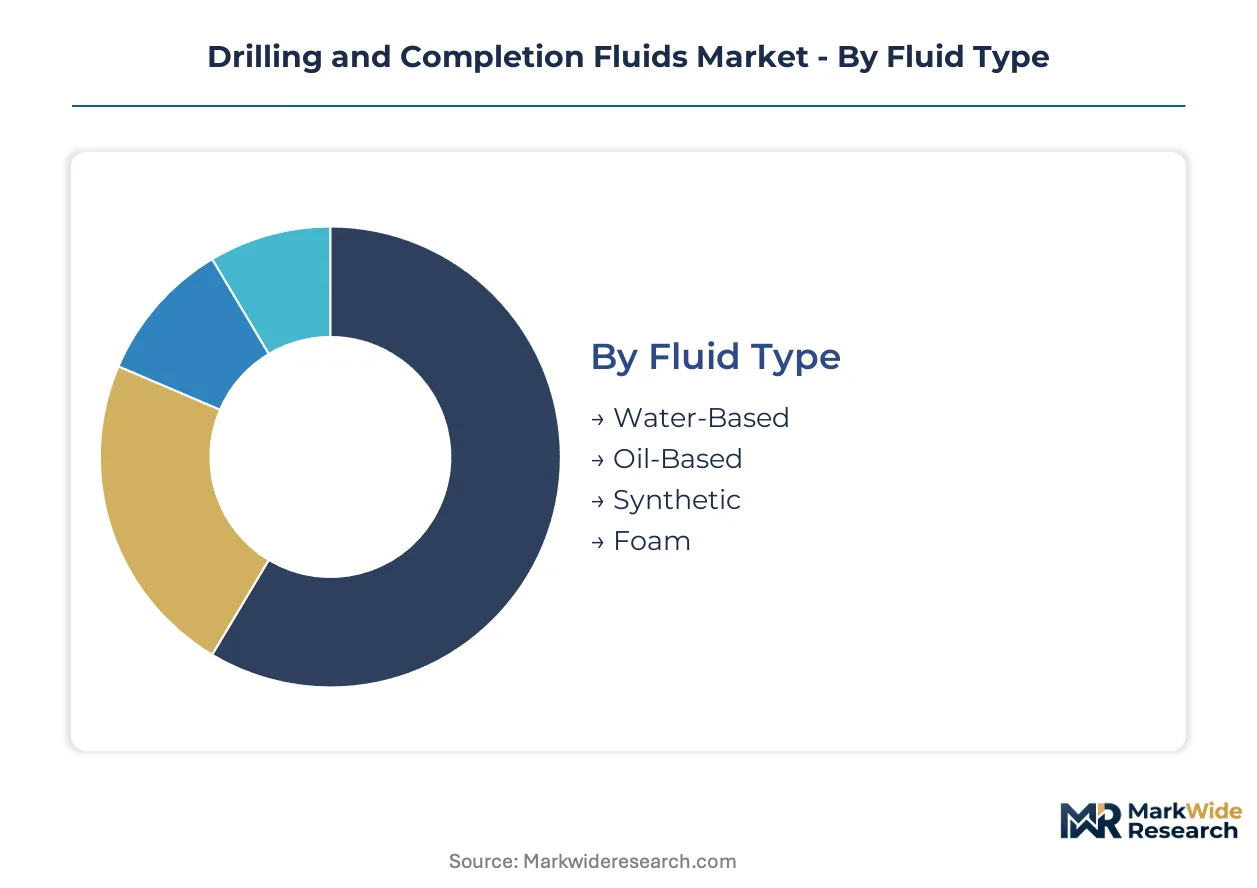
Fluid segmentation determines procurement channel access and margin structure. Water-based formulations flow through commodity distributors while synthetic systems require direct technical service relationships. Additive chemistry choices lock operators into specific supply chains with varying degrees of captive sourcing.
Fluid Type:
Channel mix varies sharply by fluid chemistry. Water-based systems move through regional blenders and bulk distributors. Synthetic formulations require integrated service company deployment with on-site engineering support.
- Water-Based:Bentonite and polymer suspensions in aqueous brines dominate land drilling procurement. Demand concentrates in Permian Basin onshore operations where disposal cost sensitivity outweighs performance premiums. EPA effluent guidelines reinforce this channel's regulatory advantage.
- Synthetic:Ester and olefin-based formulations engineered for thermal stability above 350°F anchor deepwater service contracts. Brazil's pre-salt basins and Gulf of Mexico ultra-deepwater wells drive procurement through integrated drilling packages.
- Oil-Based:Diesel and mineral oil continuous-phase systems retain niche positions in water-sensitive shales. Cuttings disposal restrictions compress addressable market outside regions with thermal treatment infrastructure.
- Foam:Nitrogen or air-liquid mixtures for underbalanced drilling and lost circulation scenarios. Specialized compressor logistics limit channel penetration to major service company networks.
Water-based fluids dominate installed base. Synthetic formulations are where expansion concentrates.
Additive Type:
Cost tier stratification separates consumable replenishment chemicals from capital-intensive base fluid systems. Viscosifiers and fluid loss additives generate recurring revenue streams. Corrosion inhibitors and lubricants attach to premium contract tiers.
- Viscosifiers:Xanthan gum, cellulose derivatives, and synthetic polymers that elevate low-shear viscosity for cuttings suspension. Continuous replenishment cycles through the drilling window create pull-through demand for automated mud plant infrastructure.
- Fluid Loss Additives:Starch, polyanionic cellulose, and synthetic polymer filtrate control agents. HPHT well proliferation in West Africa and Gulf of Mexico drives specification escalation toward synthetic chemistries with 400°F stability ratings.
- Lubricants:Ester and amide-based friction reducers for extended-reach drilling. Torque reduction specifications in directional wells command 20-40% cost premiums over base fluid pricing.
- Corrosion Inhibitors:Amine and phosphate ester chemistries protecting casing strings in sour gas environments. H2S-bearing formations in Middle Eastern and Caspian fields determine regional formulation requirements.
Viscosifiers anchor volume throughput. Fluid loss additives capture the steepest expansion trajectory.
Application:
Customer type segmentation separates procurement authority between operator direct purchasing and drilling contractor bundled services. Offshore applications concentrate buying power with integrated service providers. Onshore land drilling fragments across independent contractors.
- Onshore:Land drilling operations across Permian, Bakken, and Vaca Muerta formations. Independent drilling contractors with 10-50 rig fleets drive spot market purchasing for water-based systems.
- Offshore:Platform and drillship operations in Brazil, Gulf of Mexico, and West Africa. Petrobras and supermajor operators consolidate procurement through multi-year integrated drilling contracts.
- Well Drilling:Spud through total depth fluid services encompassing hole cleaning, pressure management, and formation evaluation. Real-time monitoring mandates from BSEE reshape service delivery models.
- Completion Operations:Post-drilling displacement to brines and packer fluids for production liner installation. Workover and recompletion activity generates secondary demand cycles distinct from drilling programs.
Onshore operations dominate rig count. Offshore applications concentrate revenue per well.
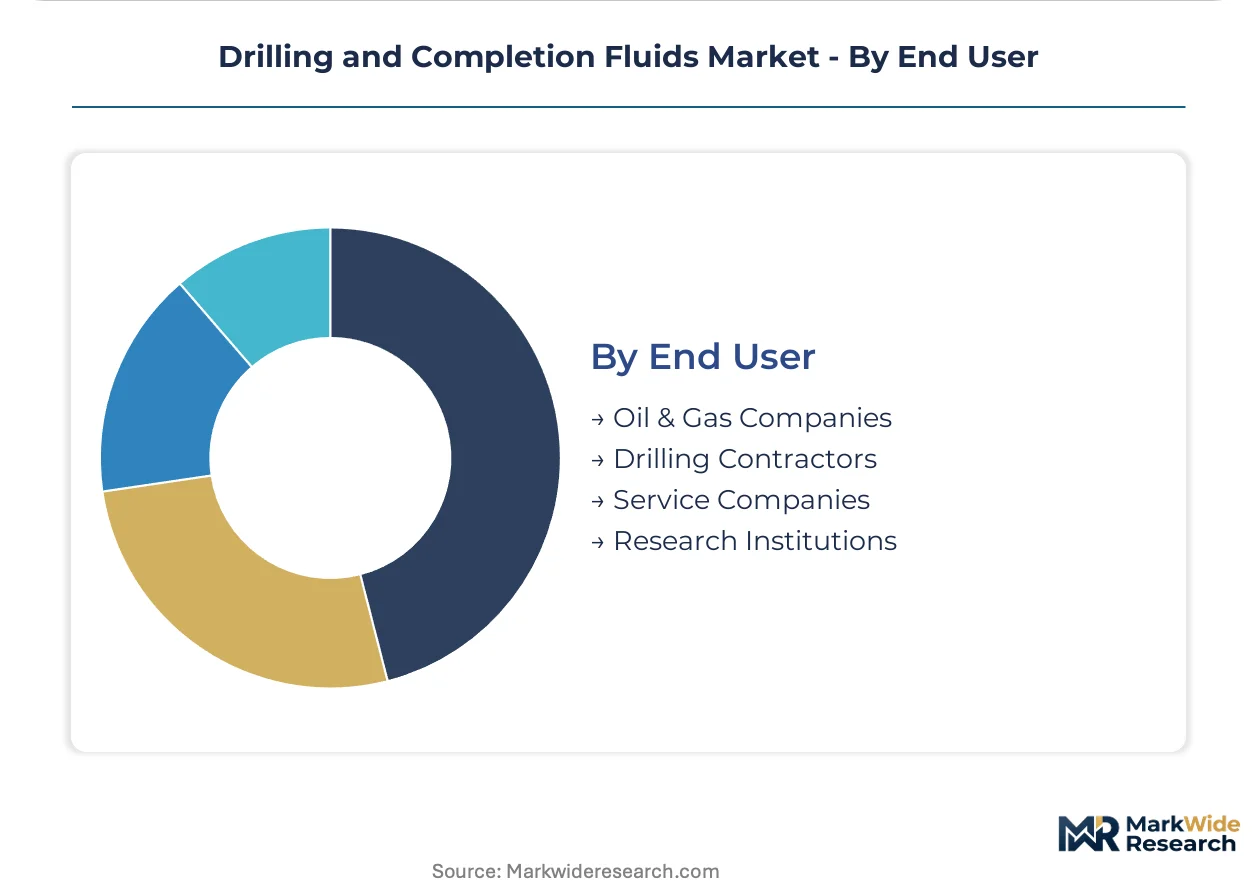
End User:
Supply concentration varies by buyer sophistication. National oil companies and supermajors maintain direct supplier relationships. Independent operators delegate procurement to drilling contractors.
- Oil & Gas Companies:Supermajors and national oil companies with in-house drilling engineering capabilities. Saudi Aramco and ExxonMobil specify fluid formulations directly and audit supplier laboratories.
- Drilling Contractors:Nabors, Helmerich & Payne, and regional independents bundling fluid supply into dayrate contracts. Margin pressure drives preference for commodity water-based systems with minimal technical service overhead.
- Service Companies:Schlumberger, Baker Hughes, and Halliburton integrating fluid formulation within directional drilling and logging-while-drilling packages. Technology differentiation concentrates in synthetic base fluid intellectual property.
- Research Institutions:University drilling research programs and national laboratory consortia. Limited procurement volume but disproportionate influence on regulatory acceptance pathways for novel chemistries.
Drilling contractors dominate transaction volume. Service companies capture technology premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent limitation guidelines and BSEE well control mandates are reshaping formulation procurement across major drilling jurisdictions. Petrobras pre-salt development contracts and West African deepwater awards concentrate synthetic fluid demand in specific basins.
United States
Gulf of Mexico ultra-deepwater projects drive synthetic-based fluid consumption for HPHT wells. BSEE real-time monitoring regulations mandate automated mud property sensors on all offshore operations. Houston anchors the largest concentration of fluid service company headquarters and technical laboratories.
Brazil
Pre-salt basin development by Petrobras consumes premium synthetic formulations for wells exceeding 20,000 feet true vertical depth. ANP local content requirements mandate domestic blending capacity for offshore service contracts. Macaé and Rio de Janeiro host the primary supply chain infrastructure for Santos Basin operations.
Norway
North Sea electrification and carbon reduction targets push operators toward lower-toxicity water-based systems. PSA Norway drilling regulations enforce strict discharge limits for synthetic base fluids. Stavanger concentrates subsea technology providers integrating fluid management with completion systems.
Saudi Arabia
Horizontal drilling in unconventional reservoirs expands demand for high-performance water-based fluids. Saudi Aramco in-house drilling engineering specifies formulations directly through audited supplier relationships. Dhahran and the Eastern Province host the primary technical centers for Red Sea and onshore shale evaluation.
Nigeria
Deepwater projects in the Bonga and Egina fields require thermally stable synthetic formulations. Department of Petroleum Resources environmental guidelines restrict oil-based fluid discharge without thermal treatment. Lagos and Port Harcourt serve as logistics hubs for West African offshore supply chains.
Drilling and Completion Fluids Market Key Industry Players
Player mix skews toward integrated oilfield service providers with captive formulation intellectual property. Three global service companies control the majority of deepwater synthetic fluid contracts through bundled drilling packages. Regional blenders occupy commodity water-based segments with minimal technical differentiation. Consolidation pressures intensify as national oil companies reduce vendor lists and extend contract durations.
Within the integrated service tier, Schlumberger Limited, Baker Hughes Co., and Halliburton Co. exemplify the archetype of technology-differentiated fluid suppliers. These entities anchor synthetic base fluid development for HPHT applications while controlling barite sourcing through captive mining operations. Independent specialists including Newpark Resources Inc. and CES Energy Solutions Corp. occupy positions in regional water-based markets where technical service overhead compresses margins.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes Co. |
| Halliburton Co. |
| Newpark Resources Inc. |
| CES Energy Solutions Corp. |
| NOV Inc. |
| TETRA Technologies Inc. |
| Weatherford International Plc |
| Chevron Phillips Chemical Co. LLC |
| Others |
Cost & Logistics Intelligence
API Specification 13A certification gates both supplier qualification and price differentiation simultaneously, forcing regional blenders to absorb laboratory investment costs while integrated service companies capture premium positioning through in-house testing capabilities.
Pricing Analysis
Certification level creates the primary spread between commodity water-based formulations and premium synthetic systems. Three-tier pricing structure across premium synthetic, standard water-based, and economy bulk-blend levels reflects technical service intensity and formulation complexity. Cost compression in water-based segments is intensifying because independent drilling contractors prioritize disposal cost minimization over performance premiums. National oil companies and supermajors exhibit lowest price sensitivity, accepting 40-60% premiums for HPHT-certified synthetic formulations with real-time monitoring integration.
Supply Chain Analysis
Strait of Hormuz transit underwrites barite supply security for Middle Eastern weighted fluid operations, though Nevada and Peru host the majority of API-grade mining capacity. Nevada, Peru, and China concentrate upstream barite extraction, while specialty polymer additives draw from Germany, Japan, and the United States. Single-source vulnerability concentrates in API-grade barite, where Nevada operations supply the majority of Gulf of Mexico demand. Distribution runs through integrated service company technical service networks for synthetic formulations, with regional bulk distributors handling commodity water-based systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where EPA effluent guidelines and BSEE certification requirements create structural barriers that protect incumbent positions while raising entry costs for challengers.
For Market Incumbents: Secure captive barite sourcing through upstream mining partnerships or long-term offtake agreements with Nevada and Peruvian operations to defend against supply chokepoint vulnerability. Lock in multi-year integrated drilling contracts with Petrobras and West African national oil companies before PFAS regulatory clarity forces synthetic formulation reformulation cycles that could disrupt established relationships. For New Entrants and Emerging Players: Lead with bio-derived base fluid technologies targeting the pre-salt basin expansion corridor, where ANP local content requirements create procurement preferences for domestic Brazilian blending capacity. Independent fluid specialists can penetrate the automated mud lab segment, offering remote testing infrastructure as a service to operators seeking BSEE compliance without integrated service company bundling. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across synthetic base fluid R&D and automated monitoring hardware, favoring asset-light formulation technology plays over capital-heavy mining integration. Acquisition targets should display proprietary bio-derived chemistry intellectual property with regulatory pre-qualification ahead of PFAS restrictions. The signal to watch is ANP local content enforcement intensity, which determines whether independent Brazilian blenders can capture share from integrated service incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Mining | Captive Nevada and Peruvian supply secures density additive availability against geographic chokepoints. |
| Bio-Derived Base Fluid Development | Ester-based renewable formulations position ahead of EPA PFAS restriction implementation. |
| Automated Mud Lab Deployment | Remote testing infrastructure enables real-time BSEE compliance without centralized laboratory delays. |
| Pre-Salt Basin Local Content Partnership | ANP-mandated domestic blending capacity opens procurement channels for Brazil ultra-deepwater contracts. |
| Real-Time Monitoring System Integration | Sensor hardware bundling with fluid services captures BSEE-mandated demand pull-through. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with drilling engineering directors, fluid procurement managers at national oil companies, mud plant operations supervisors, and BSEE regulatory compliance officers; and secondary validation through EPA effluent guideline filings, BSEE well control rulemakings, ANP local content decrees, SEC 10-K disclosures from integrated service companies, and customs trade data for barite import flows. Bottom-up rig-count modeling triangulated against top-down spending estimates from operator capital programs.
Across the analysis window, forecasts applied a segmented growth framework by fluid type, additive chemistry, application depth, and end-user procurement authority. CAGRs were derived from elasticity-adjusted demand projections for HPHT well proliferation and regulatory-driven formulation substitution. Synthetic base fluid thermal stability specifications and real-time monitoring hardware penetration served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained deepwater investment cycles or accelerated PFAS regulatory timelines would require recalibration. Forecasts reflect documented assumptions regarding Petrobras pre-salt development pacing and REACH authorization sunset dates for chrome lignosulfonate chemistries. Practitioners should keep alternative scenarios live as ANP local content enforcement and EPA effluent guideline implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Smart Well Market
Oil & Gas
Oilfield Drill Bits Sales Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Iraq Oil and Gas Market
Oil & Gas
Big Data in Oil and Gas Exploration and Production Market
Oil & Gas
China Oil and Gas Midstream Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Coal Mining Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
LNG Loading Skid Market