
 Well Casing Market | 2026-2036
Well Casing Market Size, Share, and Industry Trends Forecast 2026-2036
Well Casing Market Analysis
Offshore operators is collapsing as the fastest-growing buyer archetype in the well casing market, overtaking conventional onshore drillers in premium connection orders. Tenaris dominates seamless pipe production for high-pressure offshore environments across Latin American supply chains. Baker Hughes differentiates through proprietary thread design technology that reduces gas leak paths in HPHT wells. Halliburton leverages integrated well construction services to bundle casing with cementing and directional drilling packages.
Well casing comprises steel, polymer, or composite tubulars installed in boreholes to prevent formation collapse, isolate fluid zones, and provide pressure containment during drilling and production operations; API 5CT specifies minimum yield strengths from H40 to Q125 grades for carbon and alloy steel products. Steel casing anchors the majority of revenue due to established metallurgy and repair infrastructure, though composite casing captures growing share in corrosive CO2 injection applications where fiberglass resists chemical degradation. Geothermal energy applications represent the fastest-expanding segment as enhanced geothermal systems require casing rated for temperatures exceeding 300°C in crystalline rock formations.
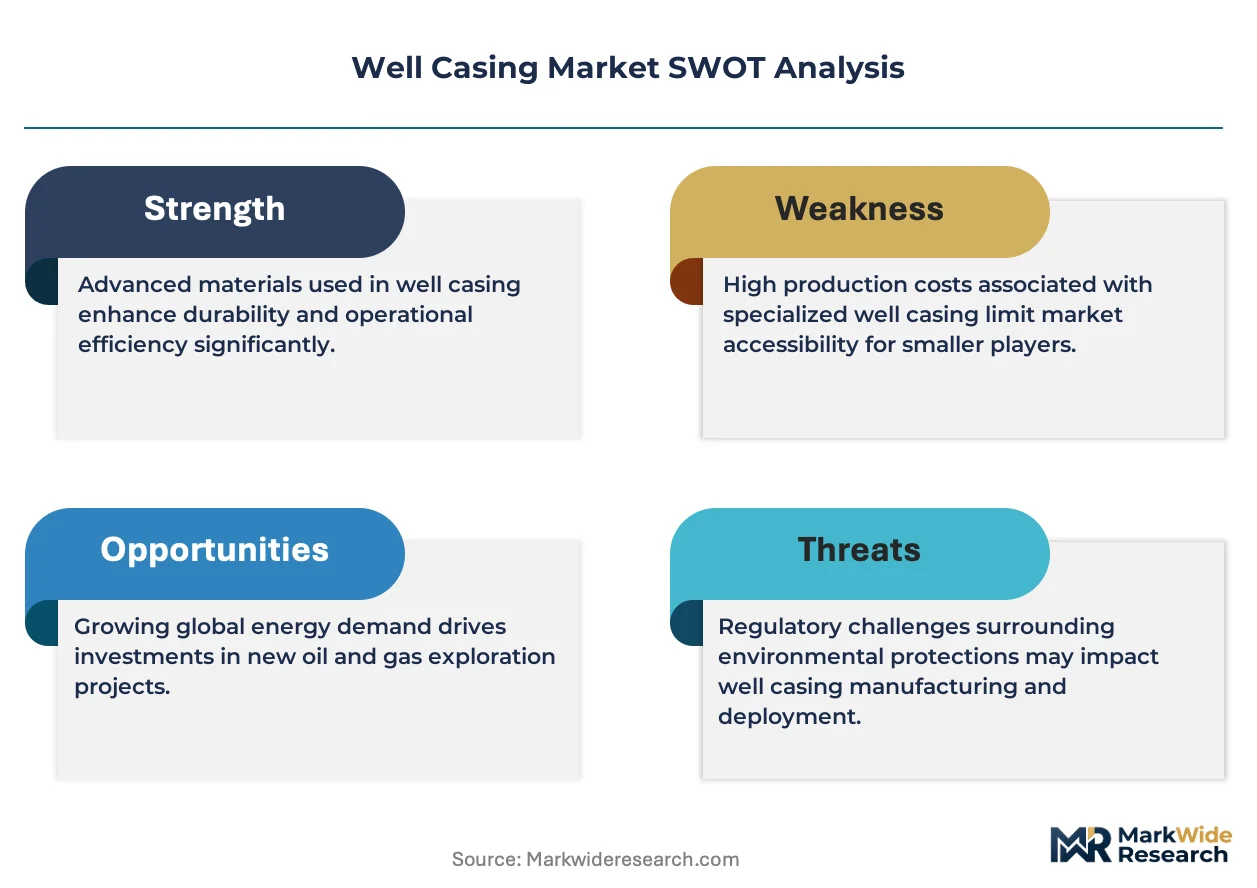
API standards, ISO 11960, and NORSOK M-001 collectively dictate material selection, testing protocols, and traceability requirements for well casing used in North Sea and Gulf of Mexico operations. The EPA's Underground Injection Control program shapes demand for corrosion-resistant casing in Class II disposal wells across US shale basins. Stakeholders must monitor evolving methane emission regulations that could mandate premium casing specifications for entire well inventories rather than new construction alone.
Market Dynamics
Deepwater drilling programs are pulling premium casing specifications into the mainstream as operators push beyond 10,000-foot depths where conventional tubulars fail under combined pressure-temperature loads. This structural shift is compressing the addressable market for standard API grades while expanding the premium tier.
Growth Catalysts
- EPA Underground Injection Control mandates:Class II disposal well construction in US shale basins requires corrosion-resistant metallurgy, forcing operators to upgrade casing specifications across entire drilling inventories.
- Enhanced geothermal systems:Crystalline rock formations exceeding 300°C temperatures in Iceland and Kenya demand specialty casing alloys previously reserved for oilfield HPHT applications.
- Permian Basin horizontal drilling:Extended-reach laterals exceeding 15,000 feet require premium threaded connections that maintain gas-tight integrity under cyclic loading.
Market Restraints
- Alloy steel input volatility:Molybdenum and chromium price swings compress margin predictability for seamless pipe producers committed to long-term drilling contracts.
- Supply concentration in Latin American mills:Dependence on a narrow production base for high-collapse grades creates delivery vulnerability during hurricane seasons.
- Fiberglass substitution ceiling:Composite casing penetration stalls above 5,000-foot depths where axial load requirements exceed fiberglass tensile limits.
Strategic Opportunities
- CO2 injection infrastructure:Carbon capture and storage projects in the US Gulf Coast and North Sea require corrosion-immune casing for permanent sequestration wells.
- Standardized modular casing systems:Pre-threaded joint inventory programs reduce rig non-productive time by eliminating on-site make-up operations.
- EU Green Deal methane regulations:Mandatory leak detection and repair protocols create retrofit demand for premium connections in legacy wellbores across Dutch and Danish sectors.
Industry Challenges
- API Q1 and ISO/TS 29001 auditor shortages:Certification backlogs delay qualified supplier status for mills seeking sour service qualification.
- Legacy wellbore compatibility:Premium connection adoption requires inventory bifurcation as operators maintain parallel stocks for brownfield workovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Well Casing Market |
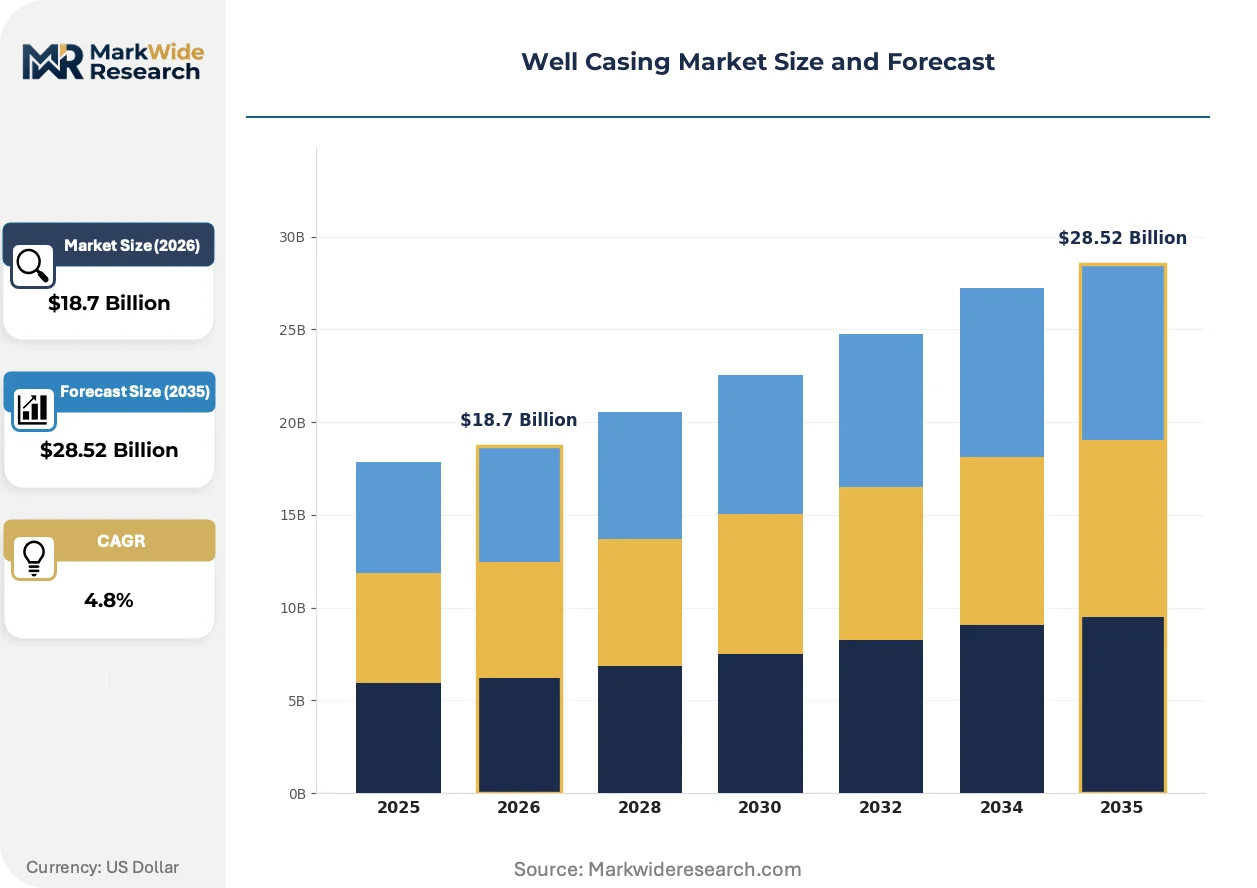
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Casing, PVC Casing, Fiberglass Casing, Composite Casing Application: Oil Extraction, Water Wells, Geothermal Energy, Mining Operations End User: Oil & Gas Companies, Environmental Agencies, Construction Firms, Research Institutions Installation Type: Drilled Casing, Installed Casing, Retrievable Casing, Permanent Casing |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, Weatherford International, Tenaris, Vallourec, National Oilwell Varco, Wasco Energy Group of Companies, Trican Well Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Well Casing Market Emerging Trajectories
Material science breakthroughs and digital thread verification are converging to redefine casing integrity assurance. Operators now demand real-time connection performance data alongside physical metallurgical certificates.
Composite casing formulations reinforced with basalt fiber are fragmenting the corrosion-resistant segment previously dominated by nickel-alloy steel. Geothermal developers in Turkey and Indonesia specify these materials for high-CO2 brine environments where steel suffers sulfide stress cracking. The technology is fragmenting procurement patterns as buyers separate deep from shallow casing decisions rather than defaulting to steel grades.
REACH substance restrictions on hexavalent chromium coatings are forcing European mills to convert to trivalent alternatives for thread compound applications. The industrial consequence is extended qualification timelines as connection friction coefficients require revalidation. North Sea operators face the tightest compliance deadlines, with NORSOK M-001 revisions mandating full material declarations by 2026.
Integrated casing-cementing service bundling is compressing standalone pipe procurement cycles. Supermajors in the US Permian and Brazil's pre-salt now specify single-contractor accountability for zonal isolation performance. This model displaces traditional split purchasing between casing suppliers and cementing service companies, concentrating vendor selection power with integrated well construction providers.
Well Casing Market Segmentation
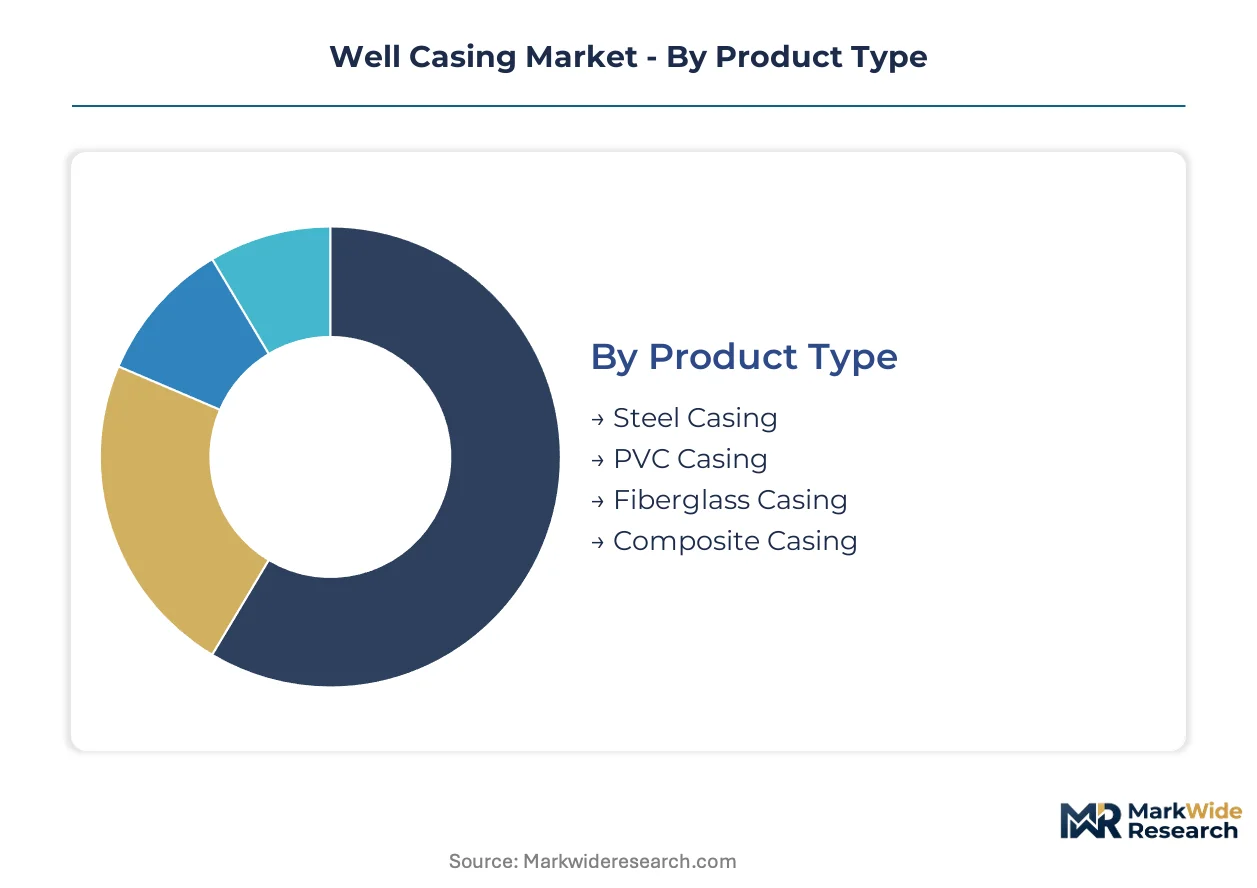
Well casing procurement patterns fragment across material technologies, downhole environments, and operator risk profiles. Each segmentation dimension reveals distinct margin structures and supply chain dependencies that reshape competitive positioning.
Product Type:
Steel grades dominate domestic production in the United States and Saudi Arabia, while composite formulations concentrate in European and East Asian export mills.
- Steel Casing:Carbon and alloy tubulars specified under API 5CT grades H40 through Q125 anchor the revenue base. Permian Basin horizontal programs and Saudi Aramco's onshore developments consume high-collapse seamless grades from domestic mills.
- Composite Casing:Basalt-fiber-reinforced formulations resist sulfide stress cracking in high-CO2 geothermal brines. Turkish and Indonesian developers specify these materials for crystalline rock formations exceeding 300°C where steel degrades.
- Fiberglass Casing:Corrosion-immune for shallow CO2 injection wells under 5,000 feet.
- PVC Casing:Water well and environmental monitoring applications in unconsolidated formations.
Steel casing commands the established base. The steepest expansion runs through composite formulations.
Application:
Cost tiers separate premium metallurgy for HPHT reservoirs from standard grades for conventional production.
- Oil Extraction:Deepwater projects in Brazil's pre-salt and the Gulf of Mexico pull premium connection specifications into mainstream procurement. Combined pressure-temperature loads beyond 10,000 feet collapse demand for conventional API grades.
- Geothermal Energy:Enhanced geothermal systems in Iceland and Kenya require specialty alloys previously reserved for oilfield HPHT applications. Temperature ratings exceeding 300°C in crystalline rock formations drive specification upgrades.
- Water Wells:Municipal and agricultural groundwater extraction in the US Great Plains and India's alluvial basins.
- Mining Operations:Dewatering and ventilation shafts in Australian and Chilean copper deposits.
Oil extraction absorbs the highest premium tonnage. Geothermal applications are climbing the fastest.
End User:
Customer type determines contract structure, with integrated service bundles displacing standalone pipe procurement.
- Oil & Gas Companies:Supermajors in the US Permian and Brazil's pre-salt now specify single-contractor accountability for zonal isolation performance. Bundled casing-cementing contracts compress standalone procurement cycles.
- Environmental Agencies:EPA Underground Injection Control mandates for Class II disposal wells force corrosion-resistant metallurgy upgrades across entire drilling inventories.
- Construction Firms:Foundation piling and dewatering systems in urban tunneling projects.
- Research Institutions:Scientific drilling programs and carbon sequestration pilots.
Oil and gas operators drive premium specification adoption. Environmental compliance is gaining share fastest.
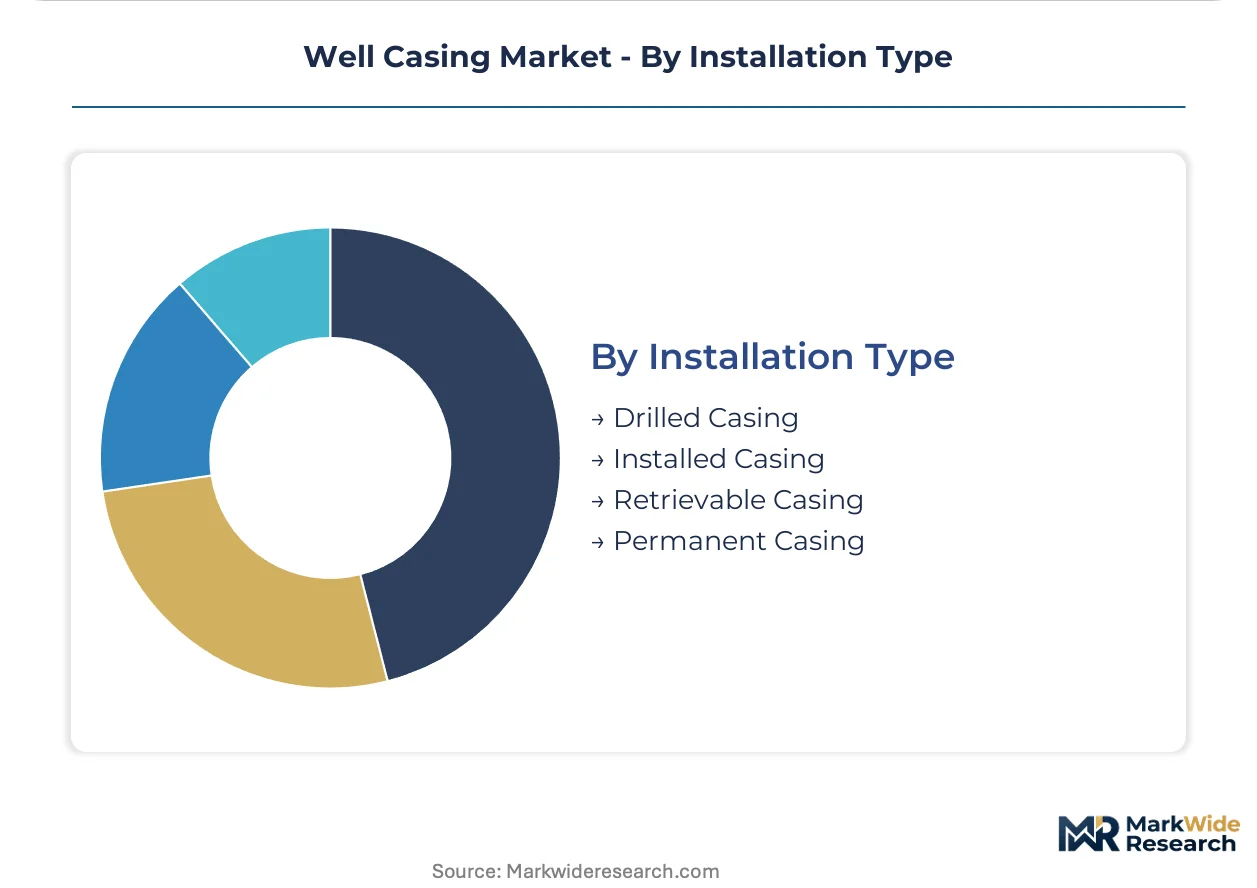
Installation Type:
Volume concentration favors permanent installations, while retrievable systems serve niche intervention economics.
- Permanent Casing:Conventional oil and gas completions anchor the installed base. Cemented production strings in North Sea and Gulf of Mexico HPHT wells require gas-tight integrity under cyclic loading for decades.
- Drilled Casing:Simultaneous drilling and casing operations in extended-reach laterals reduce non-productive time. Pre-threaded joint inventory programs eliminate on-site make-up operations in the Permian Basin.
- Installed Casing:Pre-fabricated modular systems for water well and environmental applications.
- Retrievable Casing:Temporary zonal isolation for well testing and intervention in Middle East carbonate reservoirs.
Permanent casing holds the volume base. Drilled casing systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston anchors North American well casing logistics, handling seamless pipe imports from Latin American mills that feed Permian Basin drilling programs. Pipeline interconnects to the Gulf Coast refining corridor sustain demand for corrosion-resistant grades in carbon capture injection wells.
United States
EPA Underground Injection Control mandates for Class II disposal wells in the Permian Basin force operators toward premium metallurgy. The agency's corrosion-resistant specifications now cover entire drilling inventories, not solely new construction. Houston-Galveston industrial clusters concentrate threading and inspection facilities that serve deepwater Gulf of Mexico projects.
Brazil
Pre-salt carbonate reservoirs offshore Santos Basin pull premium connection specifications into mainstream procurement. ANP regulatory frameworks mandate gas-tight integrity standards for HPHT wells beyond 10,000-foot depths. Macaé's service base hosts pre-threading operations that reduce rig non-productive time for Petrobras drilling campaigns.
Norway
North Sea HPHT developments require casing rated for combined pressure-temperature loads that collapse conventional API grades. NORSOK M-001 revisions mandate full material declarations by 2026, compressing supplier qualification timelines. Stavanger's engineering clusters anchor connection testing facilities serving Barents Sea frontier drilling.
Saudi Arabia
Saudi Aramco's onshore gas development programs consume high-collapse seamless grades from domestic Jafurah Basin manufacturing. The national oil company's sour service specifications align with API 5CT Q125 requirements for hydrogen sulfide environments. Dammam's industrial corridor hosts threading facilities integrated with kingdom-wide drilling logistics.
China
Shale gas development in Sichuan Basin drives demand for extended-reach lateral casing with premium threaded connections. MIIT domestic content policies favor local mills for standard API grades while permitting import of high-collapse seamless for deep formations. Chengdu-Chongqing manufacturing clusters produce threading equipment for 15,000-foot horizontal programs.
Well Casing Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The supplier base concentrates around integrated energy service conglomerates and dedicated tubular manufacturers, creating tiered competitive dynamics. Three archetypes dominate: full-service well construction providers, seamless pipe specialists with mill ownership, and regional threading/fabrication contractors. Capacity expansion in Latin American mills and strategic partnerships for geothermal alloy development represent the dominant competitive vectors.
Among North American integrated service providers, Schlumberger, Halliburton, and Baker Hughes occupy positions that exemplify bundled casing-cementing accountability models. These companies anchor the premium-tier competitive vector where single-contractor zonal isolation performance displaces split procurement between pipe suppliers and cementing specialists. Their market presence reflects the structural shift toward integrated well construction packages in deepwater and unconventional basins.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| Weatherford International |
| Tenaris |
| Vallourec |
| National Oilwell Varco |
| Wasco Energy Group of Companies |
| Trican Well Service |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Permian Basin operators and Latin American mills lock in both alloy steel supply access and price visibility across multi-year drilling programs, insulating buyers from molybdenum spot volatility while committing producers to fixed-volume schedules.
Pricing Analysis
Volume-discount tiering separates supermajors securing 100,000-ton annual commitments from independent operators purchasing spot cargo. Pricing stratifies across premium threaded connections for HPHT wells, standard API 5CT grades for conventional depths, and economy-tier alternatives for water well applications. Cost compression in standard grades intensifies as domestic Chinese mills expand export capacity. Independent Permian drillers exhibit highest price sensitivity, while deepwater operators in Brazil's pre-salt prioritize performance guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling dominates hurricane-season planning among Gulf Coast distributors, contrasting with just-in-time delivery preferences for pre-threaded joint programs in extended-reach laterals. Seamless pipe production concentrates in Argentina, Brazil, and Mexico. Mills draw from molybdenum feedstock anchored in Chile and chromium from South African sources. Single-source vulnerability runs through the narrow high-collapse grade production base. Distribution feeds through Houston-Galveston threading clusters serving North American onshore and offshore demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite casing formulations reinforced with basalt fiber pose a material substitution threat to steel incumbents in corrosive geothermal and CO2 injection applications, forcing metallurgy suppliers to defend their position through performance differentiation.
For Market Incumbents: Fortify sour service certification portfolios against composite encroachment in high-CO2 environments. Secure backward integration into specialty alloy feedstock through captive supply arrangements with Chilean molybdenum producers. Prioritize API Q1 and ISO/TS 29001 auditor capacity expansion to accelerate qualification timelines for emerging geothermal developers. For New Entrants and Emerging Players: Differentiate on modular pre-threaded casing systems that eliminate rig non-productive time for Permian Basin independent operators. Target the shallow CO2 injection segment under 5,000 feet where fiberglass tensile limits have not yet constrained adoption. Pursue direct contracting with enhanced geothermal developers in Turkey and Indonesia seeking corrosion-immune alternatives. For Investors and Strategic Acquirers: Capital is best deployed toward threading and inspection facility operators with established API 5CT certification infrastructure and proximity to frontier basins. Long-term viability hinges on exposure to HPHT specification upgrades rather than commodity-grade volume. Monitor EPA methane emission regulation scope expansion as the critical inflection signal for premium connection retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Specialty Alloy Capacity Expansion | Captive molybdenum-chromium supply secures margin predictability for Q125 grade commitments to Saudi Aramco. |
| Pre-Threaded Joint Inventory Programs | Eliminates on-site make-up operations, reducing rig non-productive time for Permian Basin extended-reach laterals. |
| Composite Formulation R&D Partnership | Basalt-fiber reinforcement development targets geothermal brine applications exceeding 300°C in Iceland and Kenya. |
| Integrated Casing-Cementing Service Bundling | Single-contractor zonal isolation accountability displaces split procurement in Brazil's pre-salt and US Permian. |
| NORSOK M-001 Compliance Certification | Full material declaration capability unlocks North Sea HPHT supply eligibility ahead of 2026 regulatory deadlines. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with drilling engineers, procurement directors at supermajors, threading facility operators, and geothermal project developers; and secondary validation through API certification databases, EPA Underground Injection Control permit filings, customs trade records for seamless pipe imports, and NORSOK M-001 revision documentation. Bottom-up well count projections across 15 country-level markets triangulated against top-down steel consumption estimates from mill capacity disclosures.
Across the projection horizon, the analytical framework modeled demand by material technology, application environment, and operator risk profile, with particular granularity around HPHT specification tiers and geothermal temperature ratings. CAGRs were derived from segment-level volume trajectories weighted by price realization differentials. Forecast inputs incorporated Permian Basin lateral length extension curves, pre-salt well depth progression in Brazil, and EPA regulatory scope expansion scenarios for corrosion-resistant mandates.
Material uncertainties — alloy input price volatility, hurricane-season supply disruptions, and REACH substance restriction acceleration — sit outside the modeled envelope. Forecasts reflect assumptions around continued deepwater specification upgrades and geothermal temperature rating thresholds. Revision becomes warranted when composite casing axial load performance crosses thresholds enabling penetration beyond 5,000-foot depths.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Smart Pipeline Pigging Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
Oil and Gas Downhole Vibration Monitoring and Control System Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Africa Oil and Gas Market
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
Mexico Oil and Gas Downstream Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Oil and Gas MIC Testing Market
Oil & Gas
Hydraulic Workover Units Market