
 Big Data in Oil and Gas Exploration and Production Market | 2026-2036
Big Data in Oil and Gas Exploration and Production Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data in Oil and Gas Exploration and Production Market Outlook
Cloud-native infrastructure is hardening as the dominant substrate for seismic processing and reservoir simulation, displacing legacy on-premise server farms that once anchored exploration workflows. Schlumberger leverages its DELFI cognitive E&P environment to sustain deep integration between subsurface modeling and cloud analytics. Palantir Technologies competes through specialized data fusion platforms that dominate defense-adjacent energy intelligence contracts. Baker Hughes differentiates by extending its digital twin capabilities across LNG and offshore production assets.
Big Data in Oil and Gas Exploration and Production encompasses the collection, storage, processing, and analysis of petabyte-scale geophysical, operational, and equipment sensor datasets to optimize hydrocarbon discovery, extraction, and field management. These systems typically integrate seismic surveys with real-time downhole pressure-temperature measurements and surface facility IoT streams to reduce non-productive time and maximize ultimate recovery. Reservoir Modeling applications within the Application segment lead current deployment value as operators seek to minimize dry-hole risk through probabilistic subsurface characterization. Machine Learning within the Technology segment represents the fastest-expanding capability layer, with supervised learning models now predicting equipment failures across artificial lift systems before threshold alarms trigger. Data Analytics services within the Service Type segment occupy the mature margin pool, though Predictive Maintenance is accelerating as compressor and pump fleets digitize.
The EPA enforces methane monitoring and reporting thresholds that compel operators to install continuous emissions detection backed by certified data logging systems. OSHA process safety management standards intersect with digital twin deployments, requiring validated sensor calibrations and automated alarm hierarchies for drilling hazard mitigation. The Bureau of Safety and Environmental Enforcement mandates real-time offshore production data transmission that directly shapes platform-level analytics procurement decisions. Stakeholders must monitor how evolving SEC climate disclosure rules reclassify subsurface data as audited financial inputs rather than purely technical assets.
Market Dynamics
Cloud-native seismic processing is displacing legacy on-premise server farms as the dominant substrate for reservoir simulation, forcing operators to restructure capital allocation toward subscription-based analytics platforms and away from owned infrastructure.
Growth Catalysts
- EPA Methane Mandates:Continuous emissions monitoring requirements in the United States compel operators to deploy real-time sensor networks with certified data logging systems across Permian Basin operations.
- Offshore Drilling Digitization:Deepwater operators accelerate predictive maintenance platform adoption to reduce non-productive time on floating production assets.
- Machine Learning Capabilities:Supervised learning models now predict artificial lift system failures before threshold alarms trigger, compressing maintenance cycles.
Market Restraints
- Specialized Talent Scarcity:Reservoir engineers with dual competencies in geophysics and cloud architecture command premium compensation, inflating project delivery costs.
- Legacy System Entrenchment:Decades-old SCADA infrastructure in mature basins creates technical debt that slows real-time data integration with modern analytics stacks.
- Cybersecurity Compliance Burden:NERC CIP standards for critical energy infrastructure impose audit-intensive data governance requirements on upstream operators.
Strategic Opportunities
- Carbon Capture Integration:Subsurface characterization data from enhanced oil recovery operations is converging with carbon storage site selection, opening new service revenue streams.
- Brazil Pre-Salt Expansion:Underpenetrated ultra-deepwater fields off the Brazilian coast present greenfield deployment opportunities for integrated digital twin platforms.
- EU Methane Regulation:The bloc's incoming performance standards for imported natural gas create compliance-driven demand for certified emissions monitoring across LNG supply chains.
Industry Challenges
- Data Silo Fragmentation:Exploration, drilling, and production departments maintain incompatible data formats that obstruct enterprise-wide machine learning model training.
- Sensor Calibration Drift:Downhole pressure-temperature gauges require frequent recertification to maintain OSHA process safety management compliance, disrupting continuous monitoring workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data in Oil and Gas Exploration and Production Market |
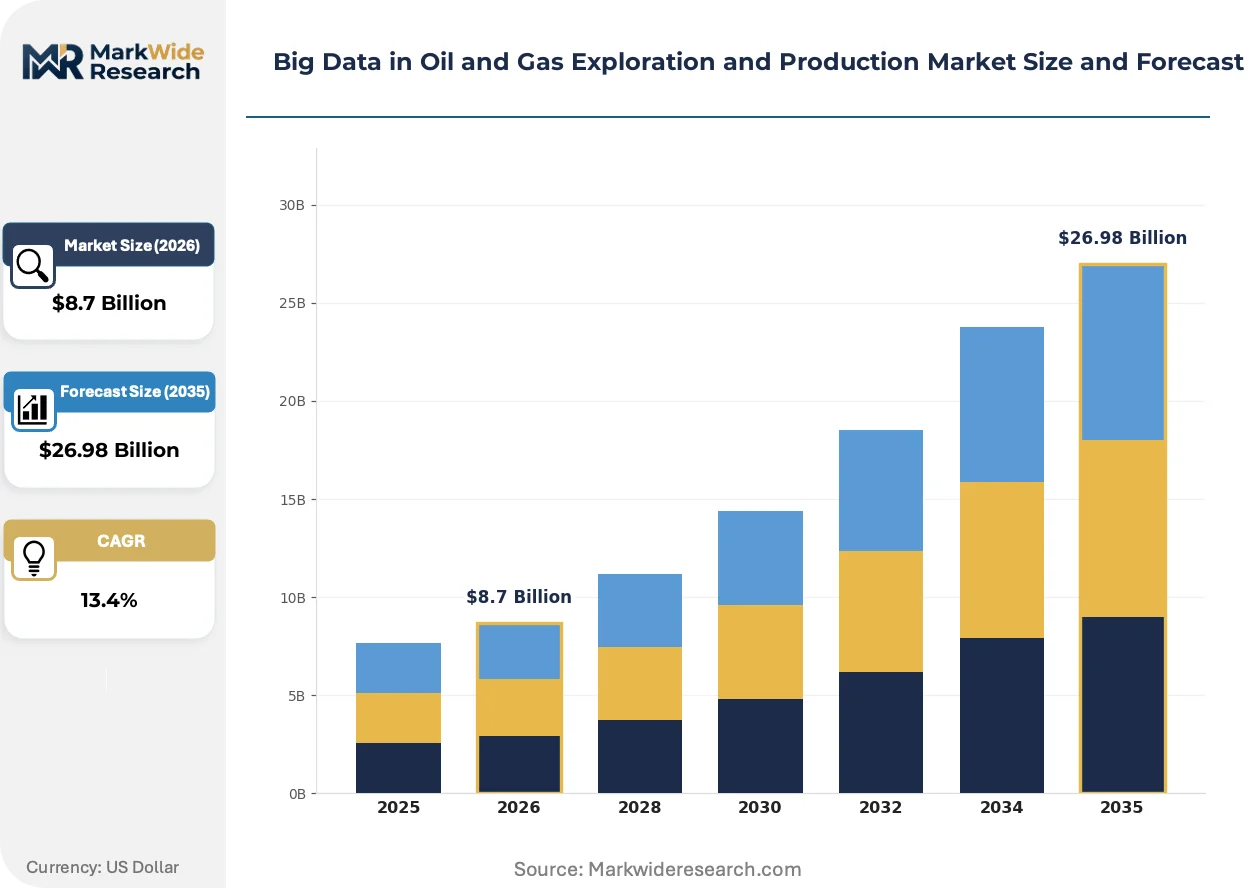
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Analytics, Predictive Maintenance, Asset Management, Exploration Services Application: Reservoir Modeling, Production Optimization, Drilling Performance, Safety Management Technology: Cloud Computing, Machine Learning, IoT Solutions, Data Warehousing End User: Exploration Companies, Production Firms, Service Providers, Regulatory Bodies |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, IBM, Microsoft, Oracle, Accenture, AWS, Palantir Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data in Oil and Gas Exploration and Production Market Strategic Shifts
Edge computing architectures are reshaping how upstream operators process petabyte-scale seismic datasets, compressing decision cycles from weeks to hours and enabling real-time reservoir management responses.
Digital twin technology is converging with physics-based reservoir simulation to create hybrid models that blend first-principles governing equations with machine learning pattern recognition. Offshore operators in the Gulf of Mexico deploy these systems to optimize artificial lift performance across subsea tieback developments. The structural consequence is compressing the traditional separation between exploration geoscience and production engineering functions.
The SEC's climate disclosure rules are reclassifying subsurface data as audited financial inputs rather than purely technical assets. This regulatory shift forces CFOs to validate probabilistic reserve estimates through independent third-party data assurance. Tight-oil producers in Texas and New Mexico face the steepest compliance burden as they retrofit legacy documentation systems to meet attestation standards.
Subscription-based analytics procurement is displacing perpetual license models as capital-constrained operators prioritize operational expenditure flexibility. Independent producers in the Permian Basin now favor metered seismic processing services over owned cloud infrastructure. Norway's Equinor-operated Johan Sverdrup field demonstrates this shift through its vendor-managed data platform arrangements.
Big Data in Oil and Gas Exploration and Production Market Segmentation
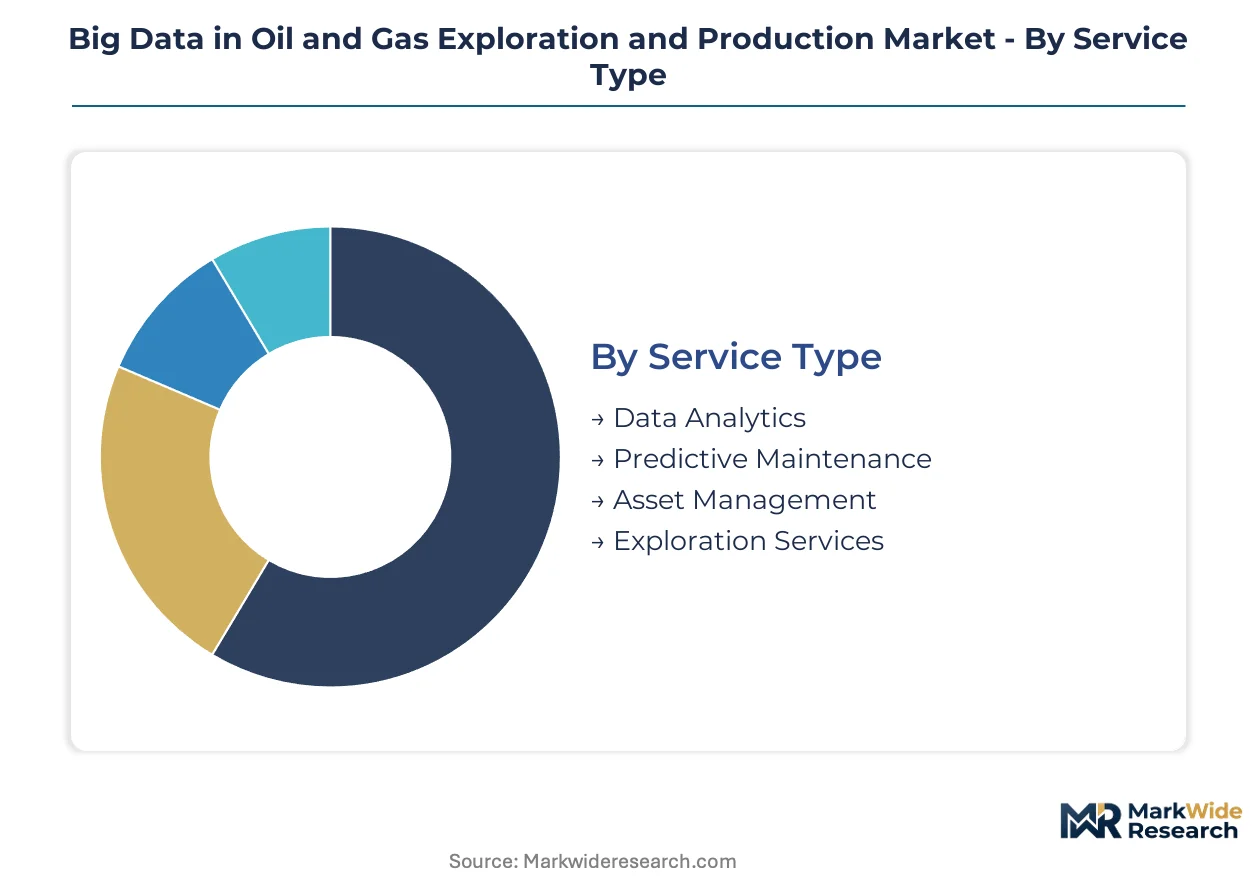
Upstream operators deploy big data solutions across heterogeneous workflows where standardization clashes with basin-specific geological complexity. Service configurations range from turnkey analytics subscriptions to bespoke reservoir characterization engagements. Procurement patterns reflect this tension between scalable cloud platforms and customized subsurface modeling.
Service Type:
Customization dominates high-value engagements while standardized modules penetrate mid-market operators seeking predictable expenditure profiles.
- Data Analytics:Mature service layer encompassing descriptive dashboards, diagnostic root-cause analysis, and prescriptive optimization algorithms. Demand concentrates among Permian Basin tight-oil producers facing investor pressure to demonstrate capital efficiency per lateral foot. Margin compression intensifies as cloud-native vendors commoditize baseline visualization tools.
- Predictive Maintenance:Supervised learning models forecast artificial lift system failures and compressor degradation curves before threshold alarms activate. Offshore drilling operators in the Gulf of Mexico accelerate adoption to reduce non-productive time on floating production assets. EPA methane monitoring mandates further compel sensor network deployments that feed these algorithms.
- Asset Management:Digital twin integration across LNG terminals and subsea production systems.
- Exploration Services:Seismic processing and probabilistic subsurface characterization for frontier basins.
Leading the category by volume: Data Analytics. Growing fastest: Predictive Maintenance.
Application:
Revenue concentration follows drilling intensity with production-stage applications commanding recurring spend versus exploration's project-based economics.
- Reservoir Modeling:Probabilistic subsurface characterization integrating seismic surveys with well log data and core sample analysis. Operators minimize dry-hole risk through stochastic simulation of trap geometry and fluid distribution. The SEC's climate disclosure rules now reclassify these outputs as audited financial inputs requiring third-party assurance.
- Production Optimization:Real-time well performance tuning through edge-computing architectures that compress decision cycles from weeks to hours. Tight-oil producers deploy these systems to maximize recovery rates per well amid declining initial production profiles. Machine learning pattern recognition identifies artificial lift inefficiencies invisible to conventional surveillance.
- Drilling Performance:ROP optimization and stuck-pipe prediction through downhole vibration analysis.
- Safety Management:OSHA process safety management compliance through validated sensor calibrations and automated alarm hierarchies.
Reservoir Modeling anchors current deployment value. Production Optimization exhibits the steepest expansion trajectory as brownfield digitization accelerates.
Technology:
Architecture choices bifurcate between hyperscale cloud elasticity and edge-latency sensitivity for time-critical operations.
- Cloud Computing:Seismic processing and reservoir simulation workloads migrate from owned server farms to subscription-based platforms. Capital-constrained independents favor metered consumption models over perpetual license procurement. Data residency requirements in Brazil and Norway shape vendor selection for pre-salt and North Sea operators.
- Machine Learning:Fastest-expanding capability layer spanning supervised failure prediction, unsupervised anomaly detection, and reinforcement learning for production scheduling. Physics-informed neural networks now blend first-principles governing equations with pattern recognition. Talent scarcity for dual-competency reservoir engineers inflates implementation costs.
- IoT Solutions:Downhole pressure-temperature gauges and surface facility sensor networks for continuous emissions monitoring.
- Data Warehousing:Petabyte-scale storage architectures for historical seismic and production datasets.
Cloud Computing dominates infrastructure spend. Machine Learning is gaining share fastest as model deployment pipelines mature.
End User:
Procurement authority fragments across technical and financial functions with divergent risk tolerances and validation requirements.
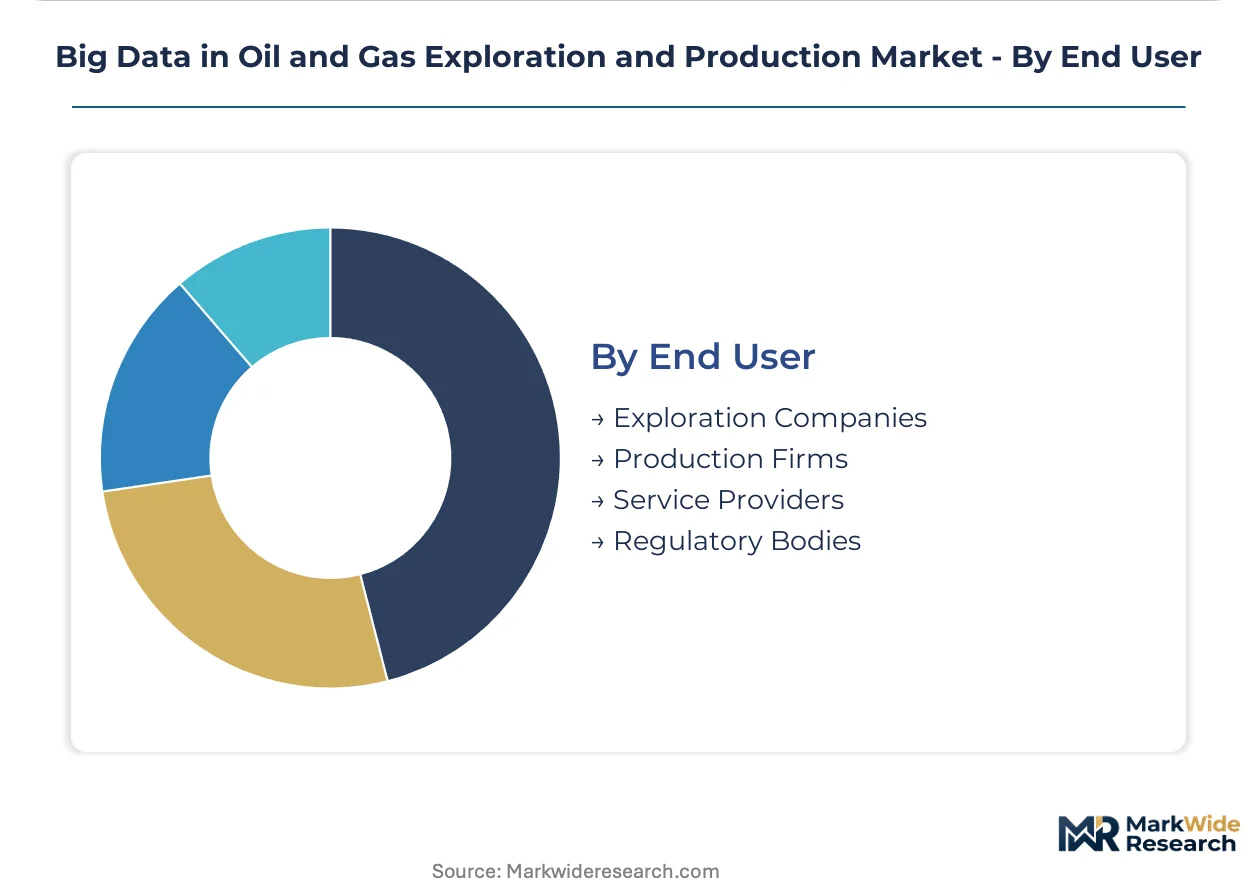
- Exploration Companies:Early-stage subsurface characterization for frontier and emerging basins. Project-based contracting with high variability in annual analytics expenditure. Dry-hole risk reduction justifies premium pricing for probabilistic modeling services.
- Production Firms:Recurring operational technology budgets supporting real-time monitoring and optimization. Brownfield asset portfolios generate sustained demand for predictive maintenance platforms. CFO scrutiny intensifies as SEC rules mandate audited data assurance.
- Service Providers:Third-party drilling contractors and equipment lessors seeking fleet-wide performance benchmarking.
- Regulatory Bodies:EPA, BSEE, and state agencies mandating continuous emissions detection and production data transmission.
Production Firms command the largest addressable spend. Regulatory Bodies represent the fastest-climbing demand segment as compliance mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin operators in Texas and New Mexico concentrate demand for real-time reservoir analytics, while Norway's North Sea assets and Brazil's pre-salt fields anchor offshore deployment value.
United States
EPA methane monitoring mandates compel continuous emissions detection across Permian Basin tight-oil operations. OSHA process safety management standards intersect with digital twin deployments for drilling hazard mitigation. Houston anchors the largest vendor ecosystem, where predictive maintenance platforms integrate with legacy SCADA infrastructure.
Norway
Equinor-operated Johan Sverdrup field demonstrates vendor-managed data platform arrangements through metered seismic processing services. Data residency requirements shape vendor selection for North Sea operators deploying cloud-native reservoir simulation. Stavanger hosts the primary concentration of subsurface modeling expertise.
Brazil
Underpenetrated ultra-deepwater pre-salt fields present greenfield opportunities for integrated digital twin platforms. The country's national petroleum regulator mandates real-time production data transmission from floating production assets. Rio de Janeiro anchors Petrobras's digital transformation procurement decisions.
Saudi Arabia
Aramco's mega-project developments drive demand for petabyte-scale seismic processing and probabilistic subsurface characterization. The Kingdom's Vision 2030 diversification program accelerates cloud analytics adoption across upstream operations. Dhahran concentrates the primary vendor engagement for reservoir simulation platforms.
United Kingdom
North Sea decommissioning timelines compress decision cycles for brownfield production optimization through edge-computing architectures. The North Sea Transition Authority mandates emissions reduction targets that force sensor network retrofits across aging platform infrastructure. Aberdeen maintains the dominant cluster of offshore digital service providers.
Big Data in Oil and Gas Exploration and Production Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service conglomerates controlling high-value reservoir characterization while cloud hyperscalers capture infrastructure spend. The vendor base organizes around three archetypes: full-stack E&P platform providers, specialized data fusion contractors, and horizontal cloud infrastructure vendors. M&A activity concentrates on tuck-in acquisitions of niche subsurface analytics firms, while strategic partnerships between operators and hyperscalers reshape procurement patterns.
Within the integrated services tier, Schlumberger, Baker Hughes, and Palantir Technologies occupy distinct positioning vectors. Schlumberger exemplifies the full-stack archetype through its DELFI cognitive environment that binds subsurface modeling to cloud analytics. Baker Hughes anchors digital twin capabilities across LNG and offshore production assets. Palantir Technologies sits within the specialized data fusion segment, dominating defense-adjacent energy intelligence contracts through pattern recognition platforms.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| IBM |
| Microsoft |
| Oracle |
| Accenture |
| AWS |
| Palantir Technologies |
| Others |
Value Chain & Pricing Dynamics
Reservoir engineers with dual competencies in geophysics and cloud architecture cluster in Houston and Stavanger, creating labor-cost differentials that separate premium-tier predictive maintenance contracts from commoditized data analytics subscriptions. EPA methane monitoring mandates inflate certified sensor calibration costs, compressing margins for mid-market operators while reinforcing pricing power for compliant full-stack providers.
Pricing Analysis
Volume concentrates in standardized cloud-native seismic processing subscriptions while margins accrue to bespoke reservoir characterization engagements. Three-tier pricing structure across premium, standard, and economy levels separates certified emissions-monitoring packages from baseline visualization tools. Pricing pressure stems from hyperscaler commoditization of storage and compute infrastructure. Independent Permian Basin producers exhibit highest price sensitivity, whereas Aramco and Equinor absorb premium pricing for vendor-managed data platform arrangements.
Supply Chain Analysis
Specialized GPU hardware for machine learning training rests on Taiwanese foundry output and South Korean memory fabrication, creating concentrated input dependencies. Cloud infrastructure software draws from US hyperscaler ecosystems and European data residency-compliant hosting. Single-source vulnerability in seismic sensor manufacturing exposes operators to lead time volatility. Distribution runs through integrated oilfield service conglomerates that bundle analytics with legacy equipment retrofit contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EPA methane monitoring mandates erect barrier-to-entry moats favoring operators with certified data logging infrastructure already deployed.
For Market Incumbents: To counter hyperscaler encroachment into infrastructure layers, Schlumberger and Baker Hughes should deepen captive supply of edge-computing hardware for offshore assets. Incumbents must accelerate in-house production of physics-informed neural networks to differentiate from commodity machine learning APIs. For New Entrants and Emerging Players: Independent data fusion specialists can partner with defense contractors to access energy intelligence contracts adjacent to Palantir's established accounts. Brazil's underpenetrated pre-salt fields offer the most penetrable geography for greenfield digital twin deployments. A regulatory-first go-to-market angle targeting EU Methane Regulation compliance across LNG supply chains bypasses entrenched US Permian relationships. For Investors and Strategic Acquirers: Re-rating potential sits with niche subsurface analytics firms given SEC climate disclosure rules reclassifying reservoir data as audited financial inputs. Long-term viability favors targets with established third-party data assurance certifications rather than pure-play cloud infrastructure vendors. The inflection signal to watch is BSEE mandating expanded real-time offshore production data transmission requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Converges enhanced oil recovery subsurface data with carbon storage site selection for new revenue streams. |
| Platform Integration | Schlumberger's DELFI environment binds subsurface modeling to cloud analytics for unified workflows. |
| Acquisition of Specialist Firm | Tuck-in targets in physics-informed neural networks compress machine learning deployment timelines. |
| Geographic Expansion | Brazil pre-salt fields present greenfield opportunities for integrated digital twin platform deployment. |
| Strategic Partnership | Vendor-managed data platform arrangements at Johan Sverdrup demonstrate metered service viability. |
Study Parameters
SEC filings, EPA enforcement records, and BSEE regulatory guidance formed the secondary backbone for compliance-driven demand quantification. Primary interviews with reservoir engineers, digital transformation officers at national oil companies, cloud procurement leads, and offshore platform managers validated technology adoption timelines. Bottom-up and top-down triangulation reconciled sensor deployment counts with aggregate analytics platform revenue disclosures.
Bottom-up modeling built from individual basin drilling intensity and emissions monitoring equipment penetration, while top-down analysis tracked hyperscaler energy sector cloud revenue allocation. Segmentation dimensions spanned service type, application workflow, technology architecture, and end-user procurement authority. CAGRs derived from curve-fitting historical platform subscription growth against regulatory mandate implementation schedules, incorporating artificial lift system failure prediction accuracy improvements as a technology-specific input.
Caveats apply where NERC CIP cybersecurity audit intensity or OSHA process safety management standard revisions could materially shift the outlook. Forecasts reflect assumptions about methane detection technology cost curves and reservoir simulation cloud migration rates. A small set of named triggers—SEC attestation deadline enforcement, EU Methane Regulation border adjustment activation, and BSEE real-time data mandate expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Aqueous Flare Meter Market
Oil & Gas
Europe Wireline Logging Services Market
Oil & Gas
Shale Shakers Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market
Oil & Gas
Malaysia Oil and Gas Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
Slickline Services Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Microbial Enhanced Oil Recovery Market