
 United States Oil and Gas Separation Market | 2026-2036
United States Oil and Gas Separation Market Size, Share, and Industry Trends Forecast 2026-2036
United States Oil and Gas Separation Market Intelligence
Aftermarket service revenue is reshaping margin distribution across the United States oil and gas separation landscape. Schlumberger Limited leverages its digital monitoring platforms to extend equipment uptime for offshore operators in the Gulf of Mexico. Honeywell International Inc. anchors its position through integrated control systems that tie separation units to broader refinery automation. Enterprise Products Partners L.P. dominates midstream separation infrastructure along the Texas Gulf Coast with extensive pipeline-connected processing networks.
Oil and gas separation encompasses the physical and chemical processes that isolate crude oil, natural gas, water, and solids from wellstream fluids, typically operating at pressures from 50 to 1,500 psi and temperatures between 80°F and 180°F depending on reservoir conditions. Gravity separation remains the foundational technology across onshore fields due to its low operational complexity and tolerance for high-solids content, while membrane separation gains traction in natural gas processing applications where dehydration and carbon dioxide removal demand precision. Centrifugal separation occupies the premium tier for offshore platforms where space constraints and high throughput requirements justify capital intensity.
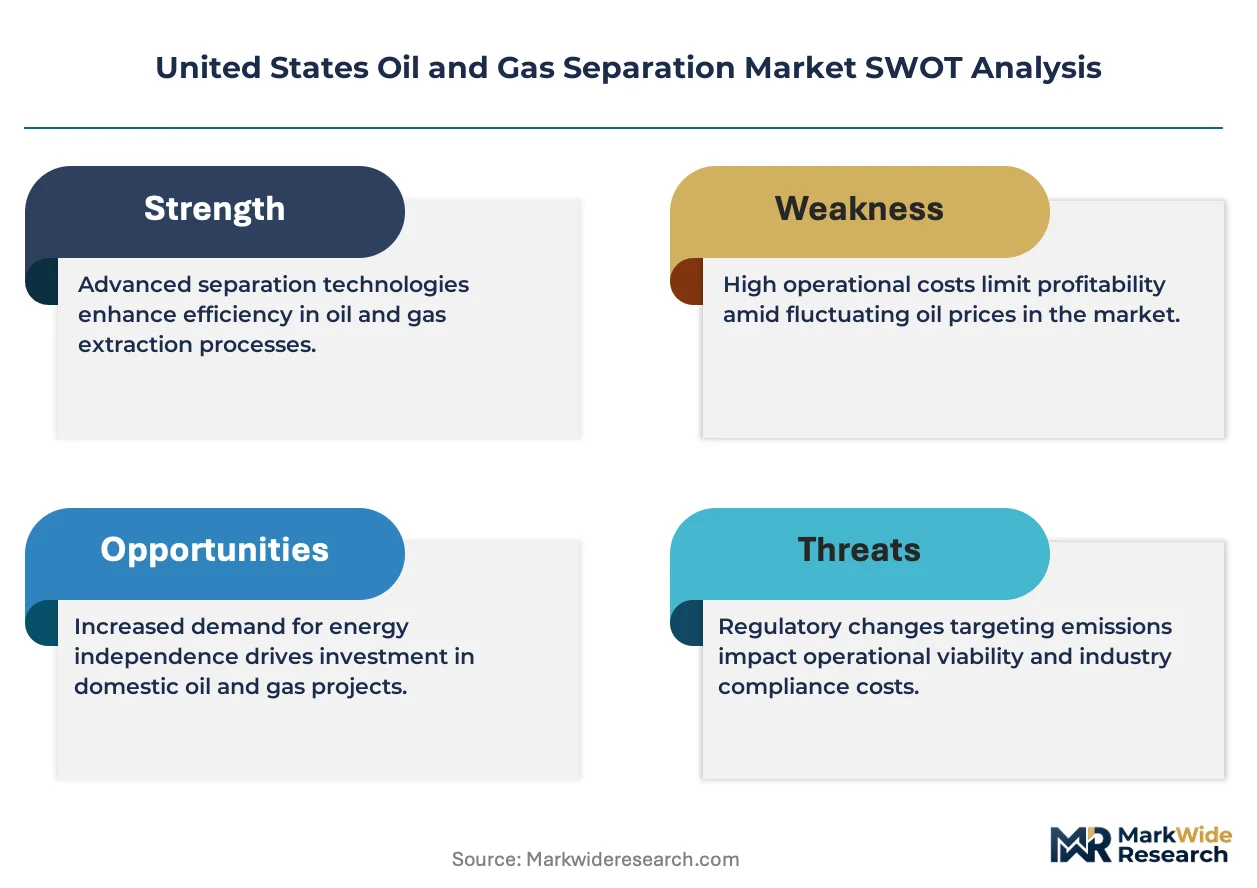
EPA New Source Performance Standards and BSEE blowout preventer regulations are elevating separation equipment specifications, particularly for offshore installations where failure tolerance has narrowed. OSHA process safety management requirements and DOT pipeline safety rules further constrain equipment design and operational protocols across onshore gathering systems. Stakeholders must weigh the trade-off between upgrading legacy gravity-based infrastructure and deploying advanced membrane systems as produced-water chemistry grows more complex.
Market Dynamics
Produced-water volumes from Permian Basin tight oil formations are forcing upstream operators to expand separation train capacity faster than original field development plans anticipated. This water-driven capacity crunch is redrawing equipment procurement priorities across Texas and New Mexico.
Growth Catalysts
- EPA Methane Regulations:New Source Performance Standards mandate tighter vapor recovery on storage tanks, driving separator retrofit demand across the Gulf Coast.
- Permian Produced-Water Surge:Water-to-oil ratios exceeding 4:1 in Delaware Basin sub-basins require higher-capacity three-phase separation infrastructure.
- Membrane Dehydration:Gas processing facilities in the Texas Panhandle are substituting glycol units with membrane systems to cut operational chemical costs.
Market Restraints
- Specialized Alloy Costs:Sour service specifications requiring duplex stainless steel for H2S-rich Delaware Basin fluids inflate vessel fabrication costs by 40-60% over carbon steel.
- Gulf Coast Fabrication Concentration:Heavy pressure vessel manufacturing clusters in Houston and Beaumont create hurricane exposure and queue bottlenecks during demand spikes.
- Gravity Separation Limits:Conventional horizontal separators face footprint constraints on legacy offshore platforms where deck loading restricts expansion options.
Strategic Opportunities
- Bakken Stranded Gas Capture:North Dakota flaring regulations are creating demand for compact separation-skid packages that enable gas-to-power at remote well pads lacking pipeline access.
- Digital Twin Integration:Combining physics-based separation modeling with real-time sensor feeds allows predictive maintenance contracts that capture recurring revenue streams.
- IRA Hydrogen Production Tax Credits:Blue hydrogen projects along the Texas Gulf Coast require novel CO2-capture-integrated separation trains for syngas conditioning.
Industry Challenges
- ASME VIII Pressure Vessel Certification:Third-party inspection backlogs at Houston-area authorized inspection agencies extend equipment delivery timelines by 8-14 weeks during peak demand cycles.
- Legacy SCADA Integration:Brownfield separator upgrades in the Permian must bridge 1990s-era control architectures with modern IIoT platforms without disrupting 24/7 production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Oil and Gas Separation Market |
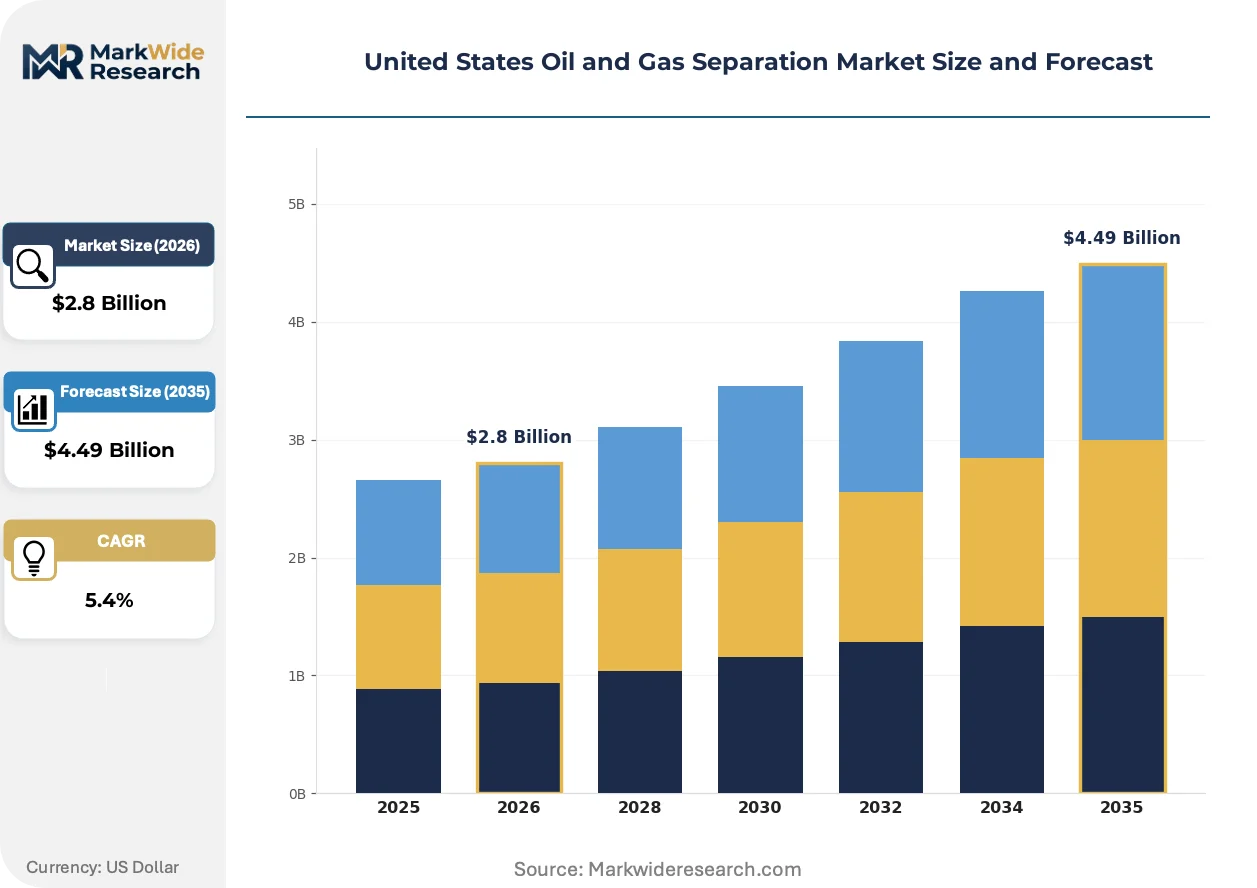
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gravity Separation, Membrane Separation, Centrifugal Separation, Heat Treatment End User: Refineries, Offshore Platforms, Onshore Drilling, Natural Gas Processing Service Type: Consulting, Maintenance, Equipment Rental, Engineering Application: Crude Oil, Natural Gas Liquids, Water Treatment, Processing Waste |
| Companies Covered | Honeywell International Inc., Bechtel, Schlumberger Limited, The Williams Companies, Inc., Fluor Corporation, TechnipFMC plc, Exterran Corporation, Enterprise Products Partners L.P., Alfa Laval AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Oil and Gas Separation Market Strategic Shifts & Innovations
Electrification of separation equipment and embedded sensor architectures are compressing the traditional 15-20 year replacement cycle for gravity-based vessels. These shifts favor modular, skid-mounted systems over field-erected designs.
Electrocoalescence technology for crude oil dehydration is rendering obsolete conventional heater-treater vessels in the Permian Basin. Pioneer Natural Resources and Diamondback Energy have piloted compact electrocoalescer skids that reduce footprint by 70% while cutting fuel gas consumption. The technology is compressing the economics of centralized tank battery consolidation versus dispersed wellhead separation.
EPA's finalized methane emissions rules for new and modified oil and gas facilities are forcing separator vapor recovery unit retrofits across the Eagle Ford Shale. Operators must install closed-vent systems capturing flash gas from production separators rather than venting to atmosphere. Small independents in South Texas are responding through equipment leasing models that spread capex across operating budgets.
Midstream operators are unbundling aftermarket service contracts from original equipment procurement, creating standalone revenue pools for predictive maintenance and spare parts logistics. Enterprise Products and Targa Resources now negotiate multi-year separation equipment service agreements separate from vessel purchases. This shift is most pronounced in the Texas Gulf Coast corridor where processing plant uptime directly ties to NGL fractionation economics.
United States Oil and Gas Separation Market Segmentation
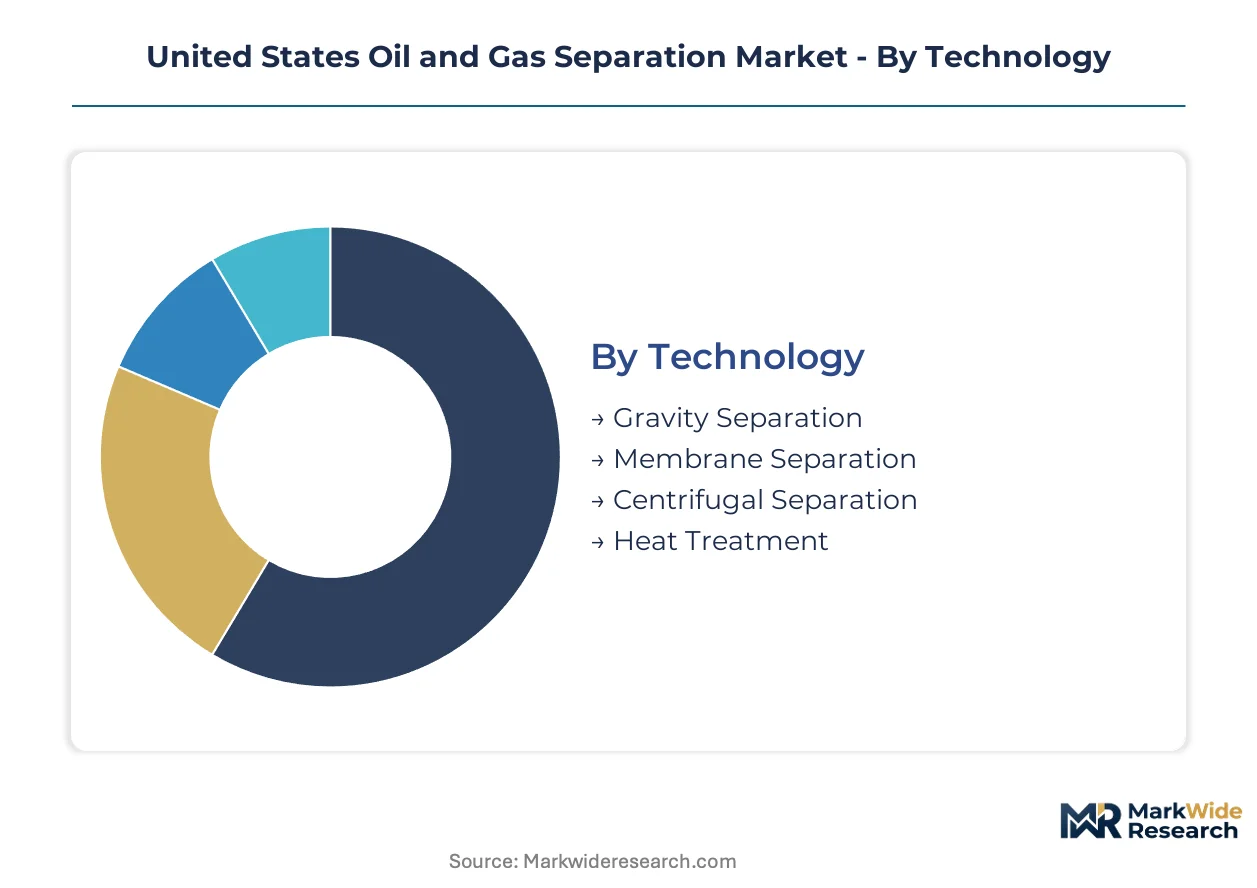
Technology choices in United States oil and gas separation dictate capital deployment cycles spanning 5 to 25 years. Equipment replacement timing varies dramatically across upstream, midstream, and downstream installations, reshaping vendor revenue predictability.
Technology:
Replacement cycles stretch from 15-20 years for gravity vessels to 3-5 years for membrane cartridges, creating divergent aftermarket revenue profiles.
- Gravity Separation:Horizontal and vertical vessels exploit density differentials at 50-1,500 psi operating pressure. Permian Basin tank batteries deploy these systems for bulk phase separation where produced-water volumes exceed 4:1 ratios, though deck loading constraints limit offshore retrofit options.
- Membrane Separation:Polymeric and ceramic membranes achieve selective permeation for CO2 removal and gas dehydration. Texas Panhandle gas processors substitute glycol units with membrane systems to eliminate chemical handling costs and reduce methane venting under EPA New Source Performance Standards.
- Centrifugal Separation:High-G-force disc-stack units handle emulsified crude where gravity settling fails. Offshore platforms in the Gulf of Mexico specify compact centrifugal skids to overcome footprint restrictions.
- Heat Treatment:Electrocoalescence and heater-treater vessels apply thermal energy to break water-in-oil emulsions. Delaware Basin operators pilot electrocoalescer skids that slash fuel gas consumption versus conventional fired vessels.
Gravity Separation dominates installed base. Membrane Separation is where expansion concentrates.
End User:
Capital intensity and regulatory exposure stratify end users into distinct procurement behaviors, from spot rentals to integrated engineering-procurement-construction contracts.
- Refineries:Complex fractionation trains require three-phase separation ahead of catalytic processing units. Gulf Coast refineries tie separator specifications to broader automation architectures under OSHA process safety management protocols.
- Offshore Platforms:Space-constrained installations demand skid-mounted, high-pressure systems certified to BSEE well-control standards. Vapor recovery retrofits are accelerating under finalized EPA methane rules for new and modified facilities.
- Onshore Drilling:Pad-mounted separation skids handle high-solids wellstream fluids from Permian tight oil formations. Electrocoalescence pilots at Pioneer Natural Resources and Diamondback Energy signal technology displacement of heater-treaters.
- Natural Gas Processing:Cryogenic and absorption-based NGL extraction requires inlet separation to protect downstream turboexpanders. Midstream operators unbundle service contracts from equipment procurement, creating standalone predictive maintenance revenue pools.
Refineries anchor equipment value. Onshore Drilling is expanding most quickly.
Service Type:
Margin structures invert across the service spectrum, with consulting and engineering commanding project-based premiums while maintenance and rental generate recurring, lower-margin revenue streams.
- Consulting:Process optimization studies and debottlenecking analyses for legacy Permian facilities. Digital twin integration projects combine physics-based modeling with real-time sensor feeds.
- Maintenance:Predictive service contracts now negotiate separately from original equipment procurement. Enterprise Products and Targa Resources structure multi-year agreements tied to NGL fractionation uptime economics.
- Equipment Rental:Leasing models spread capex across operating budgets for small Eagle Ford independents facing EPA vapor recovery mandates. Closed-vent system retrofits drive separator rental demand in South Texas.
- Engineering:ASME VIII pressure vessel design and third-party inspection coordination. Houston-area authorized inspection agency backlogs extend delivery timelines 8-14 weeks during peak demand cycles.
Maintenance commands recurring revenue scale. Engineering captures project-based margin concentration.
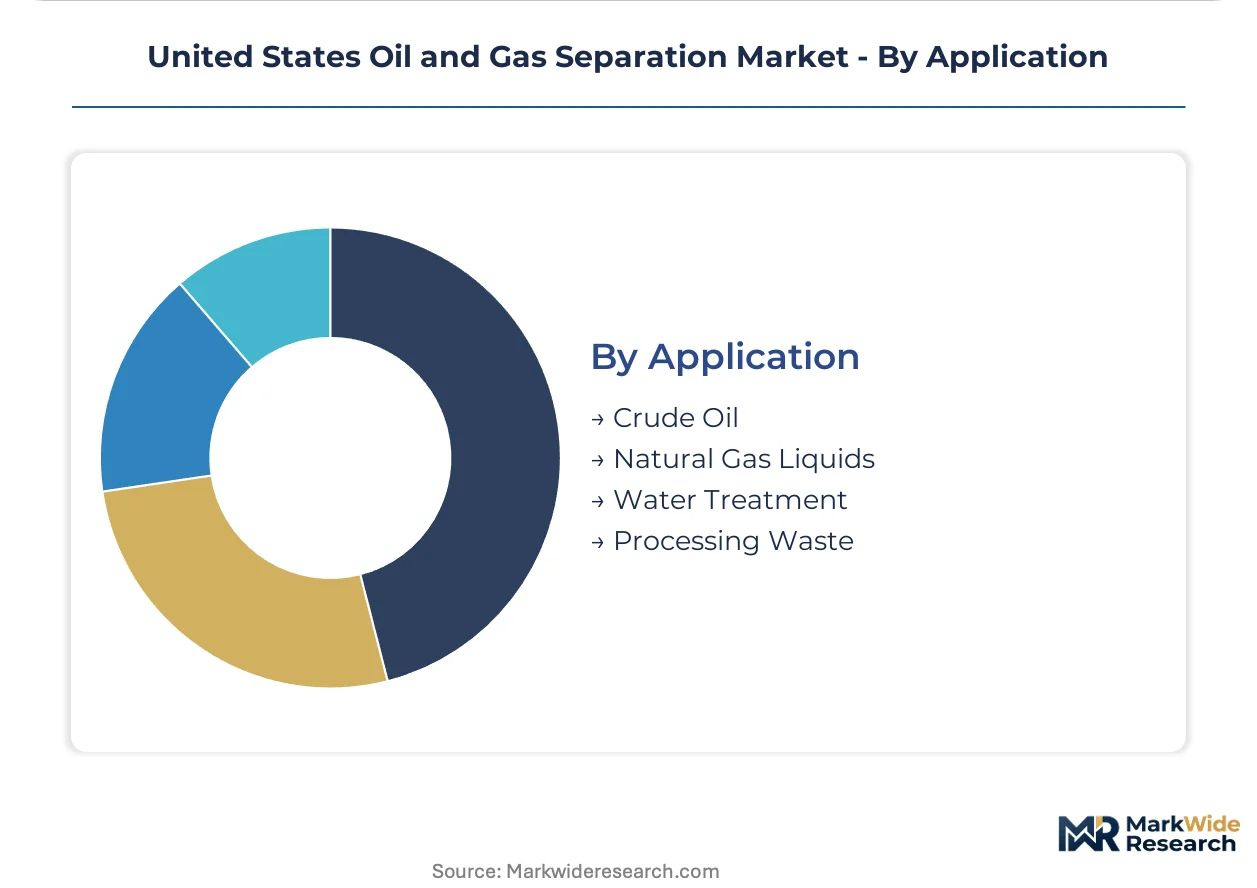
Application:
Fluid chemistry complexity and environmental discharge standards determine separation train configuration, from simple two-phase bulk separation to multi-stage polishing systems.
- Crude Oil:Dehydration and desalting to meet pipeline specifications and refinery inlet requirements. Electrocoalescence technology renders conventional heater-treater vessels obsolete in Permian pilot deployments.
- Natural Gas Liquids:Inlet separation protecting cryogenic fractionation trains from liquids carryover. Dew point control and mercury removal specifications tighten equipment metallurgy requirements.
- Water Treatment:Produced-water management for Permian disposal or reuse, with water-to-oil ratios forcing capacity expansions beyond original field development plans. Clarification and dissolved air flotation systems handle high-solids content.
- Processing Waste:Slop oil recovery and tank bottom cleaning operations. EPA discharge limits and state-level saltwater disposal regulations constrain waste stream handling economics.
Crude Oil anchors legacy infrastructure. Water Treatment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas concentrates separation demand around produced-water management and midstream processing, while New Mexico, Louisiana, Oklahoma, and North Dakota each configure equipment procurement around distinct reservoir chemistries and regulatory exposure.
Texas
Permian Basin operators face water-to-oil ratios exceeding 4:1 in Delaware Basin sub-basins, forcing three-phase separator expansions beyond original field plans. EPA New Source Performance Standards mandate vapor recovery retrofits across the Eagle Ford Shale, pressuring small independents toward equipment leasing models. Houston and Beaumont anchor heavy pressure vessel fabrication, though hurricane exposure and inspection backlogs extend delivery timelines during demand spikes.
New Mexico
Sour service specifications for H2S-rich Delaware Basin fluids require duplex stainless steel vessels, inflating fabrication costs 40-60% over carbon steel alternatives. State environmental regulations on produced-water disposal constrain tank battery configurations in the Permian's western reaches. Carlsbad and Hobbs cluster separation infrastructure around saltwater disposal well networks serving tight oil developments.
Louisiana
Offshore platforms in the Gulf of Mexico face BSEE well-control standards and finalized EPA methane rules driving vapor recovery unit installations. Space-constrained deck loading limits gravity separator expansion options, favoring compact centrifugal skids. Port Fourchon and Lake Charles concentrate fabrication and maintenance services for deepwater production facilities.
Oklahoma
SCOOP and STACK plays generate high-solids wellstream fluids demanding robust gravity separation tolerant to abrasive content. Oklahoma Corporation Commission regulations on gas capture and flaring influence separator sizing at remote well pads. Oklahoma City anchors regional equipment procurement and aftermarket service contracts for Mid-Continent operators.
North Dakota
Bakken flaring regulations create demand for compact separation-skid packages enabling gas-to-power at remote pads lacking pipeline access. State Industrial Commission gas capture targets pressure operators toward modular systems with integrated vapor recovery. Williston Basin infrastructure concentrates around Watford City and Dickinson, where winter operating conditions stress equipment metallurgy and insulation specifications.
United States Oil and Gas Separation Market Key Industry Players
Capability concentration sits with integrated technology providers; scale advantage sits with midstream infrastructure operators. The vendor base stratifies into three tiers: diversified industrial conglomerates with automation platforms, specialized oilfield service companies with digital monitoring capabilities, and midstream master limited partnerships with captive processing networks. Competitive moves center on unbundling aftermarket services from equipment procurement and integrating predictive maintenance contracts into multi-year agreements.
Within the diversified industrial tier, Honeywell International Inc. and Schlumberger Limited exemplify contrasting paths—one anchoring position through refinery automation integration, the other through offshore digital monitoring platforms. Enterprise Products Partners L.P. occupies a distinct position as midstream infrastructure scale translates into pipeline-connected processing dominance along the Texas Gulf Coast. These three represent the archetype spectrum: control-system integration, digital service extension, and captive midstream networks.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Bechtel |
| Schlumberger Limited |
| The Williams Companies, Inc. |
| Fluor Corporation |
| TechnipFMC plc |
| Exterran Corporation |
| Enterprise Products Partners L.P. |
| Alfa Laval AB |
| Others |
Cost & Logistics Intelligence
Houston Ship Channel freight corridors transmit fabrication cost volatility from Gulf Coast vessel yards directly into separator procurement budgets, concentrating pricing power among Houston and Beaumont manufacturers while forcing midstream operators to absorb transport premiums or shift to spot-market leasing models. This logistics-cost passthrough creates divergence between long-term contract pricing for integrated operators and elevated spot rates for independents lacking volume scale.
Pricing Analysis
Long-term offtake contracts dominate procurement for Permian Basin majors, locking in carbon steel vessel pricing across 3-5 year horizons while spot-market transactions prevail among Eagle Ford independents facing EPA vapor recovery mandates. Price differentiation rests on ASME VIII certification tier and duplex stainless steel metallurgy for sour service specifications. Cost compression in standard carbon steel fabrication is intensifying because hurricane-season demand spikes strain Houston-area capacity. Small independents exhibit highest price sensitivity, deferring upgrades until regulatory deadlines force action.
Supply Chain Analysis
Export control restrictions on advanced membrane ceramics and high-pressure control systems limit technology flows from Germany and Japan into domestic gas processing facilities. Raw material procurement draws from Chinese rare earth processing for ceramic membranes, Swedish specialty steel for high-pressure vessels, and domestic shale gas feedstock for polymer membrane substrates. Single-source vulnerability concentrates in Houston-area authorized inspection agencies where ASME certification backlogs extend delivery timelines. Distribution runs through midstream infrastructure operators integrating separation skids into pipeline-connected processing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States oil and gas separation market functions as a regulatory-entrenchment defensive moat, where EPA methane rules and BSEE well-control standards create asymmetric compliance burdens favoring incumbents with established certification relationships and inspection agency queue priority.
For Market Incumbents: Harden defensive positioning through captive backward integration into Houston-area pressure vessel fabrication capacity, securing queue priority at authorized inspection agencies during demand spikes. Deepen ASME VIII certification expertise to exploit third-party inspection backlogs as a competitive barrier against emerging competitors lacking established agency relationships. Prioritize predictive maintenance contract unbundling to capture recurring revenue streams before midstream operators consolidate aftermarket service procurement. For New Entrants and Emerging Players: Pursue white-space opportunities in Bakken stranded gas capture skids where North Dakota flaring regulations outpace incumbent response capacity, and in electrocoalescence technology pilots displacing conventional heater-treaters in Permian tank battery consolidation. The most penetrable segment lies in compact modular systems for remote well pads lacking pipeline access, where equipment leasing models spread capex across operating budgets for capital-constrained independents. Lead with digital twin integration capabilities to differentiate from legacy gravity-separator vendors. For Investors and Strategic Acquirers: Digital-native separation technology developers with embedded sensor architectures and physics-based modeling platforms represent the highest-conviction acquisition archetype, as electrification and predictive maintenance compress traditional 15-20 year replacement cycles. Long-term viability hinges on regulatory entrenchment deepening through successive EPA rulemakings and BSEE standard revisions. The signal to watch is ASME VIII inspection agency capacity expansion announcements, which would indicate regulatory bottlenecks easing and competitive pressure intensifying.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fabrication Capacity | Captures queue priority at Houston-area ASME inspection agencies during hurricane-season demand spikes. |
| Predictive Maintenance Contract Unbundling | Creates standalone recurring revenue pools separate from original equipment procurement at Enterprise Products scale. |
| Electrocoalescence Technology Licensing | Displaces conventional heater-treater vessels in Permian Basin pilots at Pioneer Natural Resources deployment scale. |
| Digital Twin Platform Integration | Combines physics-based separation modeling with real-time sensor feeds for predictive maintenance contracts. |
| Membrane Dehydration System Deployment | Substitutes glycol units in Texas Panhandle gas processing to eliminate chemical handling costs under EPA standards. |
Research Approach
Desk research of SEC 10-K filings from midstream master limited partnerships, EPA regulatory dockets for methane rulemakings, and BSEE well-control standard revisions preceded structured interviews with Permian Basin production engineers, Gulf Coast refinery maintenance directors, Houston-area pressure vessel fabrication procurement leads, and midstream NGL fractionation plant operators. Primary fieldwork combined with secondary validation against EIA production data, FERC pipeline capacity filings, and ASME certification records. Bottom-up equipment procurement tracking and top-down infrastructure investment analysis were triangulated to establish market sizing.
The analytical framework held EPA methane rule implementation timelines and Permian Basin water-to-oil ratio trajectories as fixed boundary conditions while varying membrane technology substitution rates and electrocoalescence adoption curves across the projection horizon. Segmentation modeling incorporated technology type, end-user capital intensity, service contract structure, and produced-water chemistry complexity. CAGRs were derived from equipment replacement cycle compression and regulatory-driven retrofit demand. Forecast inputs included Delaware Basin sour service specifications and Eagle Ford vapor recovery mandate compliance deadlines.
Sensitivities concentrate around EPA rulemaking acceleration or delay, hurricane-season fabrication capacity disruptions, and membrane ceramic supply interruptions from export control enforcement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Mud Logging Unit Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
Asphaltene Inhibitors Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Europe Coiled Tubing Market