
 Digital Oilfield Solutions Market | 2026-2036
Digital Oilfield Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Oilfield Solutions Market Analysis
The EPA's methane emissions standards is pivoting the competitive landscape by mandating continuous monitoring infrastructure that only well-capitalized technology providers can deliver at scale. Schlumberger Limited leverages its integrated hardware-software portfolio to anchor deepwater digitalization contracts across multiple basins. Halliburton Company competes through specialized edge-computing deployments that sustain real-time drilling optimization. Baker Hughes Company differentiates via predictive maintenance platforms that dominate North American shale operator procurement cycles.
Digital oilfield solutions encompass sensor networks, telemetry systems, and cloud-based analytics platforms that collect, transmit, and process subsurface and surface operational data to optimize hydrocarbon extraction efficiency. These systems typically operate across temperature ranges exceeding 150°C at downhole conditions while maintaining sub-second latency for closed-loop automation. The hardware integration segment occupies the largest value pool as operators retrofit existing assets with IoT-enabled instrumentation. AI-driven reservoir management applications represent the fastest-expanding category, with cloud computing services capturing disproportionate margin growth as vendors shift from perpetual licenses to recurring revenue models.
The US EPA, the EU's F-Gas Regulation, and Saudi Arabia's national emissions reduction framework collectively shape equipment certification requirements and data transparency obligations across major producing regions. Compliance timelines in the European Union and North America are compressing procurement cycles for certified monitoring hardware. Stakeholders must weigh the capital intensity of full-stack platform ownership against the flexibility of managed service partnerships as reservoir complexity escalates.
Market Dynamics
Aramco's procurement benchmarks are compressing vendor qualification timelines across Middle Eastern national oil companies, forcing technology providers to restructure service delivery models around integrated platform commitments rather than point solutions.
Growth Catalysts
- EPA Methane Rules:Continuous monitoring mandates in US onshore operations are accelerating hardware refresh cycles for leak detection infrastructure.
- Saudi Arabia's Emissions Framework:National reduction targets are digitizing wellhead operations across the Kingdom's mature fields faster than technical depreciation schedules would otherwise permit.
- Edge Computing Architectures:Real-time drilling optimization is pulling capital from centralized data centers toward rig-site processing units with sub-50 millisecond response thresholds.
Market Restraints
- High-Temperature Sensor Costs:Downhole instrumentation rated above 175°C relies on specialized ceramic packaging that concentrates supply among three Japanese component foundries.
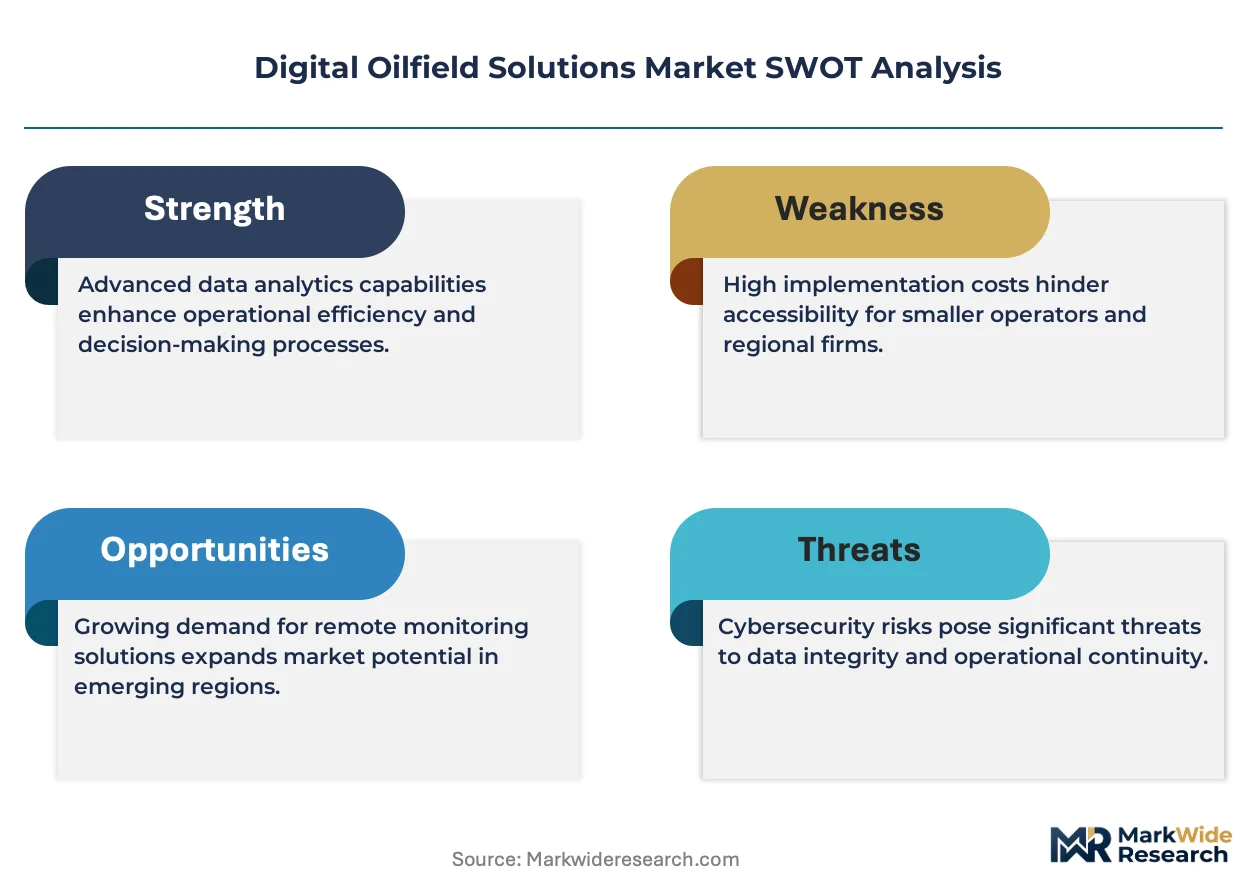
- Cybersecurity Certification Delays:IEC 62443 compliance timelines for oilfield networks extend 14-18 months, freezing procurement for operators in regulated jurisdictions.
- Legacy SCADA Integration:Proprietary protocols from 1990s-era distributed control systems resist API-standard data exchange without expensive middleware layers.
Strategic Opportunities
- Kuwait's Digital Field Pilots:Kuwait Oil Company is tendering integrated production optimization platforms across its Burgan and Minagish assets with 10-year service horizons.
- AI-Reservoir Convergence:Physics-informed neural networks are merging with traditional simulation workflows to compress history-matching cycles from months to days.
- EU F-Gas Regulation:Refrigerant phase-down schedules are creating retrofit demand for gas-compressor monitoring systems that track seal integrity in real time.
Industry Challenges
- Subsurface Data Science Talent:Reservoir engineers with simultaneous fluency in geomechanics and Python-based machine learning pipelines command compensation premiums exceeding 40% above conventional petroleum engineering roles.
- Multi-Vendor Platform Interoperability:Operators assembling best-of-breed sensor, telemetry, and analytics layers face API versioning conflicts that degrade closed-loop automation reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Oilfield Solutions Market |
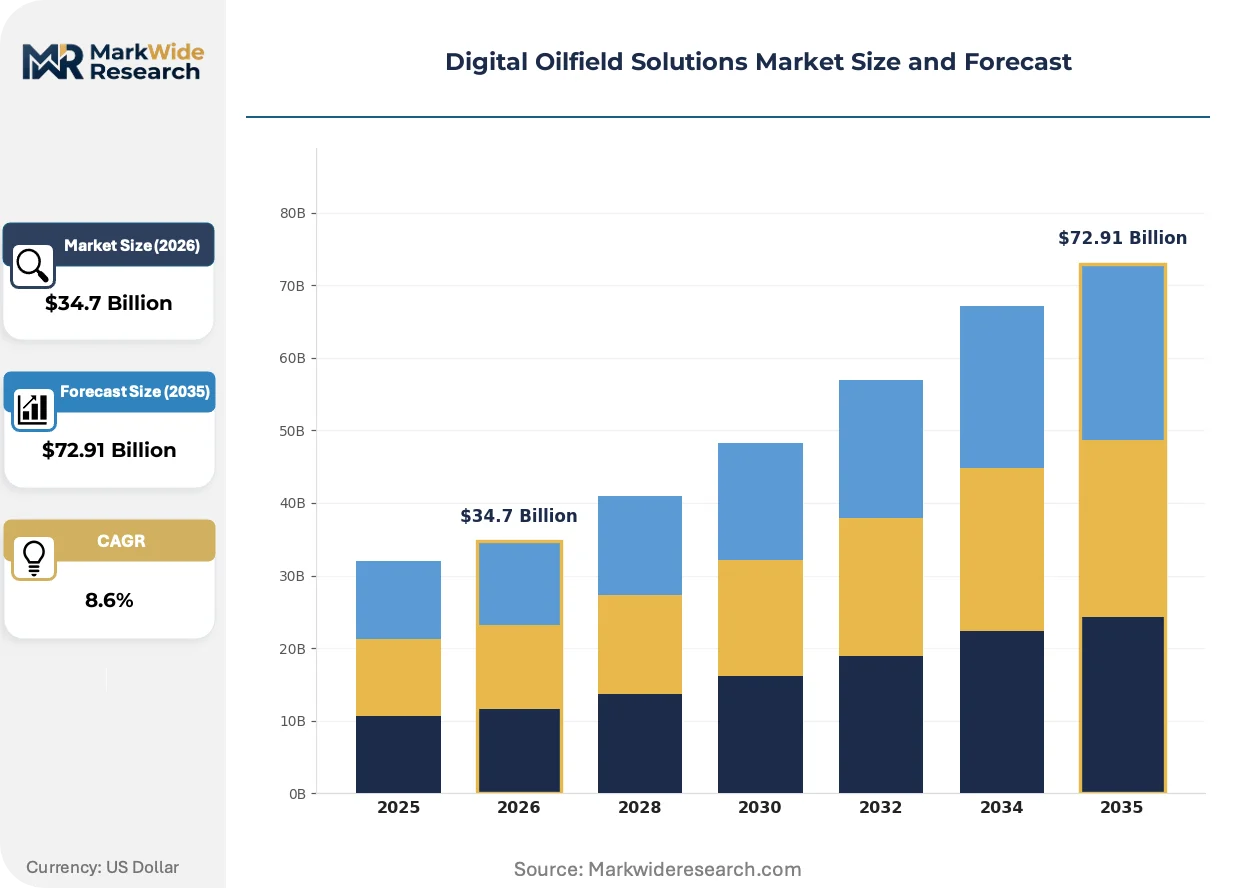
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Cloud Computing, Data Analytics Service Type: Consulting, Managed Services, Software Solutions, Hardware Integration Application: Reservoir Management, Production Optimization, Drilling Automation, Asset Tracking End User: Oil & Gas Operators, Service Companies, Equipment Manufacturers, Energy Investors |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International plc, NOV Inc., Emerson Electric Co., ABB Ltd, Pason Systems Corp., Rockwell Automation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Oilfield Solutions Market Emerging Trajectories
Digital oilfield architecture is fragmenting from monolithic enterprise platforms toward composable systems that operators can reconfigure without vendor lock-in. This decomposition is rewriting competitive advantage around integration flexibility rather than functional breadth.
Downhole sensing hardware is modularizing around standardized mechanical interfaces and digital communication buses. Independent sensor manufacturers in Norway and Texas are shipping pressure-temperature arrays that slot into legacy gauge carriers without full workover. This modularity is compressing replacement economics and enabling incremental capability upgrades that bypass capital-intensive well interventions.
The EU's F-Gas Regulation is forcing compressor station operators to install continuous seal-monitoring infrastructure with automated venting detection. Equipment suppliers are embedding infrared spectroscopy into existing pneumatic actuator housings to satisfy certification requirements without structural modifications. North American shale operators are voluntarily adopting equivalent specifications to preempt forthcoming EPA alignment with European methane intensity standards.
Subscription pricing for reservoir analytics is displacing perpetual software licenses across supermajor procurement desks. Chevron and BP are negotiating enterprise-wide access agreements that bundle cloud compute, support, and feature updates into single operational expenditure lines. This shift is most visible in the Permian Basin, where independent producers facing capital discipline pressures prefer predictable monthly costs over upfront license commitments that strain borrowing base calculations.
Digital Oilfield Solutions Market Segmentation
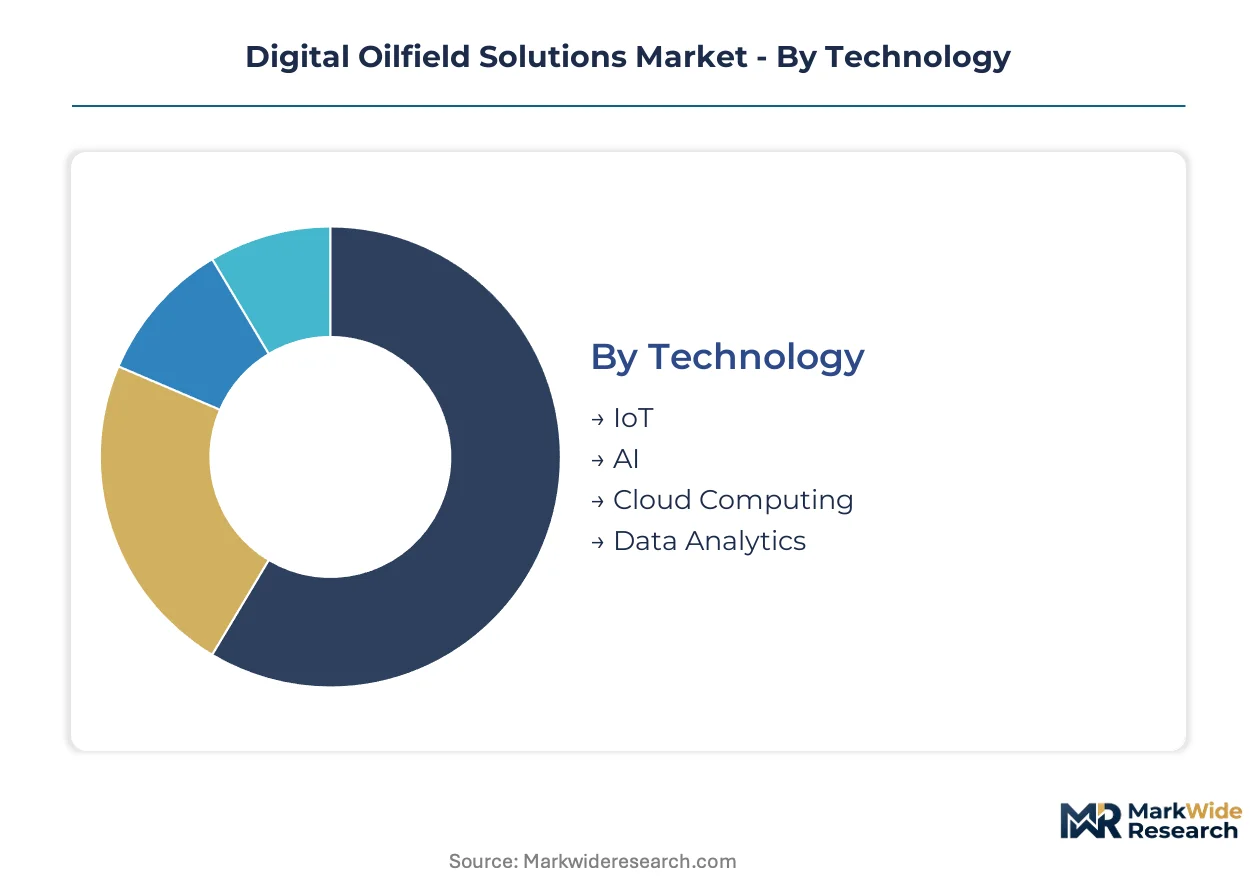
Capital allocation patterns across digital oilfield deployments vary sharply by technology maturity and integration complexity. Procurement committees weight upfront infrastructure costs against recurring operational expenditure models when selecting vendor configurations.
Technology:
Capital intensity concentrates in edge hardware and specialized downhole instrumentation that must survive temperature extremes above 150°C.
- IoT:Sensor networks combining pressure-temperature gauges, flow meters, and vibration monitors transmit subsurface data through wireless mesh protocols. Demand clusters in Saudi Arabia's mature field digitization programs where Aramco mandates standardized device certification.
- AI:Physics-informed neural networks compress reservoir simulation cycles from months to days through automated history-matching algorithms. North American shale operators deploy these tools to optimize infill drilling spacing in the Permian Basin.
- Cloud Computing:Distributed compute clusters host real-time analytics with sub-second latency requirements for closed-loop automation.
- Data Analytics:Visualization dashboards and predictive models integrate SCADA streams with enterprise resource planning systems.
IoT sensor hardware absorbs the bulk of installed capacity; AI applications are expanding most quickly.
Service Type:
Revenue models diverge between capital-intensive hardware ownership and operational expenditure-based managed service agreements.
- Hardware Integration:Downhole gauge carriers, surface telemetry units, and edge computing enclosures require specialized metallurgy and ceramic packaging. Kuwait Oil Company's Burgan field tenders specify 10-year service horizons with integrated maintenance commitments.
- Managed Services:Subscription platforms bundle cloud infrastructure, software updates, and technical support into predictable monthly fees. Independent Permian producers facing capital discipline pressures favor this structure over perpetual license purchases.
- Software Solutions:Reservoir simulation, production optimization, and drilling analytics packages deploy across on-premise and hybrid cloud architectures.
- Consulting:Implementation planning, change management, and workforce training support technology adoption.
Hardware integration commands the largest share of current procurement value; managed services are climbing the fastest as vendors shift from license sales to recurring revenue.
Application:
Functional priority varies by basin maturity, with brownfield assets emphasizing production recovery and greenfield developments targeting drilling efficiency.
- Production Optimization:Real-time artificial lift control, gas-lift automation, and facility throughput maximization systems extend plateau production from mature wells. Saudi Arabia's national emissions reduction framework accelerates wellhead digitization beyond normal technical depreciation schedules.
- Reservoir Management:4D seismic interpretation, fluid contact tracking, and pressure transient analysis integrate static and dynamic subsurface models. Supermajors deploy these capabilities across deepwater developments in the Gulf of Mexico.
- Drilling Automation:Closed-loop directional control, managed pressure drilling, and automated tripping systems reduce non-productive time.
- Asset Tracking:RFID-tagged equipment monitoring and predictive maintenance scheduling optimize spare parts inventory.
Production optimization captures the greatest deployment density; reservoir management is gaining share fastest through AI convergence with traditional simulation workflows.
End User:
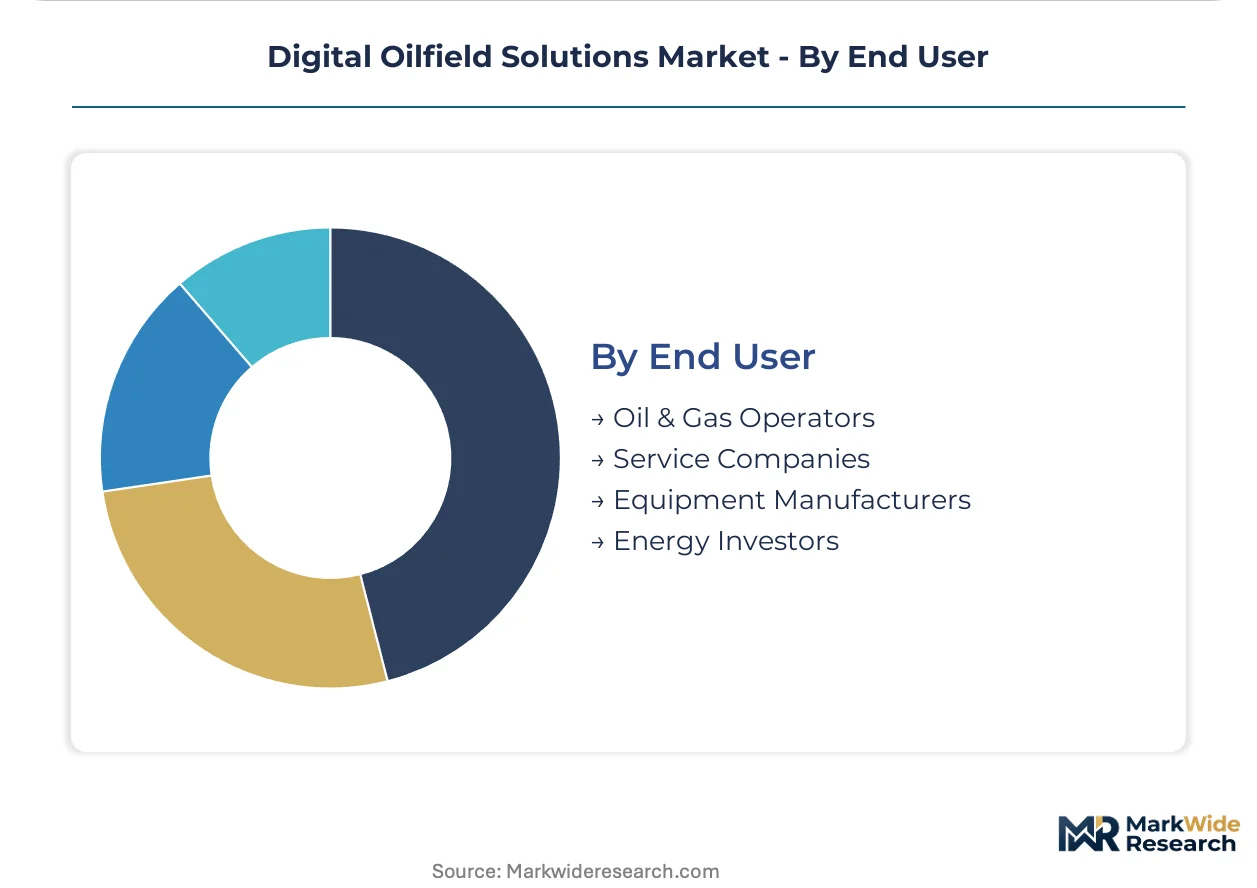
Buying authority fragments between operators controlling capital budgets and service companies specifying interoperable technical standards.
- Oil & Gas Operators:National oil companies and international majors set procurement benchmarks for integrated platform architectures. Aramco's vendor qualification timelines compress supplier margins across Middle Eastern markets.
- Service Companies:Drilling contractors and completion specialists specify edge-computing hardware for rig-site automation. Halliburton and Schlumberger influence telemetry protocol standards through proprietary system deployments.
- Equipment Manufacturers:Pump, compressor, and valve suppliers embed sensing capabilities into original equipment specifications.
- Energy Investors:Private equity and infrastructure funds demand operational transparency for reserve valuation and emissions disclosure.
Oil & gas operators direct the majority of procurement expenditure; service companies are expanding their technology influence fastest through integrated service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates in Saudi Arabia, where Aramco's integrated platform mandates are setting technical standards that ripple through Middle Eastern national oil company budgets and reshape vendor qualification timelines.
United States
EPA methane emissions rules are forcing continuous monitoring installations across Permian Basin wellheads faster than normal capital cycles permit. The country's national environmental regulator compresses hardware procurement timelines for leak detection infrastructure. Houston anchors the vendor ecosystem, with technology providers restructuring service delivery around integrated platform commitments.
Saudi Arabia
Aramco's digital transformation programs are digitizing mature field operations across the Kingdom's Ghawar and Safaniya assets. The national emissions reduction framework accelerates wellhead instrumentation beyond technical depreciation schedules. Dhahran concentrates vendor engineering resources, with procurement benchmarks compressing supplier margins across adjacent Gulf markets.
Norway
North Sea operators are deploying subsea digitalization packages to extend plateau production from aging deepwater installations. The country's petroleum regulator mandates standardized data transparency protocols for reservoir reporting. Stavanger hosts specialized sensor manufacturers shipping modular pressure-temperature arrays that slot into legacy gauge carriers.
United Arab Emirates
ADNOC's integrated control room investments are pulling capital toward centralized analytics platforms for offshore Upper Zakum operations. The national oil company's procurement frameworks emphasize 10-year service horizons with bundled maintenance commitments. Abu Dhabi concentrates engineering talent for artificial lift optimization and real-time production surveillance.
Canada
Oil sands operators are retrofitting steam-assisted gravity drainage sites with edge-computing architectures to reduce per-barrel emissions intensity. The country's federal methane regulations align with forthcoming EPA standards, accelerating monitoring hardware refresh cycles. Calgary anchors software development for reservoir analytics, with vendors shifting from perpetual licenses to subscription pricing models.
Digital Oilfield Solutions Market Vendor Landscape
United States producers anchor one tier; European automation specialists hold differentiated positions in control systems and telemetry hardware. The vendor structure concentrates around integrated service companies with full-stack platform capabilities and independent sensor manufacturers with modular hardware designs. Three archetypes dominate: bundled hardware-software providers, specialized edge-computing deployers, and predictive maintenance platform operators. Competitive moves center on strategic partnerships for cloud infrastructure access and portfolio diversification into adjacent emissions monitoring applications.
Within the integrated service tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company occupy positions that exemplify contrasting technical specializations. Schlumberger represents the full-stack platform archetype with deepwater digitalization credentials. Halliburton sits within the edge-computing specialization, emphasizing rig-site processing for real-time drilling optimization. Baker Hughes anchors predictive maintenance capabilities, particularly across North American shale operator procurement cycles. These three entities collectively illustrate how vendor positioning fragments between bundled integration and targeted functional depth.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| NOV Inc. |
| Emerson Electric Co. |
| ABB Ltd |
| Pason Systems Corp. |
| Rockwell Automation Inc. |
| Others |
Supply Flow & Price Mechanics
Aramco's compressed vendor qualification timelines are forcing technology providers to absorb upfront integration costs that would otherwise flow through to buyers, squeezing margins across hardware-software bundles while concentrating procurement power with national oil companies capable of multi-year platform commitments.
Pricing Analysis
Volume capture concentrates in hardware integration contracts while margin expansion sits with managed services and cloud analytics subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates Aramco-grade certified systems from Permian Basin deployment packages and legacy SCADA retrofit bundles. Pricing pressure stems from Kuwait Oil Company's 10-year service horizon tenders that demand integrated maintenance commitments. Independent Permian producers exhibit highest price sensitivity due to capital discipline constraints, while Saudi Aramco and ADNOC demonstrate lowest sensitivity given emissions compliance mandates.
Supply Chain Analysis
High-temperature ceramic packaging for downhole sensors rests on three Japanese specialty foundries, creating single-source vulnerability for instrumentation rated above 175°C. Silicon carbide substrates, sapphire pressure windows, and hermetic feedthrough connectors anchor component costs. Distribution runs through Houston engineering clusters for North American shale operators and Dhahran vendor qualification centers for Middle Eastern national oil companies. Tariff exposure on Japanese ceramic components threatens cost stability for edge hardware manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital oilfield architecture is transitioning from perpetual license software to subscription-based cloud analytics, with physics-informed neural networks displacing traditional reservoir simulation workflows that required months of history-matching cycles.
For Market Incumbents: Deepen backward integration into high-temperature ceramic packaging to reduce dependency on Japanese foundries and defend margin position against modular sensor entrants. Secure IEC 62443 certification pipelines ahead of compliance deadlines to freeze out competitors in regulated European and North American jurisdictions.
For New Entrants and Emerging Players: Enter via modular pressure-temperature arrays that slot into legacy gauge carriers without full workover, targeting Norway's Stavanger sensor manufacturing cluster and independent Permian producers seeking incremental upgrade paths. Emphasize API-standard data exchange protocols to bypass proprietary SCADA middleware costs.
For Investors and Strategic Acquirers: The window for entry favors edge-computing specialists with sub-50 millisecond rig-site processing capabilities and AI-reservoir convergence platforms that compress simulation cycles. Watch EPA-EU regulatory alignment on methane intensity standards as the inflection trigger for cross-Atlantic monitoring hardware demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Schlumberger's full-stack deployments anchor deepwater digitalization contracts across multiple basins. |
| Edge Computing Specialization | Halliburton's rig-site processing units sustain real-time drilling optimization with sub-50 millisecond response. |
| Predictive Maintenance Expansion | Baker Hughes dominates North American shale operator procurement cycles through asset health platforms. |
| Emissions Monitoring Certification | EPA methane rules and EU F-Gas Regulation create retrofit demand for continuous seal-monitoring infrastructure. |
| Subscription Revenue Transition | Chevron and BP enterprise agreements bundle cloud compute and support into single operational expenditure lines. |
Methodological Framework
Independent corroboration across reservoir engineering directors, digital transformation leads at national oil companies, edge hardware procurement officers, and cloud analytics vendor executives underwrites the qualitative findings. Primary interviews combined with secondary validation from SEC filings, EPA regulatory dockets, Aramco procurement disclosures, and IEC certification databases. Bottom-up sensor deployment counts triangulate against top-down platform revenue estimates.
Rate-of-change decomposition separates hardware refresh cycles from software subscription ramps across the analysis window. Segmentation dimensions include technology tier, service type contract structure, application function, and end-user buying authority. CAGRs derive from fitted trend lines through historical deployment data and regulatory compliance timeline compression. Forecast inputs incorporate Aramco's vendor qualification pace and EPA enforcement schedule acceleration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cybersecurity certification delays and Japanese ceramic supply disruptions. Forecasts reflect documented assumptions regarding emissions regulation harmonization and edge computing adoption curves. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Canada Oil and Gas Pipeline Services Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Natural Gas Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Gulf of Mexico Oil and Gas Upstream Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Dry Natural Gas Market
Oil & Gas
Russia Drill Pipe Market