
 Brazil Oil and Gas Market | 2026-2036
Brazil Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Oil and Gas Market Analysis
Multi-source procurement for offshore drilling equipment is recalibrating supply chain risk across Brazilian operators. Petrobras anchors deepwater exploration through its pre-salt field dominance. Shell Brasil leverages integrated project capabilities across Campos and Santos basin developments. 3R Petroleum Óleo e Gás SA specializes in revitalizing mature onshore concessions in the Potiguar and Recôncavo basins.
Brazil oil and gas encompasses the exploration, production, refining, and distribution of hydrocarbon resources including crude oil with API gravities ranging from light pre-salt grades to heavy offshore varieties, processed through fractional distillation and catalytic cracking to yield fuels and chemical feedstocks. The upstream segment dominates capital deployment, with pre-salt reservoirs requiring subsea separation and high-pressure injection systems at depths exceeding 2,000 meters. Downstream refining faces structural margin pressure from aging facilities, while midstream transportation infrastructure expands to connect isolated production zones to coastal terminals.
ANP licensing rounds and local content mandates shape operator procurement and field development timelines. Petrobras governance reforms under the New Gas Market program are opening pipeline access to third parties. IBAMA environmental licensing requirements constrain project approval velocity in environmentally sensitive coastal zones. Stakeholders must monitor regulatory arbitration between production acceleration targets and environmental compliance thresholds.
Market Dynamics
Pre-salt reservoir complexity is compressing development timelines across Brazilian offshore blocks, forcing operators to resequence capital deployment around subsea separation systems and high-pressure injection infrastructure at depths exceeding 2,000 meters.
Growth Catalysts
- ANP Local Content Mandates:Procurement rules for offshore platforms now require domestic sourcing thresholds, redirecting equipment spend toward Brazilian fabrication yards and engineering services.
- New Gas Market Program:Petrobras governance reforms are opening pipeline access to third parties, fragmenting midstream control and enabling independent producer offtake.
- Pre-salt Appraisal Drilling:Santos basin operators are accelerating well completion rates through subsea tieback architectures that reduce surface facility requirements.
Market Restraints
- Steel Input Volatility:Offshore platform construction faces margin pressure from fluctuating specialized alloy and thick-plate steel costs.
- IBAMA Licensing Friction:Environmental approval velocity in coastal zones constrains project sanctioning timelines for sensitive pre-salt developments.
- Subsea Equipment Supply Concentration:High-pressure Christmas tree and manifold fabrication relies on a limited supplier base concentrated in European and Asian manufacturing hubs.
Strategic Opportunities
- Mature Field Revitalization:Potiguar and Recôncavo basin onshore concessions offer low-decline production profiles through enhanced recovery and infill drilling.
- Refinery Feedstock Integration:Petrochemical operators are expanding domestic naphtha offtake, reducing import dependency for chemical precursor supply.
- Carbon Capture Adjacencies:Pre-salt CO2-rich gas streams create feasibility for saline aquifer sequestration tied to production tax incentives.
Industry Challenges
- Deepwater Completion Engineering Scarcity:Subsea system design and high-pressure well intervention expertise remains concentrated among a narrow specialist workforce.
- Legacy Refinery Asset Obsolescence:Aging downstream facilities require sustained turnaround investment to maintain distillate yield competitiveness against import parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Oil and Gas Market |
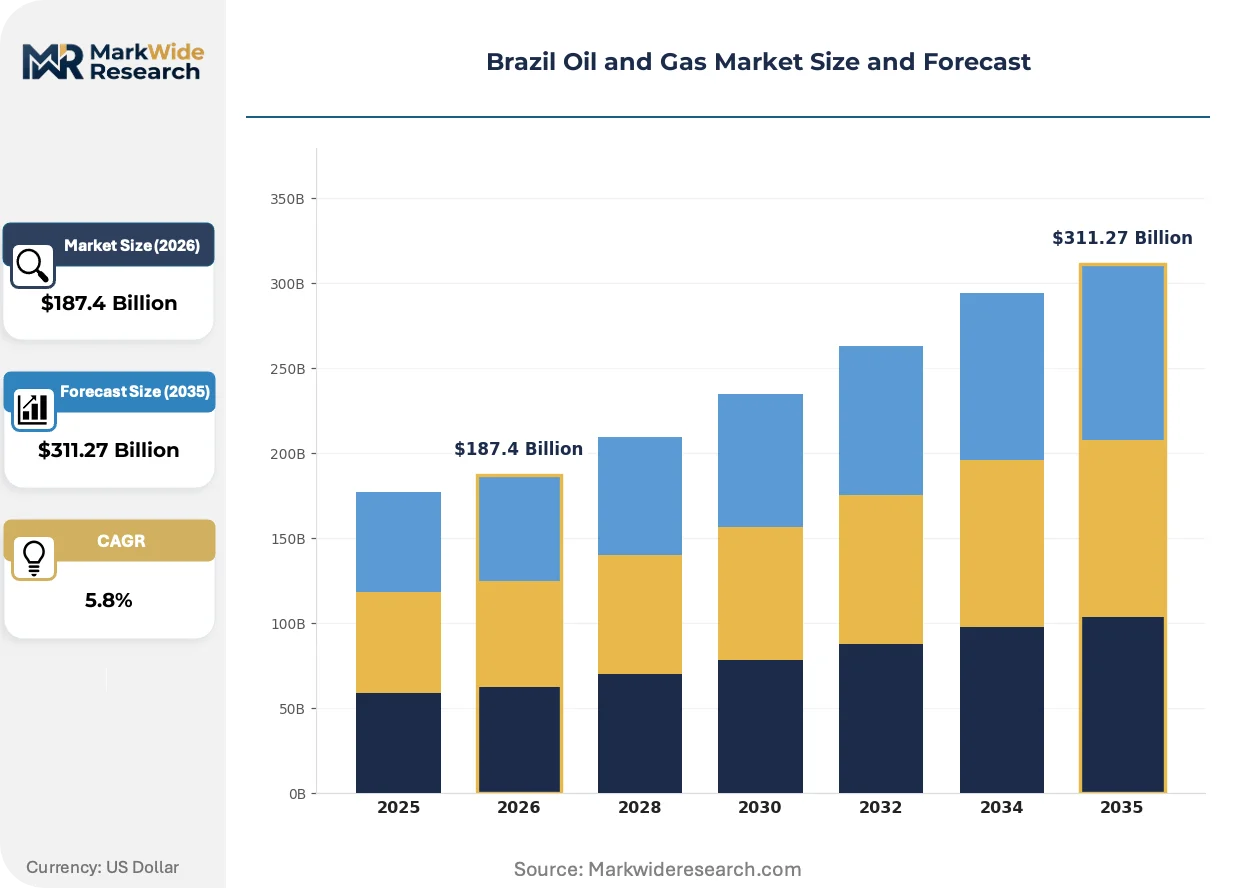
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Market Type: Upstream, Midstream, Downstream, Service Providers Technology: Exploration, Refining, Transportation, Production Application: Power Generation, Petrochemicals, Heating, Transportation Fuels End User: Industrial, Commercial, Residential, Government |
| Companies Covered | TotalEnergies, 3R Petroleum Óleo e Gás SA, Petrobras, Petroreconcavo SA, Enauta Participacoes SA, Shell Brasil, Petro Rio SA, Repsol Sinopec Brasil, Equinor ASA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Oil and Gas Market Emerging Trajectories
Digital reservoir characterization and electrified subsea processing are compressing field development cycles, while regulatory arbitration between production targets and environmental compliance is rewriting project sanctioning protocols across Brazilian offshore concessions.
Subsea electrification architectures are displacing hydraulic power and chemical injection umbilicals across Santos basin pre-salt developments. Petrobras and international partners are deploying all-electric Christmas trees and subsea boosting stations at 2,500-meter depths. This infrastructure shift is electrifying power distribution topology, eliminating hydraulic fluid leakage risks and enabling real-time downhole monitoring through permanent electrical gauges.
ANP's revised local content frameworks are tightening domestic procurement thresholds for platform hulls, topsides modules, and subsea manifolds. Operators must now certify Brazilian fabrication yard participation percentages before field development plan approval. Deepwater projects in the Campos basin are responding by consolidating engineering contracts with domestic shipyards to secure licensing round participation eligibility.
Integrated project delivery contracts are displacing traditional EPC segmented sourcing for pre-salt developments. IOCs and independents now bundle subsurface engineering, drilling, and subsea installation under single accountability structures. This procurement consolidation is most visible in the Búzios and Mero field expansions, where lump-sum turnkey terms transfer cost overrun risk to integrated service providers.
Brazil Oil and Gas Market Segmentation
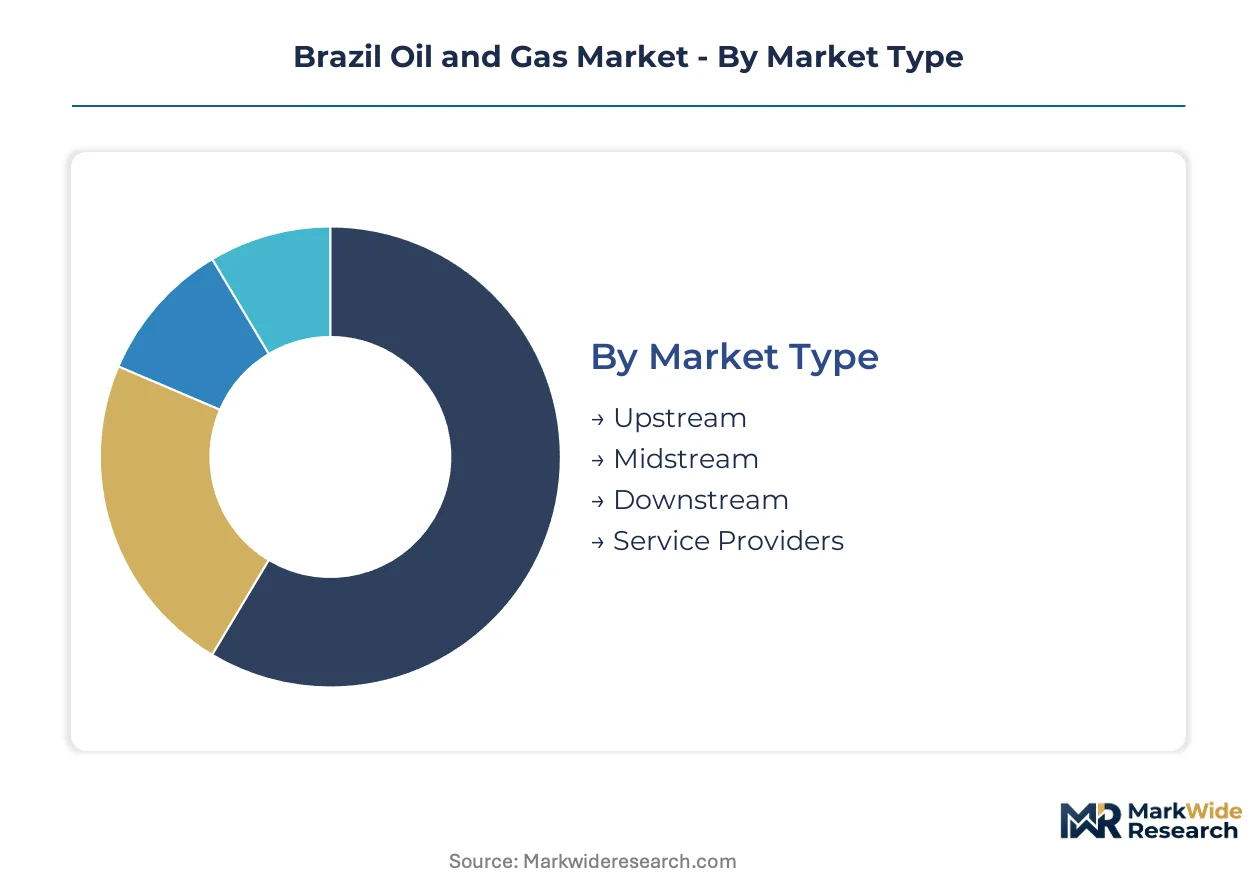
Segmentation in Brazil's oil and gas sector reveals how capital allocation, regulatory mandates, and reservoir complexity concentrate value across distinct operational layers. Understanding these divisions illuminates where ANP local content rules, pre-salt development costs, and downstream margin pressures reshape competitive positioning.
Market Type:
Supply concentration varies sharply across operational stages, with pre-salt capital intensity favoring integrated operators capable of absorbing billion-dollar field development cycles.
- Upstream:Exploration and production activities targeting pre-salt carbonate reservoirs at 2,000+ meter depths. Demand concentrates in the Santos basin where Petrobras and partners deploy subsea separation systems; ANP production-sharing contracts mandate specific investment timelines.
- Midstream:Pipeline transportation, storage terminals, and gas processing infrastructure. The New Gas Market program is fragmenting Petrobras's former pipeline monopoly, creating third-party access points for independent producers in isolated production zones.
- Downstream:Refining operations converting crude into transportation fuels and petrochemical feedstocks. Aging facilities in São Paulo and Rio de Janeiro states face structural margin pressure against import parity pricing.
- Service Providers:Drilling contractors, subsea installation specialists, and engineering consultancies. Brazilian fabrication yards capture hull and topside module construction under tightened local content thresholds.
Upstream absorbs the bulk of installed capacity; midstream is expanding most quickly under regulatory opening.
Technology:
Cost tier differentiation separates capital-intensive subsea systems from operational technologies with shorter depreciation cycles.
- Exploration:Seismic imaging, well logging, and reservoir characterization deploying 4D seismic and electromagnetic surveys. Pre-salt appraisal drilling in the Búzios field relies on high-resolution subsalt imaging to reduce dry-hole risk.
- Production:Subsea boosting, artificial lift, and high-pressure injection systems for ultra-deepwater fields. Electrified Christmas trees at 2,500-meter depths in Santos basin developments displace hydraulic power architectures.
- Refining:Catalytic cracking, hydroprocessing, and distillation units processing varying API gravity crudes. Legacy facilities require sustained turnaround investment to maintain distillate yield competitiveness.
- Transportation:Pipeline networks, tanker logistics, and coastal terminal operations connecting production zones to refining centers. IBAMA environmental licensing constrains new coastal terminal approvals in sensitive zones.
Production technology commands the highest capital intensity per unit; exploration is gaining share fastest as operators accelerate pre-salt appraisal.
Application:
Volume concentration tracks industrial demand centers, with petrochemical feedstock offtake reshaping refinery output allocation.
- Transportation Fuels:Gasoline, diesel, and aviation kerosene supplying Brazil's vehicle fleet and logistics networks. Demand concentrates in São Paulo state's industrial corridor where freight density peaks.
- Petrochemicals:Naphtha, ethane, and propane feedstocks for chemical manufacturing. Domestic refineries are expanding supply to reduce import dependency for polyethylene and polypropylene precursors.
- Power Generation:Natural gas and fuel oil for thermal electricity plants. Isolated northern regions rely on liquid fuels where pipeline infrastructure remains underdeveloped.
- Heating:Residential and commercial fuel oil and natural gas consumption. Demand clusters in southern states with seasonal temperature variation.
Transportation fuels absorb the bulk of installed capacity; petrochemicals is climbing the fastest on feedstock integration investments.
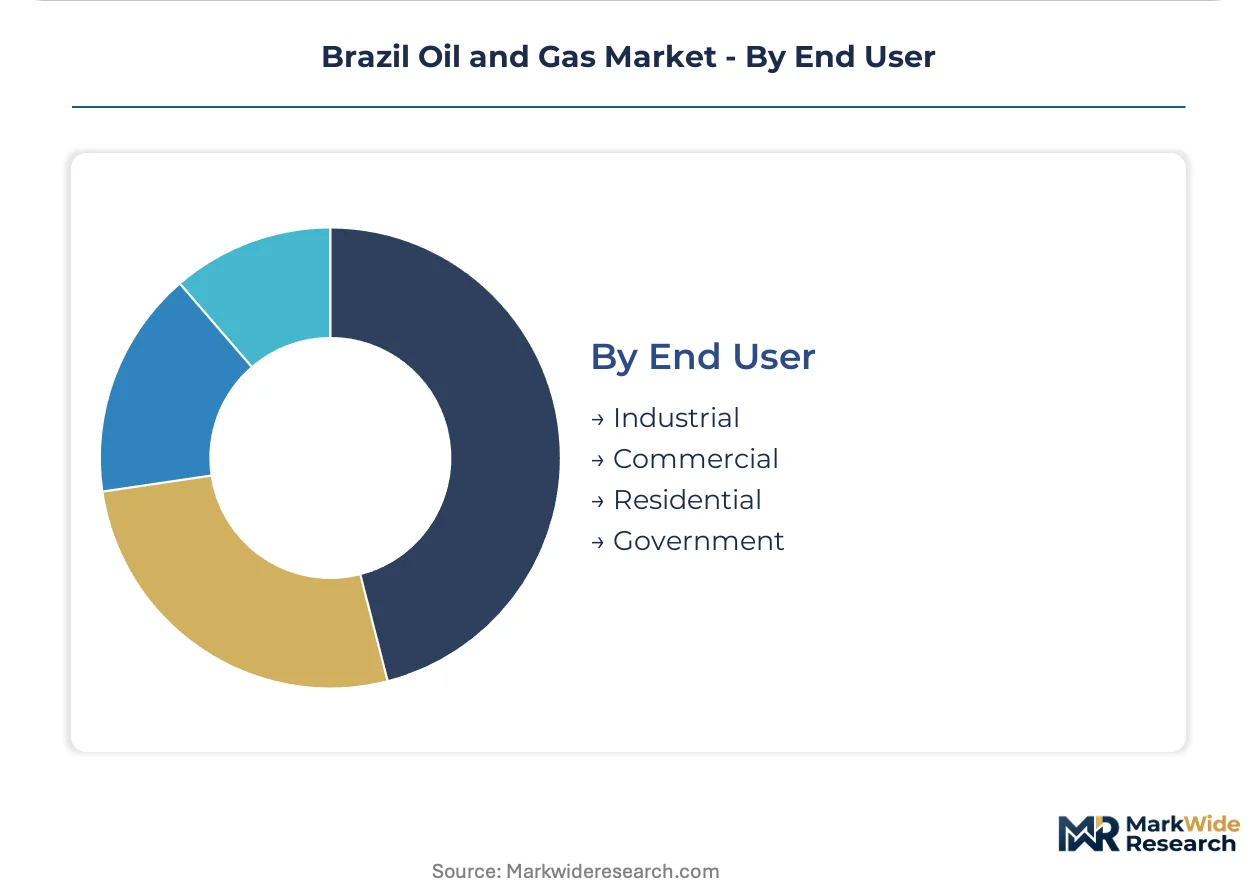
End User:
Customer type determines contract structure, with industrial offtake favoring long-term supply agreements against spot market exposure.
- Industrial:Manufacturing, mining, and chemical processing operations consuming bulk hydrocarbon inputs. São Paulo state's automotive and steel sectors anchor demand for consistent fuel and feedstock supply.
- Commercial:Retail fuel stations, aviation terminals, and marine bunkering operations. ANP price parity regulations govern downstream margin structures for independent distributors.
- Government:Strategic reserves, military procurement, and state-owned enterprise supply. Petrobras's dominance in public sector contracting shapes competitive access.
- Residential:LPG for cooking and limited natural gas connections in urban centers. Distribution infrastructure gaps constrain penetration outside major metropolitan areas.
Industrial end users absorb the bulk of installed capacity; commercial is expanding most quickly on retail network densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pre-salt carbonate reservoirs off the coast of Rio de Janeiro anchor Brazil's hydrocarbon production gravity, with subsea infrastructure investments concentrating capital deployment in the Santos basin.
São Paulo
Industrial fuel demand from automotive and steel sectors drives consumption in the ABC Paulista corridor. ANP downstream pricing regulations govern margin structures for independent distributors operating retail networks. The Cubatão refinery complex processes heavy crude imports alongside domestic pre-salt feedstock.
Rio de Janeiro
Pre-salt field development absorbs upstream capital through subsea separation systems at 2,000-meter depths. IBAMA environmental licensing constrains coastal terminal approvals in sensitive Guanabara Bay zones. Macaé serves as the primary offshore services cluster, hosting fabrication yards and engineering consultancies under tightened local content mandates.
Minas Gerais
Steel and mining operations consume diesel and fuel oil for heavy equipment fleets across the Iron Quadrangle. State environmental agencies coordinate with federal regulators on pipeline corridor permitting. Belo Horizonte anchors logistics networks distributing refined products to interior consumption centers.
Rio Grande do Sul
Seasonal heating demand peaks during winter months, creating natural gas consumption spikes in Porto Alegre metropolitan areas. Petrobras pipeline infrastructure connects southern markets to offshore production zones. Canoas hosts petrochemical complexes expanding naphtha offtake from domestic refineries.
Bahia
The Candeias basin mature fields require enhanced recovery investments to sustain production decline curves. State development agencies promote local content participation for onshore service contracts. Salvador serves as the northern logistics hub connecting isolated production to coastal terminals.
Brazil Oil and Gas Market Vendor Landscape
Integrated project delivery dominates the current landscape, with operators bundling subsurface engineering and subsea installation under single accountability structures. The market concentrates around state-affiliated and international oil companies capable of absorbing billion-dollar field development cycles. Two strategic archetypes prevail: pre-salt specialists deploying ultra-deepwater infrastructure, and mature field revitalizers targeting low-decline onshore concessions. M&A consolidation and local content compliance represent the dominant competitive moves reshaping participant positioning.
Among Brazil-based operators, Petrobras anchors pre-salt development through its dominant production-sharing contract portfolio. Shell Brasil occupies a position exemplifying integrated international capability across Campos and Santos basin developments. 3R Petroleum Óleo e Gás SA represents the mature field revitalization archetype, specializing in enhanced recovery within Potiguar and Recôncavo basin concessions.
| Leading Market Players |
|---|
| TotalEnergies |
| 3R Petroleum Óleo e Gás SA |
| Petrobras |
| Petroreconcavo SA |
| Enauta Participacoes SA |
| Shell Brasil |
| Petro Rio SA |
| Repsol Sinopec Brasil |
| Equinor ASA |
| Others |
Supply Flow & Price Mechanics
Subsea completion engineering scarcity in Macaé's offshore services cluster widens pricing spreads between integrated project bundles and unbundled procurement, with labor-cost differentials separating premium all-electric subsea systems from standard hydraulic architectures.
Pricing Analysis
Service-bundling configurations separate lump-sum turnkey contracts with embedded cost-overrun protection from unbundled EPC sourcing where operators retain completion risk. Price differentiation rests on local content certification tiers and subsea equipment integration depth; ANP-mandated domestic yard participation commands premiums over import-dependent sourcing. Cost compression in standard hydraulic systems is intensifying because European and Asian equipment suppliers face capacity constraints. Independent producers in isolated production zones exhibit highest price sensitivity, while Petrobras anchors demand for premium integrated packages.
Supply Chain Analysis
Freight costs from European and Asian manufacturing hubs to Brazilian fabrication yards concentrate subsea Christmas tree and manifold procurement around Norwegian, Singaporean, and Korean supply bases. Raw material dependencies span specialized nickel alloys, thick-plate structural steel, and high-pressure control systems. Single-source vulnerability runs through concentrated high-pressure equipment fabrication. Distribution runs through coastal terminal networks connecting Santos basin production to Macaé logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's oil and gas market operates as a supply-constrained system where deepwater completion engineering bottlenecks prop pricing for integrated project delivery above unbundled alternatives.
For Market Incumbents: Deploy local content certification as a competitive moat by consolidating engineering contracts with domestic shipyards to secure ANP licensing round eligibility. Anchor position through captive supply of subsea boosting stations and electrified Christmas trees, countering margin erosion from steel input volatility and IBAMA approval delays. For New Entrants and Emerging Players: Mature field revitalization specialists targeting Potiguar and Recôncavo basin concessions face limited integrated competition from pre-salt focused majors. Capture share through enhanced recovery service contracts with state development agencies, leveraging lower capital intensity against billion-dollar offshore development cycles. For Investors and Strategic Acquirers: Re-rating potential sits with electrified subsea technology providers given Petrobras's infrastructure shift toward all-electric architectures at 2,500-meter depths. Monitor subsea equipment order backlog accumulation as inflection indicator for capacity-constrained supplier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Project Delivery Consolidation | Lump-sum turnkey contracts transfer cost overrun risk to service providers across Búzios and Mero field expansions. |
| Local Content Certification Investment | ANP-mandated domestic yard participation thresholds secure licensing round eligibility for pre-salt developments. |
| Electrified Subsea Infrastructure Deployment | All-electric Christmas trees eliminate hydraulic fluid leakage risks and enable real-time downhole monitoring. |
| Mature Field Enhanced Recovery Programs | Low-decline production profiles in Potiguar basin concessions attract specialized revitalization operators. |
| Carbon Capture Adjacency Development | Pre-salt CO2-rich gas streams create saline aquifer sequestration feasibility tied to production tax incentives. |
Methodological Framework
Independent corroboration across upstream project engineers, subsea equipment procurement leads, ANP regulatory specialists, and downstream refinery planners underwrites the qualitative findings. Primary fieldwork combined structured interviews with fabrication yard operations managers, integrated service provider contracts directors, and petrochemical feedstock buyers. Secondary validation drew from ANP production-sharing contract disclosures, IBAMA environmental licensing databases, Petrobras governance reform filings, and Brazilian customs hydrocarbon trade records. Bottom-up field development cost modeling triangulates against top-down sector revenue aggregates.
Comparable-period anchoring calibrated the projection horizon against historical pre-salt sanctioning velocity and local content compliance trajectories. The analytical framework segments by operational stage, technology tier, application end-use, and customer type across the modeling period. CAGRs derive from equipment order backlog trajectories, licensing round participation patterns, and refinery margin compression curves. Forecast inputs incorporate subsea electrification adoption rates and ANP procurement threshold evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IBAMA approval velocity, steel alloy cost trajectories, and deepwater engineering workforce expansion. Forecasts reflect documented assumptions around regulatory arbitration timelines and equipment supplier capacity constraints. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Wireline Services Market
Oil & Gas
Australia Oil and Gas Midstream Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Global Artificial Lift Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
Azerbaijan Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Frac Tree Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Injection Well Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Blockchain in Oil and Gas Market
Oil & Gas
Digital Twin in Oil and Gas Market