
 Oil and Gas Separator Market | 2026-2036
Oil and Gas Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Separator Market Analysis
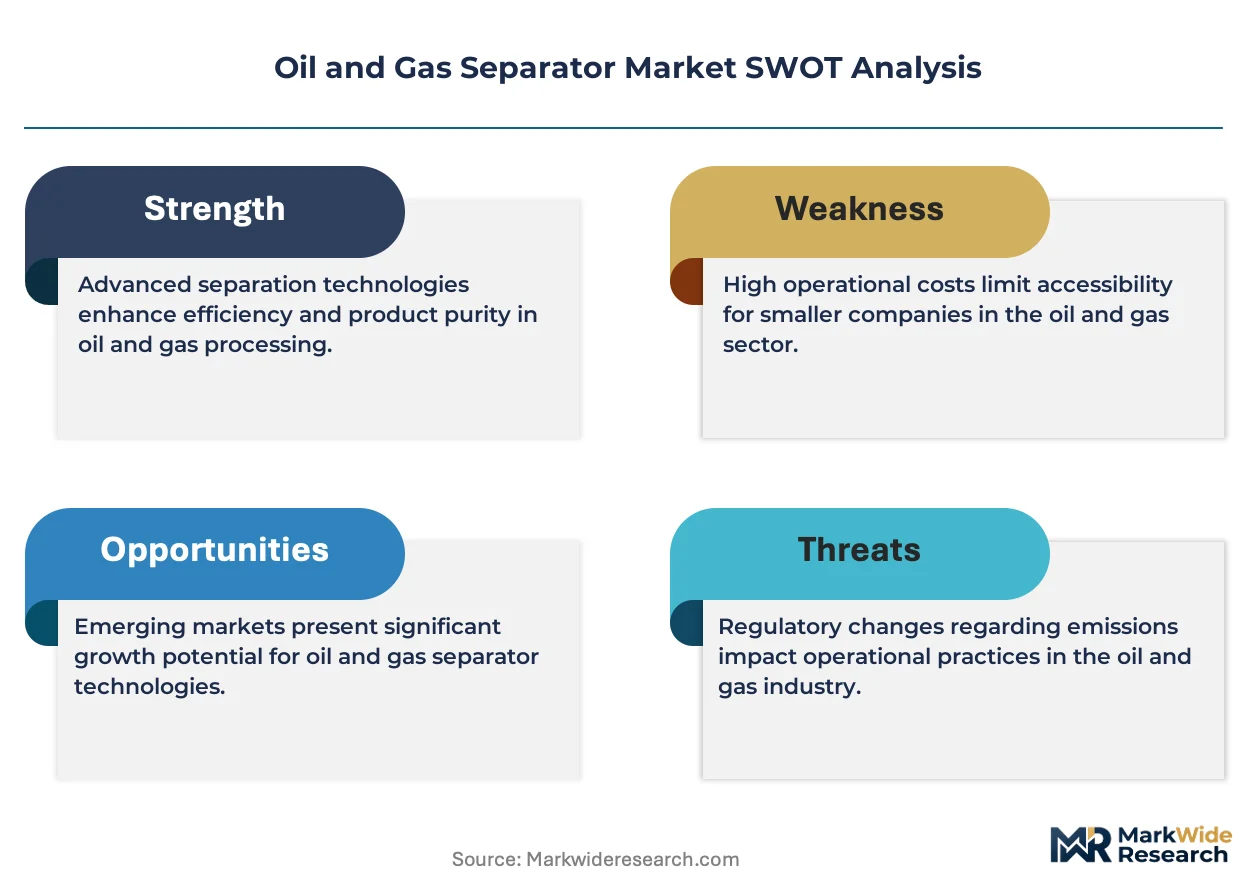
API 12J certification is reorganizing competitive access in the oil and gas separator space, raising engineering and testing barriers for new entrants. Schlumberger Limited leverages its integrated project delivery model to bundle separators with digital monitoring systems. National Oilwell Varco anchors its position through vertical control over pressure vessel fabrication and offshore platform integration. Alfa Laval AB specializes in compact cyclonic designs that reduce footprint on crowded North Sea installations.
An oil and gas separator is a pressure vessel engineered to partition hydrocarbon streams into constituent phases—typically oil, gas, and water—using gravity differentials, centrifugal force, or coalescing media, with operating pressures ranging from atmospheric to over 10,000 psi depending on field conditions. The device protects downstream processing equipment, ensures pipeline specification compliance, and enables produced water treatment prior to disposal or reinjection. Three-phase separators command the largest installed base in onshore conventional fields, while cyclonic technology captures the fastest expansion trajectory in deepwater contexts where space and weight constraints dominate. Gravity-based systems retain cost advantages in mature basins with predictable flow profiles, though margin pools are shifting toward mechanically-aided units that handle higher sand cuts and emulsion stability.
The EPA enforces effluent limitations on produced water discharge that directly shape separator specification and retrofit cycles across US onshore and offshore operations. API standards 12J and 12K govern separator design, fabrication, and performance testing, creating a compliance ladder that filters supplier participation in federal and state lease auctions. The EU F-Gas Regulation and REACH chemical restrictions are beginning to influence seal and coating material selections for European offshore deployments. Stakeholders must weigh capital intensity against regulatory durability when committing to next-generation separation architectures.
Market Dynamics
API 12J certification tightening is compressing supplier participation in North American upstream contracts, forcing engineering-heavy incumbents to absorb testing costs while marginal fabricators exit federal lease auctions entirely.
Growth Catalysts
- Subsea Tieback Expansion:Offshore operators in the Gulf of Mexico are multiplying procurement orders for high-pressure separation units as deepwater field development accelerates.
- EPA Effluent Mandates:Produced water discharge limitations are triggering retrofit cycles across US onshore basins, mandating three-phase separation upgrades.
- Permian Multi-Well Pads:Pad drilling density in West Texas is concentrating demand for higher-capacity three-phase separators that handle simultaneous flow from multiple lateral completions.
Market Restraints
- Alloy Cost Volatility:Duplex stainless steel price swings are squeezing pressure vessel margins and complicating long-dated project bids.
- Fabrication Concentration:Gulf Coast vessel shops control critical welding capacity, creating chokepoints during cyclical demand surges.
- Gravity Separator Limitations:Conventional designs face technical ceilings on sand cut tolerance and emulsion stability that mechanically-aided units now exceed.
Strategic Opportunities
- Brazil Pre-Salt Development:Santos Basin ultra-deepwater fields present untapped demand for compact cyclonic separation where platform weight constraints dominate.
- EU F-Gas Compliance:Seal and coating material restrictions are creating specification windows for European fabricators with REACH-certified supply chains.
- Digital Twin Convergence:Integration of separator hardware with real-time monitoring platforms is opening recurring revenue streams beyond equipment sales.
Industry Challenges
- API 12J Certification Timelines:Extended third-party validation cycles are delaying contract awards and stretching engineering resources.
- Weld Inspector Scarcity:Qualified ASME-certified inspectors are concentrated among retiring demographics, constraining fabrication throughput.
- Legacy Platform Integration:Brownfield installations require custom manifold adaptations that erode standardization economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Separator Market |
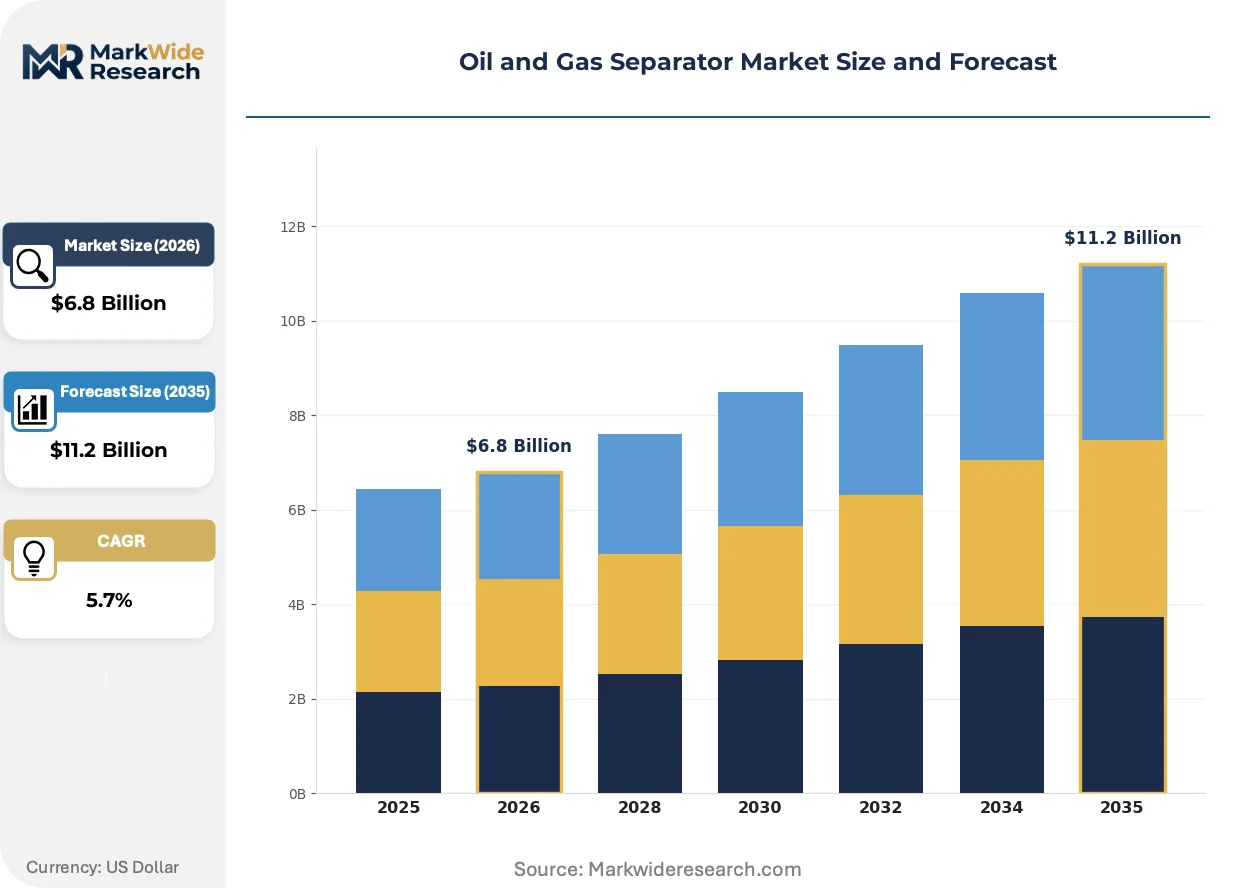
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Separator Type: Two-Phase, Three-Phase, Horizontal, Vertical Technology: Mechanically-Aided, Gravity-Based, Cyclonic, Magnetic End User: Upstream, Midstream, Downstream, Offshore Application: Oil Recovery, Gas Processing, Waste Treatment, Pipeline Transportation |
| Companies Covered | Honeywell International Inc., Exterran Corporation, Schlumberger Limited, National Oilwell Varco, Sulzer AG, TechnipFMC plc, Halliburton Company, GEA Group AG, Alfa Laval AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Separator Market Emerging Trajectories
Cyclonic separation architecture is compressing equipment footprints while digital instrumentation layers are redefining service relationships between OEMs and field operators.
Cyclonic separator technology uses centrifugal force rather than gravity settling to partition hydrocarbon phases, achieving separation efficiency in vessels one-third the size of conventional horizontal units. North Sea platform operators are adopting these designs aggressively as deck space premiums escalate. The technology is miniaturizing separation infrastructure to the point where subsea processing modules now become technically viable.
REACH chemical restrictions and the EU F-Gas Regulation are mandating fluorocarbon-free seal materials and low-VOC coating systems for North Sea deployments. Fabricators serving European offshore markets are reformulating material specifications and resubmitting type approvals. Cyclonic units with polymer-lined internals face the steepest compliance recertification burdens.
Operator procurement departments are unbundling aftermarket service contracts from initial equipment purchases, forcing separator OEMs to compete on lifecycle monitoring value rather than capital cost alone. Integrated project delivery models are fragmenting into componentized sourcing. This pattern is most visible in the Permian Basin, where independent producers prioritize unit swap speed over vendor loyalty.
Oil and Gas Separator Market Segmentation
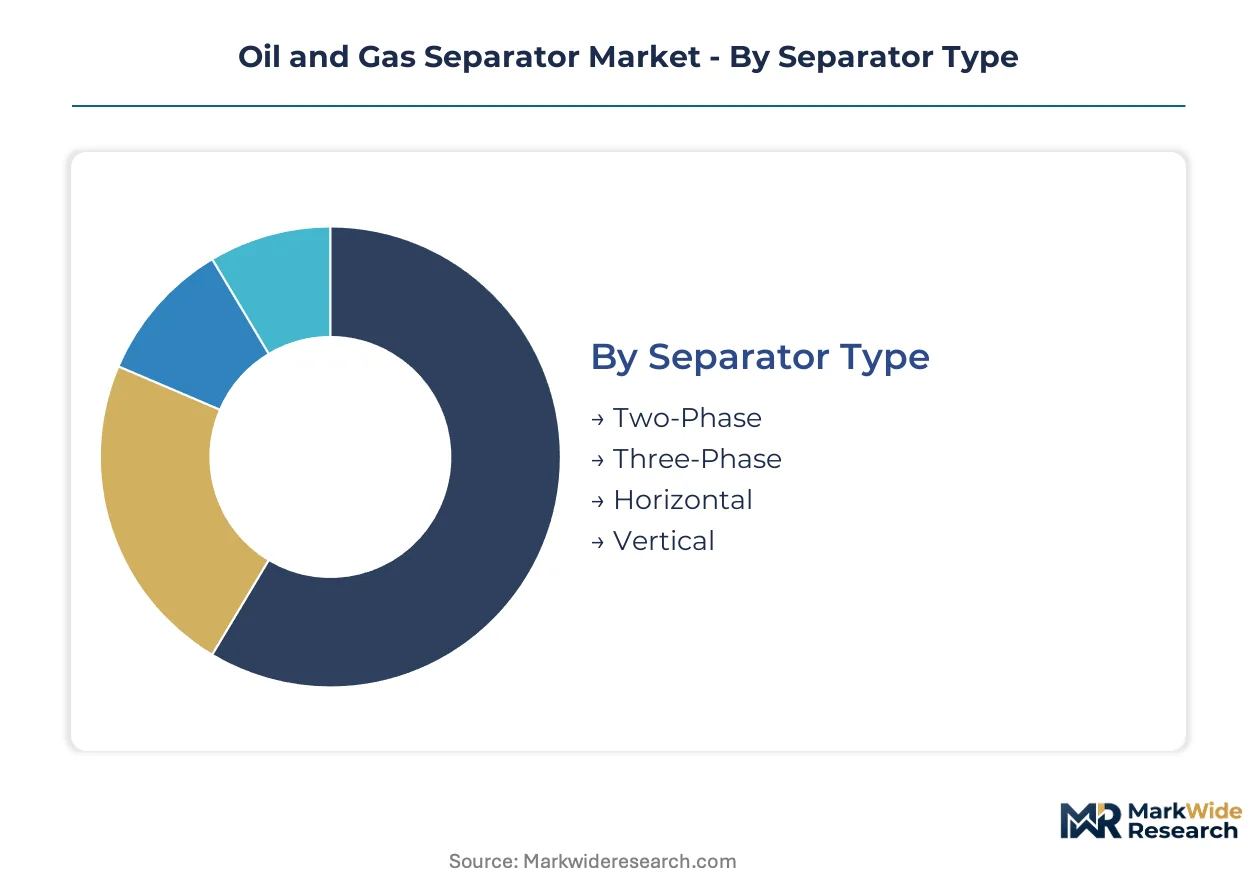
Separator procurement patterns diverge sharply across upstream, midstream, and offshore contexts, with each end-use imposing distinct pressure ratings, footprint constraints, and certification requirements. Understanding these segment boundaries clarifies why technology suppliers pursue radically different engineering strategies for Permian multi-well pads versus North Sea platform retrofits.
Separator Type:
Domestic fabrication concentrates on horizontal and vertical gravity units for US onshore basins, while export demand pulls specialized three-phase systems toward Middle Eastern and Brazilian ultra-deepwater developments.
- Three-Phase:These vessels partition oil, gas, and produced water through sequential gravity settling zones with weir controls and mist extractors. Demand clusters in the Permian Basin, where multi-well pad density requires single units handling simultaneous flow from six to twelve lateral completions without slugging instability.
- Two-Phase:Simpler oil-gas or gas-liquid separation dominates gas processing facilities and early production facilities where water cuts remain minimal. Operators in the Marcellus Shale favor these units for dry gas streams, accepting reduced complexity against faster deployment timelines.
- Horizontal:Extended residence time and large interface areas suit heavy crude applications in California's Kern County and Canada's oil sands, where emulsion stability demands prolonged settling.
- Vertical:Compact footprint and superior gas handling capacity position these units for offshore platform retrofits in the Gulf of Mexico, where deck load limits and crane capacity constrain replacement options.
Three-phase units command the established base. The steepest expansion runs through vertical separators as brownfield offshore upgrades accelerate.
Technology:
Cost tiers separate mature gravity systems from premium mechanically-aided and cyclonic architectures, with margin pools shifting toward technologies that tolerate higher sand cuts and tighter emulsions.
- Cyclonic:Centrifugal force achieves phase separation in vessels one-third the size of conventional designs, using tangential inlets and vortex finders to generate high-G separation zones. North Sea operators facing deck space premiums at BP's Clair Ridge and Equinor's Johan Sverdrup platforms are standardizing on these units despite 40-60% capital cost premiums.
- Mechanically-Aided:Internals such as plate coalescers, electrostatic grids, and flotation cells accelerate separation kinetics beyond gravity limits. The technology is displacing conventional units in Permian high-sand environments where erosion rates and emulsion stability exceed passive design thresholds.
- Gravity-Based:Passive settling remains the cost baseline for mature conventional fields with predictable flow profiles and moderate water cuts, though qualification to API 12J is narrowing the supplier base.
- Magnetic:Rare-earth magnetic grids target paraffin and asphaltene precipitation in waxy crude applications, with pilot deployments concentrated in Alaska's North Slope and West Siberian fields.
Gravity-based systems retain volume leadership. Mechanically-aided designs are gaining share fastest as unconventional reservoir characteristics spread globally.
End User:
Customer type determines procurement sophistication, with integrated majors demanding lifecycle service bundles while independents prioritize unit swap speed and capital efficiency.
- Upstream:Wellhead separation, early production facilities, and central processing platforms constitute the largest equipment volume, with specification intensity varying from basic lease automatic custody transfer units to subsea processing modules.
- Offshore:Platform weight constraints, space premiums, and regulatory complexity drive specification toward compact, high-pressure designs with integrated safety systems and remote monitoring capabilities.
- Midstream:Gathering system slug catchers, compressor station suction scrubbers, and fractionation train inlet separators require robust designs handling multiphase flow transients and variable composition streams.
- Downstream:Refinery applications including crude unit desalters, delayed coker blowdown drums, and FCC main fractionator overhead recovery represent specialized, low-volume demand with exacting metallurgy requirements.
Upstream absorbs the dominant equipment flow. Offshore procurement is climbing the fastest as deepwater tieback economics improve.
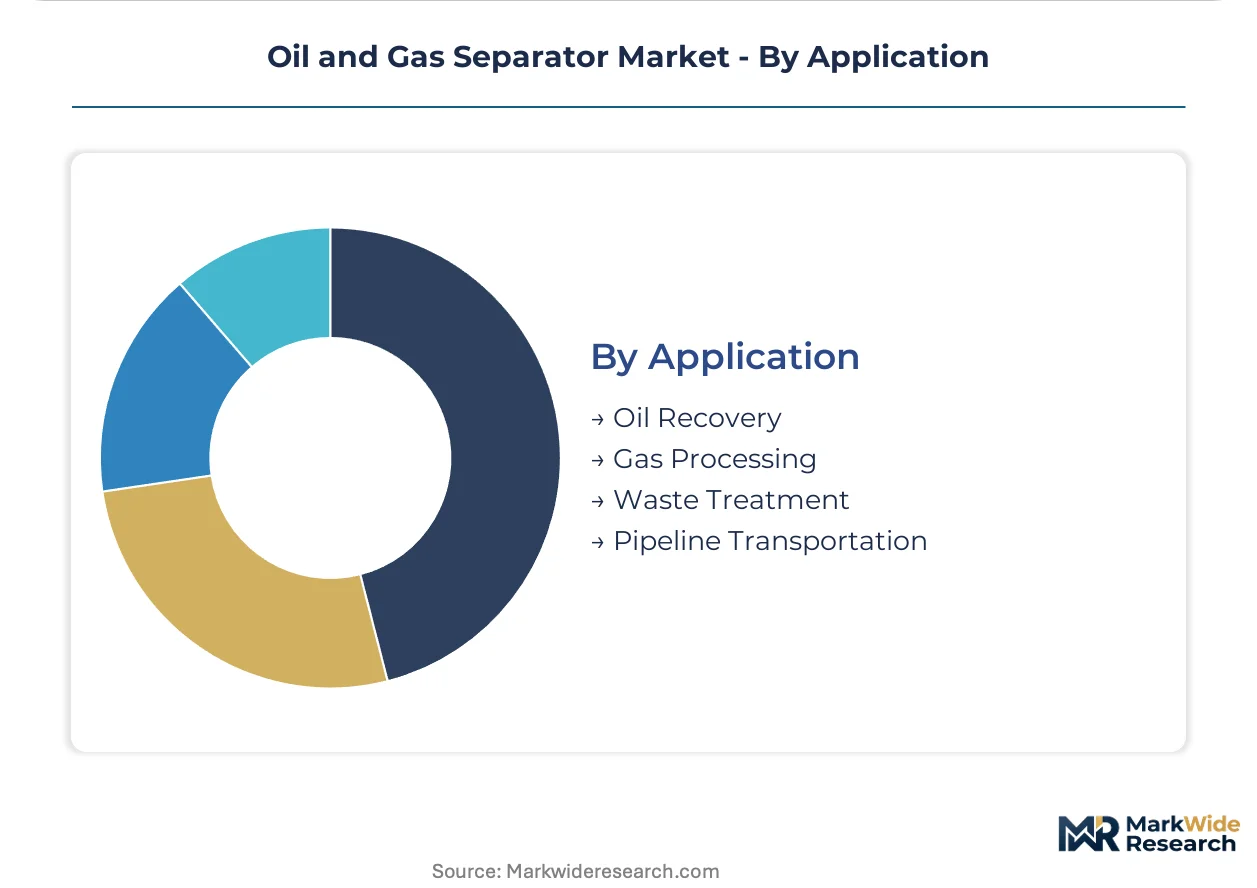
Application:
Maturity gradients separate established oil recovery applications from emerging waste treatment specifications shaped by tightening discharge regulations.
- Oil Recovery:Primary, secondary, and tertiary recovery operations require separation at wellhead, central facility, and enhanced oil injection points, with specification intensity rising for chemical flood applications handling polymer-thickened fluids.
- Gas Processing:Inlet reception, dehydration, and liquids recovery units demand precise dewpoint control and hydrate inhibition, particularly for rich gas streams from the Appalachian Basin and associated gas from Permian oil wells.
- Pipeline Transportation:Custody transfer metering and compressor protection scrubbers prioritize measurement accuracy and reliability over separation efficiency, with tariff specifications driving standardization.
- Waste Treatment:Produced water polishing, solids dewatering, and slop oil recovery are gaining specification weight as EPA effluent limits and state-level discharge prohibitions multiply retrofit obligations across US onshore operations.
Oil recovery anchors the installed base. Waste treatment is expanding most quickly as regulatory compliance cycles compress replacement intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal lease auctions and subsea tieback economics are concentrating separator procurement in the United States, Brazil, Norway, China, and Saudi Arabia. Each jurisdiction imposes distinct certification and environmental compliance frameworks that shape supplier qualification and technology selection.
United States
EPA effluent limitations on produced water discharge are mandating three-phase separator retrofits across the Permian Basin and Gulf of Mexico. API 12J certification tightening is compressing the supplier base for federal lease contracts. Houston-Galveston fabrication clusters are absorbing surge demand from offshore platform upgrades and multi-well pad developments in West Texas.
Brazil
Santos Basin pre-salt ultra-deepwater fields are generating procurement for compact cyclonic separation units where platform weight constraints dominate. ANVISA and environmental licensing requirements are extending equipment qualification timelines for foreign fabricators. Rio de Janeiro's naval and offshore engineering cluster is localizing pressure vessel production to meet local content mandates.
Norway
North Sea platform brownfield upgrades are accelerating vertical separator replacements as deck space premiums escalate. EU F-Gas Regulation and REACH chemical restrictions are mandating fluorocarbon-free seal materials and coating system reforms. Stavanger and Bergen engineering centers are standardizing cyclonic designs at Equinor's Johan Sverdrup and BP's Clair Ridge installations.
China
State-backed offshore development in the Bohai and South China Sea is driving demand for high-pressure separation infrastructure. MIIT equipment certification and GB standards are filtering import participation in national oil company tenders. Tianjin and Qingdao fabrication yards are expanding welding capacity for domestic three-phase separator production.
Saudi Arabia
Aramco's Marjan and Zuluf field expansions are specifying large-capacity separation trains for associated gas processing. Saudi Standards, Metrology and Quality Organization (SASO) technical regulations are harmonizing with API specifications for pressure equipment. Eastern Province industrial cities are concentrating vessel fabrication to support offshore and onshore megaproject execution.
Oil and Gas Separator Market Vendor Landscape
Player mix skews toward integrated energy service conglomerates with captive fabrication networks, mid-cap pressure vessel specialists, and European compact technology licensors. Market structure consolidates around engineering-heavy incumbents capable of absorbing API 12J certification costs, while marginal fabricators exit federal lease auctions. Three strategic archetypes dominate: full-service project integrators bundling hardware with digital monitoring, standalone vessel fabricators competing on delivery speed, and technology licensors monetizing cyclonic separation patents. Competitive moves center on backward integration into alloy supply chains and geographic expansion into Brazilian and Middle Eastern offshore markets.
Within the integrated service tier, Schlumberger Limited and Halliburton Company exemplify project delivery models that combine separator hardware with real-time monitoring platforms. National Oilwell Varco anchors the fabrication-centric segment through captive pressure vessel production and offshore platform integration capabilities. Alfa Laval AB occupies the compact technology licensing position, representing European specialization in cyclonic designs that reduce footprint on space-constrained installations. These three archetypes capture distinct margin pools across onshore conventional, offshore brownfield, and deepwater greenfield contexts.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Exterran Corporation |
| Schlumberger Limited |
| National Oilwell Varco |
| Sulzer AG |
| TechnipFMC plc |
| Halliburton Company |
| GEA Group AG |
| Alfa Laval AB |
| Others |
Supply Flow & Price Mechanics
API 12J certification gates both supplier qualification and price differentiation simultaneously, compressing the vendor base for federal lease contracts while allowing engineering-heavy incumbents to command premiums for validated designs. Duplex stainless steel indexation in cost-plus contracts ties vessel pricing to London Metal Exchange volatility, exposing fabricators to margin compression when alloy markets spike.
Pricing Analysis
Cost-plus contracts with London Metal Exchange duplex stainless steel indexation dominate long-dated project bids, transmitting raw material volatility directly to operator procurement budgets. Price differentiation rests on API 12J certification tier and after-sales service bundling, with validated fabricators capturing premiums over uncertified competitors. Pricing pressure stems from Permian Basin operator consolidation, where pad drilling specialists negotiate volume discounts for multi-unit orders. Independent producers exhibit highest price sensitivity, prioritizing unit swap speed over lifecycle service, while integrated majors accept capital premiums for integrated monitoring platforms.
Supply Chain Analysis
Inbound logistics costs through Houston-Galveston port congestion and Gulf Coast container availability constrain just-in-time delivery for brownfield platform retrofits. Fabrication capacity concentrates in the United States, China, and Brazil, with domestic shops controlling critical ASME-certified welding labor. The supply chain draws from duplex stainless steel mills, rare-earth magnetic grid suppliers, and polymer seal compounders. Single-source vulnerability in qualified weld inspector pools creates chokepoints during cyclical demand surges. Distribution runs through OEM direct sales for integrated project bundles and specialized distributors for standard vessel replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Permian Basin multi-well pad operators as pad drilling consolidation concentrates procurement volume among fewer independent producers. This fragmentation among buyers forces vendors to compete on unit swap speed rather than vendor loyalty.
For Market Incumbents: Compound API 12J certification investments into recurring digital service revenue, bundling separator hardware with real-time monitoring platforms to lock out standalone fabricators. Absorb extended third-party validation timelines by pre-qualifying designs across multiple federal lease auction cycles. Defend against cyclonic technology licensors by deepening backward integration into alloy supply chains and captive pressure vessel production. For New Entrants and Emerging Players: Lead with compact cyclonic designs targeting Brazil Santos Basin pre-salt platforms where weight constraints and ANVISA local content mandates disadvantage incumbent fabricators. Target European offshore brownfield upgrades where EU F-Gas Regulation and REACH compliance windows favor REACH-certified supply chain specialists. Pursue technology licensing arrangements with Rio de Janeiro engineering clusters to bypass fabrication capacity constraints. For Investors and Strategic Acquirers: API 12J certification tightening reshapes the acquisition landscape toward engineering-heavy incumbents with validated testing infrastructure and captive fabrication networks. Long-term viability favors asset-light technology licensors with cyclonic patent portfolios over capital-intensive vessel shops exposed to alloy price volatility. Monitor EPA effluent mandate enforcement intensity as the inflection signal for retrofit cycle timing and three-phase separator replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| API 12J Certification Pre-Qualification | Accelerates federal lease auction participation while locking out marginal fabricators from operator procurement shortlists. |
| Backward Integration into Alloy Supply | Hedges duplex stainless steel price volatility through captive mill relationships or long-dated offtake agreements. |
| Digital Twin Platform Integration | Transforms equipment sales into recurring monitoring revenue at Schlumberger and Halliburton integrated project models. |
| Cyclonic Technology Licensing | Captures North Sea and Brazil pre-salt premiums where platform weight constraints favor compact separation architectures. |
| REACH-Certified Supply Chain Localization | Unlocks European offshore procurement windows as EU F-Gas Regulation mandates fluorocarbon-free seal material reforms. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of API certification databases, EPA enforcement records, and federal lease auction awards. Primary interviews engaged separator OEM product managers, Permian Basin operator procurement directors, Gulf Coast fabrication shop engineers, and North Sea platform maintenance superintendents. Secondary sources included ASME boiler and pressure vessel code updates, London Metal Exchange stainless steel pricing data, and ANVISA medical-equipment crossover regulatory filings. Bottom-up unit demand modeling triangulated against top-down capex flow analysis across upstream, midstream, and offshore end-use segments.
Segmentation dimensions modeled span separator type, technology architecture, end-user category, and application context across the projection horizon. The analytical framework disaggregated three-phase, two-phase, horizontal, and vertical vessel configurations; gravity-based, mechanically-aided, cyclonic, and magnetic separation technologies; upstream, offshore, midstream, and downstream end-users; and oil recovery, gas processing, pipeline transportation, and waste treatment applications. CAGRs derived from historical replacement cycle analysis, regulatory compliance deadline clustering, and subsea tieback project pipeline assessment. Forecast inputs incorporated EPA effluent mandate retrofit obligation schedules and Brazil pre-salt field development timelines.
Underlying assumptions cover stable API 12J certification timeline durations, continued duplex stainless steel price volatility, and sustained Permian Basin pad drilling density expansion, with deviation risk concentrated in weld inspector labor availability and offshore platform brownfield upgrade sanctioning delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Tight Gas Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Africa Oil and Gas Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Kuwait Oilfield Services Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Logistics Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
Coiled Tubing System Market
Oil & Gas
Proppant Market