
 Water-Based Zinc-Ion Battery Market | 2026-2036
Water-Based Zinc-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Based Zinc-Ion Battery Market Insights
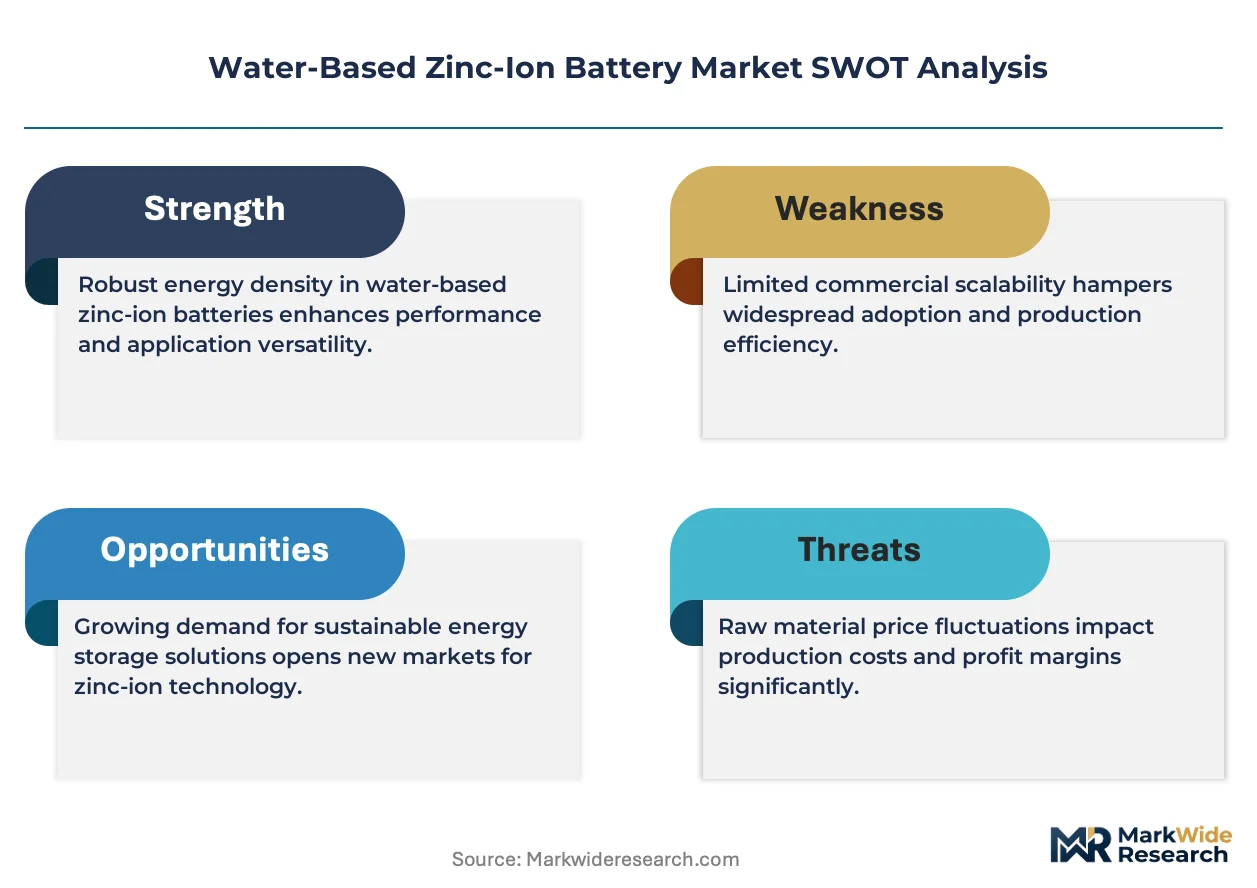
High-cycle-life configurations are reorganizing competitive dynamics in aqueous battery chemistry. Eos Energy Storage sustains manufacturing scale for grid-scale deployments through its Pennsylvania operations. Shenzhen Cubic dominates cylindrical format production for industrial backup applications. Enerpoly differentiates through proprietary cathode formulations targeting European renewable developers.
Water-based zinc-ion batteries employ mildly acidic or neutral aqueous electrolytes, typically zinc sulfate or zinc trifluoromethanesulfonate, paired with intercalation cathodes such as vanadium oxide or manganese dioxide to achieve 5000+ cycles at ambient temperature. Their primary purpose is stationary energy storage where thermal runaway risks and lithium raw material volatility disqualify conventional lithium-ion systems. Prismatic formats occupy the dominant share in grid-tied installations due to superior volumetric stacking efficiency, while stackable architectures represent the fastest-growing category as modular microgrid deployments multiply. Among end users, renewable energy operators command the most concentrated margin pool given long-duration discharge requirements and procurement scale.
China's MIIT enforces GB/T 36276 testing protocols for electrochemical storage safety, while the EU Green Deal and F-Gas Regulation indirectly steer investment toward water-based chemistries by penalizing fluorinated electrolyte alternatives. The US EPA and OSHA jointly govern workplace exposure limits for zinc processing facilities, shaping domestic manufacturing location decisions. Stakeholders must monitor cathode material supply agreements and electrolyte additive patent filings as the primary determinants of cost parity against lithium iron phosphate systems.
Market Dynamics
China's MIIT battery safety directives and updated GB standards are compressing certification timelines, forcing manufacturers to accelerate aqueous chemistry validation while lithium supply constraints persist.
Growth Catalysts
- MIIT Safety Directives:China's GB/T 36276 testing protocols mandate electrochemical storage safety standards that favor water-based systems over thermal-runaway-prone alternatives, accelerating domestic procurement.
- Vanadium Oxide Cathodes:Intercalation cathode chemistry breakthroughs enable 5000+ cycle life at ambient temperature, unlocking utility-scale renewable integration contracts.
- Germany:The EU F-Gas Regulation penalizes fluorinated electrolyte alternatives, redirecting European renewable developer capital toward aqueous zinc-ion storage.
Market Restraints
- Manganese Dioxide Supply Concentration:Cathode material sourcing depends on concentrated manganese processing capacity in southern Africa and China, creating input cost volatility.
- Energy Density Gap:Aqueous zinc-ion systems deliver lower volumetric energy density than lithium iron phosphate, limiting applications in space-constrained installations.
- US EPA Zinc Processing Limits:Workplace exposure regulations for zinc sulfate and trifluoromethanesulfonate handling restrict domestic manufacturing site selection.
Strategic Opportunities
- Modular Microgrid Deployments:Stackable battery architectures represent the fastest-growing format category as distributed renewable projects multiply across Texas and California.
- Industrial Backup Applications:Cylindrical format production for manufacturing facility uninterruptible power supplies remains underpenetrated outside China.
- Long-Duration Storage Mandates:FERC Order 2222 implementation creates procurement pathways for 4-8 hour discharge systems in US wholesale electricity markets.
Industry Challenges
- Electrolyte Additive Patent Thickets:Proprietary formulations for zinc dendrite suppression face complex licensing landscapes that delay product commercialization.
- GB/T 36276 Certification Timeline:Extended validation cycles for grid-tied electrochemical storage compress margin realization windows for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Based Zinc-Ion Battery Market |
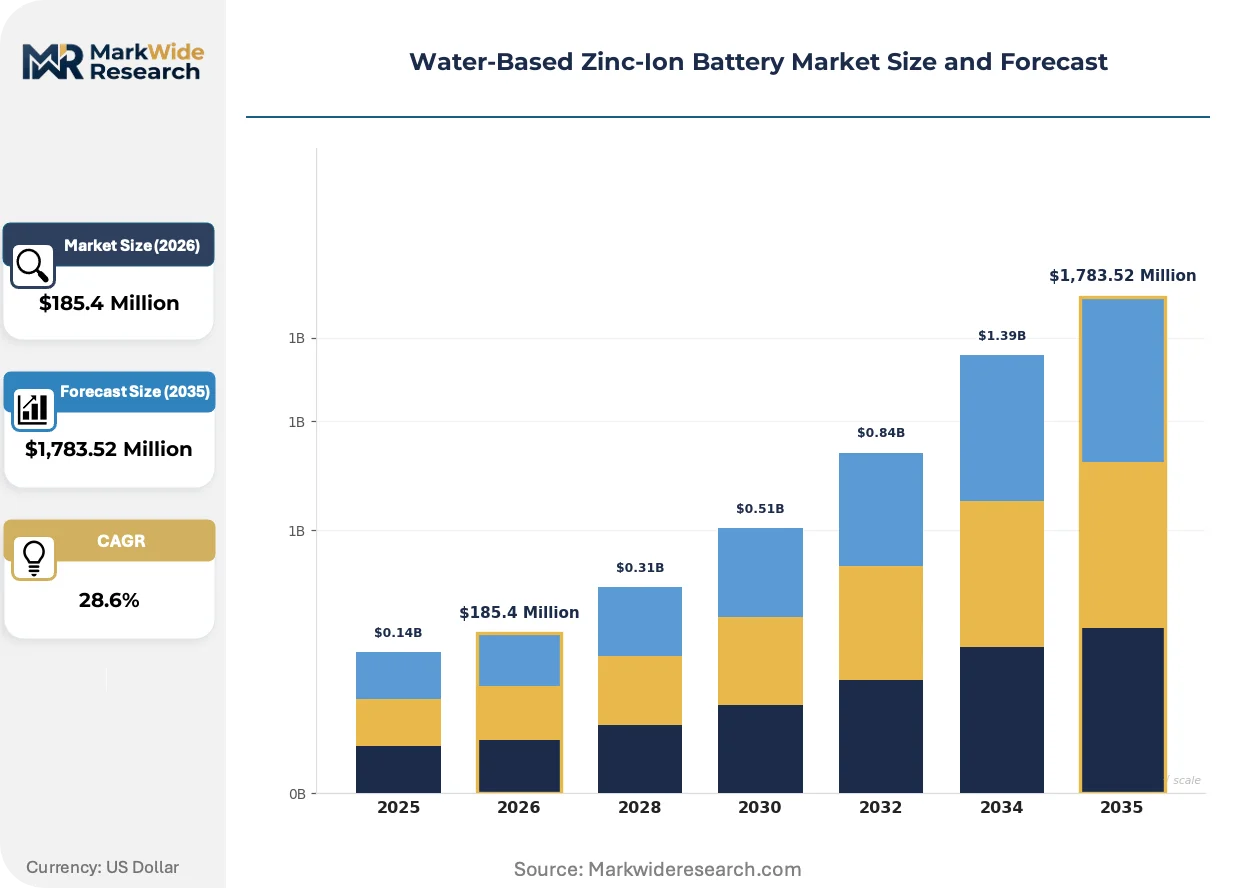
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $1,783.52 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Coin Cell, Stackable End User: Consumer Electronics, Automotive, Industrial, Renewable Energy Technology: Electrolyte System, Separator Type, Anode Material, Cathode Material Application: Energy Storage, Electric Vehicles, Portable Devices, Grid Stabilization |
| Companies Covered | Salient Energy, Eos Energy Storage, Shenzhen Cubic, Golden Feather, Ruihaipo (Qingdao) Energy, Jingyan New Energy, Ande Guangdian, ZnR Batteries, Enerpoly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Based Zinc-Ion Battery Market Trends and Innovations
Electrolyte formulation advances and cathode material engineering are redefining performance benchmarks for aqueous energy storage, while procurement patterns shift toward vertically integrated renewable developers.
Prismatic cell formats are displacing cylindrical architectures in utility-scale installations due to superior volumetric stacking efficiency and reduced thermal management overhead. Grid-scale operators in China and Germany now specify prismatic configurations for 100MWh-plus projects. This format transition is displacing incumbent cylindrical suppliers from the largest procurement contracts.
The EU F-Gas Regulation and associated delegated acts are systematically penalizing fluorinated electrolyte chemistries across stationary storage applications. European renewable developers face compliance cost premiums that redirect capital toward water-based alternatives. German and Dutch utility procurement specifications now explicitly exclude fluorinated systems from tender eligibility.
Renewable energy operators are consolidating procurement decisions under vertically integrated development arms, bypassing traditional battery system integrators. Long-duration discharge requirements and procurement scale favor direct manufacturer relationships over distributor channels. This concentration is most visible in China, where state-owned renewable developers negotiate cathode supply agreements directly with electrolyte additive patent holders.
Water-Based Zinc-Ion Battery Market Segmentation
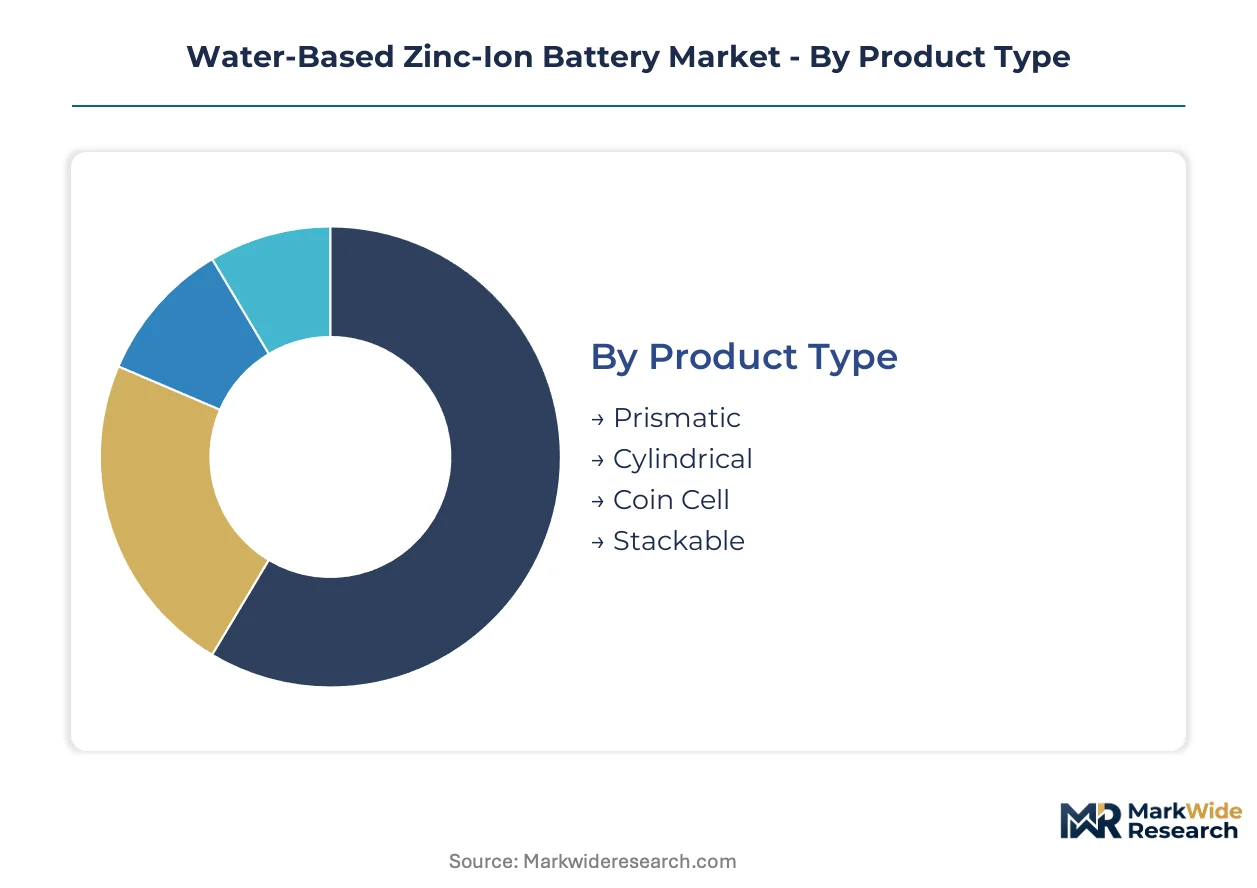
Water-based zinc-ion battery segmentation reveals divergent supply chain configurations across formats and end uses. Prismatic and stackable architectures concentrate manufacturing in China and Germany, while cylindrical production serves export markets from Pennsylvania and Shenzhen.
Product Type:
Prismatic formats dominate domestic procurement in China and Germany, whereas cylindrical and coin cell variants flow through export channels to North American industrial buyers.
- Prismatic:Rectangular cells with layered electrode stacking optimize volumetric density for utility-scale installations. Grid operators in China and Germany specify prismatic configurations for 100MWh-plus renewable integration projects where space efficiency governs total cost of ownership.
- Stackable:Modular architectures enable incremental capacity expansion for distributed microgrids. Developers across Texas and California deploy stackable systems for commercial solar-plus-storage projects requiring flexible scaling without full system replacement.
- Cylindrical:Rolled electrode designs suit high-volume manufacturing for industrial backup power.
- Coin Cell:Compact form factors address limited portable electronics and sensor applications.
Prismatic holds the largest share; momentum sits with stackable architectures.
End User:
Renewable energy operators command premium pricing through direct manufacturer relationships, while consumer electronics procurement runs through distributor channels with compressed margins.
- Renewable Energy:Utility-scale solar and wind developers require 4-8 hour discharge duration for grid-firming services. Long-duration mandates from FERC Order 2222 and EU Green Deal targets concentrate procurement volume with aqueous chemistry specialists.
- Industrial:Manufacturing facilities deploy uninterruptible power supplies for production line protection. Cylindrical format demand from Pennsylvania and Ohio automotive suppliers drives regional manufacturing investment.
- Consumer Electronics:Low-power devices represent limited addressable market due to energy density constraints.
- Automotive:Passenger vehicle applications remain underdeveloped given volumetric packaging limitations versus lithium-ion.
Renewable energy captures the dominant revenue pool; industrial applications are expanding most quickly.
Technology:
Electrolyte and cathode material choices determine manufacturing location decisions under divergent regulatory regimes for chemical handling.
- Cathode Material:Vanadium oxide and manganese dioxide formulations unlock 5000-plus cycle life. Patent licensing complexity for intercalation chemistries concentrates production with holders of additive intellectual property in China.
- Electrolyte System:Zinc sulfate and zinc trifluoromethanesulfonate solutions require mildly acidic or neutral aqueous conditions. US EPA and OSHA workplace exposure limits restrict domestic processing site selection to rural industrial zones.
- Anode Material:Zinc metal foil and composite architectures face dendrite suppression challenges.
- Separator Type:Glass fiber and polymer membrane selection influences ion transport efficiency.
Cathode material commands the steepest expansion trajectory; electrolyte systems face regulatory-driven geographic concentration.
Application:
Energy storage and grid stabilization applications concentrate procurement in China, Germany, and the United States, while portable devices remain marginal due to density limitations.
- Energy Storage:Stationary systems for renewable integration and peak shaving dominate aqueous zinc-ion deployment. China's state-owned developers negotiate cathode supply agreements directly with additive patent holders, bypassing traditional integrators.
- Grid Stabilization:Frequency regulation and voltage support services favor rapid response characteristics. German utility procurement specifications under EU F-Gas Regulation now explicitly exclude fluorinated alternatives, redirecting tenders toward water-based systems.
- Electric Vehicles:Passenger and commercial vehicle traction applications remain constrained by packaging volume requirements.
- Portable Devices:Limited penetration in consumer electronics due to inferior energy density versus lithium-ion.
Energy storage holds the largest share; grid stabilization is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cathode material processing clusters in southern Africa and manganese refining corridors in China concentrate upstream supply, while electrolyte formulation and cell assembly gravitate toward jurisdictions with favorable chemical handling regulations.
China
State-owned renewable developers in Jiangsu and Zhejiang provinces negotiate direct cathode supply agreements with additive patent holders. MIIT's GB/T 36276 testing protocols compress certification timelines for grid-tied electrochemical storage. Shenzhen and Dongguan manufacturing corridors dominate prismatic and stackable format production for domestic utility-scale deployments.
United States
Texas and California developers deploy modular microgrid systems for commercial solar-plus-storage projects requiring 4-8 hour discharge duration. FERC Order 2222 implementation creates procurement pathways for long-duration systems in wholesale electricity markets. Pennsylvania hosts grid-scale manufacturing operations serving Northeast and Midwest utility procurement.
Germany
Utility procurement specifications under EU F-Gas Regulation explicitly exclude fluorinated electrolyte alternatives from tender eligibility. North Rhine-Westphalia and Bavaria anchor renewable developer capital reallocation toward aqueous chemistry systems. German grid operators specify prismatic configurations for 100MWh-plus renewable integration projects.
Australia
Queensland and New South Wales mining operations drive industrial backup power demand for remote site electrification. The country's national energy regulator advances safety standards favoring non-flammable electrochemical storage for isolated grid applications. Perth-based engineering firms integrate stackable architectures into off-grid renewable microgrids for resource extraction camps.
Water-Based Zinc-Ion Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Incumbent cylindrical specialists from industrial battery backgrounds compete against emerging prismatic-scale players with cathode chemistry IP. The market consolidates around three strategic archetypes: vertically integrated material-chemistry firms, pure-play aqueous cell manufacturers, and renewable developer captive suppliers. Dominant competitive moves include backward integration into cathode material supply and strategic patent licensing for dendrite suppression electrolyte additives.
Among North American pure-play specialists, Salient Energy and Eos Energy Storage occupy positions within the grid-scale deployment archetype. Chinese manufacturing-scale players include Shenzhen Cubic and Ruihaipo (Qingdao) Energy, representing the cylindrical format and industrial backup specialization vectors respectively. European chemistry-focused entrants such as Enerpoly exemplify the cathode formulation differentiation archetype targeting renewable developer direct procurement relationships.
| Leading Market Players |
|---|
| Salient Energy |
| Eos Energy Storage |
| Shenzhen Cubic |
| Golden Feather |
| Ruihaipo (Qingdao) Energy |
| Jingyan New Energy |
| Ande Guangdian |
| ZnR Batteries |
| Enerpoly |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Chinese state-owned renewable developers and cathode additive patent holders lock in both vanadium oxide supply access and multi-year price visibility, compressing margin volatility for certified suppliers while locking out spot-market buyers from utility-scale procurement tiers.
Pricing Analysis
MIIT's GB/T 36276 certification mandates dictate the pricing tier structure across the aqueous battery sector, separating UL-verified prismatic configurations for 100MWh-plus grid projects from uncertified cylindrical formats serving industrial backup. Premium-mid-economy pricing differentiation rests on cathode material grade and electrolyte additive licensing status, with dendrite suppression IP commanding substantial markups. Cost compression in standard-tier cylindrical cells is intensifying because manganese dioxide supply concentration in southern Africa feeds input volatility. Renewable energy operators exhibit lowest price sensitivity given long-duration discharge mandates and direct manufacturer relationships, while industrial buyers in Pennsylvania and Ohio automotive corridors negotiate hardest on per-kWh contract terms.
Supply Chain Analysis
Manganese processing corridors in southern Africa and China's Guizhou province anchor cathode material feedstock, creating single-source vulnerability for vanadium oxide and manganese dioxide intercalation chemistries. Raw material dependencies draw from zinc sulfate refining, glass fiber separator production, and zinc metal foil rolling. Tariff exposure on Chinese electrolyte additive imports into the US and EU is reshaping domestic formulation investments. Distribution runs through direct manufacturer relationships with state-owned renewable developers, bypassing traditional battery system integrators and compressing distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based zinc-ion chemistry faces substitution defense against lithium iron phosphate cost curves and solid-state battery timelines, requiring incumbents to accelerate certification advantages before lithium supply constraints ease.
For Market Incumbents: Consolidate cathode material supply agreements with southern African manganese processors and Guizhou vanadium refiners to secure input cost predictability against spot-market volatility. Deepen backward integration into proprietary dendrite suppression electrolyte additive production to defend margin position from licensing fee erosion. Lock in GB/T 36276 and UL certification advantages before FERC Order 2222 procurement windows mature, as uncertified competitors face compressed timeline entry. For New Entrants and Emerging Players: Differentiate on stackable modular architectures for Texas and California commercial solar-plus-storage microgrids, where flexible scaling requirements and 4-8 hour discharge mandates favor incremental capacity expansion over prismatic bulk deployment. Target cylindrical format production for Pennsylvania and Ohio automotive supplier industrial backup contracts, a segment underpenetrated outside Shenzhen manufacturing corridors. Pursue direct EPC contractor partnerships rather than distributor channel buildout to bypass incumbent integrator relationships. For Investors and Strategic Acquirers: Cathode chemistry IP holders with additive patent portfolios and direct renewable developer relationships represent the highest-conviction acquisition archetype, capturing margin concentration from vertically integrated procurement shifts. Long-term viability hinges on cost parity achievement against lithium iron phosphate across the next technology cycle, with electrolyte formulation breakthroughs as the critical swing factor. Monitor FERC Order 2222 implementation velocity and EU F-Gas Regulation enforcement stringency as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Backward Integration | Upstream control over manganese dioxide and vanadium oxide refining reduces input cost volatility from southern African supply concentration. |
| GB/T 36276 Certification Acceleration | MIIT safety protocol validation unlocks Chinese state-owned renewable developer procurement and compresses competitor entry timelines. |
| Electrolyte Additive Patent Licensing | Dendrite suppression IP monetization captures recurring revenue from manufacturers lacking in-house formulation capabilities. |
| Stackable Architecture Capacity Buildout | Modular microgrid format expansion addresses Texas and California distributed solar-plus-storage demand with flexible scaling economics. |
| Direct Developer Relationship Cultivation | Bypassing traditional system integrators aligns with renewable operator vertical integration trends and secures long-term offtake visibility. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators, and refined through secondary validation against EIA storage deployment data, IEA stationary battery reports, FERC Order 2222 implementation filings, and Chinese MIIT GB standard documentation. Bottom-up capacity buildout estimates from individual manufacturing facilities were triangulated with top-down renewable integration mandate targets across the analysis window.
Variance decomposition across product format, end-use application, cathode material chemistry, and regional regulatory framework shaped the analytical architecture. Modeled outputs reflect segment-level CAGRs derived from capacity expansion announcements, certification timeline trajectories, and procurement contract visibility. Electrolyte additive patent filing velocity and cathode supply agreement disclosure patterns served as industry-specific forecast calibration inputs.
The analysis sits within stated boundaries; outcomes outside sustained lithium supply constraints, MIIT certification timeline compression, and EU F-Gas Regulation enforcement would require recalibration. Forecasts reflect documented assumptions regarding cathode material processing capacity expansion and dendrite suppression chemistry maturation. Practitioners should keep alternative scenarios live as solid-state battery commercialization timelines and lithium iron phosphate cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Japan Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Primary Battery Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Military Battery Packs Market
Batteries
Utility Battery Market
Batteries
Europe Consumer Battery Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
South America Primary Battery Market
Batteries
Netherlands Rechargeable Battery Market
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
Europe Industrial Battery Market
Batteries
Drone Lithium Battery Charger Market