
 Sensors in Oil and Gas Market | 2026-2036
Sensors in Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Sensors in Oil and Gas Market Insights
North American sensor manufacturers is broadening output for harsh-environment wellhead monitoring. Honeywell International Inc. leverages its distributed control architecture to anchor premium positioning in upstream pressure sensing. Emerson Electric Co. sustains deep integration with offshore platform operators through its Roxar subsea instrumentation line. Baker Hughes competes on fiber-optic sensing depth ratings that reach beyond fifteen thousand feet in Gulf of Mexico deployments.
Sensors in oil and gas encompass transducers that convert physical parameters including pressure, temperature, flow rate, and acoustic signatures into measurable electrical or optical signals, typically operating across temperature ranges from minus forty to two hundred degrees Celsius and pressure ratings exceeding fifteen thousand psi for downhole applications. Their primary commercial purpose centers on real-time asset integrity monitoring, enabling predictive maintenance and minimizing unplanned shutdowns in hydrocarbon extraction and processing infrastructure. Pressure sensors command the largest installed base across exploration and production fields, though fiber optic technology is capturing the fastest expansion as operators seek immunity to electromagnetic interference in subsea tiebacks. Wireless sensor networks now penetrate mature onshore basins where retrofit economics favor battery-powered transmitters over cabled alternatives, while smart sensors with embedded edge computing concentrate margin pools in integrated refinery automation packages.
The EPA enforces methane monitoring mandates under the Inflation Reduction Act that require operators to deploy continuous emissions detection at production sites, directly expanding demand for ultrasonic and optical gas imaging sensors. OSHA process safety management standards and API recommended practices further shape sensor specification, calibration intervals, and SIL certification requirements for hazardous area installations. Stakeholders must weigh capital deployment between wireless retrofit architectures and greenfield fiber optic backbone investments as field digitalization standards crystallize across major producing regions.
Market Dynamics
EPA methane mandates under the Inflation Reduction Act are forcing upstream operators to replace intermittent manual inspections with continuous emissions monitoring hardware, compressing deployment timelines and reshaping sensor procurement specifications across the Permian Basin and Gulf of Mexico.
Growth Catalysts
- EPA Inflation Reduction Act methane rules:Continuous emissions monitoring mandates at production sites directly expand demand for ultrasonic and optical gas imaging sensors, with operators facing penalties for undetected leaks.
- Permian Basin digitization:Texas and New Mexico operators are retrofitting mature well pads with wireless sensor networks to enable real-time reservoir management and predictive maintenance workflows.
- Fiber-optic sensing immunity:Subsea tieback projects favor distributed acoustic and temperature sensing for electromagnetic interference immunity in deepwater Gulf of Mexico installations.
Market Restraints
- High-purity sapphire and specialized ceramics:Downhole pressure sensor manufacturing depends on limited suppliers for transducer substrates, creating input cost volatility and lead time uncertainty.
- Subsea umbilical fabrication concentration:Gulf of Mexico fiber-optic sensor deployments rely on a narrow base of specialized marine cable manufacturers in Norway and the United Kingdom.
- API 6A and SIL certification timelines:Hazardous area sensor qualification requires extended third-party validation cycles that delay field deployment and compress vendor margins.
Strategic Opportunities
- Orphaned well monitoring programs:Pennsylvania, Ohio, and West Virginia state agencies are funding sensor deployments to monitor abandoned well methane emissions, creating public-sector demand channels.
- Edge computing convergence:Smart sensors with embedded analytics enable localized decision-making at wellheads, reducing latency for critical shutdown decisions in upstream automation.
- Battery-powered wireless retrofit architectures:Mature onshore basins favor retrofit economics over greenfield cabled infrastructure, opening deployment models for low-power wide-area network protocols.
Industry Challenges
- Subsea installation engineering specialization:Deepwater sensor deployment requires rare cross-training in marine operations, fiber splicing, and pressure-rated electronics packaging.
- Legacy SCADA integration complexity:Brownfield refineries and production facilities operate heterogeneous control systems that resist seamless integration with modern digital sensor protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensors in Oil and Gas Market |
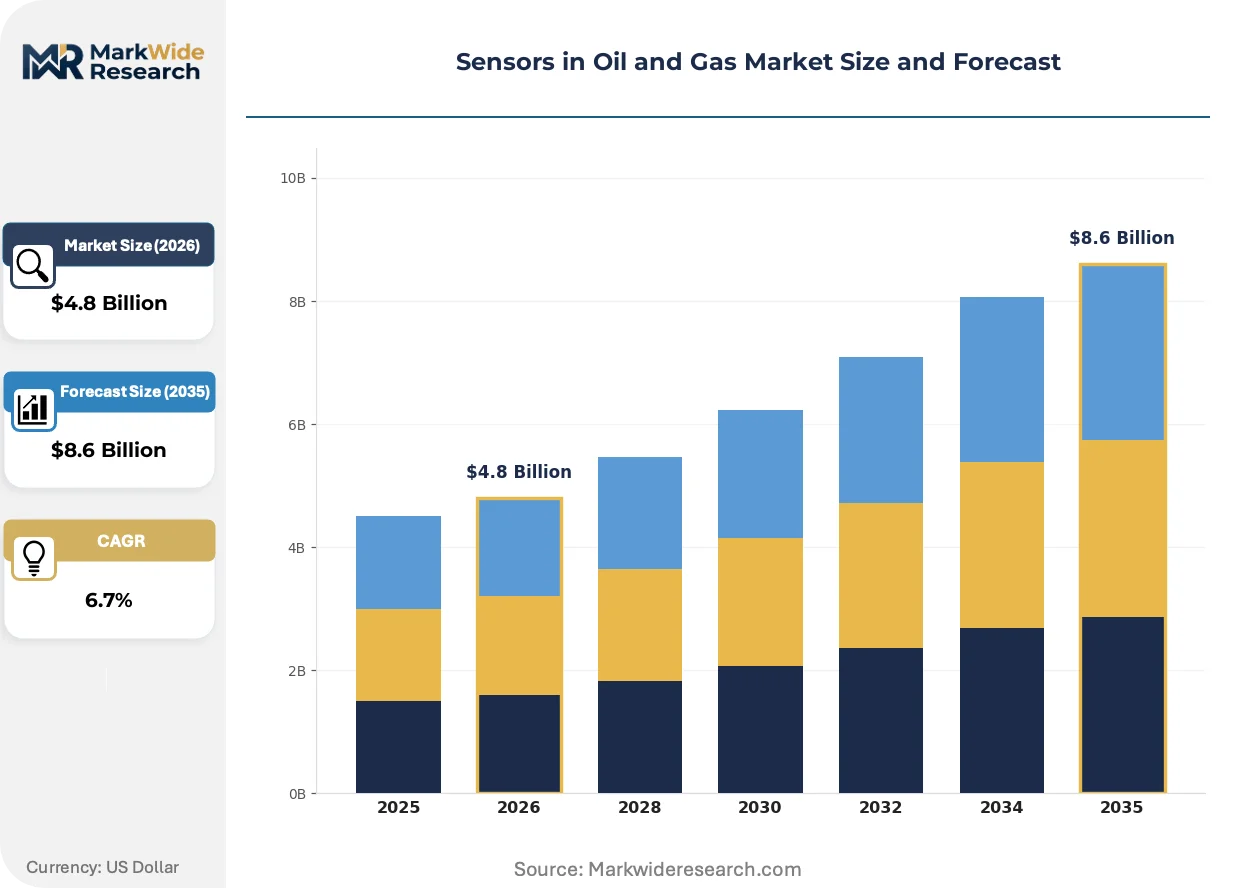
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Flow Sensors, Acoustic Sensors Application: Exploration, Drilling, Production, Refining Technology: Wireless, Smart, Fiber Optic, Ultrasonic End User: Oil Companies, Gas Producers, Service Providers, Refinery Operators |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., ABB Ltd., Siemens AG, TE Connectivity Ltd., Robert Bosch GmbH, Rockwell Automation Inc., Gems Sensors, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensors in Oil and Gas Market Trends and Innovations
Digital twin architectures are reshaping how operators consume sensor data, shifting value capture from hardware sales toward integrated analytics platforms that contextualize real-time measurements against simulated asset behavior.
Distributed fiber-optic sensing is consolidating well surveillance economics by replacing discrete point sensors with continuous temperature and acoustic profiles along the entire wellbore. Permian Basin operators are deploying this technology in horizontal laterals to detect fluid breakthrough and optimize artificial lift settings. The structural consequence is consolidating multiple legacy sensor categories into single-cable installations that reduce complexity and enable faster intervention decisions.
EPA enforcement of Inflation Reduction Act methane monitoring requirements is compressing sensor deployment schedules and tightening calibration protocols. Operators must now maintain continuous detection coverage rather than periodic manual surveys, forcing upgrades to ultrasonic and optical gas imaging systems. Upstream production sites in Texas and New Mexico face the steepest compliance curves as they retrofit thousands of existing facilities.
Buying patterns are fragmenting as supermajors consolidate sensor procurement through integrated digitalization frameworks while independent operators favor modular, vendor-agnostic hardware. Master service agreements with automation integrators are displacing direct sensor vendor relationships in large-scale offshore projects. This bifurcation is most pronounced in the Gulf of Mexico, where platform operators demand turnkey sensing-to-cloud solutions rather than component-level transactions.
Sensors in Oil and Gas Market Segmentation
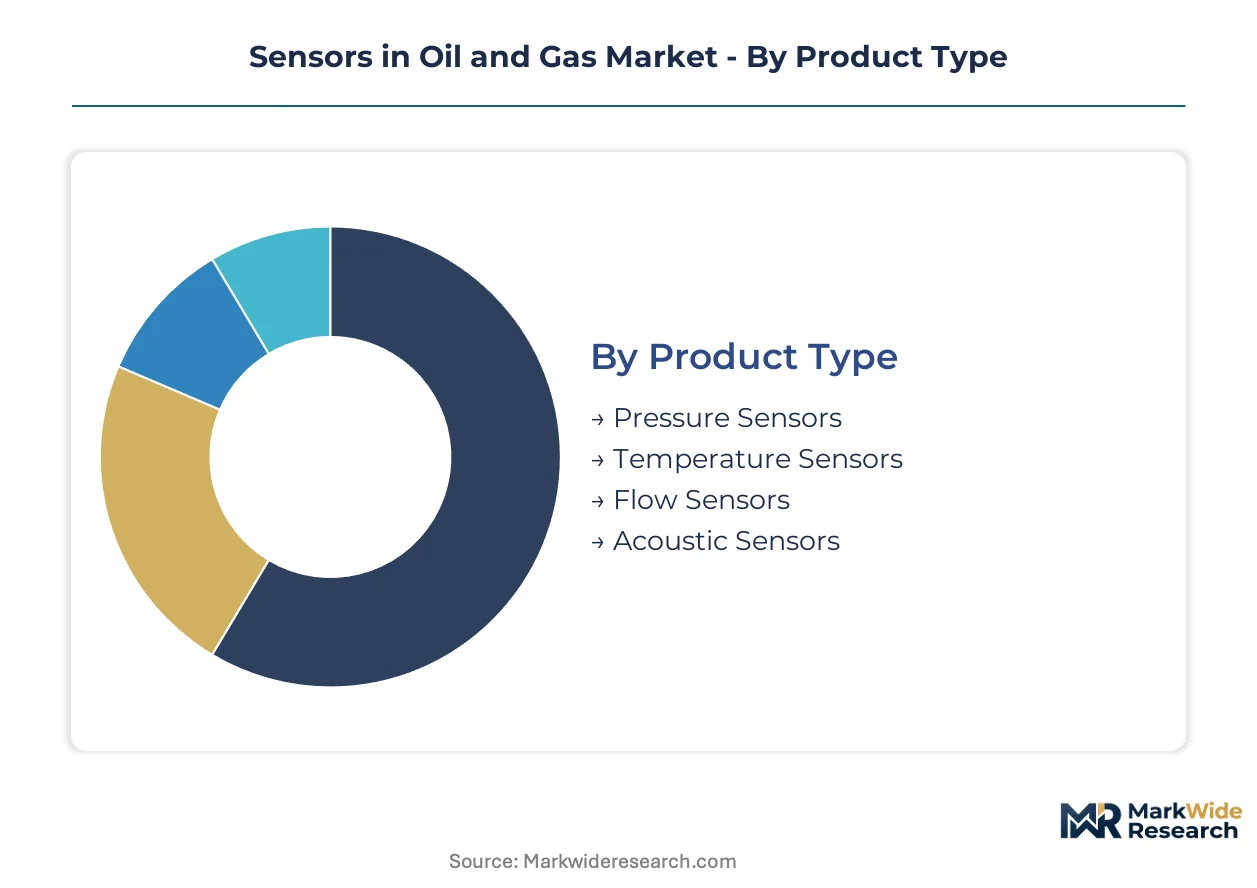
Sensor procurement patterns fragment sharply across the oil and gas value chain. Upstream operators prioritize pressure-rated transducers for wellbore integrity, while downstream buyers demand integrated smart sensor packages for refinery automation. Technology selection hinges on electromagnetic interference tolerance, retrofit economics, and regulatory compliance timelines.
Product Type:
Buyers differentiate primarily by the physical parameter being monitored and the harshness of the installation environment.
- Pressure Sensors:Piezoelectric and MEMS-based transducers dominate downhole applications with ratings exceeding fifteen thousand psi. Demand concentrates in the Permian Basin where operators monitor wellhead integrity for artificial lift optimization and EPA methane compliance.
- Temperature Sensors:Thermocouples and RTDs span minus forty to two hundred degrees Celsius across wellbore and pipeline installations. Gulf of Mexico subsea tiebacks favor fiber-optic distributed temperature sensing for electromagnetic immunity in deepwater completions.
- Flow Sensors:Coriolis and ultrasonic meters measure multiphase production streams at custody transfer points.
- Acoustic Sensors:Distributed acoustic sensing cables detect sand production and flow regime changes along horizontal laterals.
Volume sits with pressure sensors; growth tilts toward acoustic sensing for real-time production surveillance.
Application:
Deployment economics vary dramatically between greenfield installations and brownfield retrofits across the hydrocarbon lifecycle.
- Production:Wellhead monitoring, artificial lift optimization, and separator level control drive the largest installed base of pressure and temperature transducers. Texas and New Mexico operators retrofit mature pads with wireless networks to satisfy EPA continuous emissions monitoring mandates under the Inflation Reduction Act.
- Drilling:Measurement-while-drilling and logging-while-drilling systems require shock-hardened sensors rated for high-vibration downhole conditions. Directional drilling in the Permian Basin and Gulf of Mexico pushes demand for gyroscopic inclination sensors and dynamic pressure transducers.
- Exploration:Seismic acquisition and reservoir characterization employ geophone arrays and microseismic monitoring systems.
- Refining:Process control systems integrate smart sensors with distributed control architectures for distillation column optimization and safety instrumented systems.
Revenue concentrates in production applications; drilling sensors are expanding most quickly as lateral lengths extend and real-time geosteering becomes standard practice.
Technology:
Connectivity architecture choices determine total cost of ownership and integration complexity for field digitalization programs.
- Fiber Optic:Distributed acoustic and temperature sensing cables replace discrete point sensors along entire wellbores, eliminating electromagnetic interference vulnerability in subsea installations. Gulf of Mexico operators deploy this technology for sand detection and flow assurance monitoring in deepwater tiebacks.
- Wireless:Battery-powered transmitters operating on low-power wide-area network protocols enable retrofit economics in mature onshore basins where cabled infrastructure is prohibitively expensive.
- Smart:Edge-computing-enabled sensors embed localized analytics for predictive maintenance and autonomous shutdown decisions at wellheads.
- Ultrasonic:Gas leak detection systems satisfy EPA methane monitoring requirements with continuous coverage replacing periodic manual inspections.
Installed base favors wireless retrofit architectures; fiber optic systems are gaining share fastest in subsea greenfield developments.
End User:
Procurement sophistication and integration requirements diverge between integrated operators and specialized service contractors.
- Oil Companies:Supermajors and large independents specify sensor packages through master service agreements with automation integrators, demanding turnkey sensing-to-cloud solutions for offshore platforms and digital oilfield programs.
- Refinery Operators:Downstream processors prioritize SIL-certified smart sensors with embedded diagnostics for process safety management compliance and OSHA regulatory adherence.
- Gas Producers:Midstream-focused operators concentrate sensor procurement on custody transfer metering and pipeline leak detection for FERC-regulated infrastructure.
- Service Providers:Drilling contractors and completion specialists rent specialized downhole sensors on a project basis, favoring modular, vendor-agnostic hardware for operational flexibility.
Spending dominance rests with oil companies; service providers represent the steepest expansion trajectory as integrated project delivery models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin shale formations anchor upstream sensor demand as operators digitize wellheads across West Texas and southeastern New Mexico. Norwegian North Sea subsea infrastructure drives fiber-optic sensing procurement for deepwater tiebacks. Chinese Sichuan shale gas development accelerates pressure transducer deployment in high-temperature drilling environments.
United States
EPA methane monitoring mandates under the Inflation Reduction Act force Texas and New Mexico operators to install continuous emissions detection hardware across thousands of Permian Basin well pads. OSHA process safety management standards govern sensor calibration intervals for hazardous area installations. Houston anchors North American sensor procurement as supermajors consolidate digitalization contracts through integrated automation frameworks.
Norway
North Sea subsea tieback projects favor distributed fiber-optic sensing for electromagnetic immunity in deepwater completions at pressures exceeding fifteen thousand psi. The Norwegian Petroleum Directorate enforces strict well integrity monitoring regulations that mandate redundant pressure sensing on all production installations. Stavanger concentrates subsea engineering expertise where marine cable manufacturers supply umbilical infrastructure for Gulf of Mexico export markets.
China
Sichuan Basin shale gas operators deploy high-temperature pressure transducers for horizontal drilling in geologically complex formations. MEE emissions standards tighten leak detection requirements for natural gas processing infrastructure. Chongqing anchors domestic sensor manufacturing clusters serving both upstream exploration and midstream pipeline monitoring applications.
Saudi Arabia
Aramco offshore field developments in the Arabian Gulf drive demand for subsea instrumentation rated to extreme pressure and temperature conditions. The national oil company mandates digital twin integration for all new production facilities, embedding smart sensors with edge computing capabilities. Dhahran concentrates engineering procurement decisions for sensor packages across the kingdom's upstream and downstream capital programs.
Brazil
Pre-salt carbonate reservoirs in the Santos Basin require specialized downhole sensors for high-pressure high-temperature well conditions exceeding standard ratings. ANP regulatory frameworks govern well integrity monitoring and safety instrumented systems for floating production installations. Rio de Janeiro anchors subsea engineering clusters where local content requirements shape sensor procurement specifications for international vendors.
Sensors in Oil and Gas Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wireless retrofit architectures and edge-computing integration. The vendor base stratifies across three tiers: diversified industrial conglomerates with distributed control architectures, specialized subsea instrumentation houses, and modular wireless sensor developers. Competitive positioning hinges on hazardous area certification depth, fiber-optic pressure rating thresholds, and integration complexity with legacy SCADA infrastructure. Consolidation pressure intensifies as supermajors award turnkey sensing-to-cloud contracts that displace component-level vendor relationships.
Within the diversified industrial tier, Honeywell International Inc., Emerson Electric Co., and Baker Hughes exemplify contrasting strategic positions. Honeywell leverages distributed control architecture heritage to anchor premium positioning in upstream pressure sensing applications. Emerson sustains deep integration with offshore platform operators through specialized subsea instrumentation capabilities. Baker Hughes competes on fiber-optic sensing depth ratings that address extreme wellbore conditions in deepwater deployments. These three represent archetypal approaches to market participation: control-system anchoring, subsea specialization, and sensing technology depth respectively.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| ABB Ltd. |
| Siemens AG |
| TE Connectivity Ltd. |
| Robert Bosch GmbH |
| Rockwell Automation Inc. |
| Gems Sensors |
| Baker Hughes |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between SIL-rated subsea instrumentation and commodity wireless retrofit hardware manifests in both pricing power and supply chain configuration. Premium-tier vendors bundle extended calibration warranties and field engineering support into multi-year service agreements, while economy-tier suppliers compete on unbundled hardware transactions with third-party maintenance obligations.
Pricing Analysis
Warranty and calibration bundling separates premium sensor vendors from commodity competitors in contract negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects SIL certification depth, fiber-optic pressure ratings, and API 6A validation status. Cost compression in standard-tier wireless transmitters is intensifying because battery chemistry suppliers face raw material volatility. Independent operators in mature onshore basins exhibit highest price sensitivity; supermajors executing integrated digitalization frameworks demonstrate lowest sensitivity due to lifecycle cost framing.
Supply Chain Analysis
High-purity sapphire substrate supply rests on specialized ceramic manufacturers in Norway, the United Kingdom, and Germany. Transducer fabrication draws from precision machining clusters in Switzerland and Japan, while marine umbilical assembly concentrates in Norwegian coastal facilities. Single-source vulnerability pervades subsea fiber-optic cable qualification given extended API validation timelines. Distribution runs through automation integrators holding master service agreements with supermajors rather than direct component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into marine umbilical manufacturing represents the decisive upstream lever as fiber-optic deployment depth ratings become the primary competitive differentiator in deepwater markets.
For Market Incumbents: Acquire specialized marine cable engineering capabilities to secure umbilical supply for Gulf of Mexico subsea projects. Lock in long-term sapphire substrate offtake agreements with Norwegian and German suppliers to insulate against input cost volatility. Pressure sensor vendors face margin compression from emerging wireless retrofit specialists unless they anchor control system integration.
For New Entrants and Emerging Players: EPA methane monitoring mandates under the Inflation Reduction Act in the United States open a window for ultrasonic and optical gas imaging sensor deployment across thousands of Permian Basin well pads. Target orphaned well monitoring programs in Pennsylvania, Ohio, and West Virginia where state agencies fund public-sector procurement channels. Pursue battery-powered wireless retrofit architectures with LPWAN protocol specialization to bypass cabled infrastructure incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with subsea instrumentation specialists given accelerating pre-salt and deepwater tieback activity in Brazil and the Gulf of Mexico. Long-term viability favors vendors with certified fiber-optic pressure ratings exceeding fifteen thousand psi and embedded edge computing capabilities. Watch EPA enforcement intensity on continuous emissions monitoring as the inflection indicator for ultrasonic sensor demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sapphire Substrates | Captive supply of high-purity ceramic transducer materials reduces Norwegian supplier dependency. |
| Fiber-Optic Pressure Rating Extension | Fifteen-thousand-plus psi certification unlocks pre-salt carbonate reservoir contracts in Brazil. |
| Edge Computing Module Development | Embedded analytics at wellheads enable autonomous shutdown decisions for Aramco digital twin programs. |
| Wireless Retrofit Architecture Launch | LPWAN battery-powered transmitters address mature Permian Basin pad economics without cable trenching. |
| API 6A Certification Acceleration | Compressed third-party validation timelines capture EPA methane compliance deployment windows. |
Research Methodology
Document review covered regulatory filings from EPA and OSHA, API recommended practice documentation, and subsea engineering technical standards, complemented by interviews with upstream automation directors, subsea project engineers, and refinery process safety managers. Secondary validation drew from SEC 10-K disclosures of diversified industrial conglomerates, FERC infrastructure filings, and Norwegian Petroleum Directorate well integrity regulations. Bottom-up sensor deployment estimates triangulated against top-down hydrocarbon production forecasts across the analysis window.
Historical deployment patterns cross-referenced against panel input from automation integrators and supermajor digitalization program leads. Segmentation modeling spanned product type, application, connectivity technology, and end-user procurement sophistication. CAGRs were derived from regression analysis of field digitalization capital allocation trends, EPA compliance timeline compression, and fiber-optic technology substitution rates in subsea greenfield developments.
The model assumes a particular technology adoption path; alternative pathways for wireless sensor networks in mature onshore basins would alter the outlook if battery chemistry breakthroughs extend transmitter lifecycles beyond current replacement economics. Forecasts reflect assumptions regarding regulatory enforcement intensity, subsea project sanctioning rates, and legacy SCADA integration complexity. A small set of triggers—EPA penalty escalation, Norwegian umbilical supply disruption, and pre-salt reservoir productivity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Oil & Gas Equipment MRO Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Latin America Artificial Lift System Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Liquefied Natural Gas Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market
Oil & Gas
Coiled Tubing Services Market