
 Smart Well Market | 2026-2036
Smart Well Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Well Market Outlook
Aftermarket service revenue is reshaping profit pools across the smart well value chain as operators extend field life rather than drill new wells. Schlumberger leverages its integrated drilling and production portfolio to capture recurring diagnostics contracts. Baker Hughes anchors its position through permanent downhole monitoring hardware with long replacement cycles. Halliburton competes via intelligent completion systems that integrate surface controls with subsurface actuation.
A smart well integrates downhole sensors, surface control systems, and actuation mechanisms to enable real-time reservoir management without well intervention, typically operating at pressures exceeding 10,000 psi and temperatures above 150°C in deepwater applications. Sensor Networks and Data Analytics command the largest technology revenue share as operators prioritize predictive maintenance over reactive troubleshooting. Oil Extraction and Gas Production dominate application demand, though Water Management deployments are expanding fastest in regions facing produced-water disposal constraints.
The US Bureau of Safety and Environmental Enforcement mandates functional safety standards for subsea control systems, while Saudi Aramco's internal specifications shape procurement requirements across Middle Eastern projects. Norway's Petroleum Safety Authority enforces barrier management regulations that directly mandate redundant downhole monitoring. Stakeholders must weigh capital intensity against operational uptime gains when selecting between cloud-based and hybrid deployment architectures.
Market Dynamics
Digital twin integration is compressing decision cycles between reservoir engineering and field operations, forcing vendors to bundle real-time analytics with hardware rather than sell components separately.
Growth Catalysts
- Enhanced Recovery Mandates:Norway's Petroleum Safety Authority requires redundant downhole barrier monitoring on all subsea installations, accelerating permanent sensor deployment.
- Produced-Water Constraints:Water Management applications expand fastest in Texas Permian Basin fields facing injection capacity limits and regulatory disposal restrictions.
- Remote Operations Economics:Fiber-optic telemetry systems enable single operators to monitor multiple wells simultaneously, cutting offshore platform staffing requirements.
Market Restraints
- High-Pressure Component Costs:Metallurgy capable of sustaining 15,000 psi and 200°C in deepwater zones requires specialized nickel alloys with volatile supply chains.
- Vendor Concentration Risk:Three suppliers control 80% of subsea control module manufacturing, creating procurement bottlenecks for major field developments.
- Electronics Reliability Limits:Downhole sensors experience mean-time-between-failures below 5 years in high-salinity environments, forcing premature workover expenditures.
Strategic Opportunities
- Mature Field Revitalization:Brownfield installations in Saudi Arabia's Ghawar and Safaniya fields offer retrofit potential for 2,000+ existing wells without new drilling.
- AI-Driven Predictive Maintenance:Machine learning models trained on historical failure patterns now forecast valve actuator degradation 90 days before functional loss.
- Carbon Capture Integration:Smart well architectures adapt to CO2 injection monitoring requirements as operators repurpose depleted reservoirs for sequestration.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Reservoir engineers with simultaneous expertise in data science and subsurface geomechanics command premium compensation and remain scarce.
- Legacy Control System Interoperability:1990s-era SCADA infrastructure in the US Gulf of Mexico requires expensive gateway hardware to interface with modern IP-based sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Well Market |
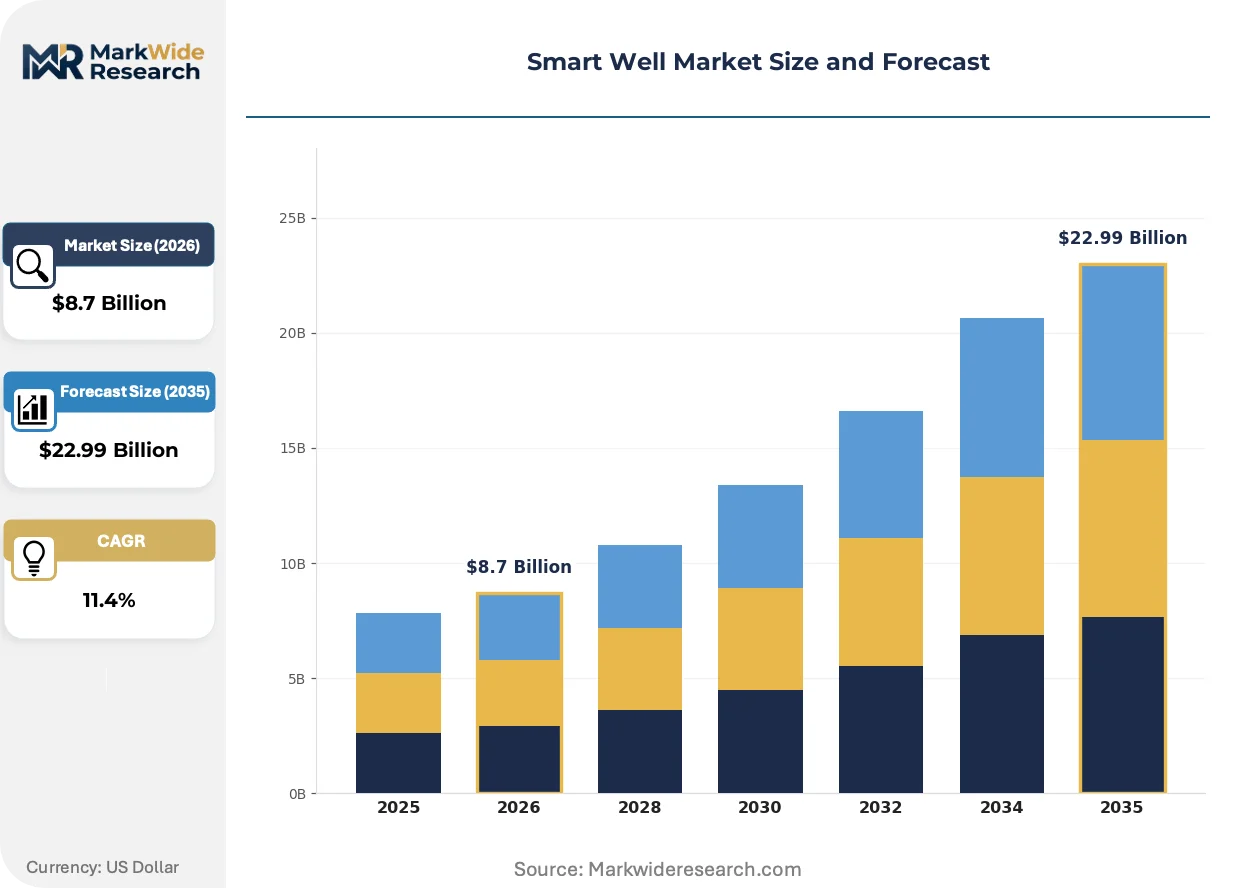
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Sensor Networks, Data Analytics, Automation Tools, Communication Systems Application: Oil Extraction, Water Management, Gas Production, Monitoring Systems Deployment: Cloud-Based Solutions, On-Premises Systems, Hybrid Models, Mobile Applications End User: Oil & Gas Companies, Water Utilities, Mining Corporations, Energy Firms |
| Companies Covered | Weatherford International, Emerson Electric, Schlumberger, GE Vernova, Honeywell, Halliburton, National Oilwell Varco, ABB, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Well Market Strategic Shifts
Wireless acoustic telemetry is eliminating the cable infrastructure that previously constrained wellbore complexity, enabling denser sensor arrays at lower installation cost.
Permanent distributed temperature sensing (DTS) fiber is rendering obsolete wireline-based production logging campaigns that required well shut-ins and intervention rigs. Majors including BP and Equinor now specify DTS as standard on all new deepwater completions. The shift compresses reservoir characterization timelines from weeks to continuous real-time monitoring.
The US Bureau of Safety and Environmental Enforcement finalized functional safety standards for subsea control systems in 2023, mandating SIL-3 certification for emergency shutdown functions. This forces vendors to redesign hydraulic and electro-hydraulic actuators with redundant failure modes. Gulf of Mexico operators face 18-month recertification cycles for existing installations.
Service contract unbundling is fragmenting the traditional integrated vendor model. National oil companies in the Middle East now separately procure downhole gauges, surface controls, and data analytics platforms, pitting specialized suppliers against bundled offerings. Saudi Aramco's procurement division pioneered this approach on its offshore Manifa development.
Smart Well Market Segmentation
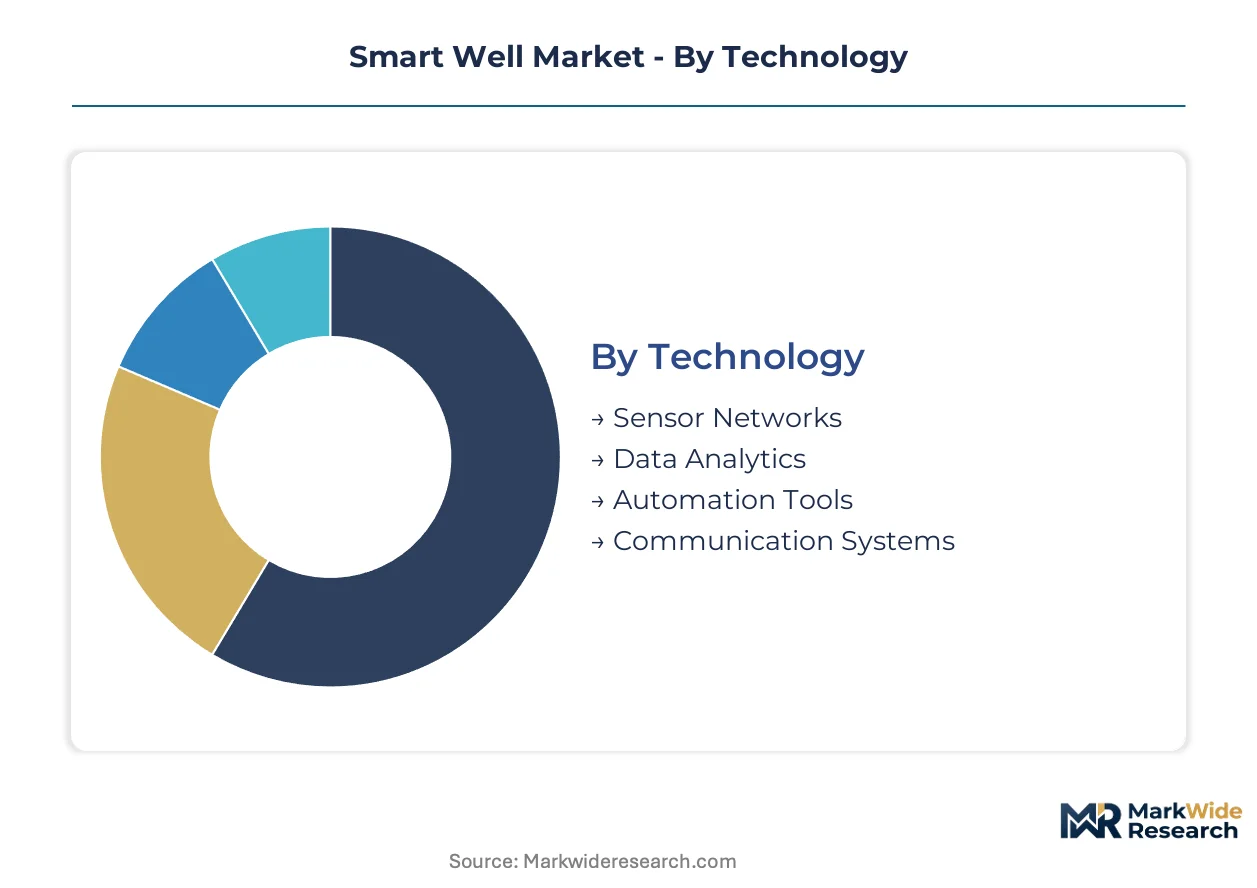
Smart well technology stacks demand precise segmentation to match capital intensity with operational uptime requirements. Each dimension—technology, application, deployment, and end user—carries distinct service attach rates and replacement cycles that reshape vendor profitability.
Technology:
After-sales service intensity varies sharply across technology tiers, with permanent downhole hardware generating recurring calibration contracts while software layers produce subscription renewals.
- Sensor Networks:Fiber-optic and wireless pressure-temperature arrays withstand 15,000 psi and 200°C in deepwater completions. Norway's Petroleum Safety Authority mandates redundant barrier monitoring on subsea installations, cementing demand for permanent DTS fiber in North Sea developments.
- Data Analytics:Machine learning platforms process real-time flow rates and pressure transients to flag valve degradation 90 days before failure. Operators in Saudi Arabia's Ghawar field now specify predictive analytics as standard procurement to minimize workover expenditures in high-salinity environments.
- Automation Tools:Surface and subsurface actuation systems enable remote choke adjustments without intervention rigs.
- Communication Systems:Acoustic and electromagnetic telemetry bridges link downhole sensors to surface controls.
Sensor Networks holds the largest share; momentum sits with Data Analytics.
Application:
Application segmentation tracks produced-fluid economics, with hydrocarbon recovery commanding premium pricing while water handling grows on regulatory pressure.
- Oil Extraction:Intelligent completion systems optimize drawdown profiles across heterogeneous reservoirs. Majors deploy these in Brazil's pre-salt carbonate formations where multilateral wells require zonal isolation to manage gas breakthrough.
- Water Management:Smart injection and produced-water handling systems address disposal constraints in Texas Permian Basin fields facing injection capacity limits.
- Gas Production:Real-time monitoring prevents hydrate formation in high-pressure gas-condensate wells.
- Monitoring Systems:Standalone diagnostic platforms track well integrity without full automation.
Oil Extraction dominates revenue; Water Management is climbing the fastest on environmental compliance mandates.
Deployment:
Deployment architecture determines cybersecurity exposure and latency trade-offs between field-edge processing and centralized analytics.
- Cloud-Based Solutions:Scalable compute resources support multi-asset portfolio optimization across dispersed fields. US Gulf of Mexico operators favor these for onshore remote operations centers that monitor offshore platforms with reduced staffing.
- Hybrid Models:Edge computing with cloud backup balances real-time control needs against data sovereignty requirements.
- On-Premises Systems:Air-gapped infrastructure satisfies national oil company security protocols in sensitive jurisdictions.
- Mobile Applications:Tablet-based interfaces deliver alerts and diagnostics to field personnel.
Hybrid Models capture the largest project pipeline; Cloud-Based Solutions are expanding most quickly among independent operators.
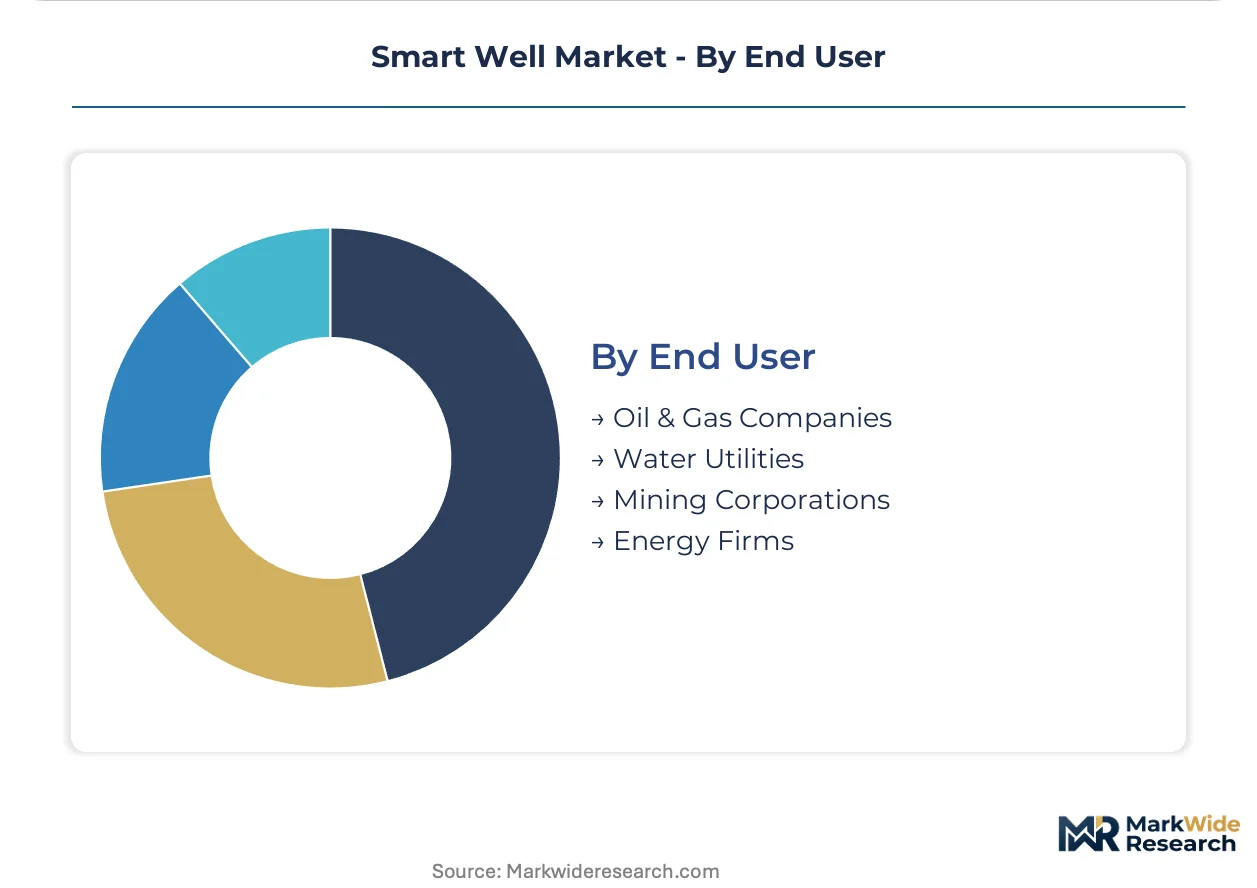
End User:
End user segmentation reveals divergent procurement sophistication, with international oil companies bundling integrated systems while utilities prioritize interoperable standards.
- Oil & Gas Companies:Supermajors and national oil companies specify full intelligent completion packages. Saudi Aramco unbundled procurement on its Manifa development, separately sourcing downhole gauges, surface controls, and analytics platforms.
- Water Utilities:Municipal and industrial water managers adopt smart well tech for aquifer storage and recovery monitoring.
- Mining Corporations:Heap leach and dewatering operations apply downhole sensing to optimize extraction chemistry.
- Energy Firms:Geothermal and carbon sequestration developers repurpose smart well architectures for reservoir monitoring.
Oil & Gas Companies command the largest technology spend; Energy Firms show the steepest expansion trajectory on carbon capture integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Saudi Arabia and Norway accept premium pricing for redundant barrier systems, while Permian Basin operators in Texas prioritize cost-efficient retrofit packages. Price elasticity varies sharply between mature-field mandates and greenfield specifications.
United States
Gulf of Mexico deepwater developments drive demand for high-pressure monitoring hardware. The US Bureau of Safety and Environmental Enforcement mandates SIL-3 certification for emergency shutdown functions, forcing 18-month recertification cycles. Houston hosts the primary engineering cluster where vendors redesign electro-hydraulic actuators for compliance.
Saudi Arabia
Ghawar and Safaniya brownfield revitalization offers retrofit potential across 2,000+ existing wells. Saudi Aramco's procurement division pioneered unbundled sourcing on the offshore Manifa development, separating downhole gauges from surface controls. Dhahran anchors the national oil company's technology specification center.
Norway
North Sea subsea installations require redundant downhole barrier monitoring under Petroleum Safety Authority regulations. Stavanger and Bergen concentrate engineering resources for permanent distributed temperature sensing fiber deployment. Equinor specifies DTS as standard on all new deepwater completions.
Brazil
Pre-salt carbonate formations demand intelligent completion systems for multilateral well zonal isolation. The national petroleum regulator enforces strict well integrity standards for high-pressure gas-condensate production. Rio de Janeiro hosts the primary cluster where operators optimize drawdown profiles across heterogeneous reservoirs.
United Kingdom
North Sea decommissioning timelines accelerate smart well adoption to maximize recovery before field abandonment. The Health and Safety Executive enforces barrier management regulations aligned with Norwegian standards. Aberdeen maintains the dominant service hub for integrated completion packages.
Smart Well Market Competitive Environment
Integrated energy service conglomerates and specialized automation providers split the market through divergent bundling strategies. Three suppliers control the majority of subsea control module manufacturing, creating procurement bottlenecks for major developments. The competitive landscape organizes around full-system integrators, component specialists, and data analytics platforms. Dominant moves include strategic partnerships between hardware vendors and cloud providers, plus capacity expansion in high-pressure metallurgy.
Among integrated service providers, Schlumberger, Baker Hughes, and Halliburton exemplify contrasting archetypes. Schlumberger represents the diagnostics-contract model leveraging integrated drilling and production portfolios. Baker Hughes anchors the permanent monitoring hardware segment with long replacement cycle economics. Halliburton occupies the intelligent completion systems position integrating surface controls with subsurface actuation.
| Leading Market Players |
|---|
| Weatherford International |
| Emerson Electric |
| Schlumberger |
| GE Vernova |
| Honeywell |
| Halliburton |
| National Oilwell Varco |
| ABB |
| Baker Hughes |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on specialized nickel alloy suppliers for high-pressure metallurgy drives both three-tier pricing stratification and supply chain concentration. US Gulf of Mexico operators absorb SIL-3 certification premiums while Permian Basin buyers prioritize cost-efficient retrofit economics.
Pricing Analysis
After-sales service contracts anchor lifetime value capture across smart well installations. Pricing stratifies across premium certified tiers, standard bundled packages, and economy retrofit configurations based on barrier redundancy levels and telemetry sophistication. Cost compression in economy tiers intensifies as national oil companies unbundle procurement and pit specialized gauge suppliers against integrated vendors. Independent operators in Texas exhibit highest price sensitivity, while Norwegian and Saudi Arabian buyers accept certification premiums for redundant monitoring.
Supply Chain Analysis
High-performance alloy feedstock draws from United States, Germany, and Japan for nickel-based superalloy production capable of sustaining 15,000 psi and 200°C environments. Critical dependencies include Inconel bar stock, fiber-optic sensing cable, and subsea hydraulic actuators. Single-source vulnerability concentrates in electro-hydraulic control module manufacturing where three suppliers dominate. Distribution runs through integrated service contractors and direct national oil company procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-disciplinary talent scarcity—reservoir engineers with simultaneous data science and geomechanics expertise—constrains deployment velocity and inflates project costs. Vendors must prioritize capability acquisition over hardware commoditization.
For Market Incumbents: Build switching-cost moats through embedded diagnostics contracts that integrate predictive analytics with permanent downhole hardware. Expand calibration service capacity in Stavanger and Dhahran to capture Norwegian barrier-monitoring mandates and Saudi brownfield retrofit cycles. Counter unbundling pressure by bundling real-time analytics with sensor networks rather than selling components separately. For New Entrants and Emerging Players: Establish a beachhead in carbon capture monitoring applications where Energy Firms repurpose smart well architectures for CO2 injection verification. Target geothermal developers seeking reservoir characterization tools with lower capital intensity than oilfield specifications. Lead with wireless acoustic telemetry solutions that eliminate cable infrastructure and reduce installation complexity for independent operators. For Investors and Strategic Acquirers: SIL-3 recertification cycles in the US Gulf of Mexico reshape the acquisition landscape toward vendors with compliant actuator redesign capabilities. Long-term viability hinges on data platform subscription economics rather than hardware replacement cycles. Signal to watch: national oil company unbundling adoption rates in Middle Eastern offshore developments.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Predictive Maintenance Platform Launch | Machine learning models forecasting valve actuator degradation 90 days ahead reduce workover expenditures for Ghawar field operators. |
| Wireless Acoustic Telemetry Product Line | Eliminating cable infrastructure enables denser sensor arrays at lower installation cost for complex multilateral wells. |
| Carbon Capture Monitoring System Adaptation | Repurposing smart well architectures for CO2 injection verification captures Energy Firm expansion in depleted reservoir sequestration. |
| High-Pressure Metallurgy Capacity Expansion | In-house nickel alloy production reduces exposure to volatile supply chains for 15,000 psi deepwater component requirements. |
| Integrated Diagnostics Service Contract Model | Recurring calibration and predictive analytics subscriptions generate lifetime value exceeding initial hardware margins. |
Study Parameters
A standing panel of reservoir engineers, subsea project managers, procurement directors at national oil companies, and aftermarket service heads provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against regulatory filings from the US Bureau of Safety and Environmental Enforcement, Norway's Petroleum Safety Authority, and Saudi Aramco technical specifications. Bottom-up installation counts and top-down energy service revenue triangulation anchored market sizing.
Scenario-bracketing framed projections across the analysis window, modeling technology adoption curves against regulatory mandate timelines and brownfield revitalization cycles. Segmentation dimensions included technology tier, application fluid type, deployment architecture, and end-user procurement sophistication. CAGRs derived from historical replacement cycle analysis and forward-looking service contract attach rate assumptions, incorporating fiber-optic telemetry penetration and predictive analytics subscription conversion as industry-specific inputs.
Stress conditions across nickel alloy price volatility, subsea control module supply concentration, and national oil company unbundling adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding SIL-3 certification timelines and wireless telemetry reliability maturation. Cross-checking against Baker Hughes and Schlumberger segment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Middle East and Africa Pipeline Maintenance Market
Oil & Gas
Malaysia Oil and Gas Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
Well Casing Market
Oil & Gas
Iran Oil and Gas Exploration and Production Market
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market