
 Iraq Oil and Gas Market | 2026-2036
Iraq Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Iraq Oil and Gas Market Foresight
Petroleum engineering talent shortages across southern Iraq are reorganizing contractor hierarchies and slowing field redevelopment timelines. BP leverages its Rumaila technical service contract to sustain production plateau targets at the world's third-largest oil field. Lukoil anchors development at West Qurna-2 through integrated drilling and enhanced oil recovery programs. PetroChina competes for service awards by positioning its engineering subsidiaries on cost-efficient brownfield rehabilitation scopes.
Iraq oil and gas encompasses the exploration, extraction, processing, and transport of hydrocarbon resources from supergiant carbonate reservoirs with API gravities ranging from heavy 20° to light 35° crude, primarily serving domestic power generation, regional export commitments, and petrochemical feedstock supply. Exploration and production services dominate value capture given the scale of undeveloped reserves in Basra and Missan provinces, while enhanced recovery technology is expanding fastest as maturing fields require waterflood and gas injection interventions to maintain output. Refining infrastructure remains structurally constrained by decades of underinvestment, creating persistent dependency on imported refined products despite abundant crude availability.
Iraq's Ministry of Oil and the federal petroleum regulator govern licensing rounds, production sharing terms, and export quota compliance aligned with OPEC frameworks, while environmental directives from the national environmental authority shape flaring reduction mandates and water management standards for operators. The central bank's foreign exchange regulations influence capital repatriation timelines for international oil companies, directly affecting investment commitment cycles. Stakeholders must monitor federal budget negotiations and Kurdistan Region export dispute resolutions to assess pipeline throughput reliability and fiscal stability.
Market Dynamics
Supergiant field maturation across Basra Governorate is forcing accelerated enhanced oil recovery deployment as natural reservoir pressure declines, while federal licensing reforms reshape contractor economics and foreign operator participation thresholds.
Growth Catalysts
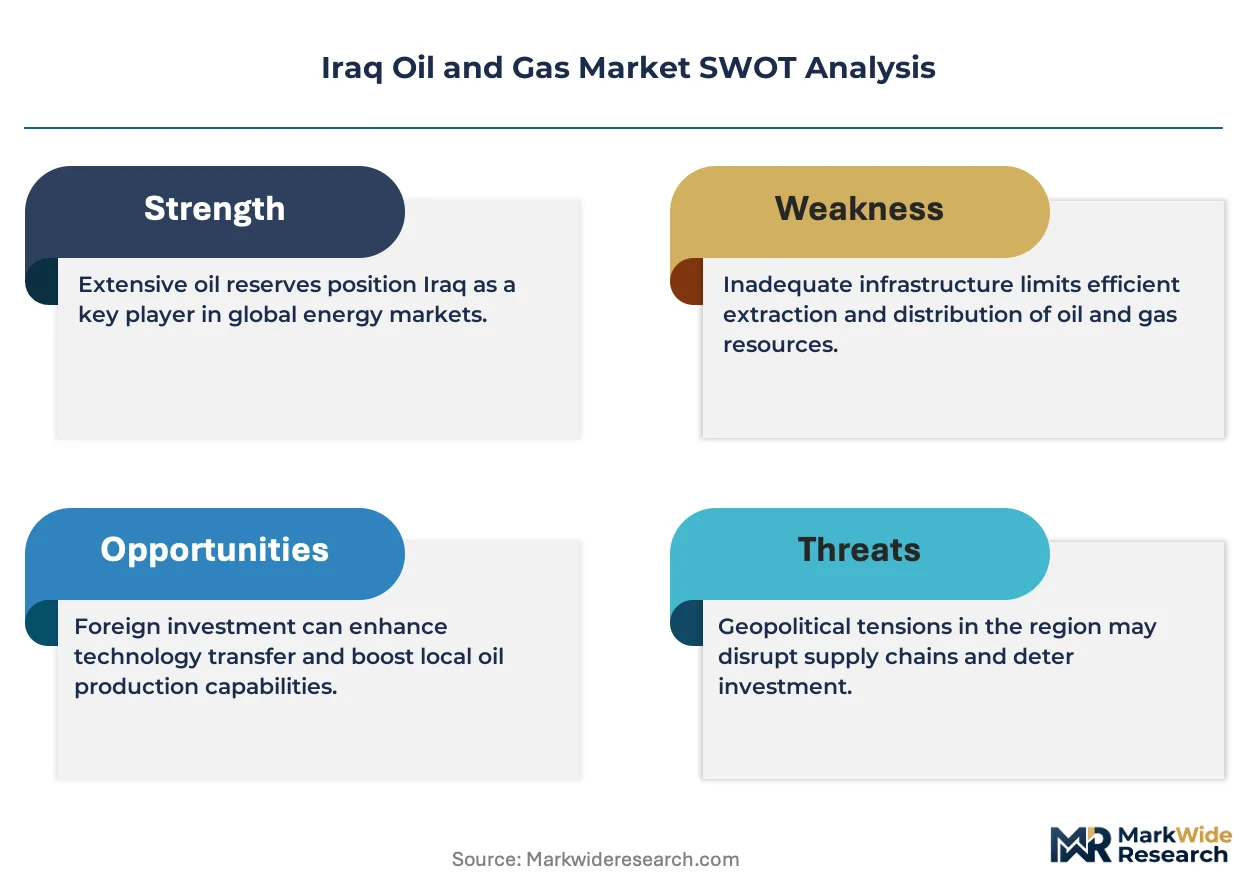
- Federal Licensing Reforms:The Ministry of Oil's revised technical service contract terms reduce cost recovery ceilings and shorten payback periods, incentivizing capital commitment from international operators.
- Basra Power Generation Expansion:Southern Iraq's grid-connected utilities are doubling fuel offtake volumes under long-term supply agreements with upstream producers.
- Waterflood Infrastructure Deployment:Maturing carbonate reservoirs at Rumaila and West Qurna fields require massive water injection capacity, driving drilling and surface facility investment.
Market Restraints
- Capital Repatriation Friction:Central Bank foreign exchange regulations extend dollar conversion timelines for international oil companies, compressing project IRR calculations.
- Refining Capacity Deficit:Domestic refining infrastructure processes under 25% of crude production, forcing structural dependency on imported gasoline and diesel.
- Flare Gas Regulatory Pressure:National environmental authority mandates for gas capture compliance impose unplanned capex on operators lacking integrated gas processing infrastructure.
Strategic Opportunities
- Missan Province Greenfield Development:Undrilled carbonate structures in southeastern Iraq offer lower recovery cost profiles than brownfield rehabilitation of supergiant assets.
- Petrochemical Feedstock Integration:Naphtha and natural gas liquids from associated gas streams can supply planned Basra petrochemical complexes.
- Kurdistan Region Export Normalization:Pipeline throughput reliability improvements would unlock stranded production from northern fields previously constrained by transit disputes.
Industry Challenges
- Petroleum Engineering Talent Scarcity:Reservoir simulation and drilling optimization expertise concentrates with aging expatriate workforces, slowing field redevelopment timelines.
- Legacy Facility Integration Complexity:Brownfield rehabilitation requires interfacing with decades-old surface infrastructure designed for different operating parameters and safety standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iraq Oil and Gas Market |
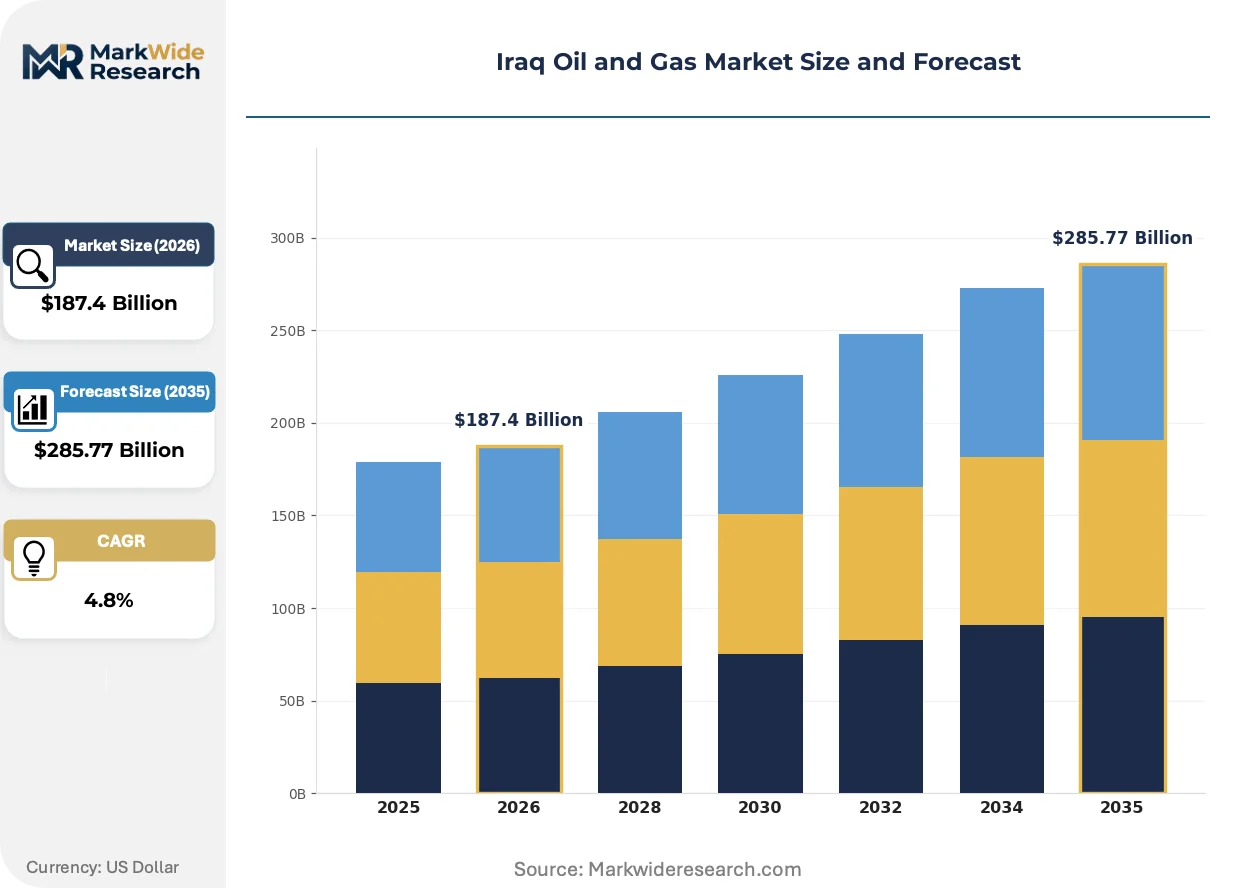
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Production, Refining, Transportation Technology: Drilling, Enhanced Recovery, Processing, Automation End User: Power Generation, Chemical Manufacturing, Automotive, Manufacturing Application: Fuel Supply, Petrochemical Production, Electricity Generation, Industrial Feedstock |
| Companies Covered | ExxonMobil, BP, Lukoil, PetroChina, Chevron, Shell, Gazprom, Petronas, South Oil Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iraq Oil and Gas Market Shifts & Advancements
Digital reservoir characterization and modular gas processing technologies are compressing development cycles, while regulatory pressure on flaring intensity accelerates investment in gas monetization infrastructure.
Intelligent well completion systems are decomposing traditional surface facility footprints by enabling downhole flow control and real-time pressure monitoring without permanent platform installations. Southern Iraqi operators are piloting these systems at West Qurna-2 to sustain plateau production with fewer wellhead interventions. This distributed architecture is decomposing centralized gathering station economics and shifting capex toward subsurface hardware.
The Ministry of Oil's revised gas capture mandates now require operators to submit integrated field development plans with zero routine flaring commitments by 2030. This regulatory pressure is redirecting drilling budgets toward gas processing infrastructure and away from oil-only production targets. Basra Governorate fields with high gas-oil ratios face the steepest compliance cost adjustments.
Long-term offtake contracting is replacing spot market sales for domestic power utilities seeking fuel security. State-owned electricity generators in southern Iraq are negotiating 10-15 year supply agreements with fixed volume floors, displacing the previous annual tender system. This contract structure is most visible in Basra Governorate where grid expansion drives baseload fuel demand.
Iraq Oil and Gas Market Segmentation
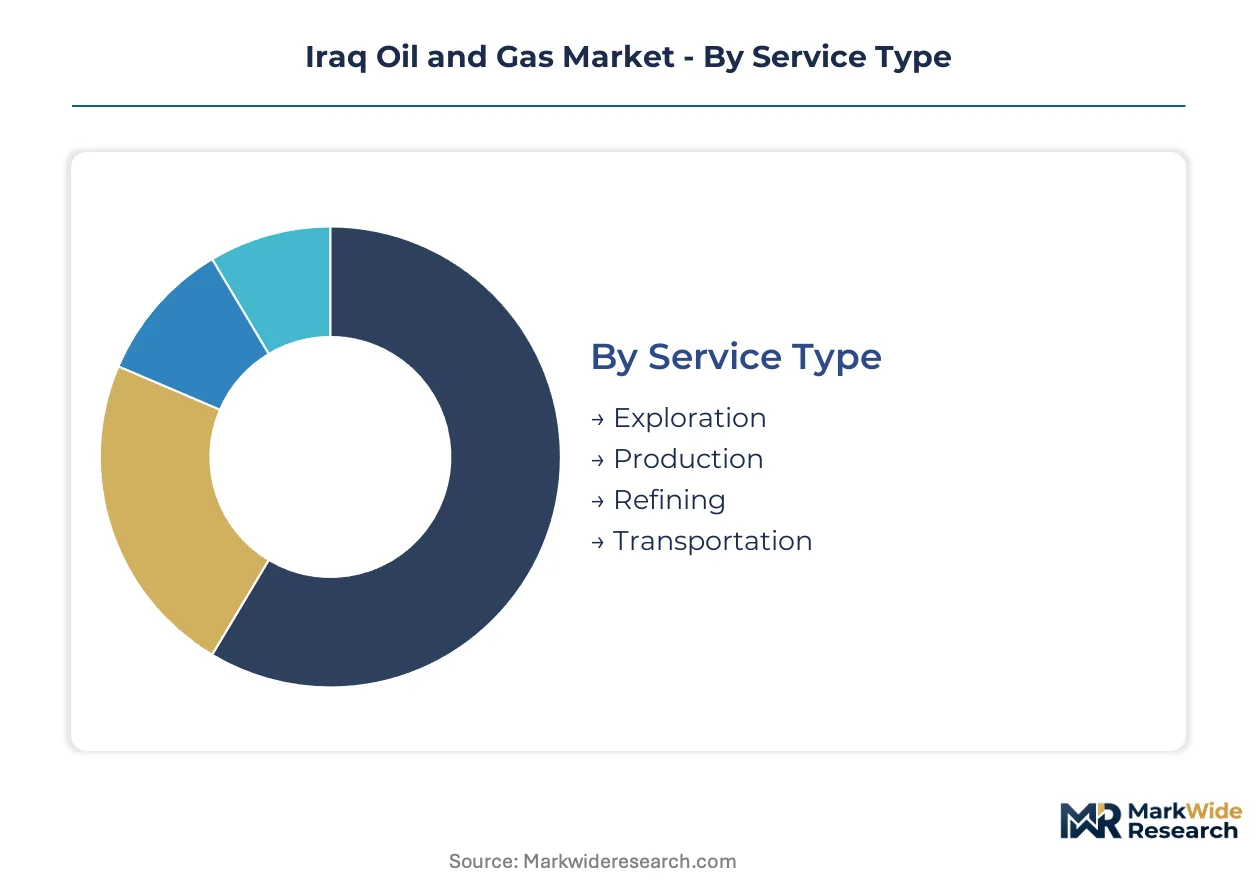
Iraq's oil and gas value chain fragments across distinct operational layers, each shaped by different capital intensity profiles and regulatory exposure. Segment boundaries reflect the dominance of upstream activities against chronic underinvestment in downstream conversion capacity.
Service Type:
Domestic demand concentrates in production and refining services, while transportation and exploration activity remains export-revenue dependent and foreign-operator led.
- Exploration:Seismic surveying and wildcat drilling target undrilled carbonate structures in Missan Province and western desert blocks. Licensing round participation from international operators drives activity, though security clearance delays and contract term disputes constrain rig mobilization timelines.
- Production:Field development, well completion, and artificial lift operations dominate service revenue given the scale of Rumaila, West Qurna, and Zubair supergiant assets. Waterflood infrastructure deployment and workover programs absorb the majority of capital allocation as natural reservoir pressure declines across mature carbonate formations.
- Refining:Capacity expansion and unit rehabilitation at Basra, Daura, and Baiji facilities attempt to reduce structural dependency on imported gasoline and diesel. Domestic crude processing rates remain below operational design due to aging equipment and feedstock quality mismatches.
- Transportation:Pipeline construction, storage terminal operation, and marine loading facility management link southern fields to export terminals at Basra and Khor al-Amaya. Transit disputes through the Kurdistan Region periodically disrupt northern export routes, forcing volume redirection through southern outlets.
Production holds the largest share; momentum sits with transportation as export corridor reliability investments accelerate.
Technology:
Cost tiers separate mature mechanical systems from digital and enhanced recovery platforms requiring specialized engineering procurement.
- Drilling:Directional and horizontal drilling technologies access fractured carbonate reservoirs with complex permeability profiles. Basra Governorate operators deploy extended-reach laterals to maximize reservoir contact while minimizing surface footprint constraints.
- Enhanced Recovery:Waterflooding, gas injection, and chemical EOR methods sustain plateau production at maturing supergiant fields. Rumaila and West Qurna-2 field operators commission massive water treatment and injection capacity to offset natural pressure depletion.
- Processing:Crude stabilization, gas sweetening, and liquids separation infrastructure conditions production for pipeline specification and export quality. Associated gas capture mandates from the national environmental authority redirect processing investment toward integrated gas utilization.
- Automation:Distributed control systems, SCADA networks, and intelligent well completions enable remote monitoring and optimization of dispersed well pads. Southern Iraqi pilots at West Qurna-2 test downhole flow control reducing wellhead intervention frequency.
Drilling commands the largest installed base; automation is climbing the fastest as labor constraints and flaring compliance drive digital adoption.
End User:
Volume concentration varies between state-dominated power utilities and fragmented industrial consumers with divergent fuel specification requirements.
- Power Generation:Grid-connected thermal plants across southern Iraq absorb heavy fuel oil and natural gas under long-term offtake agreements. Basra Governorate utilities expand generation capacity, doubling fuel procurement volumes through fixed-floor supply contracts with upstream producers.
- Chemical Manufacturing:Fertilizer and petrochemical complexes seek naphtha and natural gas liquids as feedstock inputs. Planned Basra petrochemical integration projects aim to monetize associated gas streams currently flared or reinjected.
- Automotive:Transportation fuel demand for gasoline and diesel remains structurally import-dependent given domestic refining deficits. Fuel subsidy policies distort consumption patterns and smuggling incentives across border provinces.
- Manufacturing:Cement, steel, and construction material producers consume fuel oil and natural gas for process heat. Industrial consumers face supply interruptions during peak summer electricity generation periods when fuel redirects to power plants.
Power generation holds the largest share; chemical manufacturing is gaining share fastest as feedstock integration projects advance.
Application:
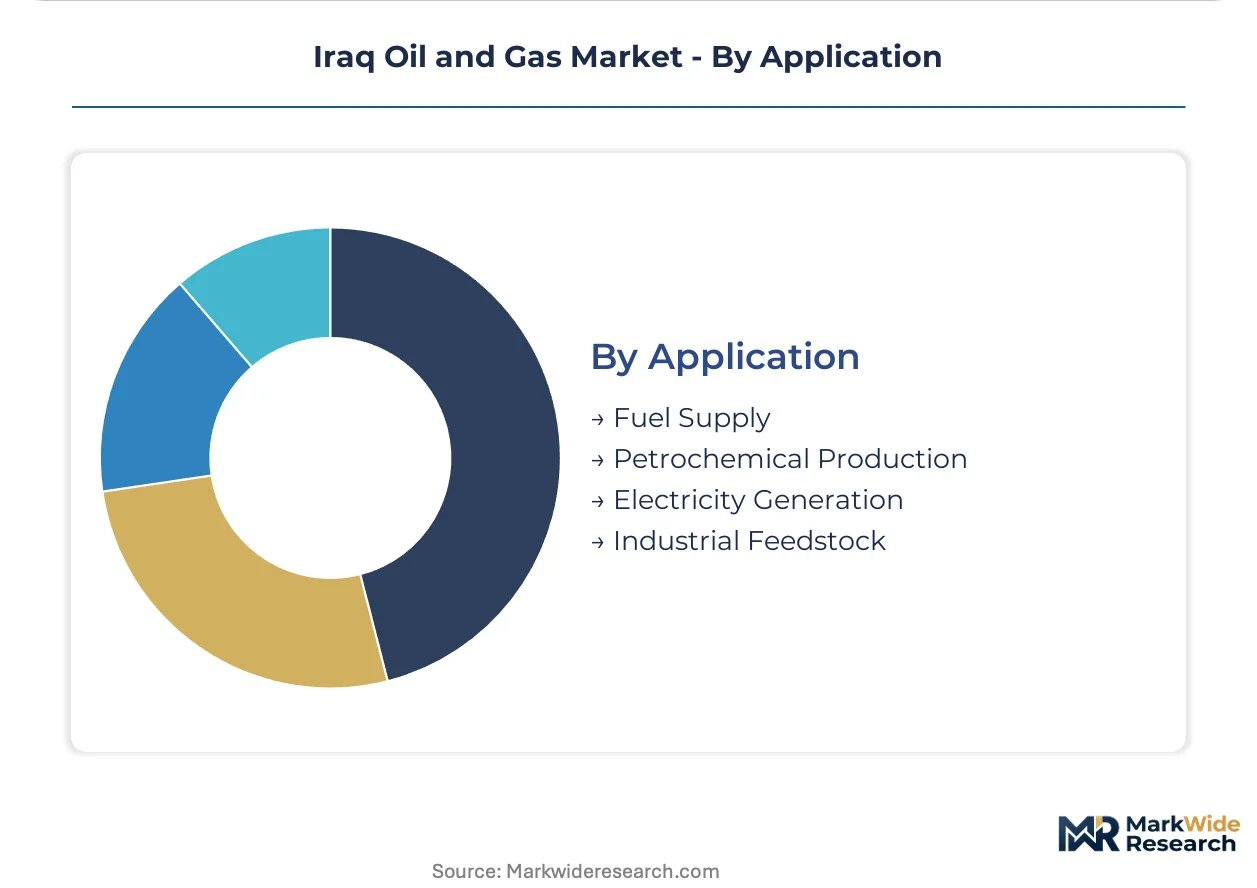
Customer type splits between state-controlled fuel allocation and private industrial procurement with differentiated pricing exposure.
- Fuel Supply:Crude and refined product delivery to domestic utilities, industrial consumers, and export markets. Ministry of Oil distribution networks prioritize power generation and transport sector allocations during supply constraints.
- Petrochemical Production:Conversion of naphtha, ethane, and propane into plastics, fertilizers, and synthetic materials. Basra Governorate complexes seek captive feedstock supply from associated gas processing to reduce import dependency.
- Electricity Generation:Direct fuel combustion in thermal power plants for grid-connected and captive industrial supply. Southern Iraq grid expansion drives baseload fuel demand through 10-15 year term contracts displacing annual tenders.
- Industrial Feedstock:Process inputs for cement kilns, steel furnaces, and manufacturing heat requirements. Manufacturing sector procurement competes with subsidized power sector offtake during supply tightness.
Fuel supply holds the largest share; petrochemical production shows the steepest expansion trajectory as gas monetization infrastructure develops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basra Governorate commands premium pricing leverage over Missan Province due to supergiant field density and established export corridor access. Federal licensing terms amplify this asymmetry by concentrating cost-recovery guarantees in southern clusters while leaving northern development exposed to transit reliability discounts.
Basra Governorate
Rumaila and West Qurna field complexes drive service contract demand for waterflood infrastructure and enhanced recovery programs. The Ministry of Oil's revised technical service contract terms reduce payback periods for operators committing capital to these supergiant assets. Zubair and Majnoon sub-clusters anchor drilling contractor deployment as plateau production targets require accelerated well completion timelines.
Missan Province
Undrilled carbonate structures in southeastern blocks attract greenfield exploration licensing from international operators seeking lower recovery cost profiles. Federal petroleum regulator field development terms impose stricter gas capture mandates on new awards, redirecting capex toward integrated processing infrastructure. Halfaya and Bazerkan field clusters host pilot drilling programs testing extended-reach lateral designs for fractured reservoir access.
Kurdistan Region
Stranded production from northern fields faces persistent pipeline throughput constraints due to federal export quota disputes and transit fee negotiations. The regional petroleum authority's production sharing contract framework offers more favorable cost recovery terms than federal technical service contracts, attracting mid-cap operators. Taq Taq and Tawke field clusters await export normalization to unlock development capital frozen by revenue uncertainty.
Dhi Qar Governorate
Heavy oil deposits in the Gharraf and Nassiriya fields require specialized thermal recovery methods, concentrating service demand among enhanced oil recovery specialists. National environmental authority flaring reduction mandates impose compliance costs on operators lacking gas processing infrastructure. Subsurface characterization programs target carbonate formations with complex permeability profiles unsuited to conventional waterflood methods.
Anbar Governorate
Western desert exploration blocks hold undrilled structures with light crude potential, though security clearance delays extend seismic surveying timelines. Central bank foreign exchange regulations compress project IRR calculations for operators committing early exploration capital. Akkas gas field development remains stalled by infrastructure security concerns and pipeline routing disputes through contested territories.
Iraq Oil and Gas Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Iraqi petroleum services sector. The market structure fragments between integrated international operators with proprietary enhanced recovery platforms and specialized drilling contractors competing on day-rate efficiency. Three archetypes dominate: supermajor field service consortia anchoring supergiant development, national oil company engineering subsidiaries capturing brownfield rehabilitation scopes, and independent drilling specialists mobilizing for exploration wildcat programs. Competitive positioning hardens through strategic partnerships binding technology licensors to local service providers, while portfolio diversification into gas processing infrastructure accelerates among operators facing flaring compliance deadlines.
Among supermajor operators, BP and Lukoil exemplify the integrated field development archetype, leveraging long-tenured technical service contracts to sustain production plateau targets at Rumaila and West Qurna-2 respectively. PetroChina occupies a distinct position as a cost-efficient engineering procurement competitor, positioning its service subsidiaries for brownfield rehabilitation awards where capital discipline outweighs technology differentiation. These three anchors demonstrate how contract tenure and geographic origin shape competitive access to federal licensing rounds.
| Leading Market Players |
|---|
| ExxonMobil |
| BP |
| Lukoil |
| PetroChina |
| Chevron |
| Shell |
| Gazprom |
| Petronas |
| South Oil Company |
| Others |
Supply & Pricing Matrix
Ninety-day drilling equipment lead times from Houston to Basra anchor procurement cycles to marine freight schedules, concentrating pricing power with integrated service providers holding bonded inventory at Umm Qasr. This inventory positioning allows supermajor consortia to command premium day rates during rig mobilization surges, while smaller contractors absorb demurrage costs that compress margins on fixed-price rehabilitation scopes.
Pricing Analysis
The customization-premium spread separates standard technical service contracts from configured enhanced recovery packages. Project-based pricing dominates upstream awards, with differentiation driven by reservoir simulation depth and integrated gas capture bundling. Cost compression in brownfield rehabilitation intensifies as PetroChina engineering subsidiaries compete on lump-sum engineering procurement. State-owned power utilities show lowest price sensitivity under 10-15 year fuel offtake agreements, while independent drilling contractors face acute margin pressure on spot-market rig deployments.
Supply Chain Analysis
Inventory positioning for intelligent well completion systems runs through Dubai Jebel Ali free zones, with final-mile logistics tethered to Basra Governorate security corridors. Manufacturing concentrates in China, USA, and UAE for downhole pumps and surface processing skids. Raw material dependencies include high-grade steel alloy, specialized elastomers, and subsea control umbilicals. Single-source vulnerability persists for gas turbine power generation modules, with distribution flowing through South Oil Company terminal networks to Rumaila and West Qurna field clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Iraqi petroleum services market fragments across contract tenure tiers, with federal licensing reforms creating niches for specialized waterflood engineering firms and modular gas processing integrators previously excluded from supergiant field awards.
For Market Incumbents: Compound field development expertise through captive training programs addressing petroleum engineering talent scarcity, while securing exclusive technology licensing for zero-flaring compliance systems. Vertical integration into water treatment infrastructure offsets margin erosion from shortened technical service contract payback periods. Defend Rumaila and West Qurna positions by embedding reservoir simulation teams within Ministry of Oil planning divisions.
For New Entrants and Emerging Players: Brownfield automation retrofit services represent the most penetrable white-space, with West Qurna-2 pilot programs validating intelligent well completion demand without platform infrastructure. Missan Province greenfield exploration offers lower recovery cost profiles and less entrenched incumbent relationships. Target procurement officers at Halfaya and Bazerkan field clusters with extended-reach lateral drilling packages bundled with real-time monitoring subscriptions.
For Investors and Strategic Acquirers: Carve-out targets emerge from national oil company engineering subsidiaries seeking capital for gas monetization infrastructure compliance deadlines. Long-term viability hinges on operators' ability to pivot from oil-only production targets to integrated field development plans meeting 2030 flaring mandates. Watch Kurdistan Region export normalization negotiations as the signal for stranded production capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Recovery Technology Licensing | Waterflood and gas injection partnerships at Rumaila sustain plateau production against natural pressure decline. |
| Integrated Gas Capture Infrastructure | Associated gas processing investments satisfy Ministry of Oil zero-routine-flaring mandates by 2030. |
| Intelligent Well Completion Deployment | Downhole flow control systems at West Qurna-2 reduce wellhead intervention frequency and surface facility footprint. |
| Long-term Fuel Offtake Contracting | Basra power utilities secure 10-15 year supply agreements displacing annual tender volatility. |
| Petrochemical Feedstock Integration | Naphtha and NGL streams from Basra Governorate fields supply planned downstream chemical complexes. |
Research Methodology
The analysis maps exploration licensing rounds, production service contracts, refining capacity utilization, and transportation infrastructure, each validated through reservoir engineers, procurement officers at South Oil Company, drilling contractors, and Ministry of Oil regulatory staff. Primary fieldwork combined structured interviews with secondary validation against OPEC quota disclosures, federal budget petroleum revenue allocations, and Basra Governorate utility expansion announcements. Bottom-up project pipeline assessments triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including IEA Iraq energy outlooks, World Bank extractive industries data, and customs records for drilling equipment imports. Segmentation modeling incorporated service type, technology tier, end-user category, and application across the projection horizon. CAGRs derived from field-level production profiles, capital commitment timelines under revised technical service contracts, and infrastructure commissioning schedules for waterflood and gas processing assets.
Underlying assumptions cover federal licensing round participation rates, Kurdistan Region export corridor resolution, and central bank foreign exchange regulation stability, with deviation risk concentrated in OPEC quota compliance enforcement and security conditions across southern Iraq logistics corridors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Zonal Isolation Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Oil and Gas Seals Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Well Completion Market
Oil & Gas
Well Testing Services Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Canada LNG Bunkering Market