
 Heat Seal Pouch Market | 2026-2036
Heat Seal Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Seal Pouch Market Foresight
Buyer concentration in the pharmaceutical sector is decoupling from traditional food-service procurement patterns as biologics manufacturers fragment their supplier base across specialized pouch converters. Amcor Limited leverages its European pharmaceutical certification network to anchor high-barrier retort pouch supply for sterile medical devices. ProAmpac LLC specializes in multi-layer coextrusion formats that sustain shelf-life claims for temperature-sensitive drug delivery systems. Mondi Group dominates kraft-paper hybrid structures that navigate growing retailer pressure to reduce plastic dependency in European pharmacy chains.
Heat seal pouches are flexible packaging enclosures sealed through the application of controlled heat and pressure, typically constructed from laminated films with seal layers ranging between 15 and 150 microns to achieve hermetic integrity against moisture, oxygen, and light intrusion. Their primary commercial purpose centers on extending product shelf life while enabling unit-dose dispensing and tamper-evident closure for regulated consumer and medical goods. Stand-up pouches occupy the fastest-growing structural position as beverage and liquid detergent brands shift from rigid bottles to shelf-ready flexible formats with spout-integrated heat seal bases. Plastic composites lead material value pools due to their tunable barrier performance, though paper-based laminates are gaining share where EU Single-Use Plastics Directive compliance shapes retailer procurement specifications.
FDA 21 CFR Part 211 cGMP requirements and EU MDR Annex I general safety and performance standards directly shape validation protocols for medical-grade heat seal pouches, forcing converters to maintain batch-level seal-strength documentation and sterility assurance testing. REACH substance restrictions and evolving ECHA proposals on intentionally added microplastics further constrain adhesive and coating selections in multi-layer pouch constructions. Stakeholders must monitor how impending EU Packaging and Packaging Waste Regulation revisions redefine extended producer responsibility obligations for flexible formats across pharmaceutical and food supply chains.
Market Dynamics
EU pharmaceutical serialization mandates are fragmenting buyer-supplier relationships as biologics manufacturers bypass traditional food-service distributors to source directly from certified pouch converters with validated sterile barrier capabilities.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization requirements for tamper-evident packaging are pulling pharmaceutical manufacturers toward high-barrier pouch formats with integrated track-and-trace features.
- Temperature-sensitive biologics:Cell and gene therapy cold-chain logistics are demanding multi-layer coextrusion pouches with validated thermal protection across ultra-low temperature ranges.
- Germany:Contract packaging services for sterile medical devices are expanding fastest in this market, concentrating demand for retort-compatible barrier structures.
Market Restraints
- Ethylene-vinyl alcohol supply concentration:High-barrier film production depends on EVOH resin availability from a limited supplier base, creating input cost volatility for multi-layer laminate converters.
- REACH substance restrictions:ECHA proposals on intentionally added microplastics are constraining adhesive and coating selections, extending R&D timelines for new pouch constructions.
- Rigid bottle substitution:Beverage and household chemical brands retain legacy bottling infrastructure, slowing flexible format penetration in high-volume liquid categories.
Strategic Opportunities
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility revisions will create first-mover advantage for converters offering recyclable mono-material laminates with validated pharmaceutical performance.
- Kraft-paper hybrid structures:Retailer pressure to reduce plastic dependency in European pharmacy chains is opening share for fiber-based barrier pouches with heat-sealable bio-polymer windows.
- Spout-integrated stand-up formats:Liquid detergent and nutritional supplement brands are shifting from rigid containers to shelf-ready flexible pouches with precision-dispensing closures.
Industry Challenges
- Batch-level seal-strength documentation:FDA 21 CFR Part 211 cGMP requirements demand continuous validation infrastructure that strains mid-cap converters with legacy quality systems.
- Sterility assurance testing capacity:ISO 11607 compliance for medical-grade pouches requires specialized cleanroom facilities and trained personnel that concentrate in limited geographic clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Seal Pouch Market |
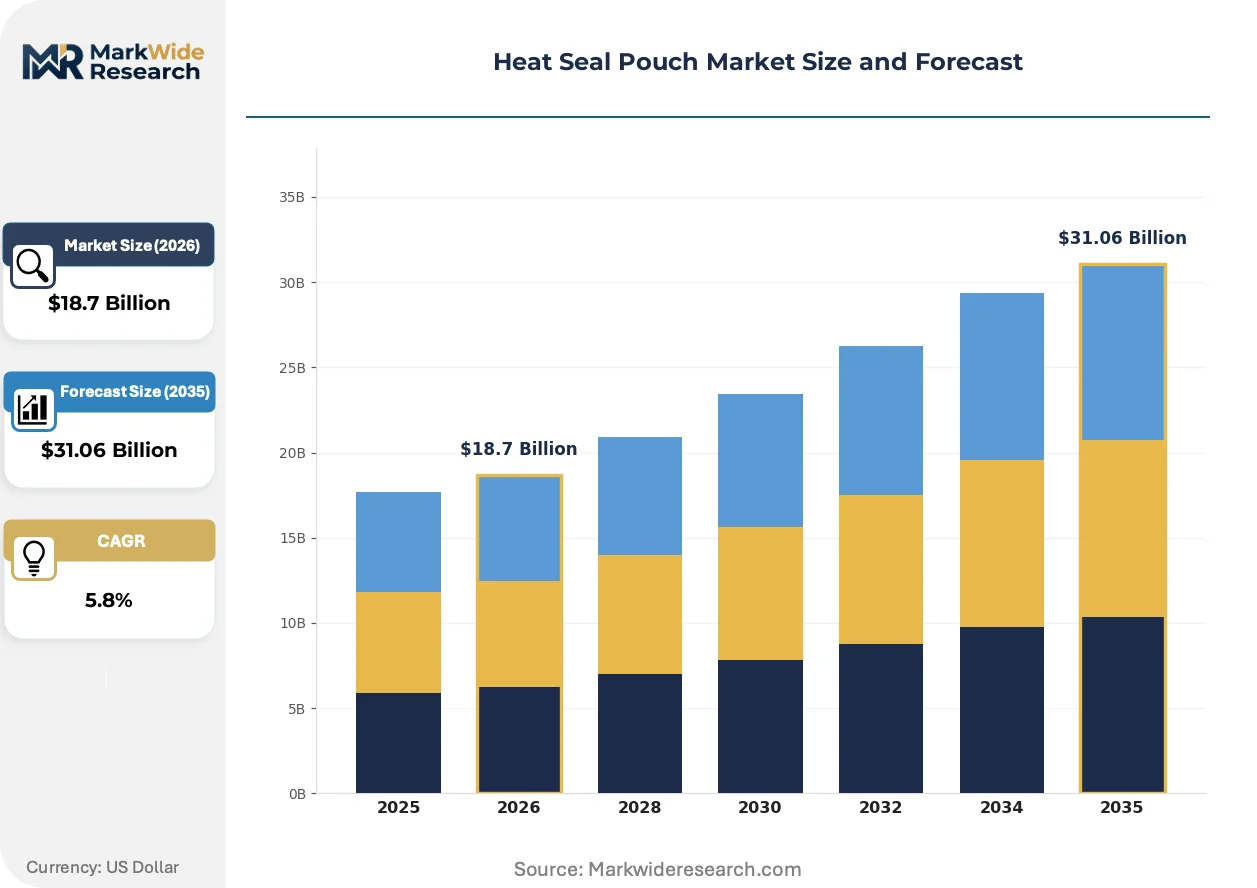
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Gusseted Pouches, Stand-Up Pouches, Retort Pouches Material: Plastic, Aluminum, Paper, Composites Application: Food Packaging, Medical Supplies, Personal Care, Household Products Closure Type: Ziplock, Tear Notch, Heat Seal, Others |
| Companies Covered | Mondi Group, ProAmpac LLC, Amcor Limited, Constantia Flexibles Group GmbH, Huhtamaki Group, Sealed Air Corporation, Sonoco Products Company, Coveris Holdings S.A., Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Seal Pouch Market Shifts & Advancements
Active barrier technologies and mono-material design principles are compressing traditional multi-layer laminate architectures while regulatory pressure on recyclability accelerates format experimentation across pharmaceutical and food-contact applications.
High-barrier mono-material polyethylene structures are unifying seal integrity with post-consumer recyclability by replacing EVOH and aluminum foil layers with advanced plasma-deposited silicon oxide coatings. Pharmaceutical contract packagers in Germany and the Netherlands are piloting these formats for non-sterile solid-dose applications. The technology is unifying previously incompatible performance requirements—moisture barrier, oxygen exclusion, and mechanical durability—within single-resin systems that satisfy emerging extended producer responsibility frameworks.
REACH Article 33 disclosure obligations and evolving ECHA restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer-based grease barriers from food-contact pouch constructions. Converters must reformulate heat-seal layers with bio-based waxes and mineral coatings to maintain performance. European pharmacy chains and ready-meal brands are most affected, with procurement specifications now mandating PFAS-free certifications that disqualify legacy laminate inventories.
Biologics manufacturers are consolidating supplier relationships around converters with integrated sterile barrier validation and cold-chain qualification capabilities. Small-molecule pharmaceutical procurement teams previously fragmented orders across commodity pouch vendors. The shift compresses vendor counts to three-to-five strategic partners per therapeutic area. This pattern is most visible in Germany's contract packaging corridor, where temperature-sensitive drug delivery systems require documented thermal protection across distribution networks.
Heat Seal Pouch Market Segmentation
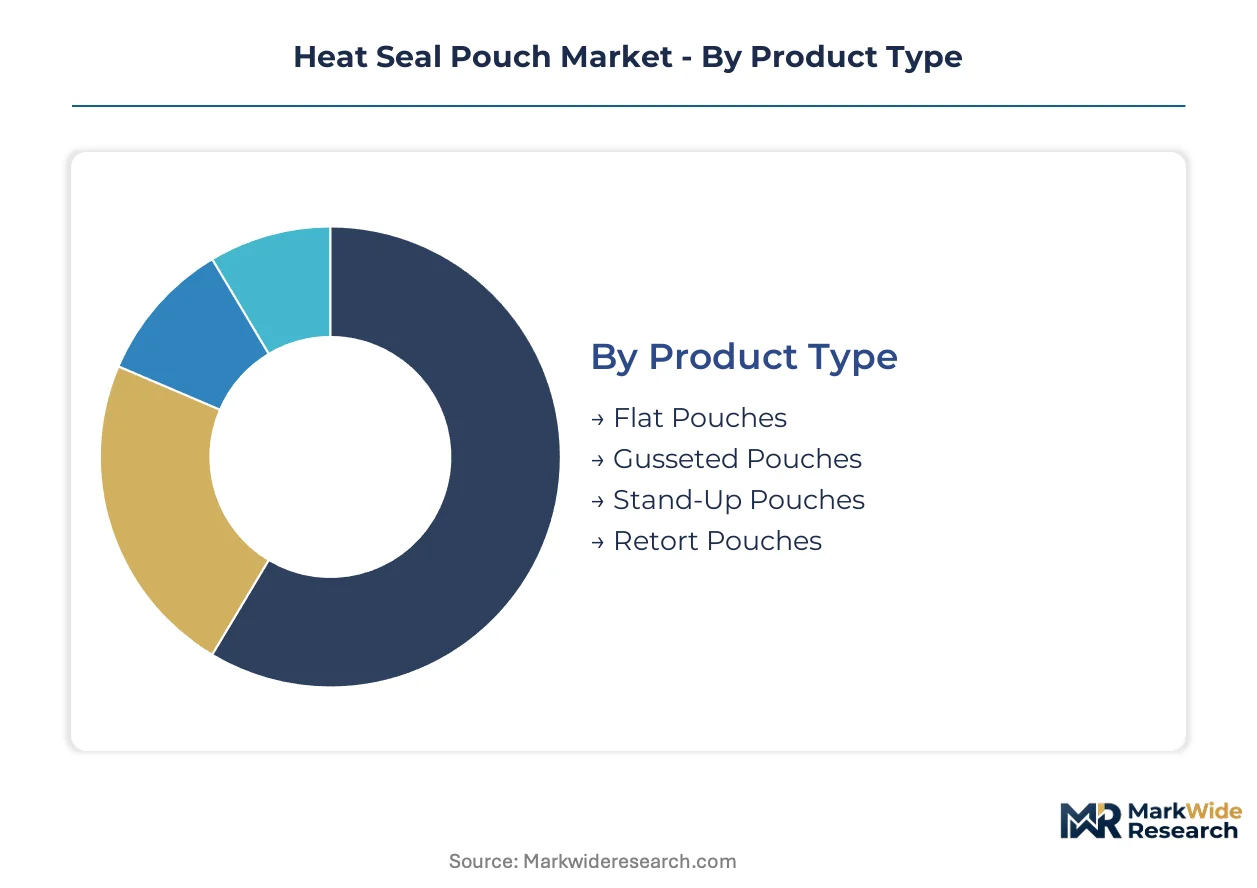
Heat seal pouch segmentation reveals divergent margin profiles across structural formats and barrier technologies. Product type and material composition determine converter capabilities and regulatory compliance pathways.
Product Type:
Volume concentrates in commodity flat formats while premium value pools shift toward specialized barrier structures with validated sterile performance.
- Flat Pouches:Two-dimensional sealed envelopes constructed from single or multi-layer films with seal widths typically between 10 and 50 millimeters. Pharmaceutical solid-dose packaging in Germany and the Netherlands consumes the highest volumes as contract packagers prioritize cost-efficient unit-dose formats for serialization compliance.
- Stand-Up Pouches:Self-supporting flexible containers with heat-sealed base gussets enabling vertical shelf display. Liquid detergent and nutritional supplement brands in France and Italy are displacing rigid bottles fastest, driven by retailer shelf-space optimization mandates and EU Single-Use Plastics Directive pressure.
- Gusseted Pouches:Side- or bottom-folded expansions increasing volumetric capacity without rigid structure. Coffee and dried food producers favor these formats for bulk retail presentation.
- Retort Pouches:Multi-layer laminates with aluminum foil or high-barrier coextrusion sustaining sterilization temperatures above 121 degrees Celsius. Ready-meal and military ration applications dominate demand.
Today's leader: Flat Pouches. Tomorrow's challenger: Stand-Up Pouches.
Material:
Barrier performance requirements and recyclability mandates are fragmenting procurement specifications across pharmaceutical and food-contact applications.
- Plastic:Polyethylene, polypropylene, and polyester films dominate through tunable seal-layer chemistry and coextrusion versatility. Temperature-sensitive biologics cold-chain logistics in Germany are pulling demand toward multi-layer coextrusion with EVOH oxygen barriers.
- Composites:Hybrid laminates uniting plastic films with aluminum foil or metallized layers for maximum barrier integrity. Sterile medical device packaging under EU MDR Annex I requirements concentrates demand here.
- Paper:Fiber-based substrates with heat-sealable bio-polymer windows or wax coatings. European pharmacy chains facing plastic reduction targets are piloting these formats for over-the-counter solid doses.
- Aluminum:Pure foil or metallized film layers providing absolute light and oxygen exclusion. High-value pharmaceutical and specialty food applications retain this material despite cost premiums.
Plastics command current volume. Composites defend premium positioning. Paper formats are climbing fastest under regulatory pressure.
Application:
End-use concentration patterns diverge sharply between regulated medical channels and price-sensitive consumer goods.
- Food Packaging:The largest consumption category spanning ready-meals, snacks, and beverages. Retort and high-barrier formats serve shelf-stable prepared foods.
- Medical Supplies:Sterile barrier pouches for devices and pharmaceutical unit-dose formats. EU Falsified Medicines Directive serialization requirements are accelerating tamper-evident pouch specifications fastest here.
- Personal Care:Single-use sachets and sample formats for cosmetics and hygiene products. Convenience positioning drives format experimentation.
- Household Products:Concentrated detergents and cleaning chemicals migrating from rigid bottles to flexible refill pouches.
Medical Supplies segment is expanding most quickly on regulatory tailwinds. Food Packaging retains volume leadership.
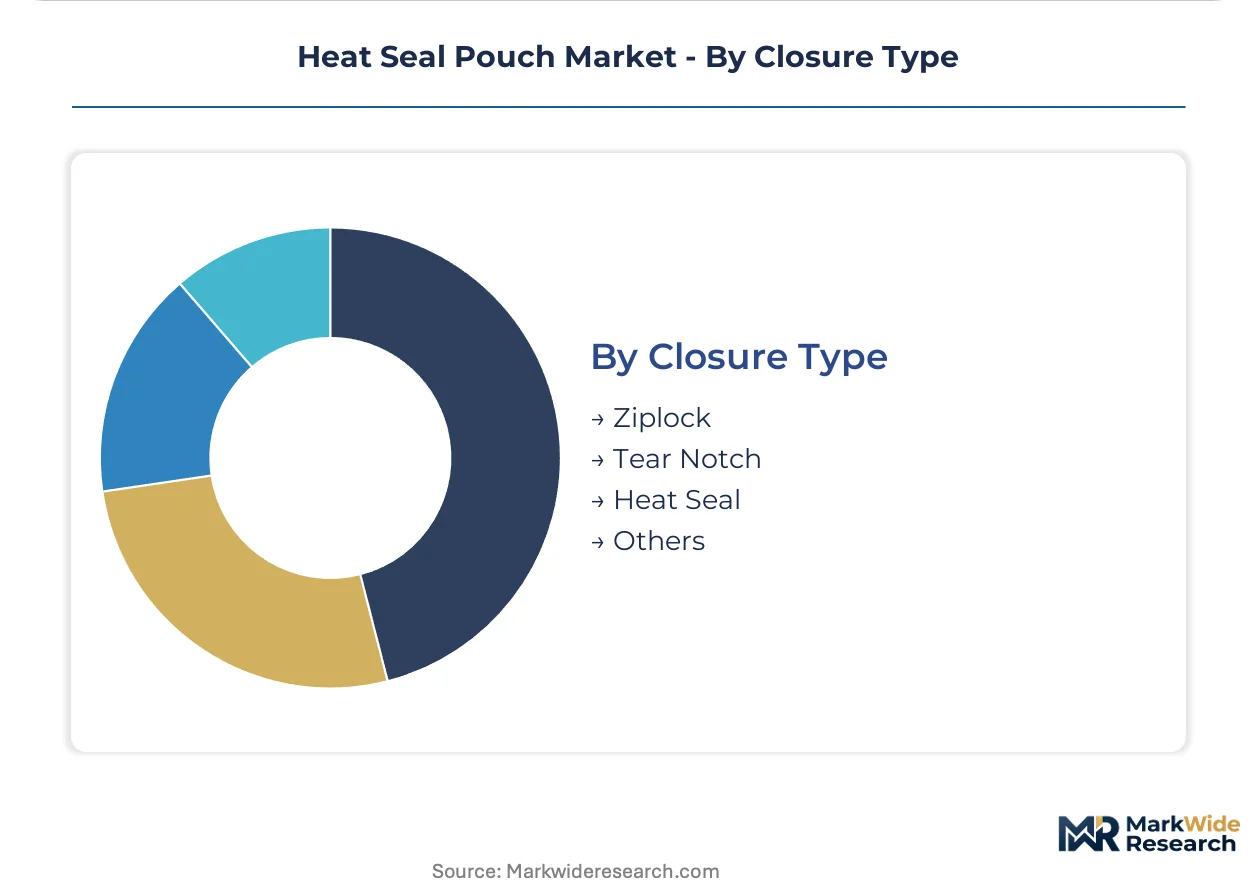
Closure Type:
Resealability functionality separates premium consumer formats from single-use medical and food applications.
- Heat Seal:Permanent hermetic closure through controlled temperature and pressure application. Medical and pharmaceutical sterile barriers require this format exclusively under FDA 21 CFR Part 211 cGMP protocols.
- Ziplock:Interlocking plastic profiles enabling repeated opening and closing. Snack foods and household refills favor this convenience feature.
- Tear Notch:Pre-scored initiation points for clean manual opening without tools. Unit-dose pharmaceutical and food service portions use this economical option.
- Others:Spout-integrated closures, laser scoring, and child-resistant mechanisms for specialized applications.
Heat Seal dominates regulated channels. Ziplock formats are gaining share fastest in consumer goods resealability race.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pharmaceutical pouch demand acceleration while the United States anchors food-service format volume, creating divergent regional specialization patterns across the forecast window.
Germany
Temperature-sensitive biologics cold-chain logistics and contract packaging services for sterile medical devices are pulling demand toward multi-layer coextrusion formats. EU MDR Annex I general safety and performance standards mandate batch-level documentation that concentrates converter activity in certified facilities. The Rhine-Main corridor hosts expanding cleanroom capacity for retort-compatible barrier structures serving pan-European pharmaceutical distribution.
United States
FDA 21 CFR Part 211 cGMP requirements for sterile barrier validation are fragmenting supplier relationships as medical device manufacturers consolidate around documented quality systems. Serialization mandates under the Drug Supply Chain Security Act are accelerating tamper-evident pouch specifications for unit-dose pharmaceuticals. The Midwest industrial belt maintains dense converter clustering for high-volume food-service flat pouch production.
China
Domestic pharmaceutical packaging upgrade programs and export-oriented medical device manufacturing are expanding demand for barrier laminates with validated seal integrity. NMPA Good Manufacturing Practice for Pharmaceutical Products revisions are elevating documentation requirements for sterile packaging materials. The Yangtze River Delta concentration of contract manufacturers is absorbing new domestic capacity for EVOH-based high-barrier films.
France
Retailer shelf-space optimization mandates and EU Single-Use Plastics Directive compliance pressure are displacing rigid bottles with stand-up pouch formats for liquid detergents and nutritional supplements. ANSM pharmaceutical packaging guidelines reinforce tamper-evident requirements for over-the-counter solid doses. The Lyon-Grenoble corridor hosts specialized converters piloting kraft-paper hybrid structures for pharmacy chain plastic reduction programs.
Netherlands
Pharmaceutical contract packaging services for serialization-compliant unit-dose formats are expanding fastest in the Benelux distribution hub. REACH Article 33 disclosure obligations are constraining adhesive selections in multi-layer laminates destined for European pharmacy chains. The Rotterdam-Antwerp logistics corridor concentrates cold-chain qualified pouch converters serving biologics manufacturers with documented thermal protection protocols.
Heat Seal Pouch Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between scale-driven integrated film producers, mid-cap converters with regional certification networks, and niche sterile barrier specialists with cleanroom assets. Three archetypes dominate: multinational packaging conglomerates with pharmaceutical certification breadth, regional converters with flexible coextrusion capabilities, and sterile barrier specialists with ISO 11607 validation infrastructure. Competitive moves concentrate on M&A for certification acquisition and capacity expansion in temperature-sensitive logistics corridors.
Among European-based diversified packaging groups, Mondi Group, Amcor Limited, and Constantia Flexibles Group GmbH occupy positions that exemplify scale-driven archetypes with cross-regional certification networks. Mondi Group represents the fiber-based barrier pivot as pharmacy chains impose plastic reduction targets. Amcor Limited anchors high-barrier retort supply for sterile medical devices through pharmaceutical certification density. Constantia Flexibles Group GmbH sits within the mid-cap converter tier with flexible coextrusion capabilities serving fragmented biologics procurement patterns.
| Leading Market Players |
|---|
| Mondi Group |
| ProAmpac LLC |
| Amcor Limited |
| Constantia Flexibles Group GmbH |
| Huhtamaki Group |
| Sealed Air Corporation |
| Sonoco Products Company |
| Coveris Holdings S.A. |
| Berry Global Inc. |
| Others |
Supply & Pricing Matrix
EVOH resin costs transmit directly from upstream petrochemical complexes through multi-layer laminate converters to pharmaceutical contract packagers, with Germany's Rhine-Main corridor absorbing the steepest input volatility as sterile barrier validation requirements lock buyers into certified supplier relationships.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for commodity flat pouches while European sterile barrier specialists maintain premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects certification density under FDA 21 CFR Part 211 and EU MDR Annex I standards. Cost compression in standard tiers intensifies because mid-cap converters compete for fragmented biologics procurement. Pharmaceutical solid-dose packagers show highest price sensitivity; sterile medical device manufacturers accept premium tiers for documented batch-level seal-strength validation.
Supply Chain Analysis
Cleanroom technician availability in Germany, the Netherlands, and China's Jiangsu province constrains sterile barrier capacity expansion. Raw material flows draw from Saudi ethylene crackers, Japanese EVOH polymerization, and Belgian adhesive formulators. Single-source vulnerability concentrates in high-barrier coextrusion equipment from Austrian and German machinery builders. Distribution runs through Rotterdam-Antwerp pharmaceutical logistics hubs serving pan-European cold-chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Demand for tamper-evident serialization-compliant pouches under EU Falsified Medicines Directive mandates elevates specification premiums across pharmaceutical channels.
For Market Incumbents: Anchor sterile barrier validation capabilities against emerging mono-material specialists by deepening certification density under ISO 11607. Expand cleanroom capacity in Germany's contract packaging corridor to capture biologics cold-chain consolidation. Defend margin position through backward integration into EVOH-based coextrusion film production, reducing exposure to resin supply concentration. For New Entrants and Emerging Players: The gap between premium sterile barrier pricing and economy flat pouch commoditization offers entry space. Target kraft-paper hybrid formats for European pharmacy chain plastic reduction programs, where retailer procurement specifications lag certified supplier availability. Pursue direct relationships with French and Italian liquid detergent brands shifting from rigid bottles to stand-up pouch formats. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap converters with regional pharmaceutical certification networks because buyer consolidation around three-to-five strategic partners per therapeutic area creates scale premiums. Focus on targets with EU MDR Annex I validation infrastructure and established cold-chain qualification protocols. Watch ECHA microplastics restriction timelines as inflection indicator for adhesive reformulation R&D burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Laminate Development | Recyclable polyethylene structures with silicon oxide coatings satisfy EU Packaging and Packaging Waste Regulation extended producer responsibility frameworks. |
| Sterile Barrier Cleanroom Expansion | ISO 14644 Class 7 facilities in Germany's Rhine-Main corridor capture biologics contract packaging demand from temperature-sensitive drug delivery systems. |
| PFAS-Free Adhesive Reformulation | Bio-based wax and mineral coating substitutions maintain heat-seal performance under REACH Article 33 disclosure obligations for European pharmacy chains. |
| Spout-Integrated Stand-Up Format Launch | Precision-dispensing closures displace rigid bottles for liquid detergents under France's retailer shelf-space optimization mandates. |
| Pharmaceutical Serialization Integration | Track-and-trace feature embedding aligns with EU Falsified Medicines Directive tamper-evident packaging requirements for unit-dose solid formats. |
Research Methodology
Direct dialogue with pharmaceutical packaging procurement managers, sterile barrier validation engineers, contract manufacturing executives, and EU regulatory affairs specialists grounded qualitative findings. Secondary validation drew from EMA packaging guidelines, FDA 21 CFR Part 211 inspection observations, REACH Article 33 substance disclosures, and ECHA microplastics restriction proposals. Bottom-up segment sizing triangulated against top-down pharmaceutical packaging expenditure estimates.
Segment-level demand projections across product type, material composition, application, and closure configuration fed into analytical framework spanning the projection horizon. CAGRs derived from regression analysis against pharmaceutical serialization mandate implementation schedules and cold-chain logistics expansion curves. Modeled inputs included EVOH resin price trajectories, cleanroom capacity buildout pipelines, and retailer plastic reduction target compliance deadlines.
Caveats apply where ECHA microplastics restriction finalization, EU Packaging and Packaging Waste Regulation extended producer responsibility implementation, or EVOH supply disruption could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Europe Retort Pouches Market
Pouch
Inflatable Pouches Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Kraft Pouch Market
Pouch
Latin America Pouch Packaging Market
Pouch
Poland Pouch Packaging Market
Pouch
Pouch-Bowl Packaging Market
Pouch
Twist Wrap Packaging Market
Pouch
Foil Zipper Bags Market
Pouch
MAP Flow Wrappers Market
Pouch
Mexico Pouch Packaging Market
Pouch
Stand Up Paper Pouches Market
Pouch
Box Pouch Market
Pouch
Peelable Pouches Market
Pouch
Feminine Care Pouch Film Market