
 Open Mouth Sacks Market | 2026-2036
Open Mouth Sacks Market Size, Share, and Industry Trends Forecast 2026-2036
Open Mouth Sacks Market Analytics
A shift from single-source to multi-source woven fabric supply is restructuring procurement economics for sack converters. Mondi Group leverages integrated pulp-to-paper operations to secure kraft linerboard supply for open mouth paper sacks. Hood Packaging anchors North American capacity with regional extrusion and conversion assets. Starlinger specializes in circular weaving and extrusion lines that equipment buyers deploy to bring film and fabric production in-house.
Open mouth sacks are industrial packaging containers with a pre-formed filling aperture, typically constructed from multi-ply kraft paper or woven polypropylene flat fabric, designed for gravity or pneumatic filling of dry bulk solids. Paper grades range from 70 to 100 grams per square meter with optional PE moisture barriers, while woven polypropylene uses 600-1200 denier tape yarns in 10×10 to 14×14 mesh counts for tensile loads exceeding 50 kilograms. Woven polypropylene leads material type volume due to its dominance in 50 kg agricultural and chemical loads, though paper variants command premium positioning in food-grade applications requiring heat-sealed or sewn closure integrity. Closure method selection tracks end use risk thresholds, with adhesive sealed and heat sealed formats displacing traditional sewn closures in moisture-sensitive food and chemical segments.
REACH and the EU Packaging and Packaging Waste Regulation govern material composition and extended producer responsibility across Europe, while FDA food contact regulations and OSHA dust exposure standards shape product specifications and workplace handling requirements in the United States. These frameworks elevate compliance costs for multi-layer laminates but create market access advantages for converters with certified recyclable or compostable mono-material constructions. Stakeholders must monitor evolving extended producer responsibility fee structures and recyclability assessment protocols to align capacity investments with regulatory cost trajectories.
Market Dynamics
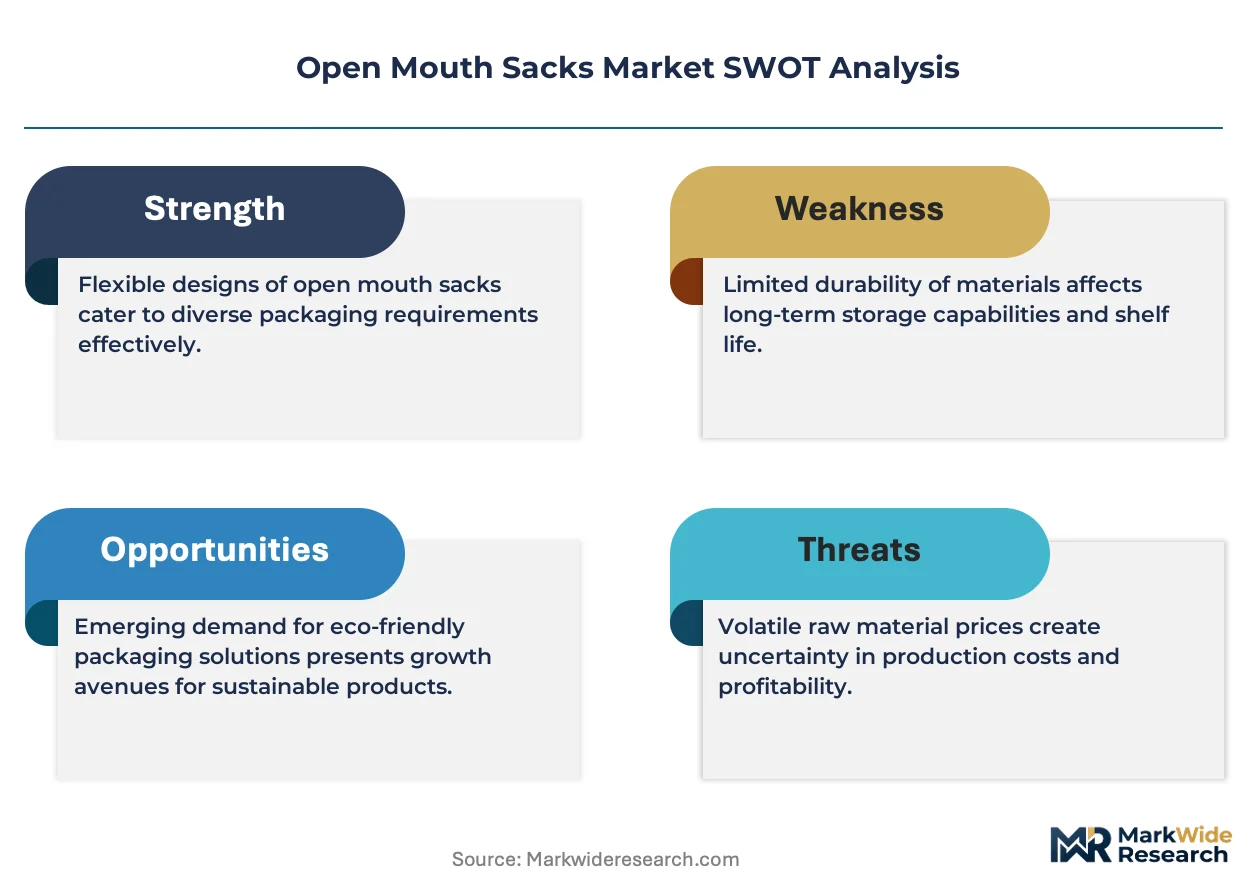
The EU Packaging and Packaging Waste Regulation is forcing sack converters to reengineer multi-layer laminates into certified recyclable mono-material constructions, compressing margins for non-compliant suppliers while creating first-mover advantages for certified producers.
Growth Catalysts
- REACH material compliance:European converters achieving ECHA-registered mono-polyethylene constructions gain preferential access to EU agricultural tenders.
- India Food Corporation procurement:Centralized wheat and rice distribution through FCI mandates woven polypropylene sacks at volumes exceeding 50 kilogram unit loads.
- Pneumatic filling automation:Chemical processors deploy gravity-fed open mouth systems to replace manual bulk loading, cutting labor exposure to dust hazards under OSHA standards.
Market Restraints
- Kraft pulp price volatility:Paper sack converters face margin compression when integrated pulp suppliers prioritize linerboard for corrugated over sack-grade kraft.
- Woven fabric supply concentration:Tape yarn extrusion capacity clusters in East Asian manufacturing zones, exposing buyers to freight cost spikes and currency fluctuation.
- Multi-layer laminate recyclability:Current adhesive lamination between paper and polyethylene layers fails EU harmonized recyclability assessment protocols.
Strategic Opportunities
- Brazil agricultural expansion:Soybean and corn export growth creates demand for 50 kilogram woven polypropylene sacks with UV stabilization for tropical storage.
- Heat-sealed closure adoption:Moisture-sensitive food-grade segments replace sewn closures with ultrasonic welding, enabling hermetic barrier integrity.
- Digital print integration:Inline flexographic and inkjet systems allow batch-specific branding without plate changeover, compressing minimum order quantities.
Industry Challenges
- Mono-material certification timelines:Third-party recyclability verification under EU harmonized protocols extends product development cycles by 8-14 months.
- Circular weaving technician scarcity:Starlinger equipment operation requires specialized training that regional vocational programs have not scaled to match installation rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Open Mouth Sacks Market |
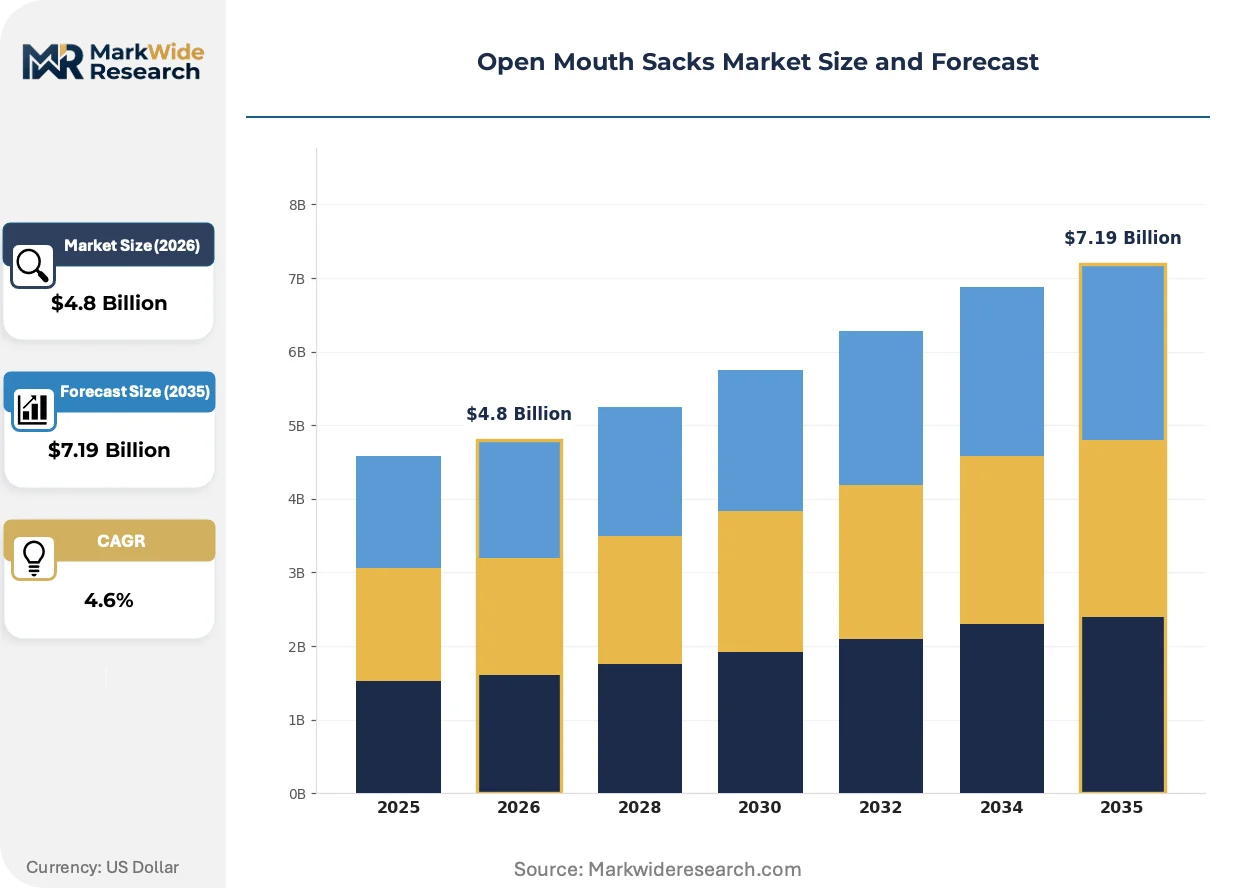
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Paper, Woven Polypropylene, Multi-layer Closure Method: Sewn, Adhesive Sealed, Heat Sealed, Tied End Use: Agriculture, Food, Chemicals, Construction Size: 5 kg, 10 kg, 25 kg, 50 kg |
| Companies Covered | Mondi Group, Hood Packaging, Ailu Group, Hamer-Fischbein, Starlinger, El Dorado Packaging, Endpak, Langston Companies, Berry Global, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Open Mouth Sacks Market Evolving Landscape
Material science advances and regulatory stringency are converging to redefine sack construction specifications, with automation and traceability becoming baseline procurement criteria rather than premium differentiators.
Mono-polyethylene woven constructions are absorbing market share from multi-layer paper-PE laminates in moisture-critical chemical and food applications. Fertilizer blenders and salt processors adopt these structures to preempt EU extended producer responsibility fees. The technology is absorbing compliance cost burdens that would otherwise fall on converters using legacy adhesive-laminated formats.
REACH substance restrictions and the EU Packaging and Packaging Waste Regulation are tightening permissible additive chemistries in sack films and coatings. Converters must reformulate slip agents and UV stabilizers to maintain ECHA registration compliance. Agricultural grain distributors in Germany and France face the strictest enforcement, driving rapid qualification of alternative additive packages.
Buyer consolidation among multinational grain traders is compressing supplier qualification timelines. Archer Daniels Midland and Cargill now mandate ISO 22000 food safety certification and batch-level QR traceability as table stakes for contract eligibility. This concentration is most pronounced in Black Sea wheat export corridors, where three traders control over sixty percent of origination volume.
Open Mouth Sacks Market Segmentation
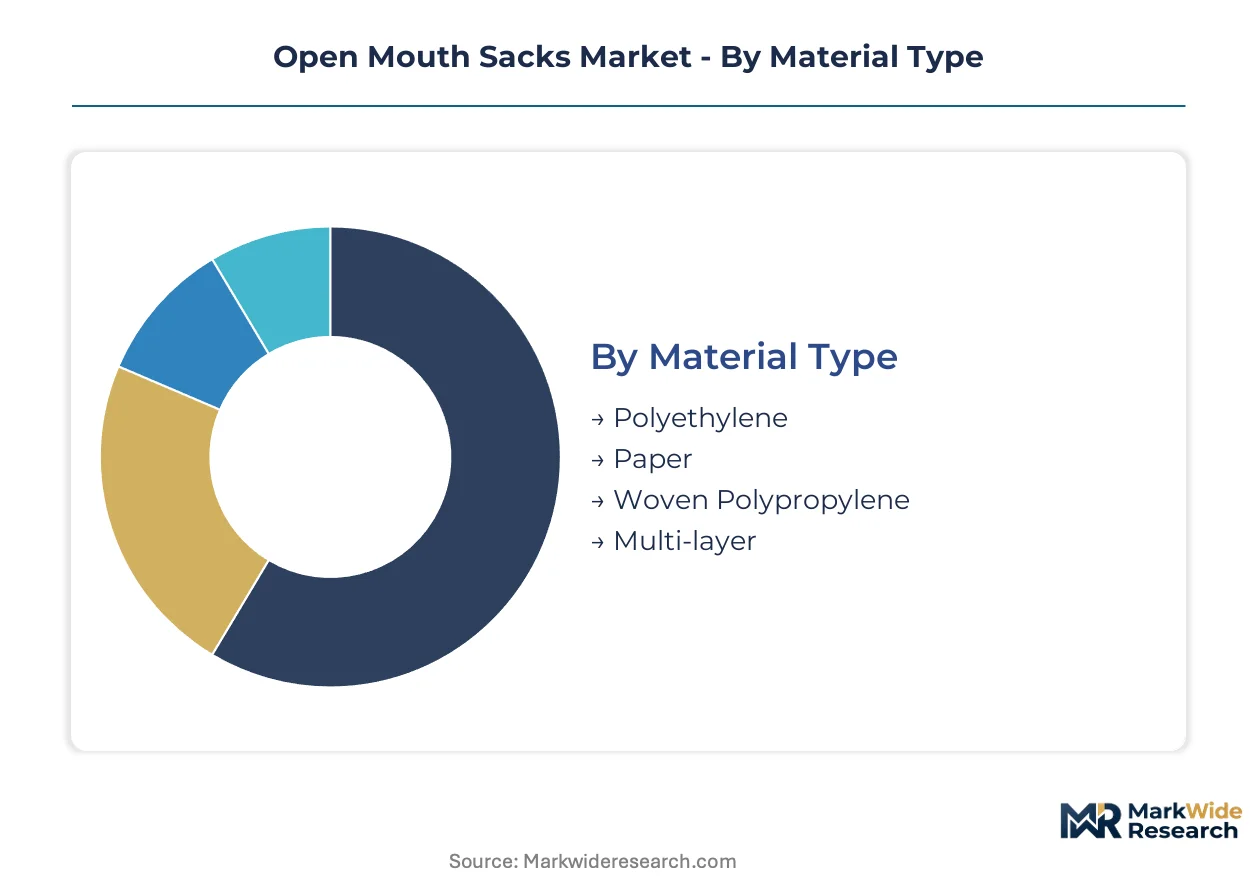
Material selection and closure integrity determine unit economics across agricultural, chemical, and food-grade applications. Procurement committees weigh moisture barrier performance against EU recyclability mandates when specifying sack constructions for bulk dry solids transport.
Material Type:
Buyers prioritize tensile strength specifications and regulatory compliance cost when selecting base substrates for 50-kilogram agricultural loads.
- Woven Polypropylene:Tape yarn constructions using 600-1200 denier fibers deliver tensile loads exceeding 50 kilograms. The Food Corporation of India procures millions of units for wheat and rice distribution, prioritizing UV stabilization for tropical storage conditions.
- Paper:Multi-ply kraft constructions range from 70 to 100 grams per square meter with optional PE moisture barriers. Food-grade applications in Germany and France command premium positioning where heat-sealed closure integrity satisfies EFSA contact material requirements.
- Polyethylene:Mono-material films absorb compliance cost burdens from EU extended producer responsibility frameworks. Fertilizer blenders adopt these structures to preempt regulatory fees.
- Multi-layer:Adhesive-laminated paper-PE constructions face margin compression under REACH substance restrictions and recyclability assessment protocol failures.
Volume sits with woven polypropylene; growth tilts toward mono-polyethylene certified recyclable formats.
Closure Method:
Moisture sensitivity thresholds and automation compatibility drive specification divergence across chemical and food processing segments.
- Heat Sealed:Ultrasonic welding enables hermetic barrier integrity for moisture-sensitive salt and fertilizer applications. Chemical processors deploy these formats with pneumatic filling automation to cut OSHA dust exposure hazards.
- Adhesive Sealed:Pressure-sensitive tape closures displace sewn formats in mid-tier chemical packaging where line speed exceeds 30 units per minute.
- Sewn:Traditional stitched closures retain cost advantage in construction aggregates and low-value agricultural commodities with minimal moisture risk.
- Tied:Manual twist-tie formats persist in artisanal food and specialty chemical niches requiring tool-free opening.
Adoption curves favor heat-sealed and adhesive-sealed formats; sewn closures defend share in price-sensitive bulk commodities.
End Use:
Regulatory stringency and batch traceability requirements fragment procurement specifications across downstream industries.
- Agriculture:Grain distributors specify woven polypropylene for 50-kilogram wheat and rice unit loads. Black Sea export corridors demand ISO 22000 certification and QR traceability as baseline contract eligibility.
- Chemicals:Fertilizer and salt processors prioritize mono-polyethylene moisture barriers. REACH-compliant additive packages for slip agents and UV stabilizers dominate German and French qualification timelines.
- Food:Heat-sealed paper sacks with EFSA-registered coatings serve premium positioning. Archer Daniels Midland mandates batch-level digital traceability for supplier qualification.
- Construction:Cement and aggregates tolerate sewn-closure woven polypropylene with minimal barrier specifications. Price sensitivity limits adoption of advanced sealing technologies.
Agriculture anchors procurement volume; chemicals and food segments climb fastest on regulatory compliance premiums.
Size:
Unit load optimization and manual handling ergonomics determine format selection across retail and industrial channels.
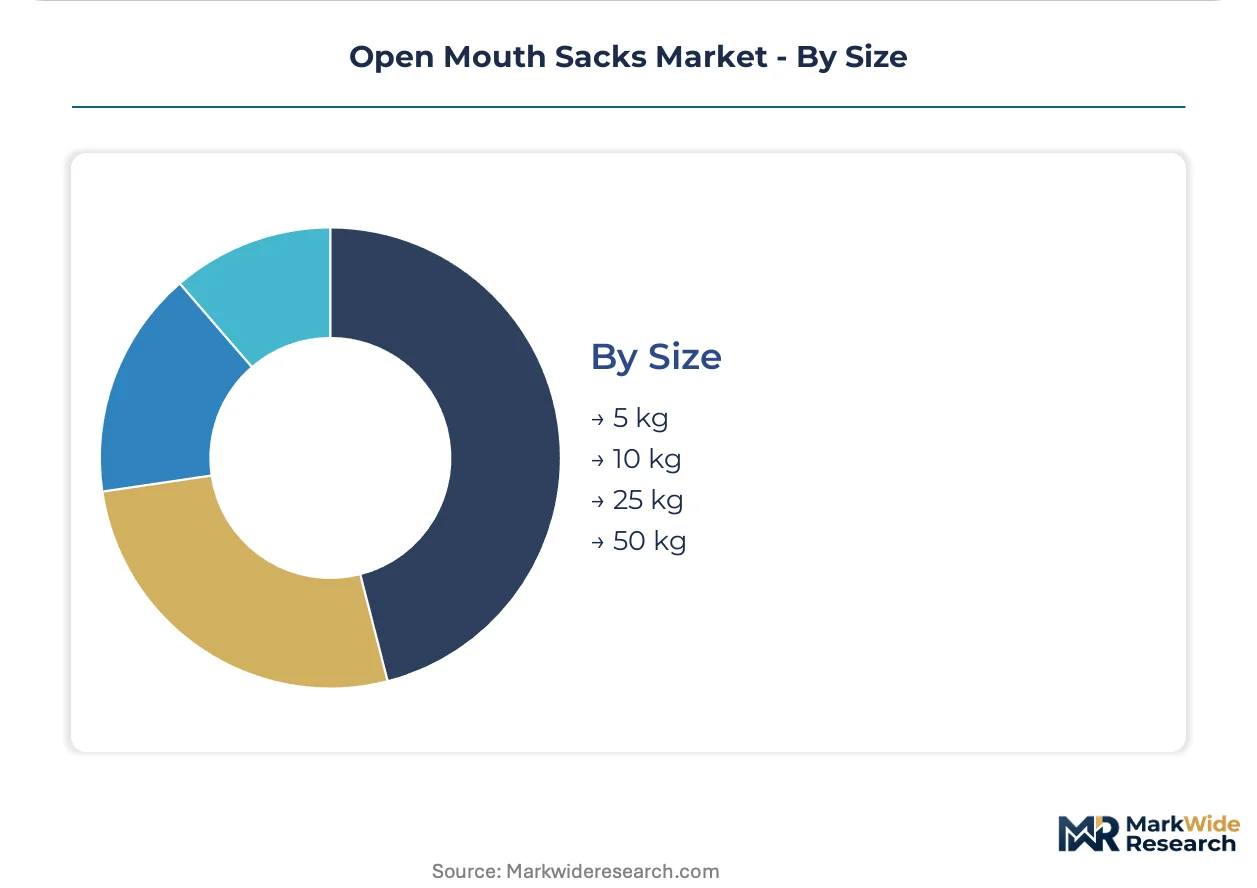
- 50 kg:Standard agricultural and chemical bulk format. Brazil soybean exporters specify UV-stabilized woven polypropylene for tropical storage.
- 25 kg:Mid-tier industrial and retail-ready construction materials. European DIY channels favor this format for cement and mortar premixes.
- 10 kg:Specialty fertilizer and seed packaging for precision agriculture. Indian state agricultural extension programs distribute subsidized inputs in this format.
- 5 kg:Premium food-grade and artisanal chemical segments. Digital print integration enables batch-specific branding without plate changeover.
50 kg dominates tonnage throughput; 25 kg and below expand on retail channel penetration and ergonomic handling mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene tape yarn extrusion clusters in East Asia feed sack conversion plants across India, Germany, Brazil, and the United States. These five markets anchor regional demand through distinct regulatory and procurement frameworks.
India
The Food Corporation of India procures woven polypropylene sacks for wheat and rice distribution exceeding 50-kilogram unit loads. FSSAI food contact regulations govern coating chemistries for grain packaging. Conversion capacity concentrates in Gujarat and Maharashtra, where state agricultural extension programs distribute subsidized inputs in 10-kilogram formats.
Germany
Fertilizer blenders and salt processors drive specification toward mono-polyethylene moisture barriers. REACH substance restrictions force reformulation of slip agents and UV stabilizers to maintain ECHA registration compliance. Industrial packaging converters in North Rhine-Westphalia and Bavaria deploy ultrasonic welding systems for hermetic closure integrity.
Brazil
Soybean and corn export growth creates demand for UV-stabilized woven polypropylene sacks rated for tropical storage conditions. ANVISA oversees additive compliance for agricultural chemical packaging. São Paulo and Rio Grande do Sul host extrusion and conversion assets serving Mercosur grain corridors.
United States
Archer Daniels Midland and Cargill mandate ISO 22000 certification and batch-level QR traceability for supplier qualification. FDA food contact regulations and OSHA dust exposure standards shape workplace handling requirements. Hood Packaging anchors North American capacity with regional extrusion assets in the Midwest and Southeast.
China
Integrated pulp-to-paper operations secure kraft linerboard supply for open mouth paper sack exports. GB standards and MIIT industrial policy guide mono-material recyclability investments. Yangtze River Delta and Pearl River Delta clusters house circular weaving equipment deployment for in-house film and fabric production.
Open Mouth Sacks Market Competitive Landscape
Capacity expansion dominates the current landscape as converters retrofit lines for mono-material certification. The vendor base stratifies across integrated pulp-to-paper operators, regional extrusion specialists, and equipment technology providers. Three archetypes define positioning: backward-integrated fiber suppliers, geographic-focused fabricators, and circular weaving technology licensors. M&A activity and strategic partnerships concentrate among mid-cap converters seeking ECHA-registered product portfolios.
Within the integrated fiber tier, Mondi Group exemplifies captive supply chain control over kraft linerboard for paper sack construction. Hood Packaging occupies a position among North American regional fabricators with distributed extrusion assets. Starlinger represents the equipment-specialist archetype, licensing circular weaving and extrusion lines that enable buyers to bring film and fabric production in-house. These three anchors illustrate divergent strategic paths: fiber integration, geographic density, and technology enablement.
| Leading Market Players |
|---|
| Mondi Group |
| Hood Packaging |
| Ailu Group |
| Hamer-Fischbein |
| Starlinger |
| El Dorado Packaging |
| Endpak |
| Langston Companies |
| Berry Global, Inc. |
| Others |
Value Network & Pricing Analysis
Kraft pulp cost volatility cascades through three pricing tiers for open mouth sacks, with integrated linerboard producers commanding premium positioning while regional converters absorb margin compression from spot-market fiber purchases.
Pricing Analysis
Warranty-backed batch certification separates premium-tier suppliers from unbundled commodity sellers. Three-tier pricing structure across premium, standard, and economy levels tracks ECHA registration status, with REACH-compliant mono-material constructions capturing 15-20% uplift over adhesive-laminated alternatives. Cost compression in standard-tier paper sacks is intensifying because integrated pulp suppliers prioritize corrugated linerboard over sack-grade kraft during fiber shortages. Agricultural cooperatives exhibit highest price sensitivity, while multinational grain traders prioritize traceability premiums over unit cost.
Supply Chain Analysis
Post-consumer woven polypropylene collection and mechanical recycling flows remain underdeveloped, limiting circular feedstock availability for certified recyclable constructions. Tape yarn extrusion clusters in China, India, and Vietnam feed conversion plants across Germany, Brazil, and the United States. Raw material supply draws from polypropylene resin, kraft pulp, and calcium carbonate fillers. Single-source vulnerability concentrates in East Asian tape yarn capacity, where freight cost spikes transmit rapidly to European and North American converters. Distribution runs through regional extrusion hubs serving downstream sack converters with just-in-time fabric rolls.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation compliance timelines are forcing sub-scale converters toward exit or acquisition, consolidating viable capacity among ECHA-registered producers with certified mono-material portfolios.
For Market Incumbents: Hedge against kraft pulp supply disruption through backward integration into recycled fiber sourcing or long-term offtake agreements with Scandinavian pulp mills. Accelerate heat-sealed closure line conversion to preempt margin erosion from REACH substance restrictions on adhesive chemistries. Defensive consolidation of regional weaving capacity in Gujarat and Maharashtra will secure supply chain control against East Asian freight volatility. For New Entrants and Emerging Players: Launch via equipment-technology partnerships targeting mid-tier chemical processors seeking in-house circular weaving capability. Brazil agricultural expansion presents the most penetrable geography, with UV-stabilized woven polypropylene demand outpacing local extrusion capacity. Direct sales to state agricultural extension programs in India bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converters with ECHA-registered product portfolios in Germany and France, where regulatory compliance costs have compressed weaker competitors. Long-term viability hinges on mono-material certification scalability and digital print integration capability. Monitor EU extended producer responsibility fee structure announcements as the decisive inflection signal for capacity valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Certification Investment | ECHA-registered constructions preempt EU extended producer responsibility fees and unlock agricultural tender access. |
| Circular Weaving Equipment Deployment | Starlinger line installations enable chemical processors to bring tape yarn extrusion in-house, cutting supplier dependency. |
| Heat-Sealed Closure Line Conversion | Ultrasonic welding systems satisfy moisture-sensitive fertilizer and salt processor specifications under REACH additive restrictions. |
| Digital Print Integration | Inline flexographic systems compress minimum order quantities for Archer Daniels Midland batch-level QR traceability mandates. |
| Regional Extrusion Hub Expansion | Gujarat and Maharashtra capacity additions serve Food Corporation of India procurement volumes while reducing East Asian freight exposure. |
Research Methodology
Multi-period observation of kraft pulp spot pricing, polypropylene resin contract terms, and ECHA registration timelines anchored the trend analysis, supplemented by interviews with sack converter plant managers, agricultural cooperative procurement leads, chemical processor packaging engineers, and Starlinger equipment sales directors. Secondary validation drew from EU Packaging and Packaging Waste Regulation impact assessments, FCI tender documentation, customs trade data for woven polypropylene fabric, and SEC filings of integrated packaging producers. Bottom-up capacity utilization estimates triangulated against top-down agricultural grain production and chemical shipment volumes.
Segment-weighting applied material type, closure method, and end-use industry dimensions across the projection horizon, with regional coefficients calibrated to India FCI procurement cycles, Brazil soybean export seasonality, and EU regulatory implementation phases. CAGRs derived from elasticity-adjusted demand modeling incorporating substitution effects between paper and woven polypropylene formats. Forecast inputs included REACH substance restriction amendment schedules and pneumatic filling automation adoption curves at OSHA-regulated chemical processing facilities.
Pulp price spike duration, ECHA registration approval delays, and circular weaving technician training bottlenecks are the dominant revision risks to capacity expansion assumptions. Practitioners should monitor EU harmonized recyclability protocol updates and Indian state subsidy program disbursement rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Russia Pouch Packaging Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Cold Seal Lamination Pouch Market
Pouch
GCC Retort Pouches Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Doyen Style Pouches Market
Pouch
Foil Zipper Bags Market
Pouch
Ziplock Products Market
Pouch
Retort Pouch Market
Pouch
Canada Pouch Packaging Market
Pouch
Digital Printed Pouch Market
Pouch
Pouch-Bowl Packaging Market
Pouch
Italy Pouch Packaging Market
Pouch
India Pouch Packaging Market
Pouch
South Africa Pouch Packaging Market
Pouch
Bio PE Pouches Market