
 Saudi Arabia Pouch Packaging Market | 2026-2036
Saudi Arabia Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Pouch Packaging Market Insights
Polyethylene terephthalate is broadening its share against conventional multilayer structures in Saudi pouch production as converters seek thinner gauges with equivalent barrier performance. Napco National leverages integrated film extrusion to control resin costs across its Riyadh and Dammam plants. Huhtamaki Oyj anchors regional growth through its Jeddah facility serving dairy and confectionery accounts with high-speed form-fill-seal formats. Saudi Modern Packaging Co. Ltd. differentiates via specialized retort pouches for ambient shelf-stable meals.
Pouch packaging denotes a flexible primary container formed from laminated films, typically two to four layers with total gauge between 80 and 150 microns, sealed on three or four sides to hold solids, liquids, or powders while minimizing material mass versus rigid alternatives. Stand-up pouches dominate value contribution due to premium shelf presence in hypermarket dairy and juice aisles, while biodegradable materials represent the fastest-expanding material class as brand owners respond to Saudi Vision 2030 circular economy targets. Zipper closures capture disproportionate margin pools because resealability commands price premiums in snack and pet food segments where portion control drives repeat purchases.
SFDA enforces food-contact material migration limits that compound suppliers to submit compliance certificates before commercial deployment, while SASO technical regulations mandate Arabic labeling and shelf-life disclosure on all consumer-facing pouches. MOHAP pharmaceutical packaging guidelines require barrier verification for drug-grade pouches, creating a dual-track compliance burden for converters serving both food and health sectors. Stakeholders must monitor how Saudi Arabia's extended producer responsibility framework evolves, as pending packaging waste rules could reshape material specifications and recycling infrastructure investments.
Market Dynamics
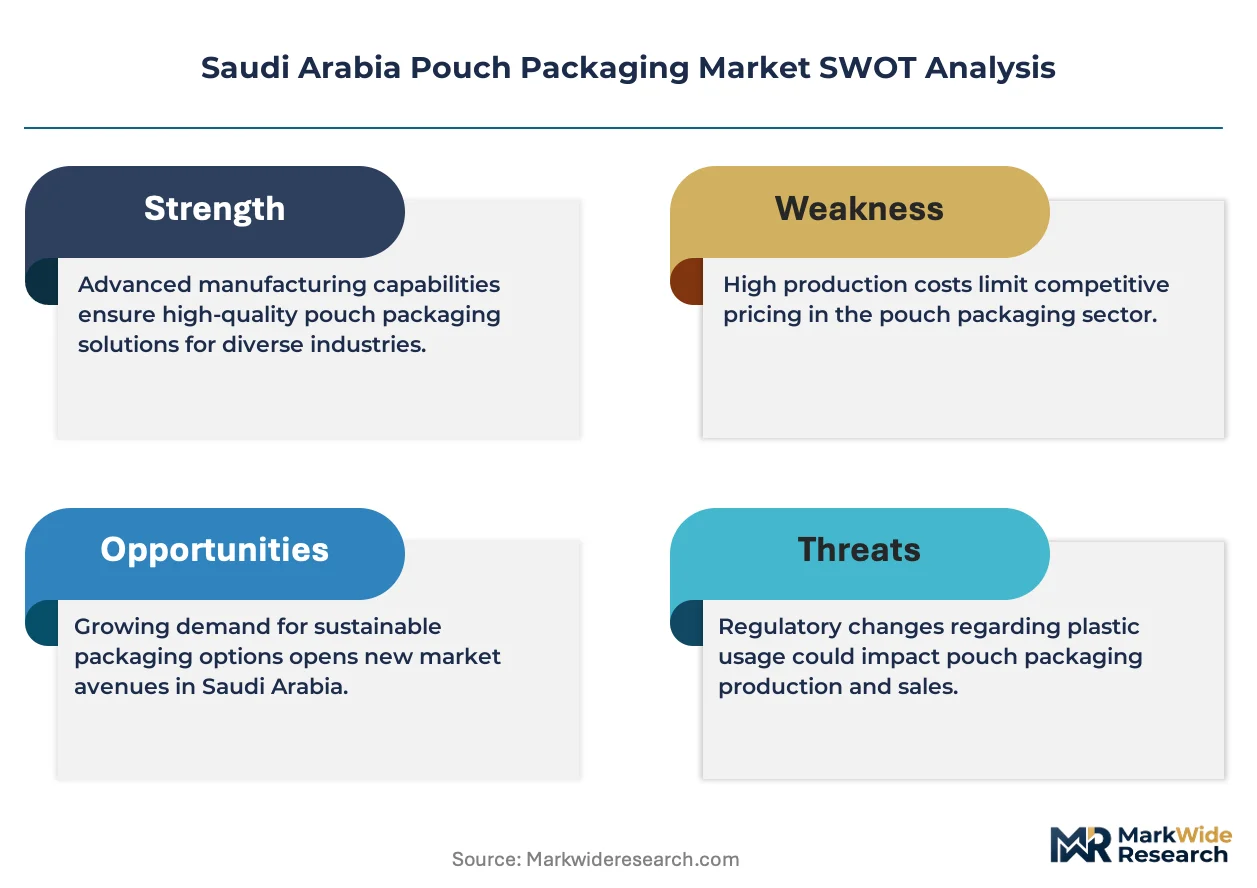
SFDA migration limits and MOHAP traceability mandates are compressing converter margins while forcing rapid material qualification cycles that favor integrated film producers with captive laboratory resources.
Growth Catalysts
- SFDA food-contact compliance:Migration certificate requirements are filtering out non-specialized importers and consolidating orders with certified domestic converters.
- Stand-up pouch formats:Dairy and juice brands in Riyadh hypermarkets are specifying premium shelf-ready structures with spouts and handles.
- Vision 2030 circular economy targets:Government procurement preferences for biodegradable laminates are accelerating pilot lines at Jeddah industrial clusters.
Market Restraints
- Resin cost volatility:Polyethylene and polypropylene feedstock prices track Aramco contract movements, squeezing converter margins during crude price spikes.
- Barrier film supply concentration:EVOH and metallized PET depend on a narrow supplier base concentrated in East Asian export hubs.
- Retort pouch technical ceiling:135°C sterilization requirements limit gauge reduction below 120 microns without seal-integrity failures.
Strategic Opportunities
- Eastern Province industrial corridor:Dammam and Jubail converter parks serve Bahrain and Kuwait export accounts with underdeveloped local supply.
- Pharmaceutical pouch formats:MOHAP barrier verification pathways for unit-dose drug packaging remain underexploited by food-specialized converters.
- Digital printing convergence:Short-run variable-data production enables brand owners to collapse SKU rationalization cycles from months to weeks.
Industry Challenges
- Multilayer recycling infrastructure:Absence of commercial delamination facilities complicates SFDA extended producer responsibility pre-compliance.
- High-speed form-fill-seal technician scarcity:Converter expansion in Jeddah and Riyadh outpaces vocational training program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Pouch Packaging Market |
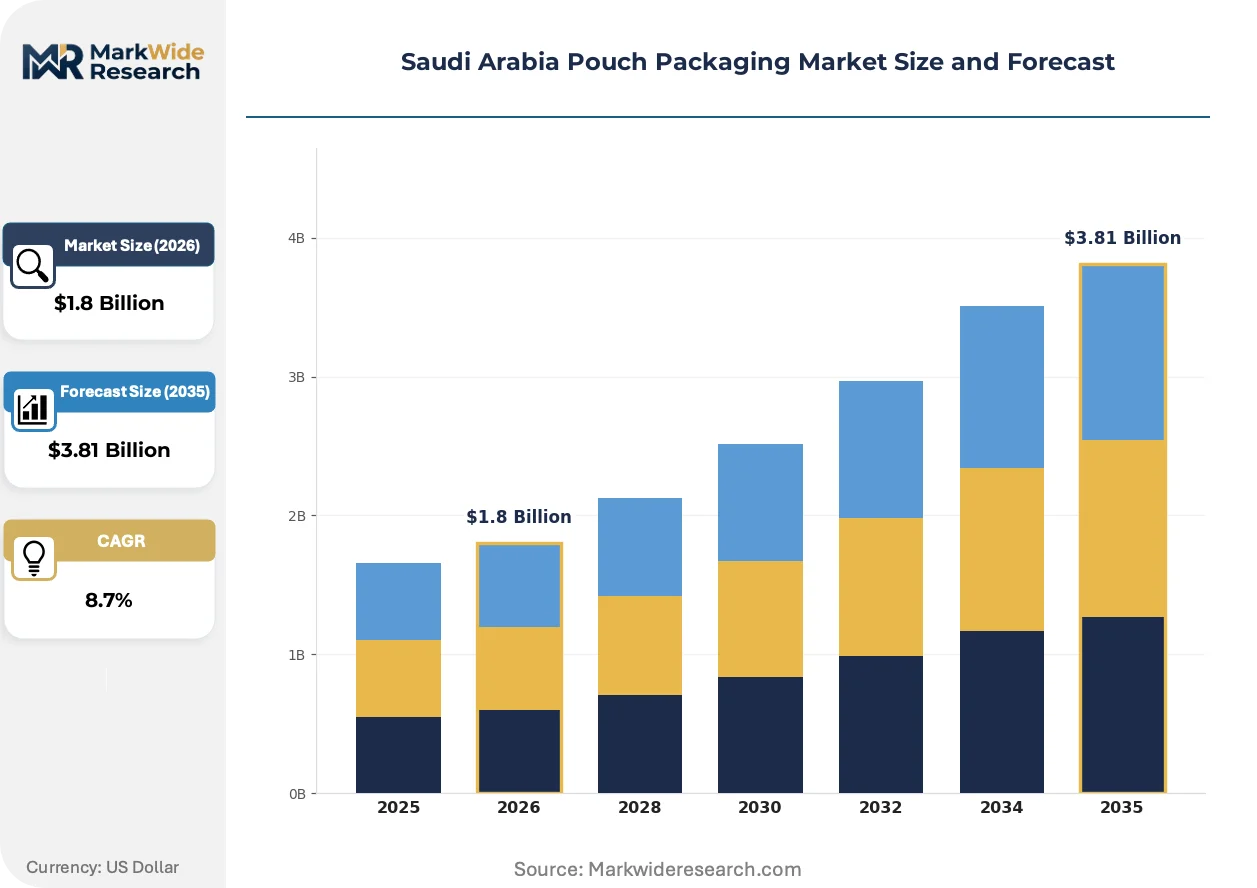
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Gusseted Pouches, Vacuum Pouches Material: Plastic, Metalized Films, Paper, Biodegradable Materials Application: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Closure Type: Zipper, Heat-Sealed, Screw Cap, Others |
| Companies Covered | Napco National, Sonoco Products Company, Huhtamaki Oyj, Sealed Air Corporation, Saudi Modern Packaging Co. Ltd., ASPCO, Flex Pack, Printopack, Obeikan Investment Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Pouch Packaging Market Trends and Innovations
Material science advances and regulatory compression are forcing simultaneous investment in thinner barrier structures and circular-design qualification protocols across Saudi converter operations.
Mono-material polyethylene pouches are achieving oxygen transmission rates below 1 cc/m²/day through advanced orientation techniques. Dairy processors in the Central Region are qualifying these structures for six-month shelf-life yogurt formats. This substrate simplification is converging with mechanical recycling stream requirements to reduce end-of-life sorting complexity.
SFDA implemented mandatory Arabic labeling and shelf-life disclosure enforcement in 2023 with phased compliance windows. Converter pre-press departments are restructuring artwork workflows to accommodate dual-language regulatory panels without compromising brand visibility. Pharmaceutical-grade pouch converters face parallel MOHAP barrier verification audits that extend qualification timelines by four to six months versus food-only certification.
Brand owners are compressing new product development cycles from eighteen months to eight months through direct converter partnerships that bypass traditional trading house intermediaries. Snack and pet food accounts in Riyadh are specifying zipper-equipped formats with minimum 10,000-unit production thresholds that favor regional converters over distant suppliers. This channel restructuring is most pronounced in private-label segments where hypermarket chains consolidate procurement through single-source converter agreements.
Saudi Arabia Pouch Packaging Market Segmentation
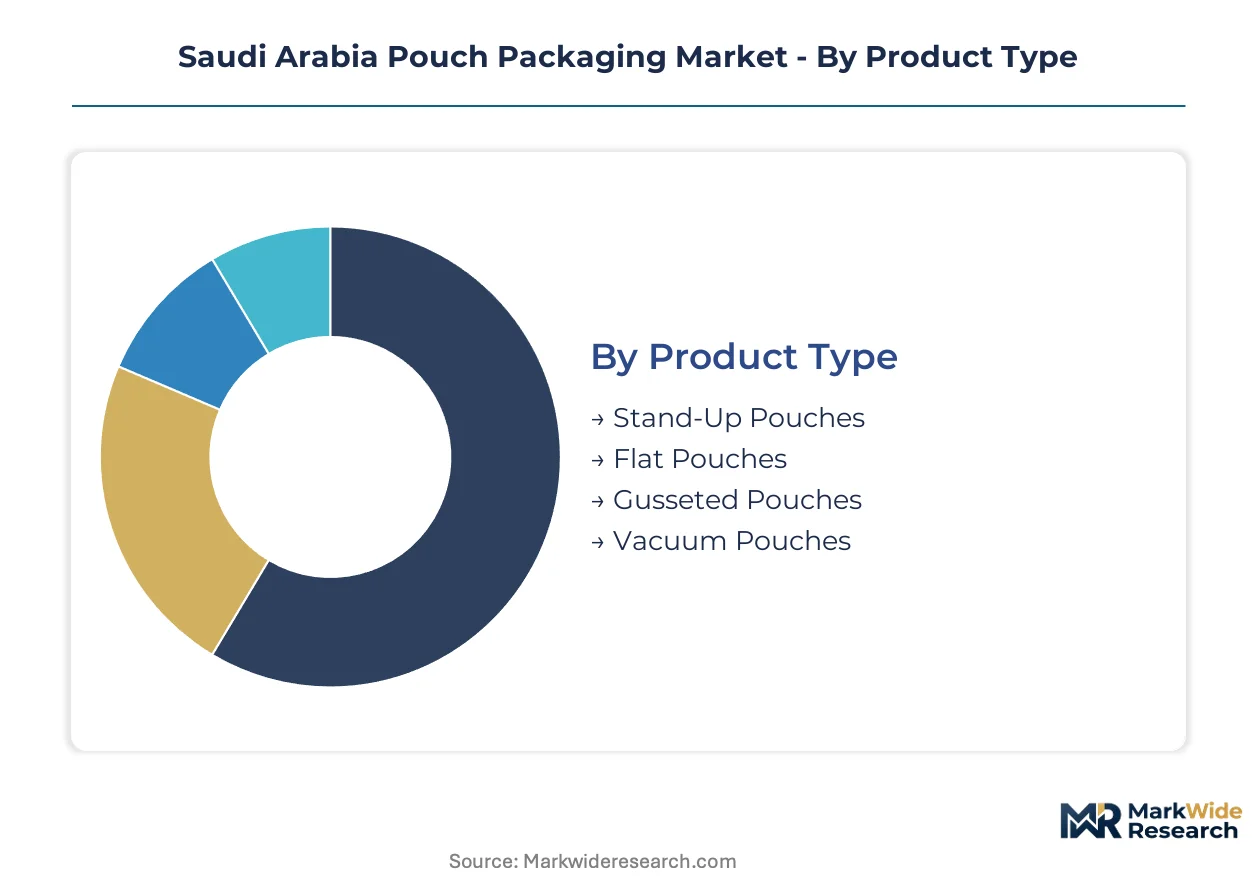
Pouch packaging in Saudi Arabia fragments across four structural dimensions that determine converter investment priorities and margin profiles. Each category reflects distinct trade-offs between shelf performance, regulatory compliance, and material cost that shape procurement decisions by Riyadh and Jeddah brand owners.
Product Type:
Customization intensity varies sharply across this category, from commodity flat formats to engineered stand-up structures requiring spout welding and handle integration.
- Stand-Up Pouches:Self-supporting bottom gusset construction enables vertical shelf display in hypermarket dairy and juice aisles. Dairy processors in Riyadh specify premium formats with integrated spouts for drinking yogurt, paying 15-25% unit premiums over flat alternatives for shelf visibility gains.
- Flat Pouches:Two-seal or three-seal configurations dominate commodity snack and frozen food applications where horizontal stacking suffices. Jeddah industrial corridor converters run flat pouch lines at higher speeds than stand-up formats, capturing volume share in export-bound confectionery.
- Gusseted Pouches:Side gusset expansion accommodates bulk dry goods and coffee beans with minimal headspace. Central Region roasters favor these for one-kilogram formats where bag stability during transport matters.
- Vacuum Pouches:Multi-layer barrier structures with oxygen scavenging layers extend shelf life for processed meats and cheese. SFDA migration testing requirements extend qualification timelines for these high-contact applications.
Most installed capacity flows through flat pouch formats. Expansion is steepest in stand-up pouches.
Material:
Cost tier stratification separates commodity resins from certified biodegradable laminates commanding procurement preference under Vision 2030 circular economy mandates.
- Plastic:Polyethylene and polypropylene laminates constitute the baseline substrate, with converters in Dammam extruding monolayer and coextruded films in-house to hedge Aramco contract volatility. Thinner gauge development—down to 80 microns for non-barrier applications—reduces resin intensity per thousand units.
- Biodegradable Materials:PLA and starch-based laminates qualify for government procurement preference under circular economy targets. Pilot production lines at Jeddah clusters are qualifying these for six-month shelf-life dairy, though oxygen barrier performance trails conventional multilayer structures by 30-40%.
- Metalized Films:Aluminum oxide or metallized PET layers provide moisture and light barriers for coffee and savory snacks. Eastern Province converters import metallized substrates primarily from East Asian suppliers, creating lead time exposure.
- Paper:Kraft and glassine structures serve dry goods and premium confectionery segments where tactile differentiation commands price premiums. Limited moisture resistance restricts paper to low-humidity storage applications.
Plastic retains dominant share in active production lines. Biodegradable materials are gaining share fastest.
Application:
Customer type divergence separates high-volume food processors from specialized pharmaceutical and personal care accounts with distinct barrier and documentation requirements.
- Food & Beverage:Dairy, juice, snack, and ready-to-eat meal segments drive absolute volume, with Riyadh hypermarket chains consolidating procurement through single-source converter agreements. Retort pouch demand for ambient shelf-stable meals is climbing as convenience formats penetrate Saudi household consumption patterns.
- Pharmaceuticals:MOHAP barrier verification requirements for unit-dose and strip packaging create qualification barriers that food-specialized converters rarely cross. Drug-grade pouch demand concentrates with converters holding dedicated cleanroom capacity.
- Personal Care:Stand-up pouches with flip-top dispensing closures serve shampoo, conditioner, and liquid soap refills. Private-label penetration by hypermarket chains is compressing development cycles and favoring regional over import supply.
- Household Products:Detergent pods and cleaning concentrate pouches require child-resistant closure integration. Volume scale remains below food segments, but SKU proliferation in concentrated formats sustains converter utilization.
Food and beverage applications absorb the majority of converter throughput. Pharmaceuticals show the steepest expansion trajectory among qualified suppliers.
Closure Type:
Margin structure separates premium resealable formats from commodity heat-sealed alternatives, with zipper-equipped pouches capturing disproportionate profit pools in snack and pet food segments.
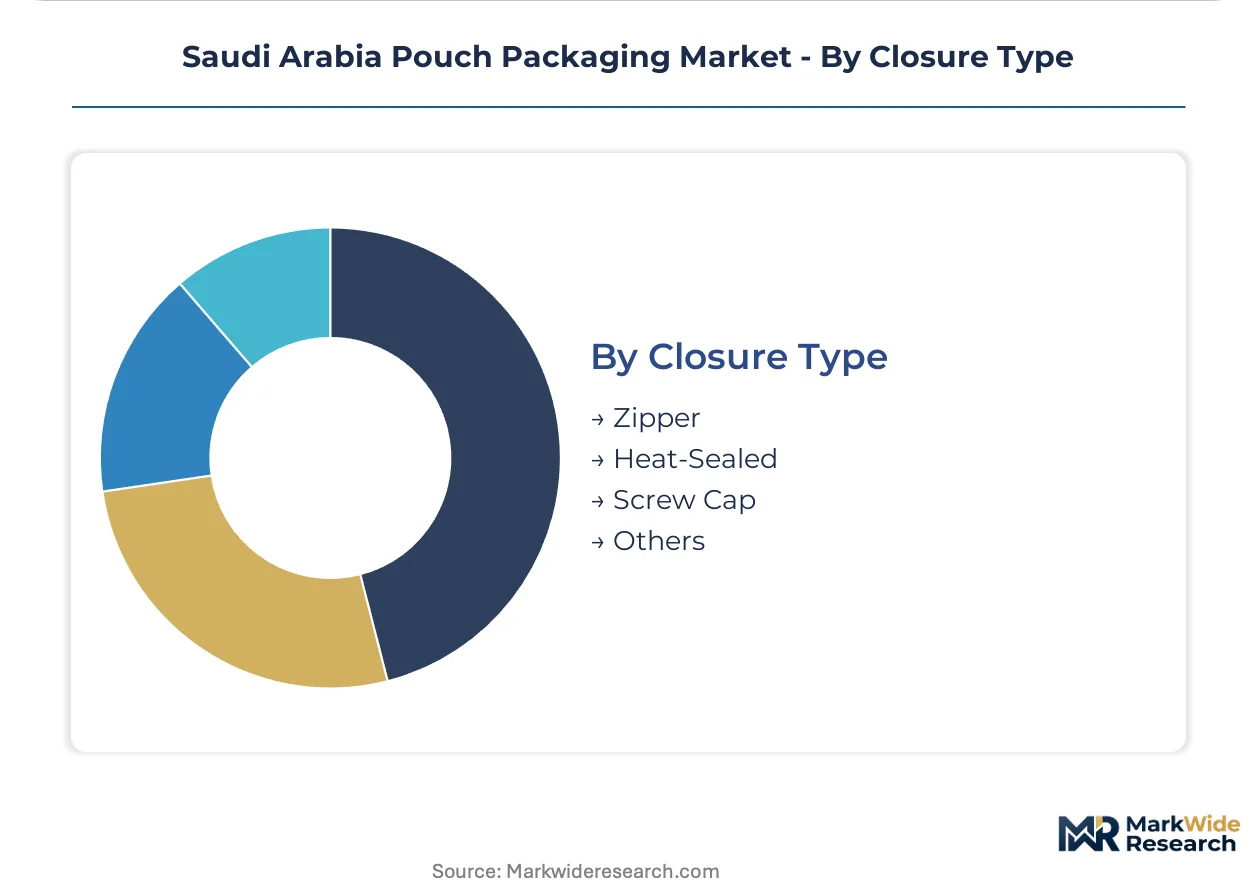
- Zipper:Press-to-close interlocking profiles enable portion control and repeat sealing, commanding 20-30% price premiums in Saudi snack and pet food aisles. Minimum order thresholds of 10,000 units favor domestic converters over distant suppliers for mid-size brand owners.
- Heat-Sealed:Permanent fusion seals across three or four pouch edges constitute the lowest-cost closure, dominant in single-serve condiments and disposable applications where resealability adds no consumer value.
- Screw Cap:Injection-molded threaded closures welded to pouch fitments serve liquid detergents, cooking oils, and large-format beverages. Spout integrity testing under SFDA migration protocols extends qualification timelines versus standard zipper formats.
- Others:Tear notches, laser scoring, and spout-with-cap combinations address niche dispensing requirements in medical nutrition and industrial chemical segments.
Heat-sealed closures retain volume leadership across installed equipment. Zipper formats are climbing the fastest as portion-control positioning penetrates premium snack segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Riyadh industrial corridor anchors Saudi Arabia's pouch packaging demand through dairy and ready-to-eat meal processing clusters. Converter capacity concentrates in three distinct sub-regions serving domestic consumption and Gulf Cooperation Council export channels.
Riyadh
Central Region dairy processors specify premium stand-up pouches with spout integration for drinking yogurt formats. SFDA food-contact compliance mandates filter procurement toward certified domestic converters with captive laboratory resources. The Riyadh Third Industrial City hosts integrated film extrusion operations supplying barrier laminates to hypermarket private-label accounts.
Eastern Province
Dammam and Jubail converter parks process export-bound confectionery and snack pouches for Bahrain and Kuwait markets. Aramco contract resin pricing volatility shapes converter margin structures across polyethylene and polypropylene feedstock purchases. The Jubail industrial cluster accommodates pilot biodegradable laminate lines qualifying for Vision 2030 government procurement preferences.
Western Region
Jeddah facilities serve dairy and confectionery accounts with high-speed form-fill-seal formats. MOHAP pharmaceutical packaging guidelines create dual-track compliance requirements for converters targeting drug-grade barrier verification. The Jeddah industrial corridor concentrates zipper-equipped pouch production for pet food and snack segments commanding resealability premiums.
NEOM Northwest
Emerging circular economy infrastructure targets mono-material recycling stream development under extended producer responsibility pre-compliance. SFDA packaging waste regulations under consultation could reshape material specifications for converters supplying this zone. The NEOM development corridor attracts pilot investments in delamination technology for multilayer pouch recovery.
Saudi Arabia Pouch Packaging Market Competitive Landscape
Global majors compete with regional champions across technology licensing and material qualification capabilities. The vendor base separates into three tiers: integrated film producers with captive extrusion, specialized pouch converters with cleanroom pharmaceutical capacity, and trading house intermediaries losing share to direct brand relationships. Two dominant competitive moves are reshaping positioning: backward integration into resin compounding to hedge feedstock volatility, and strategic partnerships with digital printing equipment providers to collapse SKU development cycles.
Within the integrated production tier, Napco National and Saudi Modern Packaging Co. Ltd. exemplify regional champions with multi-plant coordination across Riyadh and Dammam operations. Huhtamaki Oyj represents the global major archetype, anchoring premium format capabilities through Jeddah-based infrastructure. These three entities occupy distinct competitive positions: one emphasizes captive film extrusion cost control, one differentiates through retort pouch specialization, and one leverages multinational technology transfer for high-speed dairy and confectionery formats.
| Leading Market Players |
|---|
| Napco National |
| Sonoco Products Company |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Saudi Modern Packaging Co. Ltd. |
| ASPCO |
| Flex Pack |
| Printopack |
| Obeikan Investment Group |
| Others |
Pricing and Supply Chain Analysis
Riyadh hypermarket chains and dairy processors concentrate procurement through single-source converter agreements, locking in contract-based long-term offtake pricing that buffers against Aramco resin volatility. This buyer consolidation shifts pricing power toward integrated domestic producers with captive film extrusion, while fragmented snack importers absorb spot-market polyethylene fluctuations.
Pricing Analysis
Polyethylene and polypropylene feedstock costs pass through Aramco contract movements, squeezing converter margins during crude price spikes. Three-tier pricing structure across premium, standard, and economy levels separates retort pouch specialists from commodity flat pouch producers. Cost compression in standard-tier formats is intensifying because thinner gauge development below 100 microns reduces resin intensity per thousand units. Hypermarket private-label accounts show highest price sensitivity, while pharmaceutical-grade converters with MOHAP barrier verification command least sensitivity due to qualification barriers.
Supply Chain Analysis
SFDA and SASO local-content compliance mandates are reshaping sourcing patterns toward domestic converters with certified laboratory resources. EVOH and metallized PET barrier films draw from East Asian export hubs, while polyethylene feedstock rests on Aramco contract supply. Single-source vulnerability in high-barrier substrate imports creates lead time exposure for Eastern Province converters. Distribution runs through Riyadh and Jeddah industrial corridor clusters serving domestic consumption and Gulf Cooperation Council export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's pouch packaging market functions as a stable compounder anchored by Vision 2030 circular economy procurement preferences that sustain biodegradable laminate demand through policy rather than commodity cycles.
For Market Incumbents: To counter resin cost volatility eroding converter margins, prioritize backward integration into captive film extrusion at Riyadh and Dammam plants. Secure SFDA migration certificate pre-qualification to filter out non-specialized importers and consolidate procurement relationships with hypermarket chains. For New Entrants and Emerging Players: MOHAP barrier verification requirements in Saudi Arabia open a window for pharmaceutical-grade pouch specialists with cleanroom capacity, a segment food-specialized converters rarely cross. Target unit-dose drug packaging formats in Jeddah where qualification barriers extend timelines by four to six months versus food-only certification. Partner with digital printing equipment providers to collapse SKU development cycles from months to weeks for mid-size brand owners. For Investors and Strategic Acquirers: Regional packaging conglomerates are the most active acquirer in this space, seeking converters with integrated film production and SFDA-certified laboratory resources. Five-to-ten-year viability hinges on extended producer responsibility framework positioning ahead of pending packaging waste regulations. Watch for SFDA delamination facility licensing announcements as the inflection indicator for circular-economy-compliant material specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Napco National's captive resin cost control across Riyadh and Dammam plants demonstrates margin defense against Aramco volatility. |
| Pharmaceutical Cleanroom Certification | MOHAP barrier verification pathways remain underexploited by food-specialized converters, creating acquisition premiums for qualified assets. |
| Digital Printing Partnership | Short-run variable-data production enables brand owners to bypass traditional trading house intermediaries and compress development cycles. |
| Biodegradable Pilot Line Investment | Jeddah industrial clusters qualifying PLA laminates for six-month shelf-life dairy capture Vision 2030 government procurement preference. |
| Delamination Technology Licensing | NEOM development corridor pilot investments in multilayer pouch recovery position ahead of SFDA extended producer responsibility mandates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with converter operations managers, hypermarket category buyers, SFDA compliance officers, and resin procurement leads at Aramco-linked distributors. Secondary validation drew from SASO technical regulation filings, SFDA food-contact material migration certificates, customs trade data on EVOH and metallized PET imports, and SEC disclosures by listed packaging conglomerates. Bottom-up capacity utilization estimates and top-down consumption forecasts were triangulated to anchor value projections.
Segment-weighting approaches modeled stand-up versus flat pouch format splits, plastic versus biodegradable material trajectories, and food versus pharmaceutical application shares across the projection horizon. CAGRs were derived from installed capacity expansion timelines, SFDA compliance phase-in schedules, and Vision 2030 procurement preference implementation curves. Converter margin sensitivity to Aramco contract resin pricing and high-speed form-fill-seal technician scarcity informed scenario boundaries.
Revisions become necessary when SFDA packaging waste regulations under consultation materialize with mandatory delamination requirements, or when MOHAP pharmaceutical barrier verification pathways expand beyond current drug-grade pouch specifications. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Europe Pouch Packaging Market
Pouch
Utility Pouches Market
Pouch
China Pouch Packaging Market
Pouch
OPP Pouches Market
Pouch
Vacuum Chamber Pouches Market
Pouch
Four Side-Sealed Pouches Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
Doy Pouch Packaging Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Japan Pouch Packaging Market
Pouch
South Africa Pouch Packaging Market
Pouch
Foil Pouch Packaging Market
Pouch
Feed Pouches Market
Pouch
Portion Control Packs Market
Pouch
Pouch Equipment Market