
 Poland Pouch Packaging Market | 2026-2036
Poland Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Pouch Packaging Market Insights
Food and beverage demand is rebalancing toward convenience-oriented formats as Polish consumers shift from rigid containers to lightweight, portion-controlled pouches for dairy alternatives and ready meals. Amcor Group GmbH leverages its European manufacturing footprint to supply multilayer barrier films for ambient food applications. Mondi PLC anchors its position through kraft paper-based flexible solutions that align with retailer sustainability mandates. SEFKO Sp. z.o.o competes as a domestic specialist with short-run customization capabilities for mid-sized Polish food brands.
Pouch packaging denotes flexible, sealed containers constructed from laminated films or paper-plastic composites, typically featuring heat-sealed edges and optional reclosure mechanisms, designed to protect contents from moisture, oxygen, and light while minimizing material weight versus rigid alternatives. Stand-up pouches dominate volume due to their shelf presence and filling-line compatibility across Polish retail channels. Zipper pouches represent the fastest-expanding closure category as brands prioritize consumer convenience and portion control. Plastic composites retain material leadership though paper and aluminum laminates capture margin pools in premium organic and pharmaceutical applications where barrier performance commands price premiums.
Poland's pouch packaging sector operates under EU REACH chemicals regulation, EU Packaging and Packaging Waste Directive with extended producer responsibility frameworks, and BIS-equivalent Polish Committee for Standardization (PKN) norms for food contact materials. These standards mandate recyclability disclosures, restrict certain substance migrations, and impose collection targets that reshape material selection and supplier qualification processes. Stakeholders must monitor evolving EU Green Deal packaging rules and domestic waste infrastructure investments to anticipate compliance cost trajectories and material substitution timelines.
Market Dynamics
EU Packaging and Packaging Waste Regulation alignment is compressing material substitution timelines across Polish converter operations, forcing rapid transitions from multilayer plastic laminates toward recyclable mono-material structures and fiber-based alternatives before mandated collection targets take effect.
Growth Catalysts
- Extended Producer Responsibility frameworks:Poland's implementation of EU-mandated EPR schemes creates compliance-driven demand for certified recyclable pouch formats, pushing brand owners toward converter partners with verified circularity credentials.
- Food processing cluster concentration:Greater Poland Voivodeship's dense agglomeration of dairy, meat, and ready-meal manufacturers generates localized pouch consumption gravity that attracts film suppliers and co-packers.
- Mono-material barrier films:Advances in polyethylene and polypropylene barrier metallization enable recyclability compliance without sacrificing oxygen and moisture protection for ambient shelf-stable applications.
Market Restraints
- Aluminum and ethylene feedstock volatility:Laminate converters face margin compression from petrochemical price swings and energy-intensive foil production costs that resist pass-through negotiation with retail chains.
- German and Austrian film supplier dominance:Critical barrier layer supply concentrates among Central European chemical conglomerates, exposing Polish converters to currency risk and allocation priority disputes during capacity crunches.
- Mechanical recycling incompatibility:Legacy multilayer pouches containing EVOH and nylon barrier layers cannot process through existing Polish waste infrastructure, creating stranded asset risk for brands with unsold inventory.
Strategic Opportunities
- Lesser Poland Voivodeship expansion:Kraków's emerging food-tech startup ecosystem remains underpenetrated by pouch specialists, offering first-mover positioning for converters with short-run digital printing capabilities.
- EU Green Deal packaging rules:Anticipated 2030 reuse and recycling targets will mandate minimum recycled content thresholds, creating premium positioning for converters with secured post-consumer resin supply chains.
- Pharmaceutical secondary packaging:Child-resistant zipper mechanisms combined with aluminum barrier laminates are expanding into OTC and supplement applications where compliance packaging commands price premiums.
Industry Challenges
- Mono-material conversion engineering:Heat-seal layer reformulation and filling-line retrofit requirements demand polymer science expertise that Polish technical universities currently underproduce relative to industry demand.
- PKN food contact certification timelines:Migration testing and safety dossier preparation for novel bio-based coatings extend qualification cycles, delaying commercial launch windows for sustainable material innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Pouch Packaging Market |
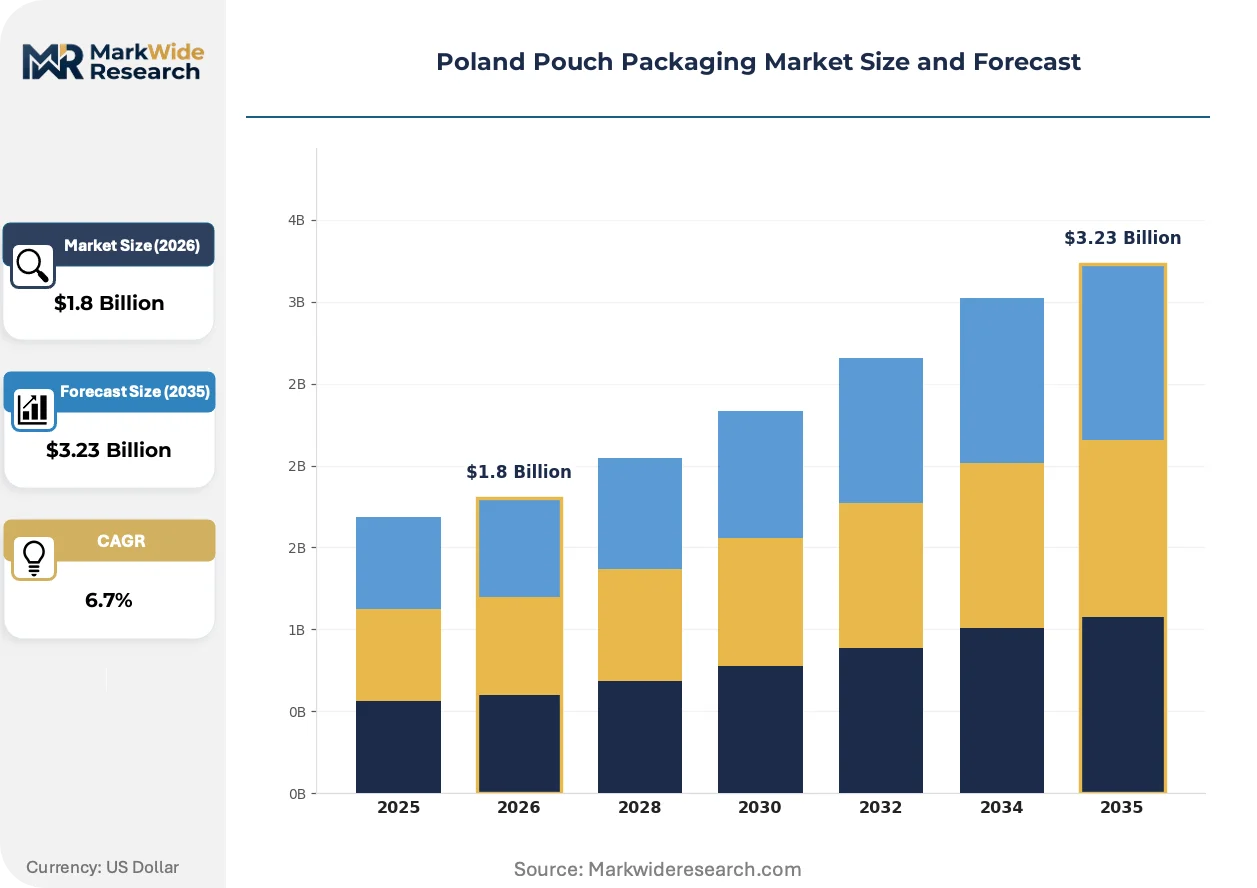
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zipper Pouches, Child-Resistant Pouches Material: Plastic, Paper, Aluminum, Composites Application: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Closure Type: Zip Lock, Spout, Heat Seal, Tear Notch |
| Companies Covered | Amcor Group GmbH, Mondi PLC, Sonoco Products Company, ePac Holdings LLC, SEFKO Sp. z.o.o, Coveris Management GmbH, Pakmar Sp. z o.o., Huhtamaki, FLEX, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Pouch Packaging Market Trends and Innovations
Material science convergence with digital production technologies is collapsing minimum order quantities and accelerating format experimentation across Polish converter operations, enabling brand owners to test regional variants without committing to plate-based print runs.
High-barrier paper-plastic laminates are expanding into ambient soup and sauce applications previously reserved for aluminum foil composites. Polish private-label retailers are adopting these formats for organic product lines where shelf appearance and sustainability credentials intersect. The technology is expanding into premium positioning across discount channel shelves that previously standardized on conventional plastics.
REACH chemical restriction expansions are prohibiting specific phthalate plasticizers and perfluorinated substances in food contact laminates. Polish Committee for Standardization is accelerating adoption of EFSA migration limit guidelines into binding national norms. Dairy alternative brands reformulating packaging specifications face compressed compliance timelines as substance sunset dates approach.
Retail chain consolidation is compressing supplier qualification cycles and centralizing procurement decisions to Warsaw-based category management teams. Regional Polish food brands are losing direct buyer relationships as Biedronka and Żabka parent entities mandate format standardization across private-label portfolios. The shift concentrates volume with converters capable of national distribution scale rather than regional specialization.
Poland Pouch Packaging Market Segmentation
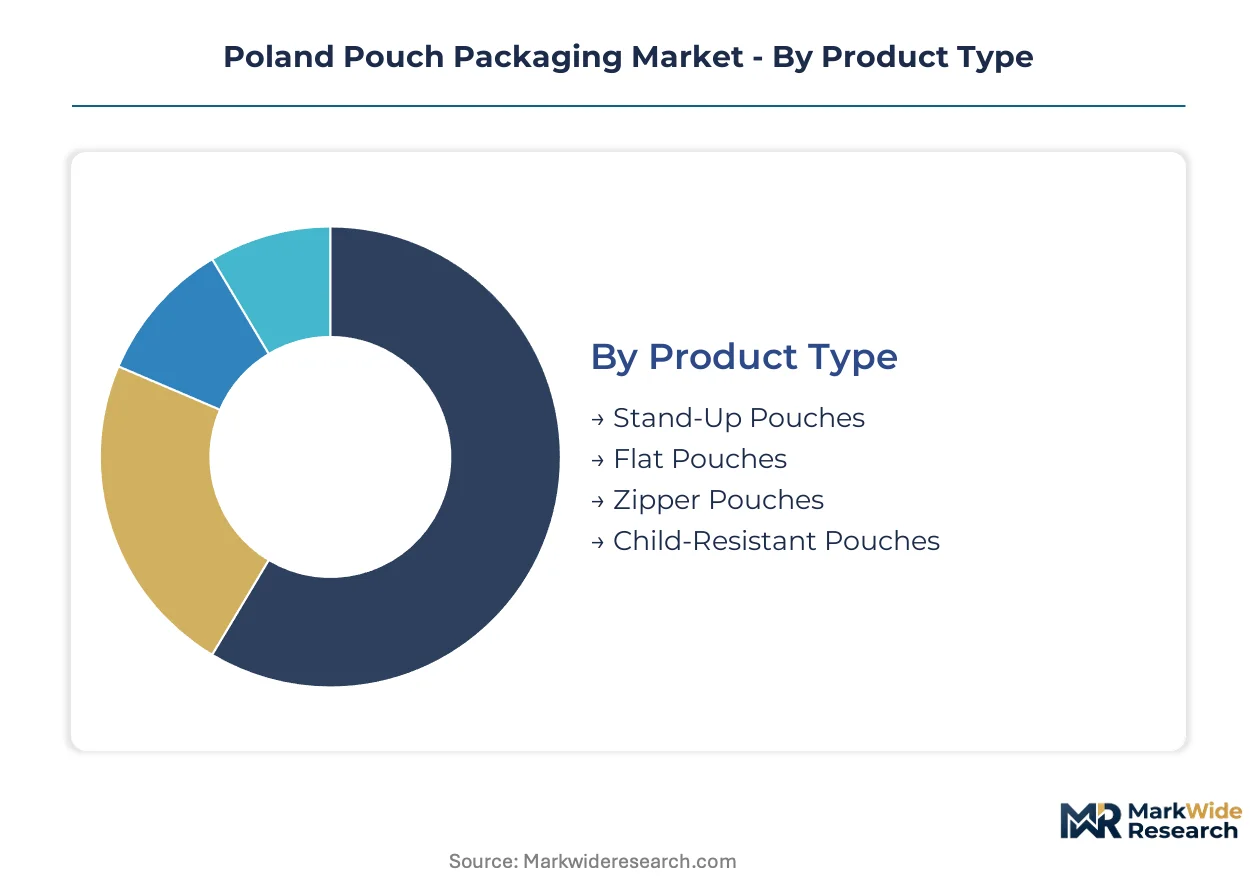
Polish pouch converters configure production lines around specific format-material combinations that determine capital deployment, barrier engineering requirements, and regulatory qualification pathways. Segment selection dictates access to Greater Poland Voivodeship food processing clusters versus pharmaceutical corridors near Warsaw.
Product Type:
Capital intensity escalates with structural complexity and reclosure mechanism integration, separating commodity flat formats from engineered stand-up configurations requiring gusset sealing and bottom fold equipment.
- Stand-Up Pouches:Gusseted bottom construction enables vertical shelf display without secondary support. Greater Poland Voivodeship dairy and ready-meal manufacturers specify these for ambient retail distribution where shelf presence drives trial purchase.
- Flat Pouches:Two-dimensional heat-sealed envelopes minimize material consumption and machine footprint. Powdered supplement and single-serve condiment brands in Lesser Poland Voivodeship favor these for cost-optimized sachet formats.
- Zipper Pouches:Reclosable track systems add polymer layer complexity and specialized sealing heads. Polish private-label retailers mandate these for portion-controlled nuts and dried fruits across Biedronka and Żabka networks.
- Child-Resistant Pouches:Dual-action opening mechanisms and opaque barrier layers require pharmaceutical-grade validation protocols. OTC medication and cannabis-adjacent wellness brands in Mazowieckie Voivodeship specify these for compliance packaging.
Most installed capacity flows through Stand-Up Pouches. Expansion is steepest in Zipper Pouches.
Material:
Raw material selection determines recyclability certification eligibility under EU Packaging and Packaging Waste Regulation, with mono-material structures commanding premium positioning versus legacy multilayer laminates facing stranded asset risk.
- Plastic:Polyethylene and polypropylene mono-materials dominate volume through compatibility with existing Polish mechanical recycling infrastructure. Amcor Group GmbH and Mondi PLC supply metallized variants that preserve oxygen barriers without aluminum foil layers.
- Paper:Kraft-based flexible substrates with bio-based coatings capture organic product lines where retailer sustainability mandates require fiber-primary construction. Polish Committee for Standardization migration testing timelines delay qualification for high-moisture applications.
- Aluminum:Foil laminates retain pharmaceutical and premium coffee segments where absolute light and oxygen exclusion justifies energy-intensive production and non-recyclable classification.
- Composites:Paper-plastic-aluminum tri-laminates persist in legacy soup and sauce applications though EU Green Deal packaging rules accelerate phase-out timelines for non-recyclable structures.
Plastic retains the largest installed base. Paper is climbing the fastest as converter investments in barrier coating technology mature.
Application:
End-use sector selection determines regulatory pathway complexity, with food contact certification through Polish Committee for Standardization representing the highest volume qualification burden versus pharmaceutical dossier requirements.
- Food & Beverage:Ambient shelf-stable and chilled ready-to-eat categories drive absolute demand volume. Greater Poland Voivodeship meat, dairy, and plant-based alternative processors specify high-barrier formats with extended shelf-life performance.
- Personal Care:Single-use mask sachets and refill pouches for liquid soaps concentrate demand in urban retail corridors. Format requirements prioritize puncture resistance and aesthetic surface printing over oxygen barrier specifications.
- Pharmaceuticals:Compliance packaging with child-resistant features and tamper-evident seals commands price premiums. Secondary packaging applications for OTC and supplement brands expand as blister pack alternatives.
- Household Products:Concentrate refills for cleaning and laundry applications prioritize chemical resistance and spout compatibility. E-commerce distribution growth drives demand for leak-proof closure systems.
Food & Beverage absorbs the majority of converter capacity. Pharmaceuticals shows the steepest expansion trajectory as compliance packaging requirements proliferate.
Closure Type:
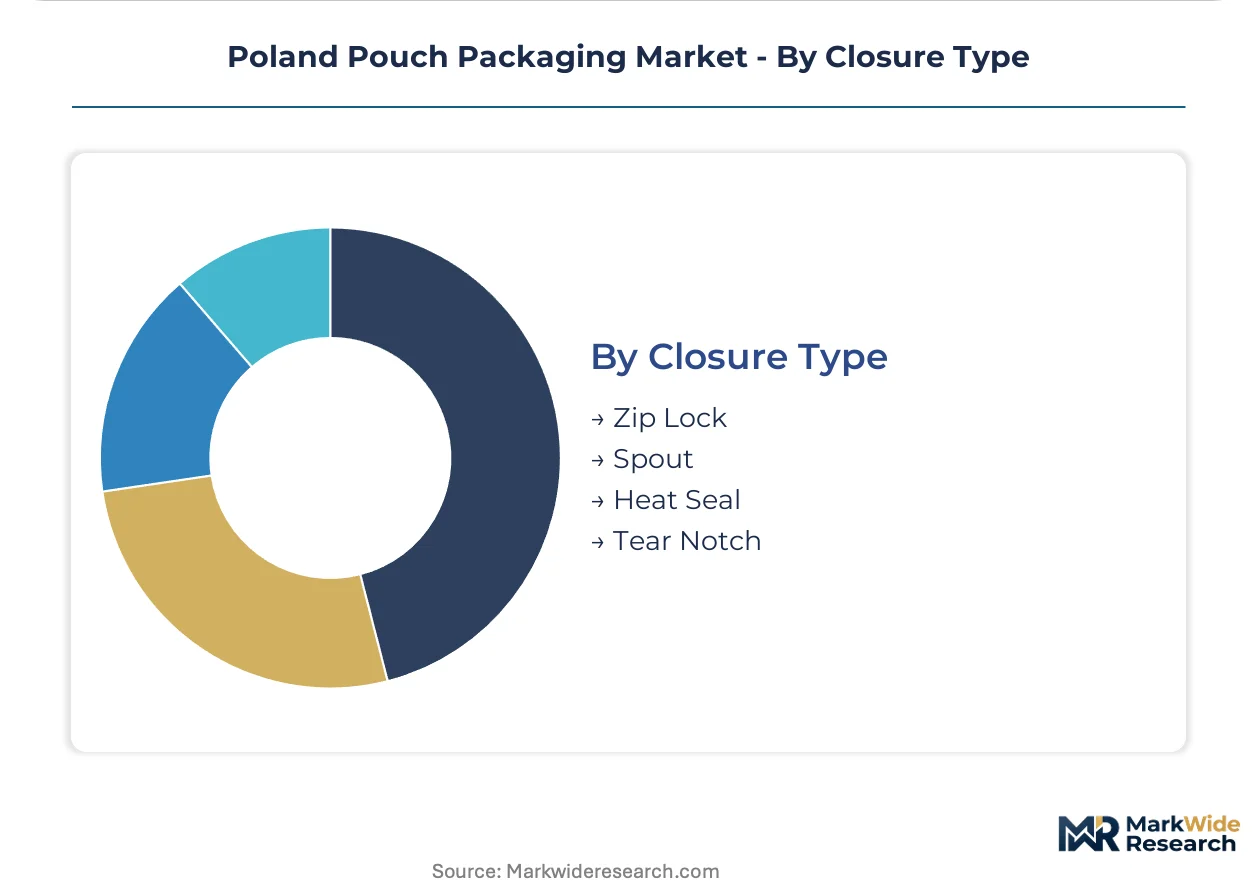
Mechanism engineering determines consumer convenience positioning and filling-line retrofit requirements, with zipper and spout systems demanding specialized sealing equipment versus universal heat-seal compatibility.
- Zip Lock:Interlocking polymer tracks enable repeated reclosure for portion control and freshness preservation. Polish snack and dried fruit brands specify these for private-label lines distributed through consolidated retail procurement.
- Spout:Integrated pour mechanisms with threaded caps suit liquid and semi-liquid contents. Baby food and smoothie applications in Mazowieckie Voivodeship drive adoption despite higher per-unit equipment investment.
- Heat Seal:Permanent fusion sealing across film layers minimizes material cost and machine complexity. Single-serve condiments and sample sachets favor this format for cost-optimized production.
- Tear Notch:Perforated opening features add minimal material cost while improving consumer access. Powdered products and dry mixes specify these as standard across flat pouch configurations.
Heat Seal retains the dominant installed base. Spout formats are gaining share fastest as liquid ready-to-drink applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping pouch packaging investment flows across Central and Eastern Europe, as Poland's alignment with EU Packaging and Packaging Waste Regulation creates cost-of-compliance gaps that attract converter capacity from non-EU neighbors while pushing domestic players toward mono-material transitions ahead of mandated collection targets.
Greater Poland Voivodeship
Dairy alternative processors and ready-meal manufacturers in Poznań and surrounding industrial zones drive concentrated pouch demand for ambient shelf-stable applications. Polish Committee for Standardization food contact certification requirements filter supplier qualification, favoring converters with established migration testing capabilities. The Konin-Turek corridor hosts film lamination facilities supplying barrier structures to meat processing clusters.
Mazowieckie Voivodeship
Warsaw-based pharmaceutical and OTC brands specify child-resistant zipper pouches for compliance packaging, creating premium segment demand distinct from commodity food applications. EU REACH chemical restrictions on phthalate plasticizers accelerate reformulation timelines for local converters serving supplement brands. The Piaseczno industrial zone attracts barrier film distributors positioning for pharmaceutical secondary packaging growth.
Lesser Poland Voivodeship
Kraków's emerging food-tech startup ecosystem generates short-run, digitally printed pouch demand for test-market launches and regional product variants. Extended Producer Responsibility framework implementation raises compliance costs for small-batch producers, creating opportunity for converters with flexible manufacturing architectures. The Tarnów chemical cluster supplies polyethylene resins for mono-material film experimentation.
Silesian Voivodeship
Katowice-area logistics and distribution centers channel imported barrier films from German and Austrian chemical suppliers to Polish converter operations. EU Green Deal packaging rules drive warehousing investments for post-consumer resin stockpiling ahead of anticipated recycled content mandates. The Gliwice-Zabrze corridor hosts co-packing facilities serving pan-European retail chains with standardized pouch formats.
Pomeranian Voivodeship
Gdańsk port infrastructure facilitates Baltic Sea import routes for aluminum foil and bio-based coating raw materials. Polish waste infrastructure investments in mechanical recycling capacity concentrate in northern corridors to process emerging mono-material polyethylene pouch streams. The Tricity metropolitan area attracts sustainable packaging R&D facilities leveraging maritime logistics for Scandinavian market access.
Poland Pouch Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational film suppliers dominating barrier material supply while domestic converters capture customization-intensive mid-volume food accounts. Market structure tilts toward consolidated upstream supply and fragmented downstream conversion, creating tiered competition between scale-driven material innovators and agile short-run specialists. Two strategic archetypes predominate: integrated multinationals with European manufacturing footprints and domestic specialists with regional customization capabilities. Competitive dynamics center on mono-material transition speed and PKN certification throughput capacity.
Within the multinational tier, Amcor Group GmbH and Mondi PLC anchor barrier film supply to Polish converter operations, representing scale-driven archetypes with metallized polymer capabilities. SEFKO Sp. z.o.o occupies a position among domestic specialists, exemplifying the short-run customization segment serving mid-sized Polish food brands with rapid format adaptation. These three entities collectively illustrate the competitive spectrum from standardized material supply to tailored converter partnerships.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Mondi PLC |
| Sonoco Products Company |
| ePac Holdings LLC |
| SEFKO Sp. z.o.o |
| Coveris Management GmbH |
| Pakmar Sp. z o.o. |
| Huhtamaki |
| FLEX |
| Others |
Pricing and Supply Chain Analysis
Mono-material barrier film conversion is compressing converter margins while simultaneously redistributing pricing power toward resin suppliers with certified recyclability credentials. Polish food brands now face stepped cost structures as EU Packaging and Packaging Waste Regulation compliance forces rapid equipment retrofit and polymer reformulation before mandated collection targets activate.
Pricing Analysis
Retailer markup layers dominate final price formation as Biedronka and Żabka procurement centralization strips regional brands of direct negotiation leverage. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade aluminum laminates from commodity polyethylene mono-materials and basic polypropylene flat pouches. Cost compression in standard-tier formats is intensifying because German and Austrian film suppliers prioritize allocation to larger Western European converters during capacity crunches. Mid-sized Polish food brands exhibit highest price sensitivity due to thin working capital buffers and limited volume leverage.
Supply Chain Analysis
Workforce availability constraints in Greater Poland Voivodeship and Mazowieckie Voivodeship are elevating labor costs for converter operations while Silesian Voivodeship logistics hubs draw technical talent from film lamination facilities. Raw material supply concentrates in Germany, Austria, and the Czech Republic for barrier layer polymers, with Saudi Arabia and Russia anchoring virgin polyethylene feedstock. Single-source vulnerability runs through Central European metallized film suppliers where allocation priority disputes strand Polish converters during demand spikes. Distribution runs through Warsaw-based category management teams that centralize procurement decisions for consolidated retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's pouch packaging sector functions as a geographic-arbitrage play where EU regulatory alignment creates compliance cost gaps against non-EU neighbors while domestic EPR implementation accelerates faster than regional waste infrastructure maturation.
For Market Incumbents: Hedge stranded asset risk in legacy multilayer laminate capacity by accelerating mono-material conversion engineering partnerships with Polish technical universities. Secure backward integration into post-consumer resin supply chains ahead of EU Green Deal recycled content mandates. Prioritize PKN certification throughput capacity expansion to compress qualification timelines for sustainable material innovations. For New Entrants and Emerging Players: The premium-to-economy price-point gap in child-resistant pharmaceutical pouches offers white-space entry as Warsaw-based OTC brands seek alternatives to incumbent aluminum laminate suppliers. Target Kraków's food-tech startup ecosystem with short-run digital printing capabilities for test-market launches. Pursue co-packing partnerships with Lesser Poland Voivodeship emerging brands lacking in-house packaging engineering. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic converters with regional customization capabilities but underdeveloped mono-material technical competencies. Five-to-ten year viability hinges on successful polymer science talent acquisition and barrier coating R&D investment. Monitor EU Green Deal packaging rule implementation velocity as inflection indicator for material substitution timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Conversion Engineering | PKN certification timelines for novel polyethylene barrier structures determine competitive positioning against multilayer incumbents. |
| Post-Consumer Resin Supply Agreement | Secured PCR streams from Polish mechanical recycling infrastructure anchor compliance with anticipated EU recycled content thresholds. |
| Digital Printing Capability Investment | Short-run flexibility captures Kraków food-tech demand while collapsing minimum order quantities for regional brand variants. |
| Child-Resistant Mechanism Patent Licensing | Pharmaceutical compliance packaging commands price premiums in Mazowieckie Voivodeship OTC and supplement applications. |
| Extended Producer Responsibility Pre-Registration | Early EPR framework compliance builds circularity credentials for Biedronka and Żabka private-label supplier qualification. |
Research Methodology
Multiple input streams — converter operations data, resin supplier allocation records, and retail procurement documentation — were reconciled across primary interviews with Polish packaging engineers, food brand supply chain directors, pharmaceutical regulatory affairs leads, and barrier film technical sales specialists. Secondary validation drew from Polish Committee for Standardization migration testing protocols, EU Packaging and Packaging Waste Directive implementation guidance, customs records for polyethylene and aluminum foil imports, and Greater Poland Voivodeship industrial cluster employment statistics. Bottom-up capacity modeling and top-down demand estimation were triangulated to cross-verify volume assumptions.
Historical production trends were cross-referenced against expert panel assessments of mono-material conversion timelines and EPR implementation velocity across the projection horizon. Segmentation dimensions modeled include pouch format type, material composition tier, end-use application sector, closure mechanism complexity, and voivodeship-level geographic demand cluster. CAGRs were derived from slope consensus across input scenarios rather than single-point extrapolation. Forecast inputs incorporated Polish waste infrastructure investment pipelines and REACH chemical restriction sunset schedules.
Caveats apply where EU Green Deal packaging rule acceleration, German-Austrian supplier allocation disputes, or PKN certification backlog could materially shift the outlook. Forecasts reflect assumptions about mechanical recycling capacity scaling and mono-material barrier performance maturation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Contour Pouches Market
Pouch
Kraft Block Bottom Pouch Market
Pouch
Inflatable Pouches Market
Pouch
UAE Pouch Packaging Market
Pouch
Global Pre Zippered Pouches Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Vacuum Chamber Pouches Market
Pouch
OPP Pouches Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Stick Pouches Packaging Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Liquid Pouch Market
Pouch
Four Side Flat Pouch Market
Pouch
India Pouch Packaging Market
Pouch
Feed Pouches Market
Pouch
Slider Pouches Market