
 Spain Pouch Packaging Market | 2026-2036
Spain Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Pouch Packaging Market Insights
Specialty food exporters are redrawing Spain's pouch packaging demand map, displacing commodity-oriented domestic buyers as the priority customer archetype. Amcor PLC leverages its European film extrusion network to supply high-barrier laminates for Iberian cured meat and olive oil exports. Constantia Flexibles anchors its position through dedicated capacity for pharmaceutical sachets and unit-dose pouches at its Spanish plants. Mondi PLC competes via integrated kraft paper-pouch solutions targeting the renewable packaging segment.
Spain pouch packaging denotes flexible primary containers constructed from multi-layer polymer films, aluminum foil laminates, or fiber-based substrates, typically ranging from 50 milliliters to five liters in fill volume, formed through horizontal or vertical form-fill-seal processes and sealed by heat, zipper, or spout closure mechanisms to protect contents from moisture, oxygen, and light. Stand-up pouches with spout closures command premium positioning in the food and beverage application due to their shelf presence and dispensing convenience, while flat pouches dominate pharmaceutical unit-dose formats where cost minimization and sterility take precedence. Compostable materials represent the fastest-growing material segment as Spanish retailers and brand owners respond to consumer pressure and regulatory timelines for packaging recyclability.
Spain's national packaging regulator enforces the Royal Decree on Packaging and Packaging Waste, which transposes EU directives mandating recyclability thresholds and extended producer responsibility schemes that directly shape converter material selection and design-for-recycling investments. BIS-equivalent Spanish standardization bodies participate in developing EN norms for flexible packaging migration limits and food contact compliance, while CE marking requirements govern pouch-making machinery safety and electromagnetic compatibility for equipment suppliers like Infipack Machinery SL. Stakeholders must monitor how Madrid interprets forthcoming EU packaging and packaging waste regulation revisions, as stricter reuse and recycling targets will force early capital allocation toward compatible mono-material lines or certified compostable structures.
Market Dynamics
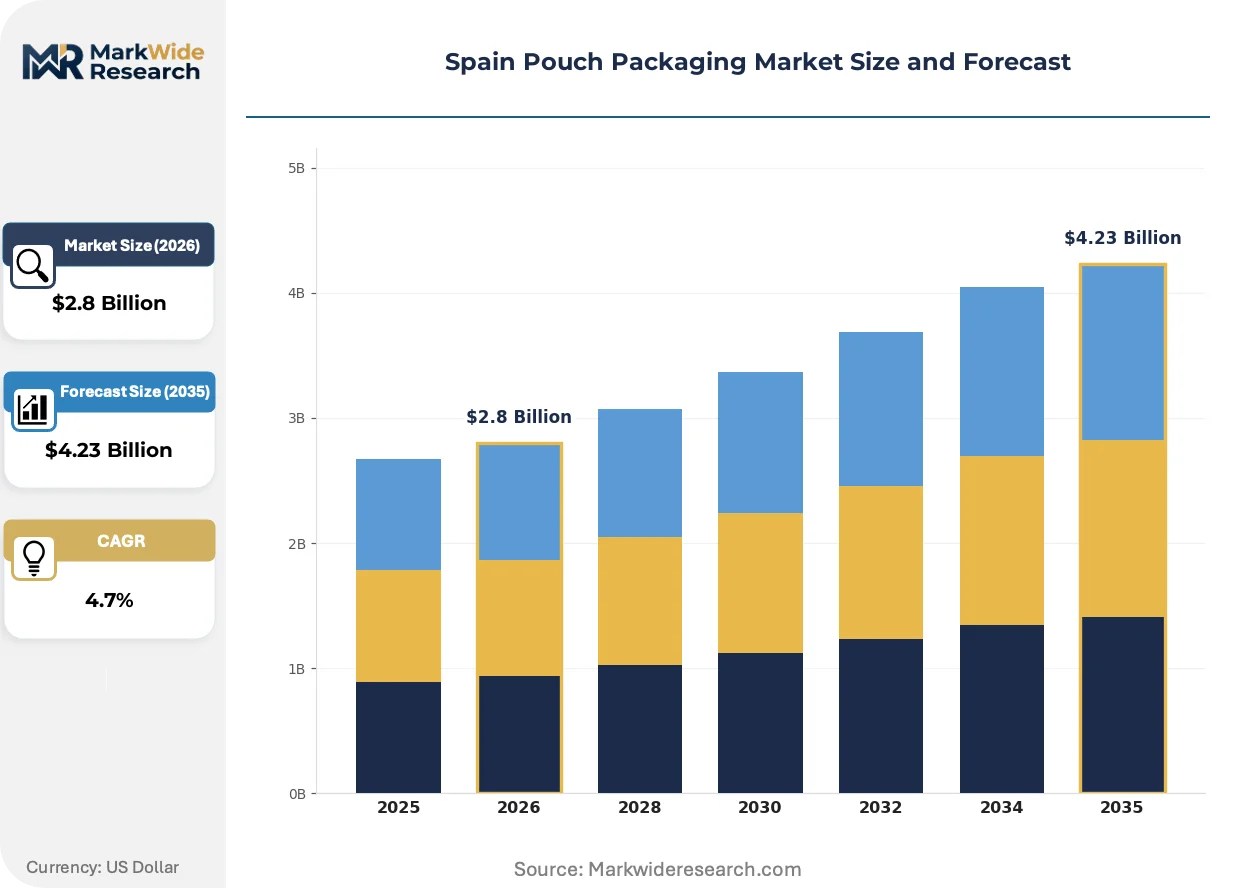
Spain's Royal Decree on Packaging and Packaging Waste is compressing converter margins while accelerating capital redeployment toward mono-material extrusion lines and certified compostable film structures across Catalonia's industrial corridor.
Growth Catalysts
- Extended Producer Responsibility:Spain's transposition of EU packaging waste directives mandates recyclability thresholds, forcing brand owners to specify mono-material pouches and creating pull-through demand for compatible converting capacity.
- Ready-to-eat meal proliferation:Food manufacturers in Barcelona's industrial cluster are expanding retort pouch formats for shelf-stable prepared foods, driving investment in high-barrier lamination and spout integration lines.
- Pharmaceutical unit-dose expansion:Spanish drug makers are displacing blister packs with child-resistant sachets for OTC and prescription products, prioritizing sterility and cost minimization in flat pouch formats.
Market Restraints
- Aluminum foil price volatility:High-barrier laminates depend on aluminum foil supply concentrated in Chinese smelters, exposing Spanish converters to input cost swings that compress margin on fixed-price contracts.
- Recyclability certification bottlenecks:Spain's national packaging regulator requires third-party validation for "recyclable" claims, creating timeline friction and compliance cost that delays product launches.
- Rigid container substitution:Glass and aluminum cans retain preference in premium olive oil segments where consumers associate rigidity with quality, limiting pouch penetration in high-value export categories.
Strategic Opportunities
- Andalusia agricultural export corridor:Seville-Málaga logistics hubs serve North African and Middle Eastern markets where Spanish pouch-packaged nuts, dried fruits, and spices face limited local competition.
- Compostable material convergence:PLA and PHA film technologies are reaching cost parity with conventional multilayers, enabling converters to capture retailer sustainability mandates ahead of regulatory deadlines.
- E-commerce direct-to-consumer channel:Spanish specialty food brands are bypassing traditional retail distribution, specifying lightweight pouch formats that reduce shipping cost and damage rates in parcel networks.
Industry Challenges
- Mono-material line conversion capex:Existing horizontal form-fill-seal equipment requires retrofit or replacement to process polyethylene-only structures, straining mid-tier converter balance sheets.
- Migration testing expertise scarcity:EN standards for food contact compliance demand specialized analytical chemistry capabilities that concentrate in Barcelona and Madrid laboratories, creating regional bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Pouch Packaging Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Ziplock Pouches, Vacuum Pouches Material: Plastic, Aluminum Foil, Paper, Compostable Materials Application: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Closure Type: Heat-Sealed, Zipper Closure, Spout Closure, Others |
| Companies Covered | Amcor PLC, Constantia Flexibles, Mondi PLC, Iflex Flexible Packaging SA, Emsur (Grupo Lantero), Sonoco Products Company, Infipack Machinery SL, SPG, Nekicesa Packaging SL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Pouch Packaging Market Trends and Innovations
Digital printing and smart packaging integration are compressing minimum order quantities while enabling batch-level traceability, reshaping how Spanish converters serve fragmented specialty food and pharmaceutical demand.
Digital printing on flexible films is fragmenting the traditional gravure-dominated supply model for short-run promotional pouches. Small-batch olive oil and cured meat exporters in Extremadura and Castile-León are adopting inkjet and toner-based systems for seasonal label variations without cylinder costs. This technology is fragmenting volume concentration among large converters, enabling regional players to capture previously uneconomic runs.
Spain's national packaging regulator is tightening interpretation of EU single-use plastics directives, specifically targeting non-recyclable multilayer structures in food service applications. Industrial consequence includes accelerated phase-out of PET/PE/AL laminates in favor of certified recyclable or compostable alternatives. The ready-to-eat meal segment is responding fastest, with Barcelona-area co-packers retrofitting lines to process mono-material polyethylene and polypropylene films.
Buyer concentration among large Spanish retail chains is compressing supplier margins while shifting procurement toward direct converter relationships. Discounters and supermarket banners are consolidating pouch sourcing through centralized technical teams, displacing traditional distributor networks. This pattern is most visible in Catalonia, where Mercadona and Carrefour España specifications now drive material selection across their private-label packaging supply base.
Spain Pouch Packaging Market Segmentation
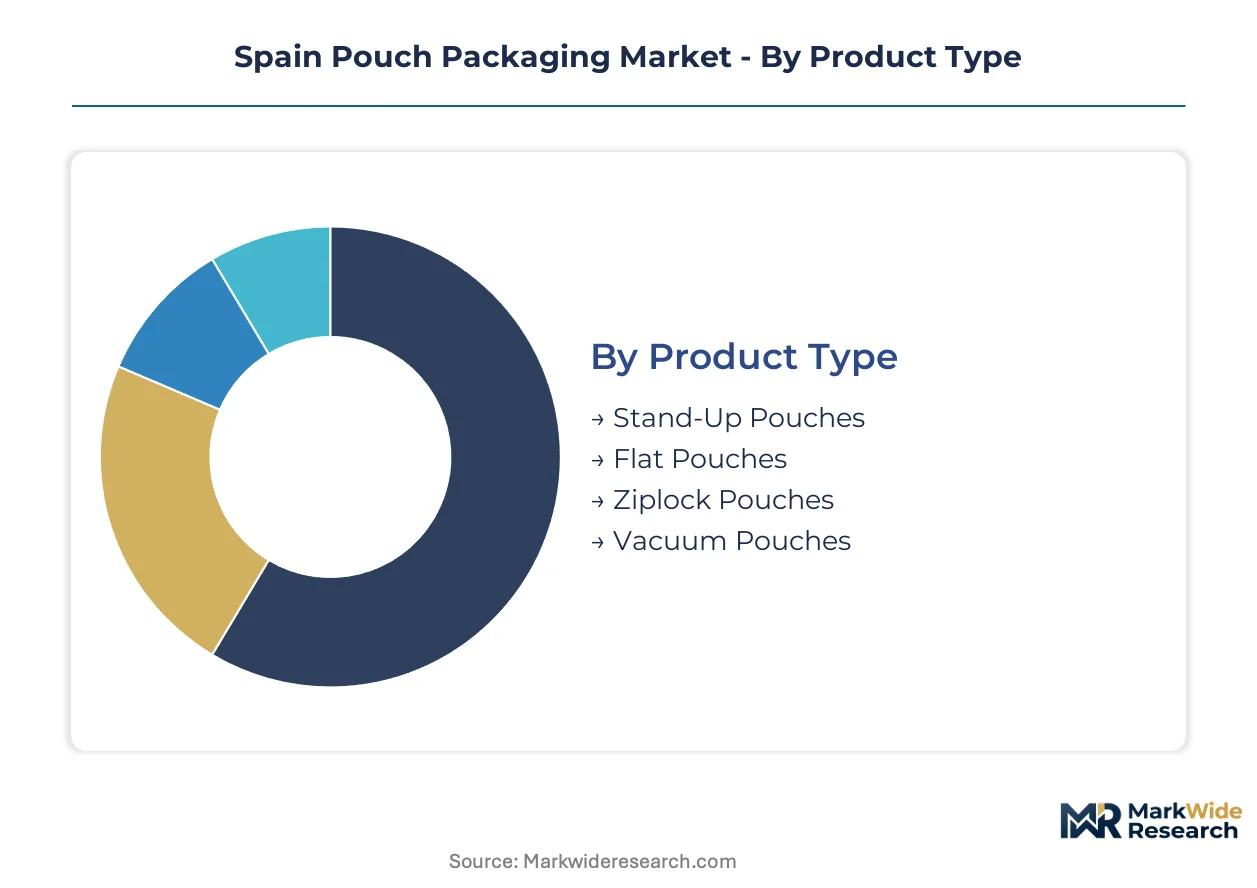
Segmentation in Spain's pouch packaging market reveals how regulatory pressure and export-oriented demand reshape converter priorities. Each dimension exposes distinct margin structures and capital allocation patterns across Catalonia's industrial corridor.
Product Type:
Channel distribution varies sharply by pouch format, with retail-facing stand-up configurations commanding premium shelf space while flat formats dominate institutional and pharmaceutical procurement.
- Stand-Up Pouches:These structures incorporate gusseted bases and high-barrier laminates that enable vertical shelf presentation. Barcelona-area food exporters specify spout-equipped variants for olive oil and premium sauces destined for North African markets where dispensing convenience drives purchase decisions.
- Flat Pouches:Two-dimensional sealed bags minimize material usage and maximize pallet density for pharmaceutical unit-dose and bulk commodity applications. Madrid pharmaceutical manufacturers favor these formats for OTC sachets where sterility and cost minimization outweigh shelf presence requirements.
- Ziplock Pouches:Reclosable interlocking profiles extend product freshness for dried fruits and nuts sold through Mercadona's private-label channels.
- Vacuum Pouches:Oxygen-evacuated structures preserve Iberian cured meats during extended export transit to Middle Eastern markets.
By volume, flat pouches lead. By growth pace, stand-up pouches with integrated spouts are climbing the fastest.
Material:
Cost tiers stratify sharply around regulatory compliance, with conventional multilayers facing displacement pressure from certified alternatives.
- Plastic:Polyethylene and polypropylene mono-materials dominate ready-to-eat meal applications as converters retrofit lines to meet Spain's Royal Decree recyclability thresholds. Catalonia's co-packers are consolidating procurement around these structures to avoid extended producer responsibility penalties.
- Aluminum Foil:Ultra-high-barrier metalized laminates protect oxygen-sensitive cured meats and coffee during ambient distribution. Spanish converters face margin compression from Chinese smelter supply concentration and price volatility on fixed export contracts.
- Paper:Fiber-based substrates with polymer windows serve specialty food brands targeting renewable packaging positioning in German and Nordic export markets.
- Compostable Materials:PLA and PHA films are gaining share fastest as retailer sustainability mandates accelerate ahead of regulatory deadlines.
By installed capacity, plastic structures dominate. By investment flow, compostable materials command the steepest expansion trajectory.
Application:
Customer type concentration determines specification complexity, with multinational food brands driving standardization while pharmaceutical buyers enforce migration testing protocols.
- Food & Beverage:Retort-capable laminates for shelf-stable prepared meals and high-barrier formats for olive oil exports absorb the majority of Catalonia's converting capacity. Barcelona's industrial cluster co-locates filling operations with film extrusion to minimize logistics cost.
- Personal Care:Unit-dose sachets for cosmetics and travel-sized formulations require precise seal integrity and aesthetic surface printing for retail differentiation.
- Household Products:Chemical-resistant structures for detergents and cleaning agents prioritize child-resistant closures and leak-proof spout engineering.
- Pharmaceuticals:Sterile flat pouches for OTC and prescription unit-dose applications demand EN-standard food contact compliance and specialized barrier properties.
By revenue concentration, food and beverage leads. By regulatory scrutiny intensity, pharmaceutical applications are advancing fastest.
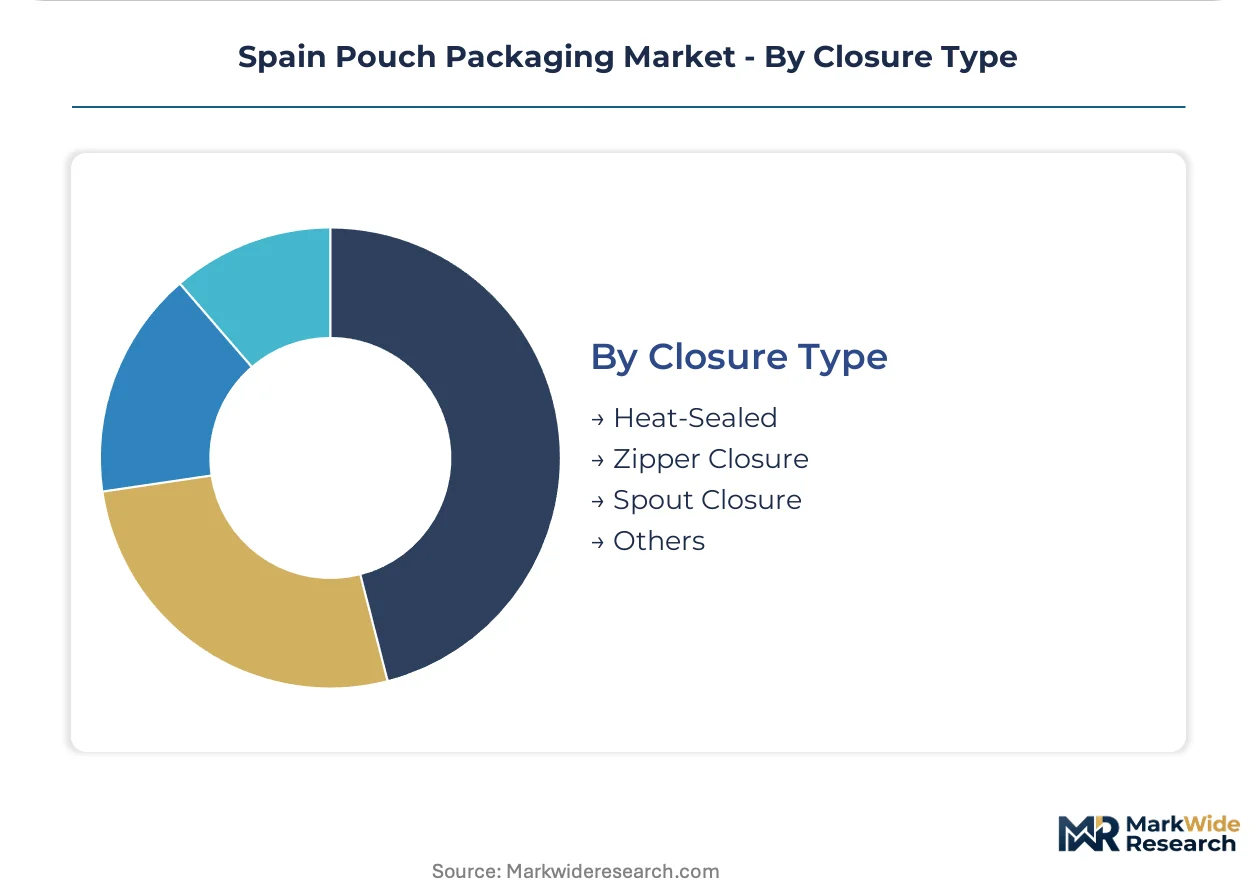
Closure Type:
Margin structure correlates with mechanical complexity, with simple heat seals commoditizing while engineered spouts capture value.
- Heat-Sealed:Basic thermal fusion closures minimize cost for commodity dried goods and pharmaceutical unit-dose formats where single-use consumption is assumed.
- Zipper Closure:Reclosable profiles add material cost but enable portion control for nuts, snacks, and coffee sold through Spanish supermarket banners.
- Spout Closure:Integrated dispensing mechanisms command 40-60% price premiums over standard formats in premium sauce and oil categories. Extremadura olive oil exporters specify these for direct-to-consumer e-commerce channels where damage reduction justifies investment.
- Others:Tamper-evident tear strips and child-resistant mechanisms serve specialized pharmaceutical and chemical applications.
By unit volume, heat-sealed closures dominate. By value capture, spout-integrated formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish pouch-packaged olive oil and cured meats flow through Barcelona-Valencia corridors toward North African and Middle Eastern buyers, with Catalonia's industrial cluster capturing the lion's share of converting capacity.
Catalonia
Barcelona's co-located extrusion and filling operations serve Amcor PLC and Constantia Flexibles with high-barrier laminates for export-bound premium sauces. Spain's Royal Decree on Packaging and Packaging Waste mandates recyclability thresholds that accelerate mono-material line investments across this industrial corridor.
Madrid
Pharmaceutical unit-dose demand from Spanish drug makers concentrates here, with flat pouch formats displacing blister packs for OTC applications. The national packaging regulator enforces EN-standard food contact compliance, creating specialized analytical chemistry bottlenecks that concentrate testing capacity in Madrid laboratories.
Andalusia
Seville-Málaga logistics hubs channel pouch-packaged nuts, dried fruits, and spices toward North African markets with limited local competition. Extended producer responsibility schemes under EU packaging waste directives push Andalusian agricultural exporters toward certified compostable structures.
Valencia
Port infrastructure supports Mediterranean export routes for retort-capable pouches serving shelf-stable prepared meal segments. The region's converters face margin compression from aluminum foil price volatility tied to Chinese smelter supply concentration.
Basque Country
Advanced manufacturing heritage supports precision pouch-making machinery suppliers serving the broader Spanish market. CE marking requirements govern equipment safety standards, with local fabricators specializing in horizontal form-fill-seal retrofits for mono-material processing.
Spain Pouch Packaging Market Competitive Landscape
Player mix skews toward multinational film extruders and regional flexible packaging specialists. The market exhibits tiered consolidation, with global converters controlling high-barrier laminate supply and mid-tier Spanish players capturing short-run specialty food demand. Three archetypes dominate: integrated polymer-to-pouch multinationals, pharmaceutical-focused flexible packaging specialists, and regional agricultural export service providers. Competitive intensity centers on mono-material line conversion capacity and recyclability certification speed.
Among integrated multinationals, Amcor PLC and Mondi PLC exemplify the polymer-to-pouch archetype, leveraging European film extrusion networks to supply Iberian exporters. Constantia Flexibles occupies a distinct position within pharmaceutical-focused flexible packaging, with Spanish plant capacity dedicated to unit-dose formats. These three companies represent the premium-tier competitive vector, where barrier technology and regulatory compliance capabilities determine customer access.
| Leading Market Players |
|---|
| Amcor PLC |
| Constantia Flexibles |
| Mondi PLC |
| Iflex Flexible Packaging SA |
| Emsur (Grupo Lantero) |
| Sonoco Products Company |
| Infipack Machinery SL |
| SPG |
| Nekicesa Packaging SL |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Catalonia's mono-material extrusion lines is compressing price floors for conventional multilayer pouches while elevating premiums for certified compostable alternatives. Spain's Royal Decree on Packaging and Packaging Waste accelerates this bifurcation by penalizing non-recyclable structures through extended producer responsibility fees.
Pricing Analysis
Current-generation mono-material polyethylene pouches trade at 15-25% discounts to prior-generation PET/PE/AL laminates, while next-generation PLA and PHA films command 40-60% premiums. Pricing stratifies across premium, standard, and economy tiers based on barrier certification grade and volume scale. Cost compression in standard-tier commodity pouches is intensifying because Chinese aluminum foil supply concentration exposes Spanish converters to input volatility on fixed export contracts. Pharmaceutical unit-dose buyers exhibit lowest price sensitivity due to sterility compliance requirements, while agricultural commodity exporters demonstrate highest sensitivity to per-unit packaging costs.
Supply Chain Analysis
Inventory cycles for high-barrier laminates stretch 8-12 weeks as Spanish converters buffer against Chinese smelter supply volatility. Raw material sourcing draws from Germany for specialty polymer resins, China for aluminum foil, and Italy for kraft paper substrates. Single-source vulnerability concentrates in aluminum foil supply, where three Chinese producers control 70% of global smelter capacity. Distribution runs through Barcelona-Valencia logistics corridors for North African and Middle Eastern export markets, with Seville-Málaga hubs serving secondary agricultural export routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's pouch packaging market rewards service-attach strategies as recyclability certification and migration testing services expand faster than base film supply. Technical compliance layers now capture margin premiums that hardware conversion alone cannot sustain.
For Market Incumbents: Consolidate mono-material line capacity in Catalonia's industrial corridor to defend against mid-tier converters retrofitting for polyethylene-only structures. Acquire specialized migration testing laboratories in Madrid to capture EN-standard compliance bottlenecks. Prioritize backward integration into certified compostable film extrusion before PLA and PHA cost parity erodes first-mover premiums.
For New Entrants and Emerging Players: Lead with digital printing capabilities for short-run specialty food exporters in Extremadura and Castile-León, where seasonal label variations and fragmented demand resist gravure-dominated supply models. Target e-commerce direct-to-consumer channels for olive oil and cured meat brands seeking damage-reduction packaging. Position around rapid recyclability certification turnaround as a service differentiator against established converter timelines.
For Investors and Strategic Acquirers: Regional agricultural export service providers with dedicated compostable film lines and North African logistics relationships represent the most defensible acquisition archetype. Monitor Madrid's interpretation of forthcoming EU packaging waste regulation revisions as the critical inflection signal; accelerated reuse targets would force premature obsolescence of multilayer line investments and revalue mono-material and compostable specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material Line Conversion | Spain's Royal Decree mandates recyclability thresholds that penalize multilayer structures through extended producer responsibility fees. |
| Compostable Film Extrusion Investment | PLA and PHA technologies reaching cost parity with conventional multilayers enable capture of retailer sustainability mandates. |
| Digital Printing Capability Buildout | Inkjet and toner-based systems fragment gravure-dominated supply for short-run olive oil and cured meat exporters. |
| Migration Testing Laboratory Acquisition | EN-standard food contact compliance concentrates analytical chemistry capacity in Barcelona and Madrid, creating regional bottlenecks. |
| E-commerce Packaging Specification Partnership | Direct-to-consumer specialty food brands demand lightweight formats that reduce parcel network shipping costs and damage rates. |
Research Methodology
A spread of perspectives from packaging converter operations directors, food and beverage procurement managers, pharmaceutical regulatory affairs leads, and retail category buyers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against Spanish customs records, EN standardization body publications, and EU packaging waste directive implementation documents. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include pouch format type, material substrate tier, end-use application, and closure mechanism complexity throughout the forecast period. CAGRs derive from trend extrapolation of installed converter capacity, regulatory compliance cost trajectories, and export demand elasticity for Iberian specialty foods. Industry-specific inputs incorporate aluminum foil price volatility indices and compostable material technology cost curves.
Forecasts assume regulatory continuity in Spain's Royal Decree on Packaging and Packaging Waste and EU extended producer responsibility schemes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Recyclable PE Pouch Market
Pouch
Doy Pouch Packaging Market
Pouch
Slider Zipper Pouch Market
Pouch
Vacuum Chamber Pouches Market
Pouch
Kraft Pouch Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Flexible Plastic Pouches Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Global Boil-In Bags Market
Pouch
Contour Pouches Market
Pouch
India Pouch Packaging Market
Pouch
United States Retort Pouches Market
Pouch
Poland Pouch Packaging Market
Pouch
Kraft Paper Pouch Market
Pouch
Canada Pouch Packaging Market