
 Anti-Static Foam Pouch Market | 2026-2036
Anti-Static Foam Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Static Foam Pouch Market Outlook
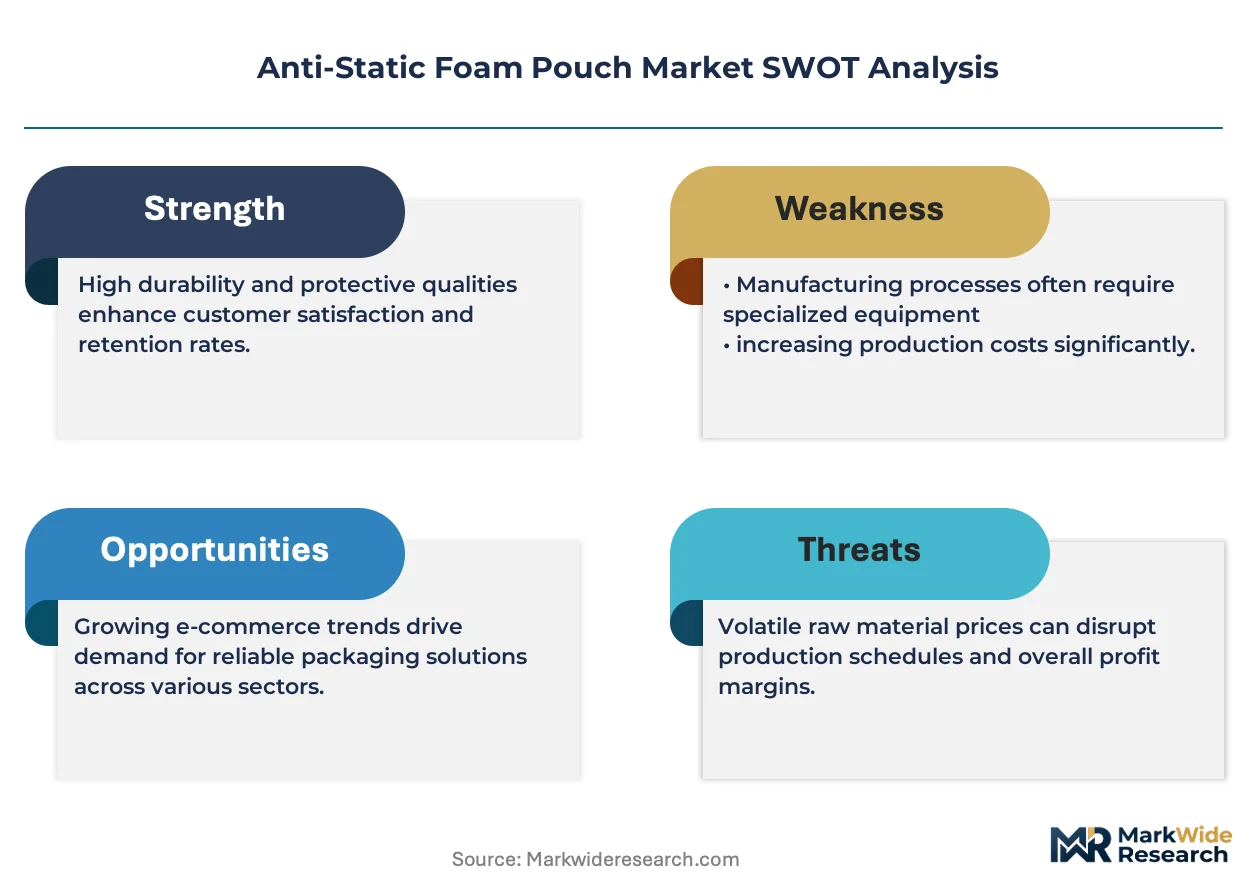
Skilled ESD engineering talent is collapsing across North American and European manufacturing hubs, forcing converters to automate lamination and pouch-sealing lines faster than workforce pipelines refill. Sealed Air Corporation leverages its global film extrusion network to sustain captive supply of conductive polyethylene grades. Pregis LLC anchors Midwest electronics logistics with localized pouch converting and same-day fulfillment capabilities. UFP Technologies, Inc. specializes in medical-grade anti-static foam configurations that differentiate its catalog from standard industrial offerings.
Anti-static foam pouches are multi-layered protective enclosures combining open-cell polyurethane or polyethylene foam with conductive or static-dissipative films, engineered to shield electrostatic-sensitive devices from triboelectric charge buildup during handling, transit, and storage. Surface resistivity typically spans 10^3 to 10^11 ohms per square, with carbon-loaded or ionic polymer coatings providing permanent ESD protection without flaking or outgassing. Foam pouches dominate unit volume due to their ubiquity in consumer electronics fulfillment, while static shielding bags command premium positioning in aerospace and defense supply chains where Faraday cage integrity is mandatory. Custom pouches represent the fastest-growing configuration as OEMs specify exact die-cut dimensions for robotic pick-and-place integration.
EPA guidelines on hazardous substance labeling intersect with OSHA workplace safety rules to mandate ESD control programs in facilities handling flammable solvents or explosive powders, directly expanding pouch demand beyond traditional electronics. CE marking under the EU's Electromagnetic Compatibility Directive requires documented ESD protection for finished equipment, compelling EU-based assemblers to source certified packaging from registered suppliers. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that could impose material recovery obligations on single-use foam packaging before the decade closes.
Market Dynamics
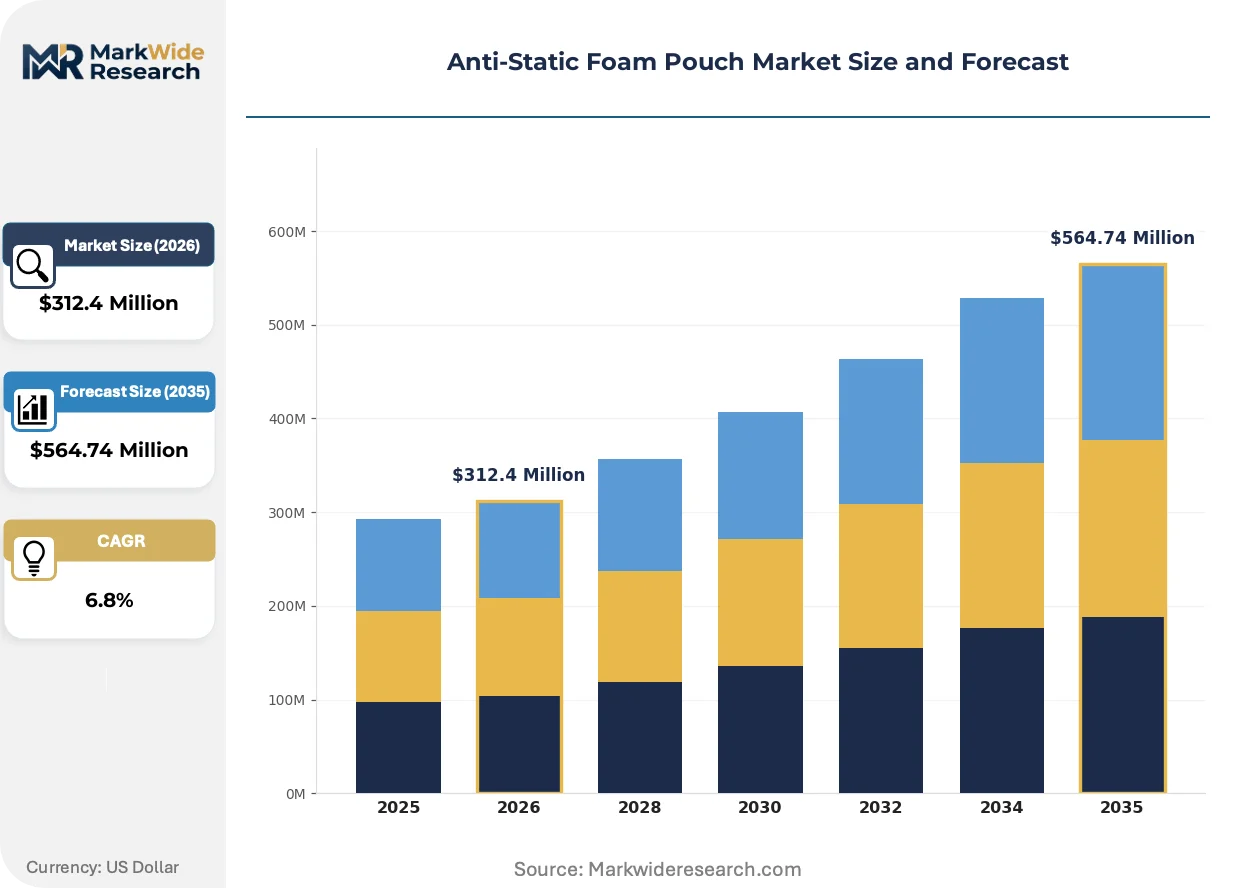
Semiconductor packaging density thresholds are forcing converters to engineer sub-mil conductive film layers that maintain Faraday shielding integrity while reducing material mass per unit. This technical imperative is compressing legacy foam-to-film lamination cycles and rewiring procurement specifications across EMS tiers.
Growth Catalysts
- RoHS substance restrictions:European electronics assemblers must eliminate hexavalent chromium and certain flame retardants from ESD packaging, accelerating demand for ionic-polymer conductive coatings that satisfy ECHA compliance without performance degradation.
- Medical device sterilization protocols:Gamma and ethylene oxide sterilization requirements for implantable electronics are expanding addressable demand for medical-grade anti-static foam configurations that withstand repeated autoclave cycles.
- China's dual carbon goals:Provincial energy intensity targets are pushing Shenzhen and Suzhou-based converters toward water-based adhesive systems and recycled polyethylene feedstocks in pouch manufacturing.
Market Restraints
- Carbon black supply concentration:Conductive grade carbon black production clusters in Texas and Louisiana, exposing foam converters to petrochemical feedstock volatility and hurricane-season supply interruptions.
- Thickness-precision limitations:Open-cell polyurethane foam thickness tolerance of ±0.5mm fails robotic pick-and-place integration requirements below 2mm die-cut specifications, restricting automation penetration.
- California SB 54 implementation:Extended producer responsibility mandates for single-use plastic packaging create compliance cost uncertainty for foam pouch converters serving West Coast electronics fulfillment networks.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for semiconductor and mobile phone manufacturing are attracting Foxconn and Dixon Technologies assembly capacity, creating localized pouch demand around Chennai and Noida.
- Biodegradable static-dissipative films:Convergence of polylactic acid substrates with carbon nanotube coatings offers compostable ESD protection for consumer electronics unboxing experiences targeting sustainability-conscious brands.
- Direct-to-fulfillment-center distribution:Amazon and Flipkart warehouse networks are bypassing traditional distributor tiers, enabling pouch converters to capture margin through vendor-managed inventory programs.
Industry Challenges
- ESD engineering talent scarcity:North American and European manufacturing hubs face collapsing pipelines of technicians trained in ANSI/ESD S20.20 audit protocols and ionization system calibration.
- Cleanroom certification timelines:ISO 14644 Class 7 cleanroom qualification for medical-grade pouch production requires 18-24 month validation cycles, delaying revenue recognition for specialty converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Static Foam Pouch Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Pouches, Custom Pouches, Roll Bags, Static Shielding Bags Material: Polyethylene, Polyurethane, ESD Foam, Vinyl End User: Electronics, Automotive, Aerospace, Healthcare Distribution Channel: Online Retail, Distributors, Wholesalers, Direct Sales |
| Companies Covered | Sealed Air Corporation, Pregis LLC, 3A Manufacturing, Polymer Packaging, Inc., UFP Technologies, Inc., Storopack Hans Reichenecker GmbH, GWP Group Limited, Atlas Foam Products, Foam Converting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Static Foam Pouch Market Strategic Shifts
Material science advances and regulatory stringency are converging to rewrite conductive packaging specifications. Converters must now engineer multi-functional films that simultaneously satisfy ESD, barrier, and sustainability requirements without trade-offs in dielectric performance.
Carbon nanotube-infused polyethylene films are displacing traditional carbon-black loaded substrates in premium anti-static pouch applications. Aerospace and defense contractors in Germany and France are specifying these materials for satellite component packaging where outgassing thresholds below 1% total mass loss are mandatory. The shift is compressing incumbent conductive compound suppliers into commodity pricing tiers while rewarding film extruders with captive nanotube dispersion capabilities.
REACH SVHC candidate list expansion is forcing reformulation of flame-retardant additives in foam substrates. ECHA's 2024 update targeting halogenated compounds requires converters serving EU medical device manufacturers to validate phosphorus-based alternatives through full biocompatibility testing suites. German packaging converters are absorbing six-figure certification costs to maintain CE-marked supply positions, while Asian exporters face exclusion from premium EU tender processes.
Robotic fulfillment integration is compressing pouch specification cycles from annual to quarterly review. Amazon Robotics installations in Poland and the Czech Republic demand die-cut dimensional tolerances of ±0.2mm and surface resistivity documentation per lot. This behavioral shift is fragmenting order volumes toward smaller-batch custom configurations and rewarding converters with digital cutting tables and inline resistivity testing stations.
Anti-Static Foam Pouch Market Segmentation
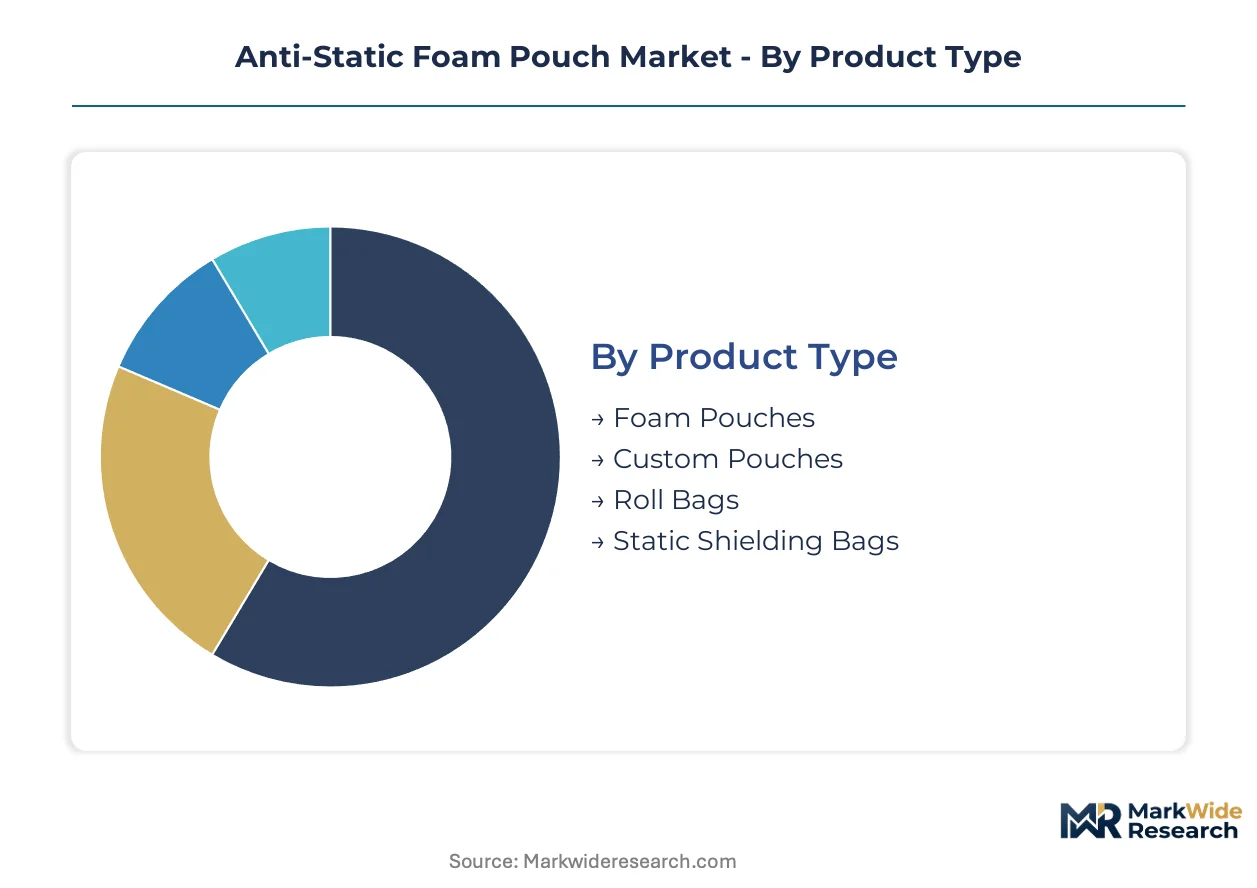
Segmentation in anti-static foam pouches reveals how procurement specifications diverge across compliance regimes and automation readiness. Material choices and product configurations map directly to end-use risk tolerance and regulatory exposure.
Product Type:
REACH SVHC restrictions and CE marking under the EU's Electromagnetic Compatibility Directive create divergent certification burdens across pouch configurations, with medical and aerospace tiers demanding documented Faraday shielding integrity.
- Foam Pouches:Multi-layered enclosures combining open-cell polyurethane or polyethylene foam with conductive films, engineered for surface resistivity between 10^3 and 10^11 ohms per square. Consumer electronics fulfillment networks in China absorb the dominant procurement volume, driven by Foxconn and BYD assembly expansion around Shenzhen and Zhengzhou. Established volume favors foam pouches; emerging adoption favors custom pouches.
- Custom Pouches:Die-cut configurations specified to exact dimensions for robotic pick-and-place integration, with ±0.2mm tolerance requirements. Amazon Robotics installations in Poland and the Czech Republic are compressing specification cycles from annual to quarterly review, rewarding converters with digital cutting tables and inline resistivity testing.
- Roll Bags:Continuous-format conductive film supplied on reels for high-volume automated packaging lines, prevalent in semiconductor wafer handling operations.
- Static Shielding Bags:Faraday cage constructions with metalized film layers for satellite component and defense electronics protection, mandatory where outgassing thresholds below 1% total mass loss apply.
Standard configurations absorb baseline volume; precision-engineered variants capture expanding automation-linked premiums.
Material:
Carbon black supply concentration in Texas and Louisiana petrochemical corridors exposes converters to hurricane-season interruptions, forcing material diversification strategies.
- Polyethylene:Dominant substrate for conductive film extrusion, with carbon-loaded and ionic polymer coatings providing permanent ESD protection without flaking. Sealed Air Corporation leverages captive global film extrusion networks to secure supply continuity. China's provincial energy intensity targets are pushing Suzhou-based converters toward recycled polyethylene feedstocks.
- Polyurethane:Open-cell foam substrate with ±0.5mm thickness tolerance limitations that fail robotic integration below 2mm die-cut specifications. German medical device manufacturers specify phosphorus-based flame-retardant alternatives under ECHA's halogenated compound restrictions, absorbing six-figure biocompatibility certification costs.
- ESD Foam:Engineered conductive foam with controlled surface resistivity for component nesting applications in cleanroom environments.
- Vinyl:Cost-competitive static-dissipative option for short-lifecycle consumer electronics with lower ESD risk profiles.
Petrochemical-linked materials anchor current supply; bio-based and recycled alternatives are gaining specification share fastest.
End User:
OSHA workplace safety rules intersect with EPA hazardous substance labeling to mandate ESD control programs beyond traditional electronics, fragmenting demand across industrial verticals.
- Electronics:Dominant consumption cluster spanning semiconductor packaging, consumer device fulfillment, and EMS tier supply chains. India's PLI scheme for electronics manufacturing is attracting Foxconn and Dixon Technologies assembly capacity around Chennai and Noida, creating localized pouch demand.
- Automotive:EV battery management systems and autonomous sensor modules require ESD protection through assembly and logistics. Battery cell manufacturers specify anti-static configurations for lithium-ion module handling where flammable electrolyte exposure risks intersect with electrostatic discharge.
- Aerospace:Satellite component packaging in Germany and France mandates carbon nanotube-infused films with outgassing thresholds below 1% total mass loss, compressing incumbent conductive compound suppliers into commodity tiers.
- Healthcare:Implantable electronics and diagnostic equipment require gamma and ethylene oxide sterilization-compatible configurations. ISO 14644 Class 7 cleanroom qualification for medical-grade production imposes 18-24 month validation cycles on specialty converters.
Electronics retains procurement volume leadership; healthcare and aerospace command steepest margin expansion trajectories.
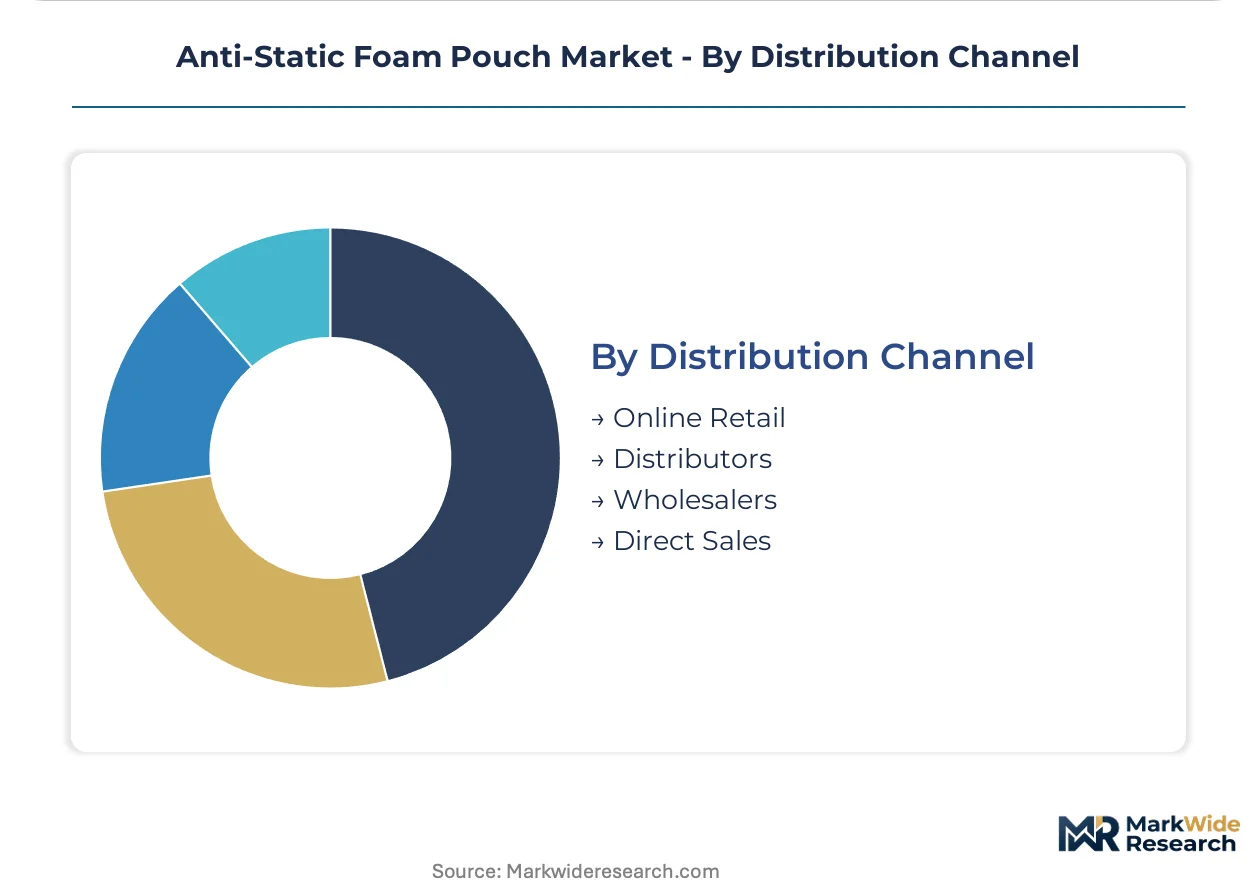
Distribution Channel:
California SB 54 extended producer responsibility mandates create compliance cost uncertainty for single-use foam packaging, rewiring channel economics for West Coast fulfillment networks.
- Online Retail:Amazon and Flipkart warehouse networks are bypassing traditional distributor tiers, enabling pouch converters to capture margin through vendor-managed inventory programs with direct-to-fulfillment-center distribution.
- Distributors:Traditional electronics component distributors maintain specification expertise and same-day fulfillment capabilities for mid-tier EMS procurement.
- Wholesalers:Volume aggregation for standard industrial configurations serving maintenance and repair operations with lower compliance complexity.
- Direct Sales:OEM-direct relationships for custom die-cut specifications requiring collaborative design iteration and lot-level surface resistivity documentation.
Intermediary channels dominate transaction volume; direct and platform-linked routes are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates procurement volume through electronics assembly density, while Germany and the United States concentrate premium-tier demand through aerospace and medical certification requirements. India and Japan represent emerging procurement expansion zones through semiconductor manufacturing incentives and precision electronics export growth.
China
Foxconn and BYD assembly expansion around Shenzhen and Zhengzhou absorbs dominant foam pouch procurement volume for consumer electronics fulfillment. Provincial energy intensity targets under dual carbon goals push Suzhou-based converters toward recycled polyethylene feedstocks and water-based adhesive systems. MIIT GB standards enforcement tightens ESD documentation requirements for export-bound component packaging.
Germany
Aerospace contractors in Stuttgart and Munich specify carbon nanotube-infused films with outgassing thresholds below 1% total mass loss for satellite component protection. ECHA REACH SVHC candidate list expansion forces phosphorus-based flame-retardant validation through six-figure biocompatibility certification costs. KBA automotive safety coordination intersects with ESD protocols for EV battery management system handling.
United States
EPA hazardous substance labeling intersects with OSHA workplace safety rules to mandate ESD control programs in facilities handling flammable solvents or explosive powders. Texas and Louisiana petrochemical corridors concentrate conductive grade carbon black production, exposing converters to hurricane-season supply interruptions. California SB 54 extended producer responsibility mandates create compliance cost uncertainty for single-use foam packaging serving West Coast fulfillment networks.
India
Production-linked incentives for semiconductor and mobile phone manufacturing attract Foxconn and Dixon Technologies assembly capacity around Chennai and Noida. BIS certification requirements tighten material traceability for ESD-safe packaging serving export markets. DGFT import substitution policies accelerate localized pouch converting capacity investment in Gujarat and Maharashtra industrial corridors.
Japan
Precision electronics exporters in Osaka and Nagoya demand die-cut dimensional tolerances of ±0.2mm for robotic pick-and-place integration. METI industrial standards coordination enforces JIS-compliant surface resistivity documentation per production lot. Kyushu semiconductor fabrication expansion creates clustered demand for medical-grade anti-static foam configurations with gamma sterilization compatibility.
Anti-Static Foam Pouch Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive film extrusion networks separating scale players from converter-dependent competitors. The market structures around three archetypes: global packaging conglomerates with polymer science capabilities, regional pouch converters with same-day fulfillment infrastructure, and medical-grade specialists with cleanroom certification assets. Competitive moves concentrate on backward integration into conductive compound supply and geographic expansion through vendor-managed inventory programs with direct-to-fulfillment-center distribution.
Among North American fabricators, Sealed Air Corporation and Pregis LLC occupy positions at opposite ends of the integration spectrum. Sealed Air exemplifies the conglomerate archetype through captive global film extrusion networks. Pregis anchors Midwest electronics logistics with localized converting capabilities. UFP Technologies, Inc. represents the medical-grade specialist tier, differentiating through cleanroom-qualified production assets. Storopack Hans Reichenecker GmbH sits within the European family-owned converter tradition, while 3A Manufacturing and Polymer Packaging, Inc. exemplify mid-scale North American specialists competing on specification responsiveness.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis LLC |
| 3A Manufacturing |
| Polymer Packaging, Inc. |
| UFP Technologies, Inc. |
| Storopack Hans Reichenecker GmbH |
| GWP Group Limited |
| Atlas Foam Products |
| Foam Converting |
| Others |
Value Chain & Pricing Dynamics
Captive film extrusion capacity at Sealed Air Corporation and comparable conglomerates compresses per-unit conductive polyethylene costs below what converter-dependent competitors can match, anchoring price floors while concentrating supply leverage among integrated players. This scale asymmetry forces mid-tier pouch converters to absorb margin compression or exit standard-grade segments entirely.
Pricing Analysis
Long-term offtake agreements dominate procurement between major EMS tiers and integrated film extruders, insulating volume buyers from carbon black feedstock volatility while locking converters into fixed-margin structures. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade cleanroom-certified configurations from industrial-grade foam pouches and commodity vinyl alternatives. Pricing pressure stems from Amazon Robotics installations demanding ±0.2mm die-cut tolerances with quarterly specification reviews, compressing converter margins on custom configurations. Tier-1 electronics manufacturers exhibit lowest price sensitivity due to ESD failure cost exposure, while maintenance-and-repair wholesalers face acute margin pressure from standardized product commoditization.
Supply Chain Analysis
China and the United States anchor conductive grade carbon black production, with Texas and Louisiana petrochemical corridors concentrating feedstock supply and exposing converters to hurricane-season interruption risks. Pouch manufacturing draws from carbon-loaded polyethylene compounds, open-cell polyurethane foam substrates, and ionic polymer coatings as core material inputs. Single-source vulnerability concentrates in conductive carbon black supply, where three Gulf Coast facilities supply North American converter demand. Distribution runs through direct-to-fulfillment-center vendor-managed inventory programs with Amazon and Flipkart, bypassing traditional electronics component distributors for high-volume consumer electronics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as vendor-managed inventory programs with direct-to-fulfillment-center distribution rewire margin capture away from distributor intermediaries. Interoperability between robotic pick-and-place systems and die-cut pouch specifications is compressing specification cycles and rewarding converters with digital cutting infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into conductive compound supply and captive cleanroom certification assets that emerging competitors cannot replicate within validation timelines. Carbon nanotube-infused film capabilities represent a critical lever for aerospace and defense contract retention, while same-day fulfillment infrastructure anchors Midwest electronics logistics against regional challengers. Threat exposure concentrates in biodegradable static-dissipative film substitutes that could displace petroleum-based substrates under extended producer responsibility mandates. For New Entrants and Emerging Players: Same-day fulfillment gaps in India's Chennai-Noida industrial corridor present immediate white-space opportunity as Foxconn and Dixon Technologies assembly expansion outpaces localized pouch converting capacity. Medical-grade gamma sterilization-compatible configurations remain under-penetrated due to ISO 14644 Class 7 cleanroom qualification barriers, offering margin expansion potential for capitalized entrants. Go-to-market positioning should emphasize vendor-managed inventory programs with direct hospital system and EMS tier relationships, bypassing distributor margin extraction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with multi-year vendor-managed inventory contracts and medical-grade cleanroom certification assets that generate sticky OEM relationships. Long-term viability across the analysis window favors specialists with carbon nanotube dispersion capabilities and regional fulfillment infrastructure in high-growth manufacturing corridors. Acquisition target archetype: mid-scale converters with digital cutting tables and inline resistivity testing positioned for robotic fulfillment integration. Signal to monitor: BIS certification requirements tightening material traceability for ESD-safe packaging serving Indian export markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Compound Supply | Captive carbon black and ionic polymer coating production insulates margin from petrochemical feedstock volatility. |
| Cleanroom Certification Investment | ISO 14644 Class 7 qualification unlocks medical-grade gamma sterilization-compatible pouch revenue streams. |
| Digital Cutting Infrastructure Deployment | Inline resistivity testing and ±0.2mm tolerance capability capture Amazon Robotics specification cycles. |
| Direct-to-Fulfillment-Center Distribution | Vendor-managed inventory programs with Amazon and Flipkart bypass distributor margin extraction. |
| Carbon Nanotube Film Capability Buildout | Outgassing-threshold compliance below 1% total mass loss secures German and French aerospace contractor specifications. |
Study Parameters
Initial hypotheses were tested against primary input from ESD engineering directors, pouch converting operations managers, electronics manufacturing services procurement leads, and medical device packaging engineers, then refined through secondary validation against SEC 10-K filings, customs and trade data, EPA hazardous substance labeling records, and ECHA REACH SVHC candidate list updates. Bottom-up demand modeling across end-use segments triangulated with top-down market sizing from conductive film extrusion capacity assessments.
Variance decomposition across product type, material substrate, end-use vertical, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers including electronics assembly expansion, regulatory compliance cost pass-through, and automation penetration curves. Industry-specific forecast inputs incorporated semiconductor packaging density thresholds and robotic fulfillment integration specifications.
Forecasts assume regulatory continuity in REACH and RoHS enforcement across European electronics assemblers, EPA and OSHA ESD program mandates in U.S. facilities, and MIIT GB standards documentation requirements for Chinese export-bound component packaging; material policy shifts in extended producer responsibility laws or carbon intensity targets would require re-modeling. Recalibration cycles align with material shifts in semiconductor fabrication expansion, cleanroom certification timeline compression, and vendor-managed inventory program adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Italy Pouch Packaging Market
Pouch
Kraft Pouch Market
Pouch
UAE Pouch Packaging Market
Pouch
Zipper Pouch Market
Pouch
Twist Wrap Packaging Market
Pouch
Brazil Pouch Packaging Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Inflatable Pouches Market
Pouch
Colombia Pouch Packaging Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Europe Pouch Packaging Market
Pouch
Digital Printed Pouch Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market
Pouch
Egypt Pouch Packaging Market
Pouch
Benelux Pouch Packaging Market
Pouch
Slider Zipper Pouch Market